
 Hybrid Vehicle Market | 2026-2036
Hybrid Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Vehicle Market Analysis
The EU Green Deal's 2035 ICE phase-out timeline is rebalancing European automaker investment toward hybrid powertrains as compliance bridges. Toyota Motor Corporation leverages its two-decade hybrid manufacturing scale to sustain cost leadership across parallel and series architectures. Hyundai Motor Company anchors its competitive position through dedicated hybrid platforms spanning SUV and sedan segments. BMW AG differentiates via performance-oriented plug-in hybrid drivetrains targeting premium fleet channels.
A hybrid vehicle combines an internal combustion engine with one or more electric motors, drawing propulsion from both energy sources through a shared drivetrain with battery packs typically ranging from 1-15 kWh depending on hybrid classification. The system captures regenerative braking energy and enables engine-off operation at low speeds, primarily serving to reduce fuel consumption and tailpipe emissions in passenger transportation. Parallel hybrid powertrains occupy the largest installed base due to manufacturing simplicity and retrofit compatibility with existing engine plants. Plug-in hybrid variants represent the fastest-expanding segment as battery energy density improves and charging infrastructure proliferates. Fleet end users concentrate margin pools through volume procurement contracts and predictable duty cycles that maximize hybrid fuel savings.
The EPA enforces Corporate Average Fuel Economy standards that tighten annually, compelling US manufacturers to expand hybrid offerings or absorb penalties. California's Air Resources Board operates under EPA waiver authority to mandate zero-emission vehicle sales percentages that hybrid powertrains partially satisfy. China's Ministry of Industry and Information Technology administers dual credit policies rewarding new energy vehicle production including plug-in hybrids. Stakeholders must monitor regulatory credit trading values and battery raw material supply agreements as determinants of hybrid program profitability.
Market Dynamics
EPA tailpipe standards and California's Advanced Clean Cars II regulation are compressing pure-ICE viability windows while fleet operators accelerate hybrid procurement based on total cost of ownership advantages.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Annual tightening compels US manufacturers to expand hybrid offerings or absorb penalties, directly stimulating powertrain diversification.
- Regenerative braking energy capture:This technology reduces fuel consumption in predictable duty cycles, making hybrid economics compelling for commercial fleet operators with fixed routes.
- China's dual credit policies:MIIT rewards new energy vehicle production including plug-in hybrids, channeling domestic manufacturing capacity toward electrified powertrains.
Market Restraints
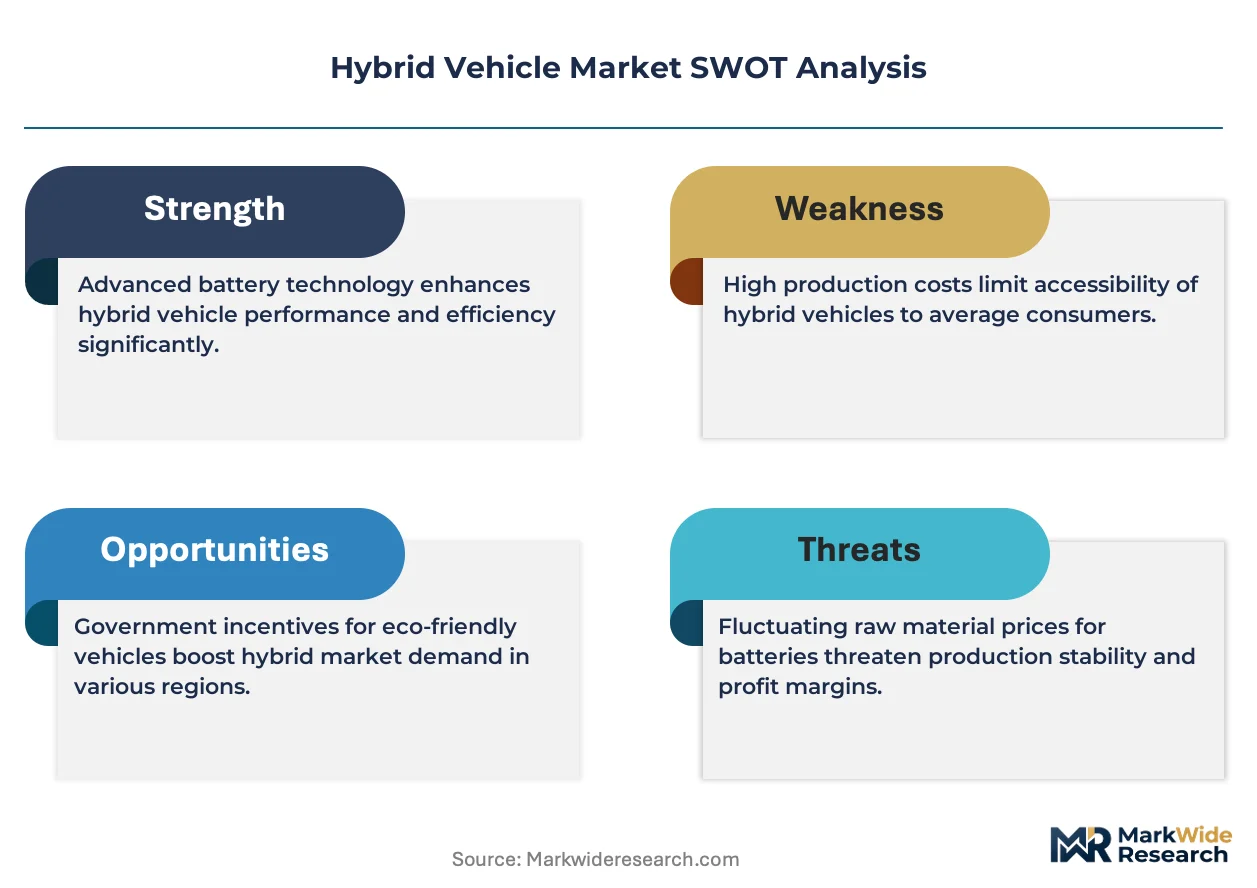
- Battery raw material concentration:Lithium and rare earth processing capacity clusters in China, creating supply vulnerability for hybrid battery pack producers elsewhere.
- Plug-in hybrid charging infrastructure gaps:Inconsistent charging network density limits electric-only range utilization in suburban and rural geographies.
- Pure battery electric substitution:Falling BEV costs and expanding range threaten plug-in hybrid relevance as a compliance bridge technology.
Strategic Opportunities
- Commercial fleet electrification mandates:California's fleet purchasing requirements create dedicated demand channels for hybrid vans and medium-duty trucks.
- India's FAME subsidy scheme:Central government incentives for strong hybrids in the sub-4 meter vehicle category open volume manufacturing scale for compact powertrains.
- Performance-oriented plug-in hybrids:Convergence of turbocharged engines with high-output electric motors enables premium positioning in European and North American fleet channels.
Industry Challenges
- Powertrain integration engineering:Calibrating engine-off operation at low speeds with thermal management requires scarce software and controls talent.
- Certification timeline compression:Multiple regulatory credit systems across EPA, California Air Resources Board, and MIIT demand parallel homologation processes.
- Legacy supplier reconfiguration:Existing transmission and engine component manufacturers face margin pressure as hybrid architectures consolidate subsystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Vehicle Market |
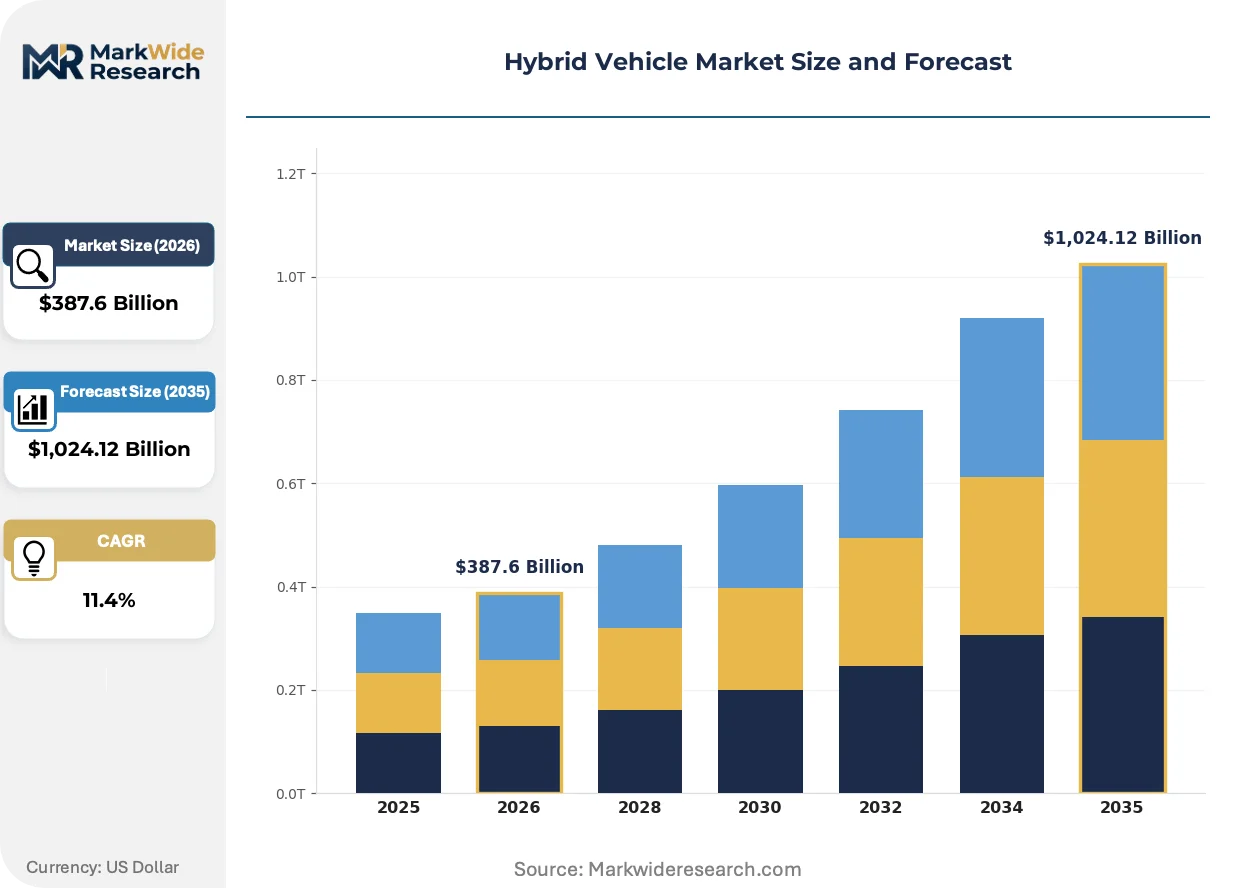
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,024.12 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Powertrain Type: Parallel Hybrid, Series Hybrid, Plug-In Hybrid, Mild Hybrid Vehicle Type: SUV, Sedan, Hatchback, Coupe Battery Type: Li-ion, NiMH, Lead Acid, Solid-State End User: Personal, Fleet, Ride-Sharing, Government |
| Companies Covered | Toyota Motor Corporation, Honda Motor Co., Ltd., Hyundai Motor Company, Ford Motor Company, Volkswagen AG, BYD Co., Ltd., Nissan Motor Co., Ltd., BMW AG, Mercedes-Benz Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Vehicle Market Emerging Trajectories
Powertrain architecture decisions are converging around dedicated hybrid platforms rather than retrofitted ICE designs, compressing development timelines and supplier qualification cycles across the industry.
Silicon carbide power electronics is consolidating thermal management efficiency in hybrid inverters, enabling higher electric motor output density. Tier 1 suppliers are adopting these modules for next-generation 800V architectures. This technology is consolidating competitive positioning around suppliers with captive semiconductor packaging capability.
The EU Green Deal's 2035 ICE phase-out timeline is rebalancing European automaker investment toward hybrid powertrains as compliance bridges. OEMs are redirecting engineering resources from pure ICE refinement to plug-in hybrid optimization. Premium fleet channels in Germany and the Netherlands are absorbing the highest concentration of these transitional powertrains.
Fleet procurement departments are consolidating vehicle sourcing decisions under sustainability officers who weight total cost of ownership against carbon accounting requirements. Traditional dealer networks are losing influence to direct fleet negotiation teams. This shift is most visible in North American commercial leasing channels where duty cycle predictability maximizes hybrid fuel savings realization.
Hybrid Vehicle Market Segmentation
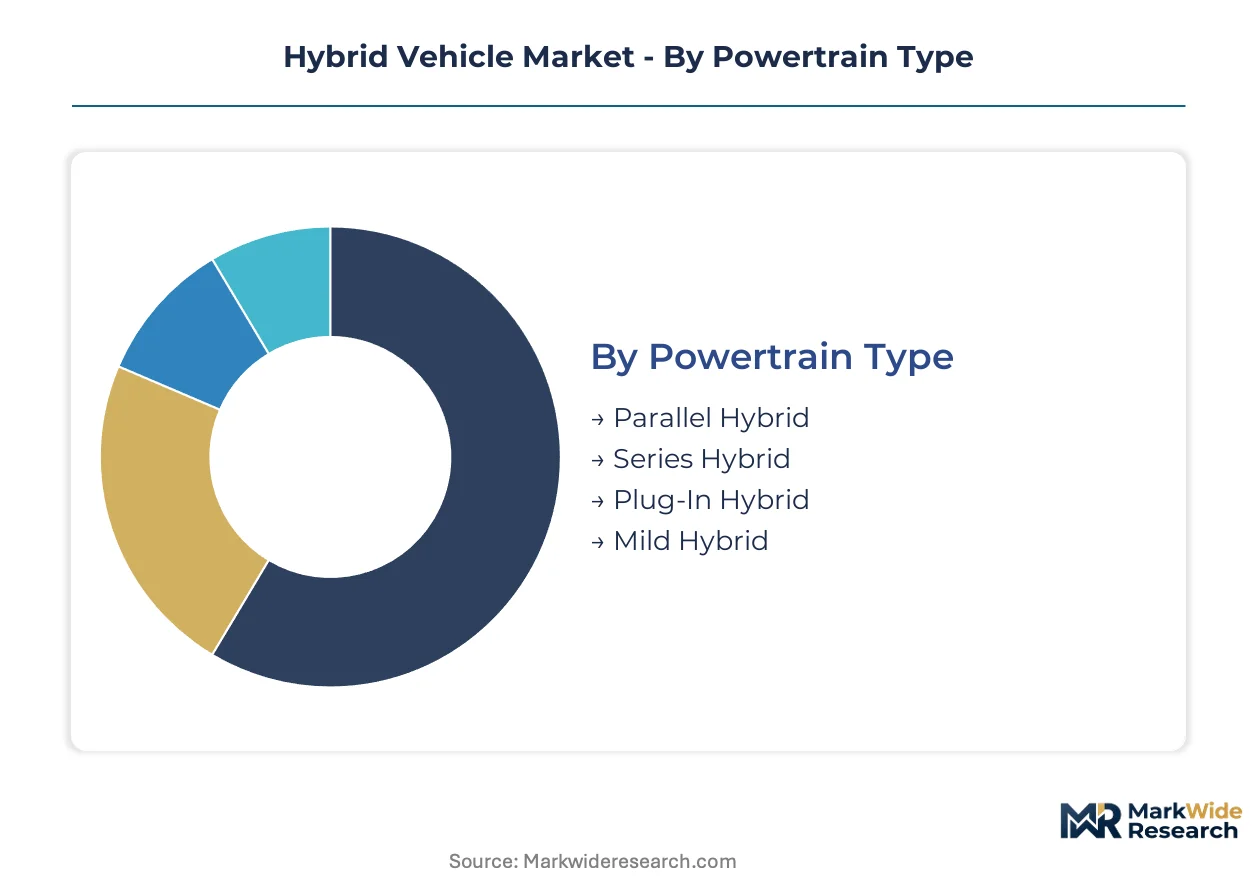
Powertrain architecture choices determine manufacturing complexity and regulatory compliance pathways for automakers. Battery chemistry selection shapes supply chain exposure and thermal management requirements. End-user segmentation separates volume economics from premium positioning strategies across passenger transportation.
Powertrain Type:
Upgrade cycles from conventional internal combustion engines to electrified powertrains are shortening as fleet operators replace vehicles ahead of regulatory deadlines.
- Parallel Hybrid:Combines mechanical coupling of engine and electric motor through shared transmission, enabling both power sources to drive wheels simultaneously. Manufacturing lines in Japan and Germany concentrate output for compact sedans serving urban taxi fleets where regenerative braking recovery maximizes fuel savings.
- Plug-In Hybrid:Incorporates larger battery packs enabling 30-80 km electric-only range with external charging capability. Demand clusters in California and the Netherlands where workplace charging infrastructure supports daily commute electrification without range anxiety penalties.
- Series Hybrid:Electric motor exclusively drives wheels while engine functions as generator; eliminates mechanical transmission complexity. Niche deployment in range-extended commercial vans.
- Mild Hybrid:48V belt-driven starter-generator assists acceleration and enables coasting; lowest electrification cost tier. Dominates European mass-market hatchbacks.
Parallel Hybrid sits at the top of the volume ranking, with Plug-In Hybrid climbing the fastest.
Vehicle Type:
Cost tier stratification separates mass-market penetration from premium fleet channels across body styles.
- SUV:Higher curb weights and aerodynamic drag demand more powerful hybrid systems with 2.0L+ engines paired to dual-motor architectures. North American family buyers and Chinese middle-class consumers drive procurement, with three-row configurations commanding price premiums that absorb battery cost inflation.
- Sedan:Lower frontal area enables smaller battery packs while maintaining competitive electric range; traditional fleet workhorse segment. Japanese and South Korean manufacturers dominate corporate leasing channels where total cost of ownership calculations favor aerodynamic efficiency over cargo flexibility.
- Hatchback:Compact footprint suits mild hybrid cost constraints; European urban preference.
- Coupe:Performance-oriented plug-in variants target enthusiast demographics; lowest volume segment.
Sedan maintains installed base leadership, though SUV is expanding most quickly across all major markets.
Battery Type:
Application-specific energy density requirements and thermal tolerance drive chemistry selection for powertrain integration.
- Li-ion:Nickel-manganese-cobalt and lithium-iron-phosphate variants deliver 150-250 Wh/kg energy density with established recycling infrastructure. Chinese cell production from CATL and BYD supplies plug-in hybrid programs globally, with cobalt-free formulations reducing supply chain concentration risk.
- Solid-State:Ceramic or polymer electrolytes eliminate thermal runaway risk while enabling 400+ Wh/kg targets; pre-commercial pilot lines in Japan and Germany. Toyota and BMW validate automotive-grade manufacturing scalability ahead of platform integration decisions.
- NiMH:Mature chemistry with proven calendar life; Toyota Prius legacy supply base.
- Lead Acid:12V auxiliary systems only; being displaced by lithium 12V replacements.
Li-ion commands current production volumes, with Solid-State gaining share fastest in premium development programs.
End User:
Customer type determines duty cycle predictability and fuel savings realization rates that justify hybrid premiums.
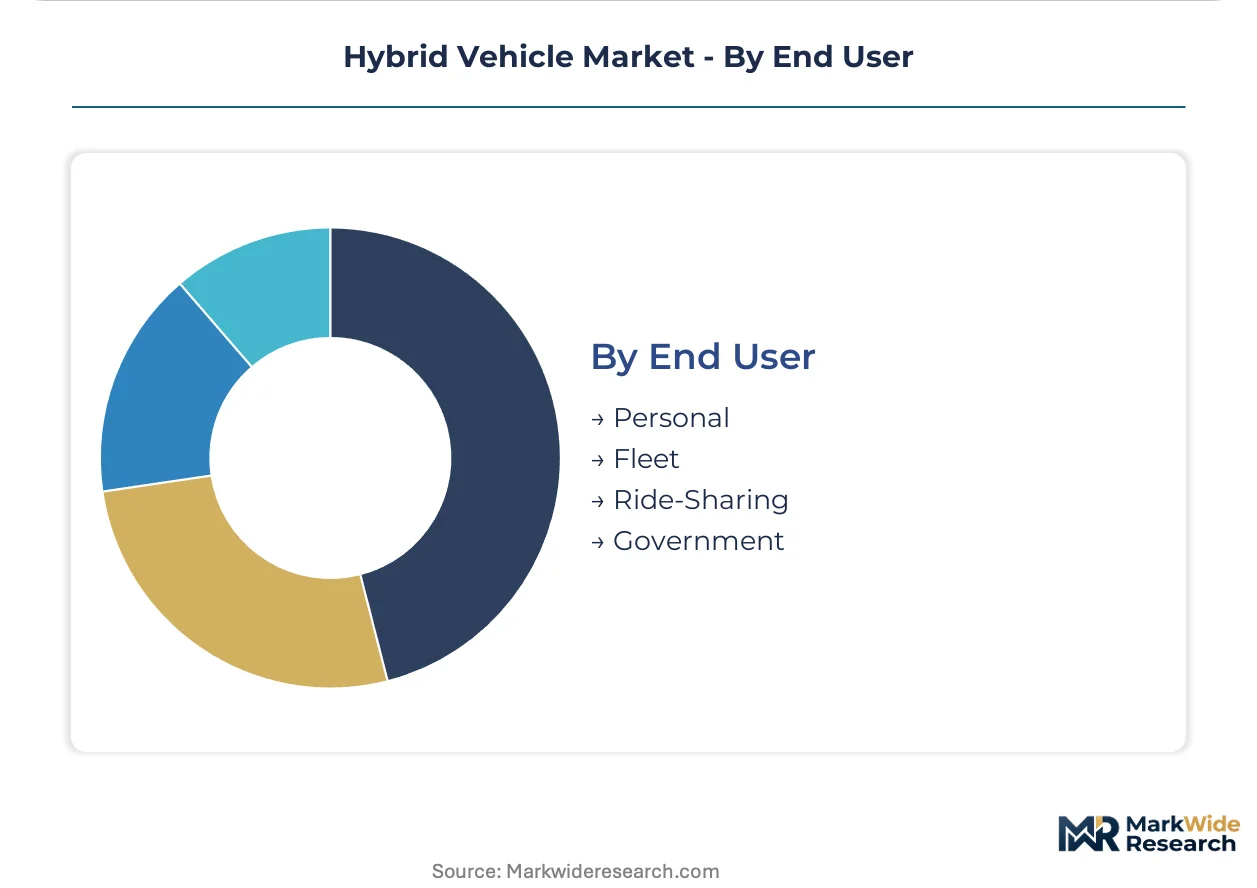
- Fleet:Corporate and government vehicle pools with centralized procurement, fixed routes, and professional maintenance maximize hybrid economics through high utilization and predictable regenerative braking opportunities. California fleet purchasing mandates and German commercial leasing tax treatment accelerate replacement cycles.
- Ride-Sharing:Platform drivers accumulate 80,000+ km annually, compressing payback periods for hybrid price premiums. Uber and Lyft incentive programs in US metropolitan areas channel demand toward qualifying vehicles.
- Personal:Individual buyers with variable usage patterns; price sensitivity limits hybrid penetration to subsidy-eligible markets.
- Government:Municipal procurement with sustainability mandates; smaller absolute volume.
Fleet dominates commercial value capture, while Ride-Sharing shows steepest expansion trajectory in urban mobility electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan pioneered mass-market hybrid manufacturing in the late 1990s, establishing the production templates and supplier ecosystems that now define global hybrid powertrain economics.
China
Domestic automakers and joint ventures consume the largest share of global lithium-ion cell output for plug-in hybrid programs. MIIT dual credit policies reward new energy vehicle production, channeling manufacturing investment toward electrified platforms. Shenzhen and Shanghai host concentrated battery pack assembly operations serving both local brands and export markets.
Germany
Premium fleet channels absorb high concentrations of performance-oriented plug-in hybrids targeting corporate leasing. KBA type-approval processes govern powertrain homologation alongside EU Green Deal compliance timelines. Stuttgart and Munich anchor engineering centers where OEMs redirect resources from pure ICE refinement to hybrid optimization.
United States
Fleet operators across California and the Northeast accelerate procurement based on total cost of ownership calculations. EPA Corporate Average Fuel Economy standards tighten annually, compelling manufacturers to expand hybrid offerings or absorb penalties. Michigan and Tennessee production lines retool for electrified powertrain assembly.
Japan
Two decades of hybrid manufacturing scale sustain cost leadership across parallel and series architectures. METI industrial policy supports next-generation solid-state battery development for automotive integration. Toyota City and Nagoya concentrate final assembly capacity and legacy supplier networks for compact hybrid systems.
South Korea
Dedicated hybrid platforms spanning SUV and sedan segments anchor export competitiveness. Domestic charging infrastructure expansion supports plug-in hybrid daily commute electrification. Ulsan and Hwaseong host integrated manufacturing complexes where captive semiconductor packaging capability consolidates inverter production.
Hybrid Vehicle Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across powertrain architecture decisions. The market structure concentrates around integrated automakers with captive battery supply agreements and dedicated hybrid platform investments. Three archetypes dominate: legacy Japanese manufacturers with two-decade production scale, European premium specialists targeting fleet channels, and Chinese vertically integrated players controlling cell supply. Competitive moves center on silicon carbide inverter sourcing and dedicated platform development timelines.
Among Japanese manufacturers, Toyota Motor Corporation and Honda Motor Co., Ltd. occupy positions defined by manufacturing scale and regenerative braking calibration expertise. Hyundai Motor Company anchors Korean competitive positioning through platform breadth. BYD Co., Ltd. exemplifies Chinese vertical integration into battery cell production. Ford Motor Company and Volkswagen AG represent Western mass-market players retooling around EPA and EU regulatory compliance windows.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Honda Motor Co., Ltd. |
| Hyundai Motor Company |
| Ford Motor Company |
| Volkswagen AG |
| BYD Co., Ltd. |
| Nissan Motor Co., Ltd. |
| BMW AG |
| Mercedes-Benz Group AG |
| Others |
Supply Flow & Price Mechanics
Fleet procurement consolidation under sustainability officers is compressing hybrid vehicle pricing power as volume buyers demand transparent total cost of ownership calculations and standardized service bundling across multi-year contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates performance-oriented plug-in hybrids from parallel hybrid fleet workhorses and mild hybrid entry segments. Price differentiation hinges on battery energy density certification and OEM captive semiconductor packaging capability for inverter thermal efficiency. Cost compression in the standard tier is intensifying because Chinese cell producers are expanding lithium-iron-phosphate output for plug-in programs. Fleet buyers exhibit lowest price sensitivity due to fuel savings realization across predictable duty cycles, while personal buyers in subsidy-lapsed markets show highest elasticity.
Supply Chain Analysis
Lithium carbonate and rare earth magnet supply rests on Chinese processing capacity, South Korean cathode material production, and Japanese separator technology. Hybrid battery pack assembly draws from nickel-manganese-cobalt cells, silicon carbide power modules, and engineered thermal interface materials. Single-source vulnerability concentrates in Chinese lithium refining where export licensing shifts create procurement uncertainty. Distribution runs through captive OEM supply agreements for Tier 1 battery pack integrators, with aftermarket service parts flowing through dealer network consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid vehicle demand compounds around regulatory milestones, with California's Advanced Clean Cars II mandate creating fleet replacement pull-through that sustains volume economics across the projection horizon.
For Market Incumbents: Deepen captive battery supply agreements with Chinese cell producers to secure lithium-iron-phosphate allocation ahead of rival procurement waves. Expand silicon carbide inverter packaging capacity in South Korea to defend margin position against emerging power electronics specialists. Accelerate dedicated hybrid platform development timelines to compress supplier qualification cycles before EPA Corporate Average Fuel Economy penalties tighten further.
For New Entrants and Emerging Players: Begin with India's FAME subsidy-eligible sub-4 meter strong hybrid segment where domestic manufacturing scale incentives reduce capital barriers. Target ride-sharing platform procurement channels in US metropolitan areas where Uber and Lyft incentive programs channel driver demand toward qualifying vehicles. Pursue white-label battery pack assembly partnerships with established Tier 1 suppliers to bypass cell chemistry R&D sunk costs.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated Chinese players controlling upstream lithium refining and downstream vehicle assembly. Long-term viability favors acquisition targets with solid-state battery pilot line validation and automotive-grade manufacturing scalability ahead of platform integration decisions. Watch Toyota and BMW solid-state manufacturing timelines as inflection indicators for next-generation energy density thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | CATL and BYD cell offtake contracts secure lithium-iron-phosphate allocation for plug-in hybrid programs. |
| Platform Standardization | Dedicated hybrid architectures reduce engineering complexity and compress development timelines versus retrofitted ICE designs. |
| Silicon Carbide Investment | Captive semiconductor packaging capability consolidates inverter thermal efficiency for 800V architectures. |
| Charging Infrastructure Partnership | Workplace charging network expansion enables plug-in hybrid daily commute electrification without range anxiety penalties. |
| Geographic Manufacturing Footprint | Michigan and Tennessee production line retooling positions US assembly capacity for EPA compliance window capture. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, Tier 1 supplier procurement leads, fleet sustainability officers, and aftermarket distributors with secondary validation against vehicle production databases, EPA certification filings, MIIT dual credit disclosures, and IHS Markit registration data. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume and value estimates.
Segment-weighting across powertrain architecture, vehicle class, battery chemistry, and end-user type drove analytical framework construction over the projection horizon. CAGRs derived from regression analysis of historical penetration curves against regulatory compliance deadlines and fuel price elasticity assumptions. Forecast inputs incorporated battery raw material supply agreements, charging infrastructure buildout schedules, and fleet procurement contract renewal patterns.
Several conditions sit outside the modeled scope, including unannounced subsidy scheme modifications, geopolitical trade restrictions on lithium processing equipment, and breakthrough solid-state battery commercialization timelines. Forecasts reflect documented assumptions about regulatory enforcement consistency and cell cost learning curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
Hydrogen Vehicles Market
Hybrid Vehicles
Asia-Pacific Mild-Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Truck Market
Hybrid Vehicles
Global Hybrid-Electric Vehicle Insulation Market
Hybrid Vehicles
Ignition Systems for Range-Extended Hybrid Powertrains Market
Hybrid Vehicles
Hybrid Drivetrain Market
Hybrid Vehicles
Europe Mild Hybrid Vehicles Market
Hybrid Vehicles
Smart Hybrid Vehicle Market
Hybrid Vehicles
Canada Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Crossover Vehicle Market
Hybrid Vehicles
Hybrid Train Market
Hybrid Vehicles
North America Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Mild Hybrid Vehicles Market
Hybrid Vehicles
Germany Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
India Hybrid Vehicles Market
Hybrid Vehicles
High-Voltage Hybrid Vehicle Market