
 Hybrid Electric Self-Driving Car Market | 2026-2036
Hybrid Electric Self-Driving Car Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Electric Self-Driving Car Market Analysis
China is reconfiguring its eastern seaboard manufacturing base for intelligent vehicle output. Toyota Motor Corporation leverages its hybrid powertrain depth to anchor autonomous platform development. Tesla sustains vertical control over AI training infrastructure and chip design. BYD Co., Ltd. dominates battery-cell cost structures through in-house lithium iron phosphate production.
A hybrid electric self-driving car integrates an internal combustion engine with one or more electric motors, coupled with sensor arrays, LiDAR, and neural-network-based decision systems enabling conditional or full automation. Its commercial purpose centers on reducing per-mile energy consumption while eliminating human-operator liability in passenger and logistics transport. Sedan configurations currently occupy the largest installed base among vehicle types, though SUV architectures are gaining share in premium fleet deployments. Level 2 autonomy leads present revenue volumes, while Level 4 systems concentrate the fastest-growing engineering investment pools. Plug-in hybrid power sources command higher margin structures than conventional hybrid variants due to larger battery capacities and extended electric-only range.
The US NHTSA Federal Automated Vehicles Policy and the EU AI Act create divergent compliance pathways for cross-border platform deployment. China's MIIT mandatory standards for intelligent connected vehicles dictate data-localization and cybersecurity architectures. ISO 26262 functional safety requirements shape semiconductor and software supplier qualification. Stakeholders must calibrate R&D roadmaps against which regulatory jurisdiction achieves type-approval reciprocity first.
Market Dynamics
Fleet operators in Germany and China are accelerating Level 4 autonomous hybrid procurement, compressing homologation timelines and forcing powertrain suppliers to synchronize electric motor outputs with neural-network inference loads.
Growth Catalysts
- MIIT Certification Mandates:China's tightening safety protocols for intelligent connected vehicles are creating tier-one supplier qualification barriers that favor established hybrid-autonomous integrators with existing type-approval relationships.
- Urban Logistics Electrification:Last-mile delivery operators across Stuttgart and Wolfsburg are specifying plug-in hybrid architectures to satisfy municipal zero-emission zone access while retaining extended-range autonomy for inter-city routes.
- LiDAR-Sensor Cost Curves:Solid-state LiDAR manufacturing scale-up is collapsing per-unit sensor costs, enabling hybrid platforms to carry redundant perception arrays without breaching fleet procurement budgets.
Market Restraints
- Lithium Iron Phosphate Supply Concentration:In-house cell production at dominant Chinese battery manufacturers is locking out second-tier hybrid powertrain suppliers from cost-competitive pack sourcing.
- NHTSA-EU AI Act Divergence:Non-reciprocal type-approval pathways between US Federal Automated Vehicles Policy and European artificial intelligence liability frameworks are forcing dual-certification R&D expenditures for cross-border platform deployment.
- Functional Safety Semiconductors:ISO 26262-qualified chip supply is bottlenecked at three foundry clusters, extending procurement lead times for safety-critical autonomous compute modules.
Strategic Opportunities
- India's Automotive PLI Scheme:Production-linked incentives for advanced automotive technology manufacturing are attracting hybrid powertrain assembly investments targeting domestic intelligent vehicle demand.
- Neural-Network-on-Chip Convergence:Integration of transformer-based decision models with domain-specific AI accelerators is opening architecture wins for semiconductor suppliers capable of unified perception-planning silicon.
- Subscription-Based Autonomy Licensing:Fleet operators are piloting per-mile software licensing models that decouple upfront hardware costs from feature activation, creating recurring revenue pools for platform developers.
Industry Challenges
- Autonomy-Safety Systems Integration:Functional safety engineers with dual competency in ISO 26262 and SAE J3016 automation levels command premium compensation, constraining headcount expansion at Tier 1 suppliers.
- Homologation Timeline Compression:China's MIIT is collapsing intelligent vehicle certification windows from 18 months to 9 months, forcing validation protocol automation and simulation-based verification investments.
- Sensor-Calibration IP Complexity:Multi-LiDAR array calibration algorithms are becoming contested patent terrain, triggering licensing negotiations that delay platform launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Electric Self-Driving Car Market |
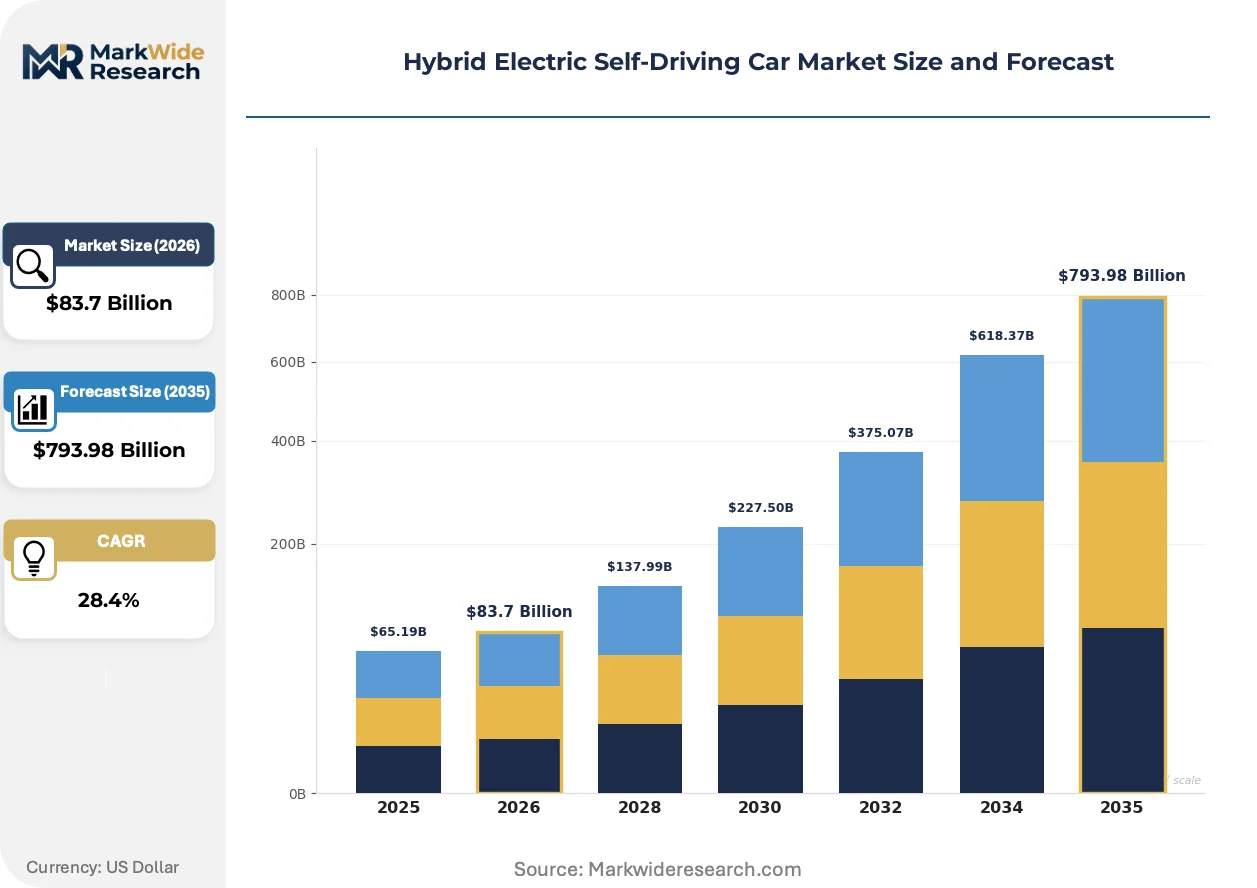
| Market Size in 2026 | $83.7 Billion |
| Market Size in 2035 | $793.98 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: SUV, Sedan, Hatchback, Coupe Power Source: Battery Electric, Hybrid, Fuel Cell, Plug-in Hybrid Autonomous Level: Level 2, Level 3, Level 4, Level 5 End User: Personal, Fleet, Rideshare, Rental |
| Companies Covered | Toyota Motor Corporation, Tesla, BYD Co., Ltd., Volkswagen Group, Hyundai Motor Group, Ford Motor Company, General Motors, Honda Motor, Mercedes-Benz Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Electric Self-Driving Car Market Emerging Trajectories
Digital twin architectures are virtualizing powertrain validation workflows, compressing development cycles while regulatory jurisdictions race to harmonize cross-border type-approval reciprocity.
Software-defined vehicle platforms are virtualizing hardware abstraction layers, allowing hybrid powertrain controllers to execute over-the-air updates without physical module replacement. Fleet operators in Germany's manufacturing corridor are deploying these architectures to synchronize battery management algorithms across distributed vehicle populations. This virtualization is collapsing the traditional boundary between powertrain engineering and cloud-based fleet optimization, enabling real-time energy consumption tuning based on route topography data.
The EU AI Act's risk-classification framework for autonomous decision systems is mandating explainability logging and human-oversight retention protocols for Level 4 platforms operating in European urban zones. Automotive manufacturers are responding by partitioning neural-network inference stacks between on-vehicle edge compute and regional cloud instances to satisfy data-sovereignty requirements. Sedan configurations with lower passenger capacity thresholds are navigating simpler conformity assessment procedures than SUV architectures intended for premium fleet deployment.
Direct fleet procurement is displacing dealer-network intermediation for Level 4 hybrid autonomous platforms, with urban logistics operators negotiating volume contracts specifying guaranteed software-update cadences and battery-health monitoring services. This channel compression is most visible in China's eastern seaboard manufacturing clusters, where municipal fleet electrification mandates are consolidating buying power among state-affiliated transport operators. After-sales service unbundling is following procurement centralization, with predictive maintenance algorithms sold separately from base vehicle hardware.
Hybrid Electric Self-Driving Car Market Segmentation
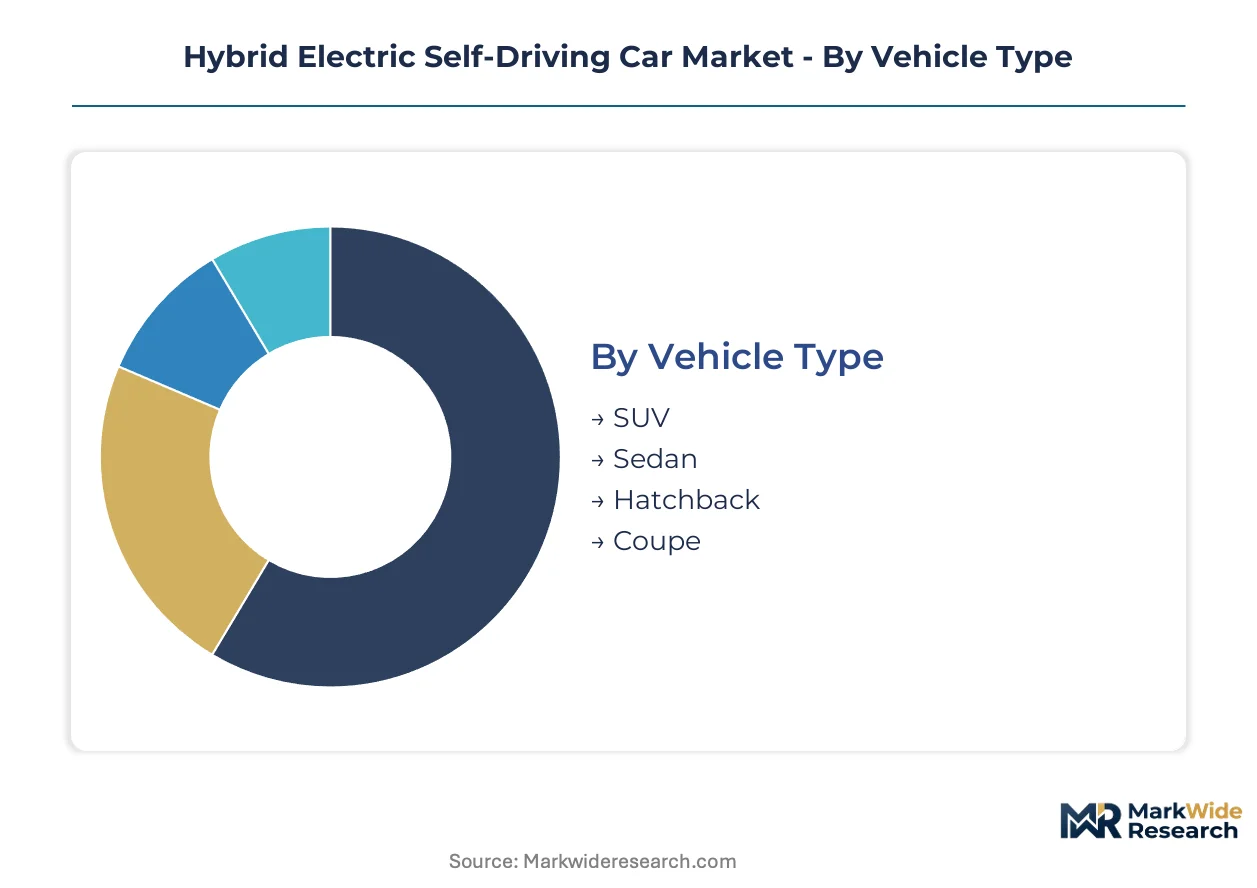
Segmentation in hybrid electric self-driving vehicles reveals divergent engineering priorities across powertrain autonomy integration. Fleet procurement patterns differ sharply from personal ownership on sensor redundancy specifications and battery sizing. Understanding these divides illuminates where capital deployment concentrates versus where margins compress.
Vehicle Type:
Mature sedan architectures dominate installed base volumes while emerging SUV platforms capture premium fleet investment flows.
- Sedan:Lower center-of-gravity chassis designs accommodate dense LiDAR arrays without compromising aerodynamic efficiency. Demand concentrates among German urban logistics operators specifying Level 4 platforms for Stuttgart-Wolfsburg corridor routes where tunnel clearances restrict roofline height.
- SUV:Elevated ride height enables ground-clearance sensor positioning resilient to road debris in mixed urban-suburban environments. China's state-affiliated fleet operators are specifying extended-wheelbase variants for eastern seaboard manufacturing zone passenger shuttle services.
- Hatchback:Compact footprints suit Japanese kei-car regulatory dimensions for narrow urban street navigation.
- Coupe:Two-door configurations attract limited production runs targeting performance-oriented autonomy testing programs.
Sedan configurations handle the majority of throughput; SUV architectures are expanding most quickly on share.
Power Source:
Cost tier stratification separates premium-margin plug-in systems from conventional hybrid variants constrained by smaller battery capacities.
- Plug-in Hybrid:Larger battery packs enable extended electric-only range critical for municipal zero-emission zone compliance. Fleet operators across Germany specify these architectures to retain diesel-range autonomy for inter-city legs while satisfying Stuttgart municipal access requirements.
- Battery Electric:Pure-electric platforms eliminate thermal management complexity from dual powertrain integration. China's MIIT certification timelines favor dedicated electric architectures for faster homologation turnaround.
- Hybrid:Conventional non-pluggable systems retain cost advantages for price-sensitive personal ownership segments.
- Fuel Cell:Hydrogen fueling infrastructure scarcity limits deployment to South Korean demonstration corridors around Seoul-Incheon.
Plug-in Hybrid commands the steepest margin expansion; Battery Electric is climbing the fastest on certification velocity advantages.
Autonomous Level:
Volume concentration sits with driver-assist systems while engineering investment pools concentrate at conditional automation thresholds.
- Level 2:Partial automation combining adaptive cruise with lane-keeping represents the revenue base across personal ownership segments. NHTSA Federal Automated Vehicles Policy permits broader deployment without redundant sensor mandates.
- Level 4:High automation eliminating human oversight in defined operational design domains attracts fleet procurement at premium price points. China's MIIT is compressing certification windows for these platforms from eighteen to nine months.
- Level 3:Conditional automation with driver takeover requirements faces liability ambiguity under EU AI Act risk-classification frameworks.
- Level 5:Full automation without operational design domain restrictions remains pre-commercial across all geographies.
Level 2 retains the dominant throughput position; Level 4 is gaining share fastest on fleet procurement acceleration.
End User:
Customer type determines software licensing model viability and service unbundling potential.
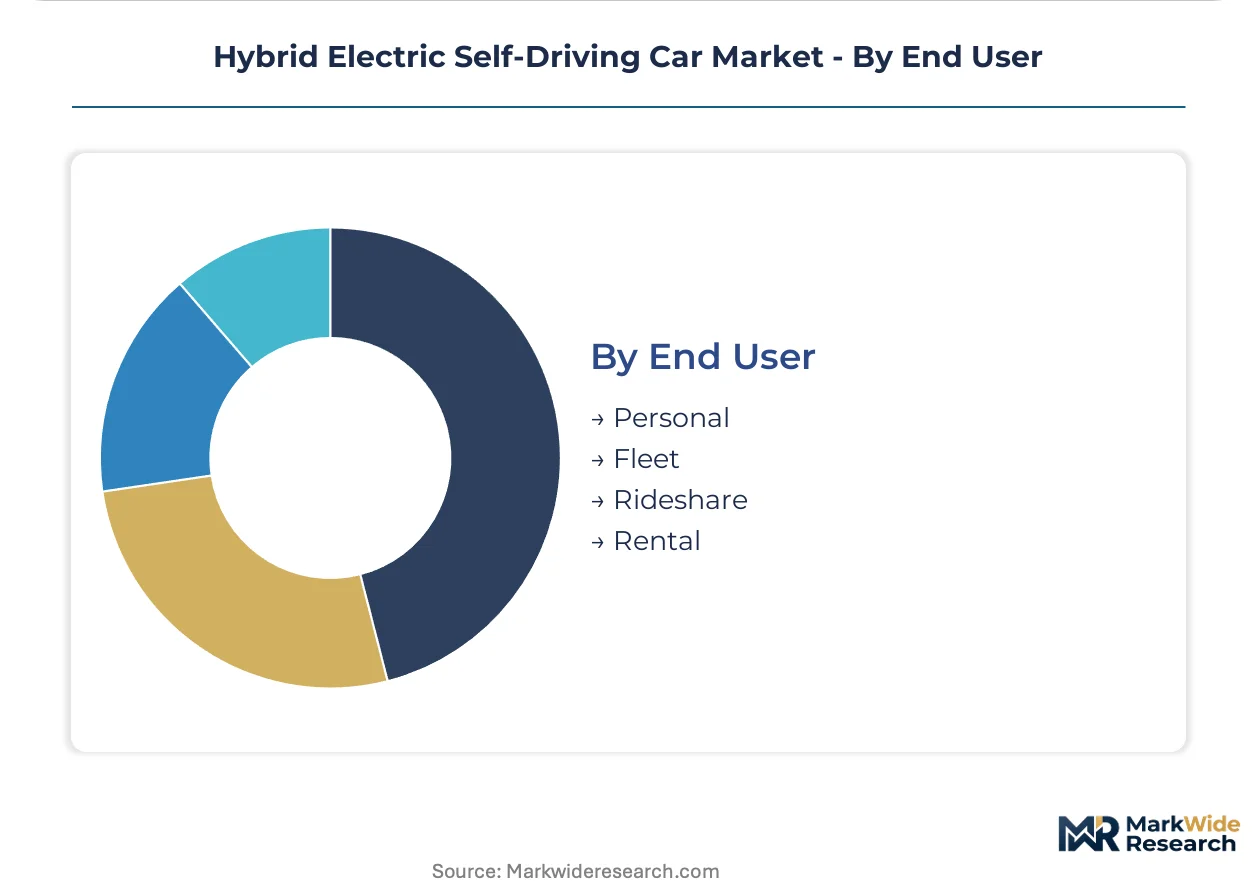
- Fleet:Centralized procurement enables subscription-based per-mile autonomy licensing that decouples hardware from feature activation. German urban logistics operators negotiate volume contracts specifying guaranteed over-the-air update cadences.
- Rideshare:High-utilization duty cycles favor powertrain architectures optimized for continuous operation. China's eastern seaboard municipal operators consolidate buying power under state-affiliated transport entities.
- Personal:Individual ownership segments show preference for Level 2 driver-assist features at lower price points.
- Rental:Short-term deployment models prioritize standardized vehicle configurations for simplified fleet management.
Fleet procurement handles the majority of Level 4 platform throughput; Rideshare is expanding most quickly on utilization economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT anchors the dominant geography through mandatory safety certification protocols that dictate homologation timelines for intelligent connected vehicles. Fleet procurement patterns concentrate manufacturing investment along three distinct national corridors.
China
Eastern seaboard manufacturing zones around Shanghai and Shenzhen are retooling for intelligent vehicle output at scale. MIIT mandatory standards enforce data-localization and cybersecurity architectures that extend certification windows. State-affiliated fleet operators in the Yangtze River Delta consolidate buying power under municipal electrification mandates.
Germany
Urban logistics operators across Stuttgart and Wolfsburg specify Level 4 plug-in hybrid platforms for zero-emission zone compliance. KBA type-approval requirements intersect with EU AI Act risk-classification frameworks for autonomous decision systems. The Baden-Württemberg manufacturing corridor hosts dense supplier clusters for LiDAR integration and powertrain controller development.
United States
NHTSA Federal Automated Vehicles Policy permits broader Level 2 deployment without redundant sensor mandates, accelerating personal ownership segment penetration. Divergent compliance pathways with European liability frameworks force dual-certification R&D expenditures. Michigan and California retain engineering concentration for neural-network training infrastructure and safety-critical semiconductor validation.
Japan
Kei-car regulatory dimensions shape compact hatchback architectures for narrow urban street navigation. METI industrial policy supports hybrid powertrain depth as a competitive anchor against pure-electric platform rivals. Nagoya-based supplier networks specialize in functional safety semiconductor qualification under ISO 26262 protocols.
India
Production-linked incentive schemes for advanced automotive technology manufacturing attract hybrid powertrain assembly investments. BIS standards for intelligent vehicle components are converging with international functional safety benchmarks. Tamil Nadu and Gujarat industrial corridors target domestic fleet demand from state transport undertakings.
Hybrid Electric Self-Driving Car Market Vendor Landscape
Capability concentration sits with hybrid-autonomous integrators possessing existing type-approval relationships; scale advantage sits with battery-cell producers controlling in-house lithium iron phosphate supply. The vendor base stratifies across three tiers: established automotive OEMs with powertrain depth, pure-play autonomy stack developers, and semiconductor suppliers qualified for safety-critical compute modules. Dominant competitive moves include backward integration into cell production and strategic partnerships for neural-network training data access.
Within the established automotive tier, Toyota Motor Corporation represents hybrid powertrain depth as a platform anchor, while Tesla exemplifies vertical control over AI training infrastructure and chip design. BYD Co., Ltd. occupies a position within the cell production tier through captive lithium iron phosphate manufacturing.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Tesla |
| BYD Co., Ltd. |
| Volkswagen Group |
| Hyundai Motor Group |
| Ford Motor Company |
| General Motors |
| Honda Motor |
| Mercedes-Benz Group |
| Others |
Supply Flow & Price Mechanics
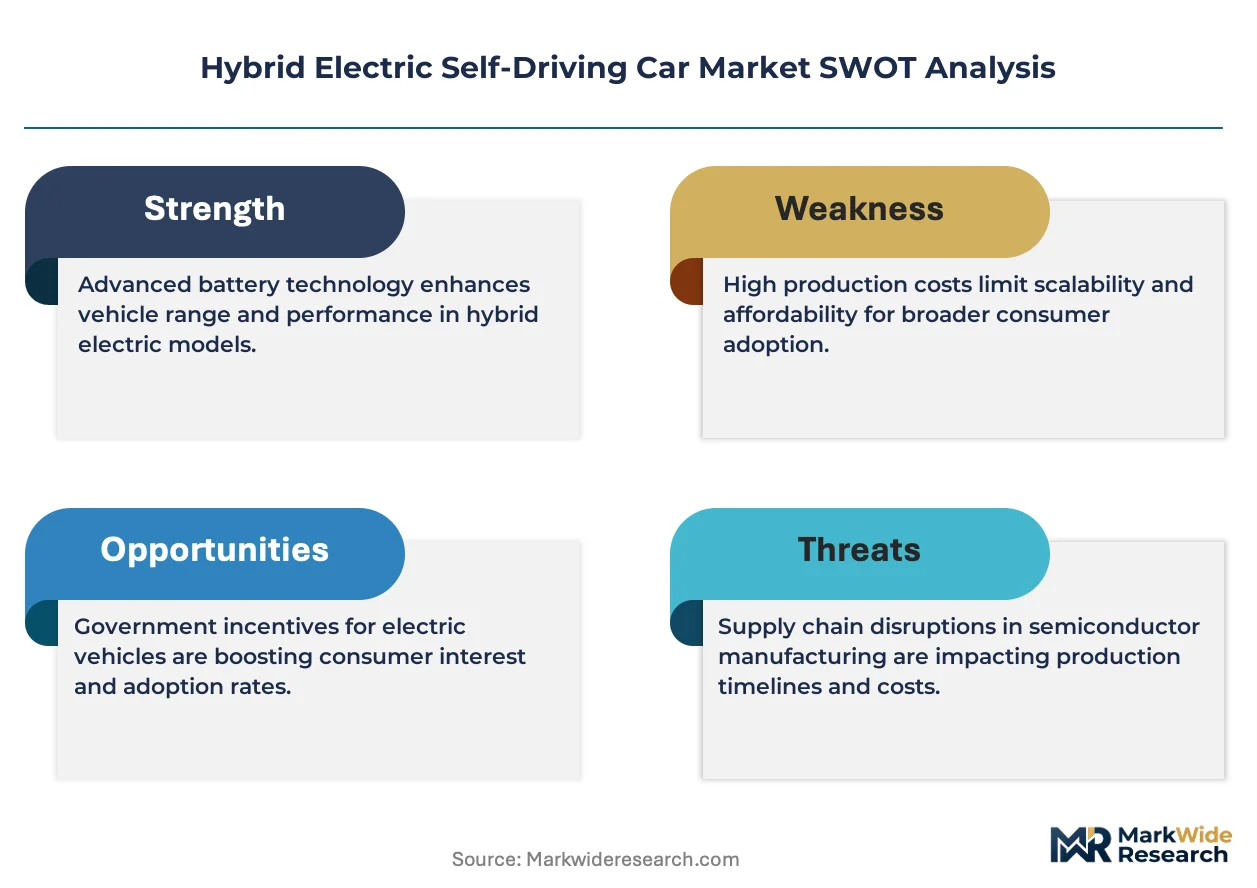
In-house lithium iron phosphate cell production at dominant Chinese battery manufacturers anchors cost structures downstream, concentrating margin pools with integrators capable of captive cathode supply rather than pack assemblers sourcing at spot.
Pricing Analysis
German fleet operators pay premiums exceeding Chinese state-affiliated buyers for identical Level 4 platform specifications due to EU AI Act compliance overhead and KBA homologation documentation requirements. Three-tier pricing structure across premium, standard, and economy levels separates plug-in hybrid architectures with extended electric-only range from conventional hybrid variants with smaller battery capacities. Pricing pressure stems from solid-state LiDAR manufacturing scale-up collapsing per-unit sensor costs and enabling redundant perception arrays at lower price points. Personal ownership segments demonstrate highest price sensitivity, while urban logistics operators accept premium positioning for guaranteed software-update cadences and battery-health monitoring services.
Supply Chain Analysis
Upstream feedstock concentration for lithium iron phosphate cathode materials centers on Chinese chemical processing clusters, with South Korean and Japanese cell manufacturers drawing refined materials from these sources for their own pack assembly operations. ISO 26262-qualified functional safety semiconductors hinge on three foundry clusters in Taiwan, South Korea, and the United States, creating single-source vulnerability for autonomous compute modules. Solid-state LiDAR optical components and rare-earth permanent magnet motors represent additional critical dependencies. Distribution runs through direct fleet procurement channels displacing dealer-network intermediation, with volume contracts consolidating buying power among municipal operators in China's Yangtze River Delta and Germany's Baden-Württemberg corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet procurement centralization among state-affiliated transport operators and urban logistics consolidators has shifted buyer power decisively, compressing supplier margins and forcing unbundling of after-sales services from base hardware.
For Market Incumbents: Insulate margin pools by deepening backward integration into lithium iron phosphate cell production and securing exclusive neural-network training data partnerships before emerging autonomy stack developers accumulate comparable datasets. Priority levers include MIIT type-approval relationship maintenance and software-defined vehicle platform investments enabling over-the-air revenue retention. For New Entrants and Emerging Players: Pursue white-space opportunities in India's Production-Linked Incentive corridors where hybrid powertrain assembly investments face limited incumbent saturation, and target neural-network-on-chip convergence for unified perception-planning silicon. The most penetrable segment sits with Tier 2 suppliers lacking ISO 26262 qualification, reachable through functional safety engineering partnerships rather than full-stack competition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed pure-play autonomy stack developers possessing MIIT certification relationships but lacking powertrain integration depth. Long-term viability over the coming decade depends on securing captive battery supply or exclusive LiDAR array calibration IP. The signal to watch is MIIT reciprocity negotiations with European regulators, which would collapse dual-certification R&D burdens and revalue cross-border platform developers.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Captive lithium iron phosphate sourcing locks out second-tier competitors from cost-competitive pack procurement. |
| Software-Defined Vehicle Investment | Virtualized hardware abstraction layers enable over-the-air battery management tuning across distributed fleet populations. |
| Geographic Manufacturing Footprint | Eastern seaboard retooling for intelligent vehicle output satisfies MIIT data-localization mandates while serving domestic demand. |
| Charging Infrastructure Partnership | Municipal zero-emission zone access requires interoperable fast-charging networks for plug-in hybrid inter-city range extension. |
| Platform Standardization | Unified sensor mounting architectures reduce multi-LiDAR array calibration complexity and accelerate homologation timelines. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, fleet operations directors at German urban logistics operators, and MIIT certification specialists at Chinese testing institutes. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings of listed automotive suppliers, and MIIT intelligent connected vehicle standard disclosures. Bottom-up segment sizing triangulated against top-down macroeconomic automotive demand indicators.
Calibration against historical production volumes and disclosed procurement contract values anchored the analytical framework across the analysis window. Segmentation dimensions modeled include vehicle class, propulsion architecture, autonomous level, and regional regulatory cluster. CAGRs were derived from slope analysis of disclosed fleet procurement trajectories and engineering investment disclosures, incorporating neural-network training infrastructure capex and solid-state LiDAR manufacturing scale-up curves as industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by capital-flush battery manufacturers into full-stack autonomy integration would shift outcomes beyond modeled ranges. Cross-checking against MIIT quarterly intelligent vehicle certification disclosures and KBA type-approval publication rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
Crossover Vehicle Market
Hybrid Vehicles
Asia-Pacific Mild-Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Powertrain Systems Market
Hybrid Vehicles
Micro-Hybrid Vehicle Market
Hybrid Vehicles
Middle East and Africa Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Crossovers Market
Hybrid Vehicles
Hybrid Train Market
Hybrid Vehicles
North America Micro Hybrid Vehicles Market
Hybrid Vehicles
Global Hybrid-Electric Vehicle Insulation Market
Hybrid Vehicles
North America Mild Hybrid Vehicles Market
Hybrid Vehicles
Europe Mild Hybrid Vehicles Market
Hybrid Vehicles
Canada Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Germany Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Hydrogen Vehicles Market
Hybrid Vehicles
Asia-Pacific Micro-Hybrid Vehicles Market
Hybrid Vehicles
North America Hybrid Electric Vehicle Battery Market