
 Plug-In Hybrid Electric Vehicles (PHEV) Market | 2026-2036
Plug-In Hybrid Electric Vehicles (PHEV) Market Size, Share, and Industry Trends Forecast 2026-2036
Plug-In Hybrid Electric Vehicles (PHEV) Market Analytics
Fleet procurement concentration is restructuring PHEV demand as logistics operators and rental aggregators consolidate orders across multi-thousand-unit contracts. Toyota Motor Corporation leverages its hybrid heritage to sustain fleet relationships through proven powertrain reliability. BYD Company Ltd. anchors commercial volume in China with integrated battery manufacturing that compresses delivery cycles.
Plug-In Hybrid Electric Vehicles combine an internal combustion engine with a rechargeable battery pack and electric motor, typically offering 30-60 miles of pure-electric range before gasoline engagement. The architecture serves transitional decarbonization for drivers lacking consistent charging access. SUV configurations occupy the dominant margin pool as families prioritize cabin space and towing capacity alongside electric running. Battery capacity segments above 20 kWh are capturing disproportionate engineering investment as OEMs seek to qualify for maximum clean vehicle incentives. Home charging infrastructure dominates residential installation patterns, though workplace charging is emerging as a fleet retention tool.
EPA tailpipe regulations and the IRA clean vehicle credit framework shape product eligibility and pricing power in the United States. EMA emissions benchmarks and the EU Green Deal's transport decarbonization pathway enforce similar compliance architectures across Europe. Stakeholders must monitor how incentive phase-out schedules and battery sourcing rules reshape competitive positioning between regional production bases and import-dependent supply chains.
Market Dynamics
Fleet operators are consolidating procurement around larger battery packs as EPA tailpipe standards and IRA clean vehicle tax credits reshape product eligibility thresholds across the United States.
Growth Catalysts
- EPA Tier 3 Standards:Stricter nitrogen oxide and particulate limits are forcing OEMs to expand electric-only range capabilities. This regulatory compression accelerates engineering investment in powertrain electrification.
- Workplace Charging Infrastructure:Fleet retention programs are embedding charging stations at logistics hubs and corporate campuses. This channel innovation reduces range anxiety among commercial drivers.
- Lithium-Iron-Phosphate Chemistry:Cell cost reductions from integrated battery manufacturing are compressing PHEV price premiums. This materials shift expands addressable demand among price-sensitive utility vehicle buyers.
Market Restraints
- Lithium Supply Concentration:Hard rock and brine extraction concentrates in Chile, Australia, and Argentina. This geographic clustering exposes cell manufacturers to export restriction risk and price volatility.
- Dual Powertrain Complexity:PHEVs require parallel development of internal combustion and electric systems. This technical burden inflates R&D budgets and extends validation timelines versus pure-electric alternatives.
- IRA Domestic Content Rules:Battery assembly and critical mineral sourcing thresholds disqualify many current models from full tax credit eligibility. This regulatory friction narrows the competitive field to vertically integrated producers.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for advanced chemistry cell manufacturing are attracting greenfield investment. This policy tailwind positions India as an emerging export hub for Asian PHEV supply chains.
- Vehicle-to-Grid Integration:Bidirectional charging hardware convergence with home energy management systems creates new revenue streams. This technology pairing monetizes idle fleet capacity during peak grid demand.
- Rural Last-Mile Logistics:Inconsistent charging infrastructure in secondary cities favors PHEV deployment over full electrification. This underpenetrated geography offers volume expansion for compact commercial van configurations.
Industry Challenges
- Powertrain Calibration Talent:Optimization of engine-battery handoff algorithms requires scarce controls engineering expertise. OEMs face recruitment competition from autonomous driving and battery management software sectors.
- Homologation Timeline Compression:Simultaneous certification against EPA, California Air Resources Board, and EU WLTP protocols strains regulatory affairs capacity. Multi-market launches demand parallel rather than sequential validation tracks.
- Legacy Dealer Network Readiness:Service technician training for high-voltage systems lags vehicle deployment. Franchise networks require capital investment in insulated tooling and diagnostic equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plug-In Hybrid Electric Vehicles (PHEV) Market |
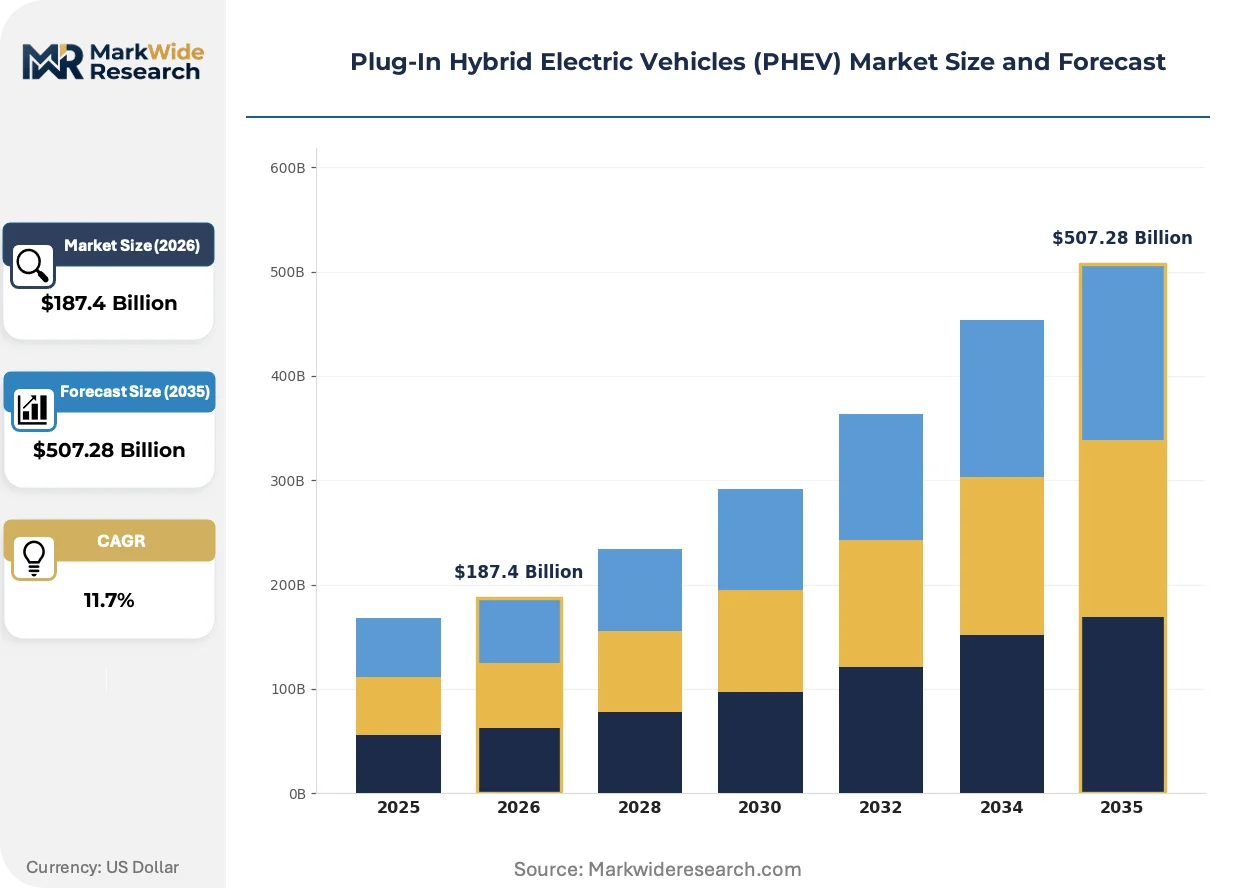
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $507.28 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: SUV, Sedan, Coupe, Minivan Battery Capacity: 10 kWh, 15 kWh, 20 kWh, 30 kWh Charging Method: Home Charging, Public Charging, Fast Charging, Work Charging End User: Individual Consumers, Fleet Operators, Government Agencies, Car Rental Services |
| Companies Covered | Toyota Motor Corporation, General Motors, Ford Motor Company, BMW Group, Mercedes-Benz Group AG, Volkswagen AG, BYD Company Ltd., Honda Motor Co., Ltd, Nissan Motor Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plug-In Hybrid Electric Vehicles (PHEV) Market Evolving Landscape
Powertrain architecture decisions are converging around extended electric range as the primary competitive differentiator, with battery chemistry and thermal management systems absorbing disproportionate engineering resources.
Silicon-carbide inverters are electrifying traction motor efficiency in next-generation PHEV platforms. Tier 1 suppliers are shipping these components to premium SUV programs at volume scale. This semiconductor transition is compressing charging losses and enabling faster DC replenishment cycles.
EU Green Deal transport decarbonization pathways are mandating fleet-average CO2 reductions through 2035. Automakers are responding by expanding plug-in variants across compact and mid-size segments previously dominated by mild hybrids. This regulatory pressure is restructuring powertrain portfolios faster than consumer demand alone would dictate.
Corporate fleet leasing is consolidating around total-cost-of-ownership contracts that internalize fuel and maintenance variability. Aggregators are displacing individual ownership for commercial applications across Germany and the United Kingdom. This procurement model shift favors PHEVs with documented residual value and predictable service intervals.
Plug-In Hybrid Electric Vehicles (PHEV) Market Segmentation
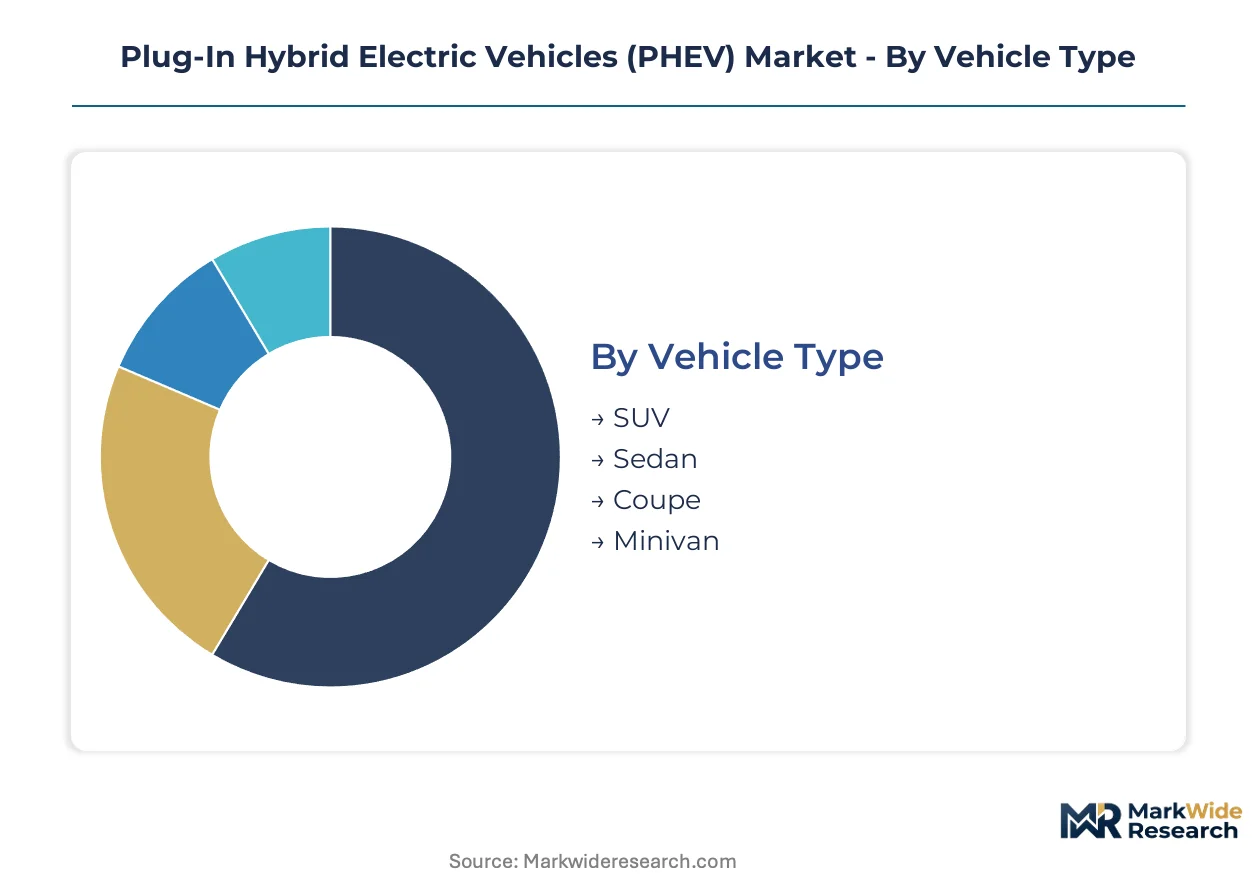
Segmentation in the Plug-In Hybrid Electric Vehicles market reveals how powertrain architecture, infrastructure access, and procurement patterns reshape competitive positioning across distinct customer profiles and use cases.
Vehicle Type:
Integration depth varies sharply by body style, with standalone fleet applications dominating commercial configurations while embedded consumer preferences drive retail demand.
- SUV:Extended wheelbases accommodate larger battery packs above 20 kWh without compromising cabin utility. Families in the United States and Germany prioritize towing capacity alongside electric-only commuting range, compressing payback periods through fuel savings on high-mileage routes.
- Sedan:Lower drag coefficients maximize electric range efficiency for urban professionals with predictable daily distances. Corporate fleet leasing in the United Kingdom concentrates procurement here due to favorable tax treatment and parking infrastructure compatibility.
- Coupe:Performance-oriented tuning targets enthusiast segments with combined powertrain outputs exceeding 400 horsepower. Limited production volumes restrict this configuration to premium pricing tiers.
- Minivan:Three-row seating configurations serve school transportation and airport shuttle operators requiring flexible fueling. The category attracts municipal procurement in Japan and South Korea where charging infrastructure remains uneven.
Volume placements concentrate in SUV configurations; the faster expansion belongs to minivan segments serving commercial route operators.
Battery Capacity:
Cost tier stratification separates compliance-focused entry packs from incentive-maximizing configurations that qualify for full clean vehicle credits.
- 10 kWh:Compact dimensions suit mild-hybrid conversions with sub-25-mile electric range. Price-sensitive markets in Southeast Asia favor this specification for urban delivery applications where daily distances remain constrained.
- 15 kWh:Mid-tier positioning balances cell cost against usable electric range for typical commuter cycles. European OEMs deploy this capacity across compact hatchback variants to meet fleet-average CO2 targets without excessive weight penalties.
- 20 kWh:Threshold qualification for maximum IRA clean vehicle tax credits in the United States drives disproportionate engineering investment. This segment anchors mainstream SUV and sedan offerings from domestic and transplant manufacturers.
- 30 kWh:Extended-range architectures approach full-electric daily usability while retaining gasoline backup for intercity travel. Premium SUV programs in China and Germany adopt this specification to differentiate against pure-electric competitors with charging anxiety.
Procurement volume clusters around 20 kWh configurations; the steepest expansion trajectory belongs to 30 kWh packs as range anxiety persists among luxury buyers.
Charging Method:
Application context determines infrastructure investment priority, with residential patterns dominating retail sales and workplace deployment anchoring fleet retention.
- Home Charging:Level 2 wallbox installation supports overnight replenishment for suburban single-family dwellings. Individual consumers in the United States and Australia exhibit strong correlation between homeownership and PHEV purchase intent.
- Public Charging:Destination charging at retail and hospitality locations extends electric range utilization for apartment dwellers. Municipal programs in France and the Netherlands subsidize curbside installation in dense urban districts.
- Fast Charging:DC rapid replenishment reduces dwell time for commercial operators with unpredictable route structures. Highway corridor deployment in Germany and California supports long-distance fleet utilization.
- Work Charging:Employer-subsidized installation at corporate campuses and logistics hubs reduces range anxiety for commercial drivers. Fleet operators in the United Kingdom negotiate charging access as a retention tool in driver shortage markets.
Residential installation dominates unit placements; workplace infrastructure is gaining share fastest among fleet retention strategies.
End User:
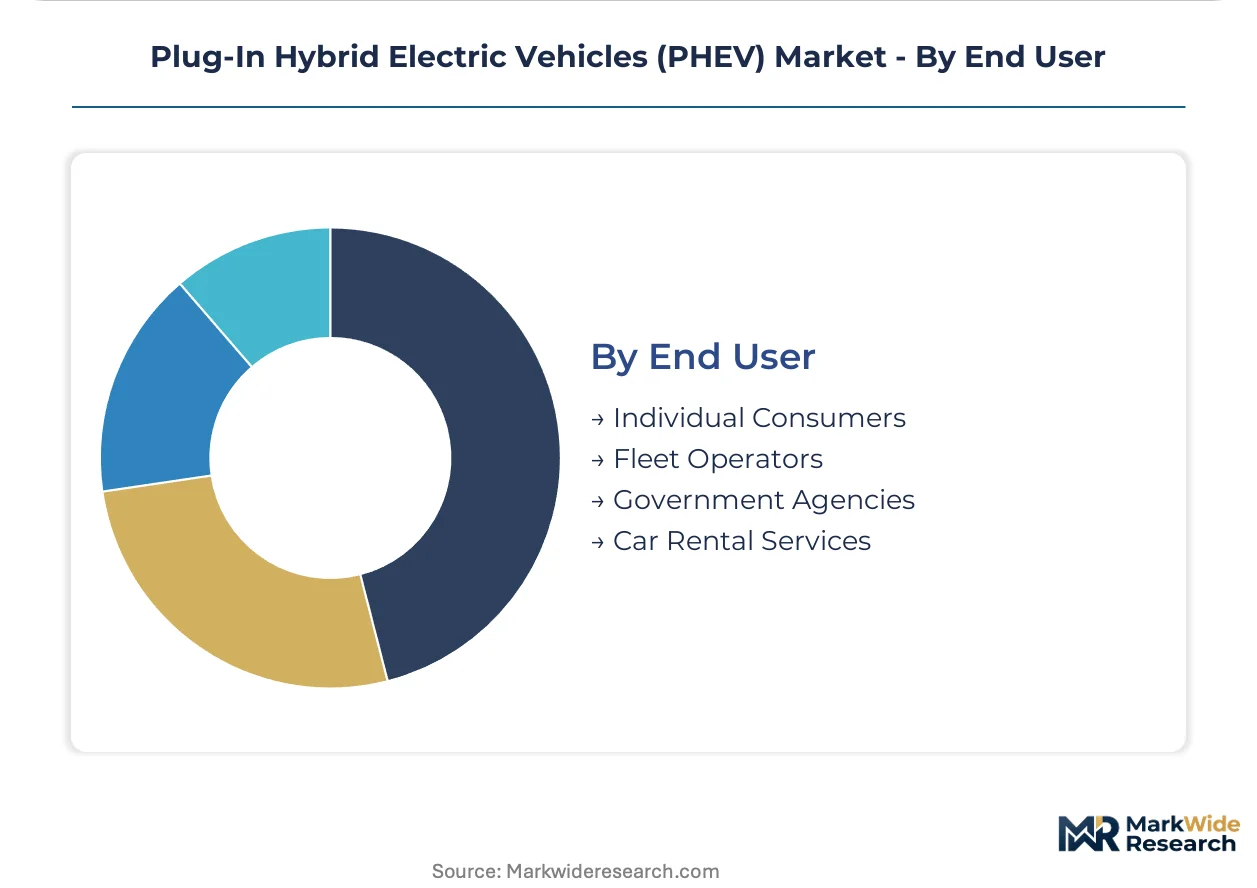
Customer type segmentation exposes divergent total-cost-of-ownership calculations and procurement cycle timelines across private and institutional buyers.
- Individual Consumers:Purchase decisions weigh upfront price premium against fuel savings and tax incentive capture. Households with consistent home charging access exhibit highest conversion rates from conventional hybrid ownership.
- Fleet Operators:Consolidated procurement across multi-thousand-unit contracts restructures manufacturer sales priorities. Logistics aggregators in Germany and the United States negotiate residual value guarantees and service interval predictability.
- Government Agencies:Public procurement mandates favor domestic assembly and minimum domestic content thresholds. Municipal police and utility fleets in the United States and China specify PHEVs for patrol routes with intermittent charging access.
- Car Rental Services:Short-term utilization patterns prioritize rapid refueling flexibility over electric range maximization. Airport-based operators in Spain and Italy favor this technology for tourist routes with uncertain charging infrastructure.
Fleet procurement commands the largest transaction volumes; car rental services are climbing the fastest as tourism recovery accelerates replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium carbonate processing clusters in Chile's Atacama Desert anchor the upstream material flows that feed cathode production for PHEV battery packs across major automotive manufacturing regions.
China
BYD and domestic OEMs command volume leadership through integrated battery manufacturing that compresses cell-to-vehicle delivery cycles. MIIT dual carbon goals and new energy vehicle mandates enforce minimum electric range thresholds that favor 20 kWh-plus configurations. The Yangtze River Delta around Shanghai anchors the densest concentration of PHEV assembly plants and lithium-ion cell gigafactories.
United States
Fleet operators in California and Texas consolidate procurement around IRA credit-eligible models with domestic content-compliant battery packs. EPA Tier 3 tailpipe standards and California Air Resources Board zero-emission vehicle mandates compress product development timelines for extended-range architectures. Detroit's engineering corridors host the primary powertrain calibration centers serving North American PHEV programs.
Germany
Premium SUV configurations dominate household demand as families prioritize towing capacity alongside electric-only commuting range. EU Green Deal transport decarbonization pathways and KBA emissions certification enforce fleet-average CO2 reduction targets through 2035. Bavaria's automotive cluster around Munich concentrates PHEV development engineering for luxury segment powertrains.
Japan
Minivan configurations serve municipal fleet operators requiring flexible fueling for school transportation and airport shuttle routes. METI carbon neutrality roadmaps incentivize commercial vehicle electrification with production subsidies for domestic assembly. The Nagoya-Toyota industrial corridor retains concentrated hybrid powertrain manufacturing expertise spanning three decades.
India
Commercial van operators in secondary cities favor PHEV deployment over full electrification due to inconsistent charging infrastructure. PLI scheme incentives for advanced chemistry cell manufacturing attract greenfield investment from Korean and Japanese battery suppliers. Tamil Nadu's Sriperumbudur automotive belt emerges as the primary assembly location for export-oriented PHEV programs.
Plug-In Hybrid Electric Vehicles (PHEV) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue battery chemistry specialization and fleet software integration. The vendor base organizes around three archetypes: vertically integrated battery-cell producers, legacy powertrain specialists with hybrid heritage, and fleet-focused aggregators bundling charging infrastructure. Consolidation pressures concentrate among mid-tier players lacking captive cell supply or scale procurement relationships. Dominant competitive moves include backward integration into lithium refining and strategic partnerships with workplace charging network operators.
Within the integrated battery manufacturing tier, BYD Company Ltd. and Toyota Motor Corporation occupy positions that exemplify divergent strategic foundations. BYD's Shenzhen-based corporate structure represents the cell-to-vehicle integration archetype, while Toyota Motor Corporation's hybrid heritage anchors its fleet relationship continuity. General Motors and Ford Motor Company sit within the legacy OEM transformation archetype, navigating IRA domestic content compliance requirements.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| General Motors |
| Ford Motor Company |
| BMW Group |
| Mercedes-Benz Group AG |
| Volkswagen AG |
| BYD Company Ltd. |
| Honda Motor Co., Ltd |
| Nissan Motor Co., Ltd |
| Others |
Value Network & Pricing Analysis
Cell-to-vehicle integration anchors supply position and pricing power for PHEV manufacturers, with captive battery production compressing procurement cycles while IRA domestic content rules reshape competitive eligibility thresholds across the United States.
Pricing Analysis
Extended warranty and battery replacement coverage separate bundled premium offerings from unbundled economy tiers in PHEV transactions. Three-tier pricing structure across premium, standard, and economy levels tracks battery capacity, brand heritage, and after-sales service depth. Price differentiation hinges on certification grade for IRA credit eligibility and volume scale in fleet procurement. Cost compression in entry-tier packs is intensifying because integrated manufacturers from China leverage LFP chemistry scale, while fleet buyers exhibit highest price sensitivity and luxury SUV segments show least.
Supply Chain Analysis
Regional distribution centers in Shanghai, Detroit, and Stuttgart coordinate hub-and-spoke patterns for battery pack and powertrain module logistics. Cathode active material production concentrates in China, South Korea, and Japan, while lithium extraction clusters in Chile, Australia, and Argentina. Cell manufacturing rests on cobalt, nickel, and lithium carbonate inputs. Single-source vulnerability in semiconductor-grade graphite exposes tiered suppliers to export restriction risk. Distribution runs through OEM captive networks and Tier 1 system integrators serving multi-brand platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PHEV market operates as a cost-of-compliance arena where IRA domestic content thresholds and EPA Tier 3 standards erect regulatory moats favoring vertically integrated incumbents with captive cell supply.
For Market Incumbents: Cement fleet relationships through residual value guarantees and service interval predictability. Threats from pure-electric substitutes with falling battery costs demand defensive capacity addition in Michigan and Tennessee to satisfy IRA assembly rules. Channel control through certified dealership high-voltage training programs represents the critical lever.
For New Entrants and Emerging Players: Begin with rural last-mile logistics operators in India and Southeast Asia where charging infrastructure gaps persist. The most penetrable segment sits in compact commercial van configurations for secondary city delivery fleets. A software-defined fleet management platform bundling charging access and route optimization offers the essential go-to-market angle.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by battery cell manufacturers seeking downstream integration. Long-term viability favors producers with demonstrated IRA compliance and multi-OEM platform supply relationships. The signal to watch is EPA credit trading price volatility as a demand inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures LFP cell allocation from CATL or BYD for IRA-compliant pack assembly. |
| Platform Standardization | Reduces powertrain calibration costs across SUV, sedan, and van variants. |
| Charging Infrastructure Partnership | Workplace installation at logistics hubs anchors fleet retention in driver shortage markets. |
| Software-Defined Vehicle Investment | Enables over-the-air engine-battery handoff algorithm updates post-homologation. |
| Geographic Manufacturing Footprint | Tennessee or Michigan assembly satisfies IRA domestic content thresholds for tax credit pass-through. |
Research Methodology
Automotive production databases, EPA certification filings, and IHS Markit vehicle registration data formed the secondary backbone. Primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, fleet operations directors, and dealership service managers validated demand assumptions. Bottom-up and top-down triangulation reconciled cell production capacity with vehicle assembly forecasts.
Bottom-up modeling of unit shipments by vehicle class, battery capacity tier, and regional production cluster anchored the analytical lens. Top-down validation checked aggregate value against OEM revenue disclosures and battery materials demand. CAGRs were derived from segment-level growth trajectories across the analysis window. Key inputs included IRA credit phase-out schedules and MIIT new energy vehicle mandate thresholds.
Underlying measurement precision varies by segment; fleet procurement volumes carry tighter precision than individual consumer conversion estimates. Forecasts reflect documented assumptions about incentive continuity and materials cost curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
Global Hybrid-Electric Vehicle Insulation Market
Hybrid Vehicles
North America Micro Hybrid Vehicles Market
Hybrid Vehicles
Asia-Pacific Micro-Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Drivetrain Market
Hybrid Vehicles
Hybrid Powertrain Systems Market
Hybrid Vehicles
Ignition Systems for Range-Extended Hybrid Powertrains Market
Hybrid Vehicles
Hybrid Electric Vehicle Market
Hybrid Vehicles
Smart Hybrid Vehicle Market
Hybrid Vehicles
Crossovers Market
Hybrid Vehicles
Europe Mild Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Cars Market
Hybrid Vehicles
Micro-Hybrid Vehicle Market
Hybrid Vehicles
United Arab Emirates Hybrid and Electric Vehicles Market
Hybrid Vehicles
Mild Hybrid Vehicles Market
Hybrid Vehicles
Hydrogen Vehicles Market
Hybrid Vehicles
Hybrid Electric Self-Driving Car Market