
 North America Hybrid Electric Vehicle Battery Market | 2026-2036
North America Hybrid Electric Vehicle Battery Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hybrid Electric Vehicle Battery Market Insights
Aftermarket service revenue is fragmenting as OEMs tighten control over battery diagnostics and module replacement protocols. LG Energy Solution leverages its Michigan-based cell production to anchor supply agreements with Detroit automakers. Panasonic Energy Co. sustains its technology leadership through cylindrical cell specialization for hybrid platforms. Samsung SDI competes on energy density improvements for plug-in hybrid architectures.
A hybrid electric vehicle battery stores electrical energy through electrochemical processes and delivers supplemental power to an internal combustion drivetrain, typically operating at 100-300 volts with lithium-ion cells dominating contemporary designs. The battery type segment shows lithium-ion chemistry occupying the majority of margin pools while solid-state prototypes advance toward commercial viability. Vehicle type demand concentrates in passenger cars where OEM integration programs drive volume, though commercial fleet electrification is expanding the addressable base. End-user procurement patterns bifurcate between OEM captive supply and aftermarket channels serving aging hybrid fleets.
The US Environmental Protection Agency tailpipe standards and California Air Resources Board zero-emission vehicle mandates compel automakers to maintain hybrid offerings as compliance bridge technologies. NHTSA battery safety protocols govern thermal runaway prevention and crashworthiness testing for North American certification. Stakeholders must monitor how domestic content requirements under the Inflation Reduction Act reshape cell sourcing strategies and supplier qualification timelines.
Market Dynamics
The US Inflation Reduction Act's domestic content bonuses are compressing cell sourcing timelines while OEMs scramble to qualify Michigan and Tennessee-based suppliers before incentive cliffs take effect.
Growth Catalysts
- California ZEV Mandate:The state's Advanced Clean Cars II regulation compels automakers to maintain hybrid offerings as compliance bridge technologies through 2035, anchoring procurement volume.
- Fleet Electrification:Corporate sustainability targets at US logistics operators are expanding hybrid commercial vehicle orders beyond passenger car segments.
- Lithium-Iron-Phosphate Chemistry:Cell producers are expanding LFP capacity for hybrid platforms to reduce cobalt exposure and thermal runaway risk.
Market Restraints
- Domestic Content Requirements:The Inflation Reduction Act's phased battery component rules disqualify Asian-sourced cells from federal tax credits, forcing supply chain reconfiguration.
- Refined Lithium Concentration:Chilean and Australian spodumene supply dominates cathode precursor feedstock, exposing North American cell plants to concentrate price volatility.
- Module Replacement Protocols:OEMs are restricting aftermarket access to battery management system software, fragmenting independent service revenue.
Strategic Opportunities
- Texas Assembly Corridor:OEM plant investments around Austin and San Antonio are creating localized demand for just-in-time cell delivery.
- Solid-State Prototypes:Sulfide-based electrolyte research is advancing toward pilot production for next-generation hybrid architectures with improved energy density.
- Second-Life Stationary Storage:Retired hybrid battery packs are finding application in commercial building backup power systems.
Industry Challenges
- Electrolyte Formulation Talent:Cell manufacturers face acute shortages of electrochemists experienced in dry electrode coating processes.
- UN 38.3 Certification Timelines:Extended testing queues for lithium-ion transport safety approvals are delaying module shipment authorizations.
- Legacy Powertrain Integration:Hybrid battery thermal management must interface with existing internal combustion cooling circuits without compromising warranty coverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hybrid Electric Vehicle Battery Market |
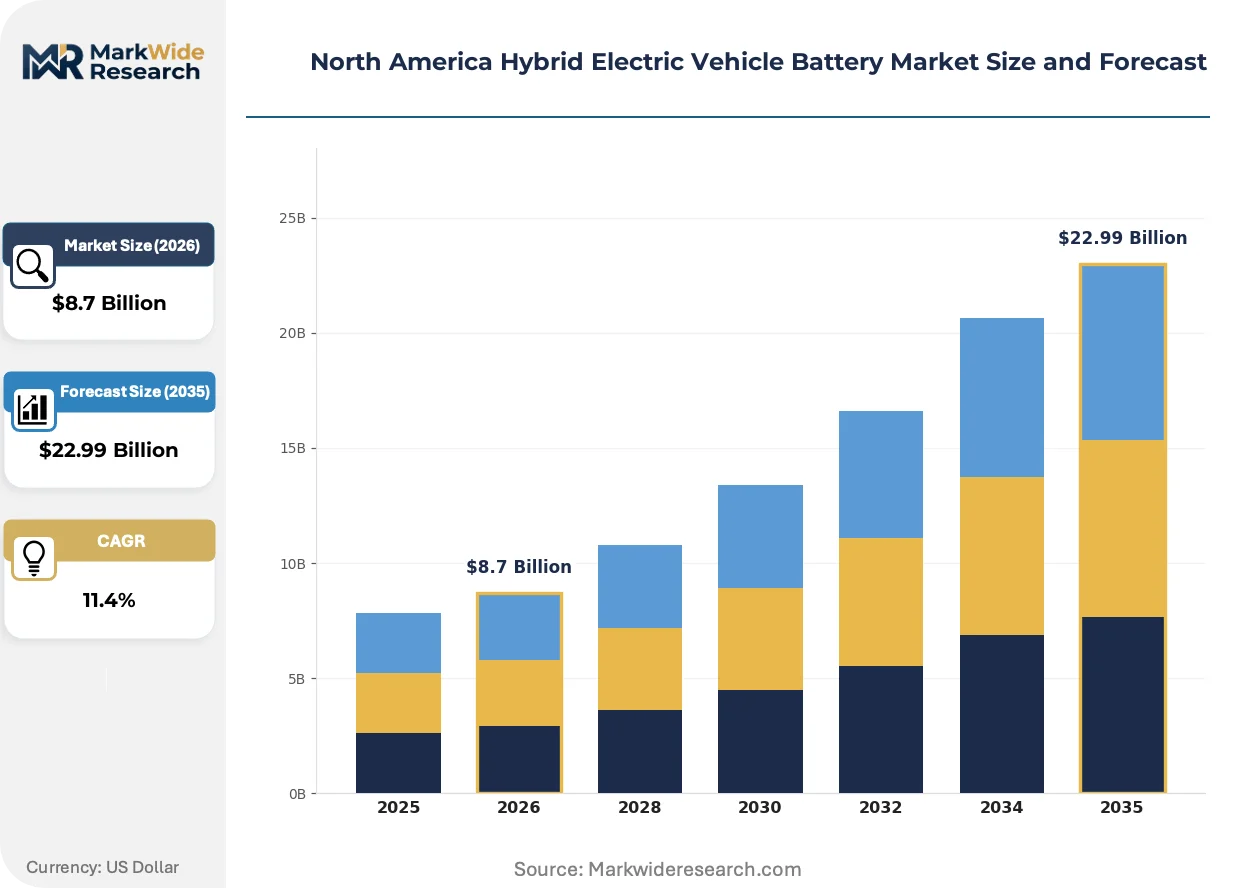
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Li-ion, NiMH, Lead Acid, Solid State Vehicle Type: Passenger Cars, Commercial Vehicles, Two-Wheelers, Buses End User: OEMs, Fleet Operators, Individual Consumers, Government Agencies Integration Level: OEM Integration, Aftermarket Installation, Hybrid Conversion Kits, Battery Swapping |
| Companies Covered | LG Energy Solution, Panasonic Energy Co., Samsung SDI, SK on, Primearth EV Energy, CATL, BYD Company, Toshiba Corporation, Hitachi Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hybrid Electric Vehicle Battery Market Trends and Innovations
Battery intelligence systems are penetrating hybrid platforms as automakers seek predictive degradation modeling to extend warranty periods and reduce residual value risk.
Silicon-anode blending is digitizing energy density optimization in hybrid cell designs. Tier 1 suppliers are adopting 5-10% silicon oxide mixtures in graphite matrices to boost specific capacity without sacrificing cycle life. The structural consequence is digitizing how OEMs simulate range degradation across 150,000-mile warranty windows, compressing validation timelines from 24 months to 14 months.
The US Environmental Protection Agency's tightened MY2027 tailpipe standards are forcing powertrain diversification. Automakers must maintain hybrid offerings alongside battery-electric investments to fleet-average compliance. Full-size pickup and SUV segments face the steepest CO2 reduction requirements, driving disproportionate hybrid battery procurement from Detroit-based OEMs.
Fleet operators are consolidating procurement through direct OEM partnerships rather than dealer networks. Large commercial buyers in California and Texas are negotiating captive supply agreements with guaranteed residual value clauses. This concentration is most visible in rental car and last-mile delivery verticals, where standardized vehicle specifications enable volume commitments exceeding 10,000 units annually.
North America Hybrid Electric Vehicle Battery Market Segmentation
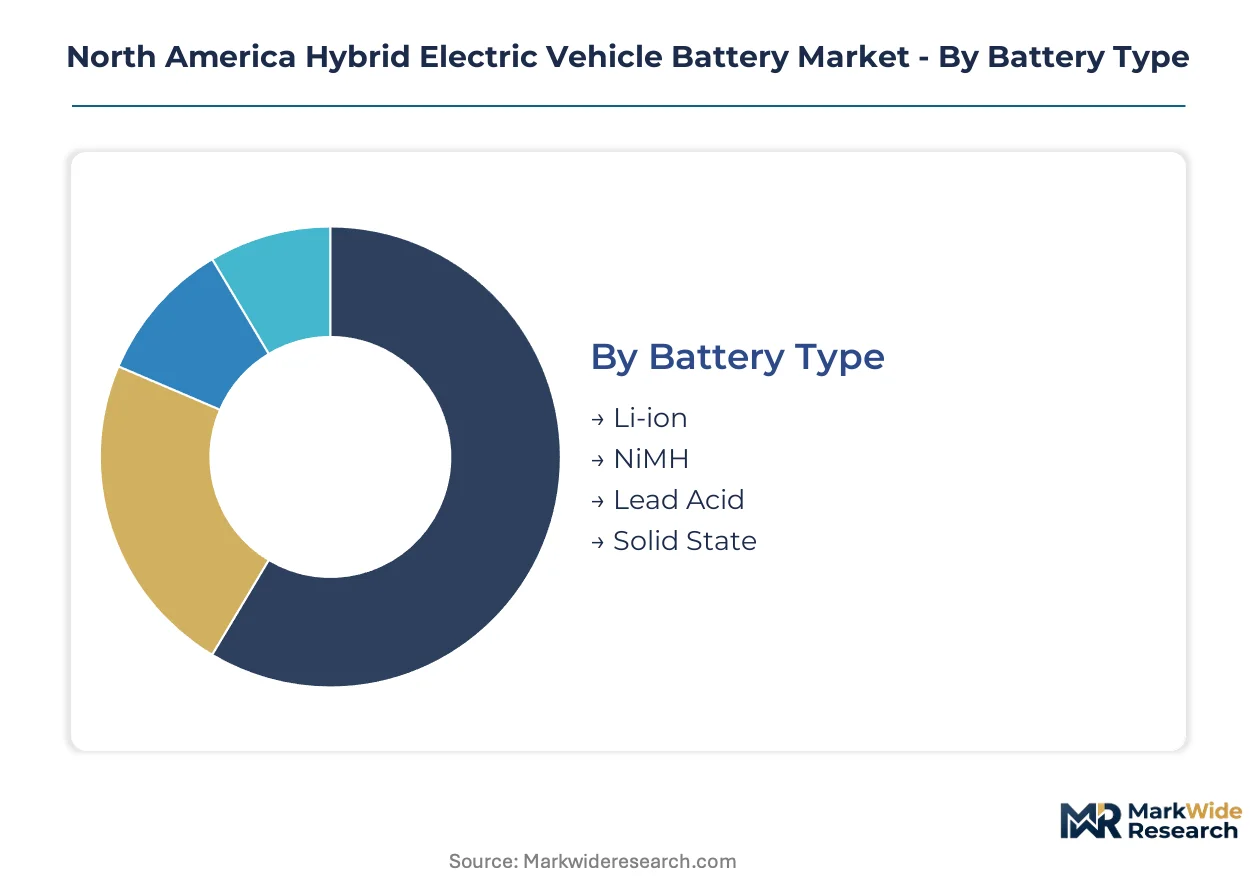
Segmentation in the North America Hybrid Electric Vehicle Battery Market reveals how chemistry choices, vehicle architectures, and procurement channels create distinct margin pools. Each dimension carries regulatory and supply chain implications that reshape supplier qualification requirements.
Battery Type:
Cost tier differentiation separates established chemistries from emerging alternatives, with thermal stability and cobalt exposure driving procurement trade-offs.
- Li-ion:Lithium-ion cells dominate contemporary hybrid designs through nickel-manganese-cobalt and lithium-iron-phosphate formulations. Michigan and Tennessee cell plants supply Detroit automakers under Inflation Reduction Act domestic content rules.
- Solid State:Sulfide-based electrolyte prototypes are advancing toward pilot production with energy density advantages over liquid electrolyte systems. Toyota and QuantumScape development programs in California target commercialization timelines aligned with next-generation hybrid architectures.
- NiMH:Nickel-metal hydride retains cost advantages in mild-hybrid applications where energy density requirements remain modest.
- Lead Acid:Absorbent glass mat designs persist in entry-level hybrid micro-hybrids and auxiliary power units.
Li-ion commands the established base. The steepest expansion runs through Solid State.
Vehicle Type:
Application diversity stretches from high-volume passenger platforms to specialized commercial duty cycles with distinct thermal management requirements.
- Passenger Cars:Compact and mid-size sedans generate the highest procurement volumes as California ZEV mandates compel hybrid compliance bridge strategies. Texas and Michigan assembly plants concentrate OEM integration programs for this segment.
- Commercial Vehicles:Class 2-4 delivery vans and shuttle buses are expanding hybrid adoption as fleet operators negotiate direct supply agreements with residual value guarantees.
- Buses:Transit agencies in California and Texas are procuring hybrid electric drivetrains for fixed-route operations.
- Two-Wheelers:Electric-assist bicycles and low-speed electric motorcycles represent a nascent aftermarket conversion opportunity.
Passenger Cars anchor current procurement volumes. Commercial Vehicles are climbing the fastest as corporate sustainability targets reshape fleet specifications.
End User:
Customer type determines contract structures, with captive OEM supply diverging sharply from aftermarket service economics.
- OEMs:Original equipment manufacturers operate integrated cell qualification programs with direct supplier agreements. Ford, General Motors, and Stellantis battery sourcing decisions in Michigan and Tennessee shape regional production economics.
- Fleet Operators:Rental car and last-mile delivery companies are consolidating procurement through guaranteed volume commitments exceeding 10,000 units annually.
- Individual Consumers:Retail replacement demand concentrates in aging Toyota Prius and Honda Insight vehicles requiring module-level service.
- Government Agencies:Municipal transit authorities and federal fleet managers specify domestic content requirements in public procurement.
OEMs retain pricing power through captive supply structures. Fleet Operators are gaining share fastest through direct partnership models.
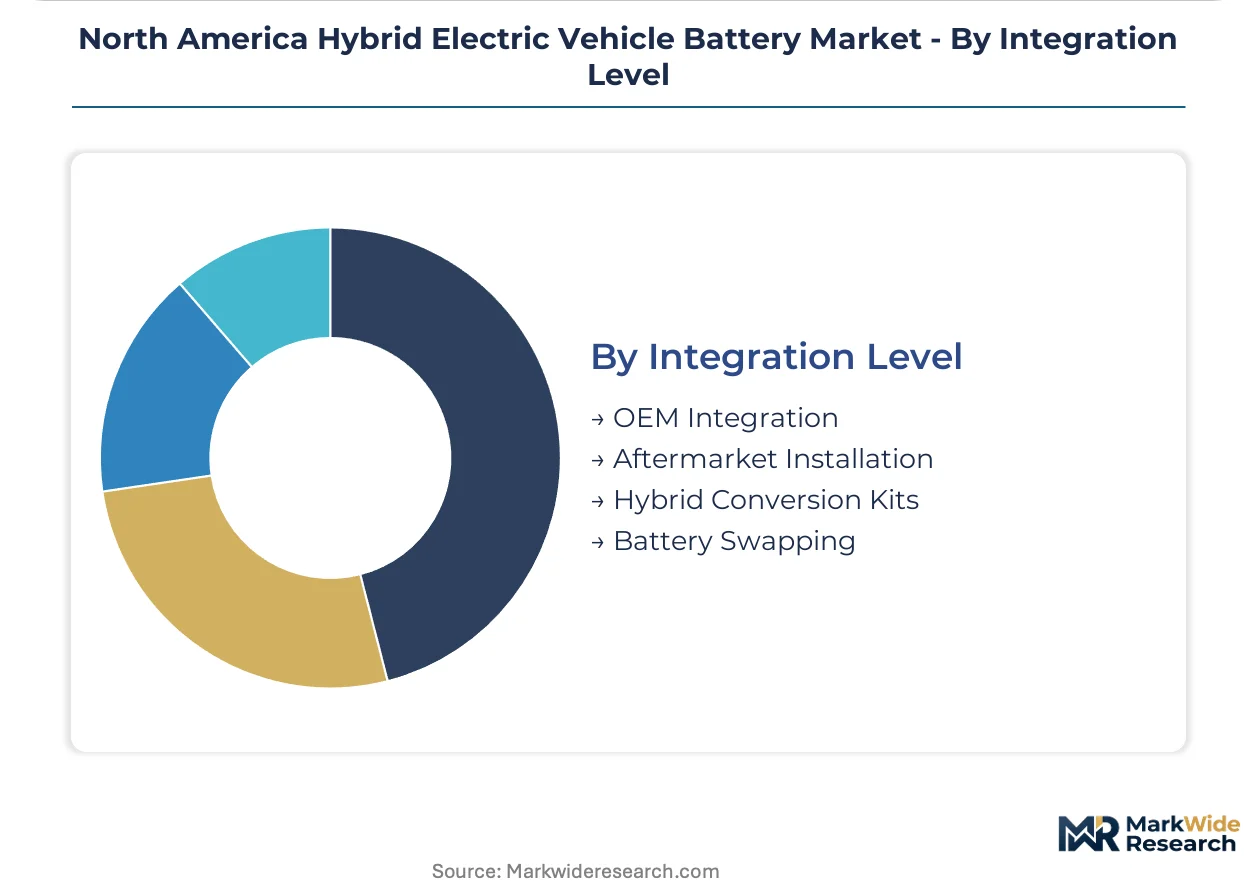
Integration Level:
Supply concentration varies dramatically across factory-integrated systems versus post-sale installation channels with diverging warranty obligations.
- OEM Integration:Factory-installed battery packs carry full vehicle warranty coverage and proprietary battery management system calibration. NHTSA thermal runaway protocols govern crashworthiness certification for these installations.
- Aftermarket Installation:Independent service providers face tightening software access restrictions as OEMs encrypt diagnostic protocols.
- Hybrid Conversion Kits:Retrofit systems for conventional internal combustion platforms remain limited by EPA certification requirements.
- Battery Swapping:Station-based exchange models are piloting in commercial fleet applications with standardized module dimensions.
OEM Integration captures the revenue base. Battery Swapping shows the steepest experimental investment trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California and Texas consume hybrid batteries through passenger car compliance programs, while Michigan absorbs cells through integrated assembly plant supply chains. Canada and Mexico participate through distinct regulatory and manufacturing pathways.
United States
California's Advanced Clean Cars II regulation compels automakers to maintain hybrid offerings as compliance bridge technologies through 2035. The US Inflation Reduction Act's domestic content bonuses compress cell sourcing timelines for Michigan and Tennessee suppliers. Detroit automakers anchor procurement through Ford, General Motors, and Stellantis battery sourcing decisions concentrated in Michigan assembly corridors.
Canada
Ontario's automotive manufacturing base generates hybrid battery demand through Stellantis and Ford assembly operations in Windsor and Oakville. Health Canada and PMRA oversee product safety standards aligned with EPA protocols. Quebec's battery materials processing sector supplies cathode precursor feedstock to North American cell plants.
Mexico
Bajío Region automotive clusters in Guanajuato and Aguascalientes host hybrid vehicle assembly for US market export. Mexico's national environmental regulator SEMARNAT coordinates tailpipe standards with EPA frameworks. Nuevo León's Monterrey metro area attracts tier-one supplier investments serving Texas assembly corridors.
North America Hybrid Electric Vehicle Battery Market Competitive Landscape
Capability concentration sits with cylindrical cell specialists and solid-state researchers; scale advantage sits with integrated conglomerates with captive automotive relationships. The vendor base organizes around three strategic archetypes: Korean-Japanese conglomerates with US manufacturing presence, Chinese producers with cost-optimized LFP platforms, and diversified industrials with materials-to-systems integration. Competitive moves concentrate on Michigan-Tennessee capacity qualification for Inflation Reduction Act compliance and direct OEM partnership structures with residual value guarantees.
Among Korean-Japanese conglomerates, LG Energy Solution, Panasonic Energy Co., and Samsung SDI occupy positions defined by US-based production assets and Detroit automaker supply relationships. These entities exemplify the integrated archetype where manufacturing proximity to Michigan assembly plants shapes qualification timelines. Their positioning reflects the structural premium placed on domestic content compliance under federal incentive frameworks.
| Leading Market Players |
|---|
| LG Energy Solution |
| Panasonic Energy Co. |
| Samsung SDI |
| SK on |
| Primearth EV Energy |
| CATL |
| BYD Company |
| Toshiba Corporation |
| Hitachi Ltd |
| Others |
Pricing and Supply Chain Analysis
Tariff exposure on Asian-sourced cathode active materials determines both pricing tier spreads and supply chain shape across the North American hybrid battery landscape. The Inflation Reduction Act's phased domestic content requirements force OEMs to reconfigure supplier qualification timelines while compressing margin structures for non-compliant cell imports.
Pricing Analysis
Long-term offtake contracts dominate procurement between Detroit automakers and Michigan-based cell producers, with spot market activity limited to cathode precursor feedstock adjustments. Pricing stratifies across premium nickel-manganese-cobalt formulations, standard lithium-iron-phosphate platforms, and economy-grade NiMH alternatives for mild-hybrid applications. Cost compression in the standard tier is intensifying because LFP capacity expansions in Tennessee and Kentucky are saturating regional supply. Fleet operators consolidating through direct OEM partnerships exhibit the lowest price sensitivity, while independent aftermarket service providers face acute margin pressure from encrypted diagnostic protocols.
Supply Chain Analysis
Export control regimes on advanced battery manufacturing equipment limit technology transfer from South Korean and Japanese producers to emerging North American facilities. Cell production draws from Chilean lithium carbonate, Australian spodumene concentrate, and Indonesian nickel sulfate as primary feedstocks. Single-source vulnerability concentrates in cathode active material processing, where Chinese refiners control majority conversion capacity. Distribution runs through just-in-time rail corridors linking Michigan assembly plants to Tennessee cell facilities, with cross-border trucking serving Texas OEM corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation through direct OEM partnerships has shifted procurement leverage toward volume buyers capable of extracting residual value guarantees. This concentration fragments pricing power among cell producers competing for captive supply agreements.
For Market Incumbents: Insulate qualification timelines by securing Inflation Reduction Act-compliant domestic content certification before incentive cliffs take effect. Expand cylindrical cell capacity in Michigan to anchor Detroit automaker platform standardization programs against emerging solid-state substitutes. Deepen backward integration into cathode precursor processing through Quebec materials partnerships to reduce Australian spodumene price volatility exposure. For New Entrants and Emerging Players: Establish a beachhead in second-life stationary storage applications for retired hybrid battery packs, where software-agnostic battery management systems lower OEM control barriers. Target commercial fleet conversion kits in Texas and California corridors where EPA tailpipe compliance deadlines accelerate procurement cycles. Lead with energy-as-a-service subscription models that bundle hardware deployment with predictive degradation monitoring. For Investors and Strategic Acquirers: The market sits at a capacity-qualification phase that favors integrated producers with captive automotive relationships and domestic content certification. Long-term viability over the next decade rests on solid-state electrolyte pilot production timelines and sulfide-based chemistry breakthroughs. Watch NHTSA thermal runaway protocol revisions as the inflection signal that could disqualify liquid electrolyte architectures from next-generation platform sourcing.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Content Certification | Unlocks Inflation Reduction Act tax credits for Michigan and Tennessee cell facilities supplying Detroit automakers. |
| Solid-State Electrolyte Pilot Production | Positions early movers for next-generation hybrid architectures targeting Toyota and QuantumScape commercialization timelines. |
| Direct Fleet Partnership Structures | Captures volume commitments exceeding 10,000 units annually with residual value guarantees from California logistics operators. |
| Cathode Precursor Backward Integration | Reduces exposure to Chilean and Australian concentrate price volatility through Quebec processing joint ventures. |
| Battery Intelligence Platform Deployment | Enables predictive degradation modeling that extends warranty periods and reduces residual value risk for OEM captive finance arms. |
Research Methodology
The analysis maps lithium-ion, solid-state, NiMH, and lead-acid chemistry sub-sectors, each validated through Tier 1 supplier procurement directors, OEM platform engineers, aftermarket service operators, and fleet sustainability officers. Primary fieldwork combined structured interviews with secondary triangulation against SEC filings, EPA certification databases, NHTSA safety protocols, and vehicle production registration data. Bottom-up cell shipment estimates were cross-referenced with top-down OEM platform production schedules across the analysis window.
Assumptions held fixed include Inflation Reduction Act domestic content bonus structures, California Advanced Clean Cars II mandate trajectories, and NHTSA thermal runaway protocol stability. Variables modeled across the projection horizon encompass lithium carbonate price bands, solid-state commercialization timelines, and fleet electrification penetration curves. CAGRs were derived from segmented volume forecasts incorporating vehicle class, propulsion architecture, and regional production cluster dimensions. Industry-specific inputs included cathode chemistry mix shifts and module replacement protocol evolution.
Stress conditions across lithium concentrate supply disruptions, tariff regime adjustments, and solid-state technology breakthrough timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory stability and OEM platform commitment continuity. Material shifts in EPA tailpipe standard stringency or Inflation Reduction Act domestic content phase-in schedules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
Hydrogen Vehicles Market
Hybrid Vehicles
Hybrid Vehicle Market
Hybrid Vehicles
North America Mild Hybrid Vehicles Market
Hybrid Vehicles
Asia-Pacific Micro-Hybrid Vehicles Market
Hybrid Vehicles
United Arab Emirates Hybrid and Electric Vehicles Market
Hybrid Vehicles
Hybrid Electric Self-Driving Car Market
Hybrid Vehicles
India Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Electric Vehicle Market
Hybrid Vehicles
Ignition Systems for Range-Extended Hybrid Powertrains Market
Hybrid Vehicles
Germany Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Europe Mild Hybrid Vehicles Market
Hybrid Vehicles
Crossovers Market
Hybrid Vehicles
Asia-Pacific Mild-Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Drivetrain Market
Hybrid Vehicles
United States Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Global Hybrid-Electric Vehicle Insulation Market