
 North America Micro Hybrid Vehicles Market | 2026-2036
North America Micro Hybrid Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
North America Micro Hybrid Vehicles Market Analytics
Fleet procurement is rebalancing toward passenger vehicles with integrated start-stop systems as corporate sustainability mandates tighten. Ford Motor Company leverages its Dearborn engineering base to sustain hybrid powertrain development for North American light-duty trucks. General Motors anchors its micro hybrid lineup around regenerative braking and DC-DC converter integration across Chevrolet and GMC nameplates. Toyota Motor Company competes through its established battery management expertise transplanted from Prius architecture into cost-optimized stop-start applications.
Micro hybrid vehicles employ internal combustion engines augmented by electric assist systems that enable engine shutdown at idle, kinetic energy recovery during deceleration, and brief torque supplementation without full electrification. Start-stop systems dominate product type revenue by volume, while lithium-ion battery packs command the densest margin pools due to cell chemistry specialization and thermal management requirements. Battery management systems lead technology segment growth as OEMs demand precise state-of-charge algorithms to preserve 48V architecture longevity. Energy recovery systems trail in deployment scale but attract engineering investment for their compatibility with existing platform tooling.
EPA tailpipe standards and NHTSA Corporate Average Fuel Economy mandates shape powertrain development timelines across Detroit Three and transplant OEMs. Transport Canada parallel regulations enforce equivalent CO2 intensity floors, creating unified compliance pressure across the US-Ontario production nexus. Stakeholders must monitor state-level zero-emission vehicle credit trading mechanisms, as California Air Resources Board rules increasingly classify advanced micro hybrids as transitional compliance pathways. The decisive variable remains whether 48V system cost curves flatten fast enough to displace conventional alternator-starter architectures before full battery-electric platforms achieve price parity in compact and mid-size segments.
Market Dynamics
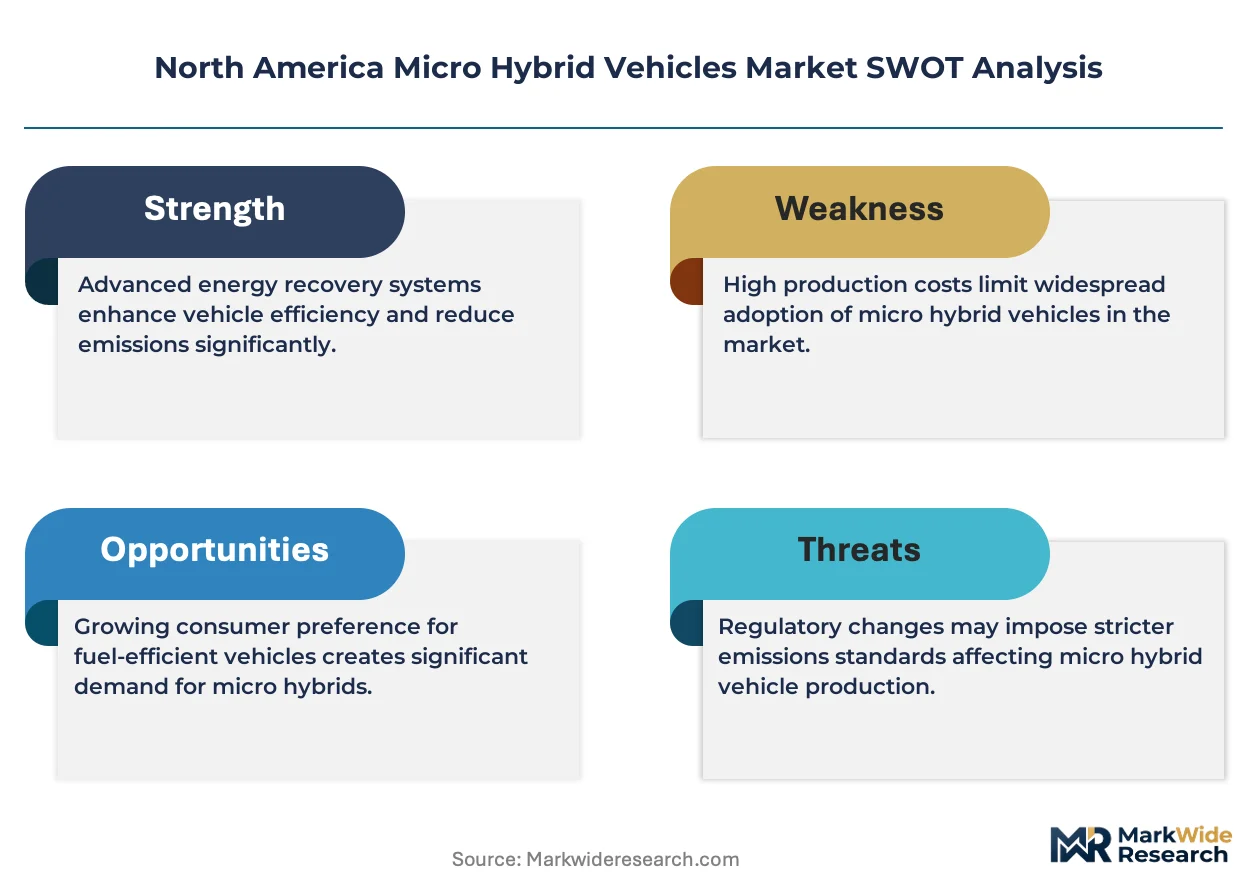
The 48V electrical architecture transition is compressing development cycles across Detroit powertrain engineering centers as OEMs race to replace 12V starter-alternator systems before full electrification reaches cost parity in light-duty segments.
Growth Catalysts
- EPA Tailpipe Standards:NHTSA Corporate Average Fuel Economy mandates force powertrain electrification investments across US and Canadian assembly plants.
- Fleet Electrification Mandates:Corporate sustainability targets at US-based logistics operators accelerate passenger vehicle orders with integrated start-stop capability.
- Lithium-Ion Cell Chemistry:Energy density improvements in 48V battery packs reduce mass penalties and enable broader light-truck deployment.
Market Restraints
- 48V System Cost Premium:DC-DC converters and enhanced starter motors add $800-$1,200 per unit versus conventional architectures, compressing margins on entry trims.
- Battery Supply Concentration:Cell production for automotive 48V applications concentrates in Asian manufacturing corridors, exposing North American OEMs to logistics volatility and tariff exposure.
- Thermal Management Complexity:Lithium-ion packs in engine-bay installations require active cooling loops that add warranty risk and service training costs.
Strategic Opportunities
- Canadian Light-Duty Fleet Conversion:Transport Canada enforcement of parallel CO2 intensity floors creates procurement pull in Ontario and Quebec commercial vehicle segments.
- State-Level ZEV Credit Trading:California Air Resources Board classification of advanced micro hybrids as transitional compliance pathways opens credit arbitrage for OEMs missing pure-electric targets.
- Regenerative Braking Integration:Convergence of brake-by-wire systems with 48V energy recovery enables platform sharing between micro hybrid and full hybrid architectures.
Industry Challenges
- Power Electronics Talent Scarcity:OEM engineering centers in Michigan and Ontario compete for limited pools of DC-DC converter and battery management system specialists.
- Legacy 12V Service Infrastructure:North American dealer networks require recertification investments to diagnose and repair 48V high-voltage subsystems safely.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Micro Hybrid Vehicles Market |
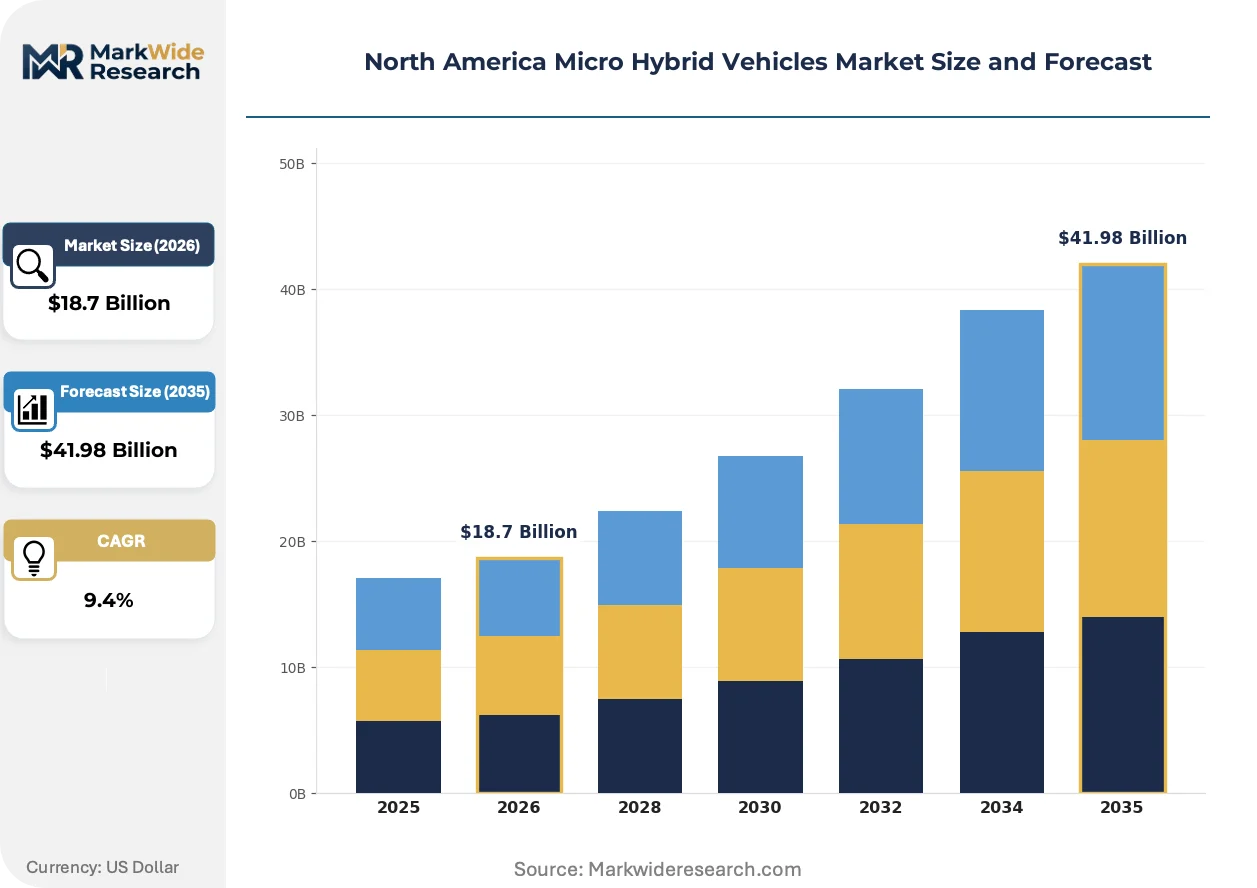
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Start-Stop Systems, Regenerative Braking, Electric Power Steering, Lithium-Ion Batteries Technology: Battery Management Systems, Energy Recovery Systems, DC-DC Converters, Power Electronics End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Fleets Distribution Channel: Online Retail, Dealerships, Independent Garages, OEMs |
| Companies Covered | Toyota Motor Corporation, Ford Motor Company, General Motors Company, Stellantis N.V., BMW Group, Mercedes-Benz Group AG, Hyundai Motor Company, Kia Corporation, Volkswagen Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Micro Hybrid Vehicles Market Evolving Landscape
Powertrain electrification is fragmenting across voltage tiers as OEMs optimize stop-start systems for regulatory compliance without committing to full battery-electric platform costs. Engineering investment concentrates on maximizing kinetic energy recovery within existing internal combustion architectures.
Silicon carbide power semiconductors are overtaking traditional silicon MOSFETs in 48V inverter applications. Tier-1 suppliers serving the Detroit Three have shifted procurement toward SiC devices for their superior switching efficiency and thermal performance. This transition is compressing inverter package sizes and enabling engine-bay integration that 12V systems cannot match.
NHTSA Corporate Average Fuel Economy mandates and EPA tailpipe rules are tightening enforcement timelines for light-duty truck segments. OEM powertrain planners have compressed hybridization roadmaps to secure compliance credits before model year 2030 thresholds. The regulatory pressure is heaviest on full-size pickup platforms where battery-electric range and towing capacity remain cost-prohibitive.
Fleet procurement departments at US-based rental and commercial operators have begun unbundling powertrain specifications from brand loyalty contracts. Procurement teams now issue standalone requests for proposals covering stop-start-equipped mid-size sedans and crossovers. This shift is most visible in Texas and Florida fleet renewals where fuel economy guarantees dominate total cost of ownership calculations.
North America Micro Hybrid Vehicles Market Segmentation
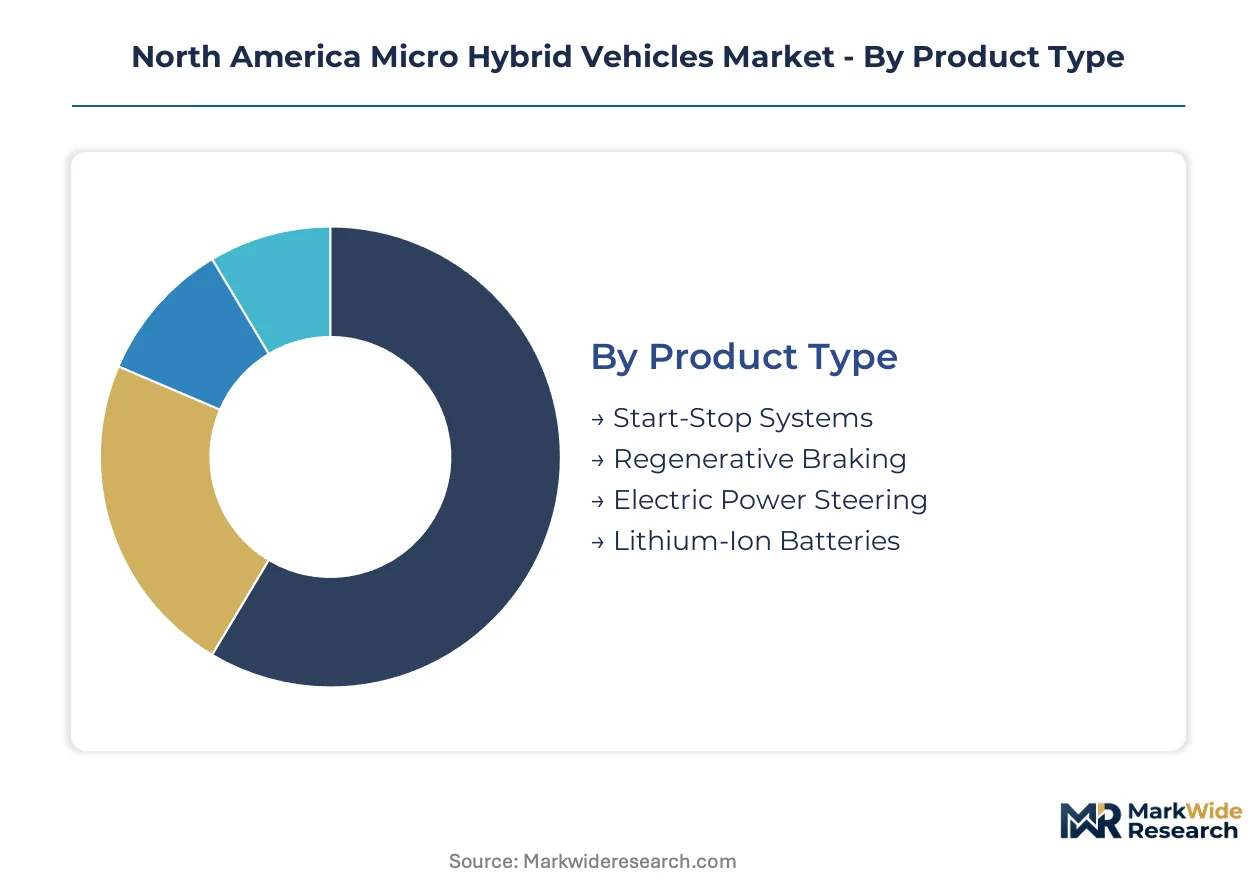
Segmentation in the North America Micro Hybrid Vehicles Market reveals how capital deployment, technical complexity, and regulatory pressure distribute across component tiers and customer channels. Understanding these divisions clarifies where OEMs concentrate engineering resources and where aftermarket opportunities emerge.
Product Type:
Capital intensity varies sharply across this category, with battery cell manufacturing and thermal management systems demanding the heaviest upfront investment.
- Start-Stop Systems:Integrated starter-generators and reinforced pinion gears enable engine shutdown at idle without driver intervention. Demand concentrates in mid-size sedans and crossovers assembled in Michigan and Ohio, driven by NHTSA Corporate Average Fuel Economy compliance timelines for light-duty fleets.
- Lithium-Ion Batteries:48V pouch and prismatic cells with nickel-manganese-cobalt chemistry require cleanroom fabrication and electrolyte filling automation. Ontario-based pack assemblers serve Detroit Three programs, constrained by cell supply concentration in Asian manufacturing corridors and tariff exposure.
- Regenerative Braking:Brake-by-wire modules capture deceleration energy for 48V storage.
- Electric Power Steering:Belt-driven and rack-mounted assist motors reduce parasitic engine load.
Start-Stop Systems absorb the bulk of installed capacity; Lithium-Ion Batteries is expanding most quickly.
Technology:
Margin structures in this category track specialization depth, with firmware-intensive segments commanding premium pricing over commodity hardware.
- Battery Management Systems:State-of-charge algorithms and cell balancing circuits preserve 48V architecture longevity across temperature extremes. Engineering investment clusters in Michigan powertrain centers, pulled by OEM demands for predictive thermal models that reduce warranty risk.
- Power Electronics:Silicon carbide MOSFETs and gate drivers convert DC battery output to three-phase motor current. Texas and California fleet procurement specifications increasingly mandate SiC efficiency guarantees in stop-start-equipped light trucks.
- Energy Recovery Systems:Kinetic capture modules integrate with existing platform tooling.
- DC-DC Converters:Buck-boost architectures bridge 48V and 12V electrical domains.
Battery Management Systems capture the densest margin pools; Power Electronics shows the steepest expansion trajectory.
End User:
Procurement scale determines contract structure, with large fleet operators unbundling powertrain specifications from traditional brand loyalty agreements.
- Fleets:Rental and commercial operators in Texas and Florida issue standalone RFPs for stop-start-equipped vehicles, prioritizing fuel economy guarantees in total cost of ownership calculations. Sustainability mandates at logistics operators accelerate passenger vehicle orders with integrated start-stop capability.
- Passenger Vehicles:Light-duty sedans and crossovers carry the volume base for 48V system cost amortization.
- Commercial Vehicles:Light-truck segments in Ontario and Quebec face Transport Canada CO2 intensity enforcement.
- Two-Wheelers:Motorcycle and scooter applications remain marginal in North American adoption.
Passenger Vehicles anchor volume shipments; Fleets is gaining share fastest.
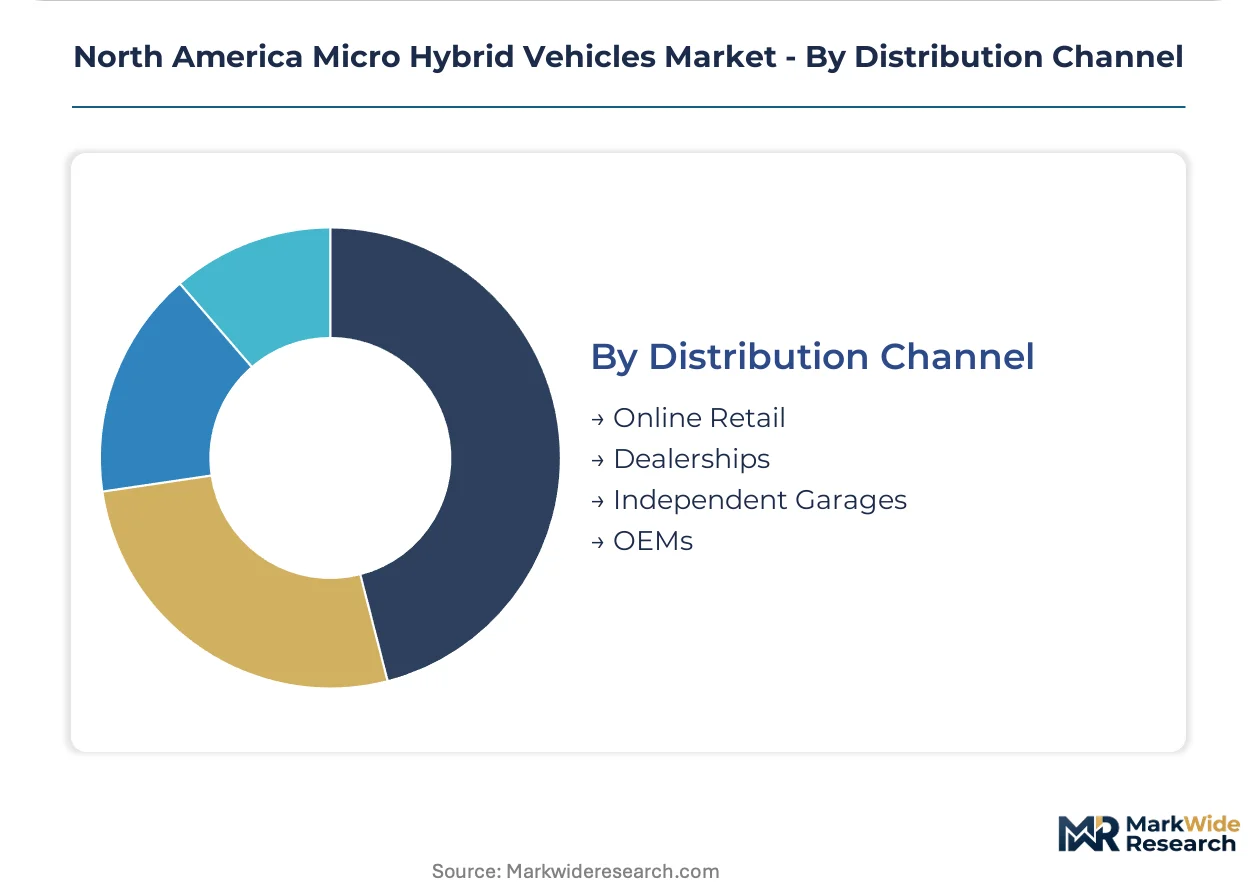
Distribution Channel:
Service complexity shapes channel viability, with high-voltage subsystem repairs requiring specialized training and equipment.
- OEMs:Factory-authorized distribution dominates 48V system warranty coverage and integration calibration. Dearborn and Detroit engineering centers specify proprietary battery management firmware that locks out independent service access.
- Dealerships:Dealer networks require recertification investments to diagnose 48V faults safely under EPA and NHTSA service protocols.
- Independent Garages:Aftermarket access concentrates in 12V legacy systems.
- Online Retail:E-commerce channels carry replacement sensors and low-voltage accessories.
OEMs control the primary installation pathway; Dealerships is climbing fastest as 48V service infrastructure expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Assembly capacity concentrates in the Great Lakes corridor while consumption spreads across coastal fleet operators and Sun Belt commercial buyers. Michigan and Ontario factories feed distribution networks stretching from Texas rental fleets to Quebec logistics hubs. The regional split between production density and dispersed demand shapes inventory logistics and powertrain calibration priorities.
United States
Fleet procurement departments in Texas and Florida issue standalone RFPs for stop-start-equipped sedans and crossovers. EPA tailpipe standards and NHTSA Corporate Average Fuel Economy mandates compress powertrain development timelines for light-duty trucks. Dearborn engineering centers anchor hybrid powertrain development for Ford Motor Company's North American truck lineup.
Canada
Transport Canada enforces CO2 intensity floors equivalent to US EPA standards, creating unified compliance pressure across the US-Ontario production nexus. Commercial vehicle segments in Ontario and Quebec face accelerated procurement timelines for micro hybrid light trucks. Windsor and Oshawa assembly plants serve as export hubs for Detroit Three programs targeting US fleet customers.
Mexico
Automotive manufacturing clusters in Nuevo León and the Bajío Region assemble components for 48V systems serving US-bound vehicle programs. Mexican production facilities benefit from proximity to Texas and California distribution corridors. The country's national environmental regulator enforces progressively tighter emissions standards aligned with US EPA benchmarks.
North America Micro Hybrid Vehicles Market Competitive Landscape
Top-tier vendors anchor the integrated OEM tier, while component specialists and battery pack assemblers occupy supporting positions. The market structure consolidates around vehicle manufacturers with captive powertrain engineering, with Tier-1 suppliers competing for inverter and battery management contracts. Strategic archetypes include full-line OEMs with hybrid heritage, truck-centric domestic manufacturers, and transplant brands leveraging global battery platforms. Competitive moves concentrate on 48V system cost reduction and regenerative braking integration with existing platform tooling.
Within the full-line OEM tier, Toyota Motor Corporation and Ford Motor Company exemplify divergent approaches to micro hybrid architecture. Toyota leverages battery management expertise transplanted from Prius lineage into cost-optimized stop-start applications. Ford anchors its development around light-duty truck segments where towing capacity requirements delay full electrification timelines. General Motors occupies a position between these vectors, integrating DC-DC converters across Chevrolet and GMC nameplates for Corporate Average Fuel Economy compliance.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Ford Motor Company |
| General Motors Company |
| Stellantis N.V. |
| BMW Group |
| Mercedes-Benz Group AG |
| Hyundai Motor Company |
| Kia Corporation |
| Volkswagen Group |
| Others |
Value Network & Pricing Analysis
Power electronics engineering talent concentrated in Michigan and Ontario commands wage premiums that compress margins on entry-tier 48V systems while sustaining pricing spreads between economy and premium micro hybrid configurations.
Pricing Analysis
Margin tightening in economy-tier 48V architectures reflects DC-DC converter and enhanced starter motor cost premiums of eight hundred to twelve hundred dollars per unit above conventional alternator-starter systems. Three-tier pricing structure across premium, standard, and economy levels differentiates primarily by battery cell chemistry grade and thermal management sophistication. Cost compression intensifies as OEMs demand lithium-ion cell cost reductions to offset warranty provisioning for engine-bay installations. Fleet procurement departments in Texas and Florida exhibit highest price sensitivity, prioritizing fuel economy guarantees in total cost of ownership calculations over brand premiums.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Detroit Three assembly plants while Tier-1 distributors serve aftermarket service networks. Cell production for automotive 48V applications concentrates in South Korea, Japan, and China, exposing North American pack assemblers to logistics volatility and tariff exposure. Raw material dependencies center on nickel-manganese-cobalt cathode chemistries, silicon carbide wafers for power semiconductors, and electrolyte formulations with lithium hexafluorophosphate salts. Single-source vulnerability in Asian cell manufacturing corridors represents the dominant structural risk. Distribution runs through just-in-time sequences from Windsor and Oshawa pack integration facilities to Michigan and Ohio vehicle assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell supply concentration in Asian manufacturing corridors props system-level pricing, creating supply-constrained conditions that favor incumbents with locked-in cathode offtake agreements.
For Market Incumbents: Extend backward integration into nickel-manganese-cobalt cathode precursor production to reduce exposure to Asian cell supply volatility. Secure captive supply of silicon carbide wafers through long-term offtake with emerging substrate manufacturers. Battery management system firmware development represents the priority lever for differentiation against transplant OEMs leveraging global platforms. For New Entrants and Emerging Players: The eight-hundred-to-twelve-hundred-dollar premium gap between economy and standard 48V tiers creates white-space for cost-optimized DC-DC converter designs targeting fleet procurement specifications. Target Canadian light-duty commercial segments in Ontario and Quebec where Transport Canada CO2 enforcement accelerates retrofit demand. Pursue direct sales to rental fleet operators unbundling powertrain specifications from traditional brand loyalty contracts. For Investors and Strategic Acquirers: Re-rating potential sits with battery pack assemblers possessing thermal management IP given NHTSA Corporate Average Fuel Economy mandate tightening. Acquisition focus should center on Ontario-based integrators with established Detroit Three program relationships and cleanroom fabrication capabilities. Watch for inflection when 48V system cost curves achieve parity with conventional architectures in compact crossover segments.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Locked cathode offtake with Korean cell producers secures volume for Michigan assembly programs. |
| Platform Standardization | Shared 48V architectures between Chevrolet and GMC nameplates amortize development across light-truck segments. |
| Software-Defined Vehicle Investment | Predictive battery state-of-charge algorithms reduce warranty risk under EPA service protocols. |
| Geographic Manufacturing Footprint | Windsor pack integration expansion serves US-Ontario production nexus compliance timelines. |
| Charging Infrastructure Partnership | Fleet depot electrification alignment positions micro hybrids as transitional compliance pathways. |
Research Methodology
Document review covered vehicle production databases, IHS Markit registration data, EPA certification filings, and NHTSA fuel economy reports, complemented by interviews with OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors, and dealership service operations. Primary fieldwork with powertrain engineering centers in Dearborn, Detroit, and Windsor informed 48V system cost structure assessments. Secondary validation drew from SEC automotive segment disclosures, Transport Canada CO2 intensity compliance records, and lithium-ion cell trade flow analysis. Bottom-up build-ups of 48V content per vehicle were cross-referenced against top-down OEM revenue segmentation.
Historical production volumes were benchmarked against expert panel inputs from Michigan and Ontario engineering centers. Segmentation modeling spanned vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived through regression analysis of technology cost curves against regulatory compliance timeline pressure. Industry-specific forecast inputs included silicon carbide device adoption rates and fleet procurement specification unbundling trends.
Inputs from OEM platform engineering centers and Tier-1 supplier procurement teams were available through the study window; gaps in cell manufacturer cost disclosure introduce uncertainty bands around 48V system price parity projections. Forecasts reflect assumptions regarding NHTSA enforcement timelines and lithium-ion cell chemistry cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
India Hybrid Vehicles Market
Hybrid Vehicles
Plug-In Hybrid Electric Vehicles (PHEV) Market
Hybrid Vehicles
Middle East and Africa Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Hydrogen Vehicles Market
Hybrid Vehicles
North America Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Hybrid Drivetrain Market
Hybrid Vehicles
Hybrid Electric Vehicle Market
Hybrid Vehicles
High-Voltage Hybrid Vehicle Market
Hybrid Vehicles
Global Hybrid-Electric Vehicle Insulation Market
Hybrid Vehicles
Electric and Hybrid Vehicles Driveline Market
Hybrid Vehicles
United Arab Emirates Hybrid and Electric Vehicles Market
Hybrid Vehicles
Canada Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Smart Hybrid Vehicle Market
Hybrid Vehicles
Crossover Vehicle Market
Hybrid Vehicles
Germany Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Asia-Pacific Micro-Hybrid Vehicles Market