
 Hypercar Market | 2026-2036
Hypercar Market Size, Share, and Industry Trends Forecast 2026-2036
Hypercar Market Analysis
The gap between electrified hypercars and traditional internal combustion flagships is shifting from powertrain philosophy to regulatory survival. Ferrari leverages its motorsport heritage to sustain brand premiums across hybrid architectures. Rimac anchors the electric frontier with in-house battery and powertrain integration. Koenigsegg differentiates through proprietary transmission technologies and extreme lightweight engineering.
A hypercar represents an ultra-low-volume, road-legal performance vehicle engineered for top speeds exceeding 350 km/h, typically constructed from carbon fiber monocoques with power-to-weight ratios above one horsepower per kilogram. These machines serve dual commercial purposes: as brand halo assets that elevate corporate technology credentials and as collectible instruments for capital preservation among elite buyers. The product type dimension shows electric architectures capturing the fastest expansion as battery energy density improves, while internal combustion variants retain scarcity premiums among collectors. Material segmentation reveals carbon fiber dominating structural applications for its specific strength, with titanium gaining ground in exhaust and suspension components where thermal tolerance matters.
The EU Green Deal and F-Gas Regulation constrain internal combustion development timelines, while EPA tailpipe standards in the United States and China's dual carbon goals under MEE oversight reshape powertrain investment calendars across manufacturers. NHTSA crashworthiness exemptions for low-volume producers in the United States create asymmetric compliance burdens that favor established specialists with dedicated homologation teams. Stakeholders must monitor how regulatory phase-out dates for combustion engines interact with residual value expectations in the collector economy.
Market Dynamics
The EU Green Deal's combustion phase-out timeline is compressing development calendars and forcing powertrain portfolio rebalancing across legacy specialists and electric entrants alike. Manufacturers now face parallel engineering tracks for regulatory compliance and collector value preservation.
Growth Catalysts
- Battery Energy Density Gains:Solid-state cell architectures are extending electric range thresholds toward parity with liquid-fuel equivalents. This unlocks new buyer segments previously anchored to refueling infrastructure.
- UAE Zero-Tax Import Regimes:Sovereign wealth-linked collectors in Dubai and Abu Dhabi deploy capital into limited-production assets without friction costs. This sustains exceptional per-capita absorption rates unmatched elsewhere.
- Carbon Fiber Monocoque Maturation:Automated fiber placement and out-of-autoclave curing are collapsing production cycle times. Specialist coachbuilders now achieve structural yields previously reserved for aerospace applications.
Market Restraints
- Lithium-Ion Supply Concentration:Cathode precursor refining clusters in the Democratic Republic of Congo and Indonesia create single-point vulnerabilities for cell manufacturers.
- NHTSA Low-Volume Exemption Asymmetry:The United States crashworthiness waiver system favors established homologation teams, erecting barriers for new entrants lacking dedicated compliance infrastructure.
- Titanium Input Volatility:Sponge pricing swings and Russian supplier exclusion are destabilizing exhaust and suspension component cost models.
Strategic Opportunities
- Saudi Arabia Giga-Project Integration:NEOM and Qiddiya developments are embedding automotive experience centers that create captive demand pipelines for ultra-luxury vehicles.
- Vehicle-to-Grid Bi-Directional Charging:Hypercar battery packs are absorbing second-life stationary storage applications. This extends asset utility beyond mobility into energy arbitrage.
- EU Battery Passport Mandates:Digital traceability requirements under the EU Green Deal are creating premium tiers for verified ethical sourcing. Early compliance captures scarcity premiums.
Industry Challenges
- Composite Repair Technician Scarcity:Carbon fiber damage assessment and restoration require specialized labor pools concentrated in motorsport hubs. Geographic mismatch with owner bases creates service friction.
- Homologation Parallel Track Costs:Simultaneous EPA, EU type-approval, and China MIIT certification demands duplicate testing fleets. Capital intensity rises without volume amortization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypercar Market |
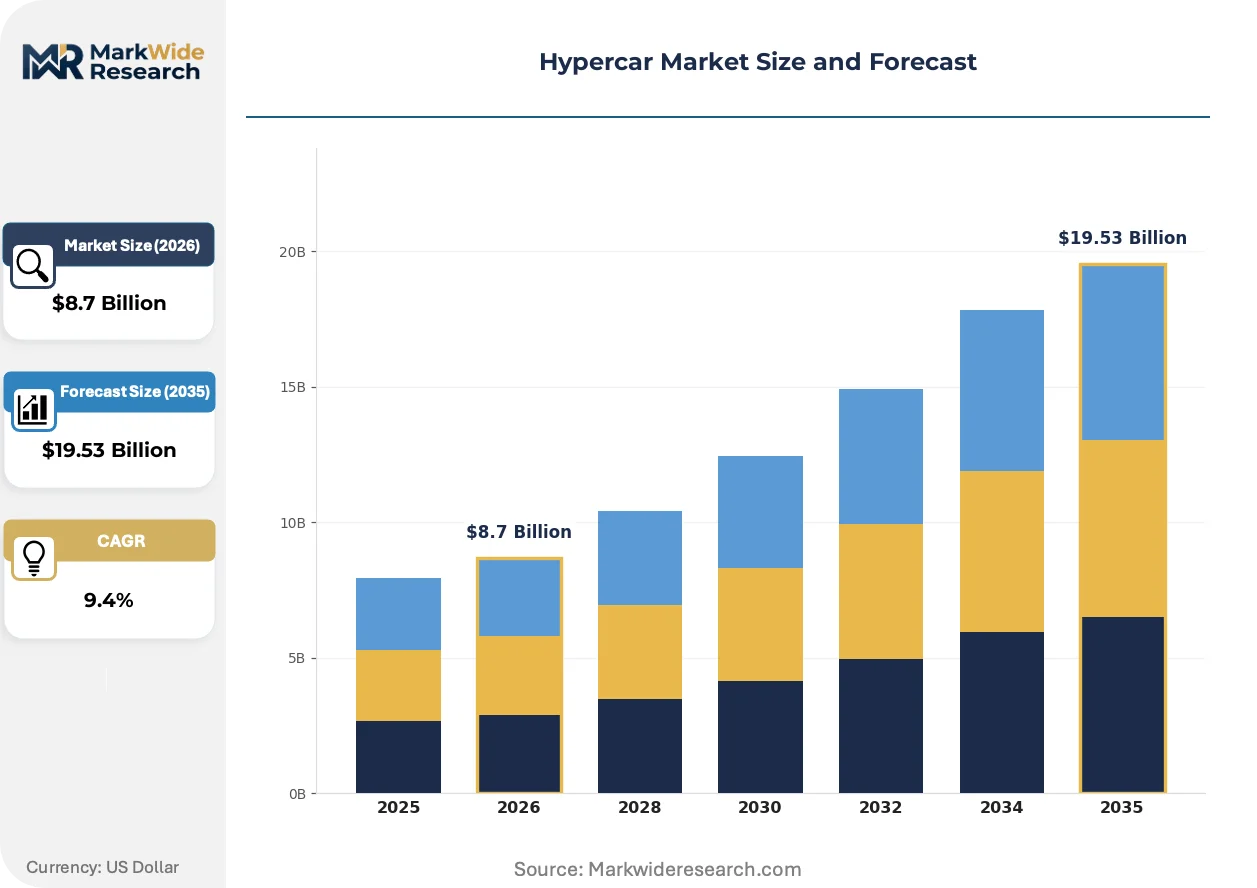
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid, Electric, Internal Combustion, All-Wheel Drive Performance Attribute: Top Speed, Acceleration, Horsepower, Torque Material: Carbon Fiber, Aluminum, Titanium, Composite Customer Type: Enthusiasts, Investors, Collectors, Track Users |
| Companies Covered | Ferrari, Aston Martin, Bugatti, Rimac, Porsche, Koenigsegg, McLaren, Mercedes-AMG, Pagani, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypercar Market Emerging Trajectories
Powertrain architecture decisions are migrating from engineering preference to regulatory survival calculus. Material science advances and digital ownership models are simultaneously reshaping production economics and collector engagement.
Solid-state battery chemistry is absorbing the thermal management burden previously handled by liquid cooling loops. Rimac and emerging specialists are integrating ceramic electrolyte cells into 800-volt architectures. This is absorbing the packaging volume and weight penalties that constrained earlier electric hypercar designs.
The EU F-Gas Regulation is prohibiting refrigerants with global warming potential above 150 in new vehicle climate systems. Manufacturers are retrofitting CO2-based heat pumps and redesigning thermal loops. European-bound production lines face the steepest retooling schedules, with compliance deadlines compressing development windows.
Collector buyers are fragmenting across direct manufacturer allocation systems and curated auction platforms. Traditional dealer networks are losing intermediation power in limited-production releases. This rotation is most visible in the United Arab Emirates, where sovereign-linked purchasers negotiate bilateral factory relationships bypassing retail channels entirely.
Hypercar Market Segmentation
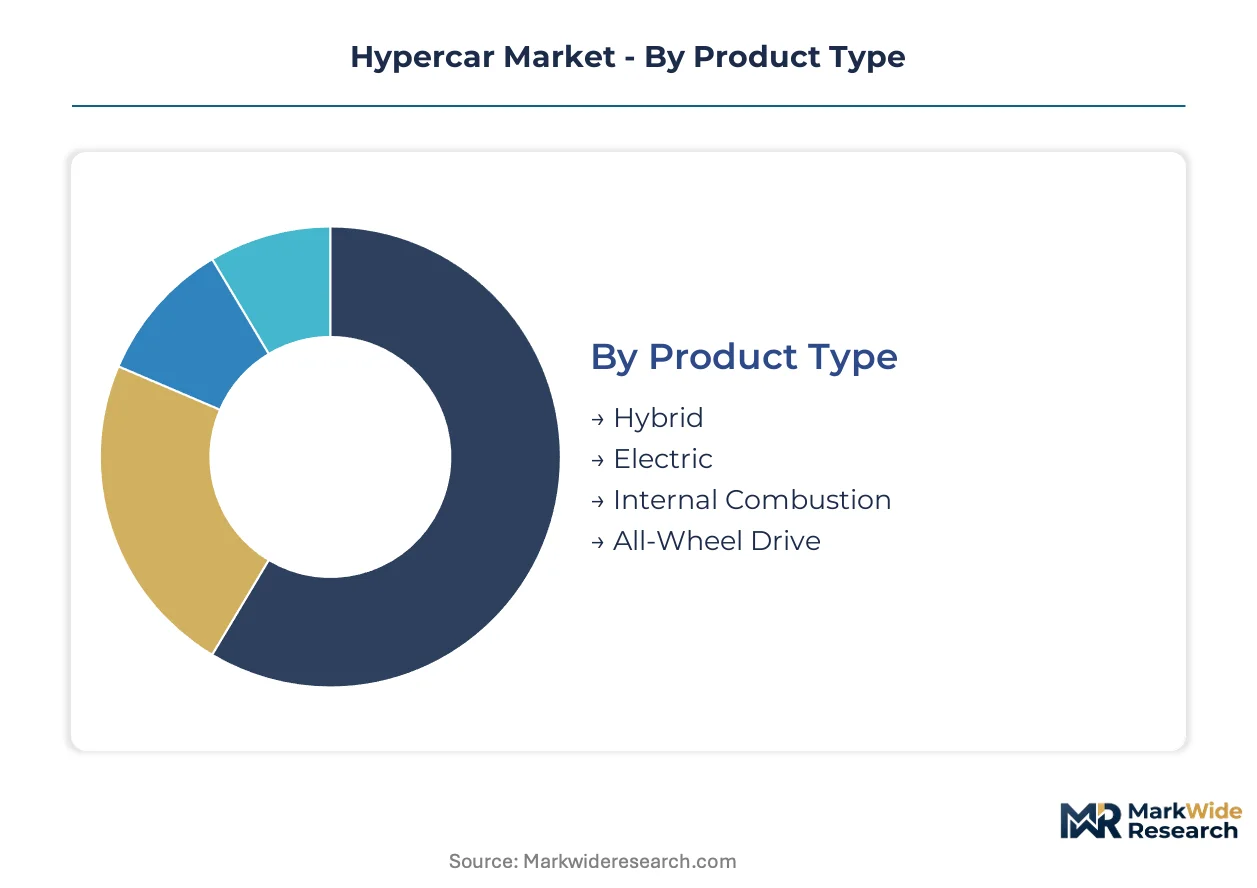
Hypercar segmentation reveals how engineering priorities fragment across divergent buyer motivations. Technical specifications, material choices, and ownership purpose each create distinct value architectures that manufacturers must navigate simultaneously.
Product Type:
Powertrain architectures sit on a spectrum from legacy combustion systems to fully integrated electric platforms, with hybrid configurations bridging operational philosophies.
- Hybrid:Combines internal combustion with electric assist for torque fill and emissions compliance. Ferrari and McLaren deploy this architecture to preserve acoustic signatures while meeting EU fleet standards. Demand concentrates in European markets where transitional powertrains satisfy collector expectations and regulatory thresholds simultaneously.
- Electric:Battery-dominant architectures with 800-volt charging and solid-state cell integration. Rimac and emerging specialists anchor development here. The UAE and Saudi Arabia absorb early production as sovereign-linked buyers prioritize technology signaling over heritage resonance.
- Internal Combustion:Naturally aspirated or forced-induction engines without electrification assist. Scarcity premiums sustain demand among collectors seeking terminal-production assets before EU phase-out deadlines.
- All-Wheel Drive:Multi-motor or mechanical torque-vectoring systems optimizing traction for sub-2.5-second acceleration benchmarks. Track-focused buyers in Germany and Japan specify this configuration for launch consistency.
Hybrid architectures lead volumes today; electric configurations are gaining share fastest as battery density thresholds cross usability thresholds.
Performance Attribute:
Specification hierarchies reflect whether buyers prioritize measurable metrics or experiential qualities, with marketing emphasis shifting by geography.
- Top Speed:V-max figures exceeding 400 km/h serve as headline specifications for Middle Eastern and American collectors. Koenigsegg and Bugatti compete here. Desert highway infrastructure in the UAE and Nevada test tracks enable validation claims that European road networks cannot support.
- Acceleration:Zero-to-100 km/h times below 2.5 seconds, enabled by instant electric torque delivery. Rimac and Tesla Roadster competitors target this metric. Asian markets, particularly South Korea and China, weight acceleration more heavily than top speed in purchase decisions.
- Horsepower:Power output figures above 1,000 hp function as comparative currency in collector circles. Internal combustion flagships retain bragging rights here as electric rivals normalize four-digit outputs.
- Torque:Instantaneous twist delivery from electric motors redefines drivability expectations. Track users in the UK and Germany specify torque-vectoring systems for corner-exit control.
Top speed specifications anchor current marketing; acceleration metrics are climbing fastest as electric architectures democratize sub-2-second performance.
Material:
Structural and component material selections trade cost, repairability, and specific strength against thermal and acoustic performance requirements.
- Carbon Fiber:Automated fiber placement and out-of-autoclave curing now achieve aerospace-grade specific strength. Monocoque construction dominates structural applications across all manufacturers. Repair technician scarcity in secondary markets creates service friction for owners outside motorsport hubs.
- Aluminum:Cast and extruded alloys persist in suspension subframes and crash structures where ductility matters. Cost efficiency sustains use in higher-volume limited editions from established specialists.
- Titanium:Exhaust systems and suspension fasteners exploit thermal tolerance and strength-to-weight ratios. Russian supplier exclusion and sponge pricing volatility are destabilizing input cost models for European manufacturers.
- Composite:Glass and natural fiber hybrids appear in non-structural panels seeking weight reduction without carbon fiber cost burdens. Emerging specialists experiment here for differentiation.
Carbon fiber leads structural applications today; titanium components are expanding fastest as thermal management demands intensify in hybrid powertrains.
Customer Type:
Buyer taxonomy separates those acquiring vehicles for use value from those treating machines as financial instruments or cultural signifiers.
- Enthusiasts:Owner-operators prioritizing driving engagement and mechanical authenticity. Manual transmissions and naturally aspirated engines retain disproportionate preference here. Concentrated in Germany, Japan, and the UK where road infrastructure supports sustained high-speed operation.
- Investors:Buyers treating limited-production slots as alternative assets with appreciation expectations. Allocation systems and factory-direct relationships bypass traditional retail channels. Sovereign wealth-linked purchasers in the UAE and Saudi Arabia dominate this segment.
- Collectors:Acquisition driven by provenance, serial number scarcity, and brand heritage narratives. Garage queens with minimal mileage command premiums at curated auction platforms.
- Track Users:Buyers specifying circuit-focused configurations with roll cages, fire suppression, and telemetry systems. Nürburgring lap time validation carries particular weight in German and American purchase decisions.
Investor-type buyers lead transaction values today; track-oriented specifications are gaining share fastest as experience centers at Qiddiya and similar developments create captive demand pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Arab Emirates absorbs hypercars at per-capita rates that dwarf Germany's volume, while Saudi Arabia's sovereign wealth deployment is redirecting regional allocation patterns entirely. Collector capital concentrates where tax regimes eliminate friction and infrastructure supports validation claims.
United Arab Emirates
Sovereign wealth-linked buyers in Dubai and Abu Dhabi negotiate bilateral factory relationships that bypass retail channels entirely. MOHAP vehicle registration frameworks accommodate low-volume imports without homologation delays. The Dubai Autodrome and Yas Marina Circuit clusters sustain track-day cultures that validate performance specifications.
Germany
The KBA enforces EU type-approval standards that compress development calendars for combustion-dependent specialists. Nürburgring lap time validation carries particular weight in purchase decisions across Baden-Württemberg and Bavaria. Stuttgart's engineering ecosystem supplies precision components to established homologation teams.
United States
NHTSA low-volume crashworthiness exemptions favor manufacturers with dedicated compliance infrastructure in California and Nevada. Desert highway infrastructure enables top-speed validation claims that European road networks cannot support. Los Angeles and Miami serve as allocation gateways for Latin American collector networks.
China
MIIT certification demands and MEE dual carbon goals are reshaping powertrain investment calendars for European entrants targeting Shanghai and Beijing buyers. State-backed industrial policy channels battery supply chain dominance toward domestic champions. Shenzhen's electronics ecosystem feeds telematics and infotainment integration.
United Kingdom
Manual transmission preferences and naturally aspirated engine demand persist among enthusiast owner-operators concentrated in the Home Counties. Historic motorsport heritage anchors brand narrative value for allocation systems targeting Middle Eastern investors. Silverstone and Goodwood clusters sustain specialized carbon fiber repair technician pools.
Hypercar Market Vendor Landscape
Top-tier vendors anchor heritage-brand positioning, while electric entrants and boutique specialists occupy differentiated tiers beneath. The competitive structure fragments across legacy combustion specialists, battery-native platforms, and ultra-low-volume coachbuilders. Three archetypes dominate: motorsport-heritage houses leveraging racing pedigree, technology-integrators controlling in-house powertrain development, and lightweight-engineering boutiques pursuing extreme specific-strength ratios. Parallel moves include regulatory compliance acceleration and collector allocation system digitization.
Within the heritage-motorsport tier, Ferrari, Porsche, and McLaren exemplify brand-premium preservation across hybrid architectures. Rimac anchors the battery-native specialist position. Koenigsegg occupies the extreme lightweight-engineering boutique segment. These three archetypes represent divergent responses to EU Green Deal phase-out timelines: heritage houses bridge combustion and electric portfolios, technology-integrators bet entirely on solid-state cell maturation, and boutiques optimize power-to-weight ratios regardless of powertrain philosophy.
| Leading Market Players |
|---|
| Ferrari |
| Aston Martin |
| Bugatti |
| Rimac |
| Porsche |
| Koenigsegg |
| McLaren |
| Mercedes-AMG |
| Pagani |
| Others |
Supply Flow & Price Mechanics
Sovereign wealth-linked collectors in the United Arab Emirates and Saudi Arabia anchor demand for allocation-based purchasing models where factory-direct relationships bypass retail intermediaries entirely. This buyer concentration sustains premium capture for manufacturers while compressing price transparency for secondary market participants.
Pricing Analysis
Factory-direct allocation systems separate bundled after-sales service packages from unbundled vehicle transactions. Pricing stratifies across heritage-combustion, hybrid-transitional, and electric-native tiers with differentiation driven by powertrain certification status and carbon fiber monocoque construction method. Cost compression in titanium-intensive exhaust components is intensifying because Russian sponge supplier exclusion has destabilized input markets. Track-oriented buyers in Germany exhibit highest price sensitivity; UAE sovereign-linked investors show least.
Supply Chain Analysis
EU Battery Passport mandates and MIIT certification requirements in China are gating supplier qualification for cell manufacturers and carbon fiber prepreg specialists. Cathode precursor refining concentrates in Indonesia and the Democratic Republic of Congo, while automated fiber placement equipment sources from Germany and Japan. Single-source vulnerability in solid-state electrolyte ceramic substrates threatens electric powertrain ramp schedules. Distribution runs through manufacturer-controlled allocation systems rather than dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hypercar market compounds steadily as ultra-high-net-worth individual allocations into tangible automotive assets intensify across Middle Eastern and Asian wealth centers.
For Market Incumbents: To counter electric-native specialist technology signaling, heritage manufacturers should deepen in-house battery cell integration partnerships and secure carbon fiber prepreg backward integration. Ferrari and Porsche must accelerate solid-state powertrain roadmaps while preserving combustion heritage narratives for collector value preservation. For New Entrants and Emerging Players: EU Green Deal F-Gas Regulation compliance deadlines open a window for CO2 heat pump thermal management specialists to penetrate European-bound production lines. White-space targets include titanium-alternative exhaust materials and out-of-autoclave curing equipment for carbon fiber repair networks. Go-to-market through Qiddiya and NEOM experience center partnerships captures Saudi sovereign capital deployment. For Investors and Strategic Acquirers: Battery-electric platform specialists are the most active acquirer in this space, consolidating solid-state cell startups and carbon fiber recycling technology. Long-term viability frames around powertrain architecture transition completion and residual value algorithm development for collector markets. Watch NHTSA low-volume exemption policy evolution as inflection signal for new entrant viability.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Battery Integration | Rimac and heritage houses absorb thermal management packaging penalties through ceramic electrolyte cell architectures. |
| Carbon Fiber Repair Network Expansion | Specialized technician pools concentrated in Silverstone and Goodwood clusters reduce service friction for global owners. |
| Factory-Direct Allocation Digitization | Bilateral UAE sovereign purchaser relationships bypass retail channels and capture scarcity premiums. |
| CO2 Heat Pump Thermal Retrofit | EU F-Gas Regulation compliance drives climate system redesign for European-bound production lines. |
| Vehicle-to-Grid Bi-Directional Capability | Hypercar battery packs extend asset utility into stationary storage and energy arbitrage applications. |
Methodological Framework
Bottom-up collector allocation modeling reconciled against top-down powertrain production tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, sovereign wealth vehicle acquisition advisors, and carbon fiber repair network operators combined with secondary validation from vehicle registration databases, customs import records, EU type-approval filings, and MIIT certification disclosures. Triangulation across these sources ensures segmentation integrity.
Input-output matrices map powertrain architecture transitions, material composition shifts, and regional absorption patterns across the projection horizon. Segmentation dimensions include propulsion type, performance attribute hierarchy, structural material, and customer archetype. CAGRs derive from regression analysis of historical allocation velocity against battery energy density improvement curves and regulatory phase-out timelines. Forecast inputs incorporate solid-state cell commercialization schedules and titanium sponge price volatility indices.
Revisions become necessary when EU Green Deal implementation timelines accelerate, NHTSA exemption thresholds shift, or solid-state battery manufacturing yields diverge from baseline assumptions. A model refresh is warranted upon material change in sovereign wealth deployment patterns into automotive tangible assets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
Hybrid Powertrain Systems Market
Hybrid Vehicles
United States Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Plug-In Hybrid Electric Vehicles (PHEV) Market
Hybrid Vehicles
High-Voltage Hybrid Vehicle Market
Hybrid Vehicles
Hybrid Electric Vehicle Market
Hybrid Vehicles
North America Micro Hybrid Vehicles Market
Hybrid Vehicles
Crossover Vehicle Market
Hybrid Vehicles
Hybrid Train Market
Hybrid Vehicles
Smart Hybrid Vehicle Market
Hybrid Vehicles
Hybrid Cars Market
Hybrid Vehicles
United Arab Emirates Hybrid and Electric Vehicles Market
Hybrid Vehicles
Crossovers Market
Hybrid Vehicles
Germany Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
North America Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Global Hybrid Vehicle Transmission Market
Hybrid Vehicles
Mild Hybrid Vehicles Market