
 Micro-Hybrid Vehicle Market | 2026-2036
Micro-Hybrid Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Micro-Hybrid Vehicle Market Analysis
Project finance tied to fleet decarbonization mandates is tilting competitive access toward asset-light mobility providers and away from pure retail-centric OEMs. Toyota Motor Corporation leverages its hybrid powertrain manufacturing scale to dominate start-stop integration costs. BMW AG differentiates through regenerative braking software calibrated for premium sedan platforms. Hyundai Motor Company anchors its position with petrol micro-hybrid variants priced for mass-market hatchback penetration.
Micro-hybrid vehicles integrate a start-stop system with a small electric motor and battery pack to recover braking energy and eliminate idle fuel burn, typically operating at 12V or 48V electrical architecture without full electric-only propulsion capability. The primary purpose is to reduce urban fuel consumption and CO2 emissions in cost-sensitive vehicle classes where full hybridization remains economically prohibitive. Start-stop systems capture the largest installed base among components, while regenerative braking hardware commands the fastest growth as 48V architectures spread. Sedan and SUV vehicle types concentrate current volume, though hatchback demand accelerates in dense Asian and European cities where parking constraints favor compact footprints.
The EU Green Deal and F-Gas Regulation constrain refrigerant and battery thermal management chemistries, while EPA fuel economy standards in the United States shape powertrain calibration targets for export-bound models. India's BIS energy labeling and PLI scheme for advanced automotive technology create localized incentive structures for domestic micro-hybrid assembly. Stakeholders must monitor how regulator convergence on real-driving emissions testing reshapes component durability specifications and warranty cost structures.
Market Dynamics
The 48V electrical architecture migration is compressing cost premiums for regenerative braking systems, forcing incumbent 12V start-stop suppliers to defend installed base through software-enabled efficiency claims.
Growth Catalysts
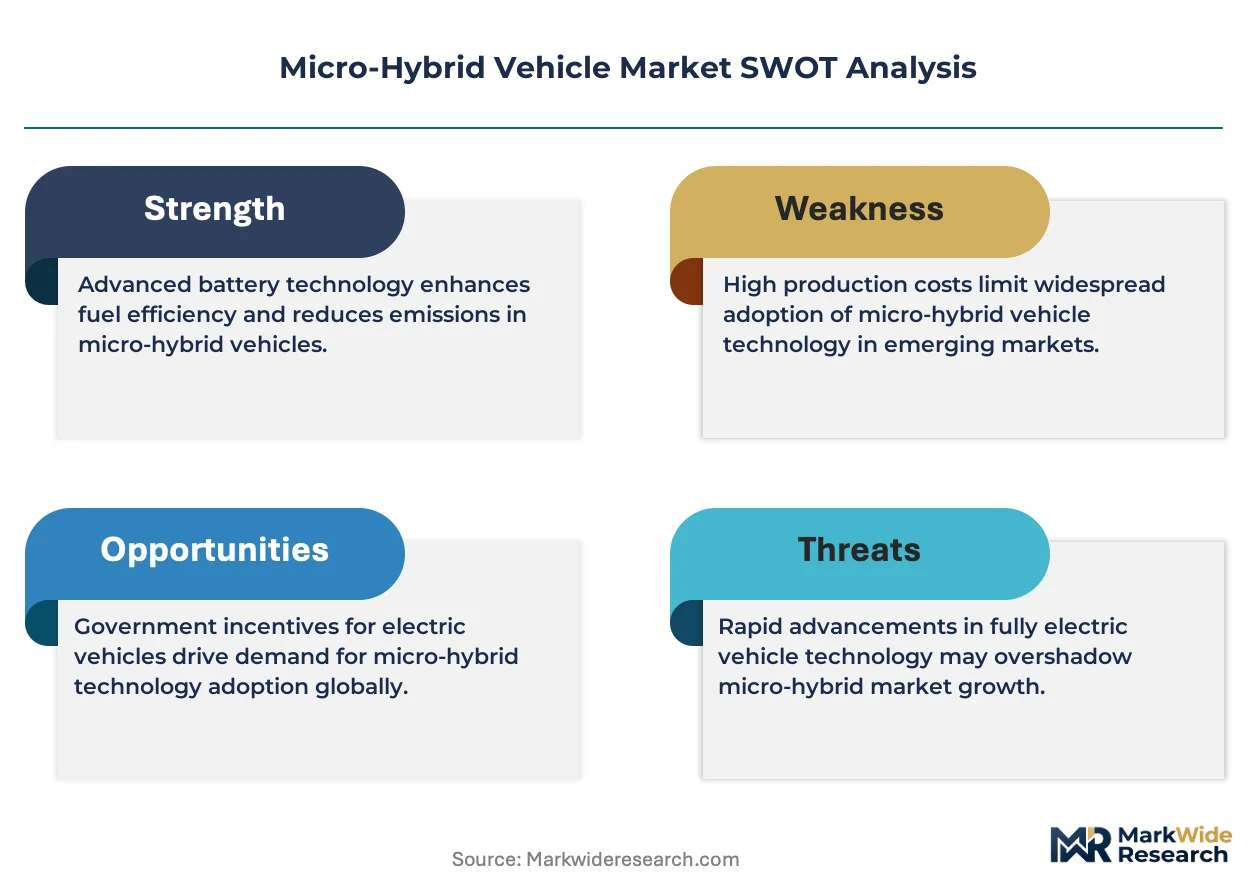
- EU Green Deal fleet mandates:Corporate vehicle procurement rules in Germany and France now penalize pure internal combustion engines, channeling fleet renewal budgets toward micro-hybrid powertrains.
- India PLI scheme localization:Domestic battery assembly incentives under the government's production-linked incentive framework reduce import dependency for lithium-ion cell packs.
- Urban congestion pricing:Low-emission zones in London, Milan, and Stockholm exempt micro-hybrid vehicles from daily access fees, accelerating private owner conversion.
Market Restraints
- Copper winding cost volatility:Electric motor stator production faces input price swings from Chilean and Peruvian concentrate supply disruptions.
- Korean battery supplier concentration:Three producers control over seventy percent of 48V lithium-ion cell capacity, creating single-source vulnerability for European assembly plants.
- REACH substance restrictions:The European Chemicals Agency's evolving candidate list for authorization complicates thermal management fluid formulation stability.
Strategic Opportunities
- Brazil flex-fuel micro-hybrid integration:Ethanol-compatible start-stop systems for Sao Paulo and Rio de Janeiro taxi fleets remain unserved by current product portfolios.
- Second-life battery stationary storage:Degraded 48V packs from retired vehicles can anchor building-scale energy arbitrage in German commercial real estate.
- Indonesia nickel-to-battery verticalization:The country's raw material endowment supports captive cell production for ASEAN-market micro-hybrid assembly.
Industry Challenges
- Power electronics thermal management expertise:48V inverter design requires semiconductor packaging skills scarce in traditional 12V alternator engineering teams.
- Real-driving emissions test compliance:The shift from laboratory to on-road certification extends validation timelines and retooling cycles for powertrain calibration departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro-Hybrid Vehicle Market |
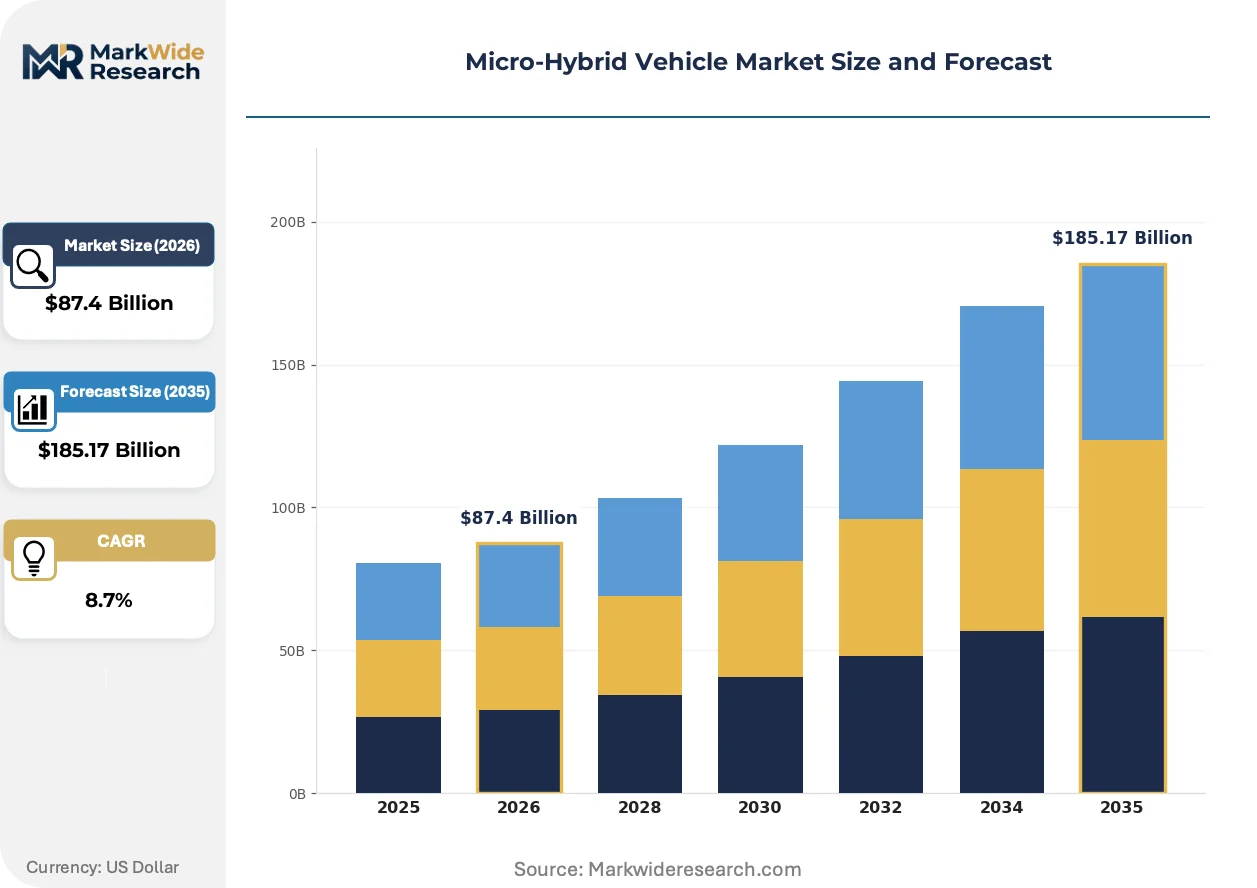
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $185.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Start-Stop System, Battery Management, Regenerative Braking, Electric Drive Vehicle Type: Sedan, SUV, Hatchback, Coupe Fuel Type: Petrol, Diesel, Ethanol, Biodiesel Market/Application: Fleet Management, Personal Use, Commercial, Car Sharing |
| Companies Covered | Ford Motor Company, BMW AG, Toyota Motor Corporation, Hyundai Motor Company, Honda Motor Co., Ltd., Volkswagen AG, General Motors Company, Nissan Motor Co., Ltd., Daimler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro-Hybrid Vehicle Market Emerging Trajectories
Component-level integration is eliminating discrete module boundaries, with power electronics and energy storage converging into unified thermal and electrical management systems.
Silicon carbide MOSFETs in 48V DC-DC converters are collapsing thermal management hardware requirements for compact vehicle packaging. Tier-1 suppliers in Germany and Japan are qualifying these wide-bandgap semiconductors for mass-market hatchback programs. The resulting footprint reduction enables trunk-mounted battery placement without cargo volume sacrifice.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in battery thermal loops, compelling suppliers to qualify carbon dioxide or hydrofluoroolefin alternatives. Compressor redesigns for lower-GWP chemistries extend development cycles by eight to fourteen months. French and Italian climate equipment specialists are capturing retrofit specification authority previously held by powertrain integrators.
Fleet procurement departments are consolidating supplier relationships around full-powertrain service contracts rather than component-by-component sourcing. German logistics operators now specify guaranteed fuel economy outcomes over hardware warranties. This performance-contracting model compresses margins for pure component vendors while rewarding system integrators with calibration and software capabilities.
Micro-Hybrid Vehicle Market Segmentation
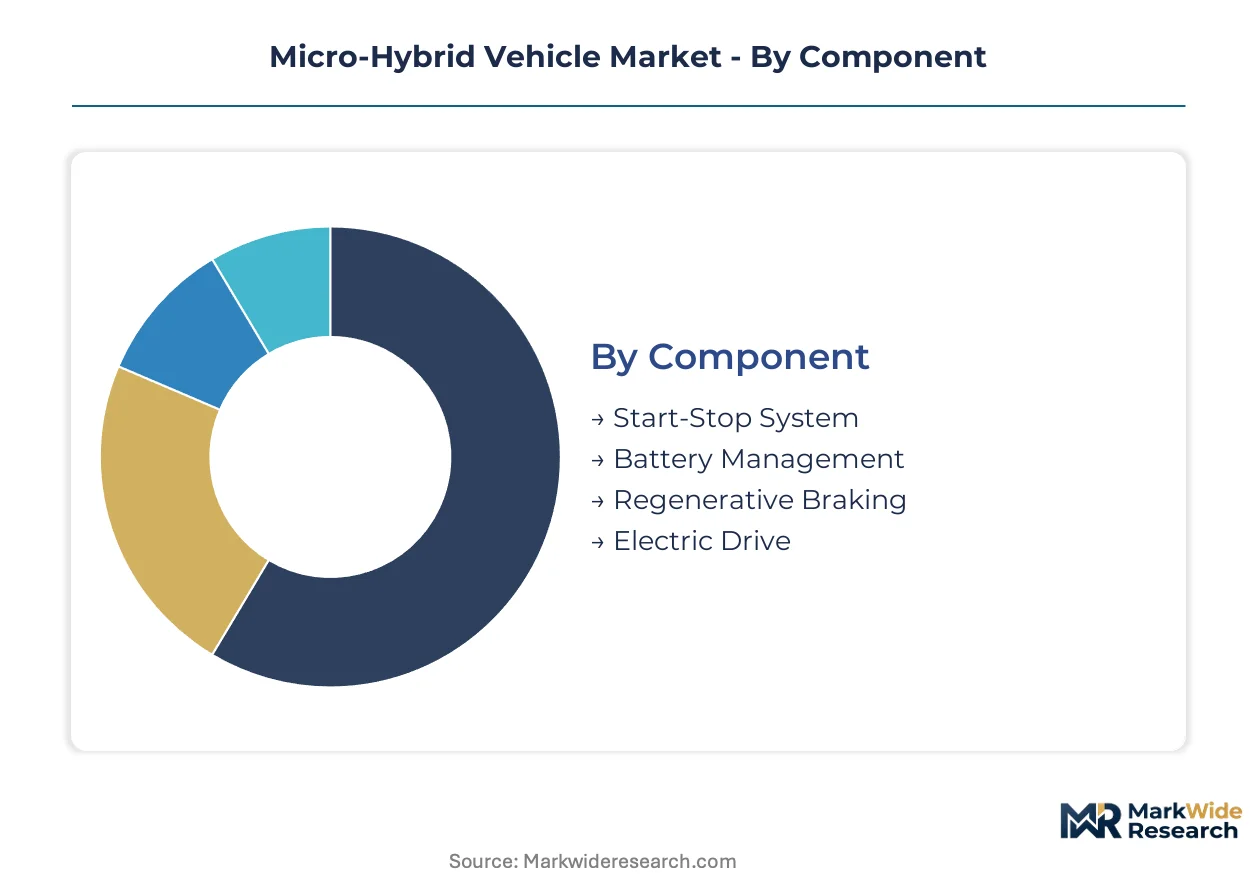
Micro-hybrid vehicle segmentation reveals how component integration depth, vehicle packaging constraints, and fuel compatibility shape procurement economics across fleet and retail channels. Distinct specification requirements emerge for urban congestion pricing compliance versus highway fuel economy optimization.
Component:
Start-stop systems anchor entry-level cost tiers, while regenerative braking and electric drive modules concentrate in premium 48V architectures targeting fleet fuel guarantees.
- Start-Stop System:Idle-elimination technology using reinforced starter motors and crankshaft sensors. Demand clusters in German and French fleet procurement where EU Green Deal corporate vehicle rules penalize pure combustion engines.
- Regenerative Braking:Kinetic energy recovery through belt-driven or crankshaft-integrated motor-generators. Deployment accelerates in Indian mass-market hatchbacks where BIS energy labeling and PLI scheme localization incentives reduce battery pack import costs.
- Battery Management:Cell balancing and thermal monitoring electronics for 12V and 48V architectures. Korean supplier concentration creates single-source vulnerability for European assembly plants.
- Electric Drive:Belt-starter generator and torque-assist motor systems. Silicon carbide MOSFET adoption in German and Japanese Tier-1 supplier programs collapses thermal management footprints for compact vehicle packaging.
The dominant share belongs to Start-Stop System, while Regenerative Braking is closing the gap fastest.
Vehicle Type:
Packaging constraints and parking infrastructure density determine powertrain specification intensity across passenger vehicle form factors.
- Sedan:Three-box passenger cars with dedicated trunk volumes. German premium sedan platforms from BMW AG deploy sophisticated regenerative braking software calibrated for highway fuel economy certification.
- SUV:Elevated ride-height vehicles with higher mass and frontal area. Chinese and Indian urban markets show concentration where family vehicle demand intersects with congestion zone access requirements.
- Hatchback:Two-box compact designs with integrated cargo areas. Demand accelerates in dense Asian and European cities where parking constraints favor smaller footprints and 48V battery trunk mounting preserves cargo volume.
- Coupe:Two-door passenger vehicles with sport-oriented positioning. Lower volume segment where micro-hybrid integration focuses on start-stop refinement rather than full 48V architecture cost.
Sedan retains the largest installed base, though Hatchback is expanding most quickly in city-center access schemes.
Fuel Type:
Combustion chemistry compatibility determines start-stop system durability specifications and thermal management calibration requirements.
- Petrol:Spark-ignition gasoline engines with lower compression ratios. Hyundai Motor Company anchors mass-market hatchback penetration with petrol micro-hybrid variants priced for volume segments.
- Diesel:Compression-ignition engines with higher thermal efficiency. European fleet operators in Germany and France favor diesel micro-hybrids for highway fuel economy under real-driving emissions test protocols.
- Ethanol:Biofuel-compatible powertrains with corrosion-resistant fuel system materials. Brazil flex-fuel micro-hybrid integration for Sao Paulo and Rio de Janeiro taxi fleets remains unserved by current product portfolios.
- Biodiesel:Fatty acid methyl ester blends requiring seal and gasket material compatibility. Niche deployment concentrated in European commercial fleet trials.
Petrol commands the broadest geographic penetration, while Ethanol presents the steepest expansion trajectory in biofuel mandate jurisdictions.
Market/Application:
Ownership and utilization models reshape warranty structures, calibration priorities, and supplier contracting approaches.
- Fleet Management:Centralized vehicle procurement with guaranteed fuel economy outcome contracts. German logistics operators now specify performance-based agreements over hardware warranties, compressing margins for pure component vendors.
- Personal Use:Individual retail acquisition with manufacturer warranty coverage. Urban congestion pricing exemptions in London, Milan, and Stockholm accelerate private owner conversion to micro-hybrid powertrains.
- Commercial:Small business and trade vehicle deployment with high daily mileage profiles. Real-driving emissions test compliance extends validation timelines for powertrain calibration departments serving this segment.
- Car Sharing:Short-term rental and subscription mobility services with intensive urban duty cycles. Asset-light mobility providers capture competitive project finance tied to fleet decarbonization mandates.
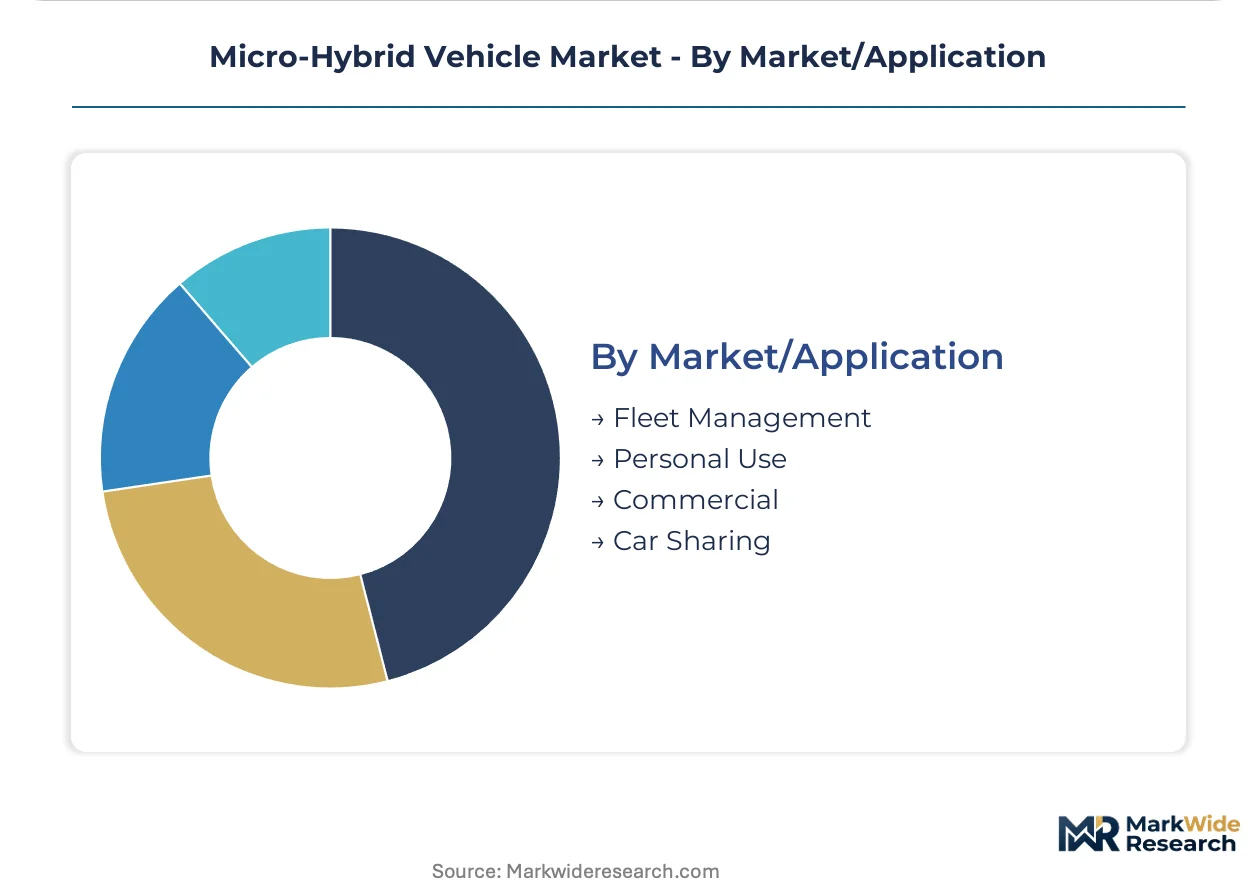
Fleet Management holds the dominant procurement volume, while Car Sharing is gaining share fastest in metropolitan mobility-as-a-service expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fleet procurement rules under the EU Green Deal now penalize pure internal combustion engines, redirecting corporate vehicle budgets toward micro-hybrid powertrains. This policy shift concentrates demand in jurisdictions with congestion pricing schemes and domestic manufacturing incentives.
Germany
KBA registration data shows corporate fleets in Berlin and Munich accelerating 48V sedan adoption ahead of 2030 emissions deadlines. The EU Green Deal fleet mandates channel procurement toward micro-hybrid powertrains with guaranteed fuel economy outcomes. Stuttgart and Wolfsburg anchor development clusters where Tier-1 suppliers qualify silicon carbide MOSFETs for mass-market programs.
China
MIIT fuel economy standards and dual carbon goals compress timelines for domestic OEM electrification roadmaps. Urban congestion zones in Beijing and Shanghai exempt micro-hybrid vehicles from license plate restrictions. The Yangtze River Delta manufacturing corridor concentrates battery pack assembly capacity serving both domestic hatchback demand and export-bound sedan programs.
India
BIS energy labeling and the PLI scheme for advanced automotive technology create localized cost structures for domestic micro-hybrid assembly. Delhi-NCR congestion penalties and odd-even driving restrictions accelerate private owner conversion. Tamil Nadu and Gujarat host emerging cell pack assembly operations reducing import dependency for lithium-ion components.
United States
EPA fuel economy standards shape powertrain calibration targets for export-bound models from Detroit manufacturers. California Air Resources Board regulations extend influence through Section 177 state adoptions. The Midwest manufacturing belt retains assembly capacity for petrol micro-hybrid SUVs targeting fleet procurement departments.
Brazil
Biofuel mandate jurisdictions present unserved demand for ethanol-compatible start-stop systems in Sao Paulo and Rio de Janeiro taxi fleets. ANVISA automotive standards intersect with national biofuel policy frameworks. The Sao Paulo metropolitan area concentrates flex-fuel vehicle demand where micro-hybrid integration remains technically unaddressed.
Micro-Hybrid Vehicle Market Vendor Landscape
Channel-controlling players compete with product-specialist players for procurement specification authority in fleet and retail segments. Market structure tilts toward consolidated system integrators with calibration capabilities and fragmented component vendors facing margin compression. Three archetypes dominate: full-line OEMs with hybrid manufacturing scale, premium-tier specialists with regenerative braking software differentiation, and mass-market hatchback providers with petrol variant cost positioning. Competitive moves concentrate on backward integration into battery pack assembly and performance-based service contracting with fleet operators.
Among full-line OEMs, Toyota Motor Corporation and Volkswagen AG exemplify scale-driven archetypes with hybrid powertrain manufacturing depth. BMW AG occupies a position within the premium-tier specialist segment where regenerative braking software calibration commands specification authority. Hyundai Motor Company anchors the mass-market penetration archetype with petrol micro-hybrid variants priced for volume hatchback segments.
| Leading Market Players |
|---|
| Ford Motor Company |
| BMW AG |
| Toyota Motor Corporation |
| Hyundai Motor Company |
| Honda Motor Co., Ltd. |
| Volkswagen AG |
| General Motors Company |
| Nissan Motor Co., Ltd. |
| Daimler AG |
| Others |
Supply Flow & Price Mechanics
Shanghai-Rotterdam container freight corridors transmit cost volatility from Asian battery assembly clusters into European fleet procurement contracts, compressing margins for 12V start-stop suppliers while amplifying price differentiation between 48V system integrators and component vendors.
Pricing Analysis
Electrical architecture tier creates the primary spread between 12V entry systems and 48V integrated powertrains, with CE-marked components commanding procurement premiums in EU Green Deal fleet mandates. Three-tier pricing structure across premium 48V, standard 12V, and economy starter-motor replacement levels stratifies by thermal management sophistication and software calibration depth. Cost compression in 12V segments is intensifying because Korean battery supplier concentration forces European assembly plants to absorb cell price volatility. Fleet procurement departments exhibit the highest price sensitivity, while premium sedan OEMs prioritize guaranteed fuel economy outcomes over unit cost.
Supply Chain Analysis
Contract manufacturing for 48V power electronics concentrates in German and Japanese Tier-1 facilities, with Bosch and Denso-affiliated plants anchoring inverter and DC-DC converter assembly. Lithium-ion cell supply draws from South Korea and China, while copper winding production rests on Chilean and Peruvian concentrate flows. Single-source vulnerability for European assembly plants stems from three Korean producers controlling over seventy percent of 48V cell capacity. Distribution runs through OEM-direct contracting for fleet volumes and aftermarket channel networks for replacement components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Micro-hybrid vehicle penetration sits at early-cycle expansion, with EU Green Deal fleet mandates and urban congestion pricing schemes accelerating adoption ahead of full electrification economics.
For Market Incumbents: Entrench manufacturing scale through backward integration into battery pack assembly in Tamil Nadu and Gujarat to capture PLI scheme localization benefits. Defend against silicon carbide MOSFET disruption by qualifying wide-bandgap semiconductor packaging capabilities before Tier-1 suppliers consolidate specification authority. Prioritize performance-based service contracts with German logistics operators to lock in fuel economy guarantee revenue streams. For New Entrants and Emerging Players: Brazil flex-fuel micro-hybrid systems for Sao Paulo and Rio de Janeiro taxi fleets represent the most penetrable entry point, with ethanol-compatible start-stop durability specifications still unserved by incumbent portfolios. Indonesian nickel-to-battery verticalization offers second-mover positioning in ASEAN-market assembly. Partner with domestic thermal management specialists in France and Italy to capture F-Gas Regulation-driven compressor redesign specifications. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors system integrators with calibration capabilities over pure component vendors facing margin compression. Long-term viability through the electrification transition hinges on software-defined powertrain architecture ownership. Target acquisition archetypes include German Tier-1 suppliers with silicon carbide qualification progress and Indian battery assembly operations with PLI scheme approval. Monitor real-driving emissions test compliance timelines as the inflection signal for validation capacity scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| 48V Platform Standardization | Toyota and Volkswagen manufacturing scale reduces start-stop integration costs across multiple vehicle architectures. |
| Battery Supply Agreement | Korean cell producer concentration creates single-source vulnerability for European OEM assembly commitments. |
| Software-Defined Vehicle Investment | BMW regenerative braking calibration commands specification authority in premium sedan fleet procurement. |
| Geographic Manufacturing Footprint | Hyundai Motor Company petrol micro-hybrid variants anchor mass-market hatchback penetration in India and Southeast Asia. |
| Charging Infrastructure Partnership | Second-life 48V battery stationary storage opens building-scale energy arbitrage in German commercial real estate. |
Methodological Framework
Cross-validation between OEM platform engineering disclosures and Tier-1 supplier procurement data anchors the qualitative findings on 48V architecture migration timelines. Primary interviews with automotive powertrain directors, fleet procurement managers, battery cell manufacturing executives, and thermal management system engineers combined with secondary validation from KBA registration databases, MIIT fuel economy filings, and BIS energy labeling records. Bottom-up vehicle production forecasts and top-down emissions regulation impact modeling triangulate volume estimates.
Calibration against historical powertrain electrification adoption curves and regulatory compliance cost structures informs the analytical framework across the projection horizon. Segmentation dimensions modeled include vehicle class, electrical architecture voltage tier, fuel compatibility, and regional production cluster. CAGRs derive from installed base turnover rates and fleet renewal cycle analysis. Key inputs include lithium-ion cell cost curves, copper price volatility indices, and real-driving emissions test compliance timelines.
Practitioners should monitor Korean battery supplier capacity allocation shifts and REACH substance restriction list updates for early signals of supply constraint or formulation disruption. Forecasts reflect assumptions on EU Green Deal implementation pace and PLI scheme localization incentives. Quarterly review of KBA corporate fleet registration data and Delhi-NCR congestion penalty enforcement is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
Hybrid Vehicle Market
Hybrid Vehicles
Europe Mild Hybrid Vehicles Market
Hybrid Vehicles
Crossovers Market
Hybrid Vehicles
Hybrid Electric Vehicle Market
Hybrid Vehicles
Electric and Hybrid Vehicles Driveline Market
Hybrid Vehicles
Ignition Systems for Range-Extended Hybrid Powertrains Market
Hybrid Vehicles
Middle East and Africa Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Hybrid Drivetrain Market
Hybrid Vehicles
North America Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Hybrid Cars Market
Hybrid Vehicles
High-Voltage Hybrid Vehicle Market
Hybrid Vehicles
Hydrogen Vehicles Market
Hybrid Vehicles
Asia-Pacific Micro-Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Powertrain Systems Market
Hybrid Vehicles
Crossover Vehicle Market
Hybrid Vehicles
India Hybrid Vehicles Market