
 Automotive Ignition System Market | 2026-2036
Automotive Ignition System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Ignition System Market Intelligence
The capital-intensity divergence between integrated ignition component manufacturers and module assemblers is collapsing as coil-on-plug architectures require in-house semiconductor packaging and thermal management capabilities. Robert Bosch leverages its captive semiconductor foundry partnerships to control ignition control module supply chains from wafer to vehicle harness. Denso Corporation anchors its competitive position through deep backward integration into ferrite core and resin molding operations for ignition coils. BorgWarner competes by extending its powertrain electronics portfolio into integrated ignition-timing systems that merge with variable valve control.
An automotive ignition system generates high-voltage electrical pulses timed to spark plug firing events, with modern coil-on-plug units delivering 35-45 kV across platinum or iridium electrode gaps to initiate controlled combustion in gasoline and gaseous-fuel engines. Conventional distributor-based architectures retain residual demand in legacy vehicle parc and low-cost commercial applications, though the technology is approaching end-of-life status in new vehicle design. Coil-on-plug configurations now dominate OEM factory installations as they eliminate distributor wear, enable individual cylinder timing optimization, and support turbocharged downsized engines requiring precise knock control. Aftermarket suppliers specializing in ignition coil replacement for high-mileage fleets occupy a stable margin pool tied to vehicle age demographics rather than new vehicle technology cycles.
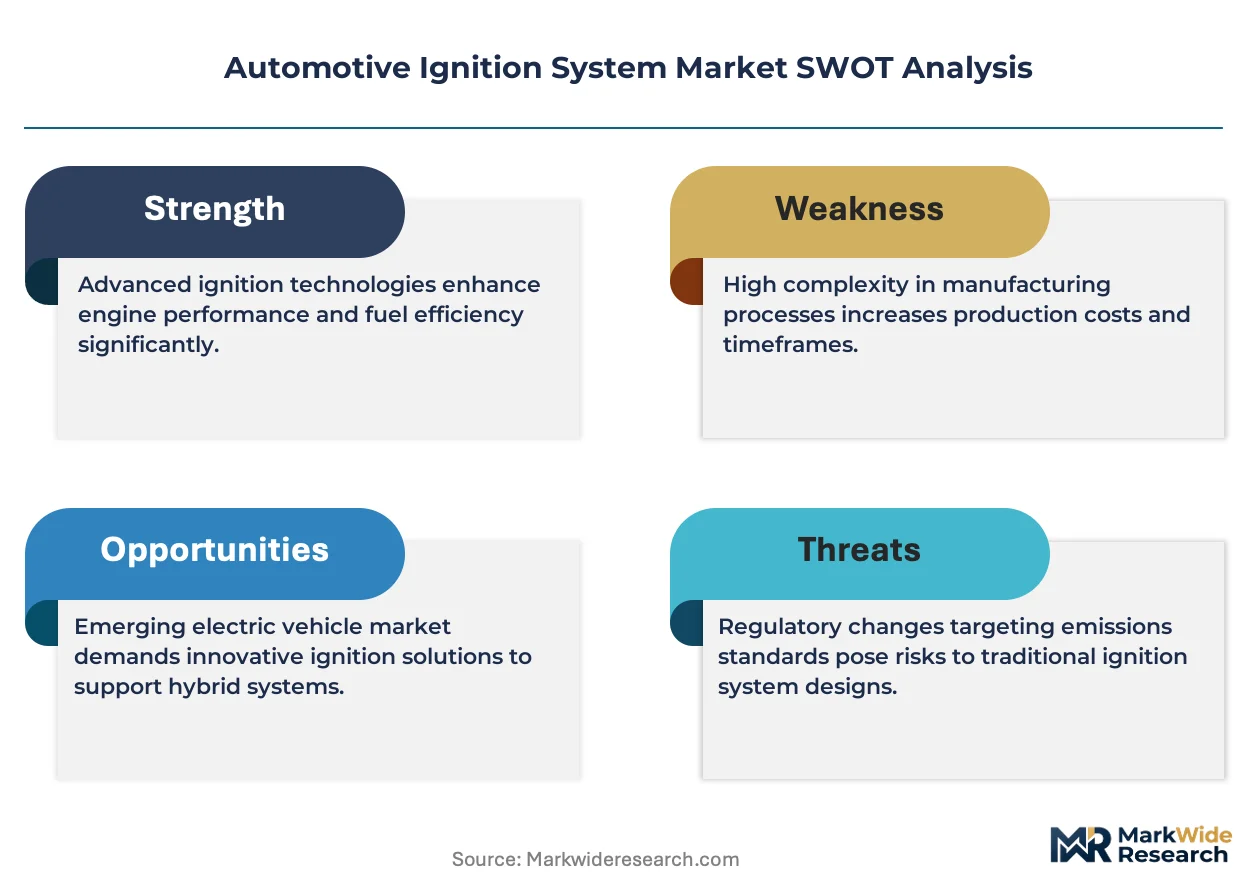
EPA tailpipe standards and California Air Resources Board zero-emission vehicle mandates in the United States are compressing the gasoline engine development window, forcing ignition system suppliers to optimize combustion efficiency for remaining internal combustion production runs. Euro 7 proposals from the European Commission would tighten particulate number limits for gasoline direct-injection engines, requiring advanced multi-strike ignition strategies that only electronic control architectures can execute. China's MIIT fuel consumption regulations and dual carbon goals are pushing domestic manufacturers toward higher-energy ignition systems that enable lean-burn combustion in hybrid powertrains. Stakeholders must monitor the pace of powertrain electrification in their target geographies to calibrate R&D allocation between ignition system refinement and pivot investments toward electric drivetrain components.
Market Dynamics
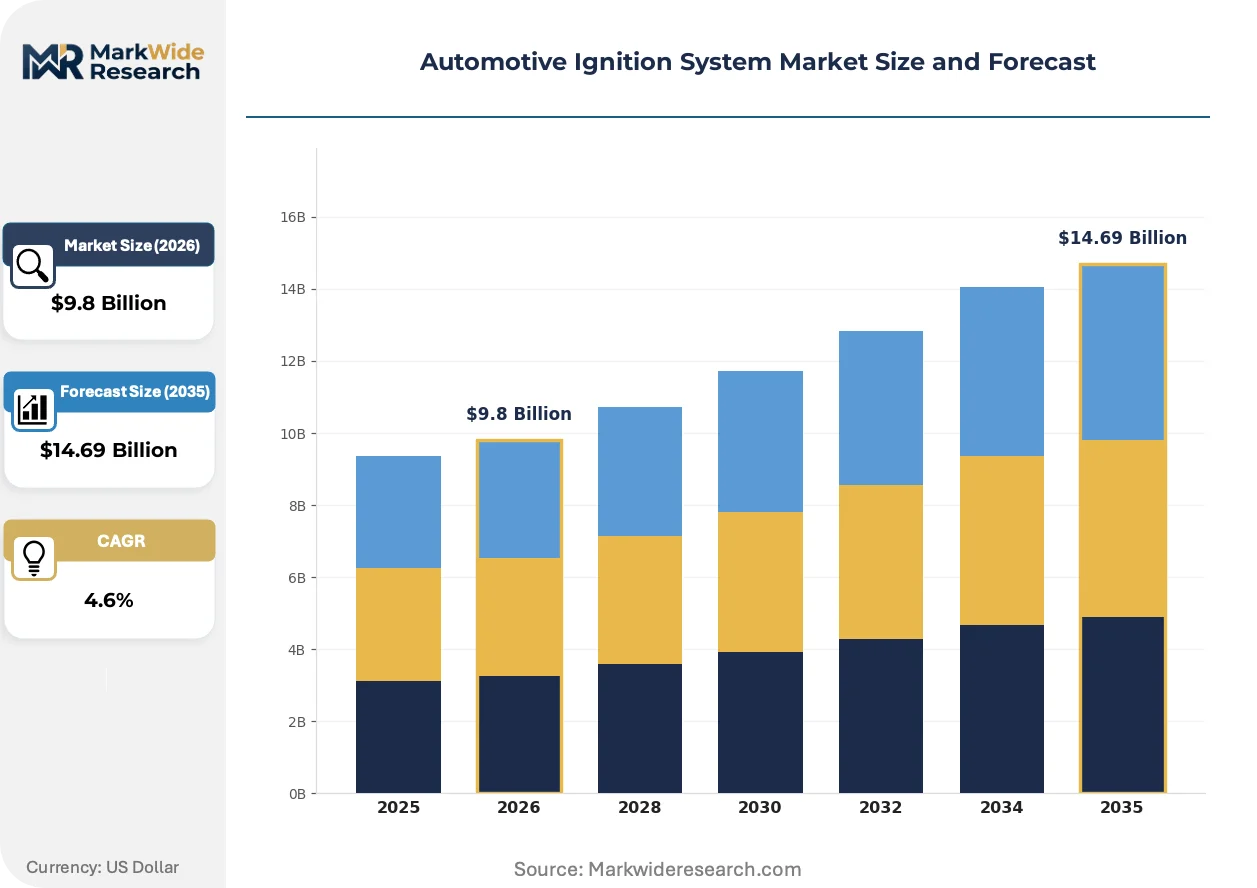
Coil-on-plug architectures are compressing supplier margins by forcing semiconductor packaging and thermal management capabilities into ignition component manufacturing, collapsing the historical division between integrated manufacturers and module assemblers.
Growth Catalysts
- Euro 7 emission standards:Tightened particulate number limits for gasoline direct-injection engines mandate advanced multi-strike ignition strategies executable only through electronic control architectures.
- Commercial vehicle fleet expansion:Emerging economies are scaling electronic ignition platform adoption across heavy-duty and medium-duty truck populations.
- China's eastern manufacturing corridor:Domestic OEMs and joint ventures are accelerating coil-on-plip production for gasoline and compressed natural gas powertrains.
Market Restraints
- Powertrain electrification timeline:EPA tailpipe standards and California Air Resources Board zero-emission vehicle mandates compress the gasoline engine development window.
- Semiconductor supply concentration:Captive foundry partnerships at tier-one suppliers limit second-tier access to ignition control module wafers.
- Residual legacy demand:Distributor-based architectures retain demand in vehicle parc and low-cost commercial applications, fragmenting R&D allocation.
Strategic Opportunities
- Lean-burn hybrid powertrains:China's MIIT fuel consumption regulations and dual carbon goals push demand for higher-energy ignition systems enabling lean combustion.
- Aftermarket coil replacement:High-mileage fleet demographics create stable margin pools decoupled from new vehicle technology cycles.
- Integrated ignition-timing systems:Convergence with variable valve control electronics opens white space in powertrain electronics bundling.
Industry Challenges
- In-house semiconductor packaging:Coil-on-plug architectures require capital-intensive thermal management and wafer-level capabilities foreign to traditional ignition coil manufacturers.
- Multi-geometry ferrite core tooling:Ignition coil producers must reconfigure resin molding and core winding operations for turbocharged downsized engine variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Ignition System Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Ignition, Distributor-less Ignition, Coil-on-Plug, Ignition Coil End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Repair Shops Technology: Ignition Timing Control, Spark Plug Technology, Fuel Management, Electronic Ignition Installation Type: Factory-installed, Aftermarket Installation, Retrofit Solutions, Modular Systems |
| Companies Covered | Robert Bosch, Denso Corporation, BorgWarner, Delphi Technologies, NGK Spark Plug, Hitachi Automotive Systems, Mitsubishi Electric Corporation, Continental AG, Diamond Electric Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Ignition System Market Strategic Shifts & Innovations
Electronic control architectures are displacing mechanical ignition timing across all engine displacement classes, with combustion optimization algorithms now governing spark delivery in real-time.
Multi-strike ignition strategies are miniaturizing high-voltage switching circuits into coil-on-plug housings previously sized for single-pulse operation. OEMs in Germany and Japan are adopting these compact architectures for downsized turbocharged engines. The technology is miniaturizing thermal management footprints while expanding knock control precision.
The European Commission's Euro 7 proposals would enforce particulate number limits that mechanical distributors cannot satisfy. Engine management suppliers are recalibrating control algorithms for gasoline direct-injection platforms. Gasoline passenger car segments in France, Italy, and Spain face the steepest compliance ramps.
Fleet procurement of ignition coils is consolidating around certified remanufacturing programs that guarantee electrode gap specifications. Independent distributors and jobbers are losing share to direct OEM-affiliated channels. This pattern is most visible in North American Class 8 truck aftermarket operations.
Automotive Ignition System Market Segmentation
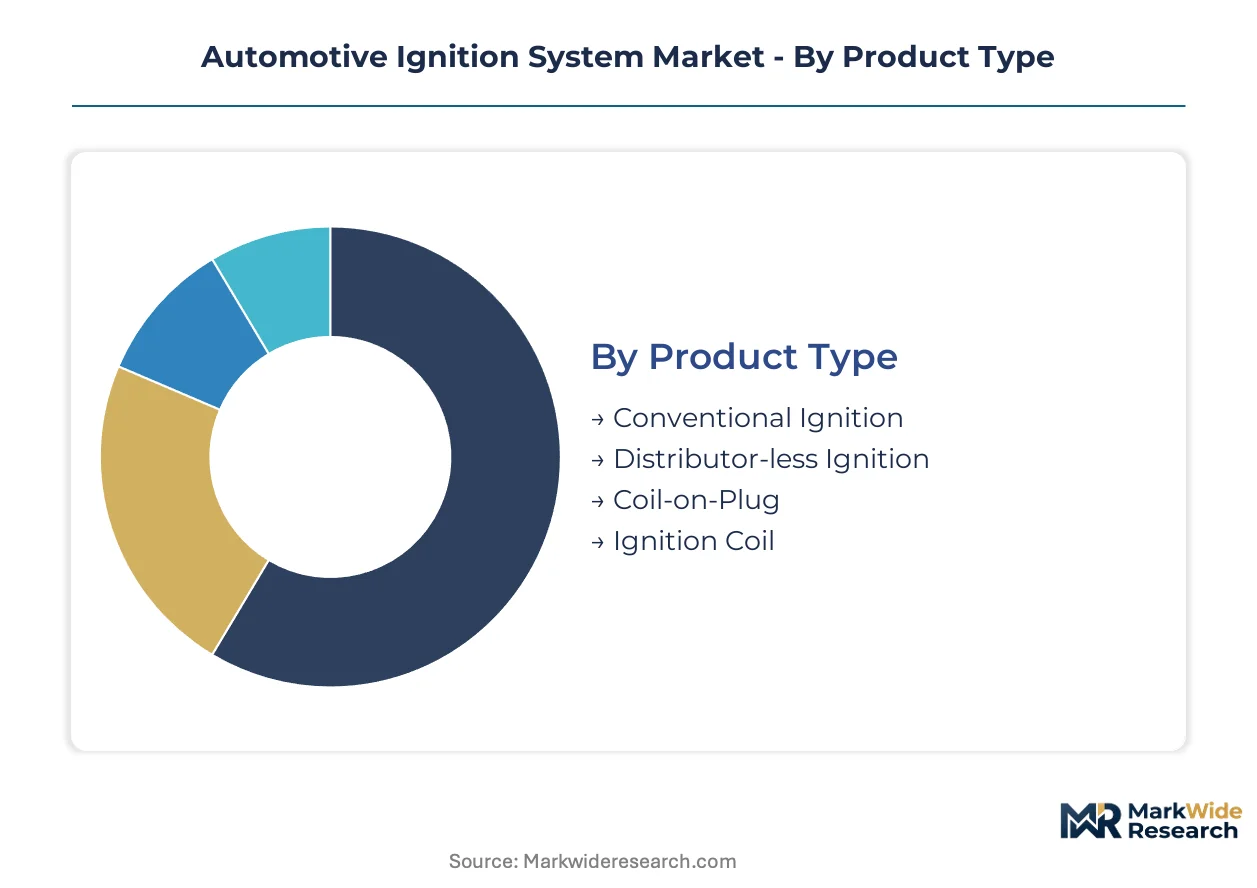
Ignition system segmentation reveals how powertrain electrification timelines and emission compliance pressures are fragmenting demand across legacy and advanced architectures. Supplier portfolios must balance R&D allocation between mature replacement markets and emerging electronic control platforms.
Product Type:
Coil-on-plug architectures face the steepest substitution pressure as distributor-less systems approach end-of-life status in new vehicle design.
- Conventional Ignition:Mechanical distributor-based systems with rotating contact breakers and high-voltage coils retain residual demand in legacy commercial vehicle parc and emerging market low-cost applications. Demand concentrates in India's heavy-duty truck aftermarket where Bharat Stage VI retrofits lag factory installations.
- Distributor-less Ignition:Waste-spark configurations with dual-ended coils serve V6 and V8 engines in North American pickup segments. Ford and General Motors continue sourcing these modules for existing powertrain architectures despite declining new platform adoption.
- Coil-on-Plug:Individual coil-per-cylinder architectures with integrated driver electronics dominate Euro 7-compliant gasoline direct-injection production.
- Ignition Coil:Standalone inductive components supply both OEM assembly lines and aftermarket replacement channels.
Coil-on-plug anchors the volume base while distributor-less ignition retains the steepest share erosion trajectory.
End User:
Customer type segmentation tracks margin structure divergence between captive OEM supply and fragmented aftermarket procurement.
- OEMs:Original equipment manufacturers specify ignition architectures during powertrain development cycles with multi-year supply agreements. Volkswagen Group and Toyota Motor Corporation are consolidating ignition module procurement around integrated powertrain electronics suppliers.
- Aftermarket Suppliers:Independent distributors and private-label manufacturers serve high-mileage vehicle parc with certified replacement coils. North American Class 8 fleet procurement is consolidating around OEM-affiliated remanufacturing programs.
- Vehicle Assemblers:Contract manufacturers and joint venture operations source ignition systems against MIIT fuel consumption regulations in China's eastern manufacturing corridor.
- Repair Shops:Service bay operators purchase ignition components through jobber networks or direct distributor relationships.
OEMs command the premium pricing tier while aftermarket suppliers absorb the steepest margin compression.
Technology:
Technology segmentation maps semiconductor content migration from mechanical timing to algorithmic combustion control.
- Ignition Timing Control:Engine management units execute real-time spark advance calculations using crankshaft position sensors and knock detection feedback. Bosch and Denso are integrating these functions with variable valve timing electronics.
- Spark Plug Technology:Noble metal electrode configurations with iridium and platinum center electrodes extend service intervals. Premium plug demand clusters in Germany's luxury passenger car segment.
- Fuel Management:Port and direct-injection coordination systems synchronize ignition events with injector pulse width.
- Electronic Ignition:Transistor-controlled switching circuits have displaced breaker points across all displacement classes.
Ignition timing control captures the highest semiconductor value per unit while electronic ignition represents the most mature, lowest-margin category.
Installation Type:
Installation segmentation distinguishes between powertrain-integrated factory supply and post-production service economics.
- Factory-installed:OEM assembly line integration requires ignition system validation against full vehicle EMC and thermal cycling specifications. China's joint venture plants are scaling coil-on-plug installation for gasoline and compressed natural gas powertrains.
- Aftermarket Installation:Service bay replacement of failed ignition components operates on compressed labor margins and parts markup.
- Retrofit Solutions:Emission compliance upgrades convert older distributor systems to electronic ignition for commercial fleet operators.
- Modular Systems:Plug-and-play ignition subassemblies simplify field replacement in remote service environments.
Factory-installed systems generate the steepest revenue per vehicle while retrofit solutions expand most quickly in emerging market commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's precision-engineering corridor while cost-sensitive procurement dominates India's commercial vehicle aftermarket. This asymmetry fragments supplier margins across geographies. Regional regulatory divergence accelerates technology stratification between emission-compliant and legacy markets.
China
Domestic OEMs and joint ventures in the eastern manufacturing corridor scale coil-on-plug production for gasoline and compressed natural gas powertrains. MIIT fuel consumption regulations and dual carbon goals push manufacturers toward higher-energy ignition systems enabling lean-burn hybrid combustion. Shanghai and Jiangsu province anchor this production expansion.
Germany
Volkswagen Group and BMW specify advanced multi-strike ignition modules for Euro 7-compliant gasoline direct-injection platforms. The European Commission's tightened particulate number limits force recalibration of engine management algorithms. Stuttgart and Munich house the development centers driving this electronic architecture migration.
United States
Ford and General Motors continue sourcing waste-spark distributor-less modules for existing V6 and V8 pickup architectures despite declining new platform adoption. EPA tailpipe standards and California Air Resources Board zero-emission mandates compress the gasoline engine development window. Detroit's engineering base manages this transition timing.
India
Bharat Stage VI retrofits lag factory installations in the heavy-duty truck aftermarket, sustaining residual demand for conventional distributor-based systems. Commercial fleet operators in Maharashtra and Gujarat drive electronic ignition platform adoption across medium-duty populations. Chennai and Pune manufacturing clusters supply these retrofit conversions.
Japan
Toyota Motor Corporation consolidates ignition module procurement around integrated powertrain electronics suppliers for hybrid powertrain optimization. METI energy efficiency guidelines and domestic carbon neutrality targets accelerate coil-on-plug integration. Aichi prefecture's supplier ecosystem supports this technology convergence.
Automotive Ignition System Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated powertrain electronics suppliers command premium positioning through semiconductor packaging capabilities, while component specialists compete on coil manufacturing scale. Three archetypes dominate: captive semiconductor foundry partners, backward-integrated ferrite core producers, and modular ignition-timing integrators. Consolidation pressure intensifies as coil-on-plug architectures collapse the historical division between integrated manufacturers and module assemblers.
Among diversified automotive suppliers, Robert Bosch, Denso Corporation, and BorgWarner occupy positions exemplifying the integrated powertrain electronics archetype. Bosch represents the captive foundry partnership model controlling supply chains from wafer to vehicle harness. Denso anchors the backward-integrated tier with in-house ferrite core and resin molding operations. BorgWarner exemplifies the portfolio extension strategy merging ignition-timing systems with variable valve control electronics.
| Leading Market Players |
|---|
| Robert Bosch |
| Denso Corporation |
| BorgWarner |
| Delphi Technologies |
| NGK Spark Plug |
| Hitachi Automotive Systems |
| Mitsubishi Electric Corporation |
| Continental AG |
| Diamond Electric Holdings |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day ferrite core lead times from Japanese suppliers concentrate pricing power among coil-on-plug manufacturers with captive resin molding operations, while module assemblers without in-house thermal management capabilities absorb margin compression from semiconductor packaging costs.
Pricing Analysis
The customization-premium spread between configured-to-order coil-on-plip modules and standard ignition coils runs wide, with Euro 7-compliant multi-strike architectures commanding substantial premiums over distributor-less waste-spark configurations. Pricing stratifies across premium, standard, and economy tiers based on semiconductor content density and thermal management grade. Cost compression in the standard tier is intensifying because captive foundry partnerships at tier-one suppliers limit wafer access for second-tier competitors. Fleet procurement teams in North American Class 8 operations exhibit the sharpest price sensitivity, while German OEM platform engineers prioritize ignition timing precision over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate OEM assembly line supply, though aftermarket distributors maintain strategic stockpiles of high-failure-rate ignition coils to service high-mileage commercial fleets. Manufacturing concentrates in China, Germany, and Japan, with Shanghai and Jiangsu province anchoring coil-on-plug production for gasoline and compressed natural gas powertrains. Supply chains draw from ferrite core deposits in East Asia, copper winding feedstock from Chile, and semiconductor wafers from Taiwan. Single-source vulnerability in ignition control module foundries poses structural risk. Distribution runs through OEM-affiliated remanufacturing programs and independent jobber networks serving repair shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor packaging capabilities sit in short supply, fragmenting competitive position between integrated powertrain electronics suppliers and component specialists lacking wafer-level competencies.
For Market Incumbents: Compound defensive positioning by deepening backward integration into ferrite core and resin molding operations, and by securing captive foundry partnerships that lock in ignition control module supply from wafer to vehicle harness. Powertrain electrification timelines in California and Europe threaten gasoline ignition volumes, making thermal management R&D and hybrid powertrain ignition optimization the priority levers for margin defense. For New Entrants and Emerging Players: Differentiate on aftermarket remanufacturing certification for high-mileage fleet segments where OEM-affiliated channels have not yet consolidated procurement. India's Bharat Stage VI retrofit market offers the most penetrable geography, with heavy-duty truck fleets in Maharashtra and Gujarat converting distributor-based systems to electronic ignition. A direct distributor relationship model bypassing fragmented jobber networks captures margin in this white space. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because coil-on-plug architectures are collapsing the historical division between integrated manufacturers and module assemblers, forcing capital-intensive capability acquisition. Targets with in-house semiconductor packaging and thermal management competencies, plus established OEM platform engineering relationships, command strategic premium. Watch the pace of Euro 7 implementation and EPA tailpipe standard compression as the signal for ignition system refinement versus electric drivetrain pivot timing.| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Packaging Integration | Captive foundry partnerships at Bosch and Denso control ignition control module supply chains from wafer to harness. |
| Multi-Strike Ignition Module Launch | OEMs in Germany and Japan adopt compact architectures for downsized turbocharged engines requiring precise knock control. |
| Aftermarket Remanufacturing Certification | North American Class 8 fleet procurement consolidates around guaranteed electrode gap specifications and direct OEM channels. |
| Backward Integration into Ferrite Cores | Denso anchors competitive position through in-house resin molding and core winding operations for ignition coil production. |
| Hybrid Powertrain Ignition Optimization | China's MIIT fuel consumption regulations push demand for higher-energy systems enabling lean-burn combustion. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and dealership operations managers; and secondary validation against vehicle production databases, IHS Markit registration data, SEC filings from diversified automotive suppliers, and MIIT fuel consumption disclosure records. Bottom-up segment sizing triangulated against top-down market envelope checks.
Across the analysis window, the forecasting framework modeled vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions. CAGRs derived from production volume trajectories, technology substitution curves for distributor-based versus electronic architectures, and regulatory compliance timelines. Euro 7 particulate number limits and EPA tailpipe standard compression served as scenario inputs.
Material uncertainties — powertrain electrification pace, semiconductor supply availability, and emission regulation implementation timing — sit outside the modeled envelope. Forecasts reflect assumptions about hybrid powertrain ignition content persistence and aftermarket replacement cycle stability. Revision becomes warranted when battery electric vehicle penetration in passenger car segments crosses thresholds that compress gasoline engine development windows beyond modeled parameters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Automotive 48V System Market
Automotive Circuit Systems
Dual Circuit Brakes System Market
Automotive Circuit Systems
Middle East and Africa Automotive LED Lighting Market
Automotive Circuit Systems
Automotive Digital Instrument Cluster Market
Automotive Circuit Systems
Automotive Horn Systems Market
Automotive Circuit Systems
Embedded Systems in Automobiles Market
Automotive Circuit Systems
Japan Automotive Adaptive Lighting System Market
Automotive Circuit Systems
Automotive Throttle Position Sensor Market
Automotive Circuit Systems
Backlit and Icon-Based Switch Systems for Commercial Vehicles Market
Automotive Circuit Systems
Steering Thermal Systems Market
Automotive Circuit Systems
Global Automotive Side Turn Indicator Market
Automotive Circuit Systems
Steering Column Control Modules Market
Automotive Circuit Systems
Automotive Grade Inductors Market
Automotive Circuit Systems
Driveline Control Systems and Devices Market
Automotive Circuit Systems
Automotive Advanced Shifter System Market
Automotive Circuit Systems
Automotive Accelerator Pedal Module Market