
 Global Hybrid-Electric Vehicle Insulation Market | 2026-2036
Global Hybrid-Electric Vehicle Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hybrid-Electric Vehicle Insulation Market Analysis
Capital-intensity divergence between in-house resin synthesis capabilities and outsourced compounders is bifurcating competitive returns across the supply base. BASF SE leverages its Ludwigshafen polymer backbone to sustain captive polyurethane supply for OEM thermal barrier programs. DuPont anchors North American demand through fluoropolymer film laminates that dominate fire-protection specifications in Detroit-area assembly plants. Morgan Advanced Materials competes via ceramic fiber boards that occupy premium positions in European bus and coach electrification tenders.
Hybrid-electric vehicle insulation encompasses engineered materials that limit heat transfer, acoustic transmission, and flame propagation across battery enclosures, power electronics housings, and passenger compartments; typical constructions achieve thermal conductivity below 0.025 W/m·K through multilayer aerogel-polymer composites laminated with aluminum foil facing. The primary commercial purpose centers on preventing thermal runaway cascade failures while preserving cabin NVH performance in electrified powertrain architectures. Aerogel formulations command the fastest expansion trajectory as cell-to-pack designs eliminate module-level air gaps and concentrate barrier requirements into thinner, higher-performance layers. Foam product forms currently lead volume shipments due to their compatibility with automated dispensing equipment at Tier-1 seating and trim suppliers. OEM end users capture the deepest margin pools by specifying proprietary material certifications that lock in dual-source requirements and extend qualification cycles.
FDA oversight of fluorinated polymer feedstocks intersects with EPA REACH-equivalent reporting on perfluorinated substance content, compelling reformulation of legacy barrier coatings. China's GB standards for new energy vehicle fire safety, enforced by SAMR and MIIT, mandate five-minute no-fire propagation thresholds that directly inflate insulation thickness and material grade requirements. EMA and ECHA coordination on end-of-life vehicle directives shapes recyclability mandates that penalize multi-material laminates without disassembly protocols. Stakeholders must monitor evolving thermal-test protocols across certification bodies to anticipate specification jumps that render existing compound qualifications obsolete.
Market Dynamics
Cell-to-pack battery architectures are compressing thermal barrier thickness requirements while simultaneously elevating performance specifications, forcing material suppliers to reformulate aerogel-polymer composites for sub-3-millimeter installations without sacrificing five-minute no-fire propagation compliance.
Growth Catalysts
- Cell-to-Pack Thermal Barriers:OEMs in Germany and Japan are mandating thinner, higher-performance insulation layers as module-level air gaps disappear, directly accelerating aerogel formulation R&D cycles.
- GB Standards Enforcement:China's SAMR and MIIT five-minute no-fire propagation thresholds are inflating material grade specifications and extending qualification timelines for barrier suppliers.
- Gyeonggi-do Localization:Hyundai-Kia supplier clusters in South Korea are captive-producing polyurethane foam systems, reducing import dependency and compressing regional lead times.
Market Restraints
- Silica Aerogel Feedstock Concentration:Precursor supply for supercritical drying processes concentrates among specialty chemical producers in the US and Germany, creating input cost volatility for mid-tier compounders.
- Multi-Material Recyclability Penalties:ECHA end-of-life vehicle directives impose disassembly protocol requirements on aluminum-foil-laminated composites, increasing compliance overhead for legacy barrier constructions.
- Fluoropolymer Reformulation Costs:EPA REACH-equivalent reporting on perfluorinated substances is compelling barrier coating reformulations that degrade legacy fire-protection performance until replacement chemistries stabilize.
Strategic Opportunities
- Indian OEM Qualification Windows:BIS certification timelines for new energy vehicle fire safety are opening first-mover advantages for aerogel suppliers establishing local testing partnerships.
- Bus and Coach Electrification:European tender specifications for electric bus thermal management are creating premium positions for ceramic fiber board systems in high-occupancy vehicle segments.
- Automated Dispensing Integration:Foam-in-place compatibility with Tier-1 seating and trim supplier equipment is enabling channel bypass of traditional sheet goods distribution.
Industry Challenges
- Dual-Source Qualification Compression:OEM proprietary material certifications are extending validation cycles and locking compounders into multi-year development commitments before volume allocation.
- Thermal Test Protocol Fragmentation:Divergent certification requirements across NHTSA, ECHA, and MIIT testing regimes are rendering single-qualification barrier designs obsolete across export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hybrid-Electric Vehicle Insulation Market |
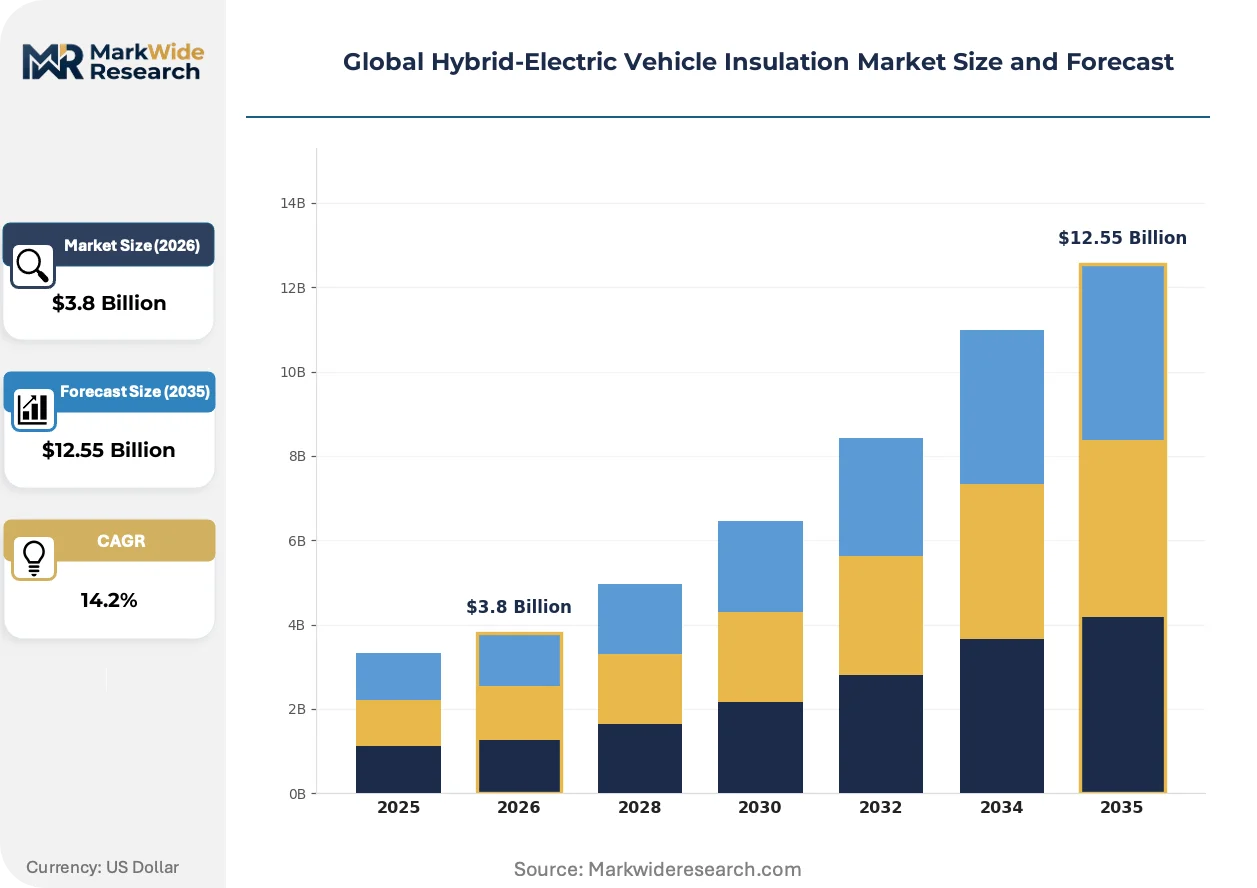
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyurethane, Fiberglass, Aerogel, Foam Product Form: Blankets, Boards, Foams, Coatings End User: OEMs, Tier-1 Suppliers, Aftermarket, Electric Vehicle Manufacturers Application: Thermal Insulation, Acoustic Insulation, Fire Protection, Vibration Damping |
| Companies Covered | 3M, BASF SE, DuPont, Autoneum, Morgan Advanced Materials, Saint-Gobain, Zotefoams plc, Unifrax, Elmelin Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hybrid-Electric Vehicle Insulation Market Emerging Trajectories
Material science convergence with automated manufacturing is collapsing the traditional separation between thermal, acoustic, and fire-protection functions into unified barrier systems.
Aerogel-polymer composite formulations are bifurcating competitive positioning across the supply base. Captive resin synthesis capabilities at integrated chemical majors now deliver cost advantages in high-volume OEM programs. Outsourced compounders without upstream polymer backbone access face margin compression as specification density increases. The technology is bifurcating the market into vertically integrated suppliers with Ludwigshafen-scale infrastructure versus formulation specialists dependent on merchant feedstock.
REACH-equivalent EPA reporting on perfluorinated substances is forcing fluoropolymer coating reformulations across North American barrier suppliers. Industrial consequence includes temporary fire-protection performance degradation during transition periods. Detroit-area assembly plants are responding by dual-qualifying alternative laminate constructions to maintain specification continuity.
Buyer concentration among passenger car OEMs is compressing switching cycles and unbundling after-sales service from material supply agreements. Tier-1 seating and trim suppliers are displacing traditional distribution channels with direct compounder relationships. South Korea's Gyeonggi-do cluster exhibits this pattern most visibly, where localized foam production has eliminated regional distributor tiers entirely.
Global Hybrid-Electric Vehicle Insulation Market Segmentation
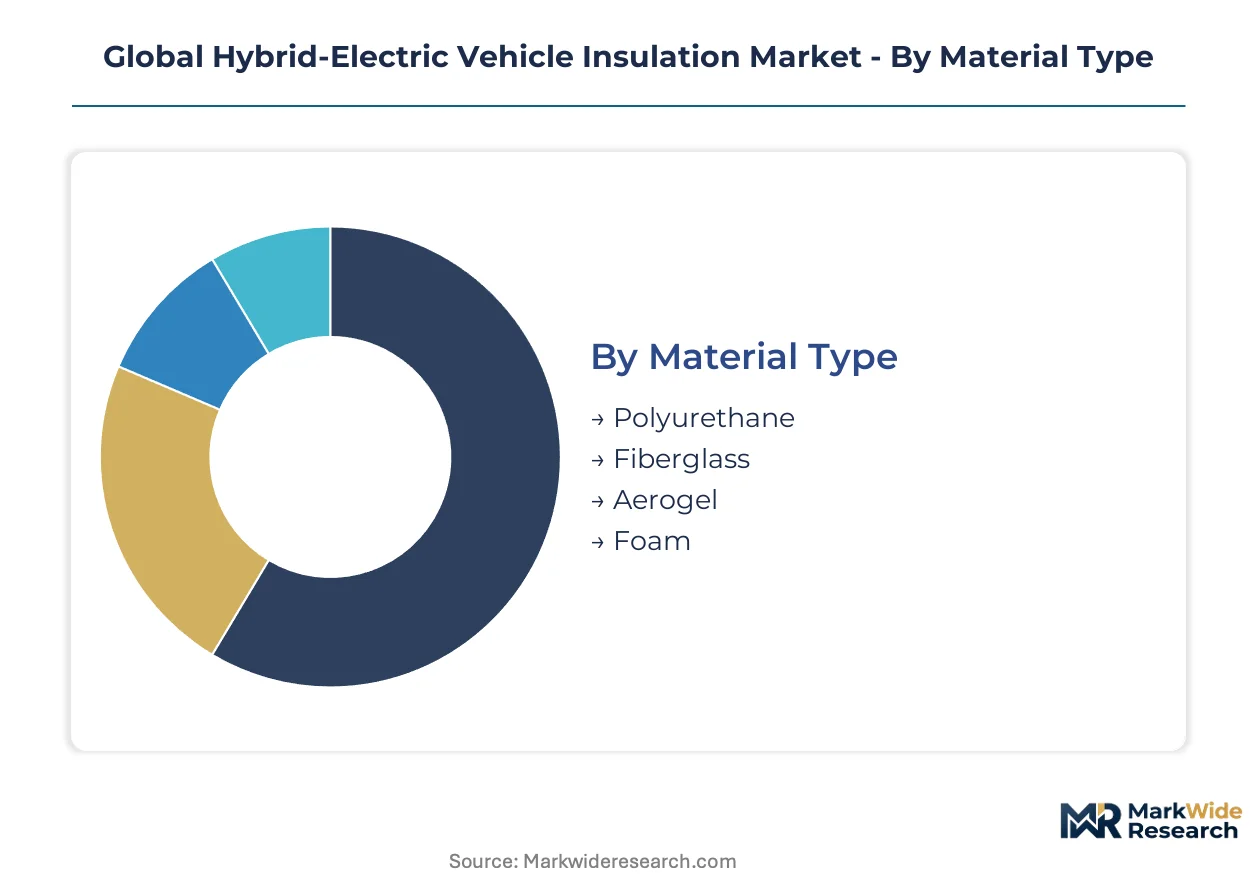
Material selection and product form determine channel economics in hybrid-electric vehicle insulation. Specification density varies sharply across battery pack, power electronics, and cabin applications, fragmenting procurement patterns and margin structures.
Material Type:
Polyurethane and aerogel formulations flow through distinct supply channels—automated dispensing systems versus precision lamination lines—creating divergent customer access strategies for compounders.
- Polyurethane:Thermoset polymer systems achieve thermal conductivity near 0.020 W/m·K through closed-cell foam structures. Hyundai-Kia suppliers in South Korea's Gyeonggi-do cluster have localized captive production, eliminating import tiers and compressing regional lead times for battery pack applications.
- Aerogel:Silica-based supercritical-dried matrices deliver sub-0.015 W/m·K performance in sub-3-millimeter thicknesses. China's NMPA and MIIT are accelerating domestic certification timelines, concentrating demand among compounders with precursor supply agreements in Germany and the US.
- Fiberglass:Woven glass fiber mats with aluminum foil facing dominate cost-sensitive bus and coach electrification tenders in Europe.
- Foam:Open-cell and closed-cell variants interface with Tier-1 seating supplier dispensing equipment, enabling direct compounder relationships that bypass traditional distribution.
By volume, polyurethane leads. By expansion trajectory, aerogel is climbing the fastest.
Product Form:
Manufacturing integration requirements separate forms compatible with robotic assembly from those requiring manual installation, reshaping margin capture across the value chain.
- Blankets:Flexible aerogel-polymer composites laminated with aluminum foil facing conform to irregular battery enclosure geometries. Germany's passenger car OEMs are scaling procurement for cell-to-pack thermal runaway protection as module-level air gaps disappear.
- Foams:In-place dispensing systems integrate with automated trim and seating production lines. South Korean supplier clusters have eliminated regional distributor tiers entirely through localized captive production.
- Boards:Rigid ceramic fiber constructions occupy premium positions in European electric bus thermal management specifications.
- Coatings:Spray-applied intumescent layers face reformulation pressure from EPA REACH-equivalent reporting on perfluorinated substances.
By shipment volume, foams dominate. By specification density, blankets command the steepest expansion trajectory.
End User:
Procurement authority concentration varies—OEMs specify proprietary certifications while Tier-1 suppliers control dispensing equipment integration.
- OEMs:Passenger car manufacturers in Germany and Japan mandate proprietary material certifications that lock in dual-source requirements and extend qualification cycles. BASF SE leverages Ludwigshafen-scale polymer backbone infrastructure to sustain captive supply for thermal barrier programs.
- Tier-1 Suppliers:Seating and trim manufacturers displace traditional distribution through direct compounder relationships enabled by foam-in-place equipment compatibility.
- Aftermarket:Service channel demand concentrates on replacement thermal barriers for battery warranty repairs.
- Electric Vehicle Manufacturers:Dedicated EV producers specify thinner, higher-performance layers than legacy hybrid programs.
By contract value, OEMs lead. By channel bypass velocity, Tier-1 suppliers are gaining share fastest.
Application:
Functional convergence is collapsing thermal, acoustic, and fire-protection specifications into unified barrier systems, elevating material grade requirements.
- Thermal Insulation:Cell-to-pack architectures compress thickness requirements while maintaining five-minute no-fire propagation compliance. China's SAMR and MIIT GB standards mandate performance thresholds that directly inflate material specifications.
- Fire Protection:Flame propagation barriers dominate battery enclosure specifications. DuPont anchors North American demand through fluoropolymer film laminates facing reformulation costs from perfluorinated substance reporting.
- Acoustic Insulation:NVH performance preservation in electrified powertrains drives multilayer composite adoption.
- Vibration Damping:Structural damping layers interface with power electronics housings in high-frequency operating environments.
By specification intensity, thermal insulation leads. By regulatory pressure, fire protection is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in South Korea and Japan demonstrate the lowest price elasticity as cell-to-pack thermal barrier specifications tighten, while Indian and Southeast Asian procurement remains acutely cost-sensitive amid nascent electrification programs. Germany anchors the highest specification density globally, with OEMs mandating proprietary certifications that extend qualification cycles and lock in dual-source requirements.
Germany
Passenger car OEMs in Stuttgart and Munich are scaling procurement of battery pack insulation as thermal runaway protection mandates tighten under KBA enforcement. The country's national automotive regulator coordinates with ECHA on end-of-life vehicle recyclability directives that penalize multi-material laminates. BASF SE leverages its Ludwigshafen polymer backbone to sustain captive polyurethane supply for OEM thermal barrier programs.
China
NMPA and MIIT are accelerating domestic certification timelines for aerogel-based barrier materials as GB standards mandate five-minute no-fire propagation thresholds. SAMR enforcement of new energy vehicle fire safety regulations directly inflates insulation thickness and material grade requirements. Yangtze River Delta compounders are localizing precursor supply agreements to reduce dependency on German and US specialty chemical producers.
United States
Detroit-area assembly plants are dual-qualifying alternative laminate constructions to maintain specification continuity amid fluoropolymer reformulation pressures. EPA REACH-equivalent reporting on perfluorinated substances is compelling barrier coating reformulations that degrade legacy fire-protection performance. DuPont anchors North American demand through fluoropolymer film laminates facing temporary transition costs.
South Korea
Hyundai-Kia suppliers in Gyeonggi-do cluster are captive-producing polyurethane foam systems, eliminating import dependency and compressing regional lead times. The country's national automotive regulator aligns certification protocols with MIIT testing regimes to facilitate export market access. Localized foam production has displaced regional distributor tiers entirely through direct compounder relationships.
Japan
METI coordination on battery safety standards is elevating aerogel formulation R&D cycles as module-level air gaps disappear from cell-to-pack designs. Passenger car OEMs in Toyota City and Hiroshima are mandating thinner, higher-performance insulation layers that concentrate barrier requirements into sub-3-millimeter installations. Domestic compounders are securing precursor supply agreements to stabilize input costs for supercritical drying processes.
Global Hybrid-Electric Vehicle Insulation Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the supply base. Integrated chemical majors with captive resin synthesis capabilities capture premium positions in high-volume OEM programs, while outsourced compounders face margin compression as specification density increases. Three archetypes dominate: vertically integrated polymer producers, specialized aerogel formulators, and ceramic fiber specialists. Competitive moves concentrate on backward integration into precursor supply and geographic localization to bypass distributor tiers.
Among diversified materials conglomerates, BASF SE and DuPont exemplify scale-driven archetypes that anchor regional supply relationships through polymer backbone infrastructure. Morgan Advanced Materials occupies a specialist position representing ceramic fiber board systems. These three entities illustrate the competitive spectrum from commodity-scale chemical production through premium-positioned thermal management solutions.
| Leading Market Players |
|---|
| 3M |
| BASF SE |
| DuPont |
| Autoneum |
| Morgan Advanced Materials |
| Saint-Gobain |
| Zotefoams plc |
| Unifrax |
| Elmelin Ltd. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between German passenger car OEMs and Ludwigshafen-scale polymer producers lock in five-year price visibility while securing dedicated aerogel-polymer composite capacity for cell-to-pack thermal barrier programs. These arrangements transfer input cost volatility from silica precursor markets onto integrated chemical majors, insulating OEM procurement from supercritical drying feedstock fluctuations.
Pricing Analysis
After-sales revenue from battery warranty thermal barrier replacements drives lifetime value capture for compounders with OEM-approved service protocols. Three-tier pricing structure across OEM-certified premium grades, standard automotive specifications, and economy aftermarket tiers separates qualification-intensive cell-to-pack barriers from cost-sensitive bus retrofit applications. Cost compression in standard-grade polyurethane foams is intensifying because South Korean captive production has eliminated import markups in the Gyeonggi-do cluster. Tier-1 seating suppliers exhibit the lowest price sensitivity due to automated dispensing equipment lock-in, while Indian BIS certification applicants face acute cost pressure from extended testing timelines.
Supply Chain Analysis
Inventory buffers for aluminum-foil-laminated aerogel blankets stretch to twelve weeks in European distribution channels due to ECHA end-of-life vehicle disassembly protocol compliance overhead. Precursor supply for supercritical drying processes concentrates among specialty chemical producers in Germany and the US, drawing from tetraethyl orthosilicate and carbon dioxide feedstocks. Single-source vulnerability in silica aerogel precursor markets threatens mid-tier compounders without captive resin synthesis capabilities. Distribution runs through direct compounder relationships with Tier-1 seating suppliers, bypassing traditional sheet goods wholesalers entirely in South Korea and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against next-generation solid-state battery architectures that may eliminate liquid electrolyte thermal runaway risks and collapse barrier material specifications. Incumbents must navigate this technology transition while preserving qualification investments in existing cell-to-pack programs.
For Market Incumbents: Consolidate backward integration into tetraethyl orthosilicate precursor supply to stabilize input costs for supercritical drying processes. Lock in dual-source qualification commitments from German and Japanese OEMs before solid-state battery prototypes reach commercial scale. Prioritize R&D in sub-2-millimeter aerogel-polymer composites that maintain specification relevance even as cell formats evolve.
For New Entrants and Emerging Players: Anchor in Indian BIS certification partnerships for new energy vehicle fire safety to capture first-mover advantage before domestic compounders localize aerogel production. Target European electric bus thermal management tenders where ceramic fiber board specifications favor specialist suppliers over integrated chemical majors. Pursue foam-in-place dispensing equipment compatibility as the primary go-to-market angle to bypass entrenched distribution relationships.
For Investors and Strategic Acquirers: Formulation specialists with MIIT-approved testing partnerships in China represent the most defensible acquisition archetype for medium-term value capture. Long-term viability hinges on material science capabilities that transfer across solid-state and liquid-electrolyte battery architectures. Monitor NHTSA thermal test protocol revisions as the critical inflection signal for specification jumps that obsolete existing compound qualifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive tetraethyl orthosilicate production insulates BASF and DuPont from German and US specialty chemical price volatility. |
| MIIT Certification Partnership | Domestic testing relationships with China's automotive regulator accelerate market access ahead of GB standard enforcement timelines. |
| Foam-in-Place Equipment Integration | Automated dispensing compatibility enables Zotefoams and Autoneum to displace traditional distribution through direct Tier-1 relationships. |
| Solid-State Battery R&D Alliance | Early engagement with Toyota and QuantumScape preserves material relevance as cell architectures eliminate thermal runaway pathways. |
| ECHA Recyclability Protocol Compliance | Disassembly-ready laminate designs protect Morgan Advanced Materials from end-of-life vehicle directive penalties in European bus tenders. |
Methodological Framework
Cross-validation between OEM thermal barrier procurement directors and aerogel compounder technical sales leads anchors the qualitative findings on specification density trends. Primary interviews with Tier-1 seating supplier plant managers, KBA certification officers, and MIIT testing laboratory directors combined with secondary validation from customs trade data, SEC chemical sector filings, and vehicle production databases. Bottom-up triangulation across material grade shipment volumes and top-down reconciliation against OEM platform electrification announcements ensured segmentation integrity.
Sensitivity analysis on silica precursor cost curves and cell-to-pack adoption rates shapes the projection framework across the analysis window. Segmentation dimensions modeled include material type, product form, end-user procurement authority, and application functional requirements, with additional granularity on regional regulatory cluster alignment. CAGRs derive from compounding annual shipment growth rates adjusted for specification grade mix shifts. Key inputs encompass OEM thermal runaway protection mandate timelines and supercritical drying capacity expansion announcements.
Material uncertainties — solid-state battery commercialization schedules, perfluorinated substance regulatory bans, and precursor supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions on certification timeline stability and OEM dual-source policy persistence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
North America Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Hydrogen Vehicles Market
Hybrid Vehicles
Hybrid Cars Market
Hybrid Vehicles
India Hybrid Vehicles Market
Hybrid Vehicles
Crossovers Market
Hybrid Vehicles
Ignition Systems for Range-Extended Hybrid Powertrains Market
Hybrid Vehicles
Crossover Vehicle Market
Hybrid Vehicles
Middle East and Africa Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Europe Mild Hybrid Vehicles Market
Hybrid Vehicles
United Arab Emirates Hybrid and Electric Vehicles Market
Hybrid Vehicles
Asia-Pacific Mild-Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Train Market
Hybrid Vehicles
Canada Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Hybrid Powertrain Systems Market
Hybrid Vehicles
United States Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
North America Mild Hybrid Vehicles Market