
 Mild Hybrid Vehicles Market | 2026-2036
Mild Hybrid Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Mild Hybrid Vehicles Market Outlook
Fleet operators are unwinding reliance on pure internal combustion engine procurement as total cost of ownership calculations favor 48-volt mild hybrid architectures for high-mileage duty cycles. Toyota Motor Corporation leverages its planetary gear hybrid expertise to anchor mild hybrid variants across mass-market nameplates. BMW AG differentiates through modular 48-volt systems that extend from compact cars into performance sedans without platform redesign.
Mild hybrid vehicles deploy a 48-volt electrical subsystem with an integrated starter generator and compact lithium-ion battery pack to recover braking energy and provide torque assist to the internal combustion engine, cutting fuel consumption without full electrification complexity. The technology serves commercial and consumer markets seeking regulatory compliance at lower price points than full hybrid or battery electric alternatives. SUVs and sedans dominate volume as two-row and three-row utility vehicles absorb integrated starter generator costs into higher transaction prices, while regenerative braking hardware standardizes fastest across European and Chinese OEM lineups. Fleet operators represent the fastest-growing end user segment as telematics-validated fuel savings justify volume procurement through direct sales channels.
The EPA, EU Green Deal framework, and China's MIIT dual carbon goals collectively tighten tailpipe CO2 thresholds that mild hybrid technology satisfies without charging infrastructure dependency. NHTSA corporate average fuel economy standards and EMA fleet emission rules shape product planning timelines and powertrain investment allocation across OEM engineering centers. Stakeholders must monitor 48-volt battery cost curves and integrated starter generator manufacturing capacity in Germany, China, and Japan to calibrate procurement and platform decisions.
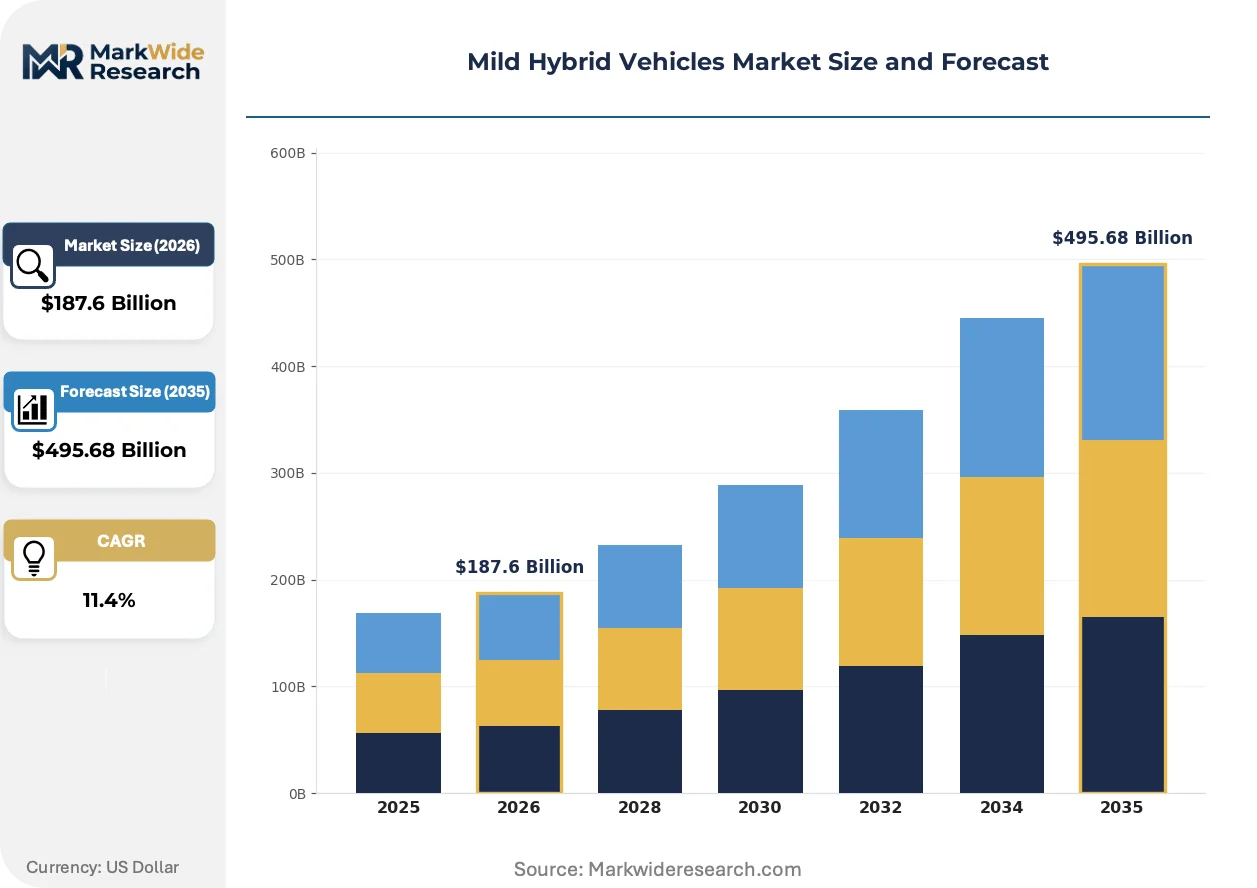
Market Dynamics
Fleet procurement departments are recalibrating capital allocation toward 48-volt architectures as total cost of ownership models incorporate carbon pricing and residual value risk from impending combustion bans.
Growth Catalysts
- EU Green Deal CO2 mandates:Fleet operators face binding emission reduction targets that 48-volt mild hybrids satisfy without charging infrastructure investment, accelerating procurement of integrated starter generator-equipped vans and sedans.
- Urban last-mile delivery expansion:E-commerce fulfillment networks in Germany and China are standardizing mild hybrid powertrains for stop-start route density where regenerative braking recovery rates peak.
- Integrated starter generator cost curves:Manufacturing scale in Chinese and German component clusters has compressed belt-driven and crankshaft-mounted system pricing toward parity with conventional starter-alternator assemblies.
Market Restraints
- Lithium-ion cell supply concentration:48-volt battery pack output depends on cathode material flows concentrated in Chinese refining operations, exposing OEMs to export control volatility and forced labor compliance audits.
- Full hybrid and battery electric substitution:Toyota's planetary gear systems and BYD's blade battery packs are capturing fleet buyers willing to absorb higher upfront capital for superior fuel economy or zero-emission zone access.
- EPA certification timeline compression:Powertrain validation cycles for 48-volt integration are extending as the agency tightens real-driving emission test protocols, delaying model year launches.
Strategic Opportunities
- India's PLI scheme for automotive:Domestic integrated starter generator manufacturing incentives are opening procurement pathways for export-oriented compact SUV platforms serving Middle East and African markets.
- Commercial vehicle electrification gaps:Light commercial van segments between 3.5 and 7.5 tonnes gross vehicle weight lack cost-effective full battery electric solutions, creating white space for 48-volt mild hybrid box trucks.
- Telematics-validated fuel economy:Fleet management platforms from Geotab and Samsara are generating auditable efficiency data that finance departments use to justify mild hybrid capital expenditure against diesel alternatives.
Industry Challenges
- Power electronics integration complexity:DC-DC converter and battery management system calibration demands software engineering talent scarce in traditional mechanical engineering centers, forcing OEMs to acquire or partner with semiconductor specialists.
- Legacy dealership service infrastructure:High-voltage safety certification requirements for 48-volt systems exceed conventional technician training, creating aftermarket service bottlenecks and warranty cost uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mild Hybrid Vehicles Market |
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $495.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Cars, SUVs, Sedans, Trucks Technology: Integrated Starter Generator, DC-DC Converter, Lithium-ion Battery, Regenerative Braking End User: Individual Consumers, Fleet Operators, Car Rental Services, Businesses Sales Channel: Online Sales, Dealerships, Auctions, Direct Sales |
| Companies Covered | Honda Motor Company Ltd, BMW AG, Toyota Motor Corporation, Daimler AG, Ford Motor Company, Volkswagen Group, Suzuki Motor Corporation, Volvo Group, Hyundai Motor Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mild Hybrid Vehicles Market Strategic Shifts
Powertrain engineering departments are converging on modular electrical architectures that decouple 48-volt subsystem design from internal combustion engine displacement, enabling faster platform refresh cycles.
Silicon carbide power semiconductors are replacing silicon MOSFETs in 48-volt inverter designs, cutting switching losses and enabling higher continuous power density for integrated starter generators. Tier-1 suppliers in Germany and Japan are qualifying automotive-grade SiC modules for 2027 model year programs. This transition is fragmenting supplier tiers as semiconductor foundries capture margin previously held by conventional automotive electronics assemblers.
China's MIIT dual carbon implementation rules are tightening corporate average fuel consumption targets for domestic OEMs, forcing accelerated 48-volt rollout across mass-market nameplates previously optimized for cost minimization. The regulation compresses engineering timelines for joint venture partners importing European powertrain intellectual property. Domestic brands including Geely and Great Wall are responding with in-house integrated starter generator development to reduce royalty outflows.
Corporate fleet leasing structures are incorporating fuel economy guarantee clauses where lessors absorb variance risk against telematics-reported consumption baselines. This transfer of operating risk from lessee to lessor is restructuring procurement evaluation criteria toward total cost of ownership certainty rather than sticker price minimization. German and Dutch fleet management companies are piloting these contracts most aggressively, with expansion into Scandinavian markets contingent on carbon tax pass-through mechanisms.
Mild Hybrid Vehicles Market Segmentation
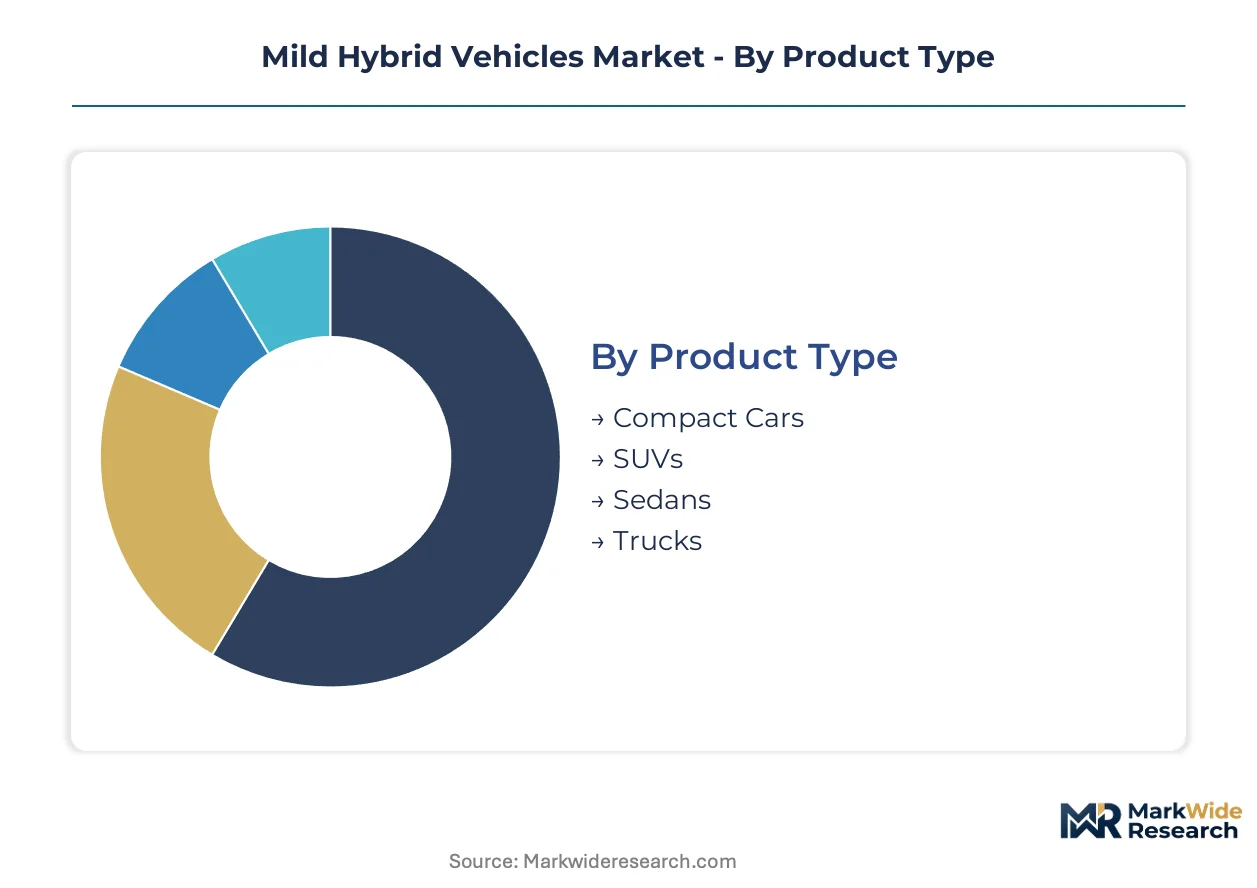
Mild hybrid vehicle segmentation reveals how 48-volt architectures adapt across vehicle classes and procurement channels. Regulatory thresholds vary by vehicle mass and duty cycle, creating differentiated compliance economics for each segment.
Product Type:
EU Green Deal CO2 fleet targets enforce stricter caps on lighter vehicle classes, pushing OEMs to prioritize mild hybrid integration where certification margins are tightest.
- SUVs:Two-row and three-row utility vehicles absorb integrated starter generator costs into higher transaction prices. German and Chinese OEMs concentrate production of 48-volt mild hybrid SUVs for executive transport pools and family buyers seeking regulatory compliance without range anxiety.
- Sedans:Mid-size and full-size sedans deploy belt-driven starter generator systems for urban delivery fleets and corporate leasing channels. The segment balances fuel economy certification requirements against cabin space and trunk volume priorities.
- Compact Cars:A-segment and B-segment hatchbacks integrate crankshaft-mounted systems to meet MIIT corporate average fuel consumption targets in China.
- Trucks:Light commercial pickups between 3.5 and 7.5 tonnes gross vehicle weight adopt 48-volt subsystems for stop-start duty cycles in last-mile logistics.
Established volume favors SUVs; emerging adoption favors Trucks.
Technology:
Component cost curves determine which 48-volt subsystems penetrate mass-market nameplates versus remaining confined to premium trim levels.
- Integrated Starter Generator:Belt-driven and crankshaft-mounted systems recover braking energy and provide torque assist. Manufacturing scale in German and Chinese component clusters has compressed pricing toward parity with conventional starter-alternator assemblies.
- Lithium-ion Battery:Compact 48-volt packs store regenerative braking energy. Cathode material flows concentrated in Chinese refining operations expose OEMs to export control volatility.
- Regenerative Braking:Friction-brake integration hardware standardizes fastest across European OEM lineups.
- DC-DC Converter:Power electronics bridge 48-volt and 12-volt electrical domains.
Integrated Starter Generator captures dominant procurement share; DC-DC Converter is climbing the fastest as silicon carbide modules qualify for production.
End User:
Total cost of ownership calculations diverge sharply between high-mileage commercial operators and low-utilization private buyers.
- Fleet Operators:Telemetrics-validated fuel savings justify volume procurement through direct sales channels. E-commerce fulfillment networks in Germany and China standardize mild hybrid powertrains for stop-start route density.
- Individual Consumers:Private buyers respond to sticker price premiums against fuel economy labeling. Residual value risk from impending combustion bans influences purchase timing.
- Businesses:Corporate fleet leasing structures incorporate fuel economy guarantee clauses where lessors absorb variance risk.
- Car Rental Services:Daily rental operators prioritize acquisition cost minimization over lifetime fuel savings.
Fleet Operators command steepest expansion trajectory; Car Rental Services lag in conversion rates.
Sales Channel:
Channel economics reshape how OEMs allocate 48-volt inventory between margin-defending retail networks and volume-driving direct contracts.
- Direct Sales:Fleet procurement departments negotiate enterprise contracts bypassing dealer markups. Finance departments use telematics data to justify mild hybrid capital expenditure.
- Dealerships:Franchise networks face high-voltage safety certification requirements exceeding conventional technician training.
- Online Sales:Digital configurators expose trim-level powertrain pricing transparency.
- Auctions:Secondary market liquidity for off-lease mild hybrid units remains thin.
Direct Sales is gaining share fastest; Auctions remain underdeveloped for 48-volt remarketing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated starter generator manufacturing clusters in Germany, China, and Japan supply 48-volt subsystems to assembly plants worldwide. OEM engineering centers localize mild hybrid production to satisfy national CO2 regulations and fleet procurement requirements.
Germany
KBA type-approval standards enforce WLTP emission ceilings that mild hybrid architectures satisfy cost-effectively. The EU Green Deal framework mandates fleet CO2 reductions that 48-volt systems deliver without charging infrastructure. Stuttgart and Munich host belt-driven integrated starter generator production for premium SUV and sedan nameplates serving executive transport pools.
China
MIIT dual carbon implementation rules tighten corporate average fuel consumption targets for domestic OEMs. GB standards for passenger vehicle energy consumption push mass-market brands toward 48-volt integration. Yangtze River Delta component clusters in Shanghai and Jiangsu province manufacture crankshaft-mounted systems for compact car platforms.
United States
EPA tailpipe standards and NHTSA corporate average fuel economy rules shape powertrain investment allocation. Fleet operators in urban logistics corridors recalibrate procurement toward 48-volt architectures as telematics validate fuel savings. Michigan and Tennessee assembly plants integrate belt-driven systems into light truck and SUV production for commercial lease channels.
Japan
METI energy efficiency guidelines favor mild hybrid deployment where full electrification infrastructure remains underdeveloped. JIS standards for automotive electrical systems accommodate 48-volt subsystem integration. Toyota City and Nagoya engineering centers leverage planetary gear hybrid expertise to anchor mild hybrid variants across mass-market nameplates.
India
PLI scheme incentives for automotive manufacturing attract integrated starter generator production for export-oriented compact SUV platforms. BIS fuel efficiency norms drive 48-volt adoption in stop-start urban duty cycles. Tamil Nadu and Gujarat component clusters supply belt-driven systems to domestic OEMs serving Middle East and African markets.
Mild Hybrid Vehicles Market Competitive Environment
Concentration sits with established automotive OEMs possessing planetary gear hybrid expertise and modular 48-volt system capabilities. The competitive structure tiers between mass-market volume producers, premium modular system specialists, and commercial vehicle integrators. Three archetypes dominate: full-line manufacturers scaling integrated starter generator production across SUV and sedan nameplates; premium brands extending 48-volt architectures into performance segments; and commercial vehicle specialists targeting light truck fleet procurement. Dominant competitive moves include backward integration into power electronics manufacturing and strategic partnerships with semiconductor foundries for silicon carbide module supply.
Among established full-line manufacturers, Toyota Motor Corporation, BMW AG, and Volkswagen Group occupy positions spanning mass-market deployment through premium modular integration. Toyota represents the planetary gear hybrid expertise archetype. BMW exemplifies premium-tier 48-volt system extension across vehicle classes without platform redesign. Volkswagen sits within the volume-scaled integration archetype, standardizing belt-driven architectures across multiple nameplates.
| Leading Market Players |
|---|
| Honda Motor Company Ltd |
| BMW AG |
| Toyota Motor Corporation |
| Daimler AG |
| Ford Motor Company |
| Volkswagen Group |
| Suzuki Motor Corporation |
| Volvo Group |
| Hyundai Motor Company |
| Others |
Value Chain & Pricing Dynamics
Manufacturing scale in Yangtze River Delta and Stuttgart component clusters compresses integrated starter generator pricing toward parity with conventional starter-alternator assemblies, anchoring price floors for fleet procurement contracts. This concentration of 48-volt subsystem production capacity in Germany and China creates tiered procurement power where volume buyers extract steeper discounts than fragmented retail channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates belt-driven systems for luxury SUVs from crankshaft-mounted units in mass-market compacts and entry-level belt-alternator starters in light trucks. Price differentiation hinges on torque output certification and after-sales service bundling. Cost compression in standard-tier 48-volt packs is intensifying because Chinese cathode material refining capacity is expanding faster than cell demand. Fleet operators exhibit lowest price sensitivity due to telematics-validated total cost of ownership models, while individual consumers in emerging markets resist premiums above conventional powertrains.
Supply Chain Analysis
Cathode material refining concentration in Chinese Jiangsu and Hunan provinces exposes OEMs to export control volatility and forced labor compliance audit risk. The 48-volt battery supply chain draws from lithium carbonate feedstocks anchored in Chile and Australia, silicon carbide wafers sourced from Japanese and German foundries, and copper winding materials from Zambian concentrate. Single-source vulnerability concentrates in belt-driven integrated starter generator crankshaft mounting hardware where German Tier-1 suppliers hold process patents. Distribution runs through direct OEM supply agreements for fleet volumes and franchised dealer networks for retail replacement parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mild hybrid vehicle adoption sits in early-cycle expansion as EU Green Deal CO2 enforcement tightens fleet emission ceilings without charging infrastructure mandates, accelerating procurement decisions previously deferred to full electrification timelines.
For Market Incumbents: Secure silicon carbide module supply through captive partnerships with Japanese and German semiconductor foundries before 2027 model year qualification deadlines. Lock in long-term cathode material offtake from Chilean and Australian mining operations to insulate against Chinese export control volatility. Defensive positioning requires accelerating crankshaft-mounted integrated starter generator production in India PLI-subsidized facilities to serve Middle East and African export markets before domestic competitors achieve scale. For New Entrants and Emerging Players: Fleet telematics integration services represent an under-served layer where incumbent OEMs lack software-native capabilities. White-space targets include fuel economy guarantee contract structuring for German and Dutch fleet lessors, and aftermarket 48-volt technician certification programs addressing dealership service bottlenecks. The most penetrable entry point is light commercial van segments between 3.5 and 7.5 tonnes gross vehicle weight where full battery electric solutions remain cost-prohibitive. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors power electronics specialists with silicon carbide inverter design capabilities and automotive-grade qualification track records. Long-term viability over the next decade hinges on 48-volt architectures serving as bridge compliance solutions through 2035 emission phase-out timelines in key markets. Acquisition targets include Tier-2 semiconductor packaging operations and battery management system firmware developers. The signal to watch is EPA real-driving emission test protocol tightening, which would extend powertrain validation cycles and favor incumbents with existing certification infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Module Qualification | Automotive-grade SiC inverter production enables higher power density integrated starter generators for 2027 model year programs. |
| India PLI Manufacturing Footprint | Domestic integrated starter generator production attracts export-oriented compact SUV platform sourcing for Middle East markets. |
| Fleet Telematics Partnership | Geotab and Samsara platform integration generates auditable fuel economy data that finance departments use to justify mild hybrid capital expenditure. |
| Cathode Material Supply Agreement | Long-term lithium carbonate offtake from Chilean mining operations reduces exposure to Chinese refining export control volatility. |
| Aftermarket Technician Certification | High-voltage safety training programs address dealership service bottlenecks and warranty cost uncertainty for 48-volt systems. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of OEM production databases, EPA certification filings, EU type-approval registries, and MIIT corporate average fuel consumption disclosures. The research team conducted structured interviews with Tier 1 supplier procurement directors, OEM platform engineering leads, fleet management company operations heads, and automotive semiconductor foundry account managers. Secondary validation sources include IHS Markit vehicle registration data, customs trade records for 48-volt battery pack imports, and SEC 10-K filings from listed automotive electronics suppliers. Bottom-up unit shipment estimates triangulate against top-down OEM powertrain investment allocation data.
Segmentation dimensions modeled span vehicle class, propulsion architecture configuration, integrated starter generator mounting type, and regional production cluster. The analytical framework projects volume and value across the analysis window by applying adoption curves derived from regulatory compliance deadlines and fleet procurement cycle timing. CAGRs emerge from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific forecast inputs include WLTP and EPA emission test protocol evolution assumptions, lithium-ion cell cost curve trajectories, and silicon carbide module manufacturing yield improvements.
Underlying assumptions cover EU Green Deal enforcement continuity, Chinese dual carbon target adherence, and stable cathode material trade flows, with deviation risk concentrated in EPA certification timeline compression and export control expansion. Forecasts reflect these baseline conditions without contingency weighting. Practitioners should keep alternative scenarios live as regulatory stringency trajectories and semiconductor supply availability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
Plug-In Hybrid Electric Vehicles (PHEV) Market
Hybrid Vehicles
Hybrid Powertrain Systems Market
Hybrid Vehicles
India Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Cars Market
Hybrid Vehicles
Hybrid Electric Self-Driving Car Market
Hybrid Vehicles
Europe Mild Hybrid Vehicles Market
Hybrid Vehicles
Germany Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Hydrogen Fuel Automotive Market
Hybrid Vehicles
Global Hybrid-Electric Vehicle Insulation Market
Hybrid Vehicles
Hybrid Truck Market
Hybrid Vehicles
Smart Hybrid Vehicle Market
Hybrid Vehicles
North America Mild Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Drivetrain Market
Hybrid Vehicles
North America Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Hybrid Vehicle Market
Hybrid Vehicles
Crossovers Market