
 Asia-Pacific Micro-Hybrid Vehicles Market | 2026-2036
Asia-Pacific Micro-Hybrid Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Micro-Hybrid Vehicles Market Outlook
The micro-hybrid market in Asia-Pacific is decoupling along the fault line between integrated start-stop systems with lithium-ion battery management and commodity lead-acid based entry configurations. Toyota Motor Corporation leverages its Prius-derived regenerative braking intellectual property to dominate premium sedan deployments across Japan and Thailand. Mahindra & Mahindra Limited anchors its position in India's compact utility segment through captive supply of localized electric motor assemblies. Hyundai Motor Company competes aggressively in South Korea's fleet channel with scalable start-stop platforms that span SUV and crossover architectures.
Micro-hybrid vehicles integrate an internal combustion engine with a small electric motor and energy storage system that enables engine shutoff during idle, kinetic energy recovery through regenerative braking, and torque assist during acceleration, typically employing 48V electrical architecture or 12V enhanced starter-generator designs. The primary purpose is to reduce fuel consumption and CO2 emissions without the cost and infrastructure burden of full electrification. Compact car and SUV product types lead volume penetration due to their price-sensitive positioning and high urban stop-go duty cycles, while start-stop technology captures the dominant share of installations as the baseline micro-hybrid function. Regenerative braking and battery management systems represent the fastest-growing technology segments as OEMs pursue incremental efficiency gains beyond simple idle shutdown.
China's MIIT enforces GB standards for new energy vehicle efficiency that effectively mandate micro-hybrid inclusion in conventional ICE portfolios, while India's BIS certification requirements and Automotive Research Association test protocols shape product qualification timelines for domestic manufacturers. Japan's METI coordinates with JIS standards bodies to harmonize 48V system safety specifications across kei-car and standard passenger vehicle categories. Stakeholders must monitor how India's PLI scheme revisions and China's SAMR antitrust scrutiny of battery supply contracts reshape competitive access to critical lithium-ion cell capacity.
Market Dynamics
The Asia-Pacific micro-hybrid market is bifurcating between 48V lithium-ion architectures and cost-optimized 12V enhanced starter-generator systems, with procurement decisions increasingly driven by fleet electrification mandates rather than consumer preference.
Growth Catalysts
- India's PLI scheme for automotive electrification components:Localized battery management system production is accelerating as component suppliers establish captive manufacturing in the Maharashtra-Gujarat corridor to qualify for performance-linked incentives.
- Fuel-efficiency mandates tightening across urban logistics:Fleet operators in last-mile delivery and municipal transport are expanding micro-hybrid procurement to comply with municipal emission restrictions in Tier-1 Chinese cities and Indian metropolitan regions.
- Regenerative braking technology maturation:Kinetic energy recovery systems are achieving cost parity with conventional alternators, enabling broader deployment beyond premium vehicle segments into compact SUVs and hatchbacks.
Market Restraints
- Lithium-ion cell supply concentration:Cathode active material processing capacity clusters predominantly in China's Fujian and Hunan provinces, creating single-source vulnerability for battery management system integrators across the region.
- Lead-acid battery cost floor:Mature recycling infrastructure and established supply chains for enhanced flooded batteries in Southeast Asia create persistent price competition against 48V lithium-ion alternatives.
- Technical limitation in cold-start performance:Start-stop system reliability degrades significantly below minus ten degrees Celsius, constraining deployment viability in northern Chinese provinces and Himalayan-adjacent Indian states.
Strategic Opportunities
- Underpenetrated Indonesian commercial vehicle segment:Jakarta's diesel fleet renewal programs and nascent emission testing regimes create first-mover advantage for micro-hybrid retrofit providers targeting light commercial vehicles.
- Technology convergence between 48V mild-hybrid and full-hybrid architectures:Shared electric motor and power electronics platforms enable OEMs to scale component volumes across electrification tiers, reducing per-unit engineering costs.
- Vietnam's emerging automotive manufacturing base:VinFast's domestic supplier development programs and the country's free trade agreements with EU markets position micro-hybrid component exports as a strategic growth vector.
Industry Challenges
- Power electronics engineering talent scarcity:Specialized expertise in bidirectional DC-DC converter design and 48V system safety architecture remains concentrated in Japan and South Korea, constraining Indian and Chinese supplier technical autonomy.
- Certification timeline compression:India's BIS and Automotive Research Association test protocols for start-stop durability and electromagnetic compatibility extend product qualification cycles by eight to fourteen months versus conventional powertrain components.
- Integration complexity with legacy 12V electrical architectures:Dual-voltage system design requires substantial wiring harness redesign and fuse protection recalibration, complicating platform migration for established vehicle programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Micro-Hybrid Vehicles Market |
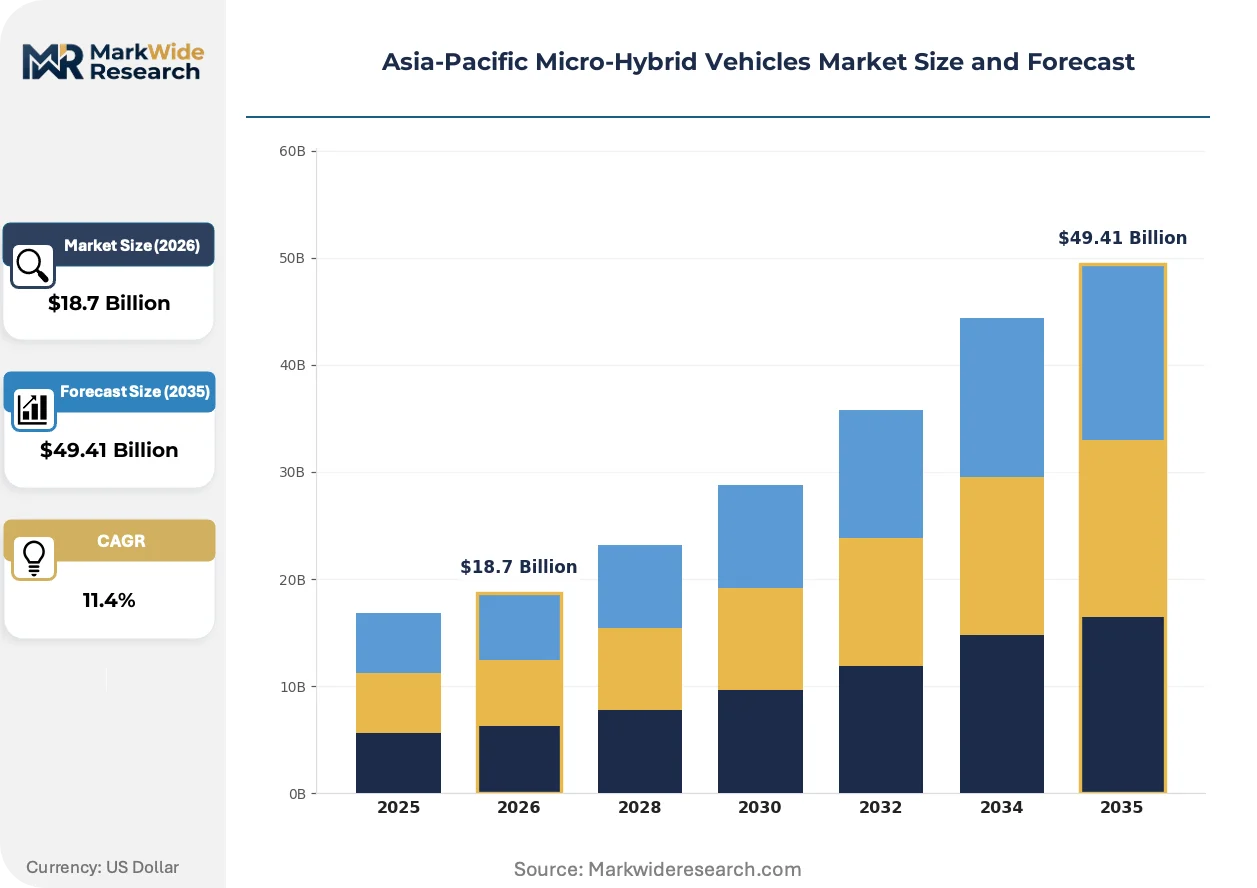
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Car, SUV, Sedan, Crossover Technology: Start-Stop, Regenerative Braking, Electric Motor, Battery Management End User: Private Customers, Fleet Operators, Government Entities, Car Rental Services Market Channel: Online Sales, Dealerships, Direct Sales, Auction Platforms |
| Companies Covered | Toyota Motor Corporation, Honda Motor Company, Nissan Motor Company Ltd, Mahindra & Mahindra Limited, Toshiba Corporation, Hyundai Motor Company, Kia Motors Corporation, BMW AG, Mercedes Benz Group AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Micro-Hybrid Vehicles Market Strategic Shifts
Intelligent battery management systems are automating real-time charge optimization and predictive thermal control, compressing the efficiency gap between micro-hybrid and full-hybrid architectures while reducing calibration burden on OEM engineering teams.
Predictive state-of-charge algorithms are automating engine restart timing and accessory load prioritization based on route topography and traffic pattern data. Tier-1 suppliers in South Korea are deploying these systems at scale for domestic OEM fleet contracts. The technology is automating the transition from reactive start-stop logic to anticipatory energy management, enabling fuel savings beyond laboratory test cycles.
China's MIIT enforcement of GB standards for new energy vehicle efficiency is mandating micro-hybrid inclusion in conventional ICE portfolios above specified vehicle mass thresholds. Domestic OEMs are responding by standardizing 48V belt-integrated starter-generator systems across mid-size sedan and SUV platforms. The regulation is compressing technology adoption timelines that previously followed voluntary corporate average fuel consumption commitments.
Fleet procurement consolidation is concentrating volume decisions among logistics operators and ride-hailing platforms with standardized vehicle specifications. Direct OEM-fleet contracting in India's urban delivery segment is displacing traditional dealer-channel purchases for start-stop equipped compact utilities. This concentration is most visible in Maharashtra and Karnataka, where municipal emission mandates coincide with e-commerce fulfillment network expansion.
Asia-Pacific Micro-Hybrid Vehicles Market Segmentation
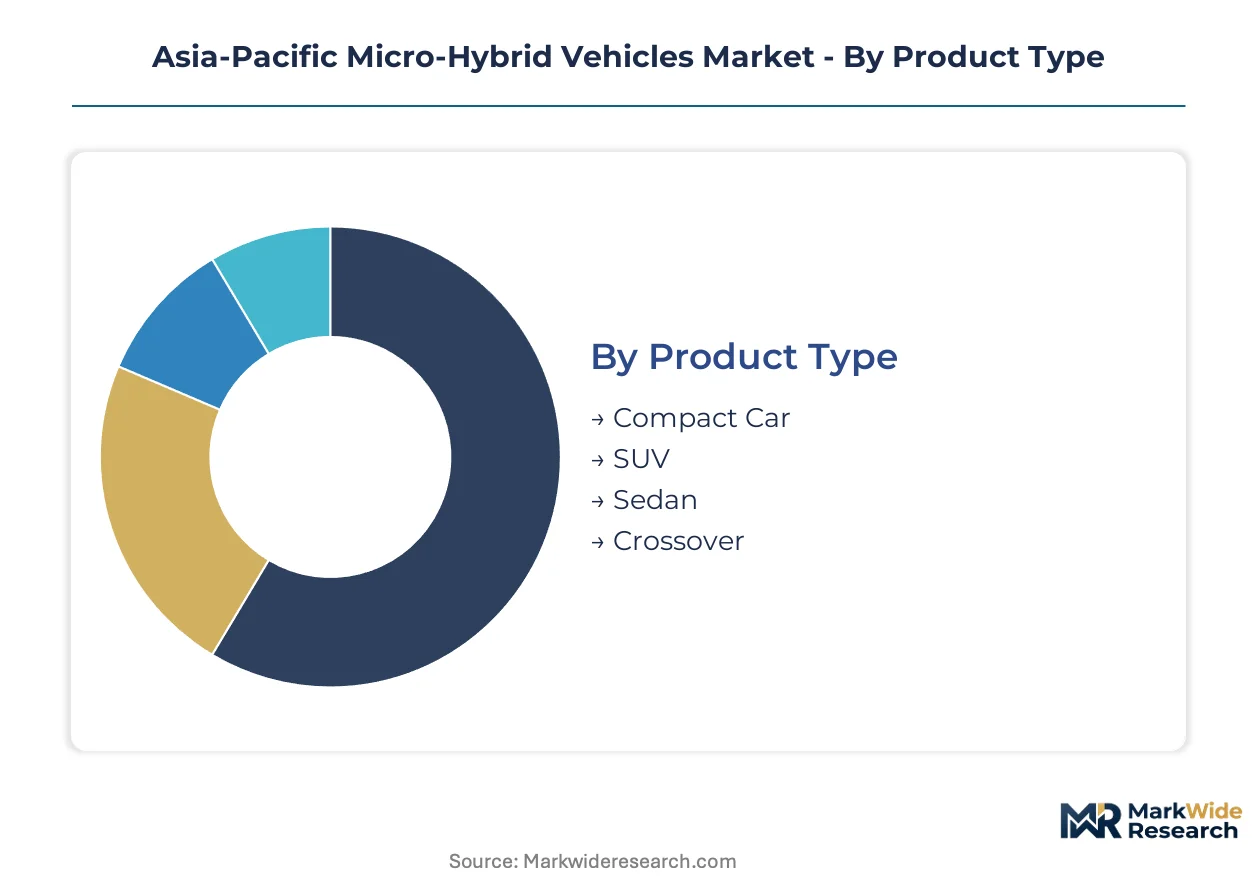
Segmentation in the Asia-Pacific micro-hybrid market exposes divergent technology economics across vehicle architectures and procurement channels. Fleet operators and private buyers prioritize different performance thresholds, while regulatory pressure varies by end-user category.
Product Type:
Vehicle mass and duty cycle patterns determine micro-hybrid system specification and payback period for fuel savings.
- Compact Car:High urban stop-go density in Indian and Southeast Asian cities maximizes start-stop activation frequency. Maharashtra and Karnataka municipal fleets specify compact micro-hybrids for last-mile delivery compliance with emission mandates.
- SUV:Heavier curb weights demand 48V belt-integrated starter-generator systems rather than 12V enhanced starters. China's Yangtze River Delta manufacturing cluster concentrates SUV micro-hybrid output for domestic consumption and ASEAN export.
- Sedan:Toyota's Prius-derived regenerative braking platforms dominate premium sedan deployments across Japan and Thailand.
- Crossover:Hyundai's scalable start-stop architectures span crossover volumes in South Korea's fleet channel.
Compact car leads on scale; SUV leads on momentum.
Technology:
System complexity tiers separate commodity 12V configurations from 48V lithium-ion architectures with bidirectional power flow.
- Start-Stop:Baseline idle shutdown function employs enhanced flooded or absorbed glass mat batteries. Cold-start reliability degradation below minus ten degrees Celsius constrains deployment in northern Chinese provinces and Himalayan-adjacent Indian states.
- Regenerative Braking:Kinetic energy recovery achieves cost parity with conventional alternators, enabling broader deployment into compact SUVs and hatchbacks beyond premium segments. South Korean Tier-1 suppliers deploy predictive state-of-charge algorithms at scale for domestic OEM fleet contracts.
- Electric Motor:Belt-integrated and crankshaft-mounted designs serve distinct torque assist requirements.
- Battery Management:Intelligent systems automate real-time charge optimization and predictive thermal control, compressing the efficiency gap with full-hybrid architectures.
Start-Stop leads on scale; regenerative braking leads on momentum.
End User:
Procurement concentration and specification standardization vary sharply across buyer categories.
- Private Customers:Price-sensitive retail buyers in India and Southeast Asia favor 12V enhanced starter-generator systems for their lower upfront cost versus 48V alternatives.
- Fleet Operators:Direct OEM-fleet contracting in India's urban delivery segment displaces traditional dealer-channel purchases. Logistics operators and ride-hailing platforms consolidate volume decisions with standardized vehicle specifications.
- Government Entities:Municipal transport procurement in Tier-1 Chinese cities and Indian metropolitan regions expands micro-hybrid adoption for emission compliance.
- Car Rental Services:Fleet renewal cycles align with manufacturer incentive programs for start-stop equipped vehicles.
Fleet operators lead on scale; government entities lead on momentum.
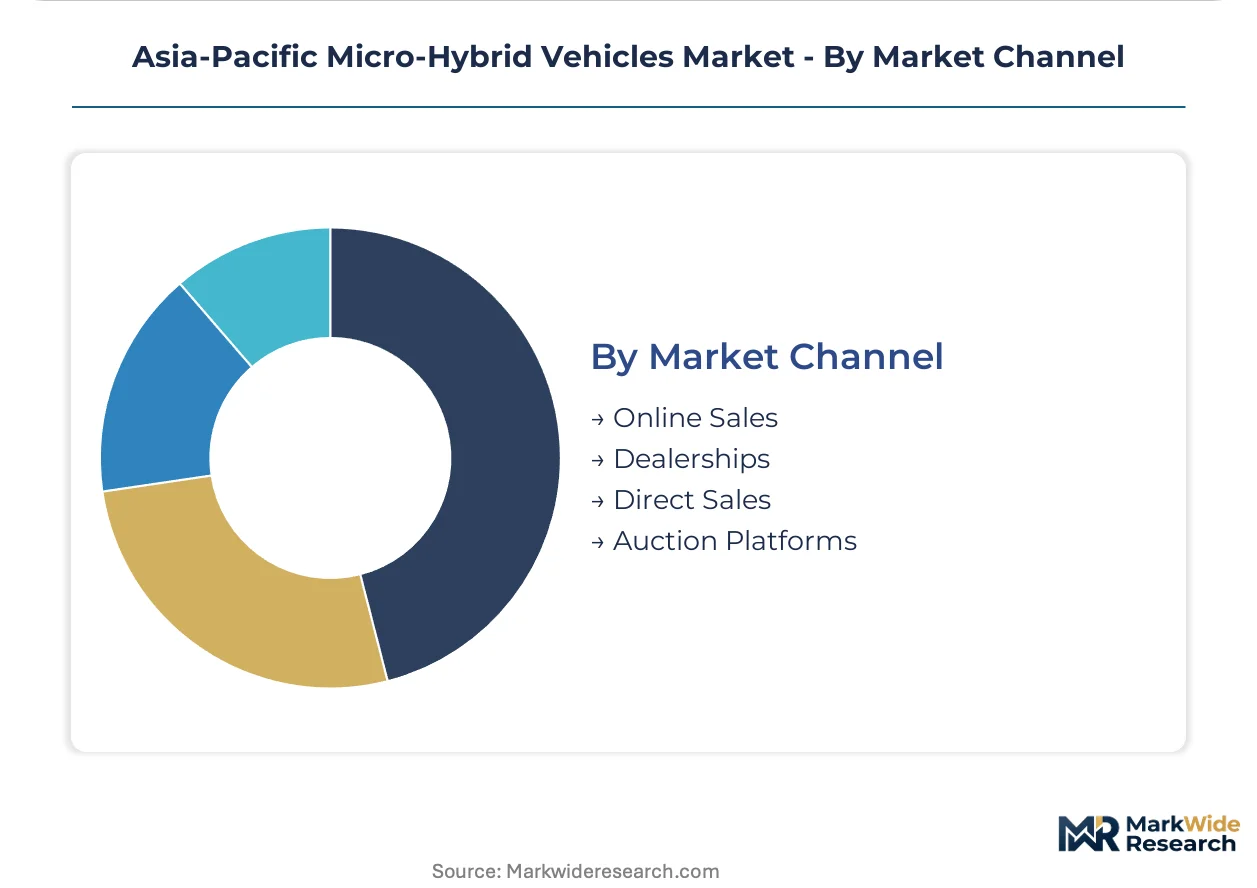
Market Channel:
Channel economics reflect vehicle specification complexity and buyer relationship requirements.
- Online Sales:Digital platforms gain traction for standardized compact car configurations with transparent pricing.
- Dealerships:Traditional retail networks retain dominance for private customer segments requiring test drive and financing facilitation.
- Direct Sales:OEM-fleet contracting bypasses dealer markups for volume fleet operator and government procurement in Maharashtra-Gujarat corridor.
- Auction Platforms:Secondary market channels serve rental fleet disposals and commercial vehicle remarketing.
Dealerships lead on scale; direct sales leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT enforcement of GB standards outpaces India's PLI scheme rollout, creating divergent compliance timelines across the region's two largest automotive markets.
China
Domestic OEMs standardize 48V belt-integrated starter-generator systems across mid-size sedan and SUV platforms to meet MIIT efficiency mandates. The Yangtze River Delta manufacturing cluster concentrates SUV micro-hybrid output for domestic consumption and ASEAN export channels.
India
Maharashtra and Karnataka municipal fleets specify compact micro-hybrids for last-mile delivery compliance with tightening emission restrictions. The PLI scheme for automotive electrification components accelerates localized battery management system production in the Maharashtra-Gujarat corridor.
Japan
METI coordinates with JIS standards bodies to harmonize 48V system safety specifications across kei-car and standard passenger vehicle categories. Toyota leverages Prius-derived regenerative braking intellectual property to dominate premium sedan deployments.
South Korea
Hyundai Motor Company competes aggressively in the fleet channel with scalable start-stop platforms spanning SUV and crossover architectures. Tier-1 suppliers deploy predictive state-of-charge algorithms at scale for domestic OEM fleet contracts.
Thailand
Japanese OEMs extend premium sedan micro-hybrid deployments from domestic plants to serve ASEAN export markets. Bangkok's logistics operators face municipal emission mandates that mirror Tier-1 Chinese city restrictions.
Asia-Pacific Micro-Hybrid Vehicles Market Competitive Environment
Top-tier vendors anchor integrated powertrain platforms, while mid-tier suppliers compete on localized component cost. The vendor base stratifies across three tiers: full-system integrators with captive battery management expertise, regional electric motor specialists serving fleet channels, and commodity battery suppliers competing on lead-acid recycling economics. Strategic moves concentrate on backward integration into lithium-ion cell sourcing and technology licensing agreements for 48V system architectures.
Within the integrated-system tier, Toyota Motor Corporation and Hyundai Motor Company exemplify divergent geographic anchoring strategies. Toyota represents the Japan-centered premium sedan deployment model, while Hyundai occupies a position within South Korea's fleet-centric volume channel. Mahindra & Mahindra Limited anchors the India-focused compact utility segment through in-house production of localized electric motor assemblies.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Honda Motor Company |
| Nissan Motor Company Ltd |
| Mahindra & Mahindra Limited |
| Toshiba Corporation |
| Hyundai Motor Company |
| Kia Motors Corporation |
| BMW AG |
| Mercedes Benz Group AG |
| Others |
Value Chain & Pricing Dynamics
Power electronics engineering talent concentration in Japan and South Korea widens labor-cost differentials against emerging manufacturing hubs, compressing pricing-tier spreads between 48V lithium-ion architectures and commodity 12V configurations. Tier-1 suppliers leverage specialized expertise in bidirectional DC-DC converter design to command premium positioning, while regional electric motor specialists in India compete on localized assembly economics.
Pricing Analysis
Bundled battery management system integration versus unbundled component procurement separates premium 48V deployments from entry-level 12V enhanced starter-generator configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under China's GB standards and India's BIS protocols. Cost compression in the 12V segment is intensifying because lead-acid recycling infrastructure in Southeast Asia sustains persistent price competition against lithium-ion alternatives. Fleet operators exhibit lowest price sensitivity due to total-cost-of-ownership optimization mandates, while private retail buyers in India and Southeast Asia favor upfront cost minimization.
Supply Chain Analysis
Cathode active material processing capacity rests predominantly on China's Fujian and Hunan provinces, creating concentrated upstream dependency for battery management system integrators across the region. Lithium-ion cell supply draws from South Korean and Japanese specialty producers alongside Chinese domestic capacity, while belt-integrated starter-generator assemblies hinge on German and Japanese precision manufacturing inputs. Single-source vulnerability in cathode precursor processing exposes Tier-1 suppliers to regulatory restriction risk under China's SAMR antitrust scrutiny. Distribution runs through direct OEM-fleet contracting channels in India's Maharashtra-Gujarat corridor and traditional dealership networks for private customer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific micro-hybrid vehicles market functions as a stable compounder, with regulatory enforcement of fuel-efficiency mandates across China and India providing predictable demand visibility irrespective of consumer preference volatility.
For Market Incumbents: Anticipate technology convergence pressure between 48V mild-hybrid and full-hybrid architectures by standardizing electric motor and power electronics platforms across electrification tiers. Prioritize backward integration into lithium-ion cell sourcing to defend against supply concentration risk in China's cathode processing corridor. OEMs must monitor India's PLI scheme revisions for localized battery management production incentives that could reshape competitive access.
For New Entrants and Emerging Players: Launch via direct fleet contracting models targeting Indonesia's underpenetrated commercial vehicle segment, where Jakarta's diesel fleet renewal programs create first-mover advantage for micro-hybrid retrofit providers. Focus initial deployment on light commercial vehicles in ASEAN markets with nascent emission testing regimes. Partner with established Tier-1 suppliers for 48V system architecture licensing to compress product qualification timelines.
For Investors and Strategic Acquirers: Automotive OEMs with captive electrification platforms are the most active acquirer in this space, seeking regional electric motor specialists with localized manufacturing footprints. Long-term viability centers on component suppliers capable of spanning 48V and full-hybrid technology convergence. Monitor India's BIS certification timeline compression and China's SAMR battery supply contract scrutiny as inflection indicators for competitive access restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Shared 48V and full-hybrid electric motor architectures reduce per-unit engineering costs for Hyundai and Toyota. |
| Battery Supply Agreement | Direct cathode precursor contracts with Fujian and Hunan processors mitigate single-source vulnerability for Tier-1 integrators. |
| Software-Defined Vehicle Investment | Predictive state-of-charge algorithms automate engine restart timing for South Korean Tier-1 fleet deployments. |
| Geographic Manufacturing Footprint | Mahindra's Maharashtra-Gujarat corridor localization qualifies for India's PLI scheme performance-linked incentives. |
| Charging Infrastructure Partnership | Technology convergence positions 48V micro-hybrid suppliers for full-hybrid upgrade pathways in Vietnam's emerging base. |
Study Parameters
Coverage spans China, India, Japan, South Korea, and Southeast Asia, with primary inputs from each market combining structured interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet operator specification managers alongside secondary validation. Regulatory filings from China's MIIT, India's BIS, and Japan's METI supplement vehicle production databases and customs trade records. Bottom-up component demand modeling and top-down OEM platform deployment analysis triangulate volume and value estimates.
Granularity-level modeling operates at vehicle class, propulsion architecture, and regional production cluster dimensions across the analysis window. CAGRs derive from segment-level growth rate synthesis calibrated against OEM platform rollout schedules and regulatory compliance timeline assumptions. Forecast inputs incorporate MIIT GB standard enforcement trajectories, India's PLI scheme incentive disbursement patterns, and fleet procurement concentration indices in urban logistics channels.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium-ion cell supply disruption scenarios and PLI scheme revision uncertainty. Assumptions reflect documented regulatory enforcement patterns and OEM platform standardization commitments. Supply chain restructuring under China's SAMR scrutiny and cold-start performance limitations in northern provinces warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
Europe Mild Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Electric Vehicle Market
Hybrid Vehicles
United States Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
High-Voltage Hybrid Vehicle Market
Hybrid Vehicles
Hybrid Drivetrain Market
Hybrid Vehicles
Hybrid Powertrain Systems Market
Hybrid Vehicles
Plug-In Hybrid Electric Vehicles (PHEV) Market
Hybrid Vehicles
Hybrid Vehicle Market
Hybrid Vehicles
Hybrid Truck Market
Hybrid Vehicles
Global Hybrid Vehicle Transmission Market
Hybrid Vehicles
North America Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Asia-Pacific Mild-Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Train Market
Hybrid Vehicles
United Arab Emirates Hybrid and Electric Vehicles Market
Hybrid Vehicles
Mild Hybrid Vehicles Market
Hybrid Vehicles
Crossovers Market