
 Ice Tea Market | 2026-2036
Ice Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Tea Market Analytics
Organic certification under USDA NOP standards is reorganizing competitive access in the North American ice tea landscape. The Coca-Cola Company leverages its Gold Peak brand infrastructure to dominate refrigerated channel placement in grocery retail. PepsiCo sustains Lipton's shelf-stable dominance through direct-store-delivery networks that control convenience store coolers. Arizona Beverages competes on price-anchored multipack formats that occupy value-tier shelf space.
Ice tea comprises brewed Camellia sinensis leaves or extracts, typically sweetened, acidified, and pasteurized for ambient or chilled distribution, delivering caffeine-forward refreshment with flavor versatility. RTD bottles lead volume but face margin compression from PET resin volatility and freight costs. Powdered mix formats anchor the fastest-growing e-commerce segment as consumers stock pantry staples through subscription channels. Green tea flavor profiles command premium placement in natural-food retail, where clean-label positioning supports higher unit economics.
FDA nutrition labeling, USDA organic standards, and state-level sugar taxes in jurisdictions like California and Philadelphia reshape formulation priorities and regional product portfolios. The FDA's added-sugar disclosure rules force transparency that disadvantages legacy high-sugar recipes while advantaging reformulated or unsweetened line extensions. Stakeholders must monitor evolving municipal sweetened-beverage tax boundaries and organic supply chain integrity to anticipate margin shifts and channel access constraints.
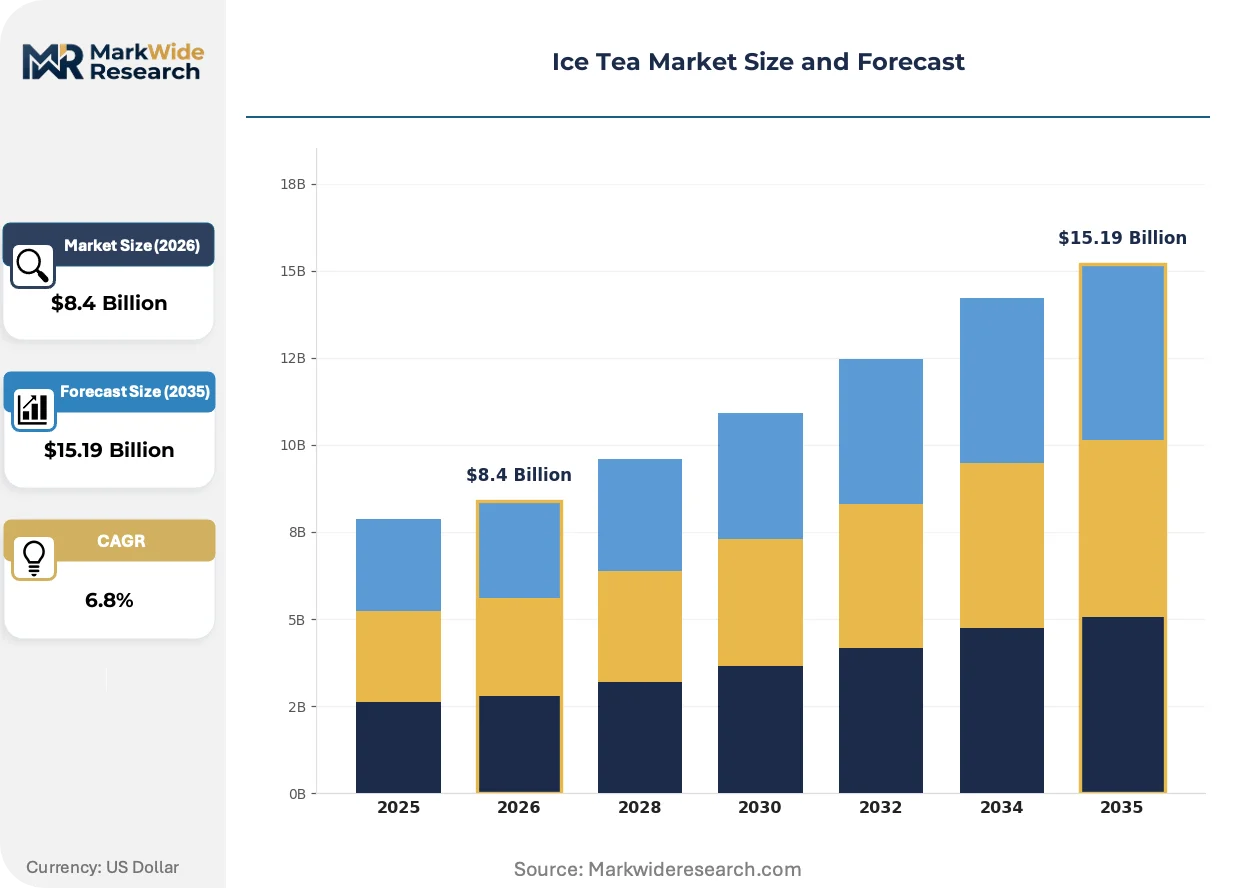
Market Dynamics
Reformulation pressure from the FDA's added-sugar disclosure rules is forcing legacy brands to strip sweetness while maintaining taste equity, compressing R&D cycles and restructuring supplier relationships across the RTD beverage value chain.
Growth Catalysts
- USDA Organic Certification:Clean-label positioning in natural-food retail commands premium shelf placement and higher unit economics, pulling conventional brands toward NOP-compliant supply chains.
- Gen Z Foodservice Demand:Health-conscious younger consumers in convenience and quick-service channels accelerate low-sugar and unsweetened SKU proliferation.
- Subscription E-Commerce:Powdered mix formats anchor the fastest-growing digital segment as pantry-stocking behavior shifts toward recurring delivery models.
Market Restraints
- PET Resin Volatility:RTD bottle margins compress unpredictably as petroleum-derived packaging costs swing with crude oil benchmarks.
- Refrigerated Channel Concentration:Dominant placement control by multinational beverage conglomerates limits cooler access for mid-tier and emerging brands.
- Sugar Tax Boundaries:Municipal sweetened-beverage levies in California and Philadelphia force fragmented state-by-state portfolio management.
Strategic Opportunities
- Green Tea Premiumization:Camellia sinensis varietals with provenance claims capture margin expansion in specialty retail and direct-to-consumer channels.
- Functional Ingredient Convergence:Adaptogen and nootropic infusions into base tea formulations target wellness-oriented consumption occasions beyond refreshment.
- Direct-Store-Delivery Bypass:Emerging brands leverage regional cold-chain logistics partnerships to circumvent incumbent cooler control in independent convenience stores.
Industry Challenges
- Organic Supply Chain Integrity:NOP-compliant leaf sourcing requires multi-year grower contracts and third-party audit infrastructure that strains working capital.
- Reformulation Timeline Compression:FDA compliance deadlines force accelerated sensory testing and consumer acceptance studies without extended market trial periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Tea Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RTD (Ready-to-Drink), Liquid Concentrate, Powdered Mix, Brewed Tea Flavor Profile: Peach, Lemon, Raspberry, Green Tea Packaging Type: Carton, Bottle, Can, Sachet Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Food Service |
| Companies Covered | The Coca-Cola Company, PepsiCo, Nestlé, Arizona Beverages USA, Unilever, Keurig Dr Pepper, BOS Brands, 4C Foods Corp, Mother Parkers Tea & Coffee, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Tea Market Evolving Landscape
Clean-label transparency requirements and channel fragmentation are simultaneously elevating ingredient provenance standards and multiplying route-to-market complexity for ice tea stakeholders.
Cold-brew extraction technology is decomposing the traditional hot-brew-and-chill production paradigm. Premium RTD startups and natural-food retailers are adopting ambient-temperature steeping protocols to reduce thermal degradation of catechins and volatile aromatics. This process shift is decomposing capital barriers between industrial-scale and craft-scale production, enabling regional brands to achieve flavor parity with multinational facilities.
The FDA's updated Nutrition Facts labeling mandate for added sugars disclosure is compressing formulation freedom for legacy sweetened recipes. Manufacturers must now declare precise sugar quantities that were previously buried in total carbohydrate lines, advantaging reformulated or zero-sugar line extensions. RTD brands with heritage high-sugar portfolios face the steepest retrofit costs and consumer acceptance risks.
Pantry-stocking through subscription commerce is displacing single-serve impulse purchases in household replenishment cycles. Powdered concentrate and multi-serve liquid formats are capturing recurring revenue streams through dedicated e-commerce storefronts and beverage-focused subscription boxes. This behavioral pivot is most visible among millennial households in coastal metropolitan markets where delivery density supports cold-chain economics.
Ice Tea Market Segmentation
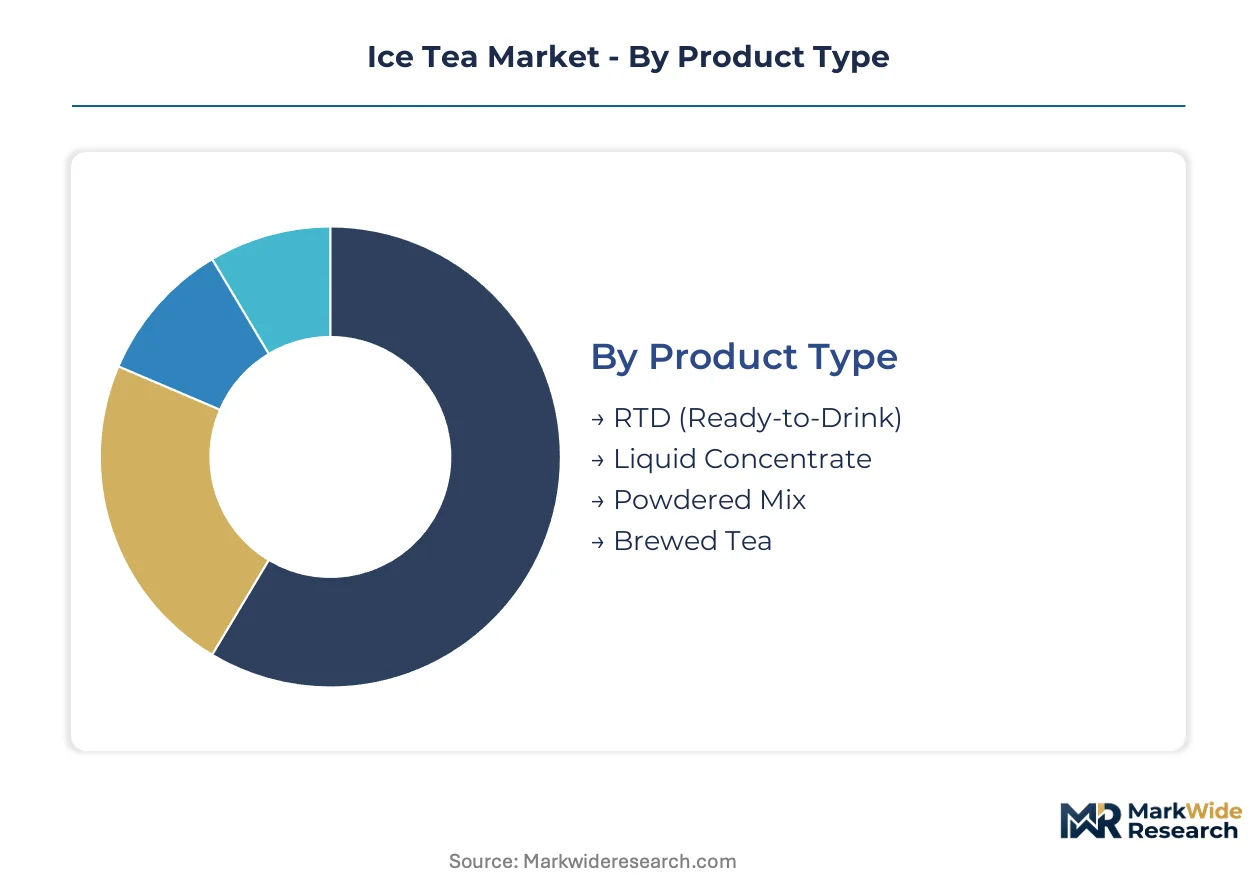
Ice tea segmentation reveals distinct channel economics and consumer occasions that reshape portfolio strategy. Format choices determine cold-chain requirements, shelf-life constraints, and margin structures across retail and foodservice touchpoints.
Product Type:
Channel placement diverges sharply between ambient-stable and refrigerated formats, with each product type commanding distinct cooler access and inventory turnover profiles.
- RTD (Ready-to-Drink):Single-serve bottles and cans dominate convenience store coolers and vending placements. PET resin volatility compresses margins unpredictably, though direct-store-delivery networks by beverage conglomerates secure premier refrigerated positioning in grocery and c-store channels.
- Liquid Concentrate:Multi-serve dilutable formats anchor warehouse club and mass merchant shelves with extended ambient stability. Household penetration concentrates in suburban markets where volume purchasing and pantry stocking behaviors reduce per-ounce cost sensitivity.
- Powdered Mix:Subscription e-commerce channels capture recurring pantry replenishment among millennial households. The format's shipping efficiency and shelf stability support direct-to-consumer margins without cold-chain infrastructure.
- Brewed Tea:Fresh-brewed dispensers and fountain systems control foodservice throughput in quick-service restaurants. Limited shelf life restricts distribution radius, favoring regional production partnerships over national scale.
By volume, RTD leads. By growth pace, powdered mix is expanding most quickly through digital subscription channels.
Flavor Profile:
Flavor selection signals price-tier positioning and clean-label compliance, with provenance claims enabling margin stratification across retail formats.
- Peach:The traditional sweetened profile anchors value-tier multipacks in mass retail. FDA added-sugar disclosure rules disadvantage this heritage formulation, forcing reformulation toward reduced-sugar variants that risk taste-equity erosion.
- Green Tea:Camellia sinensis varietals with origin claims command premium placement in natural-food retail. USDA organic certification supports unit economics 20-40% above conventional equivalents through clean-label positioning.
- Lemon:Classic citrus profiles balance accessibility and refreshment across foodservice fountain and retail bottle formats. The flavor's ubiquity limits differentiation, compressing margin capture in saturated shelf spaces.
- Raspberry:Berry infusions target younger demographics in convenience and specialty channels. Limited-run seasonal releases test flavor innovation without full portfolio commitment.
Green tea claims the steepest expansion trajectory as wellness positioning penetrates mainstream retail, while peach maintains volume leadership despite reformulation headwinds.
Packaging Type:
Material selection determines freight economics, shelf differentiation, and sustainability credentials that increasingly gate retail access.
- Bottle:PET and glass formats dominate refrigerated single-serve consumption. Resin cost volatility and lightweighting mandates drive rPET adoption pressures that strain supplier relationships.
- Can:Aluminum formats gain share in multipack and convenience channels through infinite recyclability claims. The material's thermal conductivity supports rapid chilling, advantaging impulse purchase occasions.
- Carton:Aseptic brick packs anchor ambient-stable liquid concentrate and value-tier RTD in international markets. Fiber-based substrates respond to plastic reduction commitments by major retailers.
- Sachet:Single-serve powder pouches reduce shipping weight and support portion-controlled consumption. The format enables trial-size distribution and emerging market penetration with minimal capital deployment.
Can formats are gaining share fastest on sustainability messaging, though bottles retain volume dominance in North American refrigerated channels.
Distribution Channel:
Route-to-market structure determines cooler control, data access, and promotional mechanics that separate incumbent defenders from challenger brands.
- Convenience Stores:Impulse-driven single-serve purchases concentrate in refrigerated grab-and-go sections. Direct-store-delivery networks by beverage conglomerates limit cooler access for mid-tier entrants, consolidating shelf space among legacy portfolios.
- Supermarkets:Multipack and variety-pack formats anchor household replenishment with promotional intensity. Category management relationships and slotting fees structure competitive access in perimeter coolers and center-store aisles.
- Online Retailers:Subscription and bulk formats bypass traditional cooler constraints through ambient shipping. Pantry-stocking behavior concentrates in coastal metropolitan markets where delivery density supports cold-chain economics for chilled variants.
- Food Service:Fountain dispensers and pre-portioned bottles control quick-service and institutional volume. Bidding dynamics and exclusive pour contracts lock in multi-year supply relationships that resist brand switching.
Online retailers are climbing the fastest as subscription mechanics reshape household replenishment, yet convenience stores maintain the highest velocity per square foot in beverage categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial and Gen Z households in metropolitan coastal markets drive disproportionate per-capita consumption of low-sugar and organic-certified ice tea variants. Convenience store penetration and foodservice fountain installations concentrate in suburban corridors with high commuter traffic density.
United States
Refrigerated RTD bottles dominate convenience store coolers through direct-store-delivery networks controlled by beverage conglomerates. The FDA's added-sugar disclosure rules force reformulation of heritage sweetened recipes across legacy portfolios. California and Philadelphia municipal sugar taxes fragment state-by-state product line management, with manufacturers maintaining separate SKUs for taxed and untaxed jurisdictions.
Germany
Glass-bottle formats retain premium positioning in discount grocery channels where deposit-return systems support circular packaging economics. EFSA guidance on added-sugar reduction targets influences manufacturer reformulation timelines ahead of EU-wide harmonization. The Rhine-Ruhr metropolitan corridor anchors cold-chain distribution infrastructure serving independent convenience retailers across Benelux border regions.
Japan
Unsweetened green tea variants command shelf-stable dominance in vending machines and railway station kiosks through ambient distribution networks. METI standards for food labeling transparency accelerate clean-label migration among domestic bottlers. The Kanto region surrounding Tokyo concentrates PET bottle manufacturing capacity that supplies both domestic consumption and export markets.
United Kingdom
Multipack canned formats gain share in grocery retail through price-promotional mechanics targeting household pantry stocking. The UK Soft Drinks Industry Levy pressures sugar content reduction in flavored tea formulations without triggering tax thresholds. Greater London's convenience density supports rapid trial of emerging brands through independent retailer partnerships bypassing national distributor networks.
Australia
Ready-to-drink bottles in 500ml single-serve formats dominate petrol station and convenience channel impulse purchase occasions. Health Star Rating labeling requirements influence consumer perception of sweetened versus unsweetened product positioning. Sydney and Melbourne metropolitan markets concentrate subscription e-commerce penetration where powdered mix formats capture recurring household replenishment.
Ice Tea Market Competitive Landscape
Player mix skews toward multinational beverage conglomerates with refrigerated channel control, mid-tier private-label suppliers, and emerging craft-scale entrants leveraging cold-brew differentiation. Market structure concentrates cooler access among three dominant archetypes: direct-store-delivery network operators, organic-certified specialty formulators, and value-tier multipack producers. Competitive moves center on portfolio diversification into functional ingredient categories and strategic partnerships with regional cold-chain logistics providers to bypass incumbent distribution bottlenecks.
Among multinational network operators, The Coca-Cola Company and PepsiCo exemplify archetypes of refrigerated channel dominance through established direct-store-delivery infrastructure. Arizona Beverages USA occupies a position within the value-tier multipack segment, anchoring price-competitive positioning in mass retail environments. These three entities collectively represent the competitive tension between scale-driven cooler control and emerging challenger access constraints.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo |
| Nestlé |
| Arizona Beverages USA |
| Unilever |
| Keurig Dr Pepper |
| BOS Brands |
| 4C Foods Corp |
| Mother Parkers Tea & Coffee |
| Others |
Value Network & Pricing Analysis
rPET substitution for virgin PET resin is redrawing procurement geography toward Southeast Asian recycling hubs while compressing unit economics for North American bottlers locked into long-term petroleum-indexed contracts.
Pricing Analysis
Cost-plus contracts with crude oil indexation dominate RTD bottle procurement, exposing margins to petrochemical volatility while organic leaf sourcing commands fixed-price multi-year grower agreements. Three-tier pricing structure across premium organic, standard conventional, and economy private-label levels stratifies shelf placement. Pricing pressure stems from municipal sugar tax fragmentation forcing SKU proliferation. Value-tier multipack buyers exhibit highest price sensitivity; natural-food retail channels show lowest.
Supply Chain Analysis
Inventory lead times for NOP-certified organic tea leaf stretch 18-24 months due to multi-year grower conversion requirements and third-party audit queues. Supply concentrates in India, Kenya, and Sri Lanka for Camellia sinensis leaf; China dominates green tea varietals. rPET flake, aluminum can sheet, and aseptic carton board constitute critical packaging inputs. Single-source vulnerability runs through concentrated organic certification bodies. Distribution runs through beverage conglomerate direct-store-delivery networks controlling refrigerated cooler access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as FDA added-sugar disclosure rules and Gen Z wellness preferences splinter demand across low-sugar, unsweetened, and functional subcategories that legacy portfolios cannot address uniformly.
For Market Incumbents: Consolidate cooler control through exclusive pour contracts with convenience store chains and quick-service restaurant networks. Acquire regional cold-brew specialists to neutralize craft-scale flavor parity threats. Invest in backward integration into organic leaf sourcing to secure NOP-compliant supply chains before certification bottlenecks intensify.
For New Entrants and Emerging Players: Differentiate on functional ingredient convergence—adaptogen and nootropic infusions targeting wellness occasions beyond refreshment. Penetrate subscription e-commerce powdered mix channels where incumbent DSD networks hold no advantage. Leverage regional cold-chain logistics partnerships to bypass cooler access constraints in independent convenience stores.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed organic-certified formulators lacking national distribution scale. Five-to-ten year viability hinges on portfolio migration toward clean-label and functional positioning. Watch for municipal sugar tax expansion beyond California and Philadelphia as inflection signal for reformulation capex cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerated Channel Expansion | Secures premier cooler placement against PepsiCo and Coca-Cola DSD networks in grocery retail. |
| Organic Certification Investment | Unlocks NOP-compliant supply chains and premium shelf access in natural-food retail channels. |
| Functional Ingredient Launch | Captures wellness-oriented consumption occasions through adaptogen and nootropic tea infusions. |
| Subscription E-Commerce Buildout | Establishes recurring revenue streams in powdered mix formats bypassing cold-chain infrastructure. |
| Cold-Brew Technology Adoption | Reduces capital barriers to flavor parity with multinational production facilities. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with beverage brand managers, category buyers at mass and natural-food retailers, cold-chain logistics operators, and organic certification auditors; and secondary validation against FDA labeling guidance documents, USDA NOP certification databases, Nielsen retail audit data, and customs trade records. Bottom-up volume modeling triangulated against top-down category expenditure estimates.
Across the projection horizon, forecasts segment by product type, flavor profile, packaging material, and distribution channel, with organic certification status and sugar content tier as cross-cutting dimensions. CAGRs derive from historical trajectory analysis adjusted for regulatory inflection points and channel shift elasticities. Inputs include PET resin price indices, organic acreage conversion rates, and municipal sugar tax jurisdiction mapping.
Forecasts assume regulatory continuity in FDA nutrition labeling and USDA organic standards; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Hydrogen Water Machine Market
Non-Alcoholic Beverages
Sugar Free Carbonated Drinks Market
Non-Alcoholic Beverages
Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
Zero Sugar Beverages Market
Non-Alcoholic Beverages
China Energy- Drinks Market
Non-Alcoholic Beverages
Europe Sports and Energy Drinks Market
Non-Alcoholic Beverages
Soft Drinks Market
Non-Alcoholic Beverages
Hypertonic Drinks Market
Non-Alcoholic Beverages
Europe Energy Drink Market
Non-Alcoholic Beverages
United States Energy Drink Market
Non-Alcoholic Beverages
Global Non Alcoholic Concentrated Syrup Market
Non-Alcoholic Beverages
Diet Soda Market
Non-Alcoholic Beverages
Europe Soy Beverages Market
Non-Alcoholic Beverages
Fermented Non-Dairy Beverages Market
Non-Alcoholic Beverages
United Arab Emirates Bottled Water Market
Non-Alcoholic Beverages
North America Bottled Water Processing Market