
 North America Bottled Water Processing Market | 2026-2036
North America Bottled Water Processing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Bottled Water Processing Market Insights
Premium spring and mineral certification tiers is bifurcating the North America bottled water processing landscape. PepsiCo, Inc. leverages its direct-store-delivery network to dominate convenience channel placement. Niagara Bottling, LLC anchors regional production through highly automated, high-speed filling lines across Texas and California. Danone S.A. differentiates via specialized mineral sourcing and European heritage positioning in the premium segment.
North America bottled water processing encompasses the treatment, filtration, purification, and packaging of potable water for commercial distribution, typically involving multi-barrier systems that achieve total dissolved solids below 500 ppm and microbiological compliance through reverse osmosis or ozonation sequences. Carbon filtration and ultraviolet treatment segments command substantial installed base, though reverse osmosis capacity is expanding fastest among new plant builds. Plastic bottles retain volume leadership in packaging type, while enhanced water formulations are capturing margin pools through functional additive integration.
FDA bottled water standards, EPA Safe Drinking Water Act provisions, and state-level deposit legislation collectively shape product formulation, source disclosure, and recyclability mandates across the United States and Canada. The Canadian Food Inspection Agency and Health Canada enforce parallel labeling and quality protocols that govern cross-border trade flows. Stakeholders must monitor evolving extended producer responsibility frameworks and source sustainability disclosure requirements that will reshape capital allocation decisions.
Market Dynamics
Reverse osmosis capacity expansion across southwestern US plant builds is compressing legacy carbon filtration economics while tightening microbiological compliance thresholds. This technology migration cascades through equipment procurement, operator training requirements, and source water portfolio restructuring.
Growth Catalysts
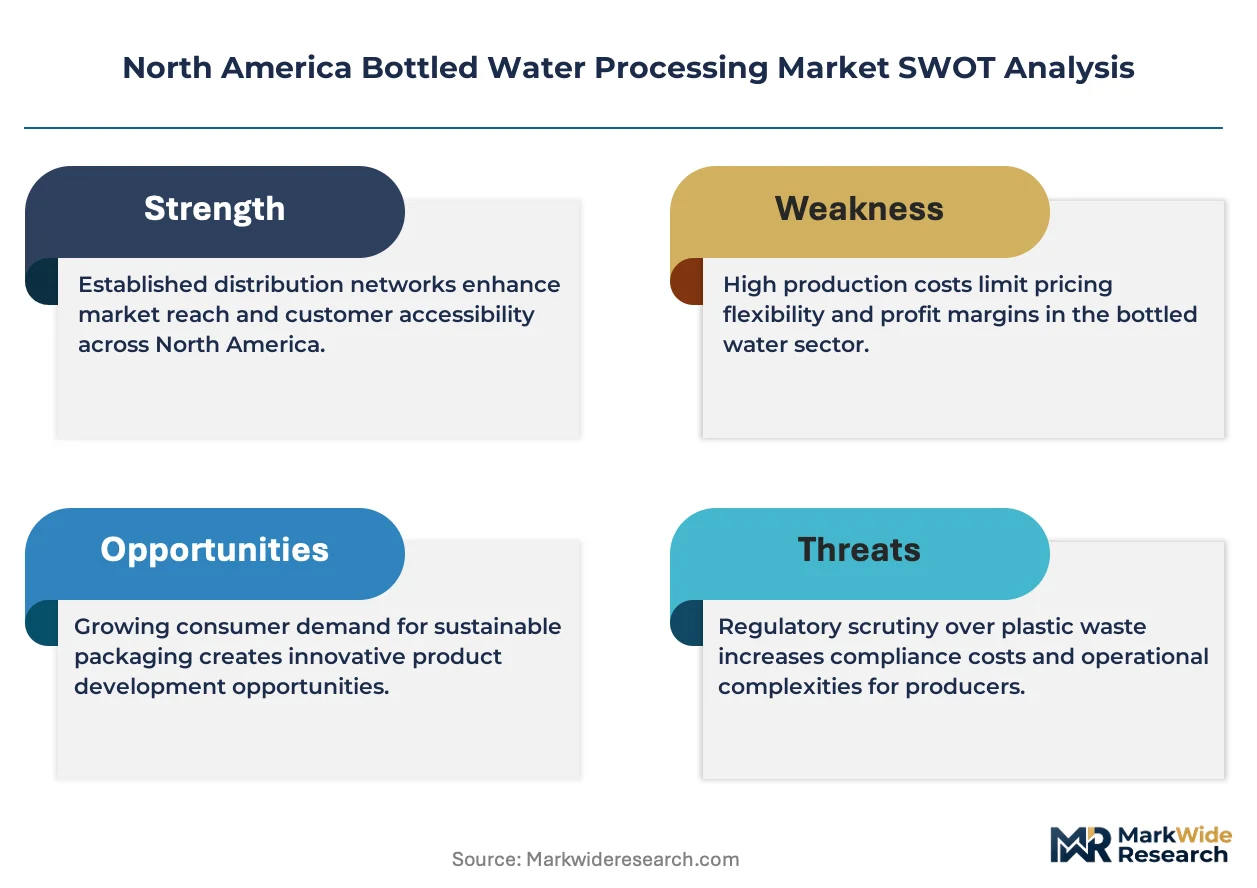
- EPA Safe Drinking Water Act amendments:Tightened contaminant thresholds for arsenic and disinfection byproducts are forcing municipal system upgrades that accelerate bottled water substitution in Arizona and New Mexico households.
- Sparkling water carbonation systems:On-premise restaurant and hotel installations are expanding at double-digit rates as hospitality operators build differentiated beverage programs without distributor dependency.
- Texas-California production corridor:Automated high-speed filling line concentration across these states creates logistics efficiency that compresses delivered cost to southwestern population centers.
Market Restraints
- PET resin price volatility:Crude oil-linked feedstock costs swing packaging economics unpredictably, squeezing margin visibility for regional bottlers without long-term polymer contracts.
- Aquifer access concentration:Sustainable groundwater withdrawal permits cluster with established producers holding senior water rights in California's Central Valley, blocking new entrants.
- Single-stream recycling contamination:MRF processing limitations degrade rPET feedstock quality, capping recycled content mandates below brand sustainability targets.
Strategic Opportunities
- Canadian extended producer responsibility frameworks:Ontario and British Columbia deposit-return expansion creates infrastructure investment incentives that favor early compliance positioning.
- Functional additive integration:Electrolyte and vitamin fortification lines retrofit existing still water plants, capturing margin pools in convenience store and fitness channel placements.
- Direct-to-consumer subscription platforms:Home and office delivery apps bypass traditional wholesale distribution, building recurring revenue with customer data ownership.
Industry Challenges
- Certified plant operator scarcity:FDA-mandated preventive controls qualified individual requirements outpace community college training program output across rural production locations.
- Ozonation system integration complexity:Retrofitting UV-dependent legacy lines with ozone contact chambers demands extended shutdown windows that disrupt seasonal demand fulfillment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Bottled Water Processing Market |
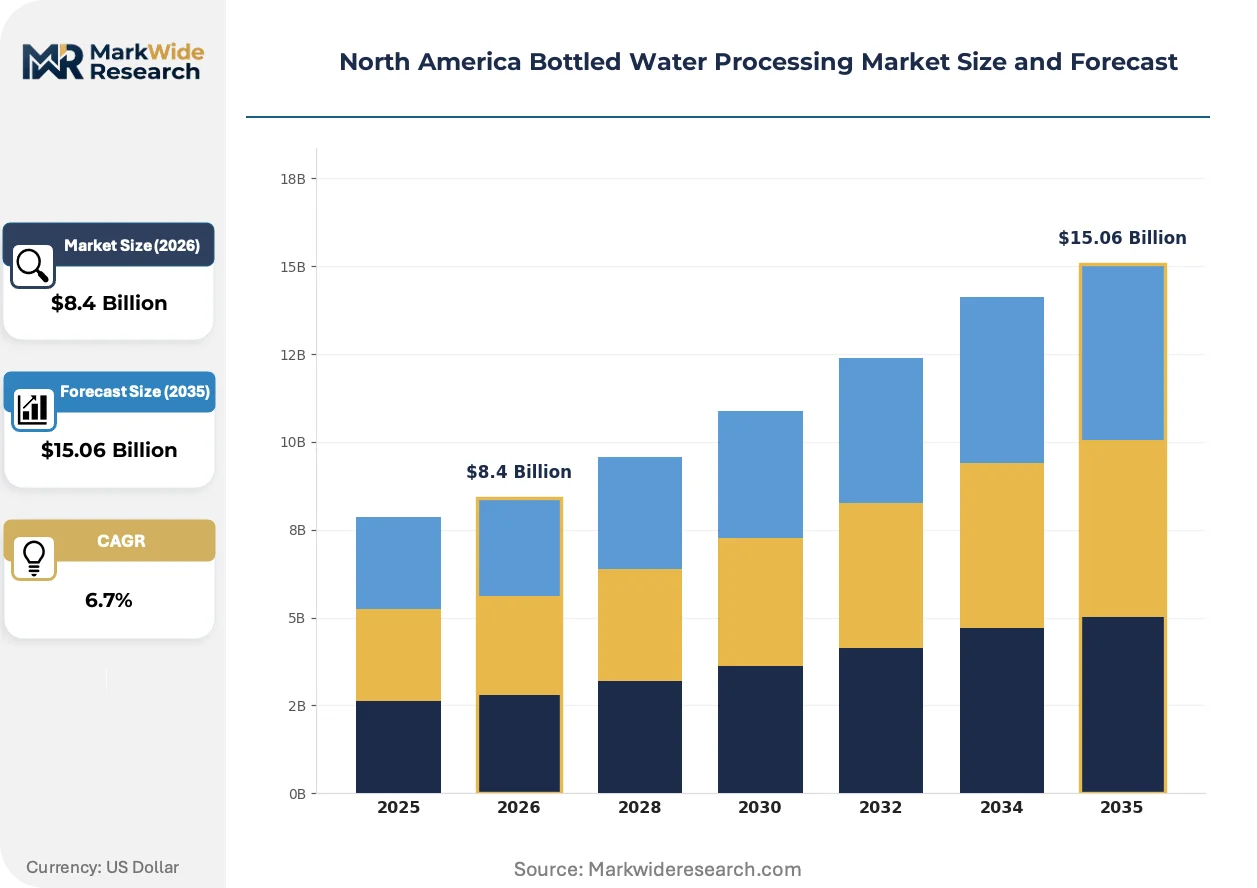
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spring Water, Mineral Water, Purified Water, Enhanced Water Technology: Reverse Osmosis, Ultraviolet Treatment, Carbon Filtration, Ozonation Packaging Type: Plastic Bottles, Glass Bottles, Pouches, Jugs End User: Retail, Hospitality, Food Service, Household |
| Companies Covered | PepsiCo, Inc., The Coca-Cola Company, BlueTriton Brands, Inc., Danone S.A., Niagara Bottling, LLC, Nestlé S.A., Krones AG, GEA Group AG, Veolia Environnement S.A., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Bottled Water Processing Market Trends and Innovations
Multi-barrier treatment architectures are fragmenting equipment vendor relationships as processors mix proprietary membrane technologies with commodity filtration stages. This modularization pressures integrated system suppliers while opening niche component markets.
Membrane bioreactor pretreatment is decomposing conventional coagulation-flocculation sequences in plants drawing from surface water sources. Southwestern processors facing seasonal algae blooms are adopting MBR-RO hybrid trains faster than groundwater-dependent competitors. The technology shift is compressing chemical handling infrastructure requirements while expanding automation vendor footprints in plant control rooms.
FDA bottled water quality standards updates are tightening finished product testing frequencies and documentation retention periods. Small and mid-size processors face disproportionate laboratory capital burdens as compliance costs scale nonlinearly with volume. The regulation is accelerating third-party testing service adoption among regional bottlers lacking in-house microbiology capacity.
Hospitality procurement is consolidating around specification-grade mineral content profiles rather than brand loyalty. Casino and resort beverage directors now contract directly with co-packers for private-label sparkling programs, disintermediating national brand distributors. This pattern concentrates most visibly in Las Vegas and Orlando hospitality corridors where volume justifies dedicated production lines.
North America Bottled Water Processing Market Segmentation
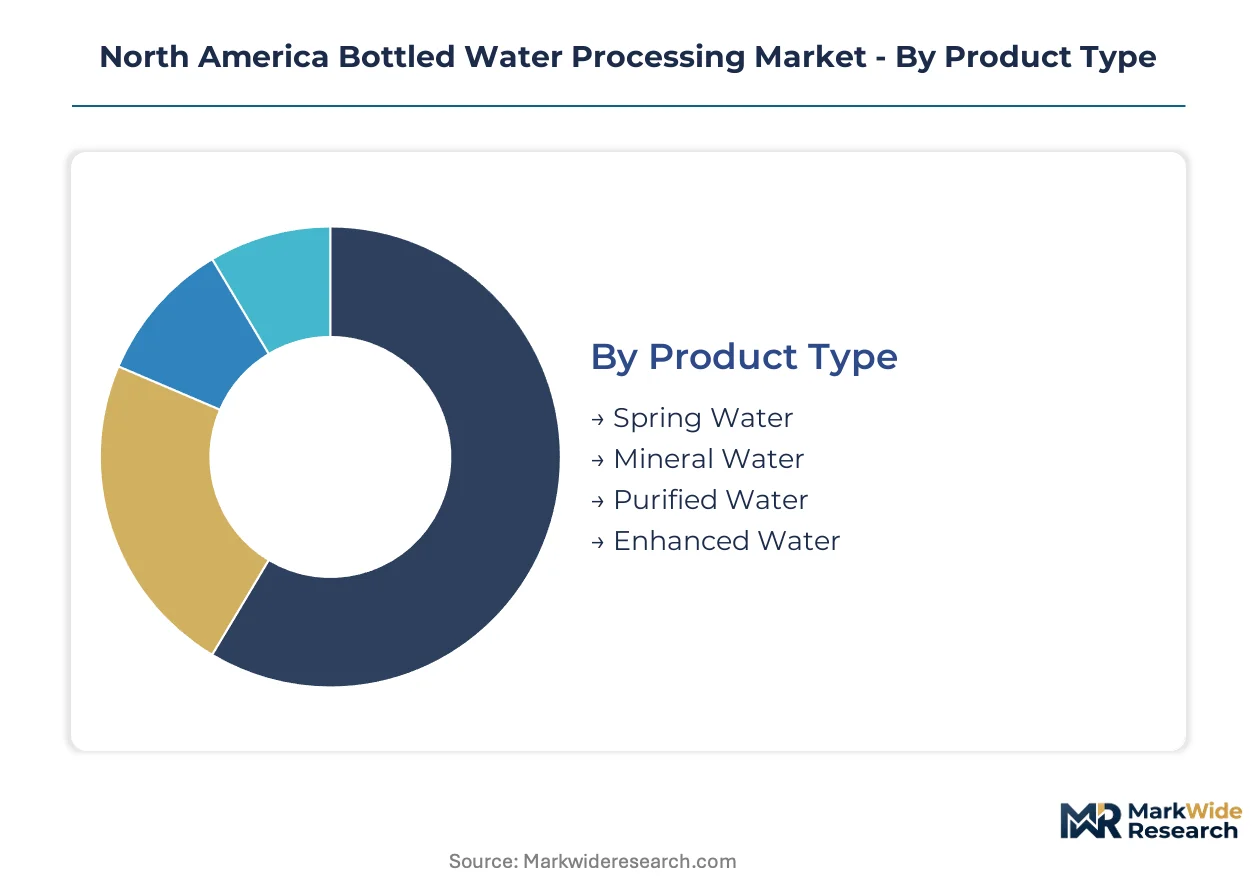
Segmentation in the North America bottled water processing market reveals how FDA certification tiers, equipment technology choices, and channel-specific packaging requirements create distinct competitive battlegrounds. Each dimension carries unique regulatory compliance burdens and margin structures that shape processor capital allocation decisions.
Product Type:
Regulatory differentiation across source certification and mineral content disclosure creates tiered compliance obligations that segment processor capabilities and brand positioning strategies.
- Purified Water:Multi-barrier treatment systems achieve total dissolved solids below 500 ppm through reverse osmosis or distillation sequences. Arizona and New Mexico households facing municipal arsenic concerns are driving per-capita consumption in this segment.
- Spring Water:FDA-mandated source protection zones and annual geological surveys define operational boundaries. Bottlers holding senior water rights in California's Central Valley command logistics advantages to southwestern population centers.
- Mineral Water:Naturally occurring mineral content must meet strict stability thresholds across production batches. Premium hospitality contracts in Las Vegas and Orlando specify mineral profiles that disqualify most regional suppliers.
- Enhanced Water:Electrolyte and vitamin fortification triggers additional labeling scrutiny under FDA food additive regulations. Fitness channel placements and convenience store sets are absorbing volume from traditional still water SKUs.
Purified water handles the majority of throughput; enhanced water is the fastest mover on share.
Technology:
Capital intensity and operator certification requirements stratify processor capabilities, with newer membrane technologies demanding different skill bases than legacy chemical treatment systems.
- Reverse Osmosis:Spiral-wound membrane configurations achieve 99% contaminant rejection across dissolved solids and microbiological parameters. Texas and California plant builds are expanding RO capacity fastest among southwestern installations.
- Carbon Filtration:Granular activated carbon beds target chlorine, volatile organic compounds, and taste-odor compounds. Established processors with fully depreciated carbon infrastructure face RO retrofit pressure from tightening EPA disinfection byproduct rules.
- Ultraviolet Treatment:Medium-pressure UV systems deliver 4-log virus inactivation without chemical residuals. Small and mid-size bottlers lacking in-house microbiology capacity are outsourcing validation testing to third-party laboratories.
- Ozonation:Dissolved ozone contact chambers provide oxidation and residual disinfection in a single stage. Retrofitting UV-dependent legacy lines demands extended shutdown windows that disrupt seasonal demand fulfillment.
Carbon filtration handles the majority of throughput; reverse osmosis is expanding most quickly on installed base.
Packaging Type:
Recyclability mandates and deposit-return legislation are reshaping material economics, with rPET quality constraints limiting recycled content achievement.
- Plastic Bottles:PET resin dominates volume through lightweight logistics and blow-molding line efficiency. Crude oil-linked feedstock volatility squeezes margin visibility for regional bottlers lacking long-term polymer contracts.
- Jugs:Multi-gallon polycarbonate and PET containers serve home and office delivery channels. Direct-to-consumer subscription platforms are building recurring revenue with customer data ownership in this format.
- Glass Bottles:Premium mineral water positioning leverages perceived purity and hospitality aesthetic requirements. Weight-based freight penalties restrict distribution radius to regional production corridors.
- Pouches:Flexible film formats target single-serve convenience and reduced material intensity. MRF processing limitations degrade feedstock recovery rates for this packaging stream.
Plastic bottles handle the majority of throughput; jugs are gaining share fastest through delivery channel expansion.
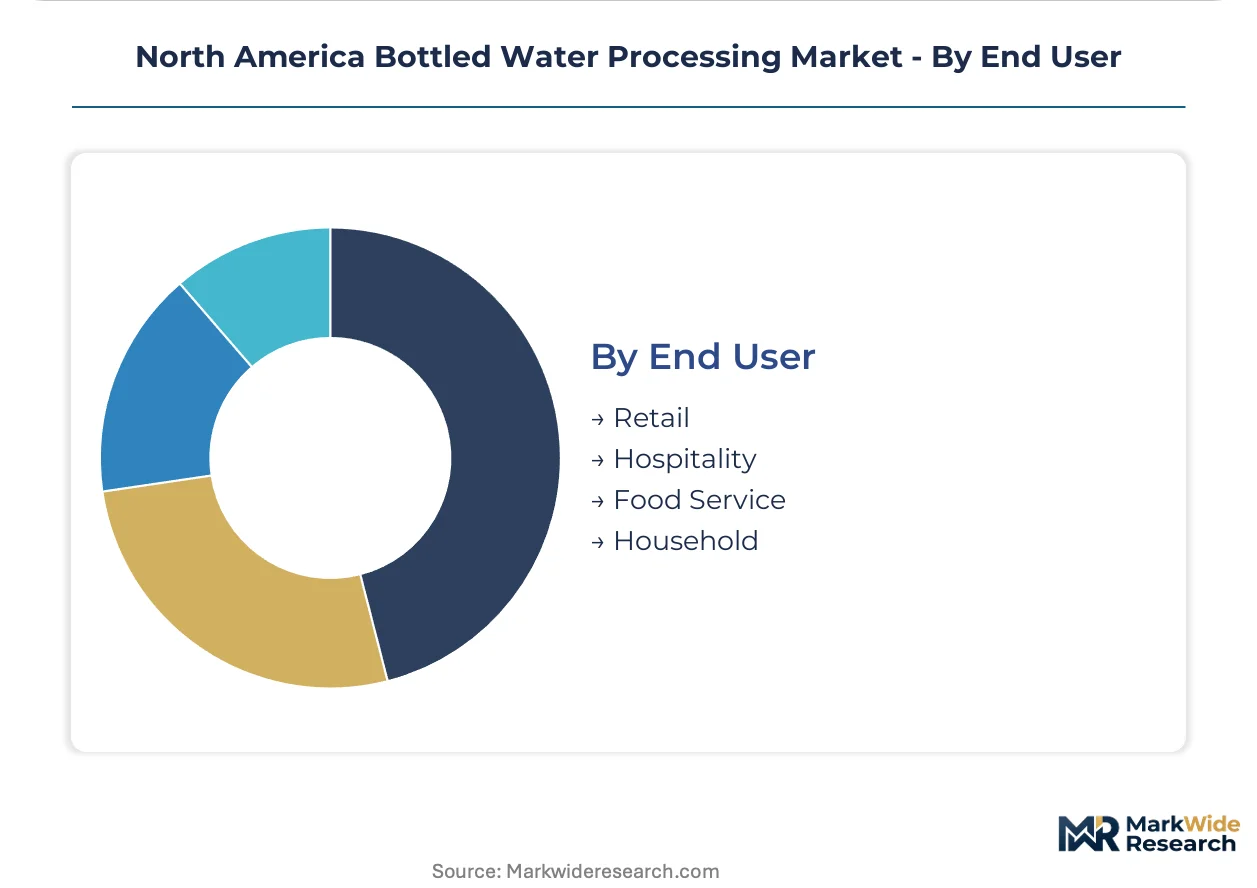
End User:
Procurement consolidation patterns and specification-grade contracting are fragmenting traditional brand-distributor relationships across channel types.
- Retail:Mass merchant and convenience store sets demand high-velocity SKU turnover with promotional funding commitments. PepsiCo's direct-store-delivery network dominates shelf placement economics in this channel.
- Hospitality:Casino and resort beverage directors contract directly with co-packers for private-label sparkling programs. Las Vegas and Orlando corridors concentrate specification-grade mineral content procurement.
- Household:Home pantry stocking and emergency preparedness purchases respond to municipal water quality advisories. Arizona and New Mexico substitution patterns accelerate during EPA Safe Drinking Water Act enforcement actions.
- Food Service:Restaurant and institutional accounts prioritize dispenser compatibility and ice machine integration. On-premise carbonation system installations are expanding at double-digit rates as operators build differentiated beverage programs.
Retail handles the majority of throughput; hospitality is climbing the fastest on specification-grade contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border water trade flows between the United States and Canada remain minimal, with domestic production capacity satisfying nearly all regional demand. Mexico imports specialized filtration equipment from U.S. and German suppliers while exporting limited volumes of premium mineral water to southwestern U.S. markets.
United States
Arid climate conditions across Arizona, New Mexico, and Texas drive per-capita consumption rates substantially above the national average. EPA Safe Drinking Water Act amendments tightening arsenic and disinfection byproduct thresholds accelerate household substitution away from municipal systems. The Texas-California production corridor concentrates automated high-speed filling capacity that compresses delivered costs to southwestern population centers.
Canada
Ontario and British Columbia deposit-return expansion creates infrastructure investment incentives favoring early compliance positioning. Health Canada and the Canadian Food Inspection Agency enforce parallel labeling and quality protocols governing cross-border trade flows with U.S. bottlers. The Great Lakes basin provides abundant source water access for processors serving both domestic and limited U.S. export markets.
Mexico
Municipal water quality inconsistency in major metropolitan areas sustains robust bottled water demand among middle-income households. Mexican federal standards under COFEPRIS align partially with FDA requirements, easing equipment qualification for U.S. suppliers. Baja California and northern border states concentrate maquiladora-style co-packing operations serving U.S. hospitality and retail channels.
North America Bottled Water Processing Market Competitive Landscape
Concentration sits with diversified beverage conglomerates and specialized regional bottlers operating distinct competitive models. The market exhibits tiered structure: multinational CPG players dominate mass retail shelf space through direct-store-delivery networks, while mid-scale regional operators compete on logistics efficiency and private-label flexibility. Three archetypes define competitive positioning: integrated beverage giants with captive distribution, high-volume regional bottlers with automated production corridors, and premium specialists leveraging mineral sourcing differentiation. Capacity expansion and private-label contract acquisition represent the dominant competitive moves reshaping market share.
Within the integrated beverage tier, PepsiCo, Inc. and The Coca-Cola Company exemplify scale-driven distribution dominance through captive retail networks. Niagara Bottling, LLC anchors the high-volume regional archetype with automated production concentration across the Texas-California corridor. Danone S.A. occupies the premium specialist position, leveraging European heritage positioning and specialized mineral sourcing protocols in the hospitality channel.
| Leading Market Players |
|---|
| PepsiCo, Inc. |
| The Coca-Cola Company |
| BlueTriton Brands, Inc. |
| Danone S.A. |
| Niagara Bottling, LLC |
| Nestlé S.A. |
| Krones AG |
| GEA Group AG |
| Veolia Environnement S.A. |
| Others |
Pricing and Supply Chain Analysis
FDA bottled water certification tiers gate both supply qualification and price differentiation simultaneously, with Purified, Spring, Mineral, and Enhanced designations creating distinct cost-to-serve profiles that processors must navigate against buyer procurement power.
Pricing Analysis
Hospitality procurement directors anchor pricing negotiations through specification-grade mineral content contracting, with Las Vegas and Orlando casino beverage programs commanding volume discounts unavailable to retail channel buyers. Three-tier pricing structure across premium mineral, standard spring, and economy purified levels separates certification-grade positioning, while PET resin volatility and rPET quality constraints compress margin visibility for regional bottlers lacking long-term polymer contracts. Price differentiation hinges on source water rights seniority and automated filling line throughput scale. Convenience store buyers exhibit highest price sensitivity; premium hospitality contracts show lowest elasticity due to brand exclusion clauses.
Supply Chain Analysis
Strategic stockpiling of PET resin and membrane filtration components dominates inventory strategy, with processors maintaining 60-90 day raw material buffers against crude oil-linked feedstock volatility. Supply concentrates in the Texas-California production corridor for finished goods, while Germany, Japan, and the United States anchor equipment manufacturing for reverse osmosis and ozonation systems. Raw material dependencies include PET resin, spiral-wound membrane elements, and ozone generation cells. Single-source vulnerability in California Central Valley groundwater rights creates permit access risk for new entrants. Distribution runs through direct-store-delivery networks for retail, with home and office delivery platforms bypassing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America bottled water processing sits in early-cycle expansion, with EPA Safe Drinking Water Act amendments accelerating household substitution away from municipal systems across Arizona and New Mexico.
For Market Incumbents: Shield market position through backward integration into source water rights acquisition in California's Central Valley, locking out new entrants from sustainable groundwater permits. Accelerate ozonation system retrofitting ahead of FDA microbiological compliance threshold tightening, converting extended shutdown windows into competitive moats against regional bottlers with legacy UV-dependent infrastructure. Channel control through direct-store-delivery network densification remains critical against PepsiCo's convenience placement dominance. For New Entrants and Emerging Players: Lead with functional additive integration capabilities targeting fitness channel placements and convenience store enhanced water sets, where electrolyte and vitamin fortification lines retrofit existing still water plants at lower capital intensity than greenfield builds. Canadian extended producer responsibility frameworks in Ontario and British Columbia offer infrastructure investment incentives favoring early compliance positioning. Direct-to-consumer subscription platforms provide customer data ownership and recurring revenue without distributor dependency. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified beverage conglomerates seeking to monetize non-core water assets, particularly regional spring water brands with senior water rights but underutilized production capacity. Long-term viability centers on processors with multi-barrier treatment architecture flexibility and hospitality channel specification-grade contracting relationships. The signal to watch is MRF processing technology advancement enabling rPET feedstock quality improvement, which would reset recycled content mandate economics and sustainability positioning thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Source Water Rights Acquisition | California Central Valley permits anchor logistics advantages to southwestern population centers. |
| Ozonation System Retrofit | FDA microbiological compliance upgrades compress seasonal demand fulfillment for competitors. |
| Functional Additive Integration | Electrolyte fortification lines capture margin pools in fitness and convenience channels. |
| Direct-to-Consumer Platform Launch | Home and office delivery apps build recurring revenue with customer data ownership. |
| Canadian EPR Compliance Positioning | Ontario and British Columbia deposit-return expansion creates infrastructure investment incentives. |
Research Methodology
Cross-validation between primary interviews with plant operations managers, FDA compliance officers, hospitality procurement directors, and membrane equipment suppliers anchors the qualitative findings against secondary validation from EPA enforcement records, FDA bottled water quality standard updates, state-level water rights registries, and customs data on filtration equipment imports. Bottom-up triangulation against top-down macroeconomic indicators ensures segment-level outputs reconcile with aggregate market dynamics.
Sensitivity analysis across the projection horizon tests forecast robustness against PET resin price volatility scenarios and EPA Safe Drinking Water Act amendment timing assumptions. The analytical framework models product type, technology choice, packaging format, and end-user channel dimensions alongside source water geology classification. CAGRs derive from installed base expansion rates and per-capita consumption elasticity to municipal water quality advisories. Forecast inputs include southwestern US precipitation patterns and hospitality construction pipeline data.
The analysis sits within stated boundaries; outcomes outside sustained EPA enforcement intensity or stable crude oil-linked feedstock pricing would require recalibration. Forecasts reflect documented assumptions regarding membrane technology adoption curves and deposit-return legislative timelines. Revision becomes warranted when rPET feedstock quality improvement crosses commercial viability thresholds or when extended producer responsibility frameworks expand beyond Ontario and British Columbia.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Carbonated Ready-To-Drink Tea Market
Non-Alcoholic Beverages
Europe Sports Drink Market
Non-Alcoholic Beverages
Vietnam Energy Drinks Market
Non-Alcoholic Beverages
Brazil Energy Drinks Market
Non-Alcoholic Beverages
Fermented Non-Dairy Beverages Market
Non-Alcoholic Beverages
Naturally Cultured Beverages Market
Non-Alcoholic Beverages
Europe Soy Beverages Market
Non-Alcoholic Beverages
Fermented Non Dairy Non Alcoholic Beverages Market
Non-Alcoholic Beverages
Soy Beverage Market
Non-Alcoholic Beverages
Non-Alcoholic Spirits Market
Non-Alcoholic Beverages
Diet Soda Market
Non-Alcoholic Beverages
Global Sugar Free Beverages Market
Non-Alcoholic Beverages
Low- and No-Calorie Soda Market
Non-Alcoholic Beverages
Lemonade Market
Non-Alcoholic Beverages
GCC Non-Alcoholic Beer Market
Non-Alcoholic Beverages
Soft Drinks Market