
 Fermented Non-Dairy Beverages Market | 2026-2036
Fermented Non-Dairy Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Fermented Non-Dairy Beverages Market Foresight
Specialized fermentation microbiologists is bifurcating the talent pipeline between artisan craft producers and industrial-scale operators. Danone S.A leverages its dairy-alternative infrastructure to anchor kefir-style oat and coconut platforms. PepsiCo Inc. competes through refrigerated distribution scale, while GT's Living Foods LLC dominates raw, unpasteurized kombucha with dedicated cold-chain control.
Fermented non-dairy beverages are microbially cultured drinks produced from plant substrates—oat, coconut, almond, or tea bases—under controlled temperature and pH conditions that yield organic acids, carbonation, and viable probiotic counts typically exceeding 10^6 CFU per serving. Their primary commercial purpose is delivering functional gut-health benefits without lactose, casein, or animal-derived inputs. Kombucha leads product type volume through established consumer recognition, though water kefir represents the fastest-growing segment as lower-sugar formulations attract diabetic and weight-management end users. Distribution channel dynamics reveal margin pools shifting toward online retailers, where subscription models capture repeat purchase velocity unavailable in conventional supermarkets.
FDA GRAS self-affirmation and USDA organic certification govern probiotic stability claims and ingredient sourcing in the United States, while EFSA novel food assessments delay European launches for unconventional starter cultures. The EU Green Deal's Farm to Fork strategy pressures manufacturers to document fermentation carbon intensity and packaging recyclability. Stakeholders must monitor whether evolving live-culture labeling requirements force reformulation investments or create compliance barriers for smaller craft entrants.
Market Dynamics
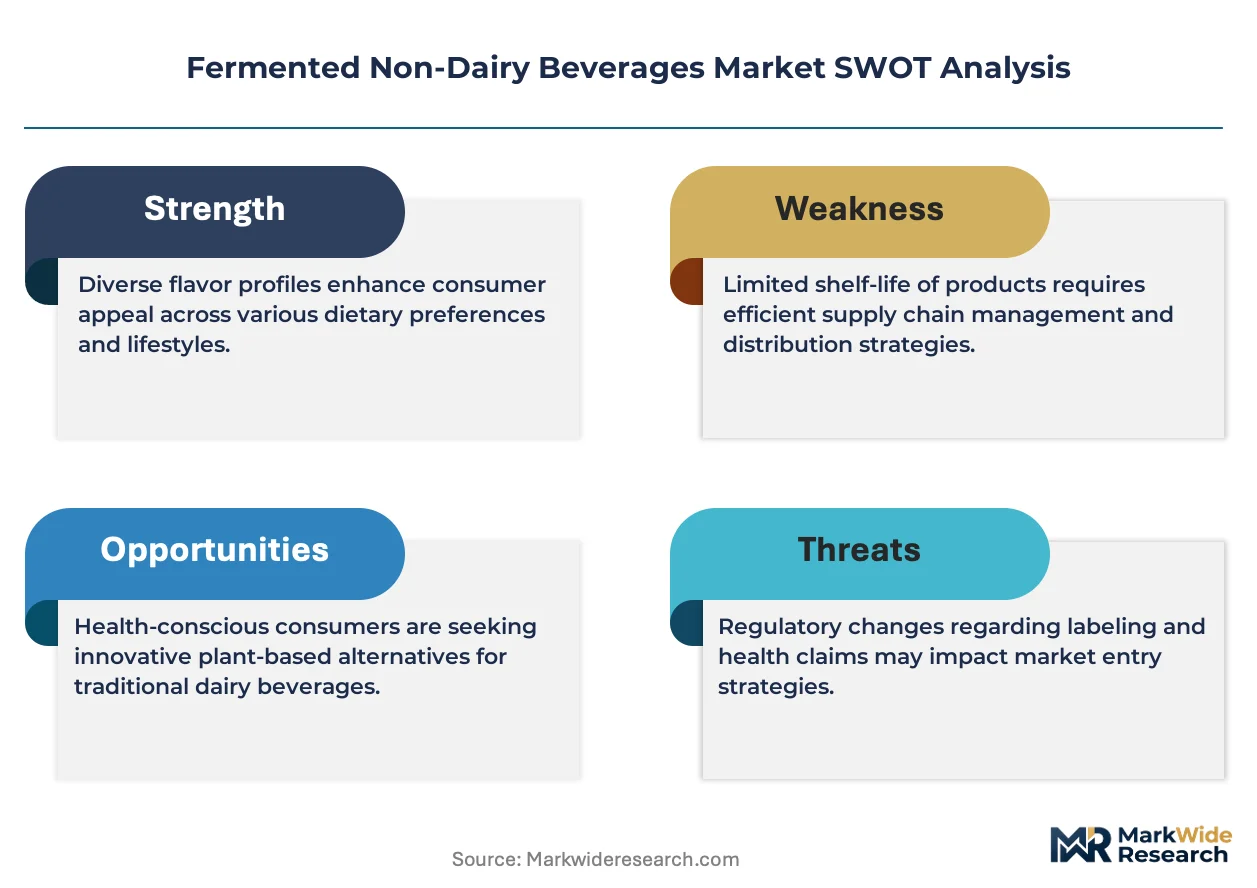
Live-culture stability requirements are forcing manufacturers to choose between shelf-stable pasteurization and refrigerated raw formats, splitting capital deployment strategies between extended distribution reach and premium positioning.
Growth Catalysts
- EFSA novel food pathways:Streamlined assessments for conventional starter cultures accelerate European product launches while maintaining safety standards.
- California functional beverage cluster:Concentrated R&D infrastructure and venture capital access enable rapid formulation iteration for oat-based kefir alternatives.
- Tea base diversification:Yerba mate and rooibos substrates attract caffeine-sensitive consumers seeking alternative polyphenol profiles.
Market Restraints
- Organic acid volatility:Fluctuating acetic acid and gluconic acid feedstock costs compress margins for industrial-scale fermentation operations.
- Cold-chain infrastructure gaps:Limited refrigerated last-mile capacity in secondary US cities restricts raw kombucha distribution economics.
- Scoby supply concentration:Mother culture sourcing clusters among three domestic suppliers, creating single-point vulnerability for craft producers.
Strategic Opportunities
- Subscription direct-to-consumer models:Recurring revenue platforms bypass slotting fee barriers imposed by conventional supermarket buyers.
- Water kefir diabetic positioning:Lower glycemic index formulations target glucose-management end users underserved by sugary kombucha variants.
- EU Green Deal carbon accounting:Documented fermentation emissions reductions qualify manufacturers for preferential procurement by sustainability-mandated retailers.
Industry Challenges
- Microbiology talent scarcity:Specialized fermentation scientists command premium compensation, squeezing craft producer hiring pipelines.
- Live-culture labeling compliance:Evolving FDA GRAS notification requirements force reformulation investments to maintain viable probiotic count claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fermented Non-Dairy Beverages Market |
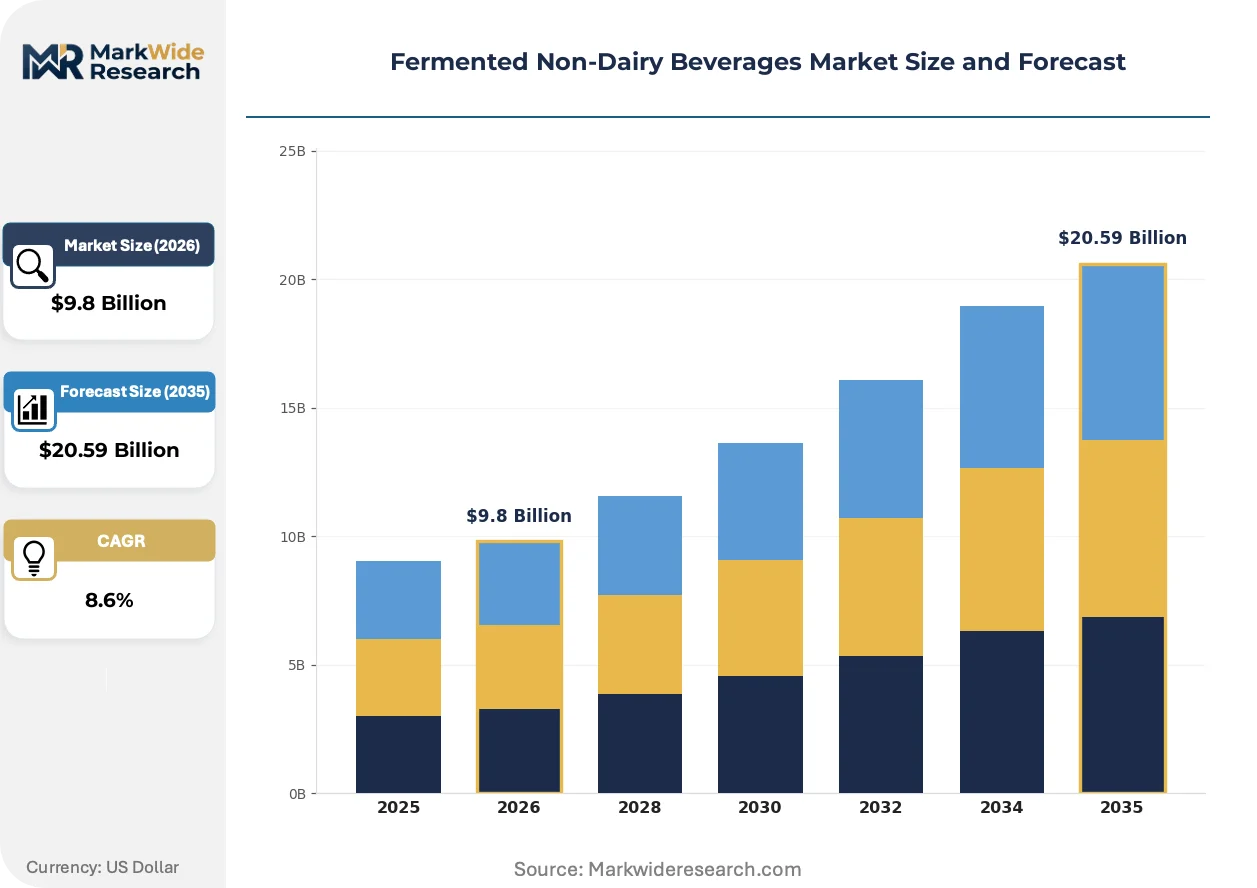
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.59 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kefir, Kombucha, Water Kefir, Tepache End User: Health-Conscious Consumers, Vegan Consumers, Fitness Enthusiasts, Organic Shoppers Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Specialty Stores Flavor Profile: Ginger, Berry, Citrus, Tropical |
| Companies Covered | DuPont de Nemours Inc, Chr. Hansen A/S, PepsiCo Inc., KeVita Inc., GT's Living Foods LLC, Danone S.A, Yakult Honsha Co. Ltd., Health-Ade LLC, General Mills Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fermented Non-Dairy Beverages Market Shifts & Advancements
Controlled-atmosphere packaging and precision fermentation are compressing the traditional trade-off between shelf stability and probiotic viability, enabling new distribution economics.
Synbiotic formulations combining specific probiotic strains with targeted prebiotic fibers are fragmenting the historical kombucha-versus-kefir category boundary. Functional beverage buyers in Germany and the Netherlands adopt these hybrid products faster than conventional segments. The technology is fragmenting brand loyalty as consumers experiment across previously distinct product formats.
EFSA health claim scrutiny under the Nutrition and Health Claims Regulation is tightening substantiation requirements for gut microbiome benefits. Manufacturers must now submit human intervention studies for novel strain-specific claims. Kombucha producers targeting German specialty retailers face the steepest compliance costs and longest approval timelines.
Direct subscription purchasing is displacing conventional supermarket replenishment among high-engagement consumers. Online platforms capture repeat velocity through personalized flavor curation and flexible delivery cadences. This pattern concentrates in California's urban corridors where digital-native beverage brands originated.
Fermented Non-Dairy Beverages Market Segmentation
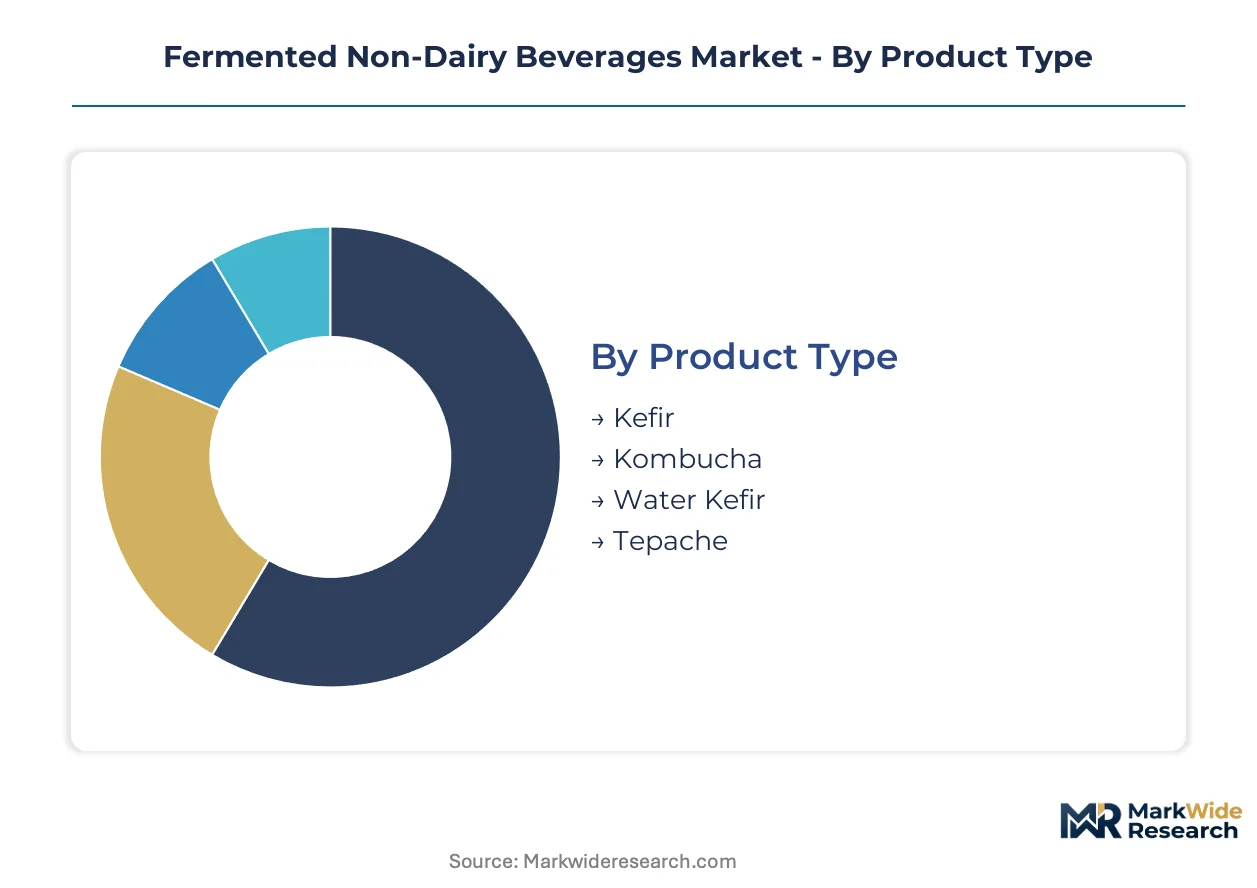
Segmentation in fermented non-dairy beverages reveals distinct purchasing behaviors across probiotic formats, ethical consumption patterns, and channel preferences. Manufacturers must align formulation investments with specific end-user microbiome expectations and cold-chain capabilities.
Product Type:
Kombucha dominates export volumes through established international distribution, while water kefir and tepache concentrate in domestic craft markets with limited shelf-stable processing.
- Kefir:Oat and coconut substrates fermented with lactobacillus and bifidobacterium strains yield creamy textures mimicking traditional dairy. California's functional beverage cluster drives oat-based kefir R&D, constrained by EFSA novel food assessments for unconventional starter cultures.
- Kombucha:Tea-based fermentation with SCOBY cultures produces acetic acid, carbonation, and polyphenol content. German specialty retailers expand shelf space despite EFSA health claim scrutiny, while GT's Living Foods LLC anchors raw unpasteurized segments through dedicated cold-chain control.
- Water Kefir:Tibicos grains ferment sugar water into lower-acidity, caffeine-free alternatives. Lower glycemic index formulations attract diabetic end users in domestic weight-management segments.
- Tepache:Pineapple rind fermentation with piloncillo sugar yields traditional Mexican profiles. Artisan producers in California and Texas serve regional Hispanic consumer bases with limited national distribution.
Kombucha holds the largest share; momentum sits with water kefir as lower-sugar positioning captures glucose-management demand.
End User:
Cost tiers separate premium probiotic seekers from value-conscious organic buyers, with vegan consumers representing the highest per-capita expenditure segment.
- Health-Conscious Consumers:Gut microbiome optimization drives repeat purchase behavior and subscription adoption. These buyers prioritize viable CFU counts over flavor variety, concentrating in urban California corridors.
- Vegan Consumers:Ethical alignment with animal-free production methods supports price premiums for certified plant-based fermentation. This segment shows lowest price elasticity across all buyer categories.
- Fitness Enthusiasts:Post-workout recovery positioning with electrolyte-enhanced formulations targets gym-adjacent retail channels.
- Organic Shoppers:USDA certification requirements govern purchase decisions, with limited tolerance for conventional ingredient tolerance thresholds.
Health-conscious consumers generate the highest volume; vegan buyers deliver the steepest margin expansion trajectory.
Distribution Channel:
Margin pools concentrate in direct subscription models, while conventional supermarkets impose slotting fee barriers that favor scaled operators.
- Supermarkets:Mass-market penetration requires pasteurized shelf-stable formats or costly refrigerated section placement. PepsiCo Inc. leverages existing refrigerated distribution scale to secure linear footage.
- Health Food Stores:Staff-educated environments support premium raw kombucha with live-culture stability claims. These channels tolerate shorter shelf lives and higher price points.
- Online Retailers:Subscription direct-to-consumer platforms capture repeat velocity through personalized curation and flexible delivery cadences.
- Specialty Stores:Curated assortments in German and Dutch urban centers favor synbiotic hybrid formats over conventional kombucha.
Supermarkets retain volume leadership; online retailers are climbing the fastest through recurring revenue bypass of slotting fees.
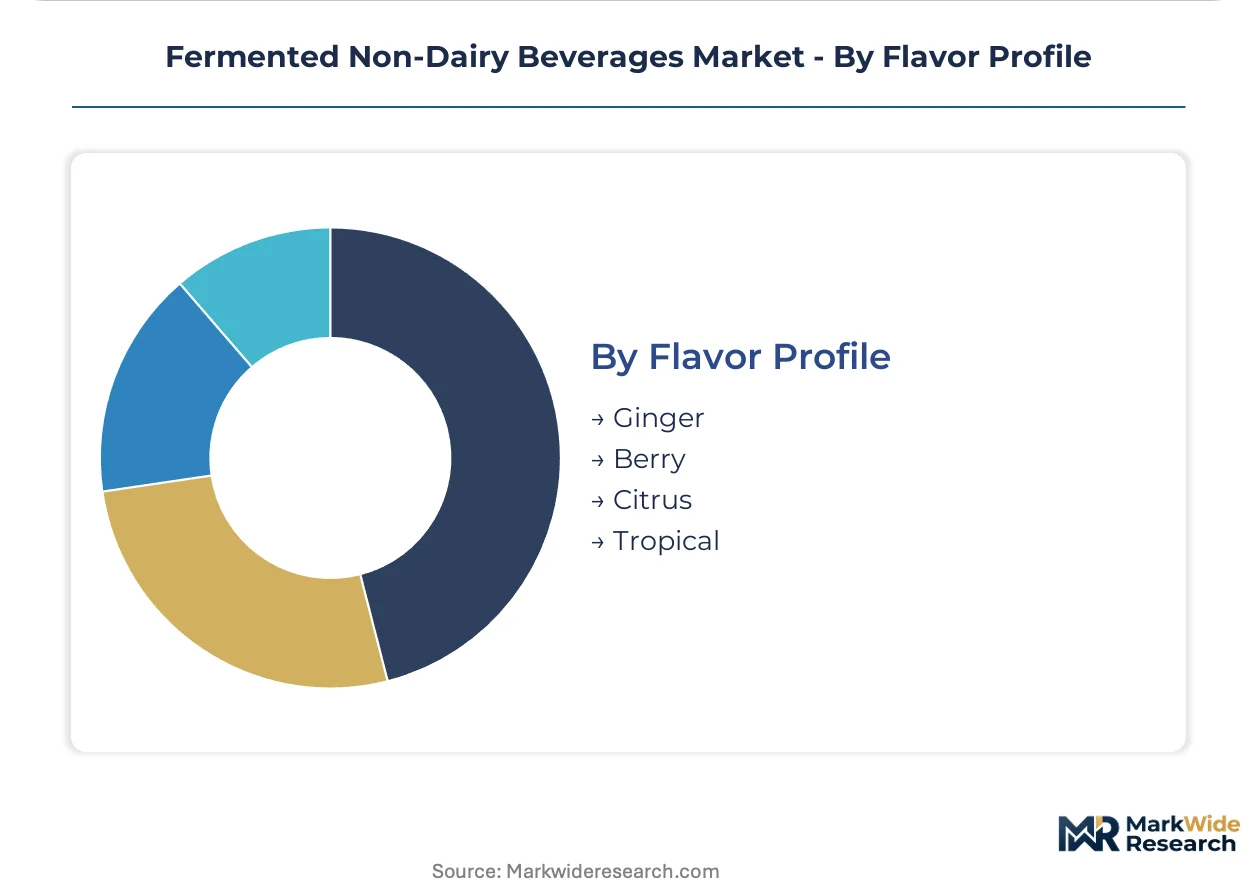
Flavor Profile:
Application-driven formulation separates functional ingredient delivery from palatability-focused mass market variants.
- Ginger:Rhizome-derived compounds enhance digestive positioning and mask fermentation acidity. Functional benefit claims support premium pricing in health food channels.
- Berry:Anthocyanin content supports antioxidant marketing while broad consumer familiarity drives trial conversion. This profile anchors mainstream supermarket placement.
- Citrus:Ascorbic acid stability challenges require modified atmosphere packaging investments. Bright acidity profiles attract younger demographic trial.
- Tropical:Pineapple and mango substrates align with tepache tradition and summer seasonal purchasing patterns. Limited year-round demand constrains production scale.
Berry formulations command the broadest placement; ginger variants gain share fastest through functional positioning premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German consumers prioritize EFSA-substantiated gut health claims, while California buyers favor raw unpasteurized formats with live-culture transparency, creating divergent product development requirements across major markets.
United States
California's functional beverage cluster drives oat-based kefir R&D and subscription direct-to-consumer models. FDA GRAS self-affirmation governs probiotic stability claims. Los Angeles and San Francisco anchor venture capital access for rapid formulation iteration.
Germany
Specialty retailers expand shelf space for probiotic kombucha despite EFSA health claim scrutiny under the Nutrition and Health Claims Regulation. The EU Green Deal pressures manufacturers to document fermentation carbon intensity. Berlin and Hamburg concentrate synbiotic hybrid adoption.
Netherlands
Urban consumers adopt synbiotic formulations faster than conventional kombucha segments. REACH compliance governs packaging material recyclability claims. Amsterdam anchors curated specialty store distribution for hybrid probiotic-prebiotic products.
United Kingdom
Health-conscious buyers in London prioritize viable CFU counts over flavor variety. The FSA enforces live-culture labeling requirements for refrigerated formats. The Southeast corridor concentrates subscription platform penetration.
Japan
Fitness enthusiasts drive electrolyte-enhanced fermented beverage demand in gym-adjacent channels. METI guidelines influence functional food substantiation standards. Tokyo anchors post-workout recovery positioning for kefir-style alternatives.
Fermented Non-Dairy Beverages Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational beverage conglomerates leveraging refrigerated distribution scale against craft producers commanding premium positioning through cold-chain control. The structure bifurcates between industrial-scale operators with dairy-alternative infrastructure and dedicated fermentation specialists. Two archetypes dominate: diversified food and beverage conglomerates with existing refrigerated networks, and focused fermentation houses with captive SCOBY supply relationships. Competitive moves concentrate on backward integration into mother culture sourcing and geographic expansion through subscription direct-to-consumer platforms.
Among diversified conglomerates, PepsiCo Inc. and Danone S.A occupy positions anchored by refrigerated distribution infrastructure and dairy-alternative platform leverage. GT's Living Foods LLC exemplifies the specialist archetype through dedicated cold-chain control. These three represent the competitive spectrum from mass-market scale to premium raw-format positioning.
| Leading Market Players |
|---|
| DuPont de Nemours Inc |
| Chr. Hansen A/S |
| PepsiCo Inc. |
| KeVita Inc. |
| GT's Living Foods LLC |
| Danone S.A |
| Yakult Honsha Co. Ltd. |
| Health-Ade LLC |
| General Mills Inc. |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between California oat processors and kefir-style manufacturers lock in both SCOBY supply access and price visibility for live-culture formulations, insulating premium raw-format producers from organic acid feedstock volatility while binding contract counterparties to minimum volume commitments under FDA GRAS notification timelines.
Pricing Analysis
Long-term offtake contracts dominate premium raw kombucha tiers, while spot purchasing governs shelf-stable pasteurized variants. Price differentiation rests on cold-chain certification grade and organic acid stability guarantees. Pricing pressure stems from gluconic acid feedstock cost compression squeezing industrial-scale fermentation margins. Vegan consumers show lowest price sensitivity; organic shoppers in conventional supermarkets exhibit highest elasticity.
Supply Chain Analysis
California and Germany anchor SCOBY mother culture production and precision fermentation R&D infrastructure respectively. Supply chains draw from tea base concentrates, tibicos grains, and controlled-atmosphere packaging films. Single-source vulnerability clusters among three domestic SCOBY suppliers. Distribution runs through refrigerated last-mile networks for raw formats and ambient logistics for pasteurized alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in synbiotic hybrid formats as EFSA health claim scrutiny bifurcates the market between substantiated premium tiers and unverified craft positioning, creating niche entry points for specialized fermentation houses.
For Market Incumbents: Compound cold-chain infrastructure advantages through backward integration into SCOBY mother culture sourcing, neutralizing supply concentration risk from the three domestic suppliers. Expand capacity in California's functional beverage cluster to capture venture capital-backed formulation iteration velocity before EFSA novel food assessments accelerate European competitive entry. For New Entrants and Emerging Players: Anchor in water kefir diabetic positioning for glucose-management end users underserved by sugary kombucha variants. Target subscription direct-to-consumer models to bypass supermarket slotting fee barriers imposed on scaled refrigerated distribution. Lead with lower glycemic index substantiation to differentiate from established tea-based fermentation brands. For Investors and Strategic Acquirers: Capital is best deployed toward specialist fermentation houses with captive SCOBY supply relationships and dedicated cold-chain control capabilities. Long-term viability hinges on regulatory navigation competence across FDA GRAS self-affirmation and EFSA novel food pathways. Watch live-culture labeling compliance evolution as the inflection indicator for reformulation investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SCOBY Sourcing | Captive mother culture supply neutralizes single-point vulnerability for craft producers. |
| Subscription Direct-to-Consumer Launch | Recurring revenue platforms bypass slotting fees and capture repeat purchase velocity. |
| Synbiotic Hybrid Format Introduction | Probiotic-prebiotic combinations fragment category boundaries in German and Dutch specialty channels. |
| California R&D Cluster Expansion | Proximity to venture capital enables rapid oat-based kefir formulation iteration. |
| EFSA Health Claim Substantiation Investment | Human intervention studies unlock German specialty retailer shelf space expansion. |
Research Methodology
A standing panel of fermentation microbiologists, refrigerated distribution logistics directors, specialty retail category buyers, and probiotic formulation scientists provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation against FDA GRAS notification databases, EFSA novel food assessment registers, USDA organic certification records, and California venture capital disbursement filings. Bottom-up volume modeling triangulated against top-down expenditure analysis.
Consistency checks validated segment-level outputs against external benchmarks including refrigerated beverage velocity data, organic acid feedstock price indices, and cold-chain infrastructure capacity surveys. The analytical framework modeled product type, end user archetype, distribution channel, and flavor profile dimensions across the projection horizon. CAGRs derived from growth rate regression analysis incorporating live-culture stability requirements, EFSA regulatory timeline assumptions, and subscription platform adoption curves.
Material uncertainties — EFSA health claim rulings, FDA GRAS notification requirement changes, organic acid feedstock price volatility, and cold-chain infrastructure buildout pace — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory pathway durations and consumer willingness-to-pay for viable CFU count transparency. Recalibration cycles align with material shifts in live-culture labeling compliance and novel food assessment streamlining.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Non-Alcoholic Drinks Market
Non-Alcoholic Beverages
United Arab Emirates Bottled Water Market
Non-Alcoholic Beverages
Fruit-Infused Water Market
Non-Alcoholic Beverages
United States Energy Drink Market
Non-Alcoholic Beverages
Zero Proof Spirit Market
Non-Alcoholic Beverages
Lemonade Market
Non-Alcoholic Beverages
Energy Drinks Market
Non-Alcoholic Beverages
Non-Dairy Beverages Market
Non-Alcoholic Beverages
Probiotic Soda Market
Non-Alcoholic Beverages
Europe Energy Drink Market
Non-Alcoholic Beverages
Africa Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Rtd Bubble Tea Market
Non-Alcoholic Beverages
Europe Sports Drink Market
Non-Alcoholic Beverages
Coffee Substitute Market
Non-Alcoholic Beverages
US Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
China Non-Alcoholic Beverages Market