
 Europe Energy Drink Market | 2026-2036
Europe Energy Drink Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Energy Drink Market Analysis
Natural caffeine extracts from green tea and yerba mate are broadening formulation economics beyond synthetic caffeine dependence. Red Bull GmbH leverages its Austrian manufacturing base to sustain premium positioning across Central European convenience channels. Monster Beverage Corporation anchors its portfolio through deep sports-event sponsorships that dominate youth-oriented retail. PepsiCo, Inc. competes via extensive supermarket distribution networks spanning multiple European markets.
An energy drink is a functional beverage containing caffeine, taurine, B-vitamins, and carbohydrates, formulated to deliver acute mental alertness and physical performance enhancement through rapid absorption. These products typically contain 80 to 300 milligrams of caffeine per serving and undergo hot-fill or aseptic processing to ensure shelf stability without preservatives. The sugar-free product type leads volume contribution as health-conscious consumers reject caloric loads, while organic formulations capture the fastest growth trajectory driven by clean-label preferences. Fitness enthusiasts among end users concentrate margin pools through higher per-capita spending and subscription-based online purchasing patterns.
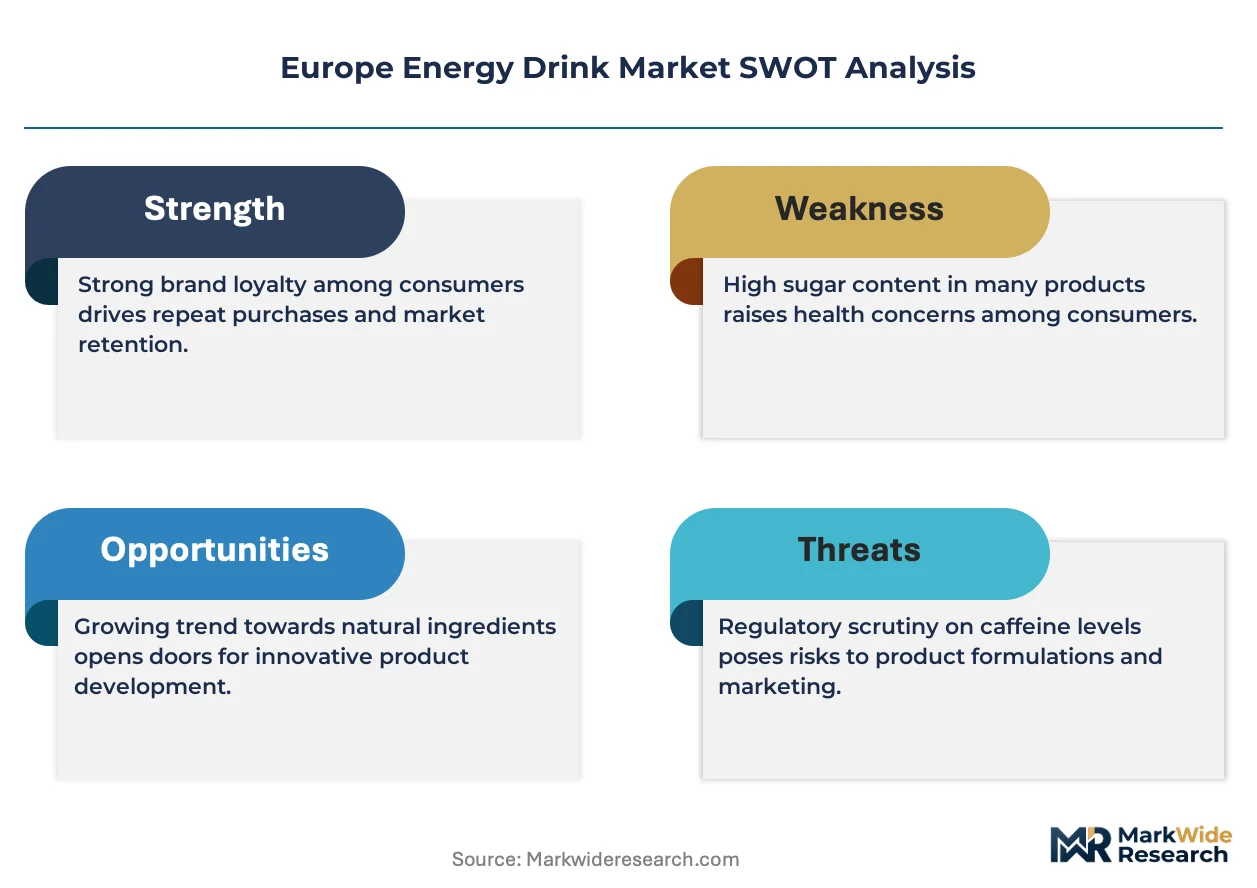
The European Food Safety Authority (EFSA) mandates strict caffeine-content thresholds and health-claim substantiation that shape product development cycles across the continent. The EU Green Deal and Farm to Fork Strategy impose escalating sustainability requirements on ingredient sourcing and packaging recyclability that filter market access for new entrants. Germany's Federal Institute for Risk Assessment (BfR) enforces additional national vigilance on novel stimulant additives beyond baseline EFSA guidelines. Stakeholders must monitor evolving caffeine-limit proposals and carbon-footprint disclosure rules to preempt compliance-driven reformulation costs.
Market Dynamics
The EU's Farm to Fork Strategy is compressing formulation cycles as manufacturers race to substitute synthetic inputs with certified-organic alternatives before mandatory disclosure deadlines hit. This regulatory acceleration is redrawing competitive boundaries between established brands and agile clean-label entrants.
Growth Catalysts
- ESG-Driven Procurement Mandates:Corporate wellness programs across Germany and France now subsidize functional beverages meeting EU Green Deal carbon-footprint thresholds, expanding institutional purchasing pools.
- Clean-Label Extraction Technologies:Supercritical CO2 processing of green tea and yerba mate is slashing residual solvent concerns while preserving bioactive alkaloid profiles for premium positioning.
- Fitness Subscription Economies:Direct-to-consumer platforms serving CrossFit and HYROX communities in the UK and Netherlands are locking in recurring revenue through personalized caffeine-dosing algorithms.
Market Restraints
- Natural Caffeine Supply Volatility:Yerba mate harvest fluctuations in South America expose European formulators to price spikes that synthetic caffeine buffers against.
- Regulatory Friction from BfR Add-on Scrutiny:Germany's Federal Institute for Risk Assessment imposes national vigilance requirements beyond baseline EFSA caffeine limits, fragmenting compliance costs.
- Functional Water Substitution:Electrolyte-enhanced still waters with moderate natural caffeine are capturing health-conscious consumers seeking hydration-plus-stimulation without taurine loads.
Strategic Opportunities
- Poland and Romania Convenience Expansion:Underpenetrated petrol-station and transit-hub channels in these markets offer first-mover advantages for brands with ambient-stable aseptic formats.
- EU Packaging and Packaging Waste Regulation:The 2025 recyclability mandates are creating openings for aluminum-bottle innovators who can pre-certify closed-loop supply chains.
- Esports and Cognitive Performance Positioning:Nootropic-adjacent formulations targeting competitive gaming communities remain underserved relative to traditional sports marketing saturation.
Industry Challenges
- Novel Food Approval Timelines:EFSA's 18-to-24-month novel food safety assessments for emerging botanical stimulants delay product launches and consume R&D budgets.
- Reformulation Capex Burden:Sugar-free transitions require capital-intensive flavor-masking investments and line reconfigurations that strain mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Energy Drink Market |
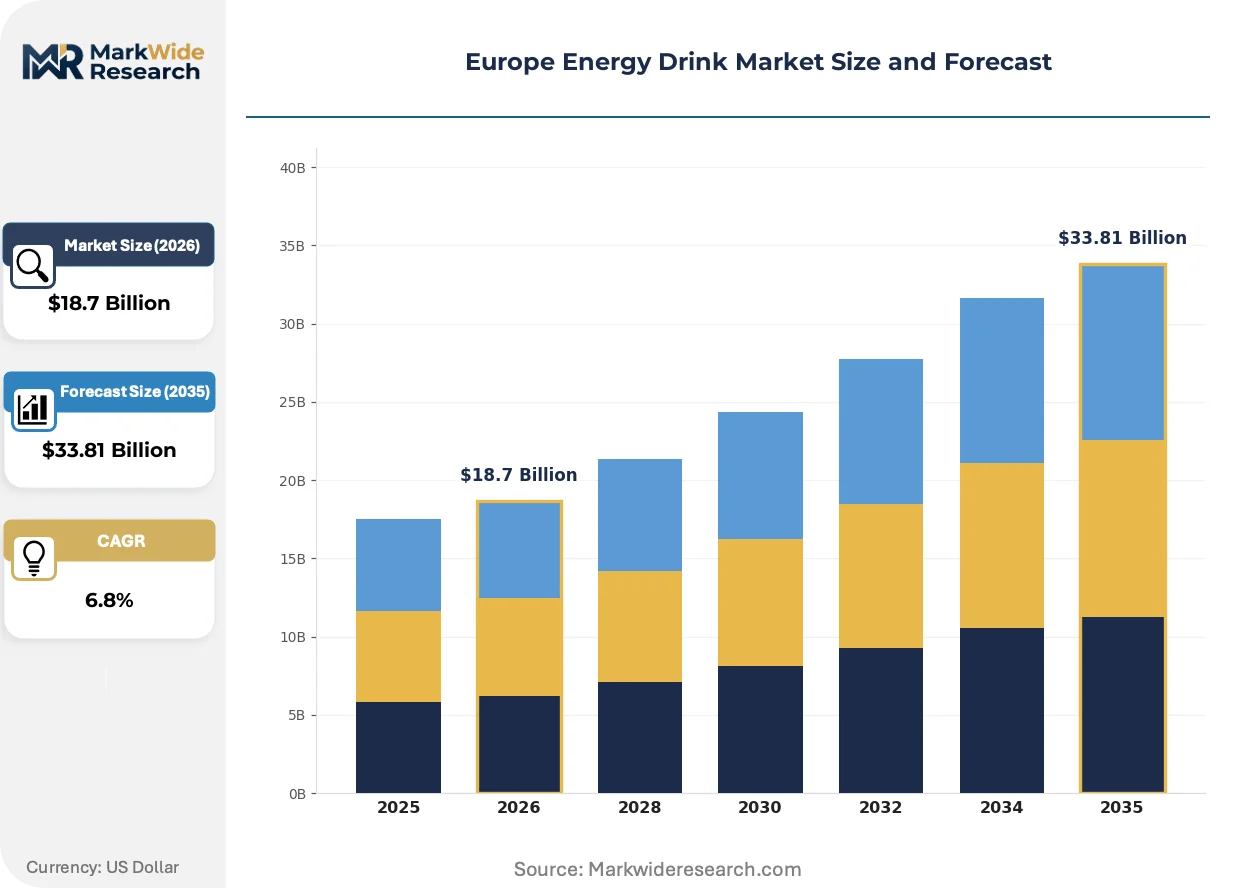
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbonated, Non-Carbonated, Sugar-Free, Organic End User: Students, Athletes, Working Professionals, Fitness Enthusiasts Distribution Channel: Convenience Stores, Supermarkets, Online Retail, Health Stores Flavor: Citrus, Berry, Tropical, Herbal |
| Companies Covered | Red Bull GmbH, Monster Beverage Corporation, PepsiCo, Inc., The Coca-Cola Company, Lucozade Ribena Suntory Limited, Suntory Holdings Limited, Vitamin Well Limited, Hell Energy, Rockstar Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Energy Drink Market Emerging Trajectories
Digital traceability infrastructure and bioactive ingredient engineering are converging to redefine how European consumers verify and experience functional beverage efficacy. These shifts are compressing traditional quality-assurance cycles while elevating transparency expectations.
Aseptic hot-fill processing with nitrogen dosing is automating shelf-life extension without chemical preservatives. German and Austrian contract manufacturers are deploying these systems at scale to serve private-label entrants. The technology is automating compliance with clean-label mandates while reducing spoilage rates in ambient distribution channels.
REACH and the EU Packaging and Packaging Waste Regulation are forcing material transitions across the value chain. Recycled aluminum content thresholds and extended producer responsibility fees are reshaping packaging procurement decisions. Sugar-free and organic sub-segments face the steepest cost adjustments as they disproportionately rely on premium single-serve formats.
Subscription-based replenishment models are displacing impulse-heavy convenience store purchasing among core 25-to-40 demographics. Nordic markets lead this behavioral pivot, with Swedish and Finnish consumers showing highest adoption of personalized delivery schedules tied to training calendars. Digital-native brands with direct distribution infrastructure capture disproportionate lifetime value from these cohorts.
Europe Energy Drink Market Segmentation
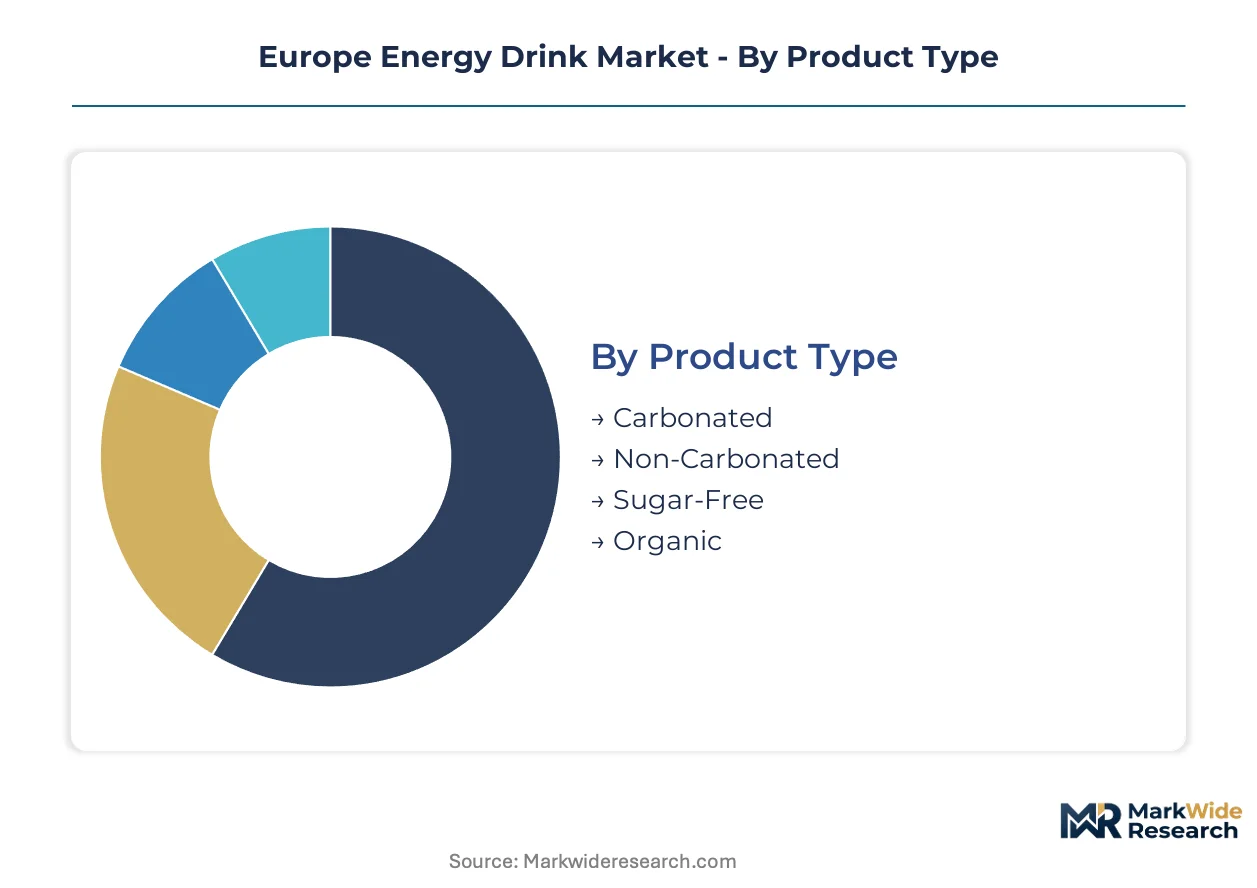
Segmentation in the Europe Energy Drink Market reveals how formulation technology, distribution infrastructure, and consumer physiology intersect to create distinct margin pools. Manufacturers must align R&D investment with the specific absorption profiles and purchasing contexts that define each segment's economics.
Product Type:
Carbonation technology and sweetener systems differentiate manufacturing complexity and shelf-stability requirements across this axis.
- Sugar-Free:Aspartame-ace-K and stevia-rebaudioside formulations dominate German and UK supermarket shelves as BfR guidance on caloric reduction tightens. Health-conscious working professionals in corporate wellness programs drive recurring volume through subscription channels.
- Organic:Certified inputs under EU Regulation 2018/848 command premium positioning in Austrian and Dutch health stores. Supply bottlenecks for organic caffeine extracts from South American yerba mate plantations constrain scaling beyond niche positioning.
- Carbonated:Hot-fill aseptic processing with CO2 saturation delivers the standard sensory profile across Central European petrol stations. Established brands leverage existing bottling infrastructure to defend convenience channel presence.
- Non-Carbonated:Still formats with rapid-absorption carbohydrate matrices target pre-workout consumption among CrossFit communities in the UK and Netherlands. Smaller pack sizes suit transit-hub vending in underpenetrated Polish markets.
Mature deployment sits with Carbonated. Newer deployment is concentrated in Organic.
End User:
Physiological demand intensity and purchasing frequency separate high-margin subscription cohorts from impulse-driven occasional buyers.
- Fitness Enthusiasts:HYROX and CrossFit participants in Sweden and Finland demonstrate highest per-capita spend through personalized caffeine-dosing subscription platforms. EFSA caffeine threshold awareness shapes their product selection criteria.
- Working Professionals:Corporate procurement subsidies under France and Germany's Green Deal compliance frameworks institutionalize bulk purchasing. Mid-afternoon consumption peaks drive demand for sustained-release formulations.
- Students:Examination-period purchasing concentrates in university-adjacent convenience stores across Spain and Italy. Price sensitivity limits penetration of premium organic positioning.
- Athletes:Traditional sports sponsorship exposure sustains brand recognition, though taurine-free alternatives erode share among hydration-focused endurance competitors.
Volume concentration rests with Working Professionals. Margin expansion is climbing the fastest among Fitness Enthusiasts.
Distribution Channel:
Cold-chain requirements and planogram negotiations determine which formulation types achieve scalable presence.
- Online Retail:Direct-to-consumer infrastructure enables personalized subscription scheduling tied to training calendars in Nordic markets. Recurring revenue models capture lifetime value from 25-to-40 demographics.
- Convenience Stores:Ambient-stable aseptic formats dominate impulse purchasing at German motorway service stations. Shelf-space fees favor established brands with trade marketing budgets.
- Supermarkets:Extensive distribution networks span multiple European markets through centralized procurement, though sugar-free SKUs face margin pressure from private-label entrants.
- Health Stores:Certified-organic and nootropic-adjacent formulations find curated placement in Austrian and Dutch specialist retailers. Staff recommendation influence sustains premium pricing.
Scale economics favor Supermarkets. Channel expansion is gaining share fastest through Online Retail.
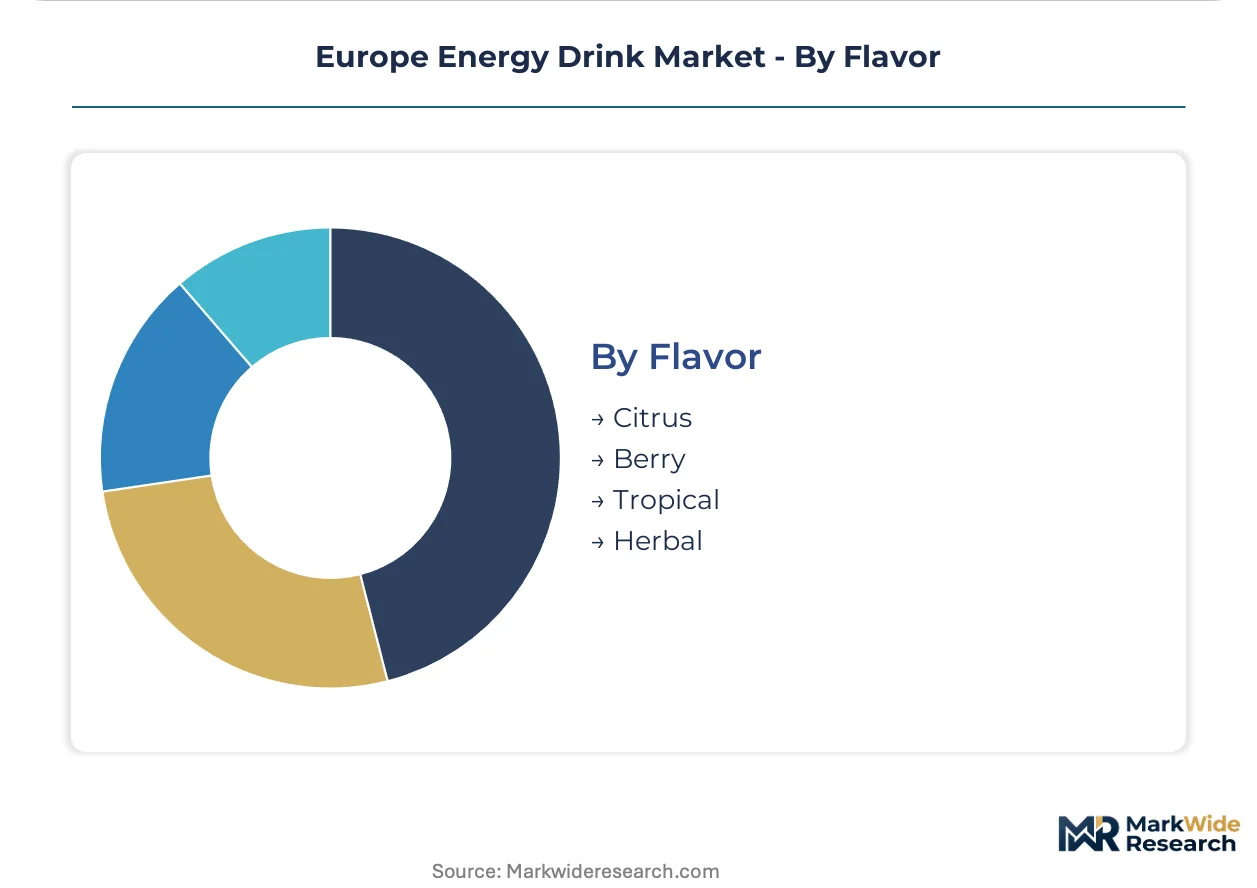
Flavor:
Botanical sourcing geography and extraction method cost structures shape formulation R&D allocation.
- Citrus:Mediterranean-sourced lemon and bergamot extracts align with clean-label positioning in Italian and Spanish markets. Supercritical CO2 processing preserves volatile compounds for premium tier placement.
- Berry:Nordic lingonberry and bilberry formulations leverage regional sourcing narratives in Swedish and Finnish retail. Anthocyanin stability challenges limit ambient shelf life.
- Tropical:Mango and passionfruit profiles target youth-oriented convenience channels through sports-event sponsorship tie-ins. Synthetic flavor cost advantages sustain mass-market pricing.
- Herbal:Yerba mate and green tea extracts deliver natural caffeine with botanical complexity for Austrian health-store positioning. EFSA novel food assessments delay new ingredient launches.
Mainstream penetration clusters around Citrus. Steepest expansion trajectory is visible in Herbal.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, where functional beverage consumption per capita leads the region. Corporate wellness programs and petrol-station distribution density sustain volume leadership. Sustainability mandates under the EU Green Deal are redrawing competitive boundaries across member states.
Germany
Fitness enthusiasts and working professionals drive per-capita consumption through subscription platforms and corporate procurement subsidies. The Federal Institute for Risk Assessment enforces national vigilance on novel stimulant additives beyond baseline EFSA guidelines. Bavaria hosts contract manufacturing clusters deploying aseptic hot-fill systems for private-label entrants.
United Kingdom
CrossFit and HYROX communities fuel demand for personalized caffeine-dosing algorithms through direct-to-consumer channels. EFSA caffeine-content thresholds shape product selection criteria among educated consumers. London anchors esports and cognitive performance positioning for nootropic-adjacent formulations.
France
Corporate wellness programs subsidize functional beverages meeting EU Green Deal carbon-footprint thresholds, expanding institutional purchasing pools. The EU Packaging and Packaging Waste Regulation imposes 2025 recyclability mandates on aluminum procurement. Paris-based health stores curate certified-organic placement with staff recommendation influence.
Sweden
Nordic consumers show highest adoption of personalized delivery schedules tied to training calendars through subscription-based replenishment models. Lingonberry and bilberry formulations leverage regional sourcing narratives in specialist retail. Stockholm digital-native brands capture disproportionate lifetime value from 25-to-40 demographics.
Poland
Underpenetrated petrol-station and transit-hub channels offer first-mover advantages for ambient-stable aseptic formats. Still formats with rapid-absorption carbohydrate matrices suit vending deployment in emerging fitness communities. Warsaw convenience retail expansion attracts brands with trade marketing budgets.
Europe Energy Drink Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments. The market structure consolidates around established beverage conglomerates with deep distribution infrastructure, while agile clean-label entrants capture niche premium positioning. Three archetypes dominate: heritage energy specialists with sports-event sponsorship exposure, diversified beverage multinationals leveraging supermarket networks, and digital-native direct-to-consumer brands. Competitive moves center on sugar-free reformulation pipelines and sustainable packaging pre-certification.
Within the heritage specialist tier, Red Bull GmbH and Monster Beverage Corporation exemplify contrasting geographic anchoring strategies. The Austrian GmbH structure of Red Bull leverages Central European manufacturing proximity, while Monster Beverage Corporation occupies a position tied to North American-origin sports marketing saturation. Among diversified multinationals, PepsiCo, Inc. represents the scale-driven archetype with extensive European supermarket penetration. These three entities anchor the competitive spectrum from premium convenience channels to mass-market retail.
| Leading Market Players |
|---|
| Red Bull GmbH |
| Monster Beverage Corporation |
| PepsiCo, Inc. |
| The Coca-Cola Company |
| Lucozade Ribena Suntory Limited |
| Suntory Holdings Limited |
| Vitamin Well Limited |
| Hell Energy |
| Rockstar Inc. |
| Others |
Supply Flow & Price Mechanics
Contract manufacturing specialists concentrated in Bavaria and Lower Austria feed labor-cost differentials into three-tier pricing spreads across premium organic, standard sugar-free, and economy carbonated tiers. ESG compliance investments compress margins at the bottom while supercritical extraction capabilities sustain premium markups.
Pricing Analysis
Volume concentrates in carbonated convenience formats while margin pools shift toward personalized subscription tiers. Three-tier pricing structure across premium, standard, and economy levels separates certified-organic positioning from mass-market impulse SKUs. Price differentiation hinges on clean-label certification status and carbon-footprint disclosure depth. Pricing pressure stems from private-label sugar-free entrants in German supermarket channels, with students showing highest price sensitivity and fitness enthusiasts demonstrating lowest.
Supply Chain Analysis
Freight cost volatility from South American yerba mate shipments to Rotterdam and Hamburg feeds into organic formulation premiums. Raw material sourcing draws from Brazil and Argentina for natural caffeine, Germany and Austria for aseptic processing equipment, and Italy for citrus extracts. Single-source vulnerability sits with South American yerba mate harvest fluctuations. Distribution runs through ambient-stable petrol-station networks for impulse volumes and direct-to-consumer platforms for subscription tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where EFSA novel food approval timelines and reformulation capex burdens force sub-scale private-label manufacturers toward exit or acquisition.
For Market Incumbents: Anchor shelf presence through exclusive aseptic hot-fill contracts with Bavarian contract manufacturers, locking out emerging clean-label competitors from production capacity. Pre-certify aluminum closed-loop supply chains under EU Packaging and Packaging Waste Regulation mandates before 2025 recyclability deadlines hit. Control convenience channel planograms through petrol-station exclusivity payments that exhaust mid-tier trade marketing budgets.
For New Entrants and Emerging Players: Capture white-space in Polish and Romanian transit-hub vending through still-format rapid-absorption carbohydrate matrices suited to emerging CrossFit communities. Target esports cognitive performance positioning in London and Stockholm where nootropic-adjacent formulations remain underserved relative to sports marketing saturation. Launch through personalized caffeine-dosing subscription platforms with training-calendar integration to bypass incumbent convenience channel dominance.
For Investors and Strategic Acquirers: Re-rating potential sits with digital-native direct-to-consumer brands given subscription revenue visibility and Nordic market penetration depth. Long-term viability across the analysis window favors assets with captive organic caffeine sourcing or proprietary supercritical extraction IP. Watch EFSA caffeine-limit proposal progression as the inflection signal for reformulation capex exposure among synthetic-dependent portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Caffeine Sourcing | Mitigates yerba mate price volatility exposure from South American harvest fluctuations. |
| Direct-to-Consumer Platform Launch | Captures recurring revenue from Swedish and Finnish fitness subscription economies. |
| Sustainability Repositioning | Aligns portfolio with EU Green Deal carbon-footprint thresholds for corporate procurement subsidies. |
| Aseptic Processing Capacity Expansion | Secures contract manufacturing slots for private-label entrants in Bavarian production clusters. |
| Esports Marketing Partnership | Penetrates underserved cognitive performance segment beyond traditional sports sponsorship saturation. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across brand managers at energy drink manufacturers, category buyers at German supermarket chains, contract manufacturing operations heads in Bavaria, and EFSA regulatory affairs specialists. Secondary sources included EFSA novel food safety assessments, EU Packaging and Packaging Waste Regulation documentation, BfR vigilance reports, and Nielsen retail audit data. Bottom-up volume builds by SKU and channel triangulated against top-down category spending estimates.
Granularity extended to product type, end-user physiology, distribution channel cold-chain requirements, and flavor extraction method cost structures across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by per-unit value realization. Industry-specific inputs incorporated EFSA caffeine threshold compliance costs and EU Green Deal carbon-footprint disclosure implementation timelines.
The model holds under stable EFSA regulatory timelines and South American yerba mate harvest patterns; deviation in novel food approval delays or climate-driven crop failures would shift capacity planning assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Diet Soda Market
Non-Alcoholic Beverages
United States Energy Drink Market
Non-Alcoholic Beverages
Global Sugar Free Beverages Market
Non-Alcoholic Beverages
Iced Tea Market
Non-Alcoholic Beverages
Naturally Cultured Beverages Market
Non-Alcoholic Beverages
Flavored Water Market
Non-Alcoholic Beverages
China Energy- Drinks Market
Non-Alcoholic Beverages
Soy Beverage Market
Non-Alcoholic Beverages
Zero Proof Spirit Market
Non-Alcoholic Beverages
Europe Soy Beverages Market
Non-Alcoholic Beverages
Europe Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
Brazil Energy Drinks Market
Non-Alcoholic Beverages
Non-Alcoholic Beer Market
Non-Alcoholic Beverages
Gulf Cooperation Council (GCC) Bottled Water Market
Non-Alcoholic Beverages
Bubble Tea Market
Non-Alcoholic Beverages
Ice Tea Market