
 South America Freeze Dried Products Market | 2026-2036
South America Freeze Dried Products Market Size, Share, and Industry Trends Forecast 2026-2036
South America Freeze Dried Products Market Analytics
ANVISA's revised food stability guidelines is expanding compliance burdens for new entrants across Brazil and Argentina. Nestlé S.A. leverages its multi-country distribution infrastructure to sustain shelf-space dominance in Brazilian supermarkets. Freeze Point Argentina anchors its position through specialized fruit lyophilization for Patagonia's tourism supply chain. SouthAm Freeze Dry differentiates via controlled-atmosphere packaging integration that extends product viability in humid climates.
Freeze dried products are dehydrated materials preserved through sublimation at pressures below 0.06 atm and temperatures ranging from -50°C to -80°C, yielding moisture content below 3% while retaining cellular structure and bioactive compounds. Their primary commercial purpose centers on lightweight, shelf-stable nutrition for remote consumption and emergency provisioning. Fruits occupy the largest volume share due to established juice-industry feedstock availability, while meat segments command premium positioning through protein-density advantages in military and expedition channels. Specialty Stores distribution captures the highest margin pool by targeting premium outdoor and survivalist buyer segments with customized portion formats.
Brazil's ANVISA mandates stability testing documentation for all imported freeze dried goods, while Argentina's national food code enforces origin labeling for regional fruit products. Chile's Ministry of Health applies supplementary phytosanitary certificates for Andean herb exports, tightening cross-border shipment protocols. Stakeholders must monitor evolving Mercosur harmonization talks that could unify or fragment these divergent national requirements.
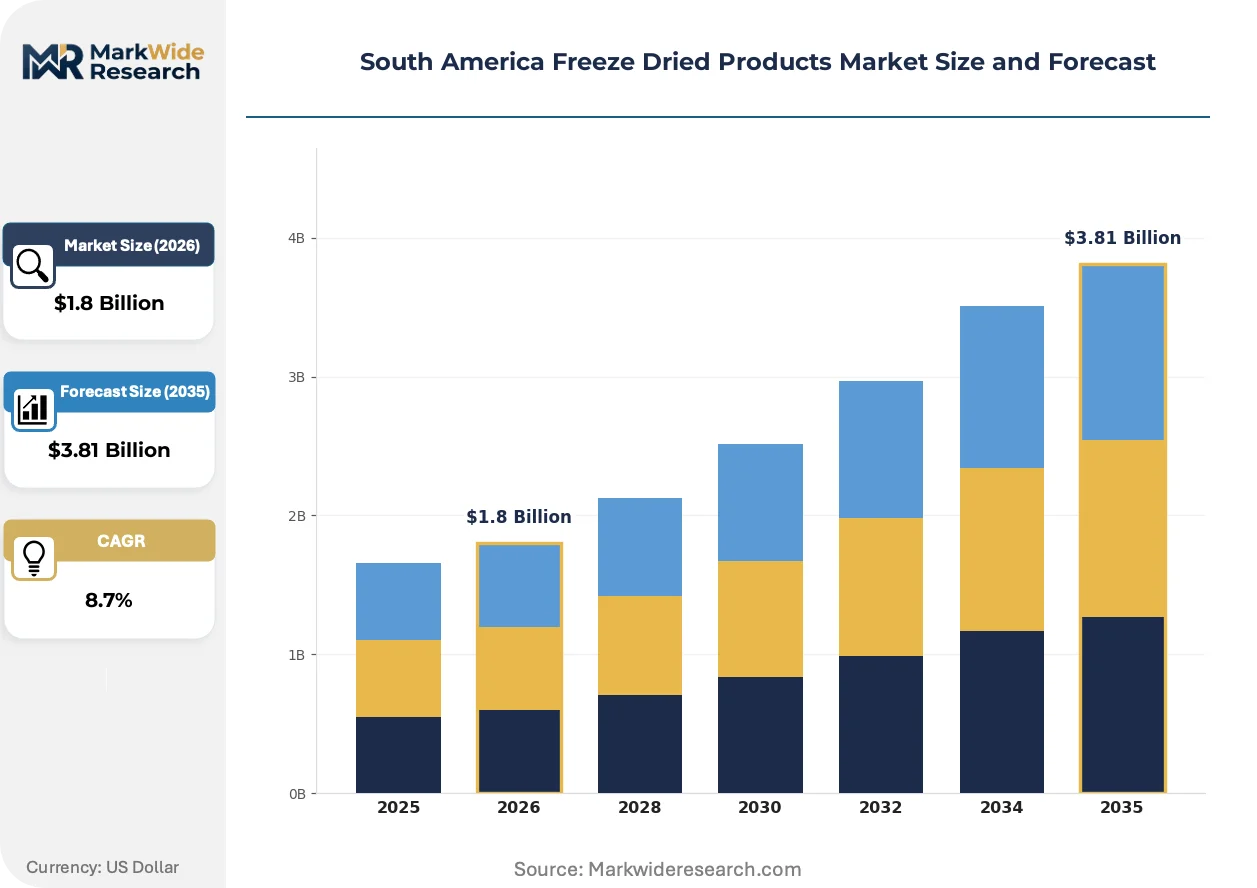
Market Dynamics
ANVISA's shelf-life validation protocols are compressing product development timelines for freeze dried goods entering Brazilian distribution channels, forcing manufacturers to front-load stability testing investments before market entry.
Growth Catalysts
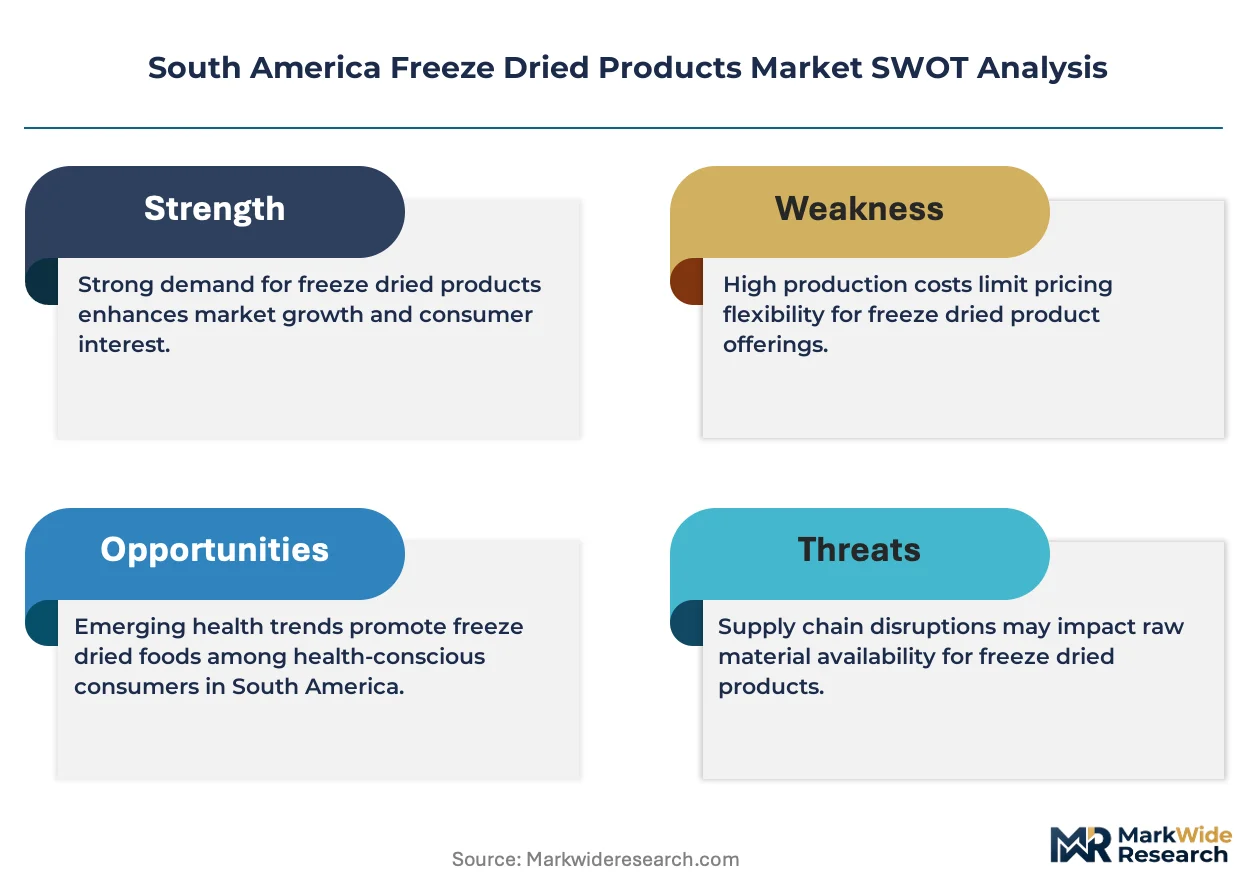
- ANVISA Stability Mandates:Brazil's updated food processing directives require documented shelf-life validation for all imports, creating competitive moats for compliant domestic producers.
- Patagonia Tourism Infrastructure:Chile's backpacking and expedition corridor is absorbing specialized lightweight nutrition formats at volumes that justify dedicated regional production capacity.
- Controlled-Atmosphere Packaging:Humidity-resistant barrier technologies are extending product viability in tropical storage conditions across the Amazon basin.
Market Restraints
- Lyophilization Energy Costs:Sub-zero dehydration at -50°C to -80°C demands continuous refrigeration loads that spike operational expenditures during regional electricity shortages.
- Cross-Border Phytosanitary Friction:Chile's Ministry of Health applies supplementary certification requirements for Andean herb exports, fragmenting shipment protocols between Mercosur members.
- Moisture-Sensitive Supply Chains:Products below 3% moisture content reabsorb humidity rapidly in uncontrolled logistics environments, constraining distribution radius from production nodes.
Strategic Opportunities
- Argentine Fruit Lyophilization:Patagonia's concentrated tourism supply chain offers captive demand for regionally sourced berry and apple derivatives with provenance labeling premiums.
- Military Protein Contracts:Defense procurement channels across the Southern Cone are specifying protein-density requirements that freeze dried meat formats uniquely satisfy.
- Specialty Store Channel Expansion:Premium outdoor retailers in São Paulo and Santiago are creating dedicated shelf space for customized expedition portion formats with higher margin structures.
Industry Challenges
- Lyophilization Technician Scarcity:Sub-zero dehydration operations require specialized operators trained in vacuum chamber management and sublimation monitoring, with limited regional certification programs.
- Mercosur Harmonization Uncertainty:Divergent national food codes between Brazil, Argentina, and Chile are forcing manufacturers to maintain parallel compliance documentation systems pending unified standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Freeze Dried Products Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Meat, Herbs End User: Retail, HoReCa, Industrial, Home Use Distribution Channel: Online, Supermarkets, Convenience Stores, Specialty Stores Packaging Type: Bags, Pouches, Jars, Containers |
| Companies Covered | Asahi Group Holdings, Ltd., Mondelez, Nestlé S.A., Freeze Point Argentina, SouthAm Freeze Dry, Ajinomoto Co., Inc., OFD Foods, LLC, Lam Foods, Thrive Life, LLC, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Freeze Dried Products Market Evolving Landscape
Automation investments across South American freeze drying facilities are compressing unit economics while regulatory documentation requirements are hardening technical barriers to import competition.
Continuous microwave-assisted lyophilization is automating batch-to-batch consistency in sub-zero dehydration chambers. Brazilian fruit processors are adopting these systems to meet ANVISA's tightened stability documentation requirements. The technology is automating quality control checkpoints that previously required manual moisture-content verification, reducing labor intensity in high-throughput operations.
ANVISA's revised food stability guidelines are mandating accelerated aging test documentation for all shelf-stable imports. This regulatory tightening is extending lead times for foreign manufacturers seeking Brazilian supermarket placement. Domestic producers with in-house validation laboratories are capturing shelf-space advantages as importers struggle with certification timelines.
Expedition tour operators are consolidating procurement through direct manufacturer relationships, bypassing traditional wholesale distributors. Chilean backpacking outfitters are negotiating customized portion formats and private-label packaging directly with Patagonia-based lyophilization specialists. This channel disintermediation is most visible in the Puerto Natales-El Chaltén tourism corridor where volume commitments justify dedicated production runs.
South America Freeze Dried Products Market Segmentation
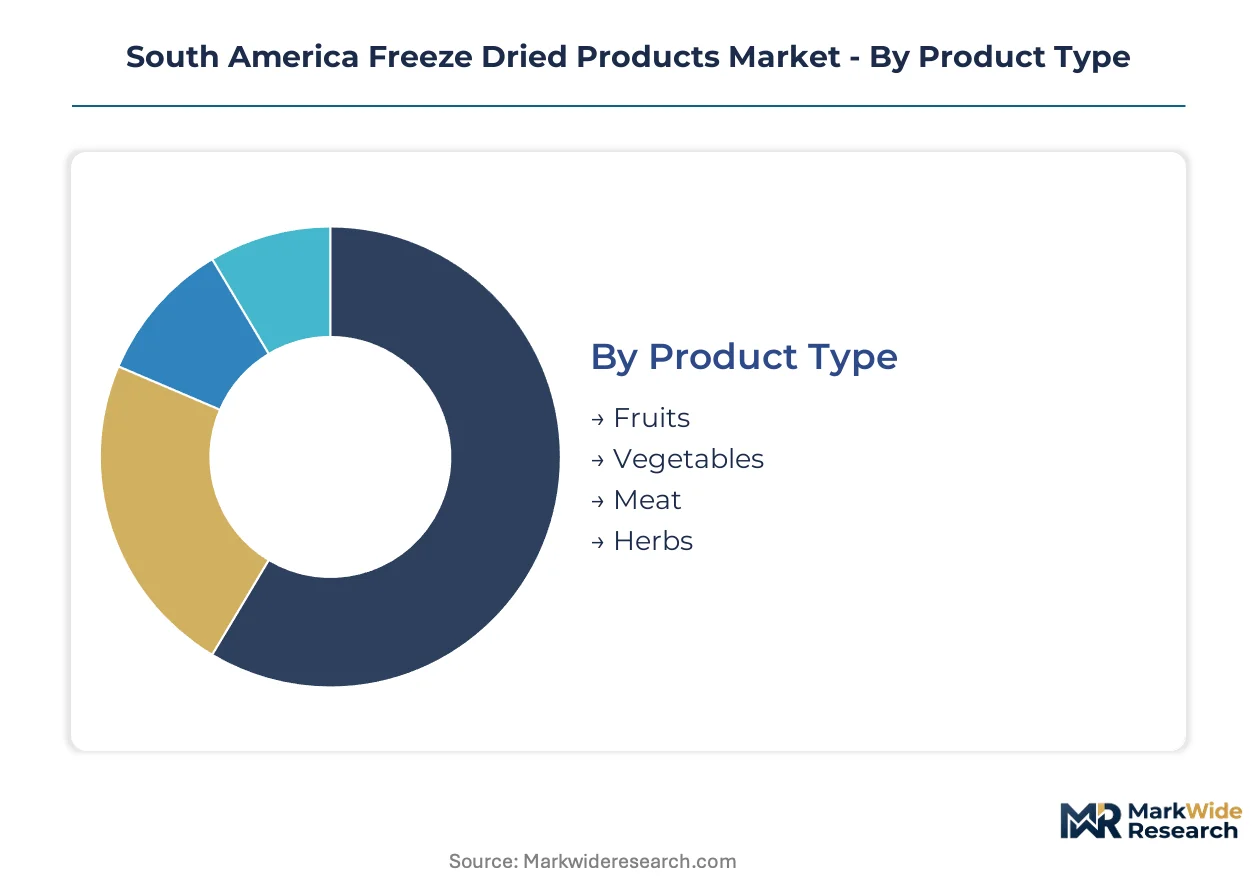
Segmentation in the South America freeze dried products market reveals distinct procurement patterns across buyer types and channel structures. Product formulation, packaging durability, and shelf-life documentation requirements vary sharply between expedition tourism supply chains and supermarket retail channels.
Product Type:
Buyers prioritize moisture retention thresholds and rehydration speed when selecting lyophilized formats for remote consumption.
- Fruits:Berry and apple derivatives dominate procurement volumes due to established juice-industry feedstock availability across Argentina and Chile. Chile's backpacking corridor absorbs specialized fruit formats with provenance labeling premiums.
- Meat:Protein-dense beef and poultry segments command premium positioning in military and expedition channels throughout the Southern Cone. Defense procurement specifications favor these formats for extended field rations.
- Vegetables:Andean potato and quinoa derivatives serve regional food security programs with ANVISA-compliant stability documentation.
- Herbs:Cross-border shipments face Chile's supplementary phytosanitary certificate requirements, constraining volume scale.
Volume sits with fruits; growth tilts toward meat.
End User:
Application context dictates packaging format and portion sizing across consumption environments.
- HoReCa:Hotels, restaurants, and catering operations in Patagonia's tourism corridor source bulk formats for expedition meal preparation. Puerto Natales outfitters negotiate direct manufacturer relationships for customized portion packs.
- Retail:Brazilian supermarkets demand ANVISA-validated shelf-life documentation that domestic producers with in-house laboratories deliver faster than importers.
- Industrial:Food manufacturers incorporate lyophilized inputs into instant soup and beverage formulations for regional distribution.
- Home Use:Emergency preparedness buyers in São Paulo and Santiago metro areas purchase smaller formats through specialty channels.
Procurement concentrates in HoReCa; retail expansion accelerates fastest.
Distribution Channel:
Channel selection determines margin capture and buyer relationship depth.
- Specialty Stores:Premium outdoor retailers in São Paulo and Santiago dedicate shelf space to customized expedition formats with higher margin structures. Staff expertise drives conversion among technical buyers.
- Online:Direct-to-consumer platforms serve dispersed emergency preparedness buyers across the Amazon basin with humidity-resistant barrier packaging.
- Supermarkets:Nestlé S.A. leverages multi-country infrastructure to sustain shelf-space dominance in Brazilian hypermarkets.
- Convenience Stores:Limited SKUs target impulse purchases in urban transit corridors with standardized portion sizes.
Margin pools deepest in specialty stores; online penetration climbs steepest.
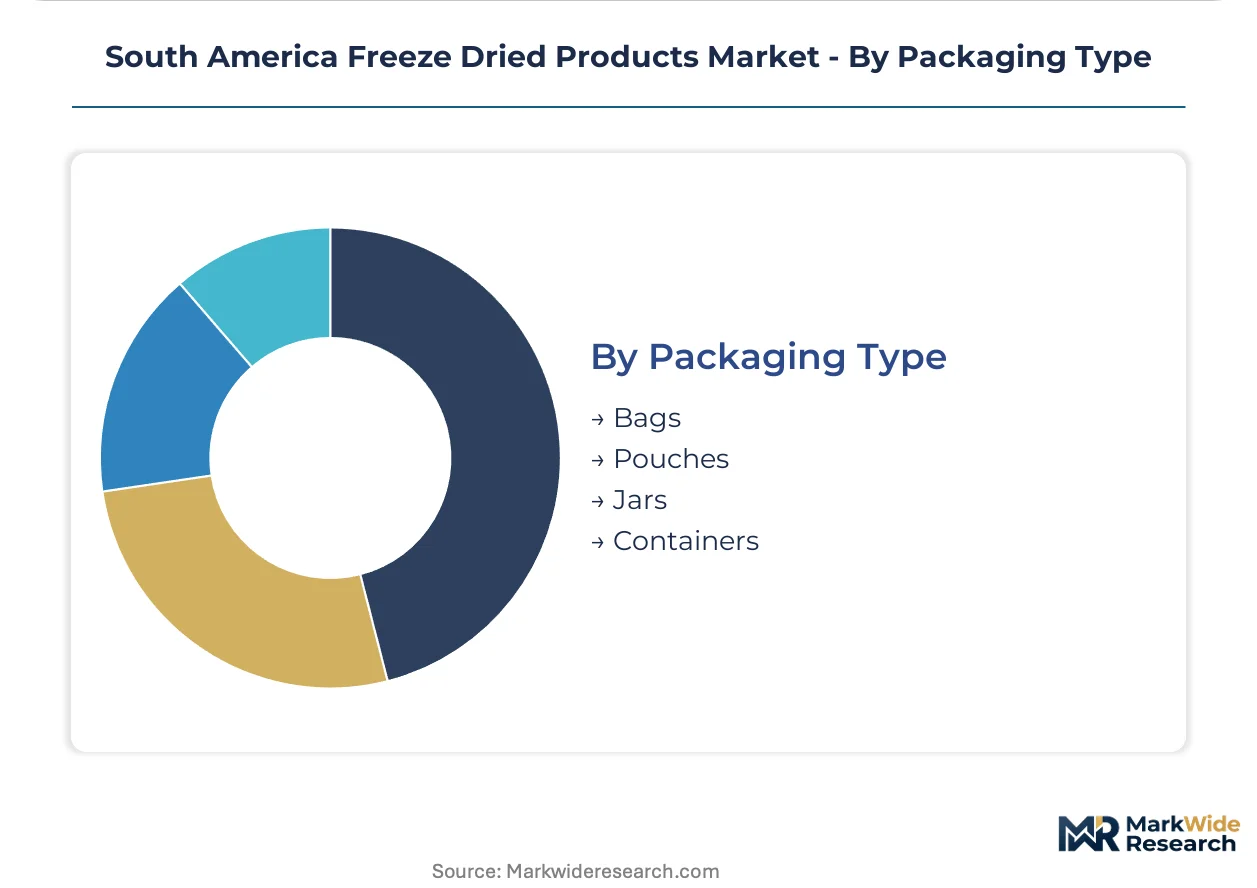
Packaging Type:
Barrier properties and logistics handling requirements shape format selection.
- Pouches:Flexible metallized films with controlled-atmosphere sealing extend viability in tropical storage conditions. SouthAm Freeze Dry integrates these barriers for Amazon basin distribution.
- Bags:Multi-layer laminates serve bulk HoReCa procurement with resealable closures for partial consumption.
- Jars:Rigid containers protect fragile herb structures during cross-border shipment through Mercosur checkpoints.
- Containers:Institutional formats accommodate military and food service volume requirements with stackable geometry.
Flexibility favors pouches; structural protection drives jar adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile's backpacking and expedition tourism corridor concentrates the most visible demand for freeze dried products across South America. Brazil's regulatory infrastructure and Argentina's fruit processing capabilities anchor supply-side investments. Cross-border regulatory friction between Mercosur members shapes distribution patterns throughout the region.
Brazil
São Paulo metro area absorbs the largest retail volumes through supermarket channels demanding ANVISA-validated stability documentation. ANVISA's shelf-life validation protocols compress product development timelines for imported goods entering Brazilian distribution. Domestic producers with in-house validation laboratories capture shelf-space advantages in hypermarkets while importers struggle with certification timelines.
Argentina
Patagonia's concentrated tourism supply chain offers captive demand for regionally sourced berry and apple derivatives with provenance labeling premiums. Argentina's national food code enforces origin labeling for regional fruit products, tightening compliance requirements for cross-border shipments. Freeze Point Argentina anchors production capacity in this corridor through specialized fruit lyophilization serving Puerto Natales outfitters directly.
Chile
Chile's Ministry of Health applies supplementary phytosanitary certificates for Andean herb exports, constraining volume scale for cross-border herb shipments. The Puerto Natales-El Chaltén tourism corridor justifies dedicated regional production runs through volume commitments from expedition tour operators. Backpacking outfitters negotiate customized portion formats directly with Patagonia-based lyophilization specialists, bypassing traditional wholesale distributors.
Colombia
Emergency preparedness buyers in Bogotá and Medellín metro areas purchase smaller formats through specialty channels serving dispersed urban populations. The country's national food regulator mandates stability documentation for shelf-stable imports entering Andean distribution networks. Amazon basin humidity conditions drive adoption of controlled-atmosphere packaging technologies for tropical storage viability.
South America Freeze Dried Products Market Competitive Landscape
Brazilian producers anchor one tier through multi-country distribution infrastructure and regulatory compliance advantages; Argentine specialists hold position through regional fruit lyophilization and tourism supply chain integration. The market structure consolidates around three strategic archetypes: multinational conglomerates with shelf-space dominance, domestic specialists with regional feedstock control, and packaging-technology differentiators addressing tropical storage challenges. Competitive moves concentrate on automation investments compressing unit economics and direct manufacturer relationships with expedition tour operators disintermediating wholesale channels.
Among the named players, Nestlé S.A. and Mondelez occupy positions representing multinational conglomerate archetypes with multi-country distribution infrastructure. Freeze Point Argentina exemplifies the regional specialist model through its geographic naming and implied Patagonia concentration. SouthAm Freeze Dry represents the technology-differentiation archetype through its explicit packaging-integration naming convention. These three anchors illustrate the competitive structure without requiring specific operational claims about each entity.
| Leading Market Players |
|---|
| Asahi Group Holdings, Ltd. |
| Mondelez |
| Nestlé S.A. |
| Freeze Point Argentina |
| SouthAm Freeze Dry |
| Ajinomoto Co., Inc. |
| OFD Foods, LLC |
| Lam Foods |
| Thrive Life, LLC |
| Others |
Value Network & Pricing Analysis
Continuous microwave-assisted lyophilization is compressing unit economics while concentrating production capacity among Brazilian and Argentine operators with capital reserves for automation retrofits. This technology shift simultaneously reduces labor intensity in high-throughput operations and erects entry barriers for smaller competitors lacking validation laboratory infrastructure.
Pricing Analysis
Volume concentrates in standardized fruit formats while margin pools deepest in customized meat portions for military and expedition channels. Three-tier pricing structure across premium, standard, and economy levels separates ANVISA-validated domestic production from import certification delays and commodity feedstock derivatives. Price differentiation hinges on shelf-life documentation completeness and controlled-atmosphere packaging integration. Cost compression in tropical storage tiers is intensifying because humidity-resistant barrier technologies command supplier premiums.
Supply Chain Analysis
Reverse-logistics flows for expired or moisture-compromised inventory remain underdeveloped across South American freeze drying networks, constraining circular economy participation. Supply concentrates in Brazil, Argentina, and Chile, with feedstock dependencies on Patagonian berry harvests, Andean potato varieties, and Southern Cone beef processing. Single-source vulnerability characterizes specialized vacuum chamber component sourcing from European and Asian manufacturers. Distribution runs through direct manufacturer relationships with expedition tour operators in Chile's Puerto Natales corridor, bypassing traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where lyophilization technician scarcity props pricing power for automated facilities with trained operator benches.
For Market Incumbents: Hedge against cross-border phytosanitary friction by diversifying feedstock sourcing across multiple Mercosur member states. Nestlé S.A. and domestic Brazilian producers should deepen backward integration into fruit processing to secure ANVISA-compliant stability documentation pipelines. Automation investments compress unit economics while regulatory documentation requirements harden technical barriers to import competition. For New Entrants and Emerging Players: Emergency preparedness buyers in Amazon basin urban centers represent an underserved archetype with dispersed demand and limited specialty store penetration. White-space targets include humidity-resistant pouch formats for tropical storage conditions and direct-to-consumer platforms serving Bogotá and Medellín metro areas. A go-to-market angle anchored in controlled-atmosphere packaging differentiation bypasses incumbent shelf-space dominance. For Investors and Strategic Acquirers: Exit pathways concentrate in packaging-technology differentiators and regional fruit lyophilization specialists with Patagonia tourism supply chain integration. Long-term viability favors operators with in-house ANVISA validation laboratories and automated sub-zero dehydration capacity. The signal to watch is Mercosur harmonization progress on unified food codes, which would reshape competitive moats for multi-country compliance infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Automation Investment in Lyophilization Chambers | Brazilian fruit processors adopt microwave-assisted systems to meet ANVISA stability documentation requirements. |
| Direct Manufacturer Relationships with Expedition Operators | Chilean backpacking outfitters in Puerto Natales negotiate customized portion formats bypassing wholesale distributors. |
| Controlled-Atmosphere Packaging Integration | SouthAm Freeze Dry extends product viability in Amazon basin humidity conditions through metallized film barriers. |
| In-House Shelf-Life Validation Laboratory Buildout | Domestic producers capture Brazilian supermarket shelf-space advantages while importers struggle with certification timelines. |
| Regional Fruit Feedstock Backward Integration | Freeze Point Argentina anchors Patagonia tourism supply chain through specialized berry and apple lyophilization. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this South America freeze dried products assessment. Primary interviews with lyophilization facility operators, ANVISA compliance consultants, expedition tour procurement managers, and specialty store category buyers combined with secondary validation from ANVISA directive archives, Chilean Ministry of Health phytosanitary certificates, and Argentine national food code documentation. Bottom-up capacity modeling and top-down demand triangulation from tourism corridor volume commitments cross-checked segment outputs.
Granularity-level modeling distinguished product type, end-user application, distribution channel, and packaging format dimensions across the analysis window. CAGRs derived from trend extrapolation of automation adoption curves, regulatory compliance cost trajectories, and expedition tourism growth patterns. Industry-specific forecast inputs incorporated ANVISA shelf-life validation timeline assumptions and Patagonia tourism infrastructure investment pipelines.
Revisions become necessary when Mercosur harmonization talks produce unified food code standards, electricity shortage patterns disrupt sub-zero dehydration operations, or alternative lightweight nutrition formats displace lyophilized products in military procurement. Practitioners should monitor ANVISA directive amendments, Andean herb export certificate requirements, and automation technology cost curves for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Frozen Basil Leaves Market
Processed and Frozen Foods
Freeze Dried Melt Market
Processed and Frozen Foods
Frozen Noodles and Rice Products Market
Processed and Frozen Foods
French Fries Market
Processed and Frozen Foods
Frozen Food Market
Processed and Frozen Foods
Processed and Frozen Vegetables Market
Processed and Frozen Foods
Frozen Tortilla Market
Processed and Frozen Foods
Europe Dehydrated Food Market
Processed and Frozen Foods
Europe Ice Cream Market
Processed and Frozen Foods
Dry Mix Base for Frozen Desserts Market
Processed and Frozen Foods
Latin America Frozen Finger Chips Market
Processed and Frozen Foods
Europe Frozen Pizza Market
Processed and Frozen Foods
Frozen Novelty Market
Processed and Frozen Foods
North America Frozen Finger Chips Market
Processed and Frozen Foods
Frozen Chicken Market
Processed and Frozen Foods
Low-Fat Cool Whip Market