
 Frozen Soup Market | 2026-2036
Frozen Soup Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Soup Market Analysis
BRC food safety certification is reorganizing competitive access for frozen soup manufacturers selling through major retail channels in North America and Europe. Nestlé leverages its global cold-chain infrastructure to sustain shelf presence across multiple continents. Campbell Soup Company anchors its position through deep brand equity in condensed and ready-to-serve formats. Kettle Cuisine specializes in premium chef-crafted recipes that command placement in specialty food shops and upscale supermarkets.
Frozen soup consists of pre-prepared broth-based or cream-based formulations, flash-frozen at temperatures below minus eighteen degrees Celsius to preserve flavor compounds and nutritional integrity, designed for extended storage and rapid reheating in commercial or residential settings. Vegetable soup leads volume production due to lower input costs and broad dietary compatibility, while single-serve bowls capture the fastest growth trajectory as portion-controlled convenience aligns with solo dining trends. Microwaveable cups retain mature demand among office workers and travel segments where heating equipment access varies.
The FDA governs nutritional labeling and pathogen control standards for frozen soup distributed in the United States, while the USDA oversees products containing meat or poultry ingredients through its FSIS inspection protocols. EFSA and national regulators across Europe enforce strict additive limits and origin labeling under the EU Food Information to Consumers regulation. Stakeholders must monitor evolving clean-label requirements and cold-chain energy costs as dual pressures that will determine which manufacturing configurations remain viable.
Market Dynamics
FDA-mandated sodium reduction timelines are forcing frozen soup manufacturers to rebuild entire formulation pipelines, compressing product development cycles from eighteen months to under ten months as brands race to maintain shelf placement.
Growth Catalysts
- Single-Serve Convenience:Solo dining patterns among urban professionals in the United States are pulling portion-controlled formats into foodservice contracts and retail freezers alike.
- Clean-Label Reformulation:EFSA additive limits under EU Food Information to Consumers regulation are accelerating recipe simplification that resonates with ingredient-conscious shoppers.
- Cold-Chain Infrastructure:Flash-freezing technology at minus eighteen degrees Celsius preserves volatile flavor compounds that retort processing destroys, opening premium positioning.
Market Restraints
- Dairy Input Volatility:Cream-based formulations face margin compression from fluctuating butterfat and milk powder costs that resist hedging.
- Freezer Space Scarcity:Retail chains in Germany and France ration linear footage, forcing smaller brands into secondary placement or delisting.
- Fresh Soup Substitution:Refrigerated deli-case alternatives with shorter ingredient lists capture health-motivated switchers in upscale supermarkets.
Strategic Opportunities
- India Urban Penetration:Nuclear households in Mumbai and Bangalore present untapped demand for heat-and-eat broths compatible with regional spice preferences.
- Meal Kit Integration:Frozen soup pouches bundled with protein and grain components are displacing standalone entrees in subscription box channels.
- USDA Bioengineered Disclosure:Early compliance with upcoming labeling mandates positions reformulated SKUs for preferential placement in natural-product aisles.
Industry Challenges
- Sensory Scientist Scarcity:Formulators who can replicate mouthfeel after sodium reduction and freeze-thaw cycles command salaries that strain mid-tier R&D budgets.
- BRC Certification Timelines:Eighteen-month audit queues at accredited bodies delay market entry for new manufacturing facilities serving British retail.
- Legacy ERP Integration:Lot-traceability modules required by FSIS for meat-containing soups clash with decades-old inventory systems at regional co-packers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Soup Market |
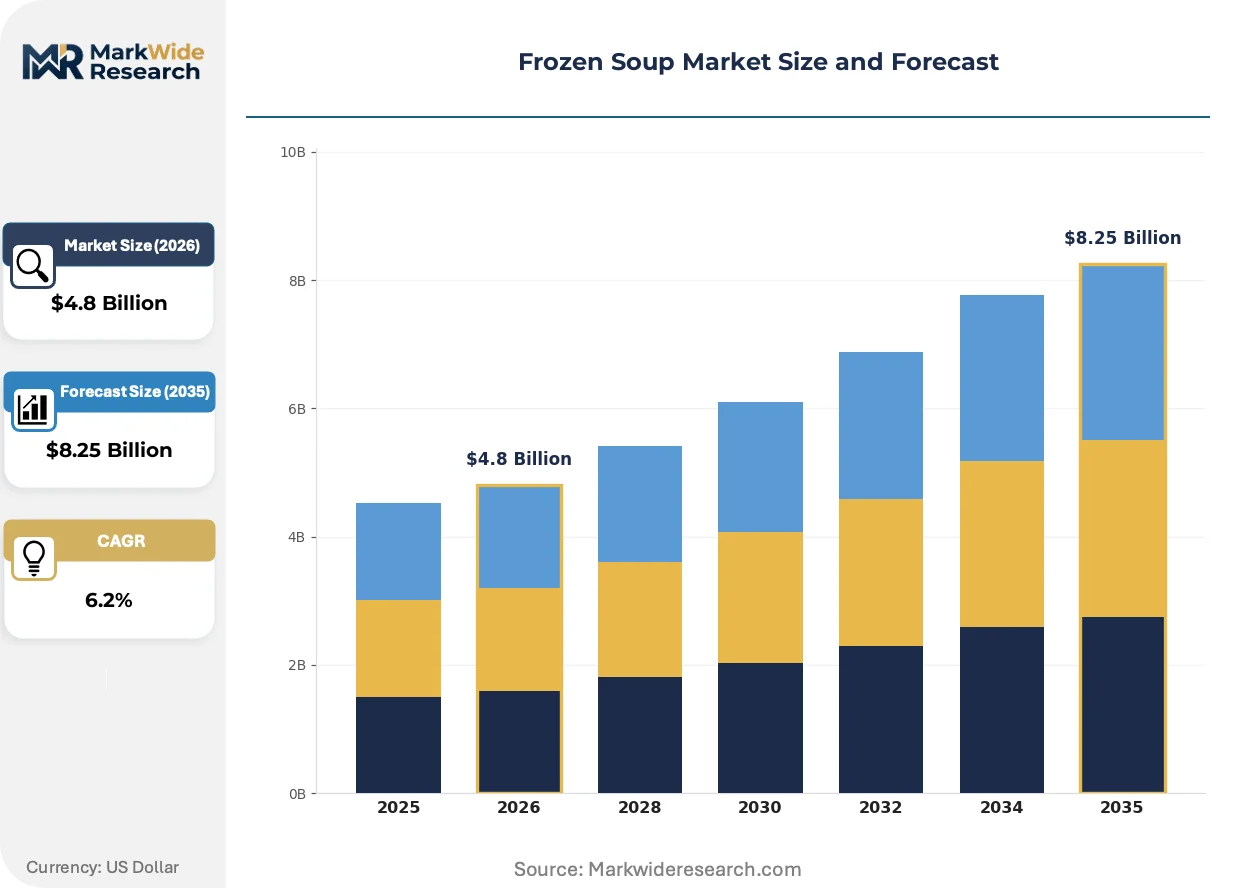
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Soup, Chicken Soup, Seafood Soup, Bean Soup Packaging Type: Microwaveable Cups, Family Size Bags, Pouches, Single-Serve Bowls End User: Households, Restaurants, Catering Services, Meal Delivery Services Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Specialty Food Shops |
| Companies Covered | Nestlé, Kettle Cuisine, Campbell Soup Company, Progresso, Amy's Kitchen, Conagra Foods, Blount Fine Foods, Tabatchnick, Kraft Heinz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Soup Market Emerging Trajectories
Flash-freezing equipment advances are compressing the quality gap between industrial and artisanal production, while regulatory disclosure mandates and channel fragmentation are rewriting how brands build consumer trust.
Individual quick-freezing tunnels with cryogenic nitrogen injection are fragmenting the capital barrier that once separated mass-market and specialty producers. Mid-size manufacturers in Italy and Spain are adopting second-generation IQF lines that preserve vegetable cell structure through ultra-rapid surface freezing. This capability diffusion is compressing the premium tier as regional brands achieve texture parity with multinational portfolios.
EU Food Information to Consumers regulation is mandating origin labeling for primary ingredients that exceeds current US disclosure requirements. Manufacturers sourcing vegetables across multiple member states must now map and verify supply chain nodes for every lot. Ready-to-serve formats containing meat face the strictest documentation burdens, pushing some brands toward all-vegetable recipes to simplify compliance.
Direct-to-freezer subscription models are bypassing traditional retail slotting fees entirely. Consumers in Australia and South Korea are accepting weekly deliveries of flash-frozen soup assortments that bypass the supermarket entirely. This channel emergence is forcing legacy brands to build captive e-commerce fulfillment capabilities or cede relationship ownership to platform intermediaries.
Frozen Soup Market Segmentation
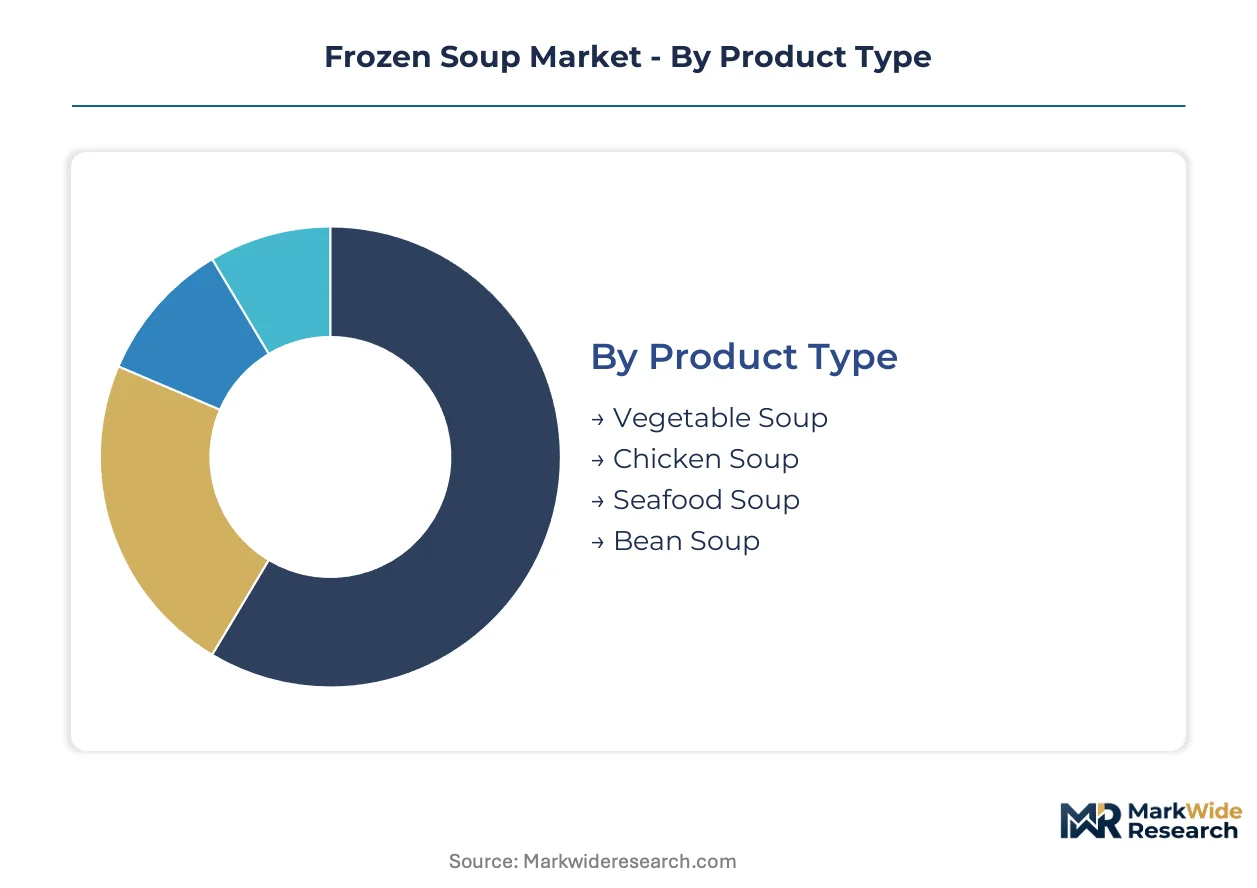
Frozen soup manufacturers configure production lines and cold-chain logistics around discrete demand clusters. Channel access, portion formats, and end-use thermal requirements dictate which segments warrant dedicated manufacturing investment.
Product Type:
Retail buyers source vegetable and chicken formulations through mainstream supermarkets, while seafood and bean varieties concentrate in specialty food shops and meal delivery channels where premium positioning sustains margins.
- Vegetable Soup:Formulations emphasize flash-frozen cruciferous and root vegetables at minus eighteen degrees Celsius to preserve cell structure through freeze-thaw cycles. Demand concentrates in United States urban households where clean-label compatibility and lower sodium targets align with FDA reformulation timelines.
- Chicken Soup:USDA FSIS inspection protocols apply to all meat-containing varieties, requiring lot-traceability systems that raise compliance costs. United States foodservice operators drive volume through food safety certification requirements that favor established suppliers with BRC documentation.
- Seafood Soup:Premium positioning in coastal United States markets and European specialty channels where origin labeling under EFSA regulations commands price premiums.
- Bean Soup:Protein-forward formulations gaining placement in meal delivery service bundles targeting vegetarian dietary preferences.
Vegetable soup dominates installed base. Chicken soup is where expansion concentrates.
Packaging Type:
Cost tiers separate commodity formats from premium positioning, with capital intensity and shelf-space economics determining channel viability.
- Microwaveable Cups:Dual-layer polypropylene constructions withstand thermal cycling from freezer to microwave. Office workers and travel segments in United States metropolitan areas sustain mature demand where heating equipment access varies unpredictably.
- Single-Serve Bowls:Portion-controlled formats align with solo dining trends among urban professionals. Meal delivery services in United States coastal cities are pulling this format into subscription contracts at rates outpacing retail velocity.
- Family Size Bags:Multi-portion polyethylene formats serve household replenishment shopping in United States suburban supermarkets.
- Pouches:Flexible packaging reduces freight cube and freezer storage footprint, enabling direct-to-consumer shipping economics.
Microwaveable cups hold the largest installed base. Single-serve bowls are climbing the fastest.
End User:
Application requirements diverge sharply between residential reheating and commercial foodservice, with HACCP compliance separating addressable markets.
- Households:Convenience-driven consumption with variable reheating equipment and inconsistent cold-chain handling in residential freezers.
- Restaurants:Back-of-house steam table integration requires rapid thaw characteristics and consistent portion yields under time pressure.
- Catering Services:Volume batch preparation with extended holding requirements favors family-size formats over single-serve.
- Meal Delivery Services:Frozen soup pouches bundled with protein and grain components are displacing standalone entrees in subscription box channels.
Households dominate installed base. Meal delivery services are gaining share fastest.
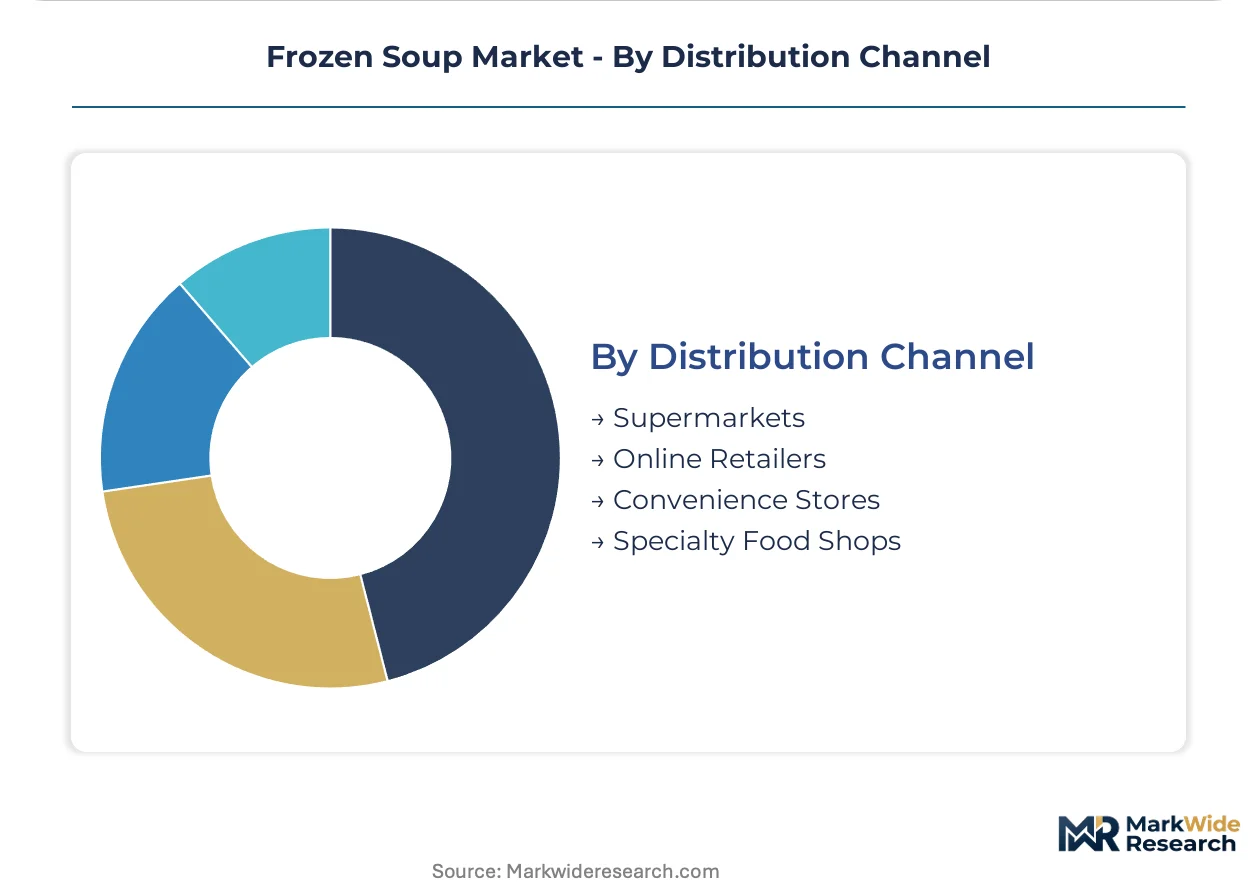
Distribution Channel:
Geography determines which channels warrant direct sales force investment versus third-party logistics arrangements.
- Supermarkets:Linear freezer footage rationing in Germany and France forces secondary placement negotiations, while United States chains offer more expansive frozen soup sets.
- Online Retailers:Direct-to-freezer subscription models in Australia and South Korea bypass slotting fees entirely, requiring captive e-commerce fulfillment capabilities.
- Convenience Stores:Grab-and-go occasions favor microwaveable cups with extended shelf-life dating.
- Specialty Food Shops:Premium chef-crafted recipes command placement through demonstrated provenance and small-batch credentials.
Supermarkets dominate installed base. Online retailers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA-mandated sodium reduction timelines and EU Food Information to Consumers regulation are accelerating reformulation investments across major frozen soup markets, with cold-chain infrastructure expansion determining which geographies sustain manufacturing competitiveness.
United States
Urban professionals in New York, Chicago, and Los Angeles drive single-serve bowl demand through meal delivery subscriptions and foodservice contracts. USDA FSIS inspection protocols apply to all meat-containing varieties, requiring lot-traceability systems that raise compliance costs for regional co-packers. Campbell Soup Company anchors market presence through deep brand equity in condensed and ready-to-serve formats distributed nationwide.
Germany
Retail chains in Berlin and Munich ration linear freezer footage, forcing secondary placement negotiations or delisting for smaller brands. EFSA additive limits under EU Food Information to Consumers regulation accelerate recipe simplification that resonates with ingredient-conscious shoppers in the Rhine-Ruhr industrial cluster. Blount Fine Foods and other premium chef-crafted suppliers target specialty food shops in Hamburg and Frankfurt.
France
Supermarket freezer space scarcity in Paris and Lyon pushes brands toward direct-to-consumer subscription models bypassing traditional slotting fees. EFSA enforces strict origin labeling requirements that exceed US disclosure standards, mandating supply chain mapping for every lot. Kettle Cuisine specializes in premium recipes commanding placement in upscale supermarkets along the Côte d'Azur.
United Kingdom
BRC food safety certification reorganizes competitive access for manufacturers selling through major retail channels in London and Birmingham. Eighteen-month audit queues at accredited bodies delay market entry for new manufacturing facilities serving British retail. Tabatchnick and other established suppliers leverage existing certification to defend shelf position.
Australia
Direct-to-freezer subscription models in Sydney and Melbourne bypass supermarket slotting fees entirely, requiring captive e-commerce fulfillment capabilities. Consumers accept weekly deliveries of flash-frozen soup assortments that bypass traditional retail entirely. Amy's Kitchen and organic-focused brands target natural-product aisles in response to clean-label preferences.
Frozen Soup Market Vendor Landscape
Player mix skews toward diversified multinationals with cold-chain infrastructure and specialty chef-crafted suppliers with premium positioning. The market exhibits tiered concentration where scale-driven portfolios coexist with regional artisanal brands. Two strategic archetypes dominate: global food conglomerates leveraging integrated supply chains, and boutique manufacturers emphasizing small-batch provenance. Competitive moves center on clean-label reformulation acceleration and direct-to-consumer channel bypass of retail slotting structures.
Within the diversified multinational tier, Nestlé leverages its global cold-chain infrastructure to sustain shelf presence across multiple continents, while Kraft Heinz occupies a position anchored in mainstream retail distribution economics. Among specialty-focused suppliers, Kettle Cuisine exemplifies the chef-crafted premium archetype commanding placement in upscale supermarkets and meal delivery channels. Campbell Soup Company represents the heritage-brand vector with deep equity in condensed formats. These three anchors illustrate how competitive positioning stratifies across convenience, premium, and traditional taste-profile segments.
| Leading Market Players |
|---|
| Nestlé |
| Kettle Cuisine |
| Campbell Soup Company |
| Progresso |
| Amy's Kitchen |
| Conagra Foods |
| Blount Fine Foods |
| Tabatchnick |
| Kraft Heinz |
| Others |
Supply Flow & Price Mechanics
Eighteen-month BRC certification queues at accredited bodies compress pricing power for new entrants while rewarding incumbent shelf placement premiums. This lead-time bottleneck concentrates margin capture among established manufacturers with existing cold-chain infrastructure and validated lot-traceability systems.
Pricing Analysis
Certification level (BRC/FDA-grade) creates the primary spread between commodity and premium frozen soup tiers. Three-tier pricing structure across premium chef-crafted, standard retail, and economy private-label levels dominates channel economics. Pricing pressure stems from dairy input volatility in cream-based formulations where butterfat hedging remains ineffective. Foodservice operators exhibit lowest price sensitivity due to HACCP compliance requirements, while suburban household replenishment shoppers drive volume through promotion-dependent purchasing.
Supply Chain Analysis
The United States and Germany anchor flash-freezing equipment manufacturing and IQF technology deployment for frozen soup production. Raw material dependencies center on cruciferous vegetable sourcing from California's Central Valley, poultry supply chains subject to USDA FSIS oversight, and nitrogen cryogenic systems for rapid surface freezing. Single-source vulnerability concentrates in specialized sensory scientists capable of reformulating sodium-reduced recipes. Distribution runs through temperature-controlled third-party logistics networks serving retail freezer cases and direct-to-consumer subscription fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Frozen soup represents a high-growth convenience disruption as FDA sodium reduction mandates and flash-freezing technology advances simultaneously reshape formulation pipelines and quality benchmarks.
For Market Incumbents: Fortify cold-chain infrastructure through captive nitrogen cryogenic capacity additions in United States Midwest production clusters. Accelerate clean-label reformulation ahead of EFSA additive limit enforcement to preempt specialty competitor encroachment. Defend against meal delivery service substitution by integrating frozen soup pouches into subscription box channels.
For New Entrants and Emerging Players: Anchor in direct-to-freezer subscription models bypassing retail slotting fees entirely, as demonstrated in Australian and South Korean markets. Target urban professional solo dining segments with portion-controlled single-serve bowls compatible with microwave reheating constraints. Pursue chef-crafted premium positioning through small-batch provenance narratives and regional spice customization for India urban penetration.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because BRC certification backlogs and sensory scientist scarcity create durable moats around incumbent manufacturing footprints. Acquisition target archetype: mid-tier regional brands with validated FSIS lot-traceability systems and underutilized IQF line capacity. Signal to monitor: meal delivery service contract volumes as leading indicator of channel shift velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Acceleration | FDA sodium reduction timelines compress product development cycles below ten months for shelf retention. |
| Direct-to-Consumer Subscription Launch | Bypasses supermarket slotting fees and freezer space rationing in German and French retail chains. |
| Cold-Chain Infrastructure Expansion | Cryogenic nitrogen IQF lines preserve volatile flavor compounds that differentiate premium positioning. |
| Meal Kit Integration Partnership | Frozen soup pouches bundled with protein components displace standalone entrees in subscription channels. |
| Regional Flavor Customization | Mumbai and Bangalore nuclear households present untapped demand for heat-and-eat broths with local spice profiles. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with frozen soup brand managers, retail category buyers at United States supermarket chains, foodservice procurement directors, cold-chain logistics coordinators, and sensory formulation scientists. Secondary validation drew from FDA FSIS inspection protocols, EFSA additive limit documentation, EU Food Information to Consumers regulatory filings, Nielsen retail audit data, and customs records tracking cryogenic equipment imports. Bottom-up volume modeling triangulated against top-down market sizing across product type, packaging format, and distribution channel segments.
Across the analysis window, projections integrated historical velocity patterns with structural drivers including regulatory reformulation mandates, cold-chain infrastructure buildouts, and channel shift dynamics. Segmentation dimensions encompassed product type (vegetable, chicken, seafood, bean), packaging configuration (microwaveable cups, single-serve bowls, family bags, pouches), and end-use application (household, restaurant, catering, meal delivery). CAGRs were derived from weighted average growth trajectories across these discrete demand clusters, incorporating input cost sensitivity models for dairy and vegetable commodity baskets.
Material uncertainties — regulatory timeline delays, cryogenic energy cost spikes, and meal delivery service contract volatility — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding FDA enforcement consistency and EFSA origin labeling implementation scope. Recalibration cycles align with material shifts in sodium reduction compliance deadlines and flash-freezing technology adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Frozen Yogurt Market
Processed and Frozen Foods
Frozen Food Market
Processed and Frozen Foods
Icebreakers Market
Processed and Frozen Foods
Dehydrated Potato Products Market
Processed and Frozen Foods
North America Frozen Finger Chips Market
Processed and Frozen Foods
Europe Frozen Finger Chips Market
Processed and Frozen Foods
Processed and Frozen Vegetables Market
Processed and Frozen Foods
GCC Frozen Finger Chips Market
Processed and Frozen Foods
Europe Frozen Food Market
Processed and Frozen Foods
North America French Fries Market
Processed and Frozen Foods
North America Freeze Dried Products Market
Processed and Frozen Foods
Frozen Pizza Market
Processed and Frozen Foods
United States Frozen Pizza Market
Processed and Frozen Foods
Bangladesh Frozen Food Market
Processed and Frozen Foods
Kimchi Market
Processed and Frozen Foods
United Arab Emirates Frozen Food Market