
 Dehydrated Potato Products Market | 2026-2036
Dehydrated Potato Products Market Size, Share, and Industry Trends Forecast 2026-2036
Dehydrated Potato Products Market Outlook
Quick-service restaurant chains is unwinding from institutional foodservice buyers as the dominant volume channel for dehydrated potato flakes and granules. Lamb Weston Holdings Inc. leverages its North American processing footprint to supply flake-based ingredients for franchise potato side dishes. McCain Foods Limited anchors its competitive stance through backward integration into proprietary potato varieties optimized for low-moisture dehydration. Idahoan Foods LLC differentiates via retail-branded instant mashed potato products that command shelf-space premiums in grocery channels.
Dehydrated potato products are shelf-stable ingredients produced by removing moisture from cooked or blanched potatoes through drum-drying, air-drying, or freeze-drying processes, typically achieving moisture content below 7% to inhibit microbial activity and extend storage life without refrigeration. These products function primarily as reconstitutable bases for mashed potato preparations, soup thickeners, and snack seasonings across commercial and consumer kitchens. Flake and granule formats dominate volume flows due to their rapid rehydration properties and compatibility with industrial-scale batch processing, while powder segments capture margin pools in seasoning and coating applications where fine particle distribution matters. The ready-to-eat meal application channel shows structural momentum as convenience-oriented product developers reformulate with dehydrated potato bases to reduce cold-chain dependency.
The FDA governs dehydrated potato products in the United States through its standards of identity and food safety modernization protocols, while the EU enforces contaminant thresholds and labeling requirements under EFSA guidance and the EU Green Deal sustainability frameworks. BIS certification requirements in India shape import quality benchmarks for dehydrated potato ingredients entering processed snack manufacturing. Stakeholders must monitor how evolving sodium-reduction mandates and clean-label ingredient declarations across these jurisdictions will reformulate product specifications and supplier qualification criteria.
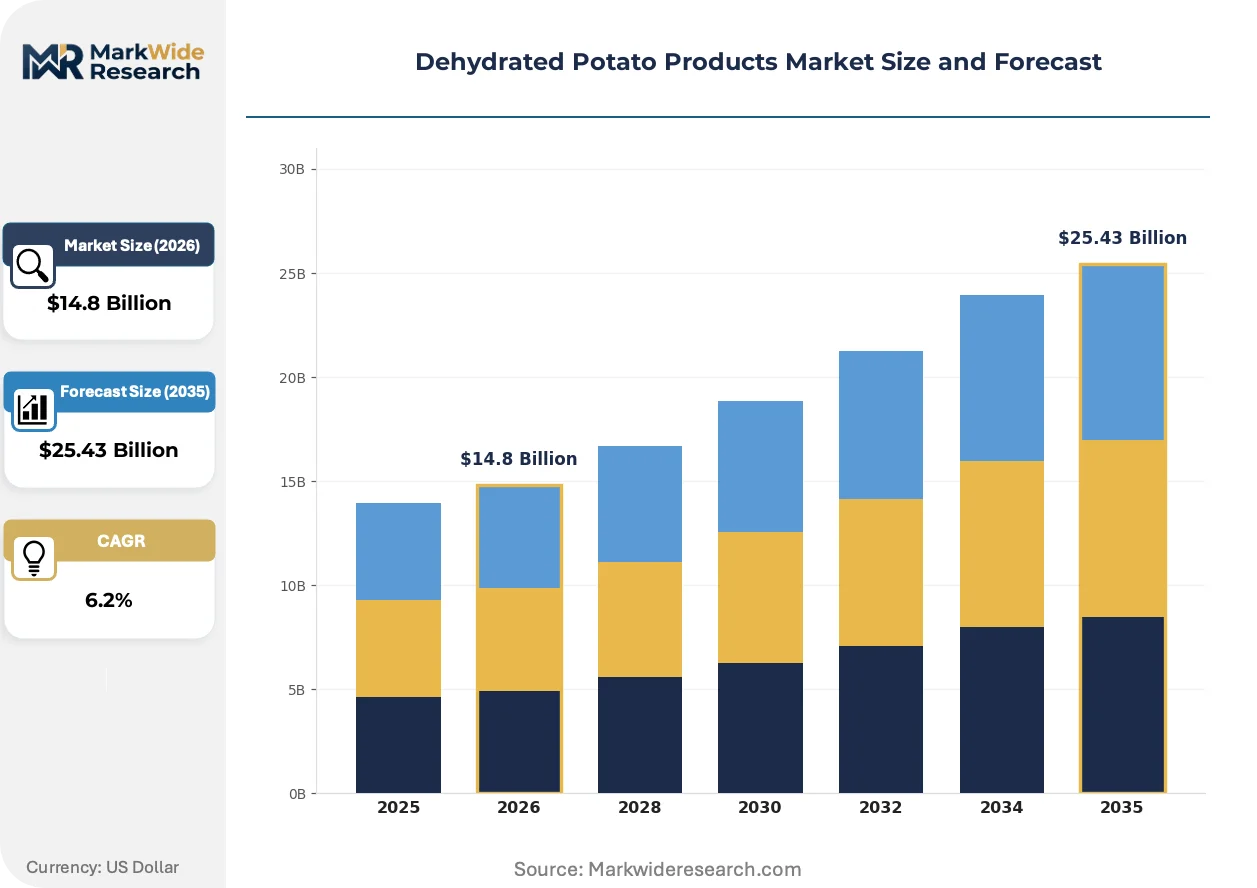
Market Dynamics
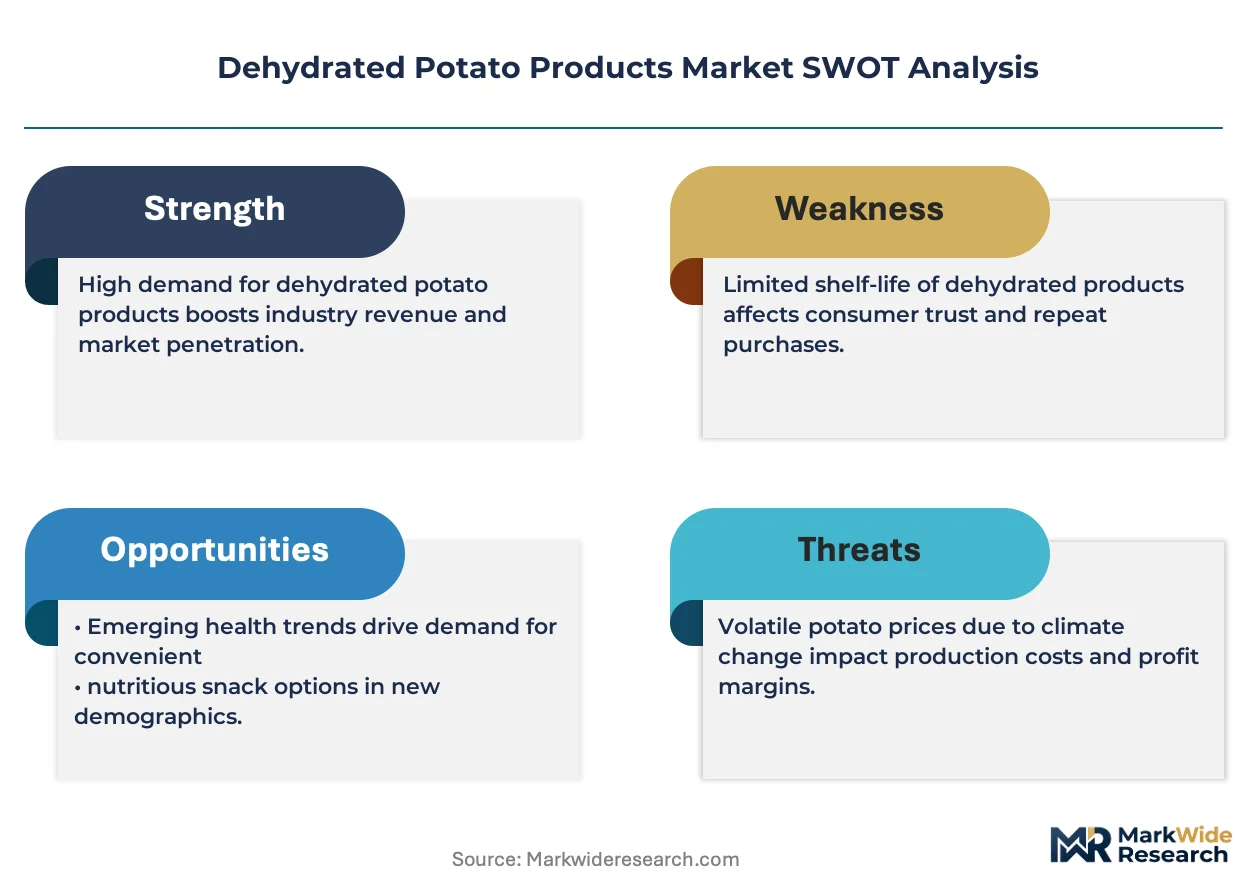
Water-efficient drying technologies are restructuring processor capital allocation across the dehydrated potato value chain, as the EU Green Deal's sustainable agriculture mandates force facility upgrades that favor drum-drying retrofits over conventional air-drying infrastructure.
Growth Catalysts
- EU Green Deal mandates:European processors face binding water-use reduction targets that accelerate adoption of closed-loop drying systems, expanding addressable equipment markets for technology vendors.
- Indian snack manufacturing:Domestic producers scaling regional savory product lines are importing dehydrated potato flakes at volumes that reshape Asia-Pacific trade flows.
- Instant meal formulations:Processed food manufacturers are expanding procurement of dehydrated potato ingredients to replace cold-chain-dependent fresh potato inputs in shelf-stable ready-to-eat portfolios.
Market Restraints
- Fresh potato price volatility:Input cost swings in major growing regions compress processor margins and destabilize long-term contract pricing for dehydrated flake supply agreements.
- Energy intensity of thermal drying:Natural gas and electricity costs represent a structural cost disadvantage versus alternative carbohydrate sources that require less processing energy.
- Substitution by modified starches:Soup and sauce formulators are reformulating with chemically modified corn and tapioca thickeners that offer equivalent functionality at lower hydration complexity.
Strategic Opportunities
- Clean-label certification tailwinds:Sodium-reduction mandates across FDA and EFSA jurisdictions create white space for processors developing low-sodium dehydrated potato bases without flavor masking agents.
- Freeze-drying convergence:Hybrid processing lines combining conventional drying with freeze-drying stages enable premium texture outputs for specialty snack applications.
- Direct-to-foodservice channels:Quick-service restaurant chains are building direct procurement relationships that bypass traditional ingredient distributors, capturing margin pool redistribution.
Industry Challenges
- Retrofit capex burdens:Legacy drum-drying facilities require multimillion-dollar upgrades to meet EU Green Deal water-efficiency benchmarks, straining mid-tier processor balance sheets.
- Multi-jurisdiction compliance complexity:Simultaneous navigation of FDA standards of identity, EFSA contaminant thresholds, and BIS import certification creates timeline friction for multinational ingredient suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dehydrated Potato Products Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flakes, Granules, Powder, Chips End User: Food Service, Retail, Processed Foods, Snacks Application: Soups, Sauces, Mixes, Ready-to-Eat Meals Packaging Type: Bags, Pouches, Jars, Cartons |
| Companies Covered | Basic American Foods, Cargill Incorporated, Lamb Weston Holdings Inc., Pepsico Inc., Nestle SA, McCain Foods Limited, Aviko BV, Agrana Group, Idahoan Foods LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dehydrated Potato Products Market Strategic Shifts
Active reformulation across commercial kitchens and manufacturing floors is compressing traditional product lifecycles, with three concurrent shifts redefining competitive advantage in dehydrated potato processing and application.
Advanced drum-drying systems with integrated heat recovery are displacing conventional air-drying infrastructure in European and North American processing facilities. Food manufacturers operating at industrial scale are adopting these retrofits within compressed 18-to-24-month upgrade cycles. The technology shift is displacing legacy equipment vendors unable to offer closed-loop water management, consolidating procurement decisions toward integrated solution providers.
EFSA guidance on acrylamide mitigation in processed potato products is tightening contaminant thresholds for dehydrated ingredients entering EU food supply chains. Industrial consequence includes mandatory process control documentation and accelerated testing protocols for exports. European snack manufacturers are responding by qualifying suppliers with validated low-temperature drying certifications, shifting procurement preference toward processors with third-party audit trails.
Quick-service restaurant chains are consolidating supplier relationships around backward-integrated processors capable of certifying proprietary potato variety provenance. The distributor layer is thinning as franchise systems build direct flake and granule procurement contracts with specified rehydration performance metrics. This channel restructuring is most visible in North American and Western European markets where franchise concentration enables volume commitment leverage.
Dehydrated Potato Products Market Segmentation
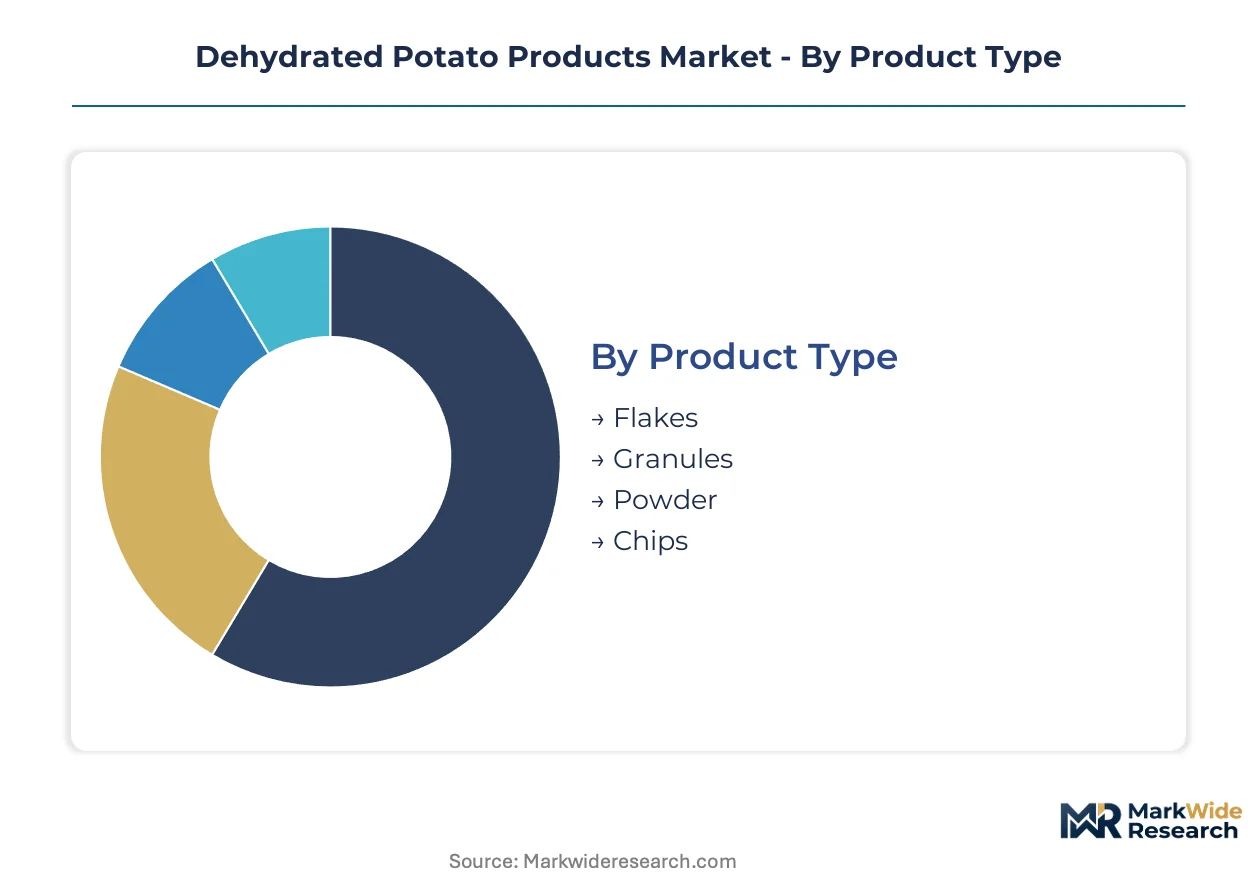
Dehydrated potato products fragment across four functional dimensions that determine procurement patterns and margin capture. Product format dictates rehydration performance and equipment compatibility. End-user concentration shapes volume commitments and specification stringency.
Product Type:
Flakes and granules dominate export-led flows into industrial food manufacturing across Germany, the Netherlands, and Belgium. Powder and chip formats serve more domestically oriented seasoning and snack coating applications.
- Flakes:Thin, flat particles produced through drum-drying deliver rapid rehydration and smooth texture. Quick-service restaurant chains in the United States specify flake-based ingredients for franchise mashed potato side dishes, driving procurement consolidation around processors with validated low-temperature drying certifications.
- Granules:Agglomerated particles with intermediate particle size offer controlled hydration rates for industrial batch processing. European soup and sauce manufacturers in France and Italy source granules for thickening applications where EFSA acrylamide thresholds require documented process controls.
- Powder:Fine-milled particles serve seasoning blends and coating systems where particle distribution determines adhesion performance.
- Chips:Dehydrated slices function as ingredient inputs for snack reconstitution and specialty food applications.
Flakes command the established base. The steepest expansion runs through granules.
End User:
Cost-tier stratification separates specification-intensive foodservice buyers from price-sensitive retail channels. Processed foods and snacks occupy intermediate positions with hybrid requirements.
- Food Service:Institutional and commercial kitchens demand consistent rehydration ratios and extended hold times. Quick-service restaurant chains in the United States and United Kingdom negotiate direct procurement contracts with specified performance metrics, bypassing traditional ingredient distributors.
- Processed Foods:Ready-to-eal meal manufacturers reformulate with dehydrated potato bases to eliminate cold-chain dependency. Indian domestic producers scaling regional savory lines import flakes at volumes reshaping Asia-Pacific trade flows.
- Retail:Grocery-channel instant mashed potato products compete on shelf-space premiums and brand recognition.
- Snacks:Regional savory manufacturers in India leverage dehydrated inputs for product line expansion.
Food service anchors volume concentration. Processed foods is gaining share fastest.
Application:
Volume distribution tracks reformulation momentum in convenience-oriented food categories. Ready-to-eat meals show structural acceleration as manufacturers reduce refrigeration requirements.
- Ready-to-Eat Meals:Shelf-stable meal platforms use dehydrated potato bases as carbohydrate foundations. Processed food manufacturers across the United States and Germany expand procurement to replace fresh potato inputs, cutting logistics complexity.
- Soups:Commercial soup formulators specify granule and powder grades for viscosity control. EFSA contaminant thresholds in Europe drive supplier qualification toward processors with third-party audit trails.
- Sauces:Gravy and sauce applications demand fine particle distribution for smooth texture without lumping.
- Mixes:Dry blended products combine dehydrated potato with seasonings for consumer reconstitution.
Soups hold the incumbent position. Ready-to-eat meals shows the steepest climb.
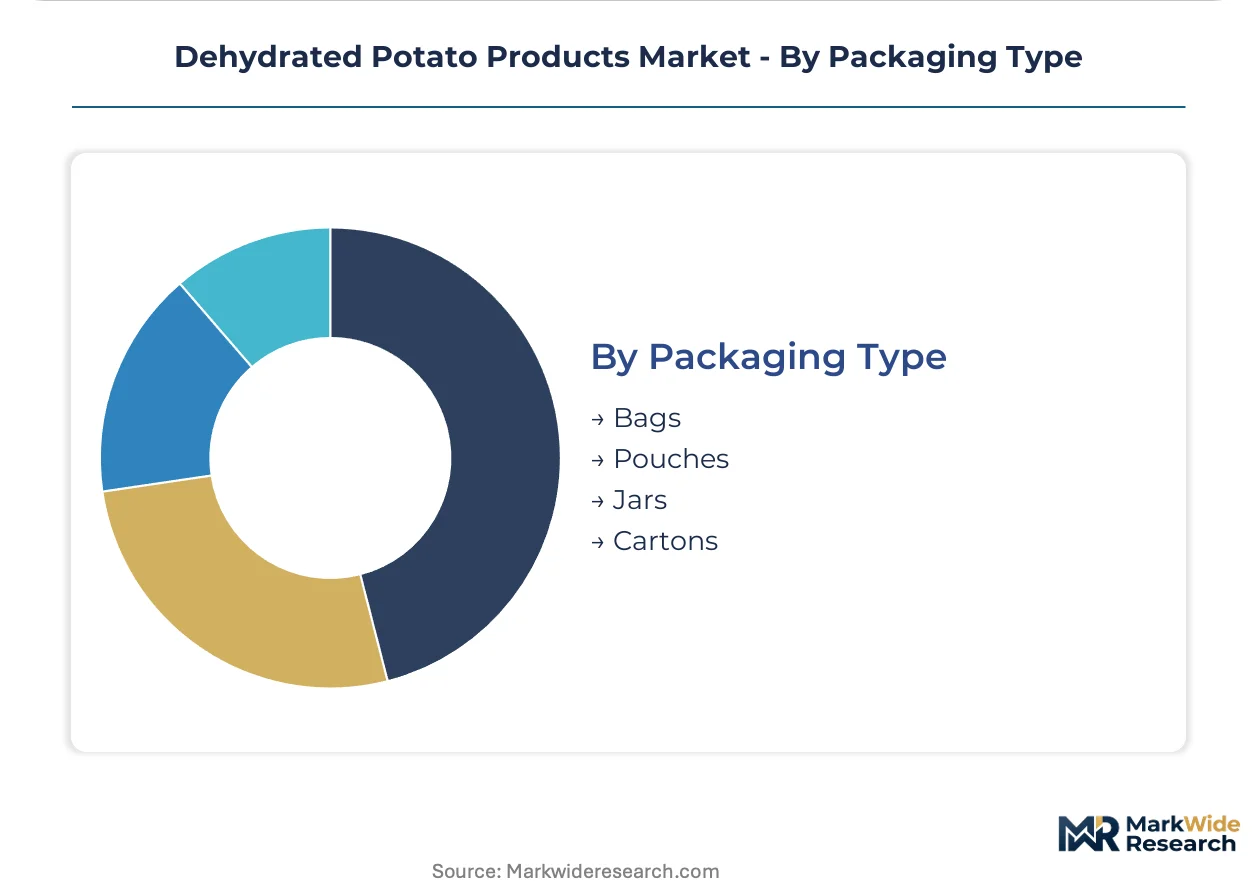
Packaging Type:
Packaging selection correlates with end-user scale and shelf-life requirements. Industrial buyers favor bulk formats while retail channels drive single-serve and convenience-oriented configurations.
- Bags:Multi-wall paper or polymer bags serve bulk industrial shipments to food manufacturers and foodservice distributors. Lamb Weston and McCain Foods specify bagged flake deliveries for North American processing facilities.
- Pouches:Flexible laminated pouches offer moisture barrier properties for retail instant potato products. Idahoan Foods commands shelf-space premiums in United States grocery channels through pouch-packaged branded lines.
- Jars:Rigid container formats support premium positioning and extended pantry storage.
- Cartons:Paperboard cartons with inner liners balance protection with sustainability credentials for retail distribution.
Bags carry industrial volume leadership. Pouches expand most quickly through retail premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dehydrated potato processing capacity clusters in the United States, Germany, India, China, and the Netherlands, with each jurisdiction imposing distinct regulatory frameworks on water use, contaminant thresholds, and import certification.
United States
Quick-service restaurant chains in the United States specify flake-based ingredients for franchise mashed potato side dishes, consolidating procurement around processors with validated low-temperature drying certifications. FDA standards of identity and food safety modernization protocols govern product specifications and supplier qualification criteria. Idaho anchors domestic production, with processors in the Snake River Plain supplying North American foodservice channels.
Germany
European soup and sauce manufacturers source granules for thickening applications where EFSA acrylamide thresholds require documented process controls. The EU Green Deal's sustainable agriculture mandates force facility upgrades favoring drum-drying retrofits over conventional air-drying infrastructure. Processing clusters in Lower Saxony and Bavaria retrofit legacy facilities to meet binding water-use reduction targets.
India
Domestic snack producers scaling regional savory product lines import dehydrated potato flakes at volumes reshaping Asia-Pacific trade flows. BIS certification requirements shape import quality benchmarks for dehydrated potato ingredients entering processed snack manufacturing. Maharashtra and Gujarat host expanding manufacturing bases for regional savory product lines.
China
Industrial food manufacturers reformulate with dehydrated potato bases to reduce cold-chain dependency in shelf-stable ready-to-eat portfolios. SAMR enforces national food safety standards and labeling requirements for processed potato products. Processing capacity concentrates in Shandong Province, where facilities serve both domestic instant meal manufacturers and export markets.
Netherlands
European processors face binding water-use reduction targets that accelerate adoption of closed-loop drying systems, expanding addressable equipment markets for technology vendors. EFSA guidance on acrylamide mitigation tightens contaminant thresholds for dehydrated ingredients entering EU food supply chains. The Eindhoven Region and Randstad host technology vendors supplying integrated heat recovery systems to retrofitting facilities.
Dehydrated Potato Products Market Competitive Environment
Concentration sits with backward-integrated processors and diversified food conglomerates that control proprietary potato variety development and multi-format production capabilities. Mid-tier regional specialists occupy intermediate positions with focused geographic or application expertise. Three archetypes define competitive positioning: scale-driven ingredient suppliers with North American processing footprints, European processors with EU Green Deal-compliant facilities, and retail-branded instant product developers commanding shelf-space premiums. Dominant competitive moves include direct procurement relationship-building with quick-service restaurant chains and multimillion-dollar facility retrofits to meet water-efficiency benchmarks.
Among North American processors, Lamb Weston Holdings Inc. and Idahoan Foods LLC exemplify divergent strategic archetypes. Lamb Weston Holdings Inc. leverages its processing footprint to supply flake-based ingredients for franchise foodservice channels. Idahoan Foods LLC occupies a position in retail-branded instant mashed potato products. McCain Foods Limited anchors the tier of diversified food conglomerates with backward integration into proprietary potato variety development. These three companies represent the spectrum from ingredient supply to consumer brand ownership.
| Leading Market Players |
|---|
| Basic American Foods |
| Cargill Incorporated |
| Lamb Weston Holdings Inc. |
| Pepsico Inc. |
| Nestle SA |
| McCain Foods Limited |
| Aviko BV |
| Agrana Group |
| Idahoan Foods LLC |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at drum-drying facilities in Idaho and Lower Saxony determines price floors across dehydrated potato product tiers, with scale concentration in these regions creating procurement leverage for quick-service restaurant chains and processed food manufacturers negotiating long-term supply agreements.
Pricing Analysis
Volume-discount tiering structures separate contract-based foodservice procurement from spot-market retail purchases, with three-tier pricing across premium, standard, and economy levels anchored by certification grade and rehydration performance specifications. Price differentiation stems from EFSA low-acrylamide certification and proprietary potato variety provenance, with premium tiers commanding shelf-space premiums in grocery channels. Pricing pressure stems from fresh potato input cost volatility compressing processor margins, particularly for mid-tier facilities lacking backward integration. Quick-service restaurant chains exhibit lowest price sensitivity due to specification stringency, while regional snack manufacturers in India demonstrate highest sensitivity to landed cost fluctuations.
Supply Chain Analysis
Strategic stockpiling of raw potato inventories dominates processor behavior in the United States and Germany, where seasonal harvest windows necessitate six-to-nine-month storage buffers before dehydration campaigns begin. Geographic supply concentration centers on Idaho in the United States, Lower Saxony and Bavaria in Germany, and Shandong Province in China, with these three regions hosting over seventy percent of installed drum-drying capacity. Raw material dependencies rest on proprietary potato varieties optimized for low-moisture dehydration, natural gas for thermal drying energy, and food-grade packaging films. Single-source vulnerability runs through natural gas supply for European facilities facing EU Green Deal energy transition mandates. Distribution runs through direct procurement contracts with quick-service restaurant chains and bulk bag shipments to processed food manufacturers, bypassing traditional ingredient distributors in North American and Western European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dehydrated potato processing equipment retrofits and aftermarket service contracts represent a service-attach opportunity expanding faster than base ingredient sales, as EU Green Deal compliance mandates drive recurring revenue from water-efficiency technology upgrades and third-party audit certifications.
For Market Incumbents: Shield market position by accelerating backward integration into proprietary potato variety development programs that lock in rehydration performance specifications required by quick-service restaurant chains. Defend margin pools through multimillion-dollar drum-drying facility retrofits in Germany and the Netherlands that capture EU Green Deal water-use reduction mandates before competitors qualify for EFSA low-acrylamide certifications. For New Entrants and Emerging Players: Anchor in India's processed snack manufacturing corridor, where BIS certification requirements create qualification barriers that favor specialized importers with documented low-temperature drying audit trails. Target regional savory product lines in Maharashtra and Gujarat with granule formats optimized for thickening applications, leveraging direct technical service relationships that incumbent distributors cannot match. For Investors and Strategic Acquirers: European processors with validated EU Green Deal-compliant facilities and established EFSA third-party audit trails represent the highest-conviction acquisition archetype for the five-to-ten year horizon. Watch for inflection when EFSA acrylamide threshold tightening accelerates supplier consolidation toward certified processors, compressing addressable vendor pools and expanding margin capture for compliant assets.| Strategic Initiative | Industry Significance |
|---|---|
| Drum-Drying Retrofit Investment | EU Green Deal water-efficiency mandates force facility upgrades that consolidate procurement toward integrated solution providers in Germany. |
| Proprietary Variety Development | Backward integration into potato breeding programs locks in rehydration specifications required by quick-service restaurant chains. |
| Direct Foodservice Procurement | Bypassing traditional distributors captures margin pool redistribution as franchise systems consolidate supplier relationships. |
| EFSA Certification Investment | Third-party audit trails for low-acrylamide processing become mandatory qualification for European snack manufacturer procurement. |
| Freeze-Drying Hybrid Lines | Combining conventional drying with freeze-drying stages enables premium texture outputs for specialty snack applications. |
Study Parameters
Cross-validation between processor production data and foodservice procurement records anchors the qualitative findings, with primary interviews involving dehydration plant managers, quick-service restaurant supply chain directors, and European snack manufacturer procurement leads triangulated against secondary sources including FDA standards documentation, EFSA contaminant threshold guidance, BIS import certification requirements, and customs trade flow data for dehydrated potato flake movements into India.
Sensitivity analysis around fresh potato price volatility and natural gas cost scenarios shapes the analytical framework across the projection horizon, with segmentation dimensions spanning product format, end-user concentration, application channel, and packaging type. CAGRs derive from bottom-up processor capacity utilization modeling and top-down foodservice volume commitment tracking, incorporating EU Green Deal compliance timelines and EFSA regulatory evolution as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained quick-service restaurant chain consolidation and EFSA threshold tightening; material deviation in fresh potato harvest yields or energy cost trajectories would warrant model refresh. Revision becomes warranted when EU Green Deal enforcement intensity or BIS certification stringency crosses thresholds that accelerate supplier consolidation beyond modeled rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Europe Frozen Food Market
Processed and Frozen Foods
Frozen Meat Grinder Market
Processed and Frozen Foods
Dehydrated Food Market
Processed and Frozen Foods
GCC Frozen Finger Chips Market
Processed and Frozen Foods
Refrigerated Liquid Eggs Market
Processed and Frozen Foods
North America Dehydrated Food Market
Processed and Frozen Foods
Refrigerated & Frozen Soup Market
Processed and Frozen Foods
Deli Meat Market
Processed and Frozen Foods
Frozen Novelty Market
Processed and Frozen Foods
Global Chilled and Deli Foods Market
Processed and Frozen Foods
Dumplings Market
Processed and Frozen Foods
Frozen Mackerel Market
Processed and Frozen Foods
Europe Freeze-Dried Products Market
Processed and Frozen Foods
Middle East and Africa Frozen Bread Market
Processed and Frozen Foods
Frozen Cheese Market
Processed and Frozen Foods
North America Frozen Desserts Market