
 Germany Frozen Snack Market | 2026-2036
Germany Frozen Snack Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Frozen Snack Market Foresight
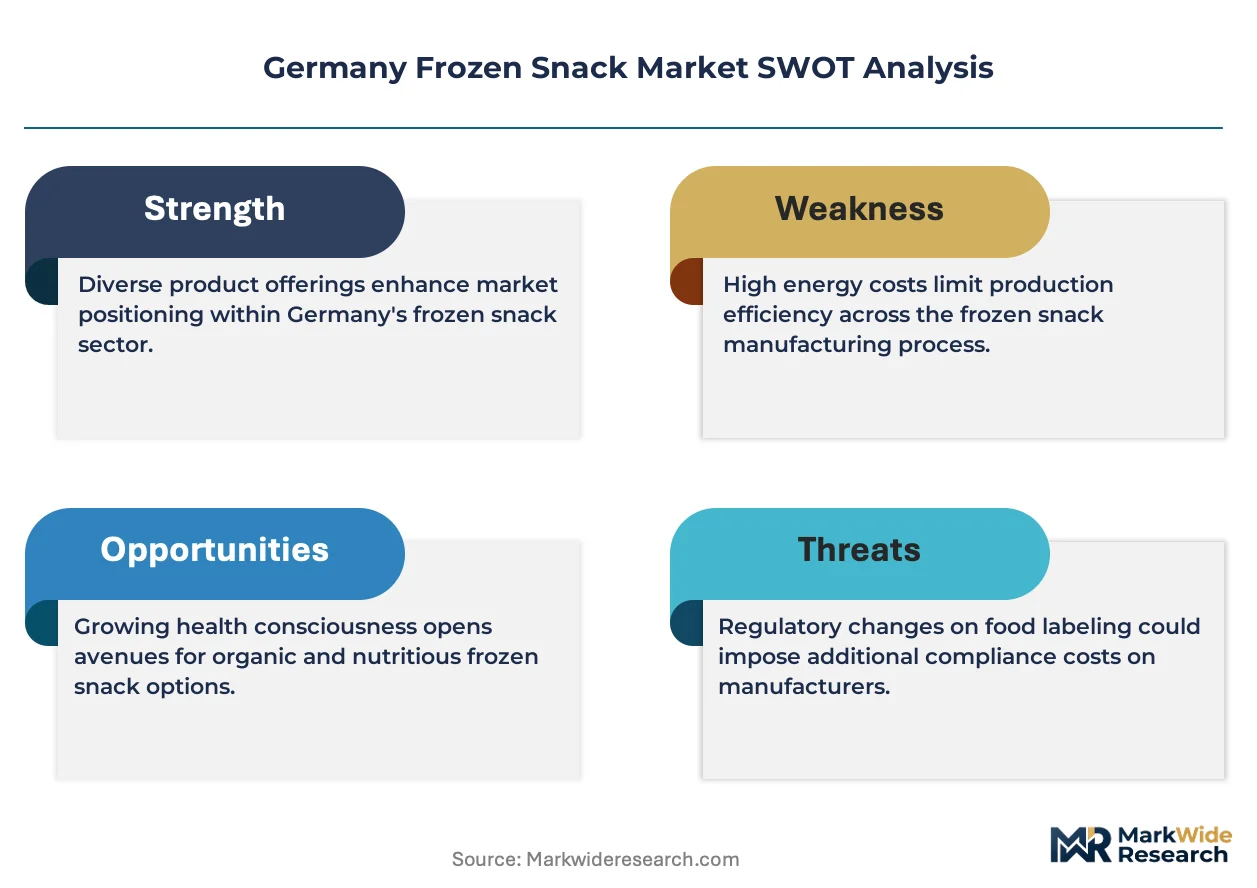
Premium clean-label specifications is redrawing competitive boundaries in Germany's frozen snack sector. Dr. August Oetker KG leverages its heritage brand equity and deep retail penetration to dominate the frozen bakery snacks tier. Frosta Aktiengesellschaft anchors its position through transparent sourcing protocols and aggressive reformulation of its frozen potato and seafood ranges. McCain Foods Limited competes via manufacturing scale and its established supply relationships with German foodservice operators.
Germany frozen snacks comprise pre-cooked, flash-frozen food items—typically stored below minus 18 degrees Celsius—designed for rapid reheating via oven, air fryer, or microwave in consumer and commercial settings. Frozen potato snacks and frozen meat snacks lead volume throughput, though frozen vegetarian snacks capture the fastest growth trajectory as plant-based protein formulations improve textural fidelity. Margin pools concentrate in the specialty food stores and online retail channels, where direct-to-consumer pricing power offsets higher last-mile logistics costs.
BfR (German Federal Institute for Risk Assessment) guidelines on acrylamide mitigation and the EU's F-Gas Regulation on refrigeration emissions shape product standards and cold-chain infrastructure investments. EFSA nutritional labeling requirements and Germany's national packaging ordinance (VerpackG) enforce transparency and recyclability mandates that elevate compliance costs for smaller entrants. Stakeholders must monitor evolving EU deforestation-free supply chain rules and their cascading impact on frozen meat and seafood sourcing decisions.
Market Dynamics
The EU Green Deal's packaging sustainability mandates are forcing frozen snack manufacturers to abandon multi-layer plastic films and transition to mono-material or fiber-based alternatives, reshaping formulation priorities and supplier relationships across Germany's cold-chain infrastructure.
Growth Catalysts
- Convenience-seeking urban households:Dual-income families in Berlin, Munich, and Hamburg prioritize time-saving meal solutions, expanding the addressable base for flash-frozen potato snacks and ready-to-heat bakery items.
- VerpackG recyclability mandates:Germany's national packaging ordinance creates compliance-driven demand for reformulated packaging substrates that qualify for dual-system recycling streams.
- Air fryer penetration:Rapid adoption of countertop convection appliances among German consumers is shifting product development toward crisper-optimized coatings and reduced-oil formulations.
Market Restraints
- Acrylamide mitigation costs:BfR guidelines on reducing Maillard reaction byproducts in starchy frozen foods require process modifications that elevate per-unit production expenses.
- F-Gas refrigeration constraints:The EU F-Gas Regulation phases down hydrofluorocarbon use in cold storage, forcing capital-intensive retrofits of distribution centers serving the frozen snack trade.
- Plant-based textural limitations:Current extrusion technologies cannot replicate the bite resistance and moisture retention of animal proteins in frozen meat snack analogs, constraining category expansion.
Strategic Opportunities
- Direct-to-consumer frozen subscription:Last-mile insulated delivery networks enable brands to bypass traditional retail slotting fees and capture full margin on premium clean-label assortments.
- Rhine-Ruhr industrial cluster proximity:Dense logistics infrastructure around Dortmund and Düsseldorf supports same-day frozen fulfillment to 15 million consumers within a 150-kilometer radius.
- EU deforestation-free supply chain rules:Early compliance with traceability mandates for palm oil and soy derivatives positions German manufacturers for preferential sourcing relationships with sustainability-screened retailers.
Industry Challenges
- Refrigerated last-mile talent scarcity:Qualified drivers with multi-temperature zone certification command wage premiums that compress margins on home-delivery frozen snack orders.
- Legacy ERP integration with traceability systems:Mid-tier manufacturers struggle to retrofit batch-tracking software that satisfies both BfR documentation requirements and retail partner data exchange protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Frozen Snack Market |
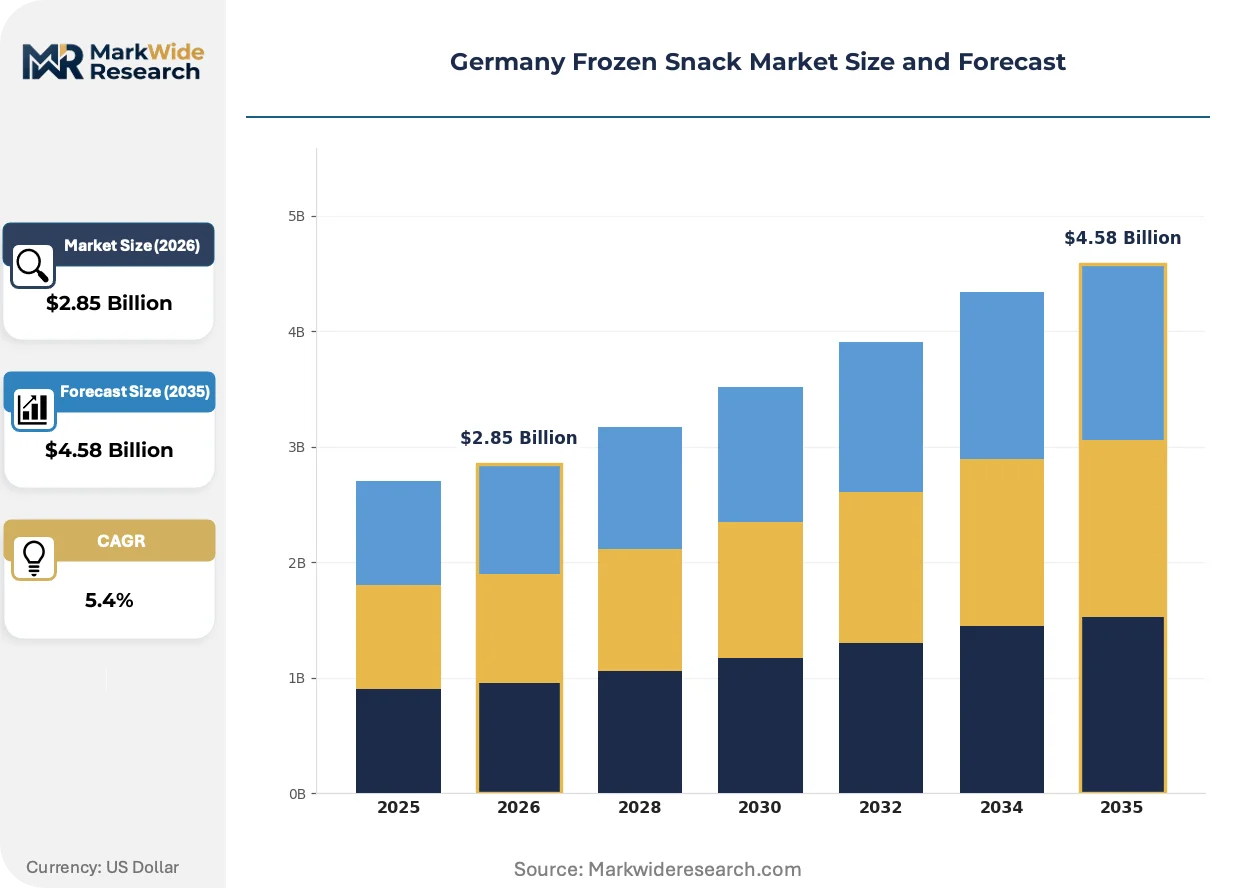
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.58 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Potato Snacks, Frozen Seafood Snacks, Frozen Vegetarian Snacks, Frozen Meat Snacks, Frozen Bakery Snacks Distribution Channel: Supermarkets & Hypermarkets, Convenience Stores, Online Retail, Specialty Food Stores, Foodservice Outlets Application: Quick Meals, Party Snacks, Children’s Snacks, On-the-Go Consumption, Appetizers Customer Type: Households, Catering Services, Retailers, Vending Operators, Institutional Buyers |
| Companies Covered | Dr. August Oetker KG, Südzucker AG, Nestle SA, Frosta Aktiengesellschaft, Nomad Foods, McCain Foods Limited, General Mills Inc, Fonterra Co-operative Group, Agrarfrost Holding GmbH and Co. KG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Frozen Snack Market Shifts & Advancements
Active packaging technologies and reformulation science are converging to extend shelf stability while eliminating synthetic preservatives, altering how German frozen snack producers compete on clean-label credentials.
Pulse-based protein isolates derived from German-grown fava beans and peas are supplanting imported soy concentrates in vegetarian snack formulations. Domestic foodservice operators and retail private-label buyers are accelerating adoption to shorten supply chains and reduce Scope 3 emissions. This ingredient pivot is compressing reliance on South American commodity markets while creating new contracting relationships with Rhineland agricultural cooperatives.
The EU F-Gas Regulation's phasedown schedule is compelling cold-store operators to deploy transcritical CO2 refrigeration systems in place of hydrofluorocarbon-based equipment. Industrial consequence includes higher upfront capital requirements but lower lifetime energy consumption and regulatory compliance risk. Frozen snack distributors in Bavaria and Baden-Württemberg are most affected, with several operators accelerating facility upgrades ahead of 2027 checkpoint deadlines.
Single-person household formation in German metropolitan centers is fragmenting traditional family-pack purchasing patterns. Convenience stores and petrol station forecourts are capturing snack occasions previously served by weekly supermarket stock-ups, displacing volume-driven retail strategies with occasion-based micro-portion formats. This shift is most visible in Berlin's dense urban districts, where 250-gram frozen snack packs now outsede 750-gram family configurations in velocity metrics.
Germany Frozen Snack Market Segmentation
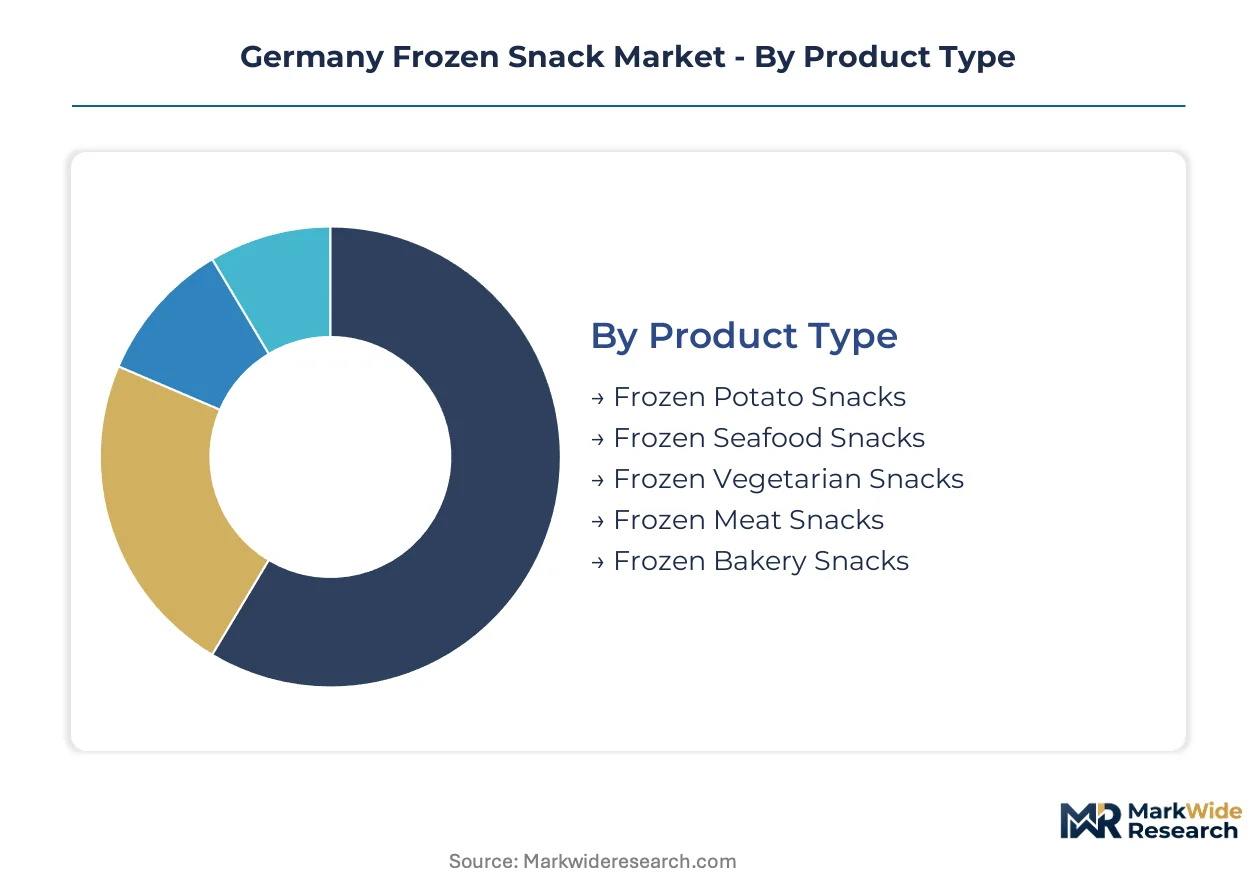
German frozen snack manufacturers configure production lines around distinct demand pockets. Each segmentation dimension reveals divergent margin structures and cold-chain requirements.
Product Type:
Frozen potato and seafood variants anchor domestic production volumes, while plant-based and meat formats serve export corridors into neighboring EU markets.
- Frozen Potato Snacks:Pre-fried and flash-frozen potato wedges, fries, and croquettes formulated for air-fryer compatibility. Berlin and Hamburg households drive volume through weekly supermarket stock-ups, though BfR acrylamide mitigation rules elevate processing costs.
- Frozen Vegetarian Snacks:Pulse-protein extrusions and vegetable-based bites targeting flexitarian consumers. Demand concentrates in Munich's premium retail channels as Rhineland agricultural cooperatives scale fava bean and pea isolate supply.
- Frozen Seafood Snacks:Breaded and unbreaded marine products from certified sustainable fisheries.
- Frozen Meat Snacks:Breaded poultry, pork, and beef items with extended shelf stability.
- Frozen Bakery Snacks:Pre-proofed and par-baked items for rapid finishing.
Frozen potato snacks hold the largest share; momentum sits with frozen vegetarian snacks.
Distribution Channel:
Channel economics split between high-volume retail partnerships and emerging direct-to-consumer routes with divergent logistics cost profiles.
- Supermarkets & Hypermarkets:Full-range frozen aisles with dedicated minus-18°C infrastructure. Edeka and Rewe systems in North Rhine-Westphalia and Bavaria command slotting fees that squeeze mid-tier brand margins.
- Online Retail:Insulated last-mile delivery of premium clean-label assortments. Same-day networks around Düsseldorf and Dortmund enable subscription models that bypass traditional retail gatekeepers.
- Convenience Stores:Micro-portion formats for impulse occasions in urban transit corridors.
- Specialty Food Stores:Curated selections with provenance documentation for discerning buyers.
- Foodservice Outlets:Bulk formats for restaurant and catering reheating protocols.
Supermarkets and hypermarkets dominate throughput; online retail climbs fastest.
Application:
Usage occasions fragment along household composition lines, with single-person urban dwellings reshaping pack size and preparation requirements.
- Quick Meals:Complete protein-carbohydrate combinations requiring single-appliance preparation. Dual-income households in Frankfurt and Stuttgart prioritize these for weekday dinner substitution.
- On-the-Go Consumption:Portable formats designed for workplace microwave or air-fryer reheating. Berlin's dense transit corridors and co-working spaces sustain velocity for individual-portion SKUs.
- Party Snacks:Shareable formats for social gatherings with extended holding tolerance.
- Children's Snacks:Portion-controlled items with simplified ingredient declarations.
- Appetizers:Elevated presentation formats for pre-meal service.
Quick meals command the greatest volume; on-the-go consumption expands most quickly.
Customer Type:
Buyer sophistication varies sharply, with institutional procurement teams imposing traceability standards that exceed household purchasing criteria.
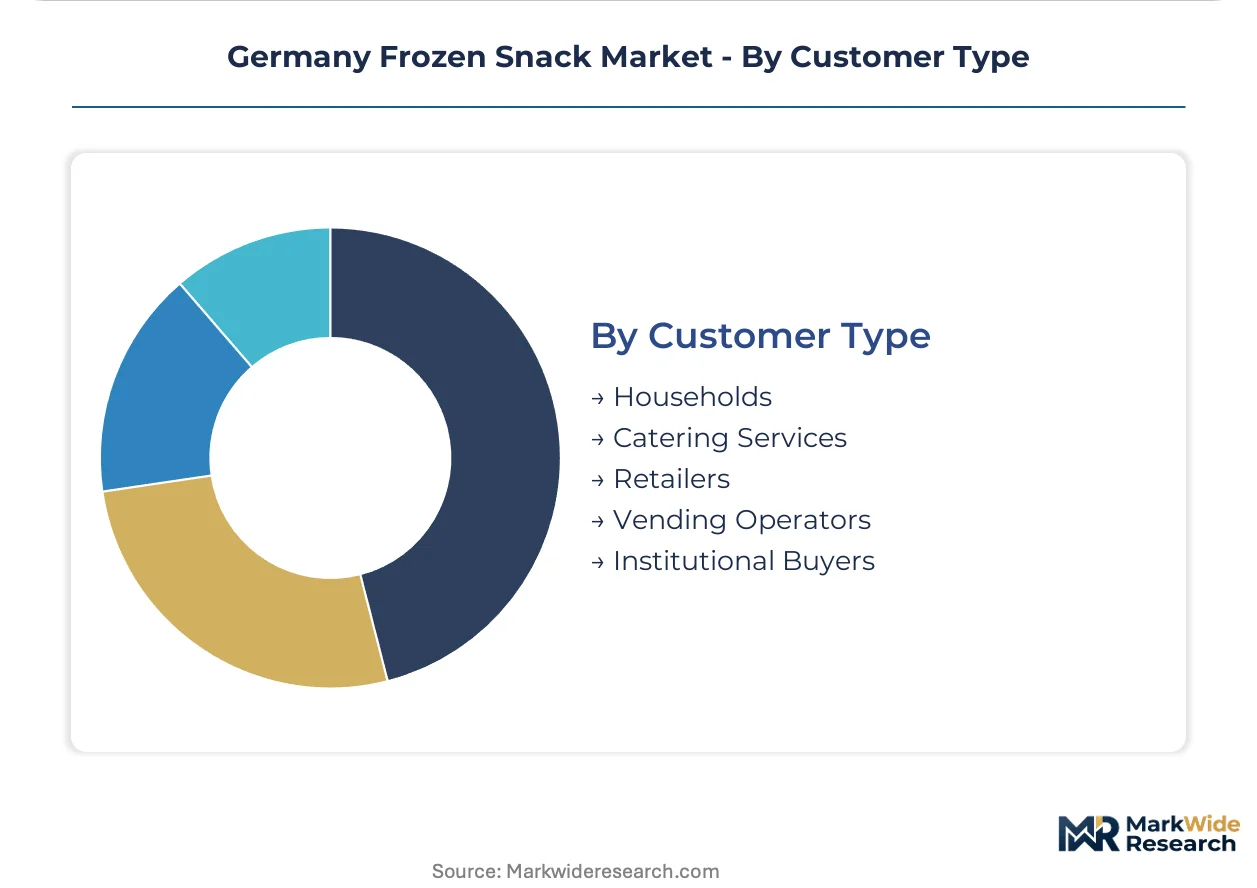
- Households:End consumers purchasing through retail or direct channels. Urban single-person formations in Hamburg and Cologne drive demand for 250-gram packs over traditional family configurations.
- Catering Services:Event and contract food operators with batch-prep requirements. VerpackG compliance documentation and BfR batch records are mandatory for contract eligibility.
- Retailers:Private-label buyers and category managers.
- Vending Operators:Automated retail channels with limited refrigeration footprints.
- Institutional Buyers:Healthcare and education facilities with nutritional procurement protocols.
Households represent the largest addressable base; catering services demonstrate the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban consumers in Hamburg and Cologne demonstrate the highest price elasticity for frozen snacks, while Munich's premium retail channels absorb cost increases with minimal volume erosion. This demand-elasticity contrast shapes regional distribution strategies and margin recovery timelines across German metropolitan corridors.
Bavaria
Dual-income households in Munich and Nuremberg prioritize time-saving meal solutions, expanding velocity for flash-frozen potato snacks and ready-to-heat bakery items. The EU F-Gas Regulation drives transcritical CO2 refrigeration retrofits in cold-storage facilities serving Upper Bavaria. Industrial clusters around Ingolstadt and Augsburg host distribution centers accelerating facility upgrades ahead of 2027 checkpoint deadlines.
North Rhine-Westphalia
Dense logistics infrastructure around Dortmund and Düsseldorf supports same-day frozen fulfillment to 15 million consumers within a 150-kilometer radius. VerpackG recyclability mandates create compliance-driven demand for reformulated packaging substrates qualifying for dual-system recycling streams. The Rhine-Ruhr industrial cluster anchors cold-chain investments as distributors retrofit minus-18°C infrastructure for mono-material transitions.
Baden-Württemberg
Stuttgart's automotive workforce sustains demand for quick-meal frozen formats designed for single-appliance preparation. BfR guidelines on acrylamide mitigation elevate processing costs for starchy frozen foods manufactured in the region. Foodservice operators in Karlsruhe and Mannheim impose traceability standards exceeding household purchasing criteria for frozen meat and seafood sourcing.
Berlin-Brandenburg
Single-person household formation fragments traditional family-pack purchasing patterns across Berlin's dense urban districts. EFSA nutritional labeling requirements enforce transparency mandates that elevate compliance costs for direct-to-consumer subscription models. Convenience stores and petrol station forecourts in Potsdam and Cottbus capture snack occasions previously served by weekly supermarket stock-ups.
Hamburg
Port-city logistics advantages position Hamburg as a gateway for frozen seafood imports from certified sustainable fisheries. Germany's national packaging ordinance drives material transitions away from multi-layer plastic films toward fiber-based alternatives. Urban consumers in the metropolitan area demonstrate highest sensitivity to price increases, compressing margins on premium clean-label assortments.
Germany Frozen Snack Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Germany's frozen snack sector. Heritage conglomerates with deep retail penetration dominate volume throughput, while agile reformulation specialists capture premium-tier margin pools. The market structure consolidates around three strategic archetypes: diversified food conglomerates leveraging manufacturing scale, regional specialists emphasizing transparent sourcing protocols, and private-label suppliers serving discounter channels. Dominant competitive moves include portfolio diversification into plant-based formats and strategic partnerships with Rhineland agricultural cooperatives for domestic protein sourcing.
Within the heritage-brand tier, Dr. August Oetker KG occupies a position exemplifying deep retail penetration and frozen bakery snack dominance. Frosta Aktiengesellschaft represents the transparent-sourcing archetype through aggressive reformulation of frozen potato and seafood ranges. McCain Foods Limited anchors the scale-driven segment, competing via manufacturing infrastructure and established supply relationships with German foodservice operators.
| Leading Market Players |
|---|
| Dr. August Oetker KG |
| Südzucker AG |
| Nestle SA |
| Frosta Aktiengesellschaft |
| Nomad Foods |
| McCain Foods Limited |
| General Mills Inc |
| Fonterra Co-operative Group |
| Agrarfrost Holding GmbH and Co. KG |
| Others |
Supply & Pricing Matrix
Ninety-day frozen inventory cycles in German cold-storage facilities concentrate pricing power among operators with transcritical CO2 infrastructure already deployed. This lead-time compression favors incumbents who can absorb VerpackG compliance costs without passing through retail slotting fee increases, while smaller players face margin erosion from dual-system recycling mandates and F-Gas retrofit capital requirements.
Pricing Analysis
After-sales revenue from direct-to-consumer subscription contracts drives lifetime value for premium clean-label assortments. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and air-fryer optimization intensity. Cost compression in the economy tier intensifies because VerpackG material transitions elevate per-unit packaging expenses. Price sensitivity peaks among urban single-person households in Hamburg, while Munich's dual-income buyers absorb premium tier increases with minimal volume erosion.
Supply Chain Analysis
Rhineland agricultural cooperatives anchor a chokepoint for domestic fava bean and pea isolate supply that underwrites plant-based snack reformulation. Raw material sourcing draws from Dutch potato processors, Norwegian certified fisheries, and French poultry suppliers. Single-source vulnerability concentrates in South American soy concentrate dependencies for legacy vegetarian formulations. Distribution runs through Edeka and Rewe systems in North Rhine-Westphalia and Bavaria, with same-day insulated delivery networks emerging around Düsseldorf and Dortmund.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's frozen snack sector sits at a platform-economics inflection where direct-to-consumer subscription interoperability with retail loyalty programs will determine next-generation margin capture. Ecosystem consolidation around last-mile cold-chain data sharing is redrawing competitive boundaries.
For Market Incumbents: Shield market share by accelerating backward integration into Rhineland pulse-protein cultivation and securing exclusive contracting relationships with agricultural cooperatives. Prioritize ERP retrofit investments that satisfy both BfR batch-tracking requirements and retail partner data exchange protocols. Defensive capacity expansion in Bavaria and Baden-Württemberg cold-storage infrastructure will outpace F-Gas checkpoint deadlines.
For New Entrants and Emerging Players: Anchor in Berlin's convenience store and petrol station forecourt channels where 250-gram micro-portion velocity outpaces traditional family-pack configurations. Target underpenetrated direct-to-consumer subscription white space with clean-label assortments bypassing supermarket slotting fees. Go-to-market execution should emphasize air-fryer-optimized coatings and domestic sourcing credentials.
For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-premium consolidation play because EU deforestation-free supply chain compliance will disqualify non-compliant mid-tier manufacturers from retail distribution within the analysis window. Acquisition targets should demonstrate transparent sourcing protocols and existing transcritical CO2 refrigeration assets. Monitor BfR acrylamide guideline enforcement intensity as the signal indicating regulatory compliance cost acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Bypasses Edeka and Rewe slotting fees while capturing full margin on premium clean-label assortments. |
| Backward Integration into Domestic Pulse Protein | Shortens supply chains from South American soy markets to Rhineland agricultural cooperatives. |
| Transcritical CO2 Refrigeration Retrofit | Secures F-Gas Regulation compliance ahead of 2027 checkpoint deadlines in Bavaria facilities. |
| Air-Fryer-Optimized Coating Reformulation | Captures countertop convection appliance penetration among Berlin and Munich urban households. |
| VerpackG-Compliant Packaging Transition | Qualifies products for dual-system recycling streams under Germany's national packaging ordinance. |
Research Methodology
Cross-validation between primary interviews with frozen snack brand managers, cold-chain logistics directors, retail category buyers, and regulatory compliance officers anchors the qualitative findings. Secondary validation draws from BfR guideline publications, EFSA nutritional labeling databases, VerpackG implementation records, and EU F-Gas Regulation phasedown schedules. Bottom-up production capacity assessments and top-down retail velocity data triangulate market sizing.
Sensitivity analysis across product type, distribution channel, and regional demand density dimensions shapes the analytical framework over the projection horizon. CAGRs derive from segment-level volume trajectories weighted by air-fryer penetration rates and single-person household formation patterns. Forecast inputs include cold-storage capacity utilization in North Rhine-Westphalia and premium channel pricing elasticity in Munich metropolitan corridors.
Decision-makers should treat outputs as directional under sustained EU Green Deal packaging mandate enforcement; material deviation would warrant model refresh. Forecasts reflect assumptions regarding VerpackG compliance timelines and F-Gas retrofit capital availability. Practitioners should keep alternative scenarios live as BfR acrylamide mitigation rule enforcement intensity evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
North America Frozen Finger Chips Market
Processed and Frozen Foods
Middle East and Africa Ice Cream Market
Processed and Frozen Foods
Frozen Dumplings Market
Processed and Frozen Foods
Frozen Tart Shells Market
Processed and Frozen Foods
Global Chilled and Deli Foods Market
Processed and Frozen Foods
South America Freeze Dried Products Market
Processed and Frozen Foods
Frozen Potato Market
Processed and Frozen Foods
Asia Pacific Freeze Dried Product Market
Processed and Frozen Foods
IQF Food Products Market
Processed and Frozen Foods
Frozen-Cooked Ready Meals Market
Processed and Frozen Foods
Frozen Noodles and Rice Products Market
Processed and Frozen Foods
Middle East and Africa Frozen Food Market
Processed and Frozen Foods
Frozen Shrimp Market
Processed and Frozen Foods
Frozen Cheese Market
Processed and Frozen Foods
Frozen Processed Meat Market
Processed and Frozen Foods
Frozen Fruit Bars Market