
 Dehydrated Potato Market | 2026-2036
Dehydrated Potato Market Size, Share, and Industry Trends Forecast 2026-2036
Dehydrated Potato Market Intelligence
Spray-drying and freeze-drying process lines is fragmenting the capital-equipment landscape across potato processing facilities. McCain Foods Limited leverages backward integration into proprietary drying systems across its North American plants. Lamb Weston Holdings, Inc. sustains geographic dominance through concentrated operations in the Pacific Northwest. Idahoan Foods differentiates via retail-brand strength in instant mashed potato segments.
Dehydrated potato denotes potato solids reduced to moisture levels below 7 percent through thermal or sublimation methods, yielding shelf-stable ingredients for reconstitution in commercial kitchens and manufacturing lines. Flakes and granules occupy the largest volume positions due to their compatibility with mashed potato reconstitution and snack extrusion. Powder commands premium positioning within bakery and soup applications where particle uniformity affects hydration behavior. Chunks and slices serve foodservice channels requiring visible potato texture in finished dishes.
The FDA governs dehydrated potato labeling under 21 CFR standards, while USDA Grading Service establishes quality benchmarks for flake and granule products. EU REACH compliance and EFSA food-contact material rules constrain export-bound processors using specific drying-aid additives. Stakeholders must monitor evolving clean-label requirements and energy-cost trajectories in thermal processing to preserve margin structures across the value chain.
Market Dynamics
Energy-cost volatility in thermal processing is forcing capital redeployment across potato drying facilities, while clean-label mandates from FDA and EFSA compress formulation flexibility for additive-dependent processors.
Growth Catalysts
- Clean-label reformulation:EFSA and FDA scrutiny of sulfite-based drying aids is pulling processors toward enzyme-based alternatives. Foodservice chains now specify additive-free dehydrated potato inputs in procurement contracts.
- Ready-meal manufacturing expansion:Frozen and chilled ready-meal producers in the United States are scaling flake and granule volumes for mashed potato components. This end-use channel now represents the dominant volume pull.
- Idaho-Washington processing cluster concentration:Proximity to raw material supply and shared infrastructure for natural gas and wastewater treatment creates cost advantages. New entrants face geographic barriers to replication.
Market Restraints
- Natural gas price exposure:Spray-drying and drum-drying operations remain thermally intensive. European processors face particular margin compression from EU ETS carbon pricing mechanisms.
- Fresh potato substitution in foodservice:Quick-service chains with in-house peeling and cutting operations bypass dehydrated inputs entirely. This substitute threat concentrates in high-volume fry and wedge applications.
- USDA grading friction:Subjective quality assessments for flake color and reconstitution behavior create lot rejection risk. Exporters to Japan face additional JIS standard alignment costs.
Strategic Opportunities
- Soup and sauce application expansion:Powder-grade dehydrated potato with sub-250-micron particle size enables clean-label thickening. This application currently captures under 15% of processed potato solids.
- EU Green Deal thermal retrofit incentives:Grants for heat-pump and solar-thermal drying retrofits reduce carbon intensity. Early adopters gain preferred-supplier status with ESG-mandated buyers.
- Direct-to-manufacturer e-procurement platforms:Ingredient marketplaces bypass traditional distributor markups for mid-size food manufacturers. This channel innovation is penetrating the 500-2,000 employee manufacturer segment.
Industry Challenges
- Drying-technician skill scarcity:Optimization of moisture uniformity across drum-dryer surfaces requires experiential knowledge. Retirement-driven attrition in Pacific Northwest facilities exceeds replacement rates.
- Legacy ERP integration with traceability systems:Lot-level genealogy requirements from FDA Food Safety Modernization Act collide with decades-old manufacturing execution software. Custom middleware development extends implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dehydrated Potato Market |
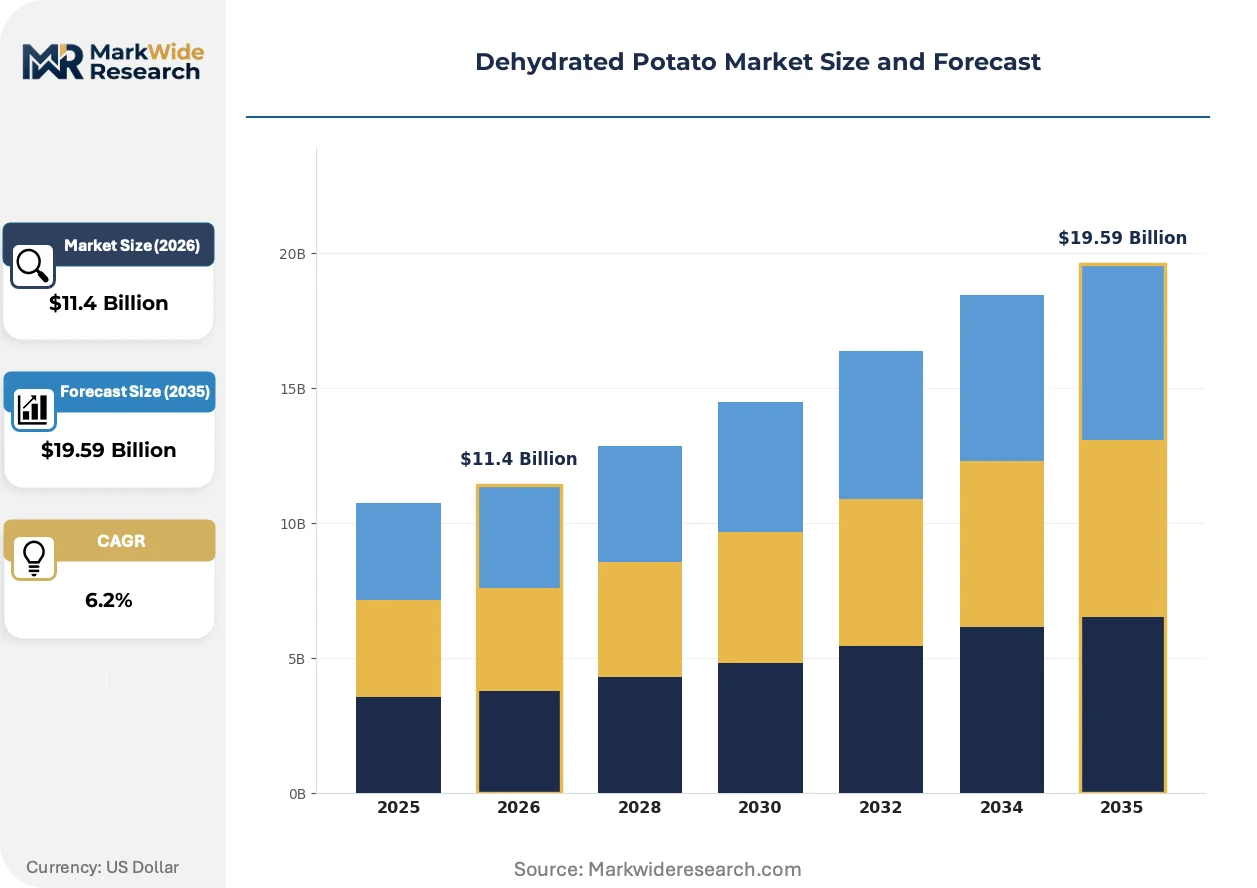
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $19.59 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flakes, Granules, Powder, Chunks, Slices Application: Snacks, Soups, Ready Meals, Bakery, Pet Food End User: Food Manufacturers, Foodservice Providers, Retailers, Food Distributors Packaging Type: Bulk Bags, Plastic Pouches, Paper Bags, Cans, Cartons |
| Companies Covered | Basic American Foods, Aviko BV, McCain Foods Limited, Agrarfrost GmbH & Co. KG, Emsland Group, Lamb Weston Holdings, Inc., J.R. Simplot Company, Oregon Potato Company, Idahoan Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dehydrated Potato Market Strategic Shifts & Innovations
Process control automation and alternative thermal technologies are compressing energy intensity benchmarks while enabling real-time quality monitoring across drying lines.
Spray-dryer control systems is digitizing moisture-content feedback loops through inline near-infrared spectroscopy. Large-scale flake producers in Idaho and Washington are retrofitting existing lines with these sensors. The technology is digitizing quality assurance staffing models while reducing out-of-specification batches.
EU REACH annex revisions are restricting specific silicate-based anti-caking agents previously common in powder-grade products. Formulators must validate replacement materials through migration testing. Bakery and soup manufacturers in Germany and France are accelerating supplier audits to verify compliance.
Foodservice distributors are consolidating purchasing decisions through centralized category management functions. Independent restaurant operators now access dehydrated potato through broadline distributor private-label programs rather than direct processor relationships. This concentration is most visible in the United States, where Sysco and US Foods control majority share of independent operator supply.
Dehydrated Potato Market Segmentation
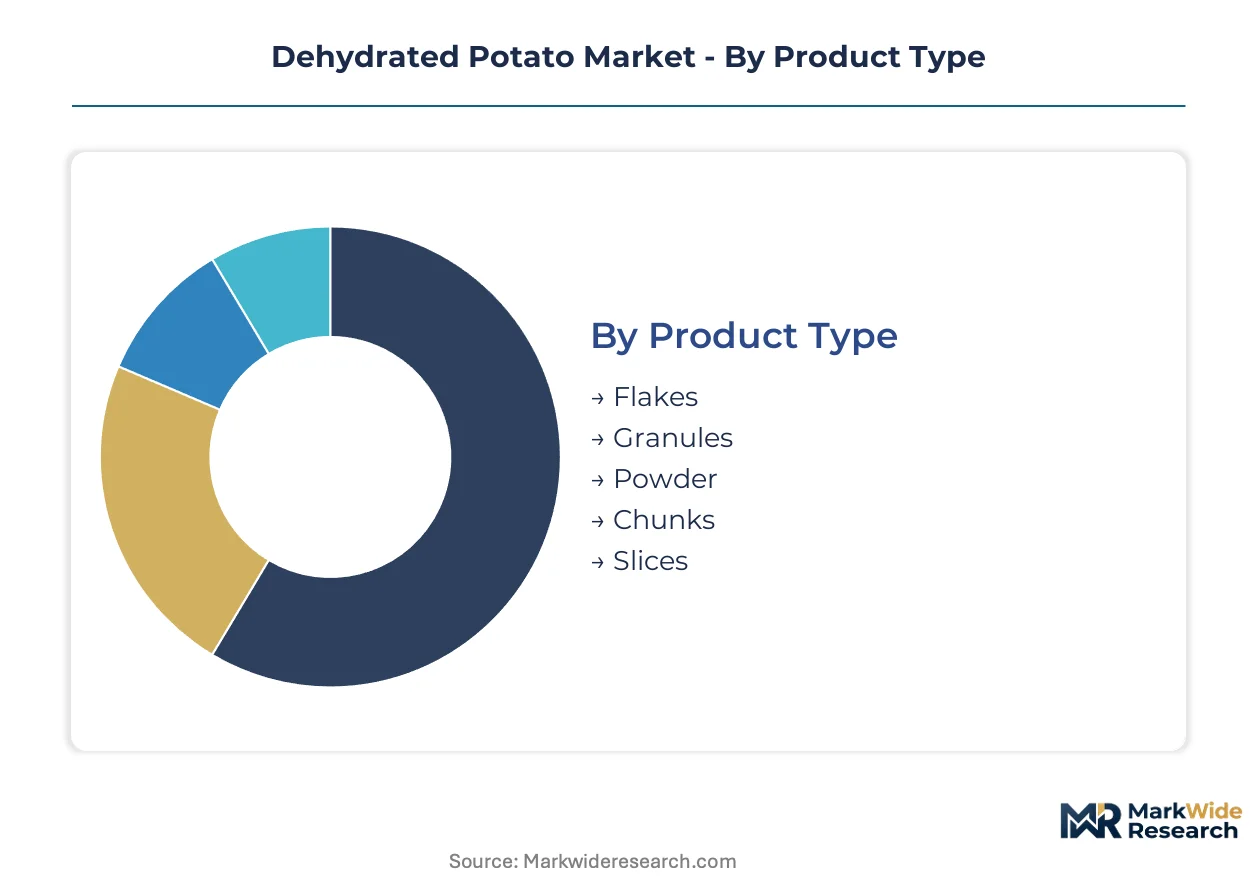
Dehydrated potato markets fragment across four structural dimensions that determine procurement patterns, margin structures, and formulation requirements. Product type governs reconstitution behavior and end-use compatibility. Application channels impose distinct quality certifications and shelf-life specifications. Understanding these segment boundaries enables targeted capacity planning and customer acquisition strategies.
Product Type:
Cost tier separation across product types reflects processing intensity, particle engineering requirements, and end-use performance premiums.
- Flakes:Thin, flat potato particles produced through drum-drying of mashed potato slurry. Foodservice chains in the United States specify flake specifications for mashed potato reconstitution in their commissary operations. USDA grading standards for color and texture create procurement gatekeeping for institutional buyers.
- Granules:Agglomerated particles formed through controlled drying and milling processes that preserve cellular structure. Ready-meal manufacturers in the Pacific Northwest cluster source granules for freeze-thaw stable mashed potato components. The segment captures premium positioning through improved mouthfeel retention.
- Powder:Fine particles below 250 microns serving bakery and soup thickening applications where hydration uniformity matters.
- Chunks:Visible potato pieces reconstituting to identifiable texture in prepared meals and camping food applications.
- Slices:Dehydrated potato disks used in casserole and scalloped potato formulations requiring layered structure.
Flakes command the established base. The steepest expansion runs through granules.
Application:
Volume concentration varies sharply across end-use channels, with thermal processing requirements and clean-label mandates reshaping supplier qualification criteria.
- Snacks:Extruded and sheeted potato products leveraging dehydrated solids for consistent dough rheology. Idaho and Washington processors supply major snack manufacturers with customized flake specifications for fryer throughput optimization.
- Ready Meals:Frozen and chilled prepared dishes incorporating mashed, sliced, or chunked potato components. This channel now drives the dominant volume pull for granule and flake grades as US retail and foodservice operators expand production lines.
- Soups:Powder-grade material enabling clean-label thickening without modified starch additives.
- Bakery:Potato flour and powder extending shelf life and moisture retention in bread formulations.
- Pet Food:Human-grade dehydrated potato serving premium pet nutrition brands seeking carbohydrate alternatives to grains.
Ready meals anchor current procurement volumes. Soups are climbing the fastest as clean-label thickening gains formulation share.
End User:
Customer type determines order scale, specification complexity, and distributor versus direct procurement routing.
- Food Manufacturers:Large-scale processors of snacks, bakery goods, and prepared meals purchasing bulk quantities with customized moisture and particle specifications. These buyers negotiate multi-year supply agreements with Idaho-Washington processing clusters.
- Foodservice Providers:Chain restaurants, institutional feeders, and contract caterers sourcing through broadline distributors or direct processor relationships. Distributor consolidation through Sysco and US Foods is compressing direct procurement for independent operators.
- Retailers:Private-label and branded grocery products including instant mashed potato and camping meal assortments.
- Food Distributors:Intermediary channel operators managing inventory and logistics for smaller manufacturers and foodservice accounts.
Food manufacturers command the established base. Foodservice providers are gaining share fastest as chain restaurant expansion accelerates.
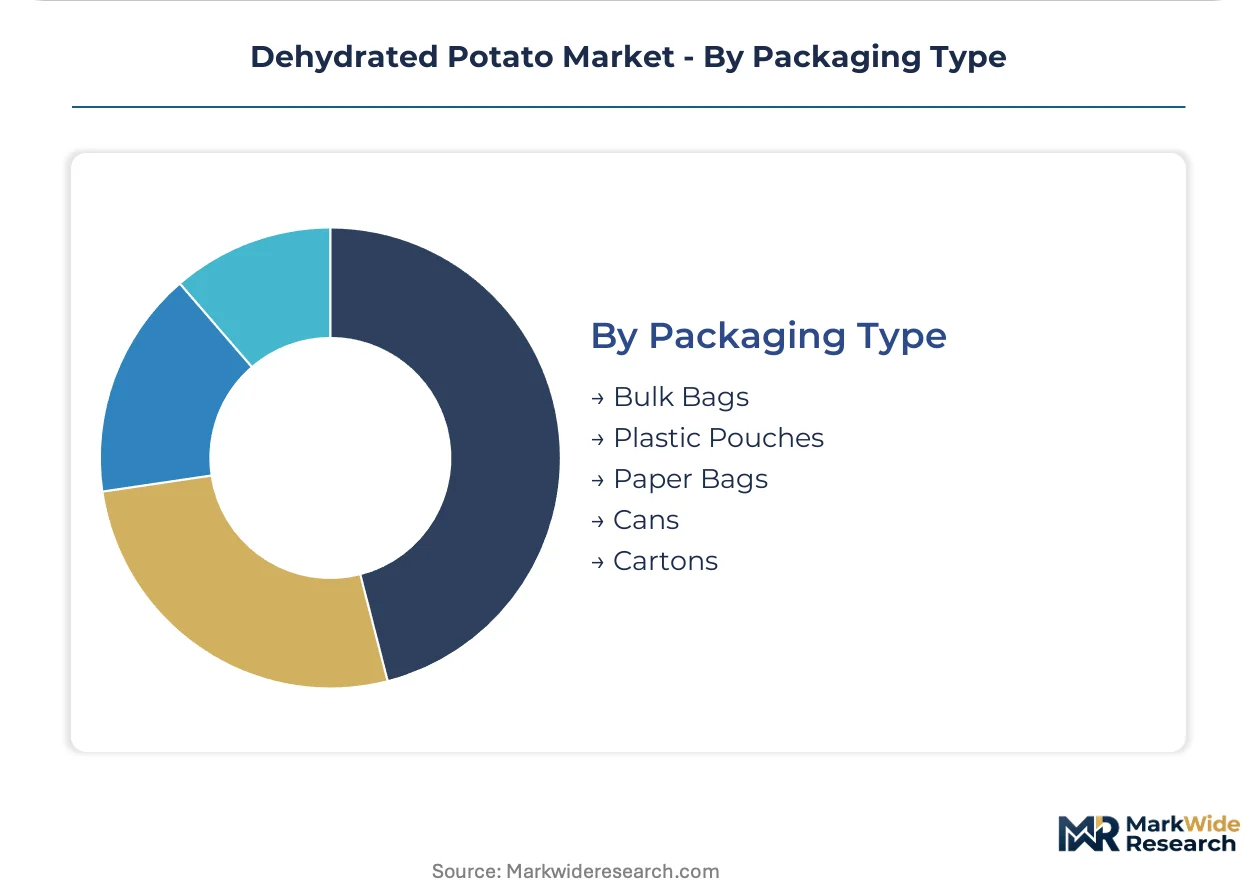
Packaging Type:
Packaging selection tracks order scale, shelf-life requirements, and handling automation compatibility across customer facilities.
- Bulk Bags:Flexible intermediate bulk containers holding 500-2000 pounds for high-volume food manufacturing lines. These units minimize handling costs for snack and ready-meal producers with pneumatic conveying systems.
- Plastic Pouches:Multi-layer barrier films for retail instant mashed potato and foodservice portion-control packs. Oxygen and moisture barrier properties preserve rehydration performance.
- Paper Bags:Kraft multi-wall constructions for institutional foodservice and industrial applications where moisture protection is secondary to cost.
- Cans:Metal containers for long-shelf-life military, emergency preparedness, and export shipments requiring maximum durability.
- Cartons:Paperboard boxes with inner liners for retail club store and foodservice case pack configurations.
Bulk bags command the established base. Plastic pouches are expanding most quickly as retail portion packs and foodservice convenience formats proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from the Idaho-Washington processing cluster supply foodservice chains across North America and Asia, while European processors face margin pressure from carbon pricing and energy cost volatility. Import demand concentrates in markets with limited domestic potato processing infrastructure.
United States
Ready-meal manufacturers in the Pacific Northwest drive granule procurement volumes for freeze-thaw stable formulations. The FDA enforces moisture-content standards under 21 CFR that shape product specifications for interstate commerce. Twin Falls, Idaho and Pasco, Washington host drum-drying facilities supplying major foodservice distributors with customized flake grades.
Germany
Bakery and soup manufacturers in Bavaria and North Rhine-Westphalia source powder-grade material for clean-label thickening applications. EFSA restrictions on silicate-based anti-caking agents under REACH annex revisions force reformulation validation through migration testing. The Emsland region maintains potato starch and dehydration operations serving Central European industrial buyers.
China
Domestic snack extrusion lines in Shandong and Hebei provinces absorb imported flake volumes for consistent dough rheology. The country's national food safety regulator enforces GB standards for dehydrated vegetable moisture content and labeling. Processing capacity expansion in Inner Mongolia targets reduced reliance on North American imports for food manufacturing inputs.
Japan
Foodservice chains and retail instant meal producers import granule and flake grades for reconstitution stability. JIS standards for dehydrated potato color and texture create additional compliance costs for exporters from the United States and Europe. The Kanto region around Tokyo concentrates distribution and secondary processing for domestic food manufacturers.
Netherlands
European headquarters of multinational food manufacturers in Rotterdam and Amsterdam drive procurement coordination for powder and granule grades. EU Green Deal thermal retrofit incentives support heat-pump drying technology adoption in Brabant processing facilities. The Randstad logistics hub enables efficient redistribution to German, French, and Belgian industrial customers.
Dehydrated Potato Market Key Industry Players
On the supply side, the industry is consolidating around scale-driven processors with captive raw material access and proprietary drying infrastructure. Three archetypes dominate competitive positioning: vertically integrated agribusinesses controlling upstream potato supply, specialized dehydration technology owners with formulation expertise, and broadline food manufacturers backward integrating into ingredient production. Capacity expansion and clean-label reformulation capability acquisition represent the dominant competitive moves across all tiers.
Among North American agribusinesses, McCain Foods Limited and Lamb Weston Holdings, Inc. exemplify scale-driven vertical integration archetypes with proprietary processing infrastructure. Idahoan Foods occupies a position within the brand-specialist tier, leveraging retail-channel strength in instant mashed potato segments. European participants including Aviko BV and Emsland Group represent regional consolidation plays with technology-focused dehydration capabilities serving industrial formulation markets.
| Leading Market Players |
|---|
| Basic American Foods |
| Aviko BV |
| McCain Foods Limited |
| Agrarfrost GmbH & Co. KG |
| Emsland Group |
| Lamb Weston Holdings, Inc. |
| J.R. Simplot Company |
| Oregon Potato Company |
| Idahoan Foods |
| Others |
Cost & Logistics Intelligence
The Idaho-Washington processing cluster concentrates drum-drying and spray-drying capacity within a 300-mile radius of Twin Falls and Pasco, creating asymmetric pricing power for processors with captive raw potato supply. Food manufacturers in ready-meal and snack extrusion channels face limited alternative sourcing for USDA-graded flake and granule specifications, compressing their negotiation leverage on contract renewals.
Pricing Analysis
Drum-drying technology commands premium positioning over legacy spray-drying lines due to superior reconstitution stability in mashed potato applications. Three-tier pricing structure across premium USDA Extra Grade, standard US Grade A, and economy ungraded tiers reflects color consistency and moisture uniformity differentials. Pricing pressure stems from natural gas cost volatility in thermal processing, with European competitors particularly exposed to EU ETS carbon pricing. Mid-size food manufacturers exhibit highest price sensitivity due to limited volume scale for long-term offtake commitments, while multinational ready-meal producers leverage multi-year contracts to lock in supply security.
Supply Chain Analysis
Extended payment terms from 30 to 60 days are becoming standard for foodservice distributors purchasing through Sysco and US Foods category management programs. Raw material supply concentrates in the United States, Germany, and the Netherlands, with the Idaho-Washington cluster feeding North American food manufacturing and Dutch facilities redistributing across Central Europe. The supply chain draws from fresh potato cultivation, natural gas for thermal processing, and enzyme-based drying aids replacing restricted sulfite additives. Single-source vulnerability concentrates in the Pacific Northwest processing corridor, where shared wastewater infrastructure and natural gas pipeline networks create correlated disruption risk. Distribution runs through broadline foodservice distributors for independent restaurant operators and direct processor relationships for large-scale food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dehydrated potato market is entering a cyclical recovery phase as foodservice channel normalization drives procurement volume restoration following pandemic-era demand compression. Raw material cost stabilization and clean-label reformulation completion cycles are resetting margin structures across processing tiers.
For Market Incumbents: Insulate margin structures by accelerating backward integration into proprietary enzyme-based drying systems ahead of REACH annex enforcement on sulfite alternatives. Expand drum-drying capacity in the Idaho-Twin Falls corridor to capture ready-meal manufacturer procurement consolidation. Fresh potato substitution in quick-service fry applications represents the most acute substitution threat requiring formulation differentiation investment. For New Entrants and Emerging Players: Establish a beachhead in powder-grade production for soup and sauce thickening applications, where clean-label demand is climbing fastest and incumbent capacity allocation favors flake and granule output. Bavarian and North Rhine-Westphalian bakery manufacturers offer penetrable entry points given EFSA-driven reformulation urgency. Direct-to-manufacturer e-procurement platforms bypass traditional distributor markups for mid-size food manufacturers seeking alternative supply sources. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors processors with heat-pump drying retrofit completion and EU Green Deal grant capture for carbon intensity reduction. Long-term viability across a 5-10 year window rests on clean-label formulation capability and foodservice distributor relationship depth. Acquisition targets should demonstrate lot-level traceability system integration with modern ERP platforms. The signal to watch is JIS standard alignment investment among exporters targeting Japanese foodservice chains, indicating quality-tier positioning discipline.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Drying Retrofit | EU Green Deal grants reduce carbon intensity for ESG-mandated buyer qualification. |
| Enzyme-Based Drying Aid Transition | REACH compliance eliminates sulfite-dependent formulation risk in export markets. |
| Direct E-Procurement Platform Launch | Bypasses Sysco and US Foods markups for mid-size food manufacturer segment penetration. |
| USDA Extra Grade Certification Investment | Unlocks institutional buyer procurement gates for commissary and military supply contracts. |
| JIS Standard Alignment Program | Enables Japanese foodservice chain supplier qualification with color and texture compliance. |
Research Approach
Initial hypotheses were tested against primary input from drum-drying plant managers, ready-meal procurement directors, foodservice distributor category buyers, and FDA regulatory affairs specialists, then refined through secondary validation. Bottom-up and top-down triangulation combined trade data from USITC and Eurostat, SEC 10-K filings from publicly traded processors, USDA Grading Service reports, and EFSA scientific opinions on food-contact materials. Energy cost modeling drew from EIA natural gas price series and EU ETS carbon market data.
Demand-supply-balance modeling across the analysis window segmented volume and value outputs by product type, application channel, end-user scale tier, and regional regulatory cluster. CAGRs were derived from historical shipment data and forward capacity expansion announcements. Forecast inputs incorporated natural gas price trajectory assumptions, clean-label reformulation adoption curves, and foodservice channel procurement consolidation patterns.
Sensitivities concentrate around EU ETS carbon pricing escalation, JIS standard enforcement timing for Japanese exports, and heat-pump drying technology cost curves. Forecasts reflect documented assumptions on raw material availability and thermal processing energy costs. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Asia-Pacific Frozen Food Market
Processed and Frozen Foods
Frozen-Cooked Ready Meals Market
Processed and Frozen Foods
Frozen Meat and Fish Market
Processed and Frozen Foods
Frozen Smoked Salmon Market
Processed and Frozen Foods
Dehydrated Potato Products Market
Processed and Frozen Foods
Middle East and Africa Freeze-Dried Product Market
Processed and Frozen Foods
Indonesia Frozen Food Market
Processed and Frozen Foods
Frozen Basil Leaves Market
Processed and Frozen Foods
Freeze Dried Mangos Market
Processed and Frozen Foods
Ice Cream and Frozen Dessert Market
Processed and Frozen Foods
Europe Frozen Food Market
Processed and Frozen Foods
IQF Food Products Market
Processed and Frozen Foods
Frozen Pizza Market
Processed and Frozen Foods
Frozen Chicken Market
Processed and Frozen Foods
Chilled Processed Food Market
Processed and Frozen Foods
Frozen Shrimp Market