
 US Frozen Food Market | 2026-2036
US Frozen Food Market Size, Share, and Industry Trends Forecast 2026-2036
US Frozen Food Market Intelligence
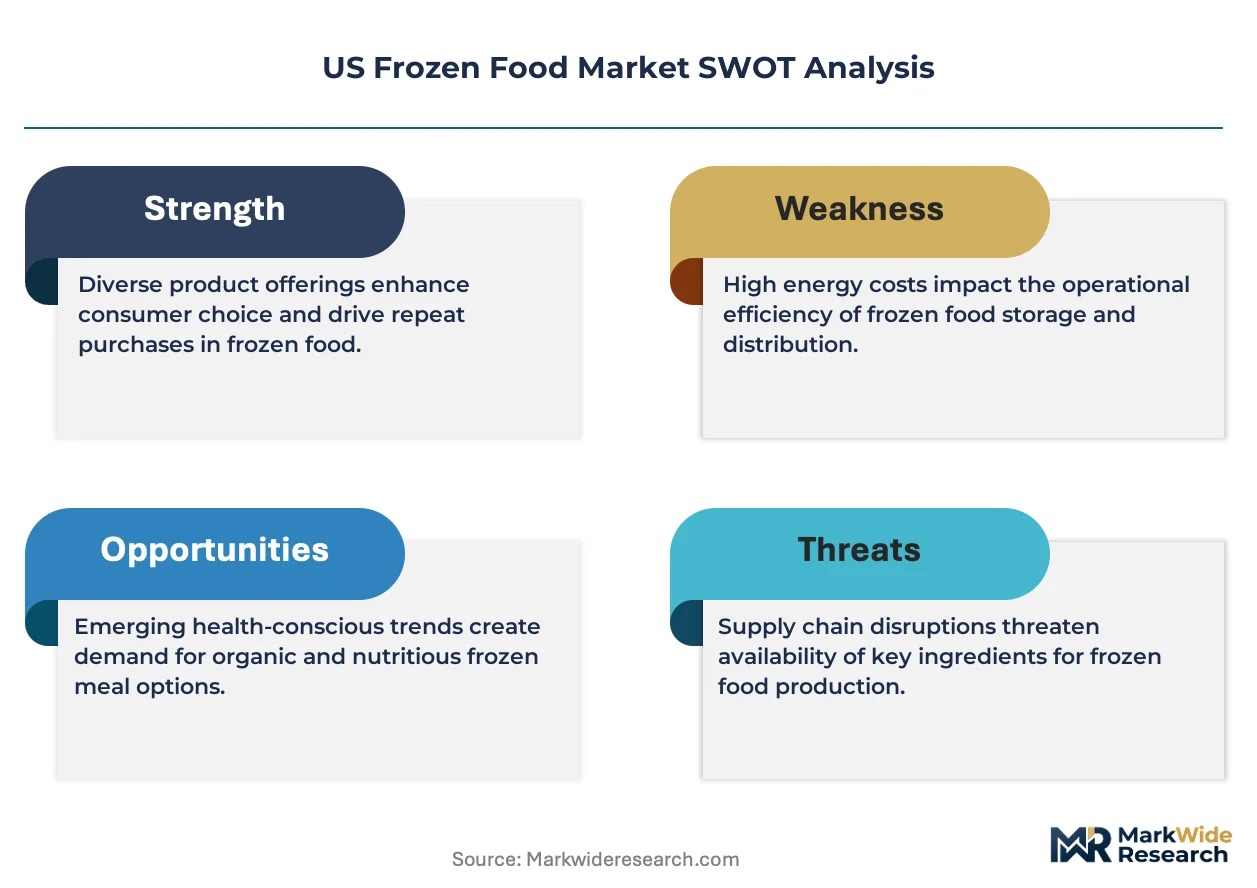
The Food and Drug Administration's Food Safety Modernization Act (FSMA) is expanding the compliance burden for new market entrants, particularly smaller producers. Large-scale operators like Conagra Brands leverage extensive distribution networks to maintain market presence across the US. Tyson Foods controls a significant portion of its raw material supply through its meat processing operations. McCain Foods differentiates through its specialization in frozen potato and appetizer products for both retail and foodservice channels.
Frozen food encompasses items preserved through a rapid freezing process, such as Individual Quick Freezing (IQF), and stored at or below 0°F (-18°C). This method inhibits microbial growth and slows enzymatic activity, extending shelf life while retaining nutritional value and taste for consumers. The frozen meat and poultry segment constitutes a mature and high-volume category within the US market. Premium frozen desserts and plant-based alternatives show significant growth, particularly among retail consumers and online shoppers.
The US Department of Agriculture (USDA) governs the labeling and inspection of meat, poultry, and egg products in the frozen category. Concurrently, the Federal Trade Commission (FTC) scrutinizes health and nutritional claims on packaging to prevent deceptive advertising. Navigating shifting consumer definitions of health, clean-label ingredients, and sustainable sourcing will determine brand leadership and margin potential.
Market Dynamics
The intersection of consumer demand for meal convenience and the rising complexity of food safety regulations defines the current market structure. This dynamic creates advantages for large, established operators while challenging smaller, niche brands entering the e-commerce space.
Growth Catalysts
- E-commerce Channel Growth:Direct-to-consumer platforms and online grocery services expand market access, catering to shopper demand for convenient, home-delivered meal solutions.
- Advanced Freezing Techniques:Technologies like Individual Quick Freezing (IQF) preserve texture and nutrients, meeting consumer expectations for higher quality in frozen products.
- Convenience-Driven Lifestyles:Demand for single-serving and ready-to-heat meals is rising among younger consumers, particularly for plant-based and ethnic cuisine options.
Market Restraints
- Cold Chain Energy Costs:The industry's reliance on energy for refrigeration exposes producers to margin pressure from electricity price volatility.
- FSMA Compliance Burden:The FDA's Food Safety Modernization Act imposes complex and costly requirements, creating a significant barrier for smaller producers.
- Raw Material Volatility:Price instability for key inputs like meat and poultry directly impacts production costs and complicates financial planning for manufacturers.
Strategic Opportunities
- Plant-Based Product Expansion:Developing plant-based frozen meals and meat alternatives caters to a growing consumer segment focused on health and sustainability.
- Diet-Specific Offerings:Launching curated lines for diets like keto or gluten-free can capture loyal customers, particularly through direct-to-consumer subscription models.
- Sustainable Packaging:Adopting recyclable or compostable packaging provides a brand differentiator for consumers prioritizing environmental impact in their purchasing decisions.
Industry Challenges
- Last-Mile Logistics:The growth of D2C e-commerce requires significant investment in specialized, temperature-controlled logistics and delivery networks, a costly operational shift.
- Marketing Claim Substantiation:Brands must navigate evolving consumer definitions of "health" while ensuring all packaging claims comply with strict FTC and USDA regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Frozen Food Market |
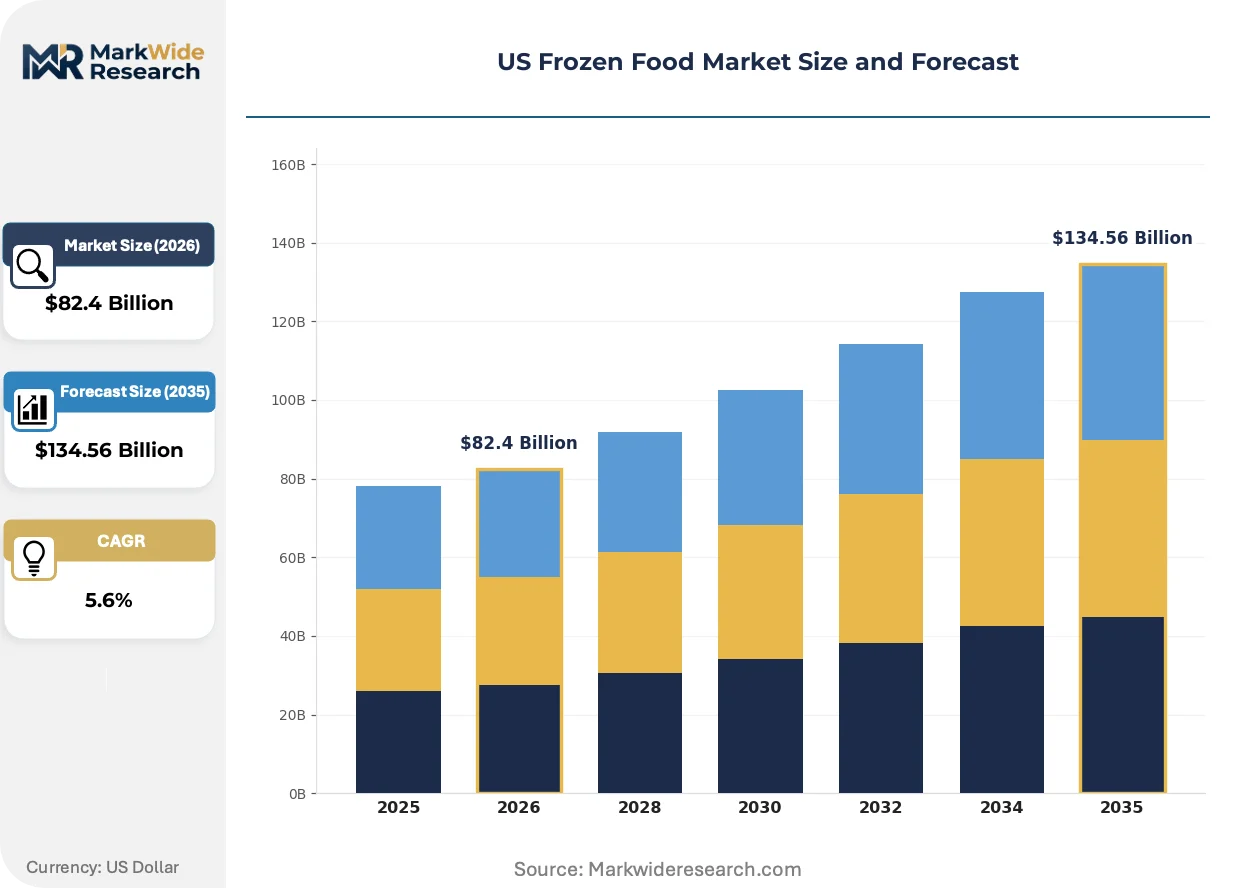
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $134.56 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Vegetables, Frozen Meat, Frozen Fruits, Frozen Desserts Customer Type: Retail Consumers, Foodservice Providers, Supermarkets, Online Shoppers Distribution Channel: Modern Trade, Online Retail, Convenience Stores, Wholesale Price Tier: Premium, Mid-Range, Budget, Discount |
| Companies Covered | Nestlé USA, McCain Foods, Conagra Brands, Ajinomoto Foods North America, Nomad Foods, General Mills, The Kraft Heinz Company, Bellisio Foods, Tyson Foods, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Frozen Food Market Strategic Shifts & Innovations
The intersection of food science innovation and evolving consumer values around health and transparency is reshaping the market. This dynamic compels brands to innovate beyond legacy product formulations and address new definitions of quality in the frozen category.
High-Pressure Processing (HPP) is a non-thermal pasteurization method that enhances food safety and extends shelf life without preservatives. Premium brands are adopting it for components in ready-meals to appeal to health-conscious consumers. HPP technology is converging with clean-label ingredient sourcing to deliver products that maintain a "fresh" perception despite being frozen.
Federal Trade Commission (FTC) oversight on packaging claims is intensifying, particularly for terms like "natural," "sustainable," and "healthy." This forces manufacturers to provide robust scientific or supply chain evidence to substantiate their marketing. The plant-based and premium dessert segments are most affected, needing to ensure their claims withstand regulatory scrutiny.
A behavioral shift from bulk supermarket purchases toward curated, on-demand orders through specialized online channels is accelerating. This pattern disintermediates traditional retail, with direct-to-consumer subscription models gaining traction for niche and premium products. This trend is most prominent in dense urban markets like those in California and the Northeast.
US Frozen Food Market Segmentation
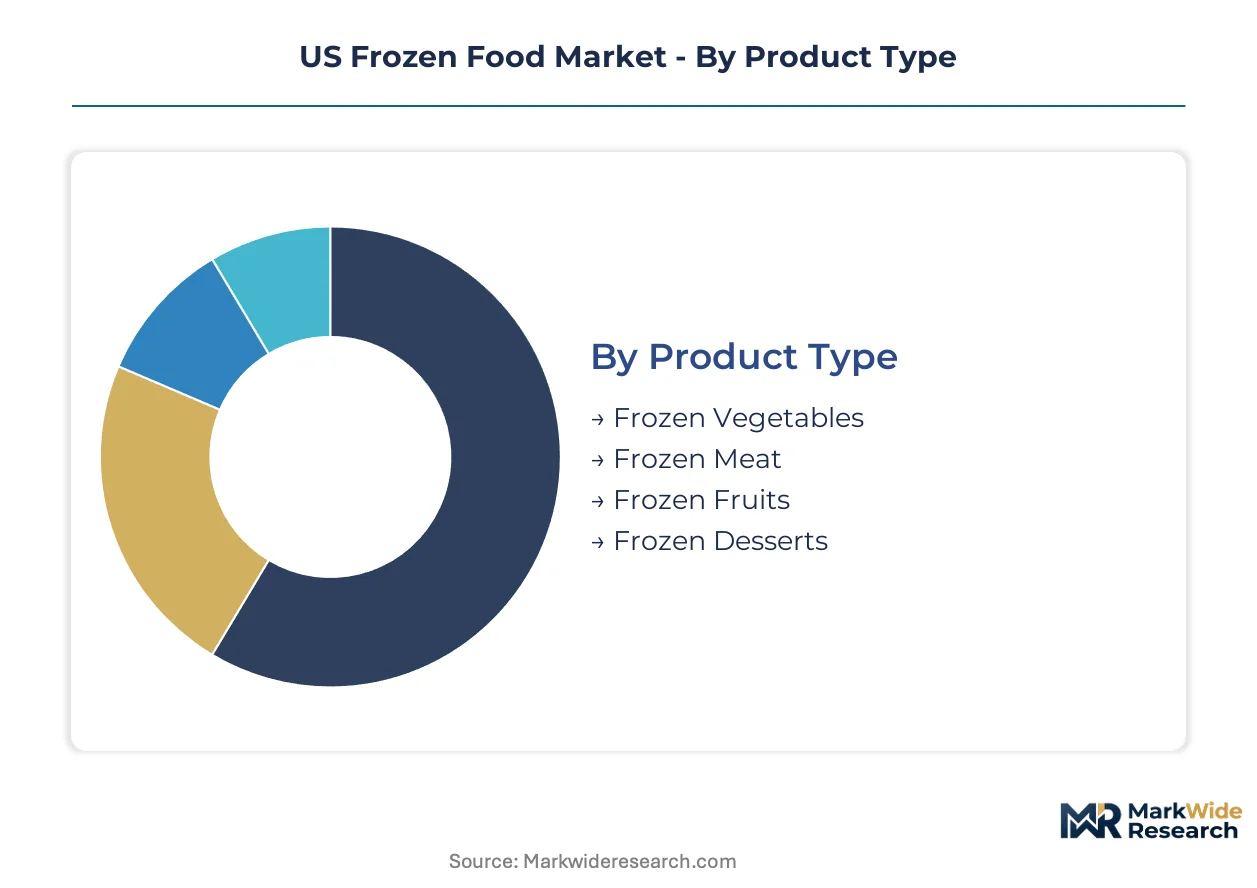
The US frozen food market structure is defined by diverse product offerings and varied consumer purchasing behaviors. Understanding these distinct segments allows manufacturers to tailor product development and distribution strategies effectively. This analysis breaks down the market by product type, customer profile, distribution methods, and price points.
Product Type:
Buyer preferences for specific frozen food categories significantly differentiate purchasing decisions within the market.
- Frozen Meat:This segment includes a wide range of red meat, poultry, and seafood products preserved through freezing. Demand for convenient, pre-portioned meat solutions remains strong across US households.
- Frozen Desserts:Encompassing ice cream, frozen yogurt, cakes, and pastries, this category often features premium ingredients and innovative flavor profiles. Online shoppers exhibit high demand for unique, high-quality frozen dessert options, especially plant-based varieties.
- Frozen Vegetables:This segment comprises individually quick-frozen (IQF) vegetables, offering extended shelf life and preparation convenience.
- Frozen Fruits:Including berries, tropical fruits, and fruit blends, these products are popular for smoothies and baking.
Frozen Meat leads volumes today; Frozen Desserts is gaining share fastest.
Customer Type:
The specific application and end-use of frozen food products vary widely across different customer groups.
- Retail Consumers:This broad category includes individuals and households purchasing frozen foods for at-home consumption. Convenience-driven lifestyles, particularly among younger demographics, fuel continued purchases of ready-to-heat meals.
- Online Shoppers:Consumers utilizing e-commerce platforms and direct-to-consumer services for their frozen food needs. This segment prioritizes home delivery, niche product availability, and often seeks diet-specific or premium offerings.
- Foodservice Providers:Restaurants, cafeterias, and institutional kitchens rely on bulk frozen food products for operational efficiency.
- Supermarkets:Traditional grocery stores serve as a primary point of sale for a wide array of frozen food items.
Demand from Retail Consumers drives significant volume, while Online Shoppers exhibit strong expansion.
Distribution Channel:
How frozen food products reach consumers and businesses determines market accessibility and logistical requirements.
- Online Retail:This channel includes dedicated e-commerce platforms, grocery delivery services, and direct-to-consumer websites. Specialized temperature-controlled last-mile logistics are critical for this expanding segment.
- Modern Trade:Consisting of large format supermarkets, hypermarkets, and mass merchandisers. These outlets leverage extensive cold chain infrastructure and broad geographic reach to serve a wide customer base.
- Convenience Stores:Smaller retail formats offering a limited selection of frozen items for immediate consumption.
- Wholesale:Bulk sales to businesses, often for further distribution or use in foodservice operations.
The shift towards Online Retail channels reshapes market access for many brands.
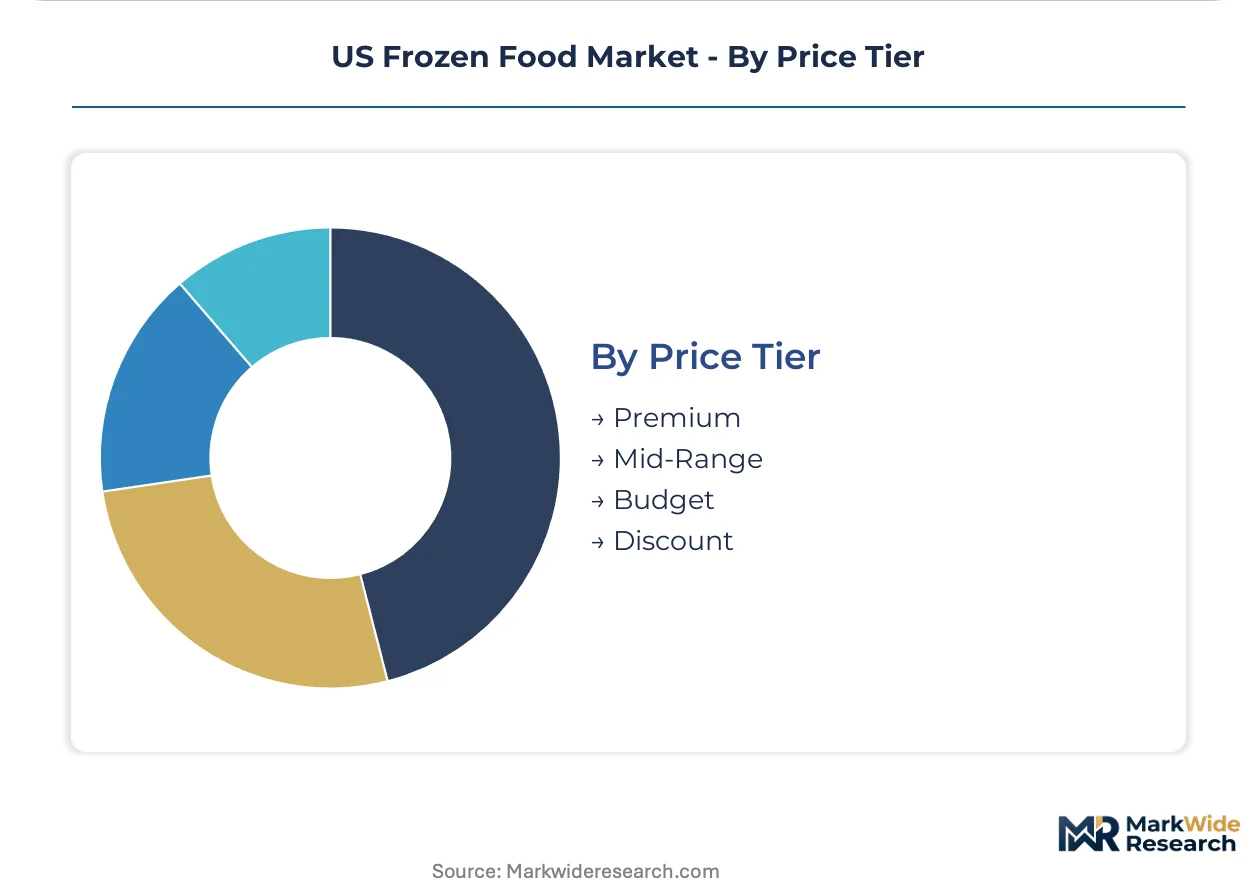
Price Tier:
Consumer's perceived value and purchasing power influence their selection across various pricing strategies.
- Premium:Products in this tier command higher prices due to specialized ingredients, advanced processing (like HPP), or unique formulations. Plant-based alternatives and gourmet frozen desserts frequently occupy this segment.
- Mid-Range:This tier represents a balance of quality and affordability, catering to the majority of US households. These products often offer established brand recognition and consistent quality.
- Budget:Characterized by lower price points, these products focus on essential frozen food items.
- Discount:Often includes bulk purchases or promotional offerings designed to attract price-sensitive consumers.
While Mid-Range options capture a broad consumer base, Premium products command higher margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A skilled workforce in food processing and logistics underpins the US frozen food market, with dense population centers driving demand for convenient meal solutions. E-commerce platforms and specialized cold chain networks connect producers to consumers nationwide. This market structure supports regional specialization and distribution efficiencies.
California
California's large, health-conscious consumer base drives demand for plant-based alternatives and premium frozen desserts. The California Department of Food and Agriculture (CDFA) enforces stringent food safety and labeling standards. Los Angeles and San Francisco Bay Area metros see high demand for niche, health-conscious frozen products.
New York Metro
Convenience-driven lifestyles and diverse ethnic cuisine preferences shape frozen food consumption across the New York Metro area. The New York State Department of Agriculture and Markets oversees food processing and distribution within the state. New York City's dense urban environment fosters rapid expansion of online grocery delivery for frozen items.
Texas
Texas exhibits strong demand for high-volume frozen meat products and ready-to-heat meals, catering to large households. The Texas Department of State Health Services ensures compliance with federal and state food safety regulations. Dallas-Fort Worth and Houston serve as major distribution hubs for frozen food products across the Southwest.
Southeast (Florida/Georgia)
The Southeast region, encompassing Florida and Georgia, shows robust demand for frozen seafood, poultry, and tropical fruit blends, influenced by local agriculture and tourism. Florida's Department of Agriculture and Consumer Services monitors food product quality and labeling. Miami and Atlanta are critical logistics points for frozen food distribution, serving both local and export markets.
Pacific Northwest (Washington/Oregon)
The Pacific Northwest, including Washington and Oregon, drives demand for organic, sustainable, and specialty frozen seafood and berry products. The Washington State Department of Agriculture (WSDA) emphasizes sustainable food practices and product integrity. Seattle and Portland are centers for innovative frozen food startups focusing on clean-label and locally sourced ingredients.
US Frozen Food Market Key Industry Players
The competitive structure tilts toward large-scale operators leveraging extensive distribution networks. This market features a tiered structure, with major brands dominating traditional retail channels while niche players emerge in e-commerce. Established incumbents, specialized product innovators, and e-commerce-focused disruptors represent key strategic archetypes. Strategic partnerships for last-mile delivery and portfolio diversification into plant-based offerings are dominant competitive moves.
At the scale-driven end of the market, Conagra Brands, Inc. exemplifies broad portfolio diversification across multiple frozen categories. Tyson Foods, Inc. occupies a position anchored by upstream control over raw material supply through its meat processing operations. McCain Foods Limited represents a global specialist archetype, focusing on frozen potato and appetizer products for both retail and foodservice channels.
| Leading Market Players |
|---|
| Nestlé USA |
| McCain Foods |
| Conagra Brands |
| Ajinomoto Foods North America |
| Nomad Foods |
| General Mills |
| The Kraft Heinz Company |
| Bellisio Foods |
| Tyson Foods |
| Others |
Cost & Logistics Intelligence
Skilled food processing and logistics workforces concentrated near dense US population centers influence pricing-tier spreads for frozen foods. Labor-cost differentials between urban and rural production sites impact overall product affordability and market positioning.
Pricing Analysis
Bundled product offerings, combining premium ingredients with specialized processing like HPP, command higher prices in the US frozen food market. Pricing stratifies across premium, mid-range, and budget tiers, driven by specialized ingredients, advanced processing techniques, and brand recognition. Cold chain energy costs and raw material volatility contribute to margin pressure across all segments. Retail consumers selecting budget options exhibit the highest price sensitivity, while online shoppers seeking premium plant-based alternatives are less price-sensitive.
Supply Chain Analysis
Dual-sourcing requirements for critical inputs mitigate risk for large-scale frozen food manufacturers in the US. Supply of raw meat and poultry concentrates in the Midwest, while fruits and vegetables are sourced heavily from California and the Pacific Northwest. Key dependencies include meat, poultry, specialized packaging, and energy for refrigeration. Commodity price volatility for these agricultural inputs represents a significant structural risk. Downstream distribution runs through a hybrid model, combining modern trade with a rapidly expanding online retail network.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US frozen food market presents a geographic-arbitrage play, leveraging regional differences in cold chain energy costs and consumer demand patterns. Lower energy costs in some production regions can offset higher last-mile delivery expenses in dense urban areas.
For Market Incumbents: Deploy extensive distribution networks to counter emerging niche D2C brands that target specific urban markets. Incumbents like Conagra Brands must also diversify their brand portfolios into plant-based offerings to address shifting consumer preferences. This strategy helps mitigate the threat from specialized startups and evolving definitions of health. Investment in advanced freezing technologies like HPP can further differentiate premium product lines.
For New Entrants and Emerging Players: Federal Trade Commission (FTC) oversight on packaging claims in the US opens a window for transparent brands with robust substantiation. Target underserved diet-specific segments like keto or gluten-free through direct-to-consumer subscription models. This approach allows for rapid market entry and builds loyal customer bases. The most penetrable segment remains premium plant-based frozen desserts for online shoppers.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists with strong local supply chains and established distribution within specific states. Long-term viability hinges on companies demonstrating agility in adopting sustainable packaging and leveraging e-commerce for niche product reach. Focus on mid-cap players innovating in plant-based or premium dessert categories. The signal to watch is accelerating consumer adoption of curated, on-demand online grocery services.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | Establishes direct customer relationships and caters to demand for convenient home-delivered meal solutions. |
| Plant-Based Portfolio Expansion | Captures growing consumer segments prioritizing health, sustainability, and ethical food choices. |
| Advanced Freezing Technology Integration | Enhances product quality, preserves texture, and extends shelf life, meeting premium consumer expectations. |
| Sustainable Packaging Adoption | Differentiates brands and aligns with environmental values of a significant portion of retail consumers. |
| Cold Chain Logistics Partnership | Optimizes last-mile delivery efficiency and reduces operational costs for temperature-sensitive products. |
Research Approach
Coverage spans all major US regions, with primary inputs from each state's food processing and logistics sectors. This approach combines in-depth interviews with food processing executives, cold chain logistics managers, retail category buyers, and e-commerce platform specialists. Secondary validation draws from USDA reports, FDA guidance documents, FTC consumer protection data, and retail sales figures. Bottom-up and top-down triangulation ensures data consistency and accuracy.
Granularity for the US frozen food market was modeled at the product type, customer profile, distribution channel, price tier, and freezing technology dimensions. The analytical framework projects volume and value outputs across the analysis window, with compound annual growth rates derived from historical trends and future projections. Key forecast inputs include consumer spending on food, energy price forecasts, and e-commerce penetration rates.
Revisions become necessary when raw material price volatility or significant shifts in cold chain energy costs materialize. Forecasts reflect assumptions regarding stable regulatory environments and consistent consumer purchasing behaviors. Deviation in e-commerce adoption rates or plant-based market penetration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Europe Dehydrated Food Market
Processed and Frozen Foods
GCC Frozen Finger Chips Market
Processed and Frozen Foods
Turkey Cold Storage Market
Processed and Frozen Foods
South America RTE Food Market
Processed and Frozen Foods
North America Frozen Desserts Market
Processed and Frozen Foods
Chocolate Ice Cream Market
Processed and Frozen Foods
Frozen Processed Food Market
Processed and Frozen Foods
Europe Ice Cream Market
Processed and Frozen Foods
Middle East and Africa Frozen Bread Market
Processed and Frozen Foods
Frozen Tart Shells Market
Processed and Frozen Foods
Middle East and Africa Freeze-Dried Product Market
Processed and Frozen Foods
Freeze Dried Tropical Fruits Market
Processed and Frozen Foods
Frozen French Fries Market
Processed and Frozen Foods
Frozen Meat and Fish Market
Processed and Frozen Foods
Europe Frozen Pizza Market
Processed and Frozen Foods
South America Frozen Desserts Market