
 Frozen Shrimp Market | 2026-2036
Frozen Shrimp Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Shrimp Market Analytics
Best Aquaculture Practices (BAP) certification is collapsing the supplier base as smaller operations fail to meet four-star standards for hatchery, feed, farm, and plant. Thai Union Group PCL leverages its integrated supply chain to sustain multi-star BAP ratings across Thai and Vietnamese operations. Minh Phu Seafood Corporation dominates Mekong Delta processing with captive farm networks that control raw material quality. Nordic Seafood A/S navigates stringent EU traceability rules by specializing in cold-water shrimp with documented chain-of-custody.
Frozen shrimp denotes decapod crustaceans harvested or farmed, then blast-frozen at minus 35 to minus 40 degrees Celsius within hours of catch to preserve texture and inhibit enzymatic degradation; the process arrests melanosis and maintains HACCP-compliant safety profiles for commercial distribution. Raw product lines occupy the highest volume tier but carry thinner margins due to commodity pricing and Asian supply abundance. Cooked and peeled segments attract premium positioning in European retail and North American food service where labor cost reduction drives procurement preferences. Vacuum-sealed packaging is displacing traditional bulk blocks in supermarket channels as shelf-life extension and presentation quality reshape buyer expectations.
The EU's IUU Fishing Regulation and the US FDA Seafood HACCP program impose documentary and inspection burdens that filter out informal traders and reward certified enterprises. Ecolabelling schemes including Marine Stewardship Council and Aquaculture Stewardship Council standards increasingly gate retail listings in German and British supermarket chains. Stakeholders must weigh traceability investment against margin compression as regulatory layers accumulate and buyer accountability requirements deepen.
Market Dynamics
Traceability mandates from the EU's IUU Fishing Regulation and the US FDA Seafood HACCP program are compressing the supplier base, rewarding certified operators while informal traders exit. This regulatory tightening intersects with food service menu expansion and retail packaging upgrades to reshape competitive positioning.
Growth Catalysts
- EU IUU Fishing Regulation:Mandatory catch documentation schemes force importers to invest in chain-of-custody systems, filtering out uncertified competitors and expanding market share for compliant enterprises.
- Food service menu expansion:Operators across North America and Europe are adding value-added shrimp preparations, pulling volume through prepared and cooked product lines.
- Blast-freezing at minus 35 to minus 40 degrees Celsius:This processing technology preserves texture and arrests melanosis, enabling longer supply chains and retail shelf-life extension.
Market Restraints
- Feed cost volatility:Aquaculture operations face input price swings for fishmeal and soy-based feeds, compressing farm-level margins and transmitting pressure upstream.
- Mekong Delta supply concentration:Processing capacity clustering in Vietnam creates geographic risk exposure to climate events and water quality disruptions.
- Enzymatic degradation limits:Even with rapid freezing, quality deterioration sets hard boundaries on distribution radius for raw product lines.
Strategic Opportunities
- Vietnam processing expansion:Preferential trade access and captive farm networks position exporters to capture share in EU and US retail channels.
- Vacuum-sealed packaging:Supermarket buyers are displacing bulk blocks with retail-ready formats that command presentation premiums.
- Aquaculture Stewardship Council certification:German and British supermarket chains are gating listings behind ASC standards, creating first-mover advantage for certified producers.
Industry Challenges
- Four-star BAP certification timelines:Smaller hatchery, feed, farm, and plant operators lack capital and technical capacity to meet Best Aquaculture Practices standards across all four nodes.
- Cold-chain capex intensity:Blast-freezing equipment and refrigerated logistics require substantial capital deployment that strains mid-tier processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Shrimp Market |
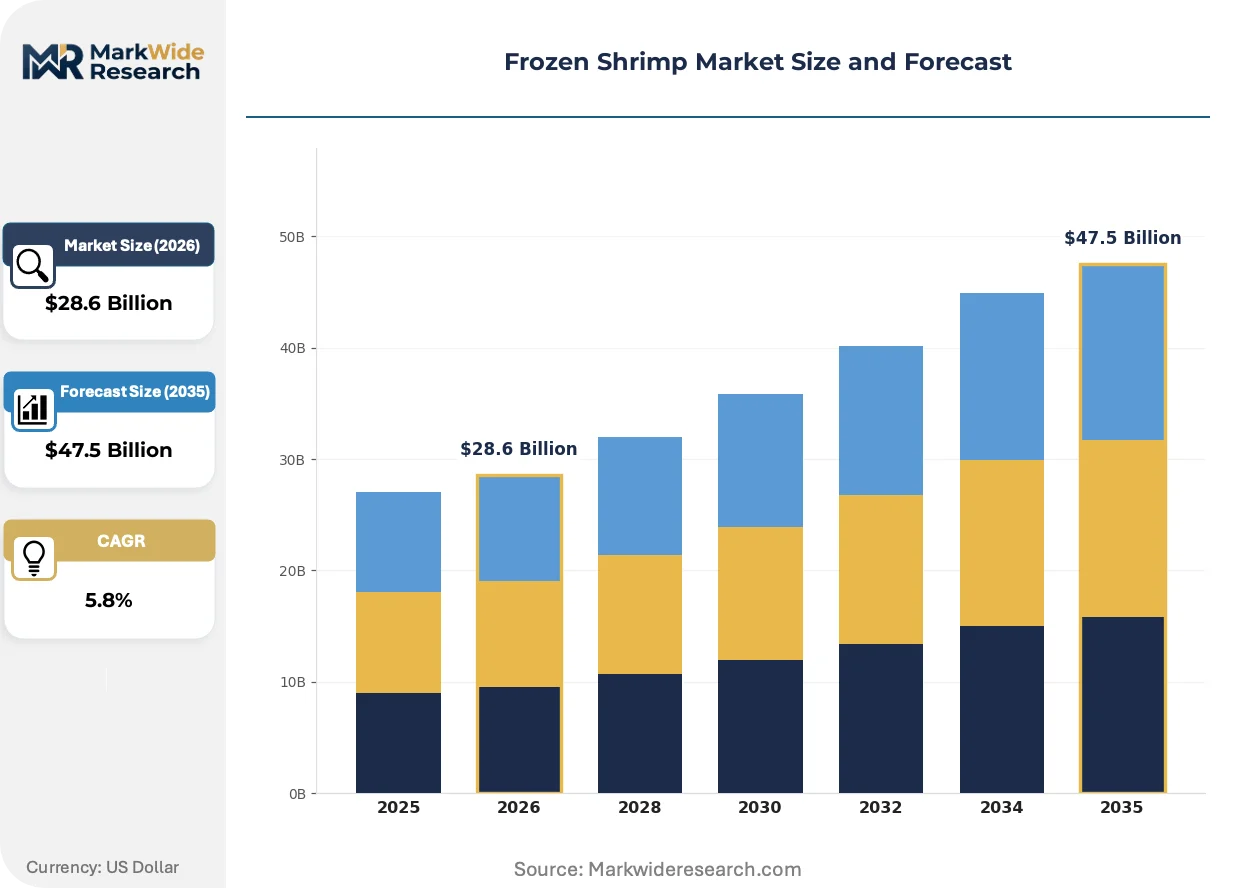
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw, Cooked, Peeled, Shell-On End User: Retailers, Restaurants, Food Service, Exporters Packaging Type: Bulk, Shrink-Wrapped, Vacuum-Sealed, Boxes Distribution Channel: Direct Sales, Wholesalers, Online Platforms, Supermarkets |
| Companies Covered | Thai Union Group PCL, Apex Frozen Foods Ltd, Charoen Pokphand Foods PCL, Aqua Star, Mazzetta Company LLC, Pacific Seafood, Nordic Seafood A/S, Minh Phu Seafood Corporation, Avanti Feeds Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Shrimp Market Evolving Landscape
Processing technology and packaging formats are compressing traditional supply chain tiers, while regulatory documentation requirements deepen data infrastructure investments across the value chain.
Individual Quick Freezing (IQF) technology uses cryogenic or mechanical freezing to separate shrimp pieces rather than forming blocks, preserving product integrity for portion-controlled retail and food service applications. European supermarket chains and North American restaurant distributors are adopting IQF systems at accelerating rates. This technology is miniaturizing batch processing economics, enabling smaller regional processors to compete with integrated giants on quality consistency.
The EU's IUU Fishing Regulation mandates documentary evidence of legal catch origin for all imported seafood, with penalties including import bans for non-compliance. This policy forces importers to deploy electronic traceability platforms and third-party verification services. Raw product importers into Germany, France, and the Netherlands face the steepest compliance burdens, driving consolidation toward enterprises with dedicated regulatory affairs functions.
Buyer certification preferences are hardening into procurement gatekeeping, with Marine Stewardship Council and Aquaculture Stewardship Council labels becoming mandatory for shelf placement in premium retail channels. Food service distributors in the United States are now specifying BAP certification in contract tenders, displacing uncertified suppliers from institutional accounts. This preference shift is most visible in the German retail and US food service verticals, where accountability requirements have moved from marketing differentiation to operational necessity.
Frozen Shrimp Market Segmentation
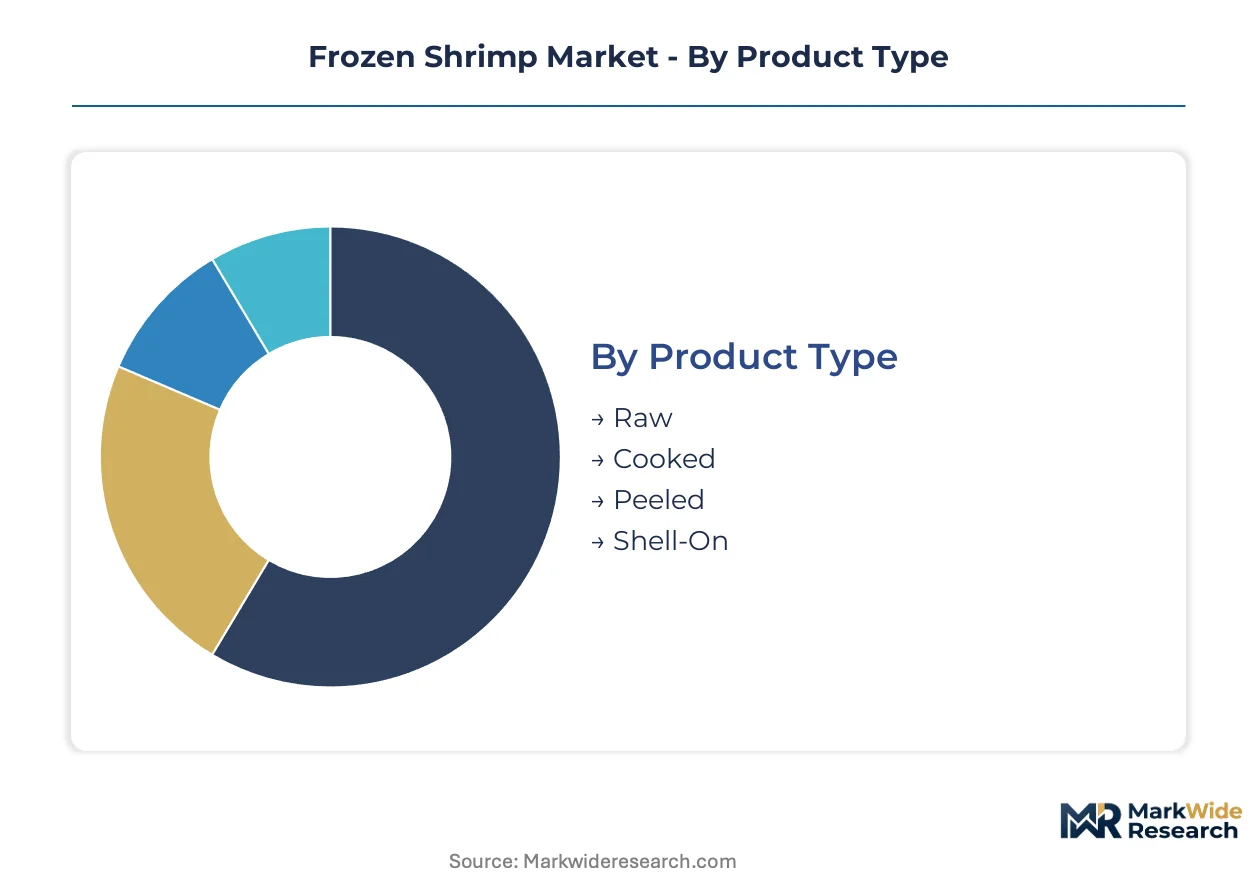
Segmentation in frozen shrimp reveals how processing depth, buyer sophistication, and logistics infrastructure allocate margin pools across the value chain. Each dimension exposes different vulnerability to substitute proteins and regulatory compliance costs.
Product Type:
Raw product lines face acute substitution pressure from alternative proteins and fresh seafood channels, while value-added preparations build defensibility through labor substitution and food safety integration.
- Raw:Blast-frozen at minus 35 to minus 40 degrees Celsius within hours of harvest to arrest enzymatic degradation and melanosis. Commodity pricing dominates Asian supply bases, with Vietnamese and Thai processors competing on volume throughput to EU and US importers facing IUU Fishing Regulation documentation burdens.
- Cooked:Thermal processing to 70-80 degrees Celsius core temperature eliminates pathogenic risk and extends shelf life. North American food service operators and European retail chains concentrate procurement here, driven by HACCP compliance requirements and kitchen labor cost reduction.
- Peeled:Mechanized or manual shell removal reduces downstream preparation time. Demand clusters in institutional food service and ready-meal manufacturing where throughput efficiency governs supplier selection.
- Shell-On:Minimal processing preserves natural barrier protection and flavor compounds. Premium positioning in specialty retail and high-end restaurant channels where presentation authenticity commands price premiums.
Raw retains volume leadership; cooked holds the steepest expansion curve as food service labor costs climb and safety accountability deepens.
End User:
Cost tier stratification separates price-sensitive volume buyers from premium-positioned channels where certification and traceability investments convert to margin.
- Retailers:Supermarket chains and independent grocers stock IQF and vacuum-sealed formats for home preparation. German and British buyers increasingly gate shelf placement behind ASC or MSC certification, filtering supplier bases toward integrated enterprises with dedicated regulatory functions.
- Restaurants:Full-service and casual dining operators specify tail-off, deveined, or breaded preparations to reduce kitchen labor. US food service distributors now mandate BAP certification in contract tenders, displacing uncertified suppliers from institutional accounts.
- Food Service:Broadline distributors and contract caterers procure cooked-peeled product for healthcare, education, and corporate feeding. Volume concentration with national distributors creates procurement leverage that compresses processor margins.
- Exporters:Re-export traders and regional redistributors arbitrage price differentials between production zones and destination markets. EU IUU Fishing Regulation compliance requirements now dominate operational priorities, favoring enterprises with captive farm-to-plant traceability systems.
Food service captures the largest volume flows; retailers command the fastest certification-driven margin expansion.
Packaging Type:
Supply concentration in Mekong Delta processing clusters shapes packaging innovation trajectories, with proximity to export ports accelerating format transitions.
- Bulk:Traditional 5-10kg frozen blocks for industrial reprocessing and food manufacturing. Cost minimization drives procurement in emerging markets and commodity trading, though quality inconsistency limits retail penetration.
- Shrink-Wrapped:Polymer film overwrap for retail-ready presentation with moderate shelf-life extension. European supermarket private label programs favor this format for mid-tier positioning between bulk commodity and premium vacuum-sealed alternatives.
- Vacuum-Sealed:Oxygen-exclusion packaging extends shelf life 40-60% over conventional methods while preserving texture and color. North American and European retail channels are displacing bulk blocks with this format, commanding presentation premiums and reducing cold-chain spoilage losses.
- Boxes:Corrugated or polymer containers for food service portion control and institutional portioning. Standardized sizing enables automated inventory management in large-scale catering operations.
Bulk retains volume leadership in commodity trading; vacuum-sealed climbs the fastest as retail presentation standards harden.
Distribution Channel:
Customer type fragmentation—industrial reprocessors versus retail consumers versus food service operators—forces channel-specific logistics investments and compliance architectures.
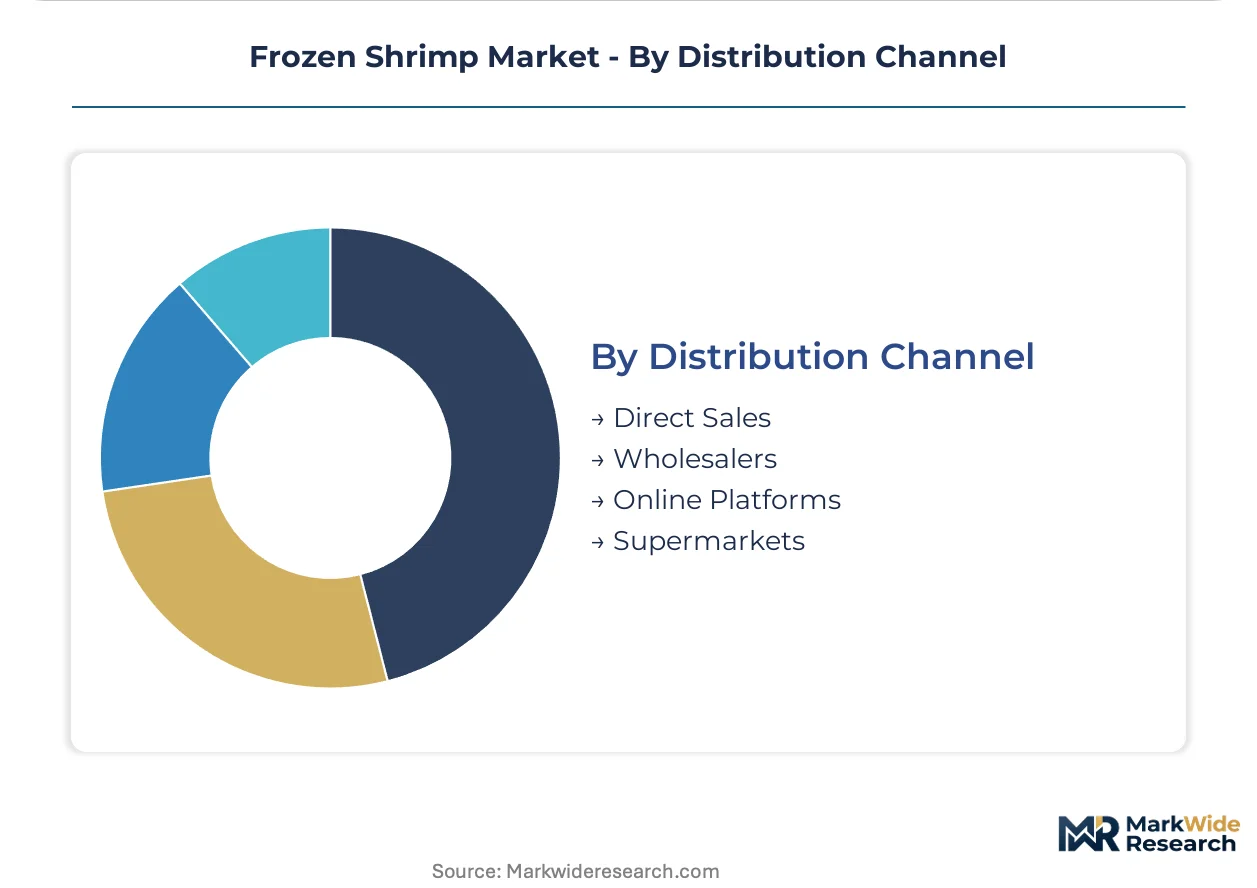
- Direct Sales:Processor-to-buyer contracts bypassing intermediary tiers. Large EU and US importers with dedicated regulatory affairs functions prefer this channel to enforce IUU Fishing Regulation documentation and ASC certification compliance.
- Wholesalers:Regional distributors aggregating volume from multiple processors for downstream fragmentation. Traditional dominance in Asian domestic markets and emerging economy food service, though traceability requirements are consolidating supplier relationships.
- Online Platforms:E-commerce direct-to-consumer and B2B procurement portals. Cold-chain last-mile capabilities limit geographic reach, but urban concentration in North America and Europe enables premium positioning for traceable, certified product lines.
- Supermarkets:Integrated retail procurement with private label development and shelf-space optimization. German chains lead in ASC mandate implementation, while US retailers specify BAP certification for sustainable seafood counters.
Wholesalers retain volume leadership in developing markets; direct sales gains share fastest as regulatory compliance concentrates buyer-supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Preferential trade access and processing capacity expansion in Vietnam are redirecting procurement flows away from traditional Thai supply bases. EU IUU Fishing Regulation compliance costs now filter supplier eligibility across all major import markets. Cold-chain infrastructure investments in Mekong Delta clusters are compressing delivery timelines to European and North American buyers.
United States
Food service distributors specify BAP certification in contract tenders, displacing uncertified suppliers from institutional accounts. FDA Seafood HACCP program inspections enforce documentary burdens that reward enterprises with dedicated regulatory affairs functions. Gulf Coast and Pacific Northwest processing hubs handle re-export volumes from Asian supply bases.
Germany
Supermarket chains gate shelf placement behind ASC certification, filtering supplier bases toward integrated enterprises with traceability infrastructure. EU IUU Fishing Regulation documentation requirements concentrate procurement relationships with importers deploying electronic verification platforms. Hamburg and Bremerhaven serve as primary entry points for Vietnamese and Thai frozen shrimp.
Vietnam
Captive farm networks in Mekong Delta provinces control raw material quality for export-oriented processing plants. Preferential trade access under EU-Vietnam Free Trade Agreement reduces tariff exposure for certified exporters. Can Tho and Soc Trang processing clusters are expanding blast-freezing capacity to meet North American retail specifications.
Thailand
Integrated supply chain operators sustain multi-star BAP ratings across hatchery, feed, farm, and plant operations. Domestic feed cost volatility transmits margin pressure upstream to processing tiers. Samut Sakhon and Surat Thani remain concentration points for value-added product manufacturing.
United Kingdom
Retail buyers mandate MSC or ASC labels for sustainable seafood counter placement, consolidating procurement toward certified Asian suppliers. Post-Brexit customs documentation requirements add verification layers for EU-originating re-exports. London-based importers specialize in cold-water shrimp varieties with documented chain-of-custody.
Frozen Shrimp Market Competitive Landscape
Player mix skews toward vertically integrated aquaculture conglomerates with captive farm-to-plant traceability systems. Mid-tier processors face consolidation pressure from cold-chain capital intensity and four-star BAP certification timelines. Two strategic archetypes dominate: integrated supply chain operators controlling multiple production nodes, and specialized cold-water shrimp traders leveraging documented origin verification. Competitive moves center on Mekong Delta processing expansion and vacuum-sealed packaging format adoption.
Within the integrated supply chain tier, Thai Union Group PCL and Minh Phu Seafood Corporation exemplify operators with multi-node BAP certification spanning hatchery through processing. Nordic Seafood A/S occupies a position among specialized cold-water shrimp traders navigating stringent EU traceability requirements. Apex Frozen Foods Ltd represents Indian subcontinent-based processors competing on volume throughput to Middle Eastern and African markets.
| Leading Market Players |
|---|
| Thai Union Group PCL |
| Apex Frozen Foods Ltd |
| Charoen Pokphand Foods PCL |
| Aqua Star |
| Mazzetta Company LLC |
| Pacific Seafood |
| Nordic Seafood A/S |
| Minh Phu Seafood Corporation |
| Avanti Feeds Limited |
| Others |
Value Network & Pricing Analysis
Feed ingredient substitution—fishmeal displacement by soy and insect protein—simultaneously redraws aquafeed sourcing geography toward Brazilian and Ukrainian suppliers and compresses farm-gate cost structures that cascade into processor pricing power. This input shift intersects with blast-freezing capital intensity to stratify margin capture across integrated and non-integrated supply chain tiers.
Pricing Analysis
Certification level (BAP four-star vs uncertified) creates the primary spread between commodity raw product and premium vacuum-sealed retail lines. Three-tier pricing structure across premium ASC/MSC-labeled, standard BAP-certified, and economy uncertified tiers governs European retail and North American food service procurement. Pricing pressure stems from Vietnamese processing overcapacity competing for EU and US import quotas. Retailers exhibit lowest price sensitivity for certified product, while bulk commodity traders face acute margin compression.
Supply Chain Analysis
Strategic stockpile preferences dominate Mekong Delta processors buffering against monsoon-disrupted farm supply, while European importers run lean just-in-time inventories tied to IUU documentation clearance timelines. Vietnam, Thailand, and India anchor global processing capacity. Supply chains draw from fishmeal, soy protein concentrate, and hatchery post-larvae inputs. Single-source vulnerability concentrates in Mekong Delta captive farm networks exposed to climate-driven water quality events. Distribution runs through direct processor-to-importer contracts for certified product and regional wholesalers for commodity bulk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to aquaculture feed cost normalization following commodity agriculture price spikes. Menu expansion in North American food service and EU retail certification mandates provide demand-side momentum.
For Market Incumbents: Compound BAP certification density across hatchery-to-plant nodes to widen margin capture against uncertified Mekong Delta competitors facing EU IUU Fishing Regulation exclusion. Expand blast-freezing capacity in Can Tho and Soc Trang clusters to compress delivery timelines for North American retail contracts. Defensive consolidation targets mid-tier processors lacking four-star certification timelines. For New Entrants and Emerging Players: Anchor in Indian subcontinent value-added processing for Middle Eastern and African markets where BAP certification gates remain porous. Target online platform direct-to-consumer channels in North American urban corridors where cold-chain last-mile infrastructure enables premium positioning for traceable product lines. Pursue co-manufacturing partnerships with established EU importers to bypass IUU documentation infrastructure barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Vietnamese processors holding captive farm networks but lacking integrated feed mill capacity. Five-to-ten year viability hinges on EU-Vietnam Free Trade Agreement tariff advantage persistence and ASC certification penetration in German retail. Watch Mekong Delta water quality incident frequency as inflection signal for supply disruption premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Four-Star BAP Certification Investment | Gates EU and US retail listings while filtering out informal competitors lacking capital for hatchery-to-plant compliance. |
| Mekong Delta Blast-Freezing Capacity Expansion | Compresses delivery timelines to North American buyers and enables IQF format adoption for portion-controlled retail. |
| Captive Farm Network Development | Secures raw material quality control and IUU Fishing Regulation documentation compliance for EU import eligibility. |
| Vacuum-Sealed Packaging Format Transition | Commands presentation premiums in German and British supermarkets while reducing cold-chain spoilage losses. |
| Electronic Traceability Platform Deployment | Enables real-time chain-of-custody verification required by EU IUU Fishing Regulation and US FDA Seafood HACCP program. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with aquaculture farm managers, seafood processing plant directors, EU import compliance officers, and North American food service procurement leads; and secondary validation through customs trade databases, EU IUU Fishing Regulation enforcement reports, BAP certification registries, and SEC filings of publicly traded processors. Bottom-up volume modeling triangulated against top-down trade flow analysis.
Across the analysis window, forecasts segmented by product type (raw, cooked, peeled, shell-on), end user (retail, restaurant, food service, exporter), packaging format (bulk, shrink-wrapped, vacuum-sealed, boxes), and distribution channel (direct sales, wholesalers, online platforms, supermarkets). CAGRs derived from historical trade volume trajectories, feed cost elasticity estimates, and certification penetration curves in German and US retail channels.
Material uncertainties—climate-driven Mekong Delta supply disruptions, EU tariff preference renegotiation, and feed ingredient price volatility—sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement continuity and buyer certification preference stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Processed and Frozen Vegetables Market
Processed and Frozen Foods
Indonesia Frozen Food Market
Processed and Frozen Foods
Freeze Dried Melt Market
Processed and Frozen Foods
Frozen Potato Market
Processed and Frozen Foods
Frozen Noodles and Rice Products Market
Processed and Frozen Foods
Global Chilled and Deli Foods Market
Processed and Frozen Foods
Asia-Pacific Frozen Yogurt Market
Processed and Frozen Foods
Refrigerated & Frozen Soup Market
Processed and Frozen Foods
Europe Dehydrated Food Market
Processed and Frozen Foods
US Frozen Food Market
Processed and Frozen Foods
Frozen Pork Belly Market
Processed and Frozen Foods
Frozen Fruit Bars Market
Processed and Frozen Foods
Frozen Sardine Market
Processed and Frozen Foods
French Fries Market
Processed and Frozen Foods
Refrigerated Liquid Eggs Market
Processed and Frozen Foods
Deli Meat Market