
 Frozen Food Market | 2026-2036
Frozen Food Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Food Market Intelligence
Quick service restaurants is recalibrating frozen protein procurement patterns as labor scarcity and speed-of-service requirements intensify across the foodservice channel. Nestlé S.A. anchors its position through R&D intensity in plant-based frozen alternatives, while Tyson Foods, Inc. dominates poultry-based frozen protein supply to institutional accounts. McCain Foods Limited controls potato-centric frozen appetizer production at manufacturing scale across North American and European processing facilities.
Frozen food encompasses products preserved through rapid temperature reduction to sub-zero states, typically maintained at minus eighteen degrees Celsius or below to arrest microbial activity and enzymatic degradation, thereby extending shelf stability for commercial distribution and household consumption. Frozen ready meals command the largest revenue pool among product type segments as time-constrained consumers prioritize convenience, while frozen seafood differentiates through premium positioning in vacuum pack formats that preserve sensory quality. Distribution through foodservice outlets is accelerating fastest as institutional buyers consolidate procurement toward centralized frozen inventory systems.
The FDA enforces Hazard Analysis Critical Control Point protocols across frozen food manufacturing facilities, while the USDA inspects meat and poultry processing operations to ensure pathogen control compliance throughout the cold chain. The EPA regulates refrigerant emissions from industrial freezing equipment under evolving environmental standards that shape capital expenditure decisions for processing plant upgrades. Stakeholders must monitor how regulatory tightening on per- and polyfluoroalkyl substances in food packaging materials will force reformulation of barrier films used across tray packaging and box packaging formats.
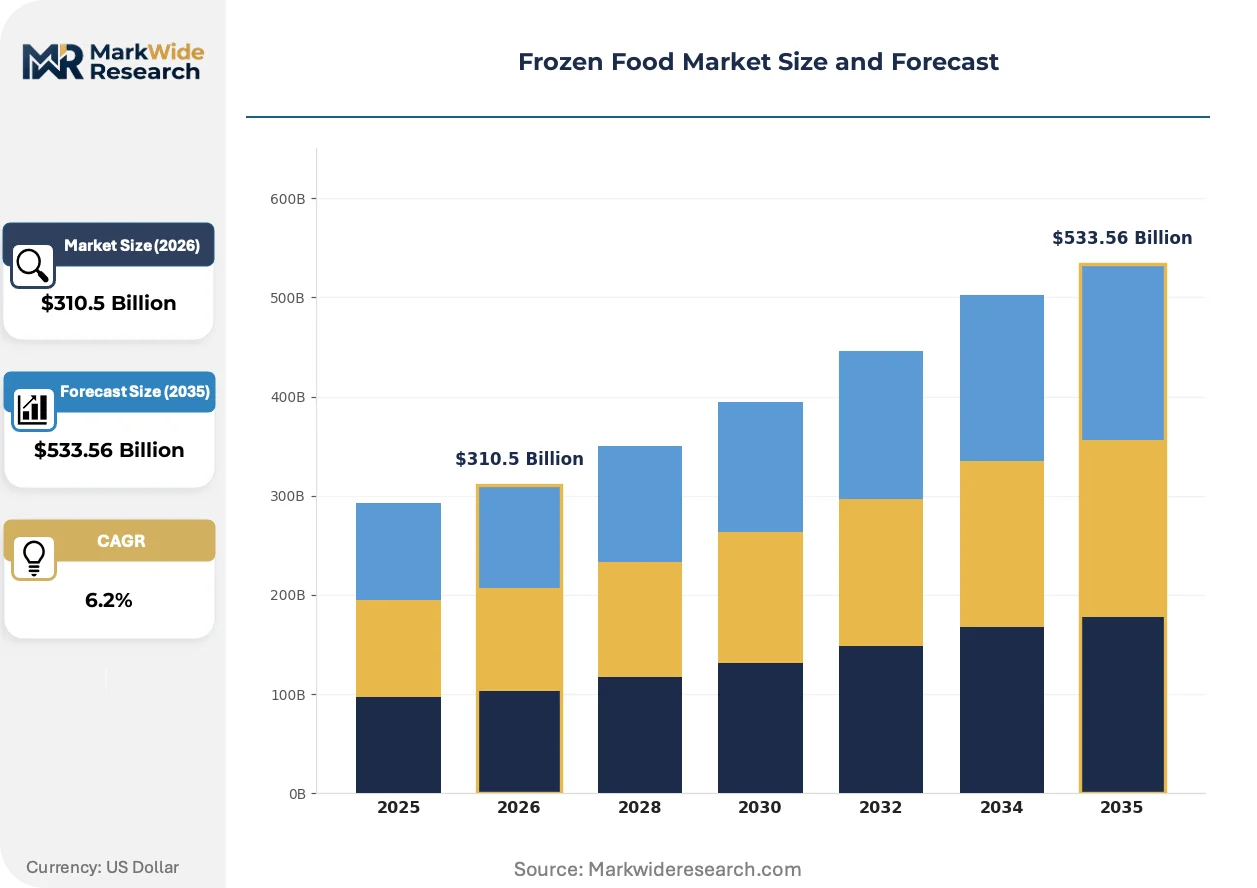
Market Dynamics
Labor scarcity across foodservice channels is accelerating frozen protein procurement as quick service restaurants automate kitchen workflows and centralize inventory management to offset wage inflation.
Growth Catalysts
- Quick Service Restaurant Automation:Chains are expanding frozen protein slots in back-of-house operations to reduce prep time and headcount requirements.
- USDA Pathogen Control Mandates:Enhanced inspection protocols for meat and poultry freezing facilities are standardizing cold-chain compliance, raising barriers for subscale operators.
- Individual Quick Freezing (IQF) Technology:Advanced blast freezing systems preserve cellular structure in vegetables and seafood, extending premium positioning for private-label retail programs.
Market Restraints
- Refrigerant Cost Volatility:Hydrofluorocarbon phase-down schedules under EPA regulations are forcing capital-intensive equipment retrofits at processing plants.
- Concentrated Cold-Storage Capacity:Third-party warehousing in the United States clusters in the Midwest and Southeast, creating regional distribution bottlenecks during peak seasonal demand.
- Fresh-Prepared Substitution:Meal-kit delivery services and refrigerated ready-to-cook formats are capturing convenience-oriented households with shorter perceived shelf-life tradeoffs.
Strategic Opportunities
- Plant-Based Frozen Protein White Space:Pea and mycoprotein formulations in frozen formats remain underdeveloped in retail freezer cases relative to refrigerated alternatives.
- Direct-to-Institution Channel Expansion:Healthcare and education foodservice buyers are consolidating procurement through group purchasing organizations favoring frozen inventory stability.
- EU F-Gas Regulation Tailwind:Natural refrigerant adoption incentives in European processing facilities are opening retrofit contracts for equipment suppliers with CO₂ and ammonia expertise.
Industry Challenges
- Cold-Chain Technician Scarcity:Industrial refrigeration system maintenance requires specialized ammonia handling certifications that lag workforce pipeline expansion.
- Legacy ERP Integration Friction:Temperature-monitoring IoT sensors and automated inventory systems face interoperability gaps with incumbent warehouse management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Food Market |
| Market Size in 2026 | $310.5 Billion |
| Market Size in 2035 | $533.56 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Vegetables, Frozen Ready Meals, Frozen Meat, Frozen Seafood, Frozen Desserts Packaging Type: Plastic Bags, Vacuum Packs, Box Packaging, Tray Packaging, Cartons Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Wholesale Distributors, Foodservice Outlets Customer Type: Household Consumers, Institutional Buyers, Food Retailers, Catering Services, Quick Service Restaurants |
| Companies Covered | Conagra Brands, Inc., General Mills, Inc., Nestlé S.A., Unilever PLC, Tyson Foods, Inc., The Kraft Heinz Company, McCain Foods Limited, Nomad Foods Ltd., GRUPO BIMBO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Food Market Strategic Shifts & Innovations
Freezing technology advancement and regulatory chemistry constraints are converging to reshape capital deployment and product formulation priorities across manufacturing footprints.
Individual quick freezing (IQF) tunnel systems using cryogenic nitrogen or carbon dioxide are consolidating quality differentiation for high-value seafood and fruit segments. Premium retail buyers and foodservice distributors specify IQF certification in procurement tenders. This technology is consolidating supplier bases as smaller freezing operations lack capital for equipment upgrades.
The EPA's phasedown of hydrofluorocarbon refrigerants under the American Innovation and Manufacturing Act is compelling processing plants to evaluate ammonia and transcritical CO₂ systems. Equipment replacement cycles are compressing as facilities face compliance deadlines. Frozen poultry and red meat operations in the southeastern United States are most exposed due to aged installed bases and high cooling load requirements.
Foodservice buyers are consolidating procurement through centralized frozen inventory programs that displace spot purchasing from local distributors. Institutional accounts including healthcare systems and contract catering operators are mandating long-term supply agreements with temperature-verified chain-of-custody documentation. This concentration is most visible in the United States, where group purchasing organizations now control significant frozen protein volume for member facilities.
Frozen Food Market Segmentation
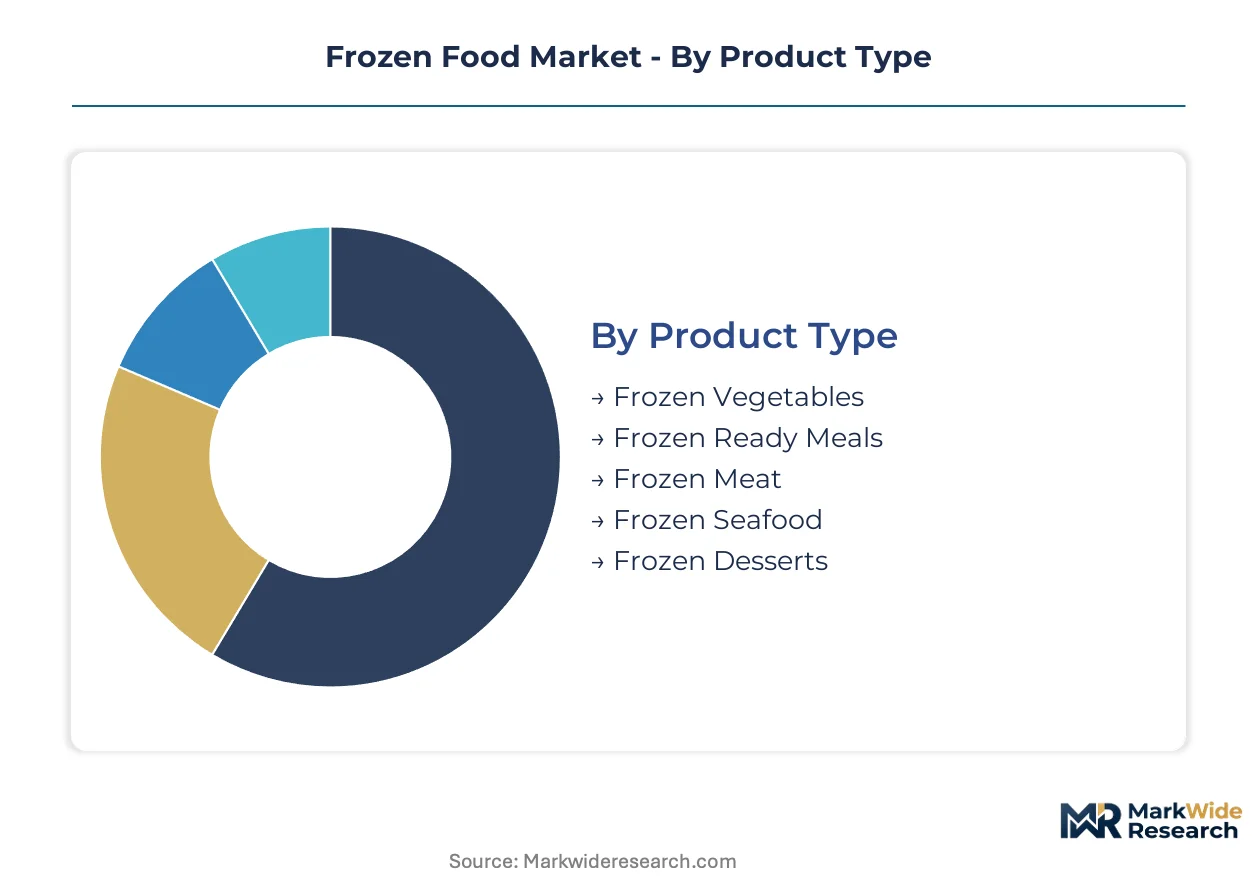
Frozen food segmentation reveals divergent margin structures across product categories, with convenience-driven formats commanding premium positioning while commodity proteins compete on procurement efficiency. Packaging and channel configurations determine cold-chain investment intensity, creating distinct competitive arenas within the same manufacturing footprint.
Product Type:
Standalone frozen products dominate retail freezer space with dedicated shelf positioning, while embedded frozen components integrate into multi-item meal solutions requiring different formulation stability.
- Frozen Ready Meals:Complete meal solutions combining protein, starch, and vegetable components in single-serve or family formats. Demand concentrates in the United States as retailers expand private-label portfolios targeting time-constrained households. Labor scarcity in foodservice channels accelerates institutional procurement of bulk frozen meal formats.
- Frozen Vegetables:Individual quick freezing preserves cellular structure in broccoli, peas, and mixed blends for extended shelf stability. Quick service restaurants in the United States scale procurement for back-of-house automation, displacing fresh prep workflows. Seasonal harvest concentration in California and Midwest growing regions shapes supply timing.
- Frozen Meat:Poultry, beef, and pork cuts maintained at minus eighteen degrees Celsius through USDA-inspected cold chains.
- Frozen Seafood:Vacuum-packed fish and shellfish segments leveraging IQF technology for texture preservation.
- Frozen Desserts:Ice cream, frozen yogurt, and novelty formats requiring dedicated freezer infrastructure distinct from standard frozen food.
Volume placements concentrate in Frozen Ready Meals; the faster expansion belongs to Frozen Vegetables.
Packaging Type:
Cost tier stratification separates premium barrier formats from commodity packaging, with film chemistry investments tracking regulatory pressure on per- and polyfluoroalkyl substances.
- Vacuum Packs:Multi-layer barrier films remove atmospheric oxygen to arrest lipid oxidation in seafood and premium meat segments. Foodservice distributors in the United States specify vacuum-sealed formats for extended inventory holding periods. FDA scrutiny of PFAS migration from packaging materials is forcing film reformulation across tray and box formats.
- Tray Packaging:Rigid polypropylene or aluminum structures supporting microwave-ready meal formats with lidding film seals. Retailers in the United States favor tray formats for vertical freezer display efficiency and brand visibility. Extended producer responsibility regulations in California and New York are shifting material selection toward recyclable mono-polymer structures.
- Plastic Bags:Polyethylene formats for bulk vegetable and protein storage at lowest unit cost.
- Box Packaging:Paperboard cartons with moisture barriers for frozen desserts and breaded appetizers.
- Cartons:Gable-top and rectangular formats for frozen juice concentrates and specialty items.
Tray packaging captures the largest volume commitment; vacuum packs are climbing the fastest on foodservice premiumization.
Distribution Channel:
Customer type determines channel selection, with institutional procurement favoring wholesale consolidation while household demand fragments across retail formats.
- Foodservice Outlets:Direct supply to restaurants, hotels, and contract caterers with temperature-verified chain-of-custody documentation. Group purchasing organizations in the United States now control significant frozen protein volume for healthcare and education member facilities. Centralized frozen inventory programs displace spot purchasing from local distributors.
- Supermarkets:Multi-brand freezer cases with private-label expansion across ready meals and vegetable blends. Retailers in the United States are consolidating supplier bases toward manufacturers with IQF certification and nationwide cold-chain coverage. Slotting fee structures favor established brands with proven velocity metrics.
- Wholesale Distributors:Broadline supply to independent restaurants and smaller institutional accounts.
- Online Retailers:Direct-to-consumer frozen delivery requiring last-mile cold-chain integrity.
- Convenience Stores:Limited freezer space prioritizing high-velocity single-serve and handheld formats.
Supermarkets anchor current volume; foodservice outlets are gaining share fastest on procurement consolidation.
Customer Type:
Maturity differentiation separates established household penetration from emerging institutional automation trends, with margin profiles inversely tracking purchase scale.
- Quick Service Restaurants:Chain operators automating kitchen workflows through centralized frozen protein procurement. Labor cost inflation in the United States accelerates back-of-house frozen slot expansion to reduce headcount and prep time. Speed-of-service requirements favor pre-portioned frozen formats over fresh preparation.
- Institutional Buyers:Healthcare systems, education facilities, and contract catering operators mandating long-term supply agreements. Procurement through group purchasing organizations in the United States favors frozen inventory stability over fresh delivery complexity. USDA pathogen control mandates standardize supplier qualification criteria.
- Household Consumers:Individual purchasers prioritizing convenience and extended shelf life for home freezer storage.
- Catering Services:Event and corporate dining operators with variable demand requiring inventory flexibility.
- Food Retailers:Supermarket and convenience store operators merchandising frozen categories for margin contribution.
Household consumers maintain the deepest volume base; quick service restaurants show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwest cold-storage tax credits in the United States are concentrating frozen food manufacturing capacity near Chicago and Omaha distribution nodes. These incentives accelerate processing plant consolidation while reshaping regional procurement patterns for institutional buyers.
United States
Private-label expansion at Kroger and Albertsons drives frozen ready-meal formulation investment. The FDA enforces updated Listeria control guidelines across processing facilities. Chicago anchors North American cold-chain logistics with third-party warehousing clustering along I-80 corridor routes.
Germany
Discount retail chains Aldi and Lidl scale frozen vegetable private-label sourcing for price-sensitive households. The EU F-Gas Regulation accelerates ammonia refrigerant retrofits in processing plants. Bavaria's Ingolstadt region hosts equipment suppliers specializing in transcritical CO₂ freezing systems for meat operations.
China
Quick service restaurant chains expand frozen protein procurement as labor costs rise in tier-one cities. SAMR implements stricter cold-chain traceability requirements for imported seafood. Yangtze River Delta processing zones near Shanghai consolidate IQF technology adoption for export-oriented vegetable operations.
United Kingdom
Meal-kit subscription fatigue redirects convenience demand toward premium frozen ready meals. The FSA enforces enhanced allergen labeling for frozen composite foods. London's M25 orbital distribution network concentrates temperature-controlled warehousing for foodservice channel supply.
Japan
Aging demographics expand single-serve frozen meal demand in metropolitan convenience retail. METI promotes energy-efficient freezing equipment subsidies under carbon neutrality targets. Osaka-Kobe industrial corridor maintains seafood IQF processing dominance for domestic and export markets.
Frozen Food Market Key Industry Players
Top-tier vendors anchor multinational scale advantages, while mid-tier specialists compete on regional cold-chain density and category-specific formulation expertise. The market exhibits tiered consolidation with protein-centric conglomerates controlling institutional procurement channels and diversified food manufacturers defending retail freezer space. Strategic archetypes include vertically integrated protein processors, R&D-intensive plant-based innovators, and private-label manufacturing platforms. Competitive moves center on M&A-driven category expansion and capital-intensive equipment modernization to meet refrigerant phase-down deadlines.
Within the diversified food manufacturer tier, Nestlé S.A. and General Mills, Inc. exemplify portfolio breadth across frozen meal and dessert categories. Tyson Foods, Inc. occupies a distinct position as a protein-anchored supplier with institutional channel penetration. These three entities represent divergent strategic postures: multinational brand architecture, North American retail concentration, and protein supply chain control respectively.
| Leading Market Players |
|---|
| Conagra Brands, Inc. |
| General Mills, Inc. |
| Nestlé S.A. |
| Unilever PLC |
| Tyson Foods, Inc. |
| The Kraft Heinz Company |
| McCain Foods Limited |
| Nomad Foods Ltd. |
| GRUPO BIMBO |
| Others |
Cost & Logistics Intelligence
Ammonia-certified refrigeration technicians in the United States Midwest command wage premiums that compress margins for regional processors while widening spreads between premium IQF-certified and economy-grade frozen protein tiers.
Pricing Analysis
Short lead-time premiums separate frozen protein procurement contracts from spot-market inventory discounts in the United States foodservice channel. Three-tier pricing structure across premium, standard, and economy levels tracks USDA inspection tier and IQF certification status. Pricing pressure stems from refrigerant retrofit capital requirements passing through to contract rates. Quick service restaurants exhibit highest price sensitivity among buyer archetypes, while healthcare group purchasing organizations absorb premiums for temperature-verified chain-of-custody documentation.
Supply Chain Analysis
Reverse-logistics flows for temperature-compromised frozen inventory concentrate disposal costs in the United States Southeast, where third-party cold-storage capacity clusters around Atlanta and Jacksonville distribution nodes. Supply draws from China for IQF processing equipment, Argentina for beef raw material, and Vietnam for pangasius whitefish feedstock. Single-source vulnerability runs through concentrated Midwest ammonia refrigeration engineering capacity. Distribution runs through foodservice broadline distributors consolidating toward national group purchasing organization contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold-storage capacity scarcity in the United States props pricing power for incumbent operators with existing ammonia infrastructure, constraining volume response to demand expansion.
For Market Incumbents: Hedge refrigerant compliance exposure by accelerating transcritical CO₂ equipment pilots in European processing facilities ahead of EPA phase-down deadlines. Defend margin position through backward integration into pea protein isolate supply for plant-based frozen formulations, offsetting commodity poultry cost volatility. Prioritize group purchasing organization contract renewals before healthcare procurement consolidation peaks.
For New Entrants and Emerging Players: Enter via direct-to-institution channels serving education foodservice buyers in the United States Southwest, where cold-storage infrastructure gaps create procurement bottlenecks for incumbent distributors. Target mycoprotein frozen protein white space in retail freezer cases, where refrigerated alternative saturation leaves frozen formats underdeveloped. Deploy temperature-monitoring IoT integration as differentiated service layer for healthcare accounts.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale IQF equipment suppliers given EPA refrigerant retrofit mandates accelerating replacement cycles across southeastern United States poultry operations. Long-term viability favors manufacturers with captive ammonia handling certifications and established USDA inspection protocols. Monitor EPA enforcement intensity on hydrofluorocarbon phase-down timelines as inflection signal for equipment demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant System Retrofit | EPA hydrofluorocarbon phase-down deadlines compress equipment replacement cycles for aging ammonia infrastructure. |
| Plant-Based Protein Line Extension | Nestlé R&D intensity in frozen alternatives validates category expansion for pea and mycoprotein formulations. |
| Group Purchasing Organization Partnership | Healthcare procurement consolidation favors suppliers with nationwide cold-chain coverage and temperature-verified documentation. |
| IQF Certification Investment | Foodservice distributors specify cryogenic nitrogen tunnel systems for premium seafood and vegetable texture preservation. |
| Direct-to-Institution Channel Buildout | Education and healthcare buyers displace spot purchasing through centralized frozen inventory programs. |
Research Approach
Independent corroboration across FDA inspection records, USDA cold-chain compliance filings, and EPA refrigerant equipment registrations underwrites the qualitative findings on regulatory enforcement intensity. Primary interviews with frozen food plant managers, foodservice procurement directors at group purchasing organizations, ammonia refrigeration system engineers, and retail category buyers combined with secondary validation from customs trade data, SEC 10-K filings of protein processors, and Nielsen retail audit data. Bottom-up volume modeling across product type, packaging format, distribution channel, and customer type segments triangulated against top-down macroeconomic anchors.
Comparable-period anchoring to historical frozen protein demand cycles calibrated the projection horizon against labor cost inflation trajectories and quick service restaurant automation adoption curves. Segmentation dimensions modeled include product category, packaging barrier technology tier, channel concentration level, and institutional buyer archetype. CAGRs derived from regression-weighted scenario outputs incorporating refrigerant retrofit capital deployment timing and private-label expansion velocity across United States retailers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden EPA enforcement acceleration or Midwest cold-storage capacity expansion. Practitioners should monitor FDA Listeria guideline revision timelines and ammonia technician certification pipeline expansion for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Middle East and Africa Frozen Food Market
Processed and Frozen Foods
US Frozen Food Market
Processed and Frozen Foods
Freeze Dried Melt Market
Processed and Frozen Foods
Cold Storage Market
Processed and Frozen Foods
Dehydrated Potato Market
Processed and Frozen Foods
Canned Vegetables Market
Processed and Frozen Foods
South America Frozen Desserts Market
Processed and Frozen Foods
Spiral Freezer Market
Processed and Frozen Foods
Frozen Pizza Market
Processed and Frozen Foods
Chilled Soup Market
Processed and Frozen Foods
Freeze Dried Mangos Market
Processed and Frozen Foods
Frozen Processed Meat Market
Processed and Frozen Foods
Europe Frozen Desserts Market
Processed and Frozen Foods
Frozen Dumplings Market
Processed and Frozen Foods
Global Frozen Fish and Seafood Market
Processed and Frozen Foods
Europe Frozen Pizza Market