
 Ice Structuring Protein Market | 2026-2036
Ice Structuring Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Structuring Protein Market Analytics
Buyer concentration among large food manufacturers is realigning procurement patterns across the ice structuring protein value chain. Kaneka Corporation leverages its fermentation expertise to supply recombinant protein grades at commercial scale. Nichirei Corporation anchors Japanese domestic demand through integrated cold-chain partnerships with processed seafood and frozen dessert producers. Unilever competes by embedding these proteins directly into captive ice cream formulation pipelines across European manufacturing sites.
Ice structuring proteins are a class of polypeptides that bind to ice crystals and modulate their growth, typically derived from fish blood serum or produced via microbial recombinant expression at active concentrations of 0.01–0.1% w/w; their primary commercial purpose is to control ice recrystallization in frozen foods, cell preservation media, and cosmetic emulsions. Natural proteins still occupy the largest revenue share due to established extraction from Antarctic fish species, though recombinant proteins are displacing wild-source dependence as biotechnology end users scale GMP-compliant production. Food and beverages dominates application volume, while pharmaceuticals commands the steepest unit economics due to cryopreservation stringency.
FDA oversight of food additive petitions and EFSA Novel Food assessments shape market access timelines for new protein sources, with Japan's Ministry of Health, Labour and Welfare adding layer-specific safety documentation for recombinant variants. The EU F-Gas Regulation indirectly pressures cold-chain efficiency, amplifying interest in proteins that reduce freeze-thaw energy intensity. Stakeholders must monitor how regulatory divergence between FDA GRAS self-determination and EFSA centralized pre-market approval reshapes geographic launch sequencing.
Market Dynamics
Recombinant expression platforms in microbial hosts are displacing wild-source extraction from Antarctic fish, compressing supply timelines and requalifying food additive petitions across FDA, EFSA, and Japan's Ministry of Health, Labour and Welfare jurisdictions.
Growth Catalysts
- EU F-Gas Regulation:Cold-chain efficiency mandates amplify demand for proteins that reduce freeze-thaw energy intensity in frozen dessert manufacturing.
- Biotech clusters in Japan:METI-backed fermentation infrastructure enables commercial-scale recombinant production with GMP-compliant documentation.
- Cryopreservation protocols:Cell therapy developers are integrating these proteins into preservation media for biologics manufacturing.
Market Restraints
- Regulatory friction:EFSA Novel Food assessments impose 18-24 month pre-market approval timelines that delay European launches.
- Supply concentration risk:Fermentation capacity for pharmaceutical-grade proteins clusters in Japan and select EU biotech hubs.
- Input cost volatility:Recombinant production depends on refined carbohydrate feedstocks and specialized bioreactor media formulations.
Strategic Opportunities
- Underpenetrated geographies:South Korean frozen seafood processors represent untapped demand for ice recrystallization control.
- Regulatory tailwind:Japan's streamlined recombinant food additive pathway accelerates market access relative to EU centralized review.
- Technology convergence:Precision fermentation combined with AI-driven protein engineering is shortening strain development cycles.
Industry Challenges
- Specialized talent scarcity:Industrial microbiologists with GMP fermentation experience command premium compensation in biotech labor markets.
- Certification timeline compression:Dual-track FDA GRAS self-determination and EFSA Novel Food submissions strain regulatory affairs capacity.
- Supply chain reconfiguration:Shifting from wild-catch Antarctic sourcing to microbial production requires new cold-chain logistics partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Structuring Protein Market |
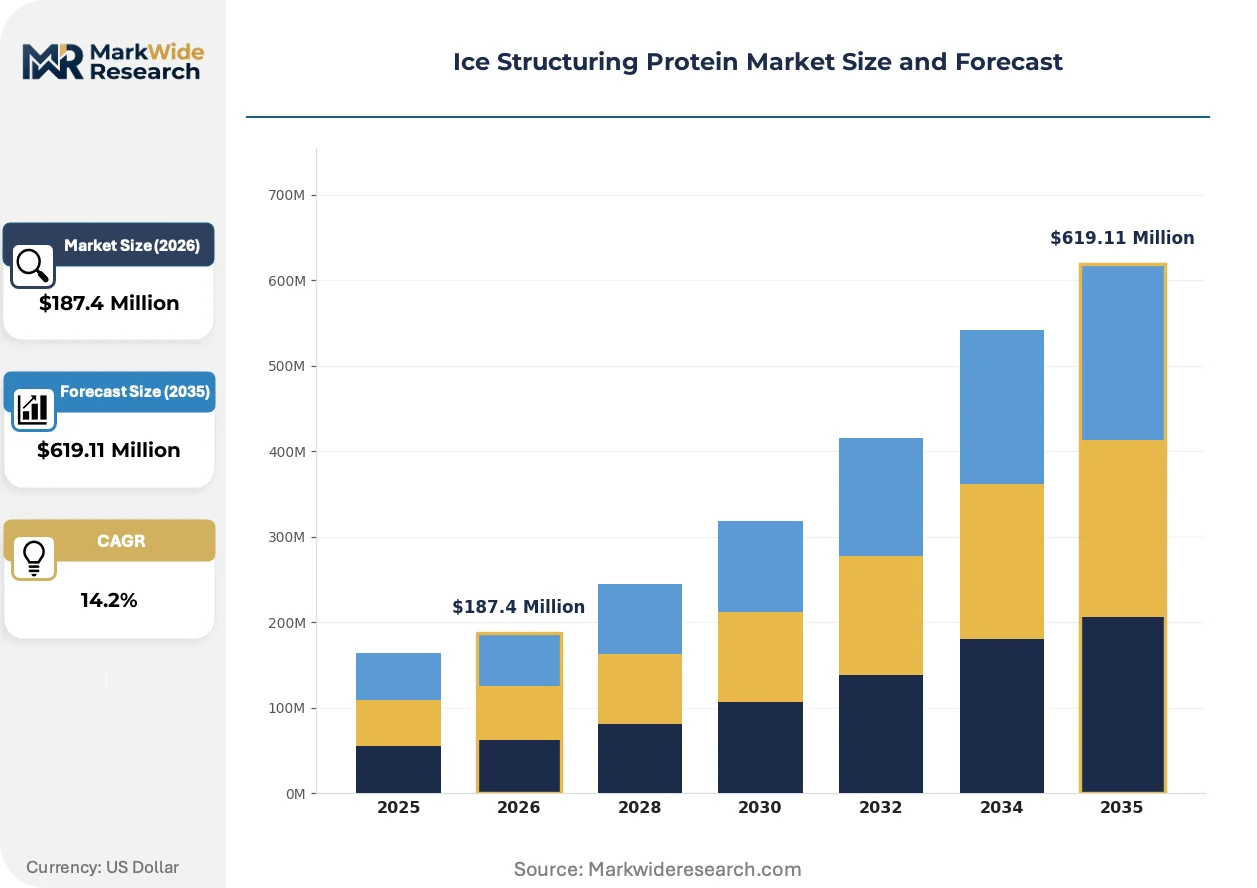
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Proteins, Synthetic Proteins, Recombinant Proteins, Peptides Application: Food & Beverages, Pharmaceuticals, Cosmetics, Biotechnology End User: Food Manufacturers, Personal Care Companies, Research Institutions, Nutraceutical Firms Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Kaneka Corporation, Nichirei Corporation, A/F Protein Inc., Unilever, Sirona Biochem, ProtoKinetix Inc., Ingredion Incorporated, Shanghai Yu Tao Industrial Co., Ltd., Cargill, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Structuring Protein Market Evolving Landscape
Expression system diversification and regulatory pathway optimization are compressing development timelines while expanding addressable applications beyond frozen foods into cell preservation and cosmetic formulations.
Precision fermentation using Pichia pastoris and Komagataella phaffii chassis organisms is expanding into pharmaceutical-grade production, displacing legacy bacterial systems that struggled with post-translational modifications. Contract development and manufacturing organizations in Japan and Germany are scaling 10,000-liter bioreactor trains to meet food and biopharma dual demand. This capacity expansion is compressing unit economics and enabling tiered pricing stratification across research, food, and clinical grades.
EFSA's evolving Novel Food guidance on recombinant proteins is tightening toxicology requirements while creating equivalence pathways for well-characterized microbial hosts. Food manufacturers are responding by front-loading safety documentation and engaging scientific advisory panels before formal submission. The regulatory burden falls heaviest on startups lacking established regulatory affairs infrastructure.
Long-term offtake agreements are displacing spot purchasing in frozen dessert manufacturing, with multinational food corporations locking in three-to-five-year supply contracts. This contractual shift concentrates procurement leverage among large buyers and marginalizes smaller regional processors lacking volume commitments. The pattern is most pronounced in European manufacturing sites where cold-chain energy costs drive formulation standardization.
Ice Structuring Protein Market Segmentation
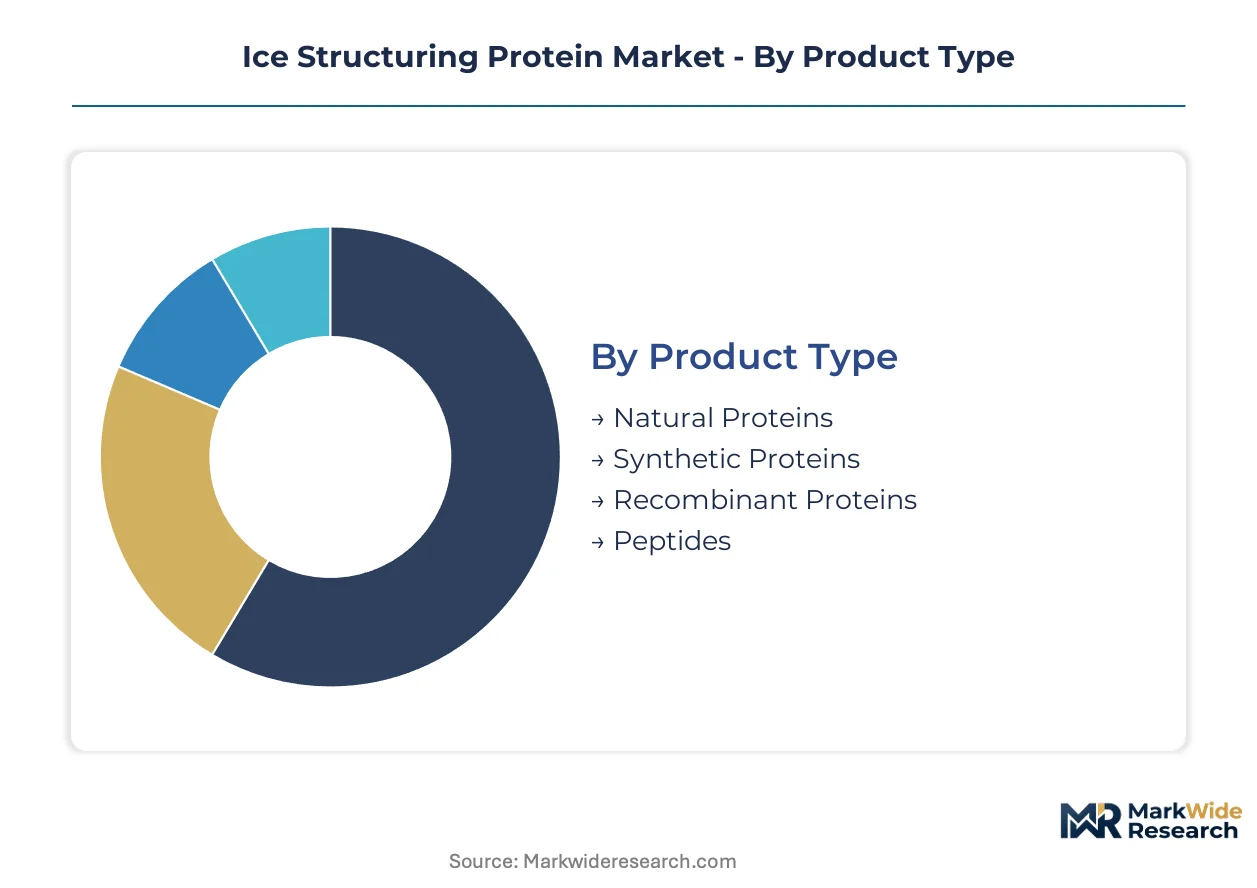
Segmentation in the ice structuring protein market reveals how procurement patterns diverge between commodity food additive buyers and specialized pharmaceutical-grade purchasers. Technical specifications, regulatory documentation requirements, and volume thresholds reshape competitive positioning across each category boundary.
Product Type:
Standalone protein formulations dominate food manufacturing procurement, while embedded recombinant systems serve biopharma integration pipelines.
- Natural Proteins:Extracted primarily from Antarctic fish blood serum with established extraction protocols and decades of safety documentation. Demand concentrates in Japanese frozen seafood processing, where traditional supply chains and consumer familiarity with marine-derived additives sustain procurement despite recombinant alternatives.
- Recombinant Proteins:Produced via microbial fermentation in Pichia pastoris or Komagataella phaffii chassis organisms at active concentrations of 0.01–0.1% w/w. Pharmaceutical-grade demand in Germany and Japan drives GMP-compliant production scale-up, with EFSA Novel Food assessments and FDA GRAS petitions reshaping geographic launch sequencing.
- Synthetic Proteins:Chemically synthesized analogs with precise sequence control for cosmetic emulsion applications.
- Peptides:Short-chain variants engineered for targeted ice-binding affinity in research-scale cell preservation protocols.
Volume placements concentrate in Natural Proteins; the faster expansion belongs to Recombinant Proteins.
Application:
Cost tier stratification separates commodity food additive buyers from premium pharmaceutical and cosmetic purchasers willing to absorb documentation and certification premiums.
- Food & Beverages:Frozen dessert manufacturers and cryopreserved meat processors embed these proteins directly into formulation pipelines to control ice recrystallization and reduce freeze-thaw energy intensity. EU F-Gas Regulation compliance pressures amplify procurement across European manufacturing sites.
- Pharmaceuticals:Cell therapy developers integrate proteins into preservation media for biologics manufacturing, with cryopreservation stringency commanding the steepest unit economics. Japan's streamlined recombinant food additive pathway accelerates market access relative to EU centralized review timelines.
- Cosmetics:Emulsion stability applications in premium skincare formulations.
- Biotechnology:Research-grade supply for academic and institutional cryopreservation protocol development.
Revenue concentration sits with Food & Beverages; Pharmaceuticals climbs the fastest.
End User:
Customer type fragmentation splits between large-scale integrated processors and fragmented research-scale purchasers with divergent volume and documentation requirements.
- Food Manufacturers:Multinational frozen dessert and processed seafood corporations lock in three-to-five-year supply contracts, concentrating procurement leverage and marginalizing smaller regional processors lacking volume commitments.
- Research Institutions:Academic and government laboratories drive demand for research-grade proteins with flexible specification tolerances and smaller batch requirements.
- Personal Care Companies:Cosmetic formulators seeking emulsion stability in premium product lines.
- Nutraceutical Firms:Emerging purchasers exploring protein integration into functional food formulations.
Contract value aggregates in Food Manufacturers; Research Institutions expand most quickly.
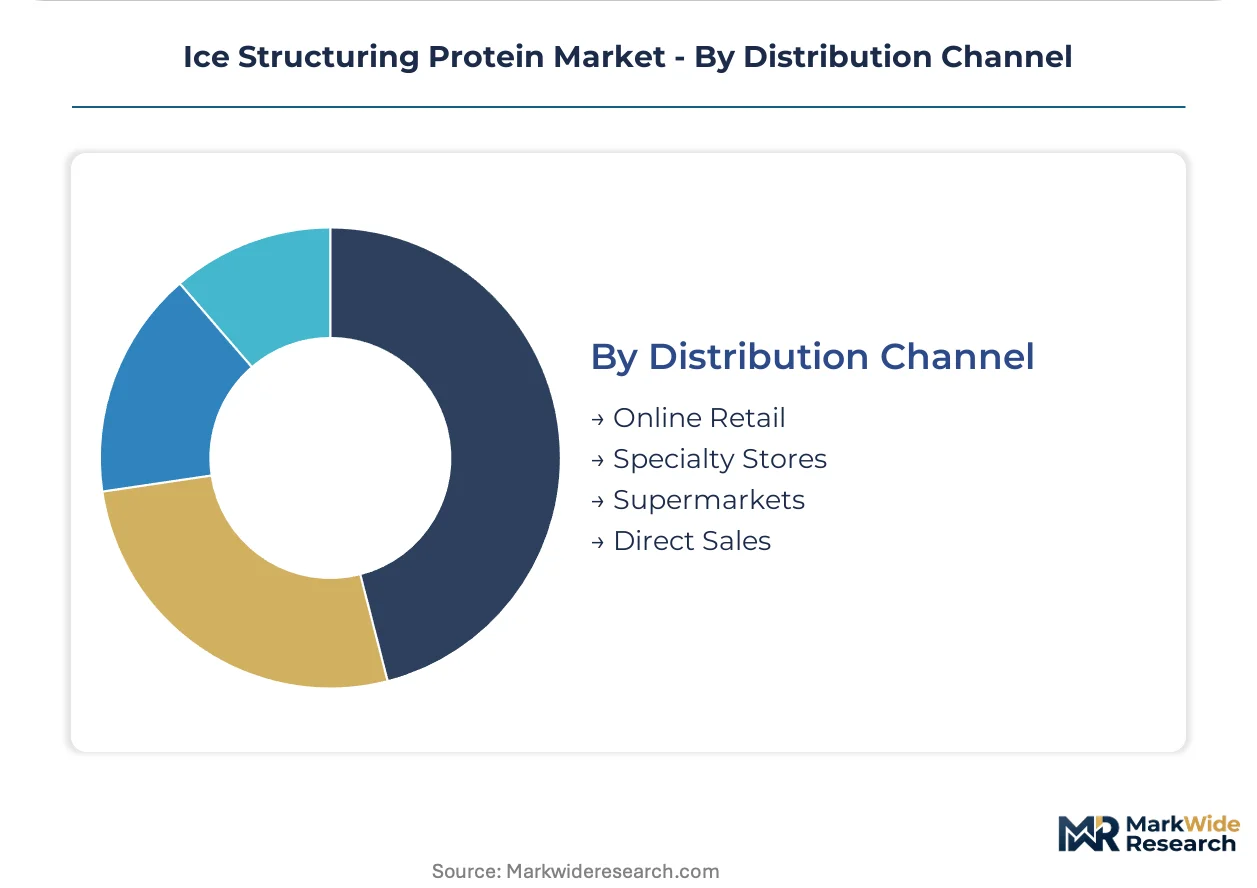
Distribution Channel:
Supply concentration in fermentation hubs reshapes channel configuration, with direct relationships dominating pharmaceutical-grade transactions.
- Direct Sales:Pharmaceutical and large food manufacturers establish long-term offtake agreements with Japanese and German fermentation facilities, bypassing intermediaries to secure GMP-compliant documentation and volume guarantees.
- Specialty Stores:Research-grade protein distribution through scientific supply houses serving institutional purchasers with technical support requirements.
- Online Retail:Small-volume research-grade procurement by fragmented academic and startup purchasers.
- Supermarkets:Limited consumer-facing protein products in specialized functional food categories.
Transaction volume flows through Direct Sales; Online Retail gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese food manufacturers command the largest procurement volumes for ice structuring proteins, while German pharmaceutical developers and South Korean seafood processors are accelerating their integration of these polypeptides into formulation pipelines.
Japan
Frozen dessert and processed seafood manufacturers drive domestic consumption through established cold-chain partnerships. METI-backed biotech clusters in the Kanto region provide GMP-compliant fermentation infrastructure for recombinant protein scale-up. Tokyo-Osaka industrial corridors anchor commercial production with integrated supply agreements linking Kaneka Corporation to multinational food processors.
Germany
Cell therapy developers in Bavaria and Baden-Württemberg integrate pharmaceutical-grade proteins into cryopreservation media for biologics manufacturing. EFSA Novel Food assessments impose 18-24 month pre-market timelines that delay recombinant launches relative to other jurisdictions. Munich-Stuttgart biotech corridors host contract manufacturing organizations scaling 10,000-liter bioreactor capacity to serve dual food and pharma demand.
United States
FDA GRAS self-determination pathways enable faster market access for food additive petitions compared to centralized European review. Frozen dessert manufacturers embed proteins directly into captive formulation pipelines to reduce freeze-thaw energy intensity. Greater Boston and San Diego biotech clusters concentrate cell preservation research driving pharmaceutical-grade procurement.
South Korea
Seafood processors in Busan-Ulsan represent underpenetrated demand for ice recrystallization control in cryopreserved fish products. MFDS regulatory frameworks for novel food ingredients are evolving to accommodate recombinant protein submissions. Daegu-Gyeongbuk industrial zones are emerging as fermentation capacity hubs serving regional processed food manufacturers.
United Kingdom
Ice cream formulators leverage EU F-Gas Regulation compliance pressures to justify protein adoption for cold-chain efficiency. Post-Brexit divergence from EFSA centralized review creates parallel submission requirements through the Food Standards Agency. London-Southeast research institutions drive academic demand for research-grade proteins in cryopreservation protocol development.
Ice Structuring Protein Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue precision fermentation and AI-driven protein engineering to compress strain development cycles. The vendor base stratifies across three tiers: integrated fermentation specialists with GMP documentation capabilities, regional extraction operations serving natural protein demand, and research-stage startups advancing synthetic analogs. Dominant competitive moves include long-term offtake agreements that lock in three-to-five-year supply commitments and backward integration into captive bioreactor capacity.
Within the integrated fermentation tier, Kaneka Corporation and Nichirei Corporation exemplify Japanese producers leveraging established METI-backed infrastructure. Unilever occupies a position as a downstream formulator embedding proteins directly into captive manufacturing pipelines. Shanghai Yu Tao Industrial Co., Ltd. represents Chinese supply capability serving regional processed food demand.
| Leading Market Players |
|---|
| Kaneka Corporation |
| Nichirei Corporation |
| A/F Protein Inc. |
| Unilever |
| Sirona Biochem |
| ProtoKinetix Inc. |
| Ingredion Incorporated |
| Shanghai Yu Tao Industrial Co., Ltd. |
| Cargill, Incorporated |
| Others |
Value Network & Pricing Analysis
Carbohydrate feedstock costs for Pichia pastoris fermentation cascade through three distinct pricing tiers, with pharmaceutical-grade recombinant proteins commanding premiums over food-grade equivalents as GMP documentation requirements accumulate downstream. Cold-chain logistics expenses from Japanese and German bioreactor hubs to European frozen dessert manufacturers further stratify landed costs across buyer segments.
Pricing Analysis
Volume placements concentrate in long-term offtake agreements for food-grade natural proteins, while margins concentrate in pharmaceutical-grade recombinant tiers where cryopreservation stringency commands certification premiums. Price differentiation rests on GMP compliance level and volume scale, with multinational frozen dessert manufacturers leveraging three-to-five-year contracts to compress unit costs. Pricing pressure stems from recombinant production scale-up in METI-backed Japanese clusters, eroding wild-source extraction premiums. Research institutions exhibit highest price sensitivity due to fragmented batch requirements; cell therapy developers show lowest sensitivity due to cryopreservation protocol criticality.
Supply Chain Analysis
Regional distribution centers in Tokyo-Osaka and Munich-Stuttgart biotech corridors anchor hub-and-spoke patterns for pharmaceutical-grade shipments, while food-grade volumes flow through direct manufacturer relationships bypassing intermediaries. Supply concentrates in Japan, Germany, and select United States biotech clusters. Raw material dependencies include refined carbohydrate feedstocks, specialized bioreactor media formulations, and Antarctic fish blood serum for natural extraction tiers. Single-source vulnerability runs through fermentation capacity concentration in Japanese METI-backed facilities. Distribution runs through direct sales channels for pharmaceutical and large food manufacturers, with research-grade volumes transiting specialty scientific supply houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around fermentation scale and regulatory documentation capabilities, with EFSA Novel Food assessment timelines forcing capital-constrained startups toward acquisition or exit.
For Market Incumbents: Deepen backward integration into captive bioreactor capacity in the Kanto region to secure GMP-compliant production volumes against emerging precision fermentation entrants. Lock in three-to-five-year offtake agreements with multinational frozen dessert manufacturers before Japanese competitors expand Munich-Stuttgart capacity. METI infrastructure subsidies present a timing threat to European producers lacking equivalent state support. For New Entrants and Emerging Players: FDA GRAS self-determination in the United States opens a window for faster market entry relative to EFSA centralized review timelines, enabling revenue generation while European submissions progress. Target South Korean frozen seafood processors in Busan-Ulsan, where MFDS regulatory frameworks are evolving and incumbent penetration remains limited. Pursue contract manufacturing partnerships with established Japanese fermentation facilities to bypass capital-intensive capacity buildout. For Investors and Strategic Acquirers: Long-term offtake agreement announcements from multinational food corporations are the leading indicator that recombinant protein supply is tightening and acquisition premiums are compressing. Position for five-to-ten-year viability in precision fermentation platforms with AI-driven strain engineering capabilities, as these technologies shorten development cycles and displace legacy extraction methods. Target acquisition archetype: research-stage startups with validated microbial hosts but lacking regulatory affairs infrastructure to navigate dual-track FDA and EFSA submissions.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | 10,000-liter bioreactor trains in Japanese METI-backed clusters compress unit economics for pharmaceutical-grade output. |
| Regulatory Pathway Optimization | Front-loaded toxicology documentation accelerates EFSA Novel Food equivalence pathways for well-characterized microbial hosts. |
| Long-Term Supply Agreement | Three-to-five-year offtake contracts with Unilever and Nichirei concentrate procurement leverage among volume-committed buyers. |
| AI-Driven Protein Engineering | Strain development cycle compression enables faster response to cell therapy developer formulation requirements. |
| Cold-Chain Logistics Partnership | Integrated distribution agreements with Tokyo-Osaka industrial corridors reduce freeze-thaw energy intensity for European manufacturers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with fermentation facility managers, regulatory affairs leads at protein suppliers, frozen dessert formulation scientists, and cell therapy preservation protocol developers. FDA GRAS petitions, EFSA Novel Food assessments, and Japan Ministry of Health, Labour and Welfare submissions provided regulatory trajectory validation. Bottom-up volume modeling from bioreactor capacity utilization combined with top-down demand aggregation from food manufacturer procurement disclosures.
Data-stream reconciliation across production capacity databases, import-export statistics, and end-user procurement patterns informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application grade, end-user scale, and geographic regulatory cluster. CAGRs derived from fitted growth curves anchored to documented capacity expansion timelines and offtake agreement durations. Industry-specific forecast inputs encompass METI subsidy disbursement schedules and EFSA guidance evolution timelines for recombinant protein toxicology requirements.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation combined with AI-driven protein engineering would alter the outlook if strain development cycles compress faster than baseline assumptions. Forecasts reflect documented capacity expansion commitments and regulatory submission timelines, with recombinant production scale-up rates and EFSA assessment duration volatility representing primary revision risks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Frozen Pork Belly Market
Processed and Frozen Foods
Frozen Noodles and Rice Products Market
Processed and Frozen Foods
Global Frozen Fish and Seafood Market
Processed and Frozen Foods
North America Frozen Finger Chips Market
Processed and Frozen Foods
North America Dehydrated Food Market
Processed and Frozen Foods
Freeze Dried Fruit Extract Market
Processed and Frozen Foods
Freeze Dried Tropical Fruits Market
Processed and Frozen Foods
Frozen Pizza Market
Processed and Frozen Foods
Frozen Food Market
Processed and Frozen Foods
Cold Cuts Market
Processed and Frozen Foods
Frozen Dough Market
Processed and Frozen Foods
Vegan Frozen Pizza Market
Processed and Frozen Foods
Middle East and Africa Frozen Bread Market
Processed and Frozen Foods
Frozen Sardine Market
Processed and Frozen Foods
Frozen Meat and Fish Market
Processed and Frozen Foods
Global Frozen Breakfast Entrees/Sandwiches Market