
 Global Chilled and Deli Foods Market | 2026-2036
Global Chilled and Deli Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chilled and Deli Foods Market Intelligence
The EU's Corporate Sustainability Reporting Directive (CSRD) is consolidating market access for suppliers who can document their environmental footprint, rewriting the cost-of-entry calculus. This favors large-scale manufacturers with sophisticated supply chain tracking systems. The Kraft Heinz Company leverages its extensive distribution network to meet varied regional tastes and regulatory requirements. Tyson Foods, Inc. specializes in the processed meats category, controlling a significant portion of its protein supply chain for quality assurance.
Chilled and deli foods encompass a category of perishable food products requiring continuous refrigeration between 0°C and 5°C to maintain safety and quality. These items are typically ready-to-eat or ready-to-heat, offering convenience through minimal preparation time. Ready Meals and Prepared Salads represent high-growth product segments, driven by consumer demand for healthy, quick options. While Supermarkets remain the dominant distribution channel, online retailers are gaining share through subscription models and rapid delivery services in metropolitan areas.
Food safety regulations enforced by bodies like the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) dictate stringent cold chain management and allergen labeling protocols. Adherence to ISO 22000 for food safety management systems is becoming a prerequisite for competing in top-tier markets. Success for market participants will be determined by their ability to navigate the interplay between food safety compliance, sustainable packaging innovation, and evolving consumer dietary preferences.
Market Dynamics
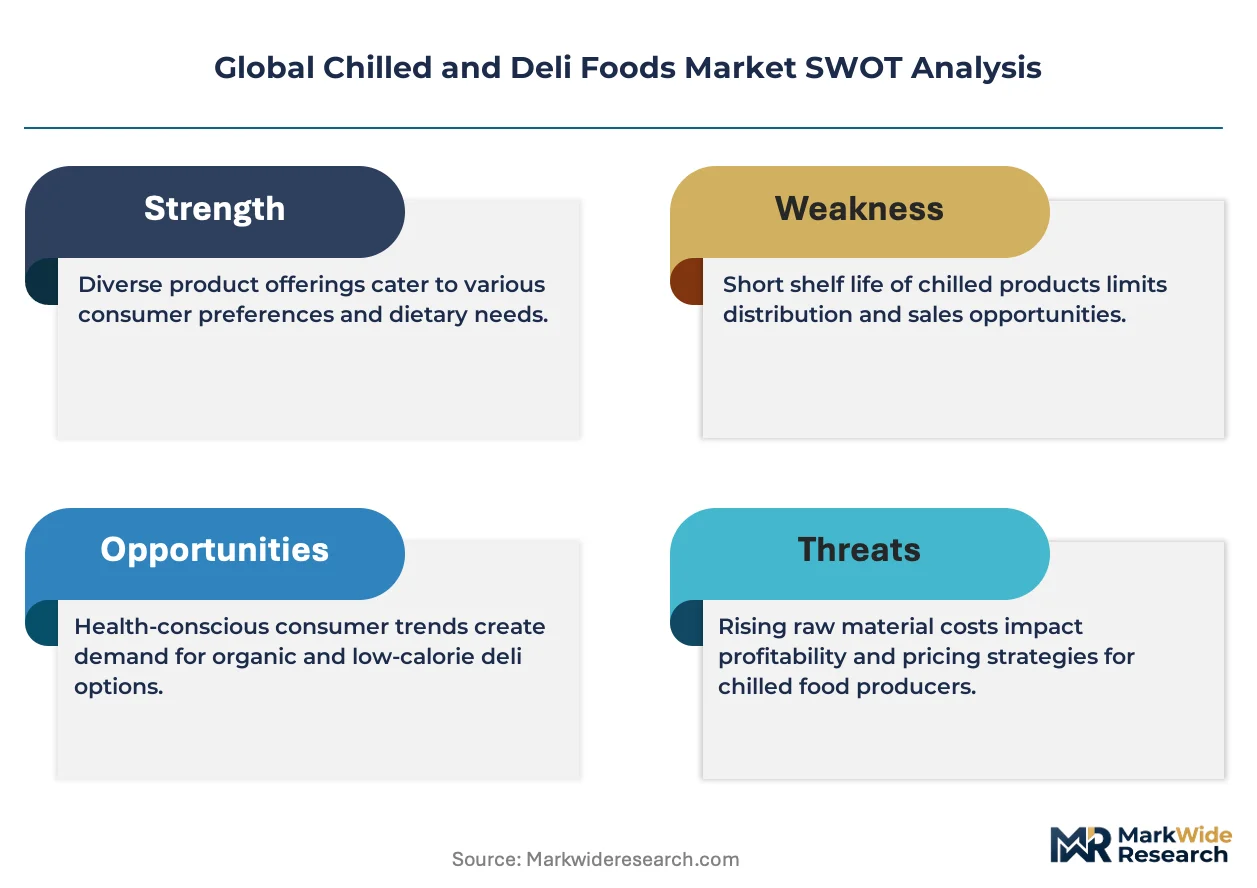
The central tension in the chilled and deli foods market is the collision between stringent new sustainability mandates, such as the EU's Farm to Fork Strategy, and the non-negotiable energy intensity required for cold chain logistics and food safety.
Growth Catalysts
- Urbanization in Asia:Rapid urban expansion in cities across China and India fuels consumer need for convenient, ready-to-eat meal solutions like prepared salads and chilled meals, aligning with fast-paced lifestyles.
- Corporate Foodservice Demand:Corporate cafeterias and institutional food service providers are increasingly sourcing high-quality, pre-prepared chilled and deli items to streamline kitchen operations and offer diverse menu options with minimal labor.
- Sustainability Reporting Mandates:The EU's Corporate Sustainability Reporting Directive (CSRD) creates a preference for suppliers with documented, transparent supply chains, providing an advantage for those who invest in environmental footprinting.
Market Restraints
- Energy Price Volatility:The market's reliance on continuous refrigeration makes operating costs highly sensitive to fluctuations in electricity and fuel prices, impacting margins across the entire cold chain from production to retail.
- Protein Supply Concentration:Dependence on a small number of large-scale meat processors for key inputs like poultry and beef creates supply chain vulnerabilities and pricing pressures for downstream deli food manufacturers.
- Inherent Perishability:The short shelf-life of chilled foods, despite modified atmosphere packaging, creates a constant risk of spoilage and food waste, limiting distribution reach and inventory flexibility for retailers.
Strategic Opportunities
- Plant-Based Deli Alternatives:Developing and marketing plant-based versions of traditional deli meats and prepared salads caters to growing vegan and flexitarian consumer segments, opening a new product category.
- Subscription Box Models:Direct-to-consumer subscription services for curated meal kits and prepared salads offer a channel to bypass traditional retail, especially for reaching consumers in dense urban centers like London and New York.
- Expansion in Latin America:Markets such as Brazil and Mexico show nascent demand for convenient meal solutions, presenting an opportunity to introduce chilled ready meals tailored to local culinary preferences.
Industry Challenges
- Multi-Jurisdictional Compliance:Navigating the divergent and evolving food safety and labeling regulations from bodies like the FDA and EFSA requires significant regulatory expertise and ongoing investment in compliance systems.
- Sustainable Packaging Transition:Implementing recyclable or compostable packaging materials while maintaining the necessary barrier properties for food preservation and shelf-life extension presents a significant technical and operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chilled and Deli Foods Market |
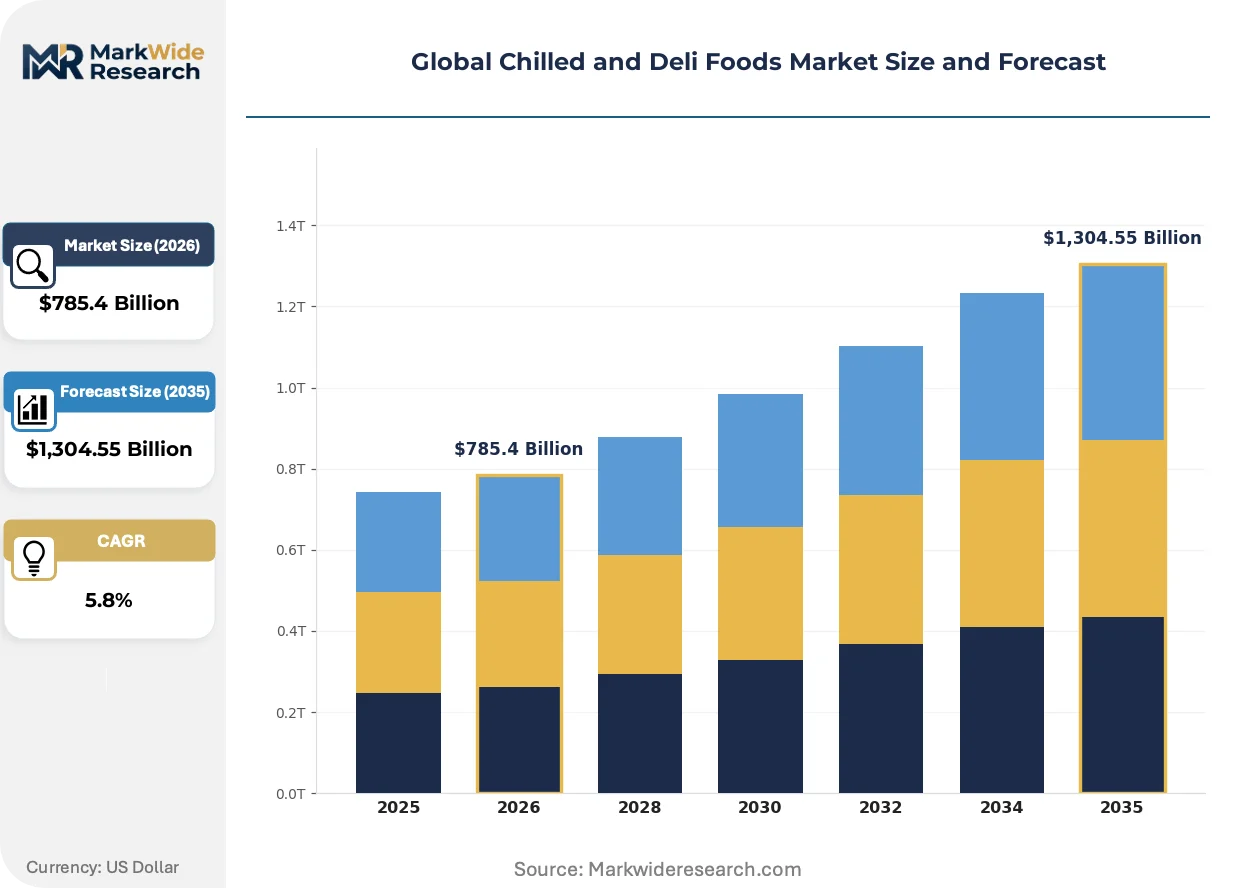
| Market Size in 2026 | $785.4 Billion |
| Market Size in 2035 | $1,304.55 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready Meals, Processed Meats, Fresh Cheese, Prepared Salads, Gourmet Sandwiches Packaging Type: Vacuum Packs, Modified Atmosphere Packs, Flow Wrap, Clamshell Containers, Film Wrap Distribution Channel: Supermarkets, Convenience Stores, Foodservice Outlets, Online Retailers, Specialty Shops Customer Type: Households, Catering Services, Corporate Cafeterias, Educational Institutions, Healthcare Facilities |
| Companies Covered | Conagra Brands, Inc., The Kraft Heinz Company, Nestle S.A., PepsiCo, Inc., General Mills, Inc., Unilever PLC, Greencore Group Plc, Kellogg Company, Tyson Foods, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chilled and Deli Foods Market Strategic Shifts & Innovations
Digitalization of the cold chain is reshaping market competition, shifting focus to verifiable claims about sourcing, safety, and environmental impact. This drive for transparency connects directly with consumer demand for healthier, sustainable food options.
Smart packaging incorporates time-temperature indicator (TTI) labels to monitor product condition from factory to retail. Premium food brands adopt this technology to ensure cold chain integrity and reduce spoilage. The ability to provide this verifiable data is consolidating market access for suppliers, disadvantaging competitors with less transparent systems.
The European Union's Farm to Fork Strategy establishes ambitious targets for sustainable food systems, impacting packaging and sourcing. Its mandates are forcing manufacturers to redesign packaging to improve recyclability and reduce material use. The prepared salads segment is most affected, accelerating a shift toward fiber-based trays and mono-material films.
Consumer purchasing decisions are increasingly guided by a desire for personalized nutrition and specific health outcomes. This behavior creates demand for deli products fortified with probiotics or ready meals with clean, functional ingredient lists. This trend is most visible in metropolitan areas across the United States and Germany, where niche brands leverage online channels.
Global Chilled and Deli Foods Market Segmentation
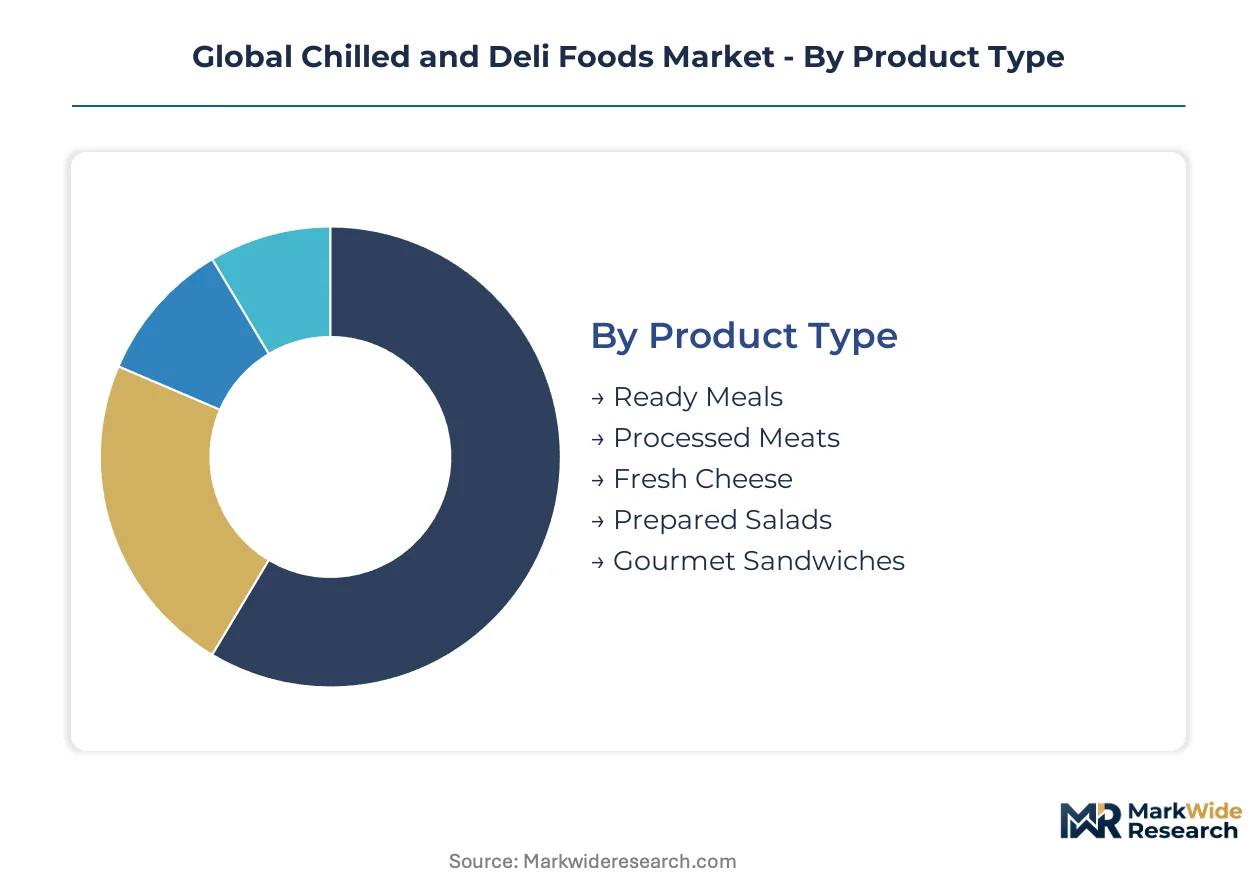
Segmentation provides a granular view of the Global Chilled and Deli Foods Market, highlighting distinct areas of investment and consumer engagement. Understanding these divisions helps market participants tailor product development and distribution strategies. This analysis illuminates where specific capital outlays yield the highest returns.
Product Type:
Production of certain chilled and deli food product types demands significant capital expenditure for specialized processing equipment and cold chain infrastructure.
- Ready Meals:These pre-cooked or partially cooked food items require minimal preparation before consumption, often featuring a protein, starch, and vegetable component. Demand concentrates in urban centers across China and India, driven by fast-paced lifestyles and the need for convenient, healthy options.
- Prepared Salads:These ready-to-eat vegetable and protein combinations are pre-washed, pre-cut, and often include dressings or toppings. Consumer appetite for these healthy, quick options concentrates in urban centers across China and India, aligning with busy schedules.
- Processed Meats:This category includes deli slices, sausages, and cured meats, often requiring specific curing, smoking, or cooking processes for preservation.
- Fresh Cheese:Soft cheeses like mozzarella, ricotta, or feta, characterized by their high moisture content and short shelf life, demand careful handling.
- Gourmet Sandwiches:Pre-assembled sandwiches featuring premium ingredients, often sold in grab-and-go formats for convenience-seeking consumers.
Ready Meals absorbs the bulk of installed capacity; Prepared Salads is expanding most quickly.
Packaging Type:
Packaging choices for chilled and deli foods directly influence shelf-life extension and product presentation, with material costs varying significantly across formats.
- Modified Atmosphere Packs:These packages replace ambient air with a specific gas mixture to extend product shelf life and maintain freshness, crucial for perishable items. This technology is widely adopted across Europe and North America to comply with stringent food safety standards.
- Vacuum Packs:This method removes air from the package before sealing, preventing oxidation and inhibiting microbial growth, commonly used for processed meats and cheeses. Adoption is high in markets like Germany and the United States for preserving product quality.
- Flow Wrap:A flexible packaging technique where products are individually wrapped in a continuous film, often used for single-serve deli items or baked goods.
- Clamshell Containers:Rigid, hinged containers, typically made from PET or RPET, providing protection and visibility for items like prepared salads.
- Film Wrap:Simple, flexible plastic film used to cover and protect products, common for fresh cheese blocks or deli counter items, offering basic protection.
Modified Atmosphere Packs dominate product preservation; Clamshell Containers are gaining share due to visibility and convenience.
Distribution Channel:
Distribution channels for chilled and deli foods segment the market based on consumer access and purchasing habits, dictating logistical complexities.
- Supermarkets:These large-format retail stores offer a wide assortment of chilled and deli products, serving as the primary purchasing point for most households. Their extensive cold chain infrastructure supports high-volume sales across countries like the United States and the United Kingdom.
- Online Retailers:E-commerce platforms and dedicated grocery delivery services provide direct-to-consumer options for chilled and deli foods, often through subscription models. This channel is experiencing rapid growth in metropolitan areas such as London and New York, driven by convenience.
- Convenience Stores:Smaller retail outlets offering a limited selection of ready-to-eat and ready-to-heat chilled items for immediate consumption by busy individuals.
- Foodservice Outlets:Restaurants, cafes, and institutional caterers sourcing bulk chilled and deli products for meal preparation and menu diversity.
- Specialty Shops:Niche retailers focusing on gourmet, artisanal, or imported chilled and deli items, often with a curated selection for discerning customers.
Supermarkets account for the largest volume; Online Retailers show the steepest expansion trajectory.
Customer Type:
Customer types for chilled and deli foods reflect diverse consumption patterns and procurement requirements, influencing product format and delivery.
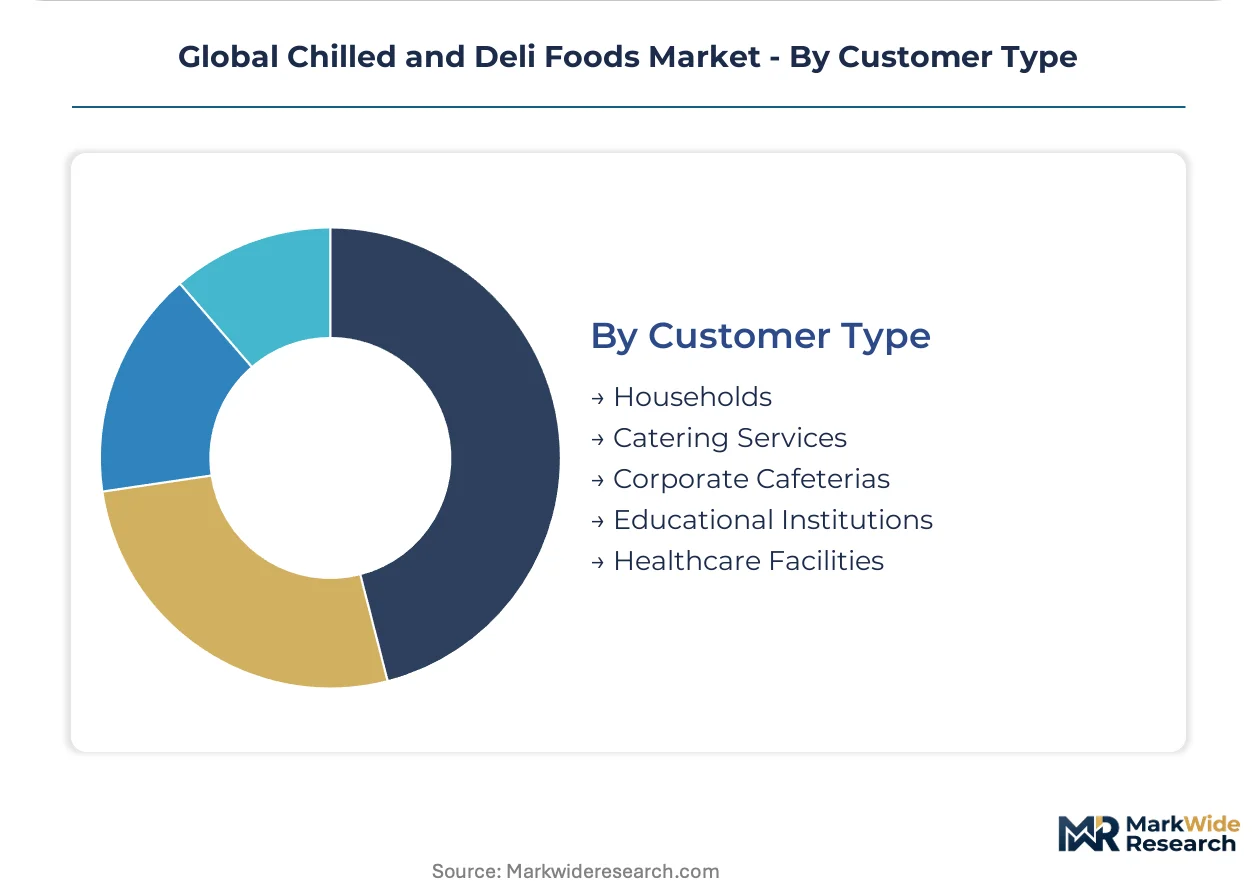
- Households:Individual consumers purchasing chilled and deli foods for at-home consumption, driving demand for convenience and diverse product offerings. This segment represents the largest consumer base, with preferences varying significantly across regions from Germany to Japan.
- Corporate Cafeterias:On-site food service providers within businesses, increasingly sourcing high-quality, pre-prepared chilled and deli items for employee meals. This demand is a significant contributor to market expansion, particularly in major business hubs.
- Catering Services:Businesses providing food for events, parties, and functions, requiring bulk quantities of chilled and deli components for large-scale preparation.
- Educational Institutions:Schools and universities sourcing chilled and deli foods for student and staff meals, prioritizing nutritional value and cost-effectiveness.
- Healthcare Facilities:Hospitals and care homes utilizing chilled and deli items for patient and staff meals, with strict dietary and safety requirements for vulnerable populations.
Households generate the most revenue; Corporate Cafeterias are experiencing the fastest uptake.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones across Asia are driving significant investment in food processing infrastructure, concentrating production capabilities for chilled and deli items. These zones offer fiscal incentives and streamlined regulatory processes, attracting both domestic and international food manufacturers. This strategic approach fosters localized supply chains, reducing logistics costs and improving market responsiveness for perishable goods.
China
Rapid urbanization in Chinese cities fuels substantial demand for convenient, ready-to-eat meal solutions like prepared salads and chilled meals. The national GB standards for food safety ensure product quality and consumer trust across diverse offerings. Major food processing clusters in the Yangtze River Delta region are expanding capacity, serving metropolitan areas like Shanghai and Nanjing with diverse chilled food options.
India
Demand for convenient meal solutions in India's urban centers like Bengaluru and Mumbai is accelerating, driven by evolving consumer lifestyles. The Food Safety and Standards Authority of India (FSSAI) actively regulates product labeling and cold chain management for imported and domestic goods. Processing and distribution hubs in the Delhi-NCR region are optimizing logistics for chilled and deli products, enhancing market penetration.
United States
Consumer demand for personalized nutrition and clean-label deli products is reshaping the market across major US metropolitan areas. The US Food and Drug Administration (FDA) enforces stringent food safety and allergen labeling protocols for all chilled food imports and domestic production. Key food innovation centers in California and New York City are fostering new brands leveraging online channels for direct-to-consumer delivery.
Germany
A strong preference for healthy, functional ingredients in chilled ready meals and deli alternatives characterizes the German market. The European Food Safety Authority (EFSA) mandates strict cold chain and hygiene standards, influencing local manufacturing practices. Bavaria, a hub for specialty food manufacturers, is seeing increased investment in sustainable packaging solutions for its diverse product range.
United Kingdom
Supermarkets remain the dominant distribution channel for chilled and deli foods across the United Kingdom, with online retailers gaining share in urban centers. Adherence to EFSA guidelines for food safety and traceability is a prerequisite for market entry and sustained growth. London's dense urban environment is a prime market for rapid delivery services offering curated meal kits and prepared salads.
Global Chilled and Deli Foods Market Key Industry Players
Global conglomerates anchor one tier; regional specialists hold distinct positions within the chilled and deli foods market, reflecting varied operational scales and geographic focuses. The market structure exhibits a tiered consolidation, where large multinational food companies compete with agile local producers. Strategic archetypes include diversified food giants, specialized protein processors, and convenience food innovators. Dominant competitive moves involve portfolio diversification into plant-based alternatives and strategic geographic expansion into emerging urban markets.
At the scale-driven end, The Kraft Heinz Company and Nestle S.A. exemplify global food conglomerates leveraging extensive distribution networks and brand recognition. These entities occupy a position focused on broad market penetration and diverse product portfolios. Greencore Group Plc, a Europe-based specialist, represents an archetype focused on convenience food solutions and prepared meals, particularly catering to specific regional tastes and retail partnerships.
| Leading Market Players |
|---|
| Conagra Brands, Inc. |
| The Kraft Heinz Company |
| Nestle S.A. |
| PepsiCo, Inc. |
| General Mills, Inc. |
| Unilever PLC |
| Greencore Group Plc |
| Kellogg Company |
| Tyson Foods, Inc. |
| Others |
Cost & Logistics Intelligence
Industrial Electricity Price Index fluctuations cascade through the chilled and deli foods supply chain, directly impacting cold chain logistics and manufacturing costs. This volatility influences pricing tiers for perishable goods, from production to final retail.
Pricing Analysis
Premium pricing for short lead times characterizes the high-convenience segment, while bulk orders for corporate cafeterias often secure contract-based long-term offtake agreements. Pricing stratifies across premium, standard, and economy tiers, driven by quality grade and brand recognition. Margins are tightening due to energy price volatility and raw material costs for protein inputs. Households exhibit high price sensitivity, whereas corporate buyers prioritize consistent quality and convenience.
Supply Chain Analysis
Packaging return and recycling flows are becoming critical reverse logistics considerations, driven by EU Farm to Fork mandates. Geographic supply concentration for key inputs rests in regions like the Yangtze River Delta for processed foods and the US Midwest for proteins. The supply chain relies heavily on raw materials such as fresh produce, processed meats, and specialized packaging films. Protein supply concentration creates a structural risk for downstream deli manufacturers. Distribution primarily runs through established supermarket networks, with online retailers gaining share in metropolitan areas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Chilled and Deli Foods Market is a cost-of-compliance story, where the EU's Corporate Sustainability Reporting Directive (CSRD) creates a significant barrier-to-entry moat for compliant players.
For Market Incumbents: Hedge against raw material price volatility by diversifying protein sourcing across multiple geographic regions. Invest strategically in advanced cold chain technologies to mitigate energy price fluctuations and improve product shelf life. Leverage sophisticated supply chain tracking systems to meet stringent environmental footprinting requirements. This proactive approach defends market share against agile niche players and evolving regulatory pressures.
For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting urban centers like London and New York. Develop plant-based deli alternatives and personalized nutrition meal kits to capture white-space opportunities. The most penetrable segment remains health-conscious consumers in dense metropolitan areas. Focus on a strong online presence and rapid delivery services as a primary go-to-market angle.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialists with strong regional distribution and sustainable packaging solutions in established markets like Germany. The market offers long-term viability, anchored by enduring consumer demand for convenience and health-oriented options. Target companies with verifiable claims about sourcing and environmental impact. Practitioners should monitor the adoption rates of smart packaging technologies as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Sustainable Packaging R&D | Reduces environmental footprint and complies with evolving EU Farm to Fork mandates. |
| Plant-Based Portfolio Expansion | Captures growing flexitarian and vegan consumer segments in key urban markets. |
| Cold Chain Digitalization | Enhances food safety, reduces spoilage, and optimizes logistics costs across the supply chain. |
| Emerging Market Entry | Taps into nascent demand for convenient meal solutions in Latin American cities. |
| Direct-to-Consumer Channel Development | Bypasses traditional retail, offering curated products and rapid delivery to urban consumers. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing a comprehensive market overview. This analysis combined primary interviews with industry stakeholders, including food manufacturers, retail buyers, logistics providers, and food safety regulators, for validation. Secondary data sources like EFSA reports, FDA guidelines, and FSSAI regulations informed the market sizing. Bottom-up and top-down triangulation ensured robust market estimates.
Product type, packaging type, distribution channel, customer type, and regional consumption patterns were modeled at a granular level across the analysis window. The analytical framework integrated historical data with future projections. Compound Annual Growth Rates (CAGRs) were derived through regression analysis and expert validation. Urbanization rates and per capita disposable income served as key industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for sustainable packaging materials would alter the outlook. Forecasts reflect assumptions regarding economic stability and regulatory enforcement. Geopolitical instability and new trade barriers represent specific risk factors that could revise forecasts. Practitioners should monitor consumer dietary preference shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Processed and Frozen Fruits Market
Processed and Frozen Foods
North America Frozen Food Market
Processed and Frozen Foods
Europe Frozen Finger Chips Market
Processed and Frozen Foods
Individual Quick Frozen Cheese Market
Processed and Frozen Foods
Refrigerated Liquid Eggs Market
Processed and Frozen Foods
North America Frozen Desserts Market
Processed and Frozen Foods
Frozen Ready Meals Market
Processed and Frozen Foods
Cambodia Frozen Food Market
Processed and Frozen Foods
Europe Frozen Desserts Market
Processed and Frozen Foods
US Frozen Food Market
Processed and Frozen Foods
Freeze Dried Vegetables Market
Processed and Frozen Foods
Frozen Noodles and Rice Products Market
Processed and Frozen Foods
Vegan Frozen Food Market
Processed and Frozen Foods
Freeze Dried Fruits Market
Processed and Frozen Foods
Ice Structuring Protein Market
Processed and Frozen Foods
United States Frozen Yogurt Market