
 Frozen Tortilla Market | 2026-2036
Frozen Tortilla Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Tortilla Market Intelligence
Automated dough sheeting and high-speed flash-freezing technology is narrowing the quality gap between fresh and frozen tortillas, improving texture and taste parity. Gruma SAB de CV leverages its extensive manufacturing scale to influence market pricing and secure large foodservice contracts. General Mills, Inc. differentiates through strong brand recognition and its vast retail distribution channels in North America. Grupo Bimbo SAB de CV competes by applying its large-scale bakery production expertise to the tortilla category.
Frozen tortillas are pre-cooked or par-baked unleavened flatbreads made from nixtamalized corn or wheat flour. The products are cryogenically frozen to maintain a specific moisture content, which preserves texture and prevents spoilage without requiring extensive chemical preservatives. Flour tortillas command the largest market share due to their pliable texture and widespread use in wraps and burritos. Demand for corn and whole wheat tortillas is expanding rapidly, driven by consumer preferences for gluten-free and high-fiber options.
Product standards are governed by food safety authorities such as the U.S. Food and Drug Administration (FDA), which mandates specific labeling for allergens like wheat. The European Food Safety Authority (EFSA) imposes strict rules on food contact materials, impacting packaging selection for producers exporting to the region. Future profitability will depend on balancing clean-label ingredient sourcing against fluctuating grain commodity prices while meeting consumer expectations for convenience.
Market Dynamics
The primary force shaping the frozen tortilla market is the convergence of food service demand for operational efficiency and consumer desire for healthier, convenient meal options. This dynamic is amplified by processing innovations that improve the sensory attributes of frozen products.
Growth Catalysts
- QSR Sector Growth:Expansion within the Quick Service Restaurant sector creates sustained demand for standardized, long-shelf-life tortillas that streamline kitchen operations and ensure product consistency across international franchise locations.
- Health-Conscious Consumerism:A pronounced shift in consumer preference toward gluten-free and high-fiber diets is elevating demand for corn and whole wheat tortillas, which are perceived as healthier alternatives to traditional flour varieties.
- Flash-Freezing Advancements:Cryogenic freezing technology preserves the specific moisture content and pliable texture of tortillas, narrowing the quality gap with fresh-made alternatives and boosting consumer acceptance in retail channels.
Market Restraints
- Commodity Price Volatility:Producer margins are directly exposed to fluctuations in the global prices of corn and wheat, making cost management and forward purchasing critical but challenging for maintaining stable end-product pricing.
- Cold Chain Dependency:The market's reliance on an unbroken, energy-intensive cold chain from factory to consumer adds significant logistical complexity and cost, creating a high barrier to entry for smaller manufacturers.
- Substitution from Fresh Products:In markets with a strong bakery presence, particularly in Mexico and the southern United States, fresh tortillas remain a significant substitute, limiting frozen product penetration due to cultural preference for freshness.
Strategic Opportunities
- Alternative Flour Development:There is a significant opportunity to formulate and market tortillas made from non-traditional flours such as chickpea, almond, or cassava to capture share within the rapidly expanding gluten-free and grain-free food segments.
- European Market Expansion:Producers can target European countries where demand for Mexican and Latin American cuisine is rising, but local production capacity for authentic, high-quality frozen tortillas remains underdeveloped.
- Clean-Label Formulations:Leveraging advanced freezing as the primary preservation method allows for the creation of clean-label products without chemical preservatives, appealing directly to consumers scrutinizing ingredient lists for artificial additives.
Industry Challenges
- Allergen Segregation:Manufacturers producing both wheat and corn tortillas face the operational challenge of preventing cross-contamination, requiring stringent adherence to FDA allergen control plans and often necessitating separate production lines.
- Sustainable Packaging Mandates:Meeting evolving regulations like the European Union's directives on packaging waste requires investment in new materials that are both recyclable and capable of withstanding cryogenic temperatures without compromising food safety.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Tortilla Market |
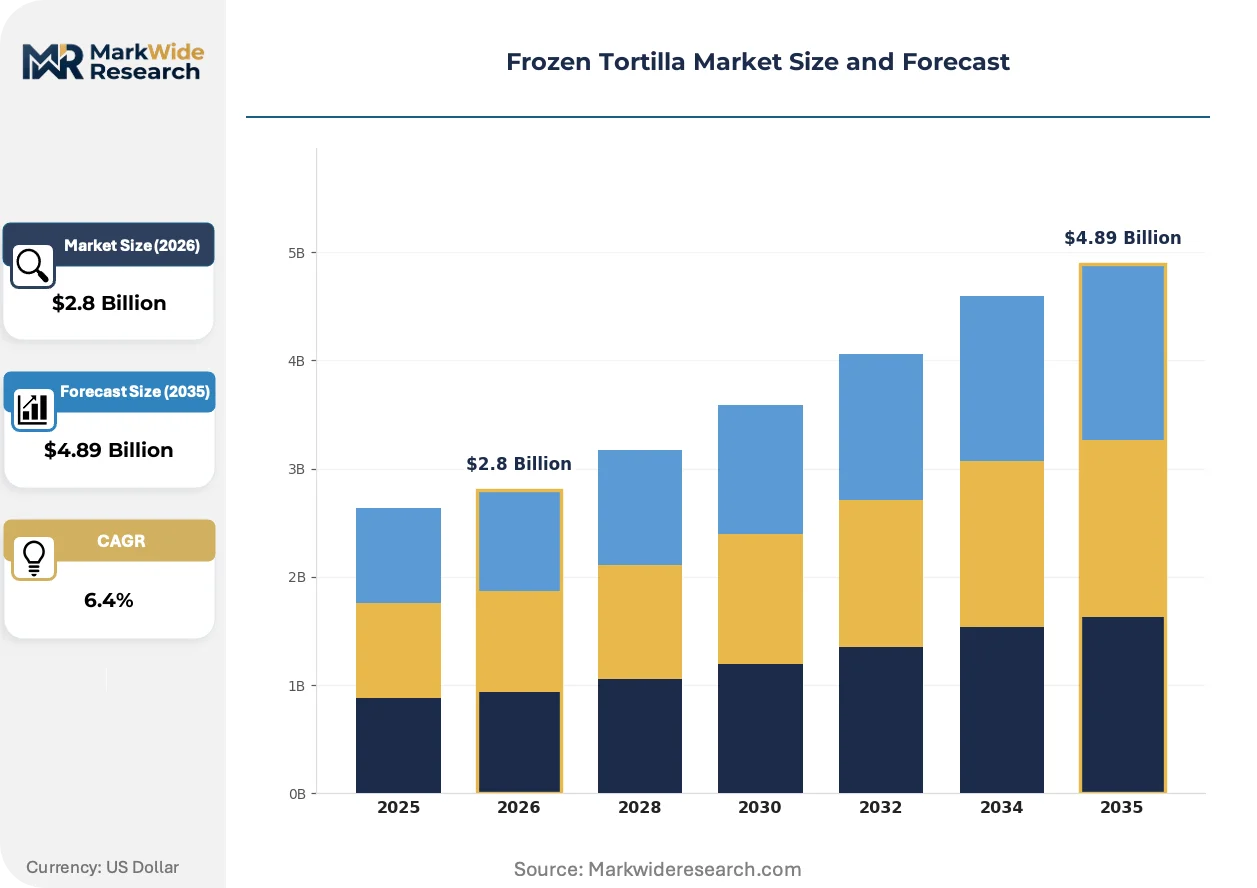
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corn Tortilla, Flour Tortilla, Whole Wheat Tortilla, Spinach Tortilla, Tomato Tortilla Application: Foodservice, Quick Service Restaurants, Retail Consumption, Catering Services, Home Cooking Packaging Type: Plastic Bags, Vacuum Sealed Packs, Cardboard Boxes, Paper Wraps, Bulk Packs Customer Type: Supermarkets & Hypermarkets, Specialty Food Stores, Online Retailers, Convenience Stores, Wholesale Distributors |
| Companies Covered | Gruma SAB de CV, Grupo Bimbo SAB de CV, General Mills, Inc., Azteca Foods Inc., Tyson Foods, Inc., Ole Mexican Foods Inc., Mission Foods, Grupo Liven, S.A., PepsiCo Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Tortilla Market Strategic Shifts & Innovations
Innovations in food science and processing technology are fundamentally altering the competitive landscape. These advancements are closing the perceived quality gap between fresh and frozen tortillas, reshaping both consumer expectations and commercial procurement strategies in the food service industry.
Automated dough sheeting technology provides precise control over tortilla thickness and diameter, ensuring high levels of consistency. Food service clients, particularly large QSR chains, are rapidly adopting this technology to guarantee product uniformity across thousands of locations. This level of automation is digitizing quality control, reducing manual error and enabling rapid shifts in production to meet custom specifications for different menu items.
New food safety regulations from authorities like the U.S. FDA and the EFSA are increasing compliance burdens. The FDA’s rules on allergen labeling, for instance, mandate clear identification of wheat, forcing strict production segregation. For manufacturers exporting to Europe, EFSA regulations on food contact materials dictate the types of plastics and films that can be used in packaging, influencing cost and material sourcing.
Consumer purchasing behavior is shifting toward smaller, variety-pack formats in the retail sector. This disrupts the traditional model of selling single-type bulk packages, forcing manufacturers to adapt production lines for greater flexibility. This trend is most prominent in North American supermarkets, where households seek to experiment with different tortilla types for various meals without committing to a large quantity.
Frozen Tortilla Market Segmentation
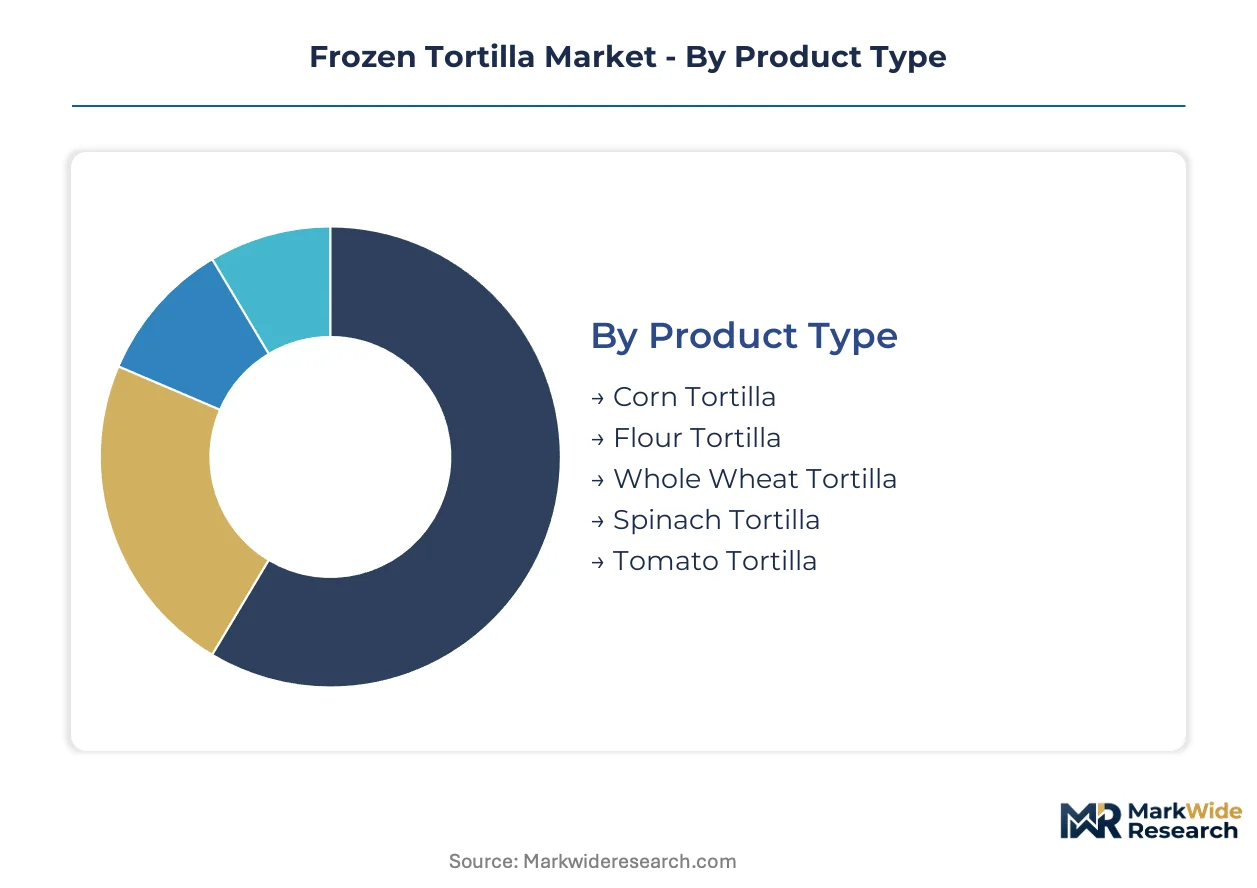
The frozen tortilla market segments reflect distinct product characteristics, end-user applications, packaging preferences, and customer channels. Understanding these divisions is critical for manufacturers to tailor product development, optimize distribution networks, and implement targeted marketing strategies for diverse consumer needs.
Product Type:
The after-sales service intensity for frozen tortillas varies significantly by product type, reflecting diverse customer expectations and operational requirements for handling and preparation.
- Flour Tortilla:These pliable, unleavened flatbreads are made from wheat flour and are preferred for their soft texture and versatility in wraps, burritos, and quesadillas. Demand for flour tortillas concentrates in the United States, driven by widespread adoption in QSRs and retail for convenient meal solutions.
- Whole Wheat Tortilla:Comprising whole grain wheat flour, these tortillas offer a higher fiber content and a distinct nutty flavor, appealing to health-conscious consumers. The market for whole wheat tortillas is expanding rapidly in North America, propelled by consumer preferences for healthier and functional food options.
- Corn Tortilla:Made from nixtamalized corn, these tortillas provide a traditional flavor profile and are naturally gluten-free, serving as a staple in Mexican cuisine.
- Spinach Tortilla:Infused with spinach, these tortillas offer a mild vegetable flavor and a distinctive green color, often marketed as a healthier or novelty option.
- Tomato Tortilla:These tortillas incorporate tomato paste, providing a subtle tangy flavor and a reddish hue, appealing to consumers seeking variety and visual appeal.
Flour Tortilla holds the largest share; momentum sits with Whole Wheat Tortilla.
Application:
The application of frozen tortillas directly influences demand patterns and product specifications across various end-use environments.
- Quick Service Restaurants:QSRs utilize frozen tortillas for menu consistency and operational efficiency, requiring products that perform reliably under high-volume, rapid preparation conditions. This segment drives significant volume in the United States and Canada, supported by the need for standardized ingredients across franchise locations.
- Retail Consumption:This segment encompasses tortillas sold directly to consumers through grocery stores and supermarkets for home preparation, emphasizing convenience, variety, and ease of storage. Retail consumption is particularly strong in North America, where consumers seek convenient meal components.
- Foodservice:This broad category includes restaurants, cafes, and institutional kitchens that use frozen tortillas for menu items, valuing bulk packaging and consistent quality.
- Catering Services:Catering operations rely on frozen tortillas for large-scale events, prioritizing ease of handling, consistent quality, and extended shelf life for menu flexibility.
- Home Cooking:Individual consumers purchase frozen tortillas for meal preparation, valuing convenience, taste, and the ability to store products for extended periods.
Quick Service Restaurants represents the fastest-growing segment, driven by operational efficiencies.
Packaging Type:
Packaging type often correlates with different cost tiers, impacting both consumer perception and logistical expenses for frozen tortilla products.
- Plastic Bags:These flexible, cost-effective bags are commonly used for retail packaging of frozen tortillas, providing visibility and protection against freezer burn. Plastic bags dominate the retail segment in the United States due to their low cost and consumer familiarity.
- Vacuum Sealed Packs:Vacuum sealing removes air to prevent oxidation and freezer burn, significantly extending shelf life and preserving product freshness and texture. These packs are gaining traction in European markets for premium and clean-label frozen products, appealing to consumers seeking longer preservation without additives.
- Cardboard Boxes:Often used for bulk or multi-pack presentations, cardboard boxes provide structural integrity and a surface for branding and product information.
- Paper Wraps:Environmentally friendly paper wraps are sometimes used for individual or smaller portions, appealing to consumers focused on sustainable packaging options.
- Bulk Packs:Large-format packaging designed for foodservice and wholesale customers, prioritizing cost-efficiency and minimizing waste for high-volume users.
Plastic Bags maintain widespread adoption due to cost-effectiveness, while Vacuum Sealed Packs are gaining share for their preservation benefits.
Customer Type:
Different customer types exhibit distinct purchasing behaviors and volume requirements, shaping distribution strategies for frozen tortilla manufacturers.
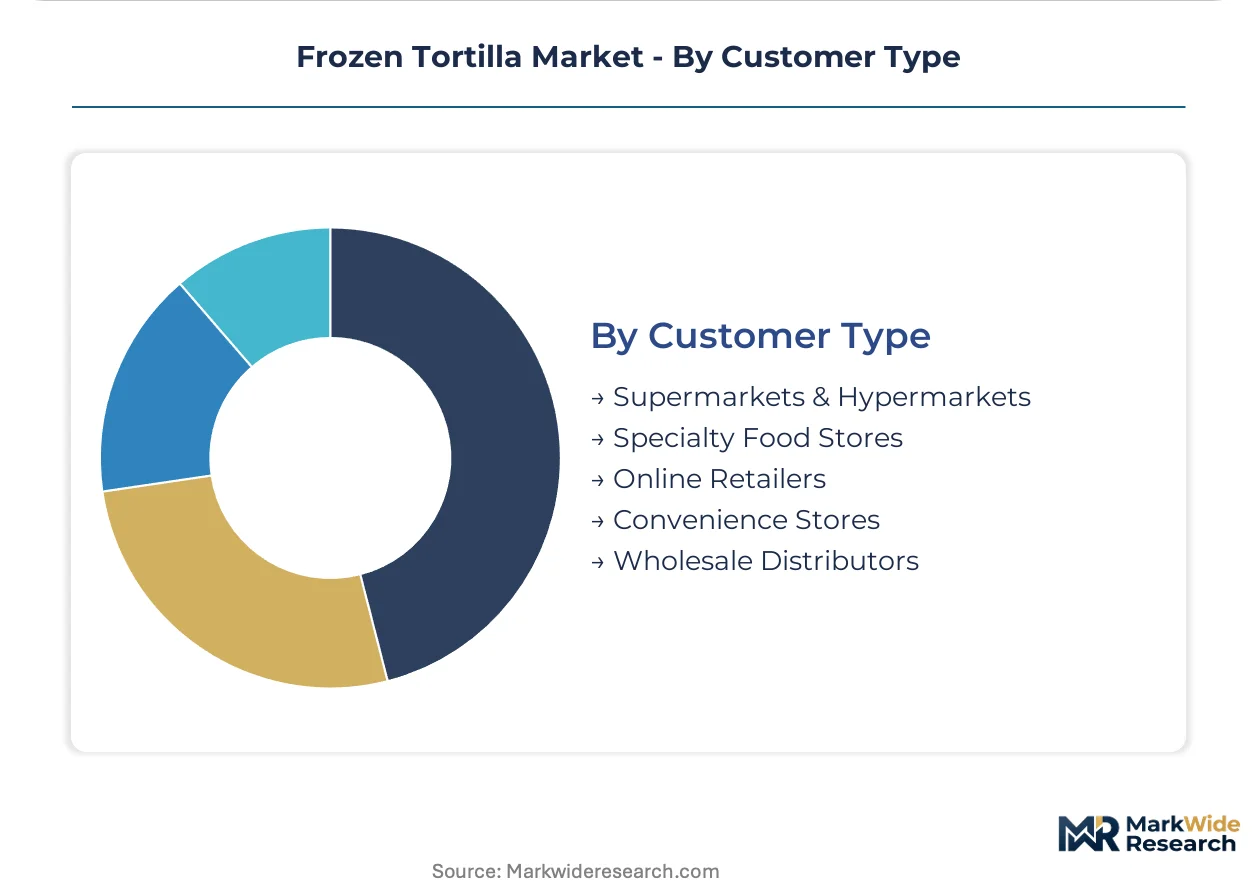
- Supermarkets & Hypermarkets:These large retail outlets serve a broad consumer base, offering a wide selection of frozen tortilla products across various brands and types. Supermarkets & Hypermarkets remain the primary distribution channel for frozen tortillas in North America, driven by extensive reach and consumer convenience.
- Online Retailers:E-commerce platforms provide consumers with convenient access to frozen tortillas, often featuring niche products and bulk options with home delivery services. The online retail channel is expanding significantly in Europe, catering to consumers seeking specialty ingredients and home delivery.
- Specialty Food Stores:These stores cater to specific dietary needs or gourmet preferences, offering premium or unique frozen tortilla varieties like gluten-free or organic options.
- Convenience Stores:Smaller retail formats that provide quick access to essential frozen tortilla products, often in single-serve or smaller package sizes for immediate consumption.
- Wholesale Distributors:These entities supply frozen tortillas in bulk to foodservice establishments, catering services, and smaller retail outlets, acting as a crucial link in the supply chain.
Supermarkets & Hypermarkets serve as the foundational distribution channel, with Online Retailers demonstrating pronounced growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration in Quick Service Restaurants (QSRs) and retail channels drives significant demand for frozen tortillas across key markets. These consumers prioritize operational efficiency and convenience, shaping product development and distribution strategies. Flash-freezing advancements further support market expansion.
United States
Consumer demand for convenient meal solutions and QSR operational efficiency drives frozen tortilla consumption in the United States. The U.S. Food and Drug Administration (FDA) mandates specific labeling for allergens like wheat, influencing production processes. Major QSR chains in the Southern United States, particularly Texas, adopt frozen tortillas for consistent menu offerings.
Mexico
Mexican consumers maintain a strong culinary tradition for tortillas, influencing both fresh and frozen product markets. Mexican food safety authorities enforce local standards for food processing and ingredients, impacting manufacturers. Production hubs around Mexico City and Guadalajara cater to both domestic consumption and export.
Canada
Canadian QSRs and retail consumers seek frozen tortillas for their versatility and extended shelf life, streamlining kitchen operations. Health Canada oversees food safety and labeling requirements, ensuring product compliance for consumers. Urban centers like Toronto and Vancouver exhibit high demand from diverse populations.
Germany
Rising interest in global cuisines, especially Mexican and Latin American, stimulates frozen tortilla demand in Germany. The European Food Safety Authority (EFSA) sets strict rules on food contact materials, impacting packaging selection. Cosmopolitan cities such as Berlin show growing consumption in both retail and foodservice sectors.
Spain
Spanish consumers are increasingly adopting frozen tortillas for convenient meal preparation and exploring new culinary experiences. The Spanish Agency for Food Safety and Nutrition (AESAN) aligns with EU directives on food safety and quality standards. Major cities like Madrid and Barcelona are emerging as important centers for ethnic food distribution.
Frozen Tortilla Market Key Industry Players
Channel-controlling players compete with product-specialist players, shaping the frozen tortilla market structure. This market exhibits a tiered structure, from large-scale producers with global reach to regional manufacturers and niche innovators. Strategic archetypes include global food conglomerates, specialized ethnic food suppliers, and private label manufacturers. Companies pursue capacity expansion and strategic partnerships to secure market position and expand distribution channels.
Scale-driven players like Gruma SAB de CV, a Mexican-based company, influence market pricing through extensive manufacturing capabilities and large foodservice contracts. General Mills, Inc., a U.S.-based multinational, leverages its strong brand recognition and vast retail distribution networks in North America. Grupo Bimbo SAB de CV, another Mexican-based conglomerate, applies its large-scale bakery expertise to the tortilla category, diversifying its product portfolio and reaching new consumer segments.
| Leading Market Players |
|---|
| Gruma SAB de CV |
| Grupo Bimbo SAB de CV |
| General Mills, Inc. |
| Azteca Foods Inc. |
| Tyson Foods, Inc. |
| Ole Mexican Foods Inc. |
| Mission Foods |
| Grupo Liven, S.A. |
| PepsiCo Inc. |
| Others |
Cost & Logistics Intelligence
Commodity price volatility for corn and wheat determines both pricing tier spreads across frozen tortilla products and supply chain shape. This instability forces manufacturers to manage input costs carefully, affecting product offerings and sourcing locations.
Pricing Analysis
Cost-plus contract patterns, frequently indexed to corn and wheat futures, define frozen tortilla pricing for large foodservice accounts. Price differentiation stems from quality grade, particularly between premium clean-label products and standard offerings, alongside volume scale for bulk purchasers. Pricing softness in the retail segment stems from consumer demand for value options. Retail consumers exhibit high price sensitivity, while Quick Service Restaurants prioritize consistent product performance and operational efficiency.
Supply Chain Analysis
Cold chain dependency from factory to consumer adds significant logistical complexity and cost for frozen tortillas. Geographic supply concentrates in Mexico and the United States, reflecting primary production and consumption hubs. Raw material dependencies center on corn and wheat flour, making sourcing vulnerable to agricultural market shifts. Distribution runs through wholesale distributors for foodservice and directly into large supermarket and hypermarket networks for retail consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The frozen tortilla market is experiencing a buyer-power shift, driven by the consolidating purchasing power of Quick Service Restaurant chains. These large buyers dictate product specifications and volume, influencing manufacturer strategies.
For Market Incumbents: Entrench market position by expanding manufacturing scale in high-demand regions like Mexico and the United States. Invest in advanced flash-freezing technology to further narrow the quality gap with fresh products, mitigating the threat of substitution from fresh tortillas. Leverage extensive retail distribution networks and long-term QSR contracts for sustained channel control. This strategy defends against new entrants and maintains pricing influence.
For New Entrants and Emerging Players: European market underpenetration for authentic, high-quality frozen tortillas presents a significant entry opportunity. Target this region by introducing clean-label formulations and alternative flour tortillas, such as chickpea or cassava, appealing to health-conscious consumers. Focus on online retail channels to reach specialty ingredient seekers and build brand recognition. This approach leverages rising interest in global cuisines.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors specialized manufacturers with advanced processing capabilities. Long-term viability remains strong, driven by sustained QSR demand and evolving consumer health preferences over the next decade. Identify niche innovators specializing in alternative flour formulations or sustainable packaging as prime acquisition targets. The signal to watch is the accelerating adoption rate of non-traditional flour tortillas in North American retail.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Flash-Freezing | Enhances product texture and shelf life, narrowing the quality gap with fresh tortillas for QSRs. |
| Develop Alternative Flour Tortillas | Captures market share within the rapidly expanding gluten-free and grain-free food segments. |
| Expand into European Markets | Addresses rising demand for Mexican cuisine in regions with underdeveloped local production capacity. |
| Implement Clean-Label Formulations | Appeals to health-conscious consumers scrutinizing ingredient lists for artificial additives and preservatives. |
| Optimize Cold Chain Logistics | Reduces operational costs and strengthens distribution efficiency for frozen products from factory to retail. |
Research Approach
Cross-validation between industry reports and company filings anchors the qualitative findings for this market analysis. Primary interviews with QSR procurement managers, retail category buyers, food scientists, and cold chain logistics specialists provided direct insights. Secondary validation sources included U.S. Food and Drug Administration mandates, European Food Safety Authority regulations, and relevant trade association reports. This approach integrates bottom-up and top-down triangulation for robust data synthesis.
Calibration of demand-side drivers against supply-side capabilities informed the quantitative modeling framework across the analysis window. Segmentation dimensions included product type, application, packaging type, customer type, and regional consumption patterns. Compound Annual Growth Rates were derived through regression analysis of historical trends and projected market dynamics. Key industry-specific forecast inputs included grain commodity price forecasts and Quick Service Restaurant expansion rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by global food conglomerates would shift outcomes. Forecasts reflect assumptions about stable regulatory environments. Unforeseen shifts in consumer dietary preferences or severe cold chain disruptions could revise projections. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Popsicle and Ice Cream Bar Market
Processed and Frozen Foods
Chilled Meal Kits Market
Processed and Frozen Foods
Freeze Dried Mangos Market
Processed and Frozen Foods
South America Frozen Food Market
Processed and Frozen Foods
Frozen French Fries Market
Processed and Frozen Foods
Frozen Mackerel Market
Processed and Frozen Foods
Frozen Snacks Market
Processed and Frozen Foods
Frozen Shrimp Market
Processed and Frozen Foods
Cambodia Frozen Food Market
Processed and Frozen Foods
Freeze Dried Fruit Extract Market
Processed and Frozen Foods
North America Freeze Dried Products Market
Processed and Frozen Foods
Asia-Pacific Frozen Yogurt Market
Processed and Frozen Foods
Processed and Frozen Fruits Market
Processed and Frozen Foods
North America Frozen Food Market
Processed and Frozen Foods
Freeze Dried Melt Market
Processed and Frozen Foods
Chocolate Ice Cream Market