
 Frozen Meat and Fish Market | 2026-2036
Frozen Meat and Fish Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Meat and Fish Market Foresight
Individually frozen portion packs is broadening buyer choice across retail and foodservice channels by reducing waste and enabling precise inventory rotation. Tyson Foods leverages its vertically integrated poultry network to sustain cost advantages in bulk frozen distribution. JBS S.A. anchors its position through beef and pork processing scale across multiple continents. Maruha Nichiro Corporation specializes in high-value frozen seafood with deep cold-chain control from vessel to retail shelf.
Frozen meat and fish denotes animal proteins preserved at temperatures below minus eighteen degrees Celsius through blast freezing or cryogenic methods to arrest microbial activity and maintain nutritional integrity over extended storage periods. The primary commercial purpose centers on stabilizing supply across seasonal harvest cycles and enabling long-distance trade from production zones to consumption centers. Beef and poultry command the largest volume positions within product type segmentation, while seafood generates disproportionate margin contribution due to catch variability and premium positioning. Vacuum sealed and modified atmosphere packaging configurations capture growing share as retailers prioritize shelf-life extension and visual freshness signaling.
FDA and USDA inspection protocols in the United States mandate pathogen testing and temperature documentation for imported frozen proteins, directly shaping supplier qualification and border clearance timelines. EFSA and EU Green Deal sustainability criteria are tightening carbon footprint disclosure requirements for cold-chain logistics serving European retail and Horeca channels. Stakeholders must monitor evolving traceability mandates and energy cost trajectories in freezing technology to preserve margin structures as regulatory compliance deepens.
Market Dynamics
Labor cost inflation across foodservice operations is accelerating frozen protein procurement as operators trade kitchen prep for pre-portioned inventory. Cold chain infrastructure gaps in emerging supply zones are forcing capital deployment toward blast freezing and controlled-atmosphere storage.
Growth Catalysts
- Quick-service restaurant expansion:Chain operators in Vietnam and Nigeria are converting central kitchens to frozen protein hubs to standardize output across franchise locations.
- EU Green Deal cold-chain standards:Carbon disclosure mandates for refrigerated logistics are qualifying efficient operators for preferential retail shelf access in European markets.
- Blast freezing automation:Cryogenic tunnel systems are compressing processing cycle times and extending shelf-life windows for export-bound seafood consignments.
Market Restraints
- Energy cost volatility:Natural gas and electricity price swings in Germany and South Korea are compressing freezing facility margins.
- Input supply concentration:Wild-catch tuna and premium cod quotas concentrate in Pacific Rim vessel fleets, creating harvest variability exposure.
- USDA border inspection backlog:Extended FDA pathogen testing queues at US ports are delaying clearance for Latin American beef exporters.
Strategic Opportunities
- Underpenetrated African retail:Cold store construction in Lagos and Nairobi is creating first-mover advantage for frozen poultry distributors.
- Modified atmosphere packaging convergence:Vacuum-seal and gas-flush technologies are opening premium positioning in Middle Eastern supermarket channels.
- Brazilian ANVISA modernization:Updated import sanitation protocols are streamlining eligibility for re-export processing hubs serving Atlantic trade routes.
Industry Challenges
- Cold chain technician scarcity:Refrigeration system maintenance expertise lags facility expansion in Southeast Asian port zones.
- Freezer fleet capex intensity:Containerized reefer unit procurement demands heavy capital allocation from logistics operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Meat and Fish Market |
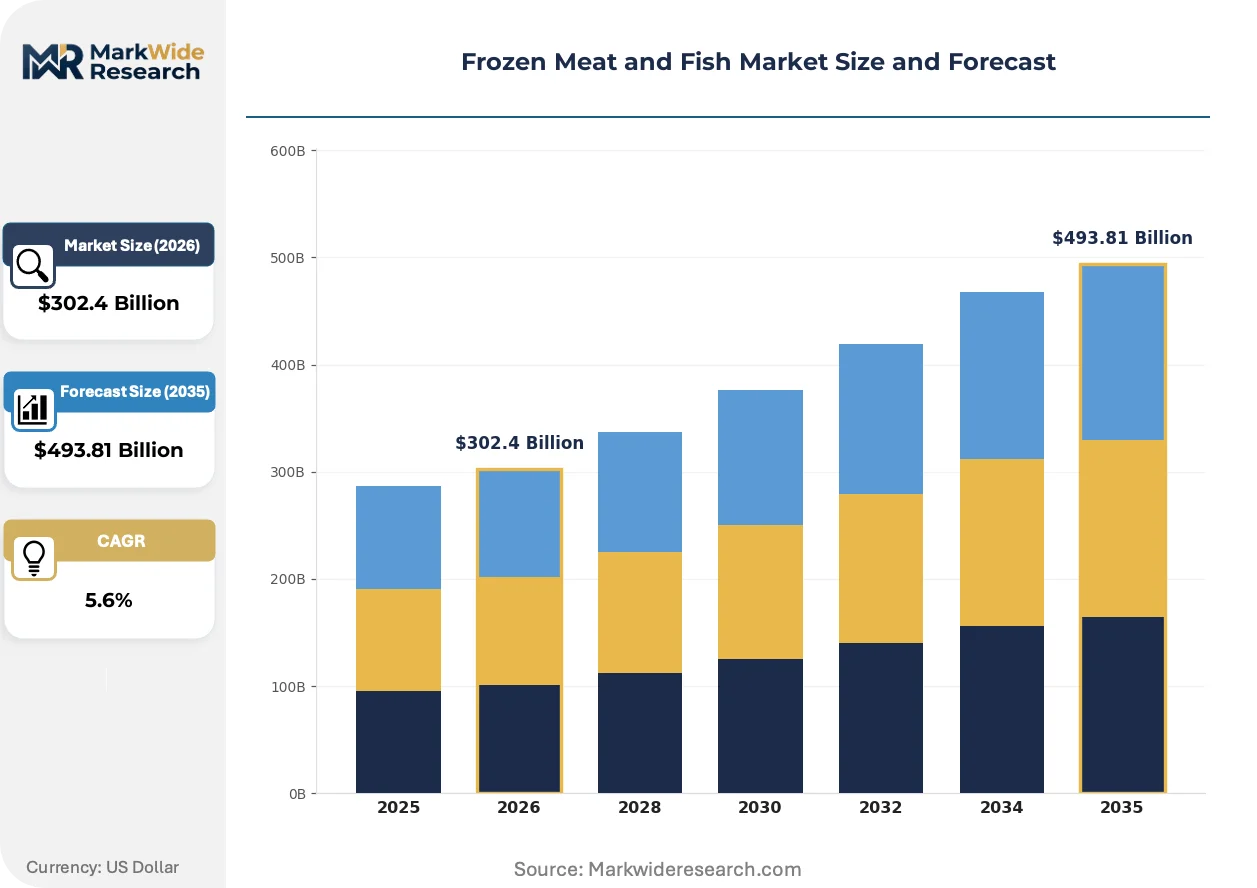
| Market Size in 2026 | $302.4 Billion |
| Market Size in 2035 | $493.81 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Poultry, Pork, Seafood, Lamb Packaging Type: Vacuum Sealed, Tray Pack, Bulk Packs, Individually Frozen Portions, Modified Atmosphere Packaging Application: Foodservice, Retail, Institutional Kitchens, Ready-to-Eat Manufacturers Customer Type: Supermarkets, Specialty Stores, Horeca, Wholesalers |
| Companies Covered | Tyson Foods, Inc., JBS S.A., Cargill, Incorporated, Thai Union Group PCL, Mowi ASA, Conagra Brands, Inc., Maruha Nichiro Corporation, Perdue Farms, Inc., Nomad Foods Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Meat and Fish Market Shifts & Advancements
Digital traceability and automated portioning are compressing the gap between harvest and retail shelf. Processing technology is shifting toward continuous freezing systems that preserve cellular structure.
Individual quick freezing (IQF) technology is unifying portion control with inventory precision. Foodservice distributors in Japan and the United Arab Emirates are adopting IQF lines at accelerated pace. This unification is eliminating bulk-thaw waste and enabling single-unit picking for restaurant operators.
EFSA sustainability disclosure requirements are tightening carbon accounting for European cold-chain logistics. Operators must now document refrigeration emissions across port-to-shelf transit. Frozen seafood importers serving EU retail are retrofitting fleets with lower-GWP refrigerants to maintain qualification.
Buyer concentration among hotel chains is compressing supplier negotiation cycles. Large hospitality procurement offices in Dubai and Singapore are displacing fragmented distributor relationships with direct mill contracts. This consolidation is most visible in bulk frozen beef tenders for cruise line and resort catering operations.
Frozen Meat and Fish Market Segmentation
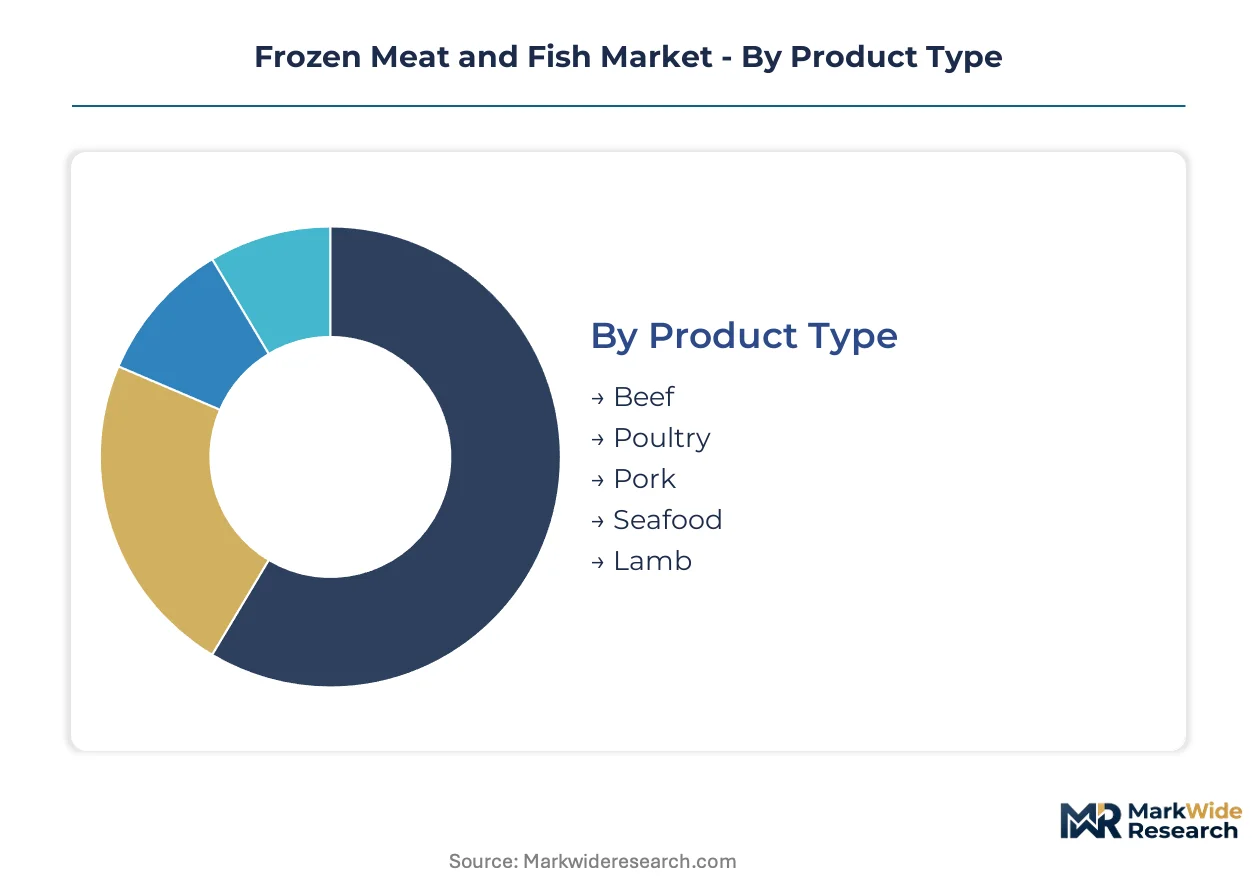
Segmentation in frozen proteins reveals how supply concentration, packaging technology, and channel requirements fragment procurement patterns. Buyers optimize inventory rotation and margin preservation differently across beef tenders, IQF seafood portions, and vacuum-sealed retail cuts.
Product Type:
Supply concentration in animal protein harvesting creates divergent margin structures and cold-chain requirements across species categories.
- Beef:Grain-finished and grass-fed carcasses undergo blast freezing within hours of slaughter to preserve marbling integrity. Quick-service chains in the United Arab Emirates and Saudi Arabia concentrate procurement of frozen beef tenders for standardized burger patty production.
- Poultry:Whole birds and cut portions dominate volume throughput in frozen distribution networks due to shorter production cycles and consistent sizing. Southeast Asian processing hubs in Thailand and Vietnam are expanding cryogenic tunnel capacity to serve re-export demand from Middle Eastern retail consolidators.
- Pork:Frozen pork bellies and loin cuts serve bacon and processed meat manufacturing lines with extended shelf-life requirements. EU Green Deal carbon disclosure mandates are reshaping supplier qualification for European cold-chain logistics.
- Seafood:Wild-catch and aquaculture species preserved through individual quick freezing command premium positioning due to harvest variability. Japanese and South Korean importers prioritize vessel-to-freezer traceability for tuna and mackerel consignments.
- Lamb:Halal-certified frozen lamb carcasses and primal cuts serve Middle Eastern and North African markets with religious slaughter protocol requirements. Australian and New Zealand export processors dominate cold-store allocations for Gulf Cooperation Council retail channels.
Beef absorbs the bulk of installed capacity; poultry is expanding most quickly.
Packaging Type:
Cost tier differentiation in packaging technology separates commodity bulk supply from premium retail-ready presentation.
- Vacuum Sealed:Oxygen-extraction protocols extend shelf life by suppressing aerobic microbial growth on protein surfaces. European supermarket chains mandate vacuum-sealed configurations for private-label frozen beef and pork lines.
- Tray Pack:Polystyrene or cardboard trays with overwrap film balance visibility with cost efficiency in mid-market retail positioning. Brazilian and Argentine exporters favor tray packs for supermarket channel entry in price-sensitive Latin American markets.
- Bulk Packs:Twenty-kilogram carton blocks serve foodservice distributors and institutional kitchens with high-throughput defrosting operations. Hotel chains in Dubai and Singapore convert bulk frozen seafood into portion-controlled menu items through central kitchen processing.
- Individually Frozen Portions:IQF technology isolates single units for precise inventory picking and zero-thaw-waste operations. Japanese convenience store operators and UAE foodservice distributors are accelerating adoption of IQF poultry and seafood lines.
- Modified Atmosphere Packaging:Gas-flush configurations replace oxygen with nitrogen or carbon dioxide to preserve color and delay oxidation. Premium supermarket channels in Germany and France specify MAP for frozen salmon and shellfish retail presentation.
Bulk packs dominate volume throughput; individually frozen portions are gaining share fastest.
Application:
Customer type and volume scale determine packaging specifications, delivery frequency, and price negotiation leverage across end-use channels.
- Foodservice:Restaurants, hotels, and catering operations prioritize portion consistency and rapid thaw characteristics in frozen protein procurement. Chain operators in Vietnam and Nigeria are converting central kitchens to frozen protein hubs for franchise standardization.
- Retail:Supermarkets and specialty stores demand shelf-ready packaging with extended dating and visual freshness signaling. Modified atmosphere and vacuum-sealed configurations are capturing share in European and Middle Eastern retail channels.
- Institutional Kitchens:Hospitals, schools, and military facilities source frozen proteins through tender-based procurement with strict nutritional and safety documentation requirements. ANVISA modernization in Brazil is streamlining eligibility for institutional suppliers.
- Ready-to-Eat Manufacturers:Processed food producers require frozen proteins as input materials for frozen meals, snacks, and prepared dishes. Portion precision and microbiological consistency determine supplier selection for RTE manufacturing lines.
Foodservice absorbs the bulk of installed capacity; ready-to-eat manufacturing is climbing the fastest.
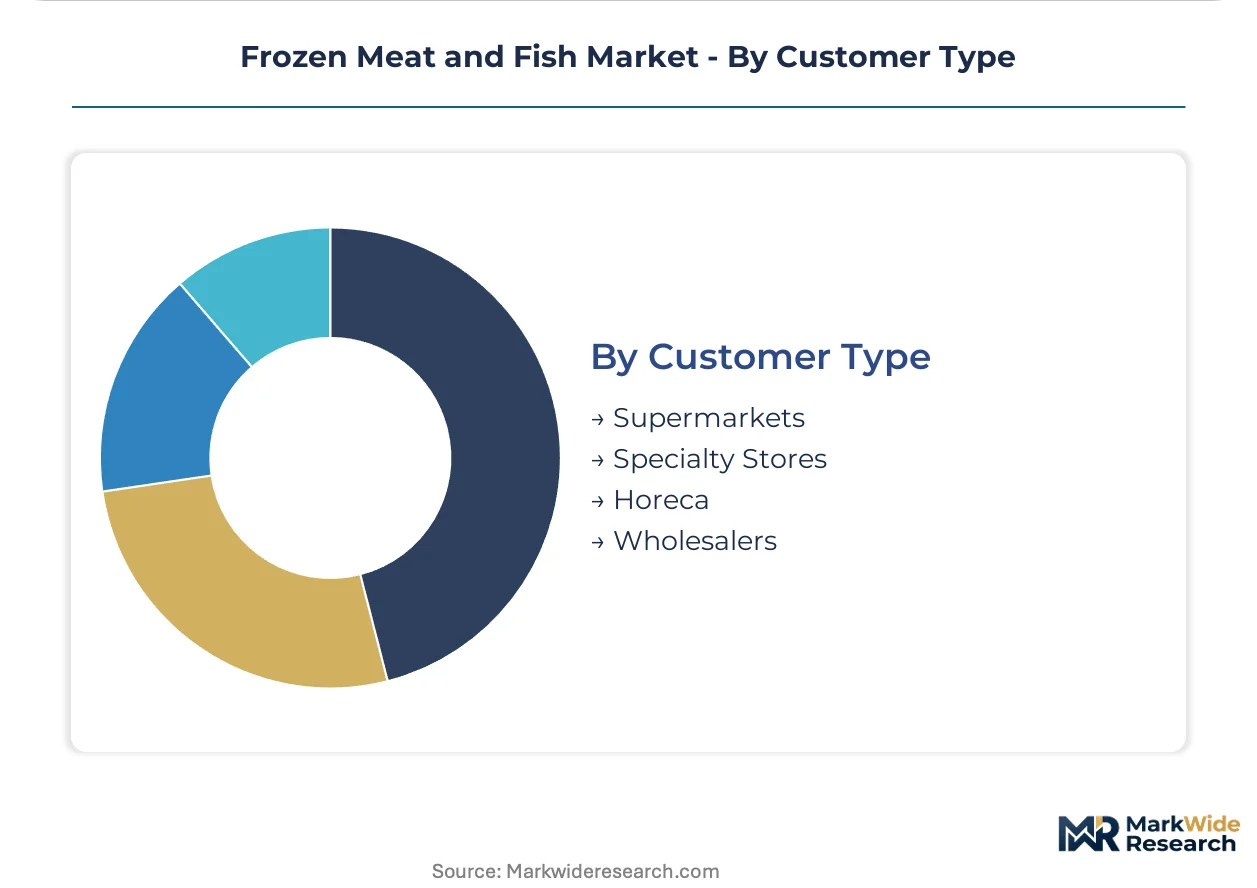
Customer Type:
Channel structure and buyer concentration reshape pricing power and distribution economics across frozen protein procurement tiers.
- Supermarkets:Large-format retail chains negotiate direct mill contracts for private-label frozen beef, poultry, and seafood lines. Buyer consolidation in Dubai and Singapore is displacing fragmented distributor relationships.
- Specialty Stores:Halal butchers, organic retailers, and ethnic grocers source certified frozen proteins with provenance documentation. Lagos and Nairobi cold store construction is creating first-mover advantage for specialty poultry distributors.
- Horeca:Hotels, restaurants, and cafes demand flexible portion sizes and just-in-time delivery from frozen protein distributors. Cruise line and resort catering operations in the Caribbean and Mediterranean contract directly for bulk frozen beef tenders.
- Wholesalers:Regional distributors aggregate frozen protein volumes for fragmentation to smaller retail and foodservice accounts. Cold chain technician scarcity in Southeast Asian port zones constrains wholesaler facility expansion.
Supermarkets absorb the bulk of installed capacity; horeca is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Manaus Free Trade Zone and Vietnam's Chu Lai Open Economic Zone are accelerating frozen protein processing investments through tax holidays and duty exemptions on cold-chain equipment imports.
United States
Quick-service restaurant chains and hotel operators drive frozen beef and poultry procurement volumes. FDA and USDA inspection protocols mandate pathogen testing and temperature documentation for imported proteins, shaping supplier qualification timelines. Port modernization at Houston and Savannah is expanding reefer container throughput capacity for Latin American exporters.
Brazil
Beef and poultry processing clusters serve Atlantic trade routes with expanding cryogenic tunnel capacity. ANVISA import sanitation protocol modernization is streamlining eligibility for re-export hubs. São Paulo state cold-store construction is creating distribution advantages for frozen pork exporters targeting Middle Eastern retail channels.
Vietnam
Central kitchen conversion among chain operators is standardizing frozen protein procurement across franchise networks. Port infrastructure investments at Hai Phong are reducing reefer vessel turnaround times for seafood re-export. Da Nang processing zones are attracting Japanese and South Korean IQF technology licensing agreements.
Germany
Supermarket private-label demand concentrates procurement of vacuum-sealed beef and pork configurations. EU Green Deal carbon disclosure mandates for refrigerated logistics are qualifying efficient operators for retail shelf access. Hamburg port cold-chain facilities are retrofitting with lower-GWP refrigerants to maintain EU market qualification.
Nigeria
Hotel chain expansion in Lagos and Abuja is converting procurement offices to direct frozen protein contracts. Cold store construction gaps are forcing capital deployment toward blast freezing infrastructure. Port modernization at Apapa is improving reefer container clearance velocity for poultry importers.
Frozen Meat and Fish Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across frozen protein value chains. Tyson Foods and JBS S.A. anchor consolidated positions through multi-species processing scale and captive distribution networks. Three archetypes dominate: vertically integrated agribusiness conglomerates, seafood-focused specialists with vessel-to-retail cold-chain control, and regional poultry processors with cryogenic tunnel investments. Competitive moves concentrate on M&A for geographic footprint expansion and strategic partnerships for IQF technology licensing.
Among US-based agribusiness conglomerates, Tyson Foods, Inc. and Cargill, Incorporated exemplify scale-driven diversification across beef, poultry, and pork categories. Maruha Nichiro Corporation represents the seafood-specialist archetype with deep cold-chain integration from harvest through retail shelf presentation. JBS S.A. anchors the Brazilian-origin processing tier with multi-continental beef and pork operations. These three entities occupy distinct competitive positions without direct product overlap, reducing price-based confrontation while concentrating procurement leverage against upstream suppliers.
| Leading Market Players |
|---|
| Tyson Foods, Inc. |
| JBS S.A. |
| Cargill, Incorporated |
| Thai Union Group PCL |
| Mowi ASA |
| Conagra Brands, Inc. |
| Maruha Nichiro Corporation |
| Perdue Farms, Inc. |
| Nomad Foods Limited |
| Others |
Supply & Pricing Matrix
Quick-service restaurant procurement consolidation across Vietnam and Nigeria is forcing blast freezing capacity additions in Southeast Asian port zones, compressing margins for operators unable to secure long-term energy contracts. This demand-side pressure reshapes supplier economics as cold chain capex intensity concentrates pricing power among integrated processors with captive freezing infrastructure.
Pricing Analysis
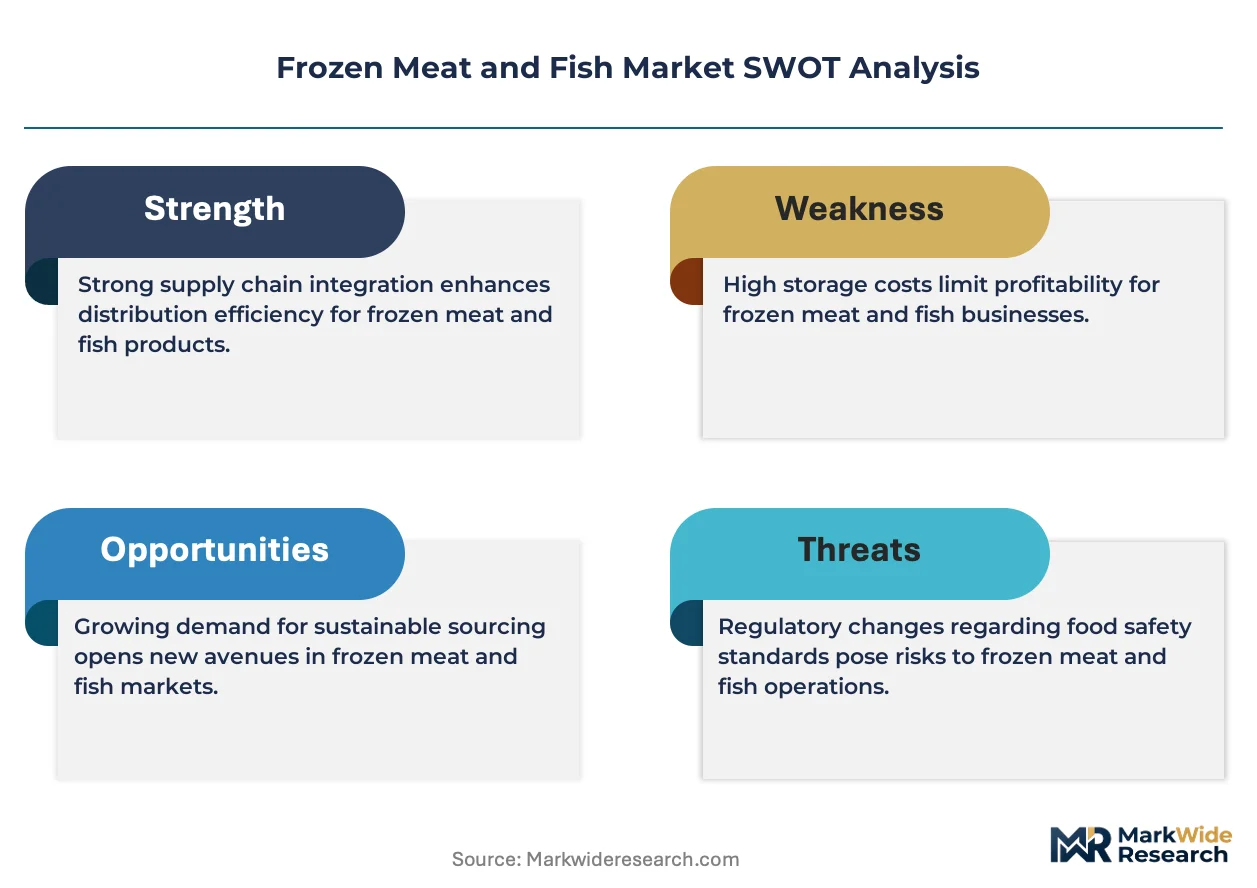
Lead-time premiums dominate frozen protein pricing as hotel chains in Dubai and Singapore pay above-spot rates for guaranteed vessel-to-freezer documentation. Three-tier pricing structure across premium, standard, and economy levels separates IQF seafood portions with full traceability from bulk-packed commodity tenders and unbranded tray-pack retail cuts. Pricing pressure stems from natural gas volatility in Germany and South Korea freezing facilities. Foodservice distributors exhibit highest price sensitivity due to thin menu margins, while cruise line procurement offices accept premium positioning for consistency guarantees.
Supply Chain Analysis
Certification gating through FDA pathogen testing and EU Green Deal carbon disclosure mandates shapes supplier qualification timelines and eligibility for retail shelf access. Supply concentrates in Brazil, Vietnam, and Thailand as primary processing hubs, with Australia and New Zealand anchoring halal lamb exports to Gulf Cooperation Council markets. Raw material dependencies center on wild-catch tuna quotas, grain-finished beef carcasses, and cryogenic refrigerant supply. Single-source vulnerability in Pacific Rim vessel fleets for premium cod creates harvest variability exposure. Distribution runs through regional cold-store aggregators in Lagos, Nairobi, and São Paulo serving fragmented wholesale accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blast freezing technician scarcity across Southeast Asian port zones props pricing for operators with in-house maintenance capabilities, creating durable margin advantages for integrated incumbents.
For Market Incumbents: Hedge against energy cost volatility by securing long-term natural gas contracts for German and South Korean freezing facilities. Backward integration into cryogenic tunnel manufacturing through licensing partnerships with Japanese technology providers defends margin position against capital-light re-export competitors in Vietnam and Nigeria. For New Entrants and Emerging Players: Begin with underpenetrated African retail cold-store construction in Lagos and Nairobi, where first-mover advantage in frozen poultry distribution remains unclaimed. Target specialty halal-certified lamb segments serving ethnic grocers in European urban centers, leveraging direct mill contracts to bypass entrenched wholesaler relationships. For Investors and Strategic Acquirers: The window for entry favors seafood-specialist operators with vessel-to-retail cold-chain control and documented lower-GWP refrigerant retrofits qualifying for EU shelf access. Watch for ANVISA protocol modernization completion as inflection signal for Brazilian re-export hub consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| IQF Technology Licensing | Japanese equipment providers capture premium positioning as Vietnamese processors expand cryogenic tunnel capacity. |
| Backward Integration into Cold-Chain Logistics | Tyson Foods and JBS S.A. defend margin structures through captive reefer fleet procurement and port facility ownership. |
| Modified Atmosphere Packaging Scale-Up | Vacuum-seal and gas-flush configurations unlock premium supermarket channels in Germany and France. |
| Halal Certification Investment | Australian and New Zealand processors secure Gulf Cooperation Council retail access through religious slaughter protocol compliance. |
| Lower-GWP Refrigerant Retrofit | EU Green Deal qualification hinges on documented carbon footprint reduction across Hamburg and Rotterdam port facilities. |
Research Methodology
Independent corroboration across cold-chain logistics operators, quick-service restaurant procurement directors, and supermarket category buyers underwrites the qualitative findings in this study. Primary interviews with blast freezing facility engineers, port authority reefer terminal managers, and ANVISA regulatory affairs specialists combined with secondary validation from FDA import inspection records, EU EFSA sustainability disclosure filings, and Brazilian customs trade data. Bottom-up capacity assessments across São Paulo, Bangkok, and Ho Chi Minh City processing zones triangulate against top-down trade flow analysis.
Rate-of-change decomposition across the projection horizon isolates volume growth from price mix effects in beef, poultry, and seafood segments. The analytical framework models product type, packaging configuration, application channel, and customer concentration tier as primary segmentation dimensions. CAGRs derive from fitted trend extrapolation adjusted for regulatory inflection points including ANVISA modernization timelines and EU Green Deal implementation phases. Forecast inputs incorporate cryogenic tunnel capacity expansion pipelines and reefer container fleet procurement schedules.
Underlying measurement precision varies by segment; IQF seafood portions with documented traceability carry tighter precision than commodity bulk beef tenders subject to spot market volatility. Forecasts reflect documented assumptions regarding cold chain infrastructure investment continuity and energy price normalization trajectories. A model refresh is warranted upon material change in EU carbon disclosure enforcement intensity or Pacific Rim wild-catch quota allocations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Frozen Meat Market
Processed and Frozen Foods
Europe Freeze-Dried Products Market
Processed and Frozen Foods
Asia-Pacific Frozen Pizza Market
Processed and Frozen Foods
Asia-Pacific Frozen Yogurt Market
Processed and Frozen Foods
Global Frozen Breakfast Entrees/Sandwiches Market
Processed and Frozen Foods
Icebreakers Market
Processed and Frozen Foods
Freeze Dried Tropical Fruits Market
Processed and Frozen Foods
Latin America Frozen Finger Chips Market
Processed and Frozen Foods
Frozen French Fries Market
Processed and Frozen Foods
Dumplings Market
Processed and Frozen Foods
Processed and Frozen Vegetables Market
Processed and Frozen Foods
South America RTE Food Market
Processed and Frozen Foods
Freeze Dried Vegetables Market
Processed and Frozen Foods
Frozen Tart Shells Market
Processed and Frozen Foods
Scandinavia Frozen Food Market
Processed and Frozen Foods
Asia Pacific Frozen Desserts Market