
 Germany Endoscopy Devices Market | 2026-2036
Germany Endoscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Endoscopy Devices Market Foresight
The EU Medical Device Regulation is realigning the cost-of-entry calculus for manufacturers serving Germany, forcing upgrades to clinical evidence portfolios and quality management systems. Medtronic PLC leverages its broad therapeutic endoscopy portfolio to sustain hospital contracting relationships across German federal states. KARL STORZ SE & Co. KG anchors its position through rigid endoscope specialization and in-house production of optical components. Richard Wolf GmbH differentiates via integrated OR infrastructure that combines endoscopic instruments with surgical visualization towers.
Germany endoscopy devices encompass optical and digital instrument systems—typically featuring distal tip diameters of 1.9 mm to 13 mm, CMOS or CCD image sensors, and integrated irrigation/insufflation channels—designed for diagnostic visualization and therapeutic intervention within hollow organs and body cavities. Flexible endoscopes dominate procedure volumes in gastroenterology and pulmonology, while rigid systems command premium pricing in orthopedic and urologic surgical suites. High-definition imaging technology leads installed-base upgrades, though narrow band imaging gains traction in early cancer detection protocols across German oncology networks. Video endoscopes capture expanding share as hospitals phase out analog fiber-optic systems.
The Federal Institute for Drugs and Medical Devices enforces post-market surveillance under the EU MDR transition, while DIN standards govern sterilization validation for reusable devices. Germany's statutory health insurance system, through the Institute for Quality and Efficiency in Health Care, shapes reimbursement thresholds that filter device adoption into ambulatory versus inpatient settings. Stakeholders must monitor the interplay between centralized procurement by hospital alliances and emerging quality-based reimbursement models that reward diagnostic accuracy over procedure volume.
Market Dynamics
The EU MDR is compressing manufacturer timelines for clinical evidence generation while Bavarian and North Rhine-Westphalian hospital alliances centralize procurement, creating simultaneous pressure on compliance costs and pricing power.
Growth Catalysts
- EU MDR conformity requirements:The Medical Device Regulation mandates upgraded quality management systems that favor established manufacturers with robust clinical documentation, filtering out marginal competitors and consolidating procurement relationships.
- Minimally invasive surgical expansion:German university medical centers in Heidelberg and Tübingen are scaling laparoscopic and arthroscopic program volumes, driving replacement cycles for rigid endoscope systems.
- Narrow band imaging protocols:Oncology networks across Baden-Württemberg are embedding NBI-enhanced detection into standardized screening pathways, accelerating demand for video processor upgrades.
Market Restraints
- Optical component supply concentration:German endoscope manufacturers depend on captive in-house production or limited Japanese suppliers for high-precision rod lens systems, creating vulnerability to input bottlenecks.
- Reprocessing cost escalation:DIN EN ISO 17664 sterilization validation requirements for reusable flexible endoscopes are extending turnover times and consuming specialized technician labor.
- Single-use endoscope substitution:Bronchoscopy and cystoscopy segments face displacement pressure from disposable alternatives that eliminate cross-contamination liability and reprocessing infrastructure.
Strategic Opportunities
- Ambulatory surgery center penetration:Outpatient endoscopy volumes in Saxony and Thuringia remain below western German benchmarks, presenting expansion targets for mobile visualization units.
- AI-assisted polyp detection:Computer-aided diagnosis algorithms are gaining CE marking under MDR, enabling premium positioning for integrated endoscope-processor systems.
- Hospital alliance direct contracting:Purchasing cooperatives like Rhön-Klinikum and Sana are consolidating vendor panels, rewarding suppliers with full OR integration capabilities.
Industry Challenges
- Specialized technician shortages:Reprocessing departments face recruitment gaps for DIN-certified sterile supply professionals capable of complex endoscope decontamination.
- Legacy system integration friction:Analog fiber-optic inventories in smaller municipal hospitals resist phased upgrade to digital video platforms due to capital constraint and workflow disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Endoscopy Devices Market |
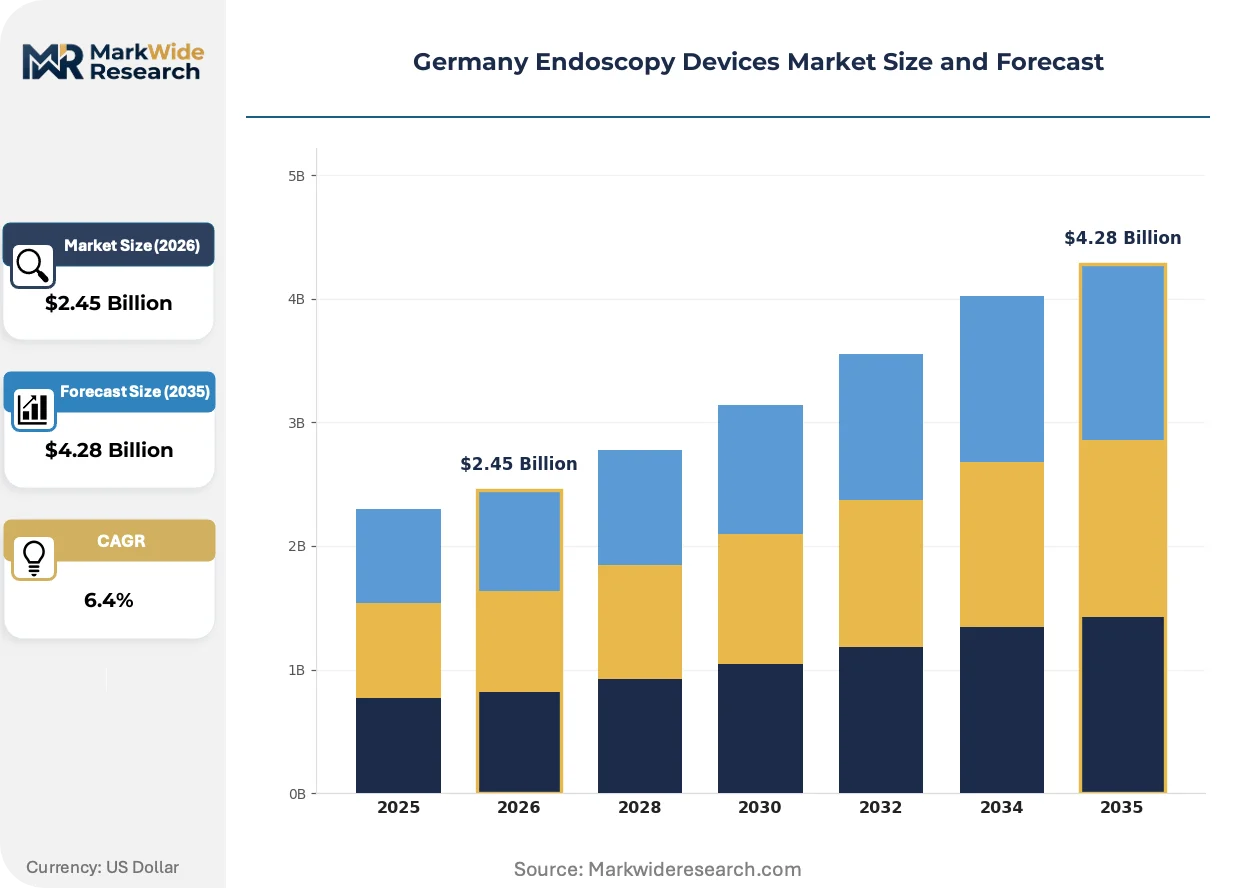
| Market Size in 2026 | $2.45 Billion |
| Market Size in 2035 | $4.28 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Endoscopes, Rigid Endoscopes, Capsule Endoscopes, Video Endoscopes Application: Gastroenterology, Pulmonology, Urology, Gynecology, ENT End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Specialty Clinics Technology: High-Definition Imaging, Narrow Band Imaging, 3D Visualization, Ultrasound Endoscopy |
| Companies Covered | Medtronic PLC, B. Braun Melsungen AG, Olympus Medical Systems Corporation, Richard Wolf GmbH, Fujifilm Holdings Corporation, KARL STORZ SE & Co. KG, Stryker Corporation, Johnson & Johnson, Boston Scientific Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Endoscopy Devices Market Shifts & Advancements
Digital imaging architectures and regulatory evidence requirements are simultaneously elevating technical barriers and reshaping competitive positioning across German endoscopy supply chains.
4K and 3D visualization systems are rewriting the standard for surgical precision in German orthopedic and urologic suites. University hospitals in Munich and Berlin are completing installed-base upgrades at compressed replacement cycles. The technology is compressing differentiation space for manufacturers lacking native optical component production.
MDR post-market surveillance obligations are extending clinical follow-up timelines for reusable endoscope manufacturers. The Federal Institute for Drugs and Medical Devices is intensifying adverse event reporting scrutiny. German rigid endoscope specialists are absorbing compliance costs through vertical integration into optical manufacturing.
Hospital procurement alliances are unbundling service contracts from capital equipment sales in favor of performance-guaranteed utilization models. Vendor risk is transferring to outcome-based maintenance commitments. This pattern concentrates in North Rhine-Westphalia's integrated care networks.
Germany Endoscopy Devices Market Segmentation
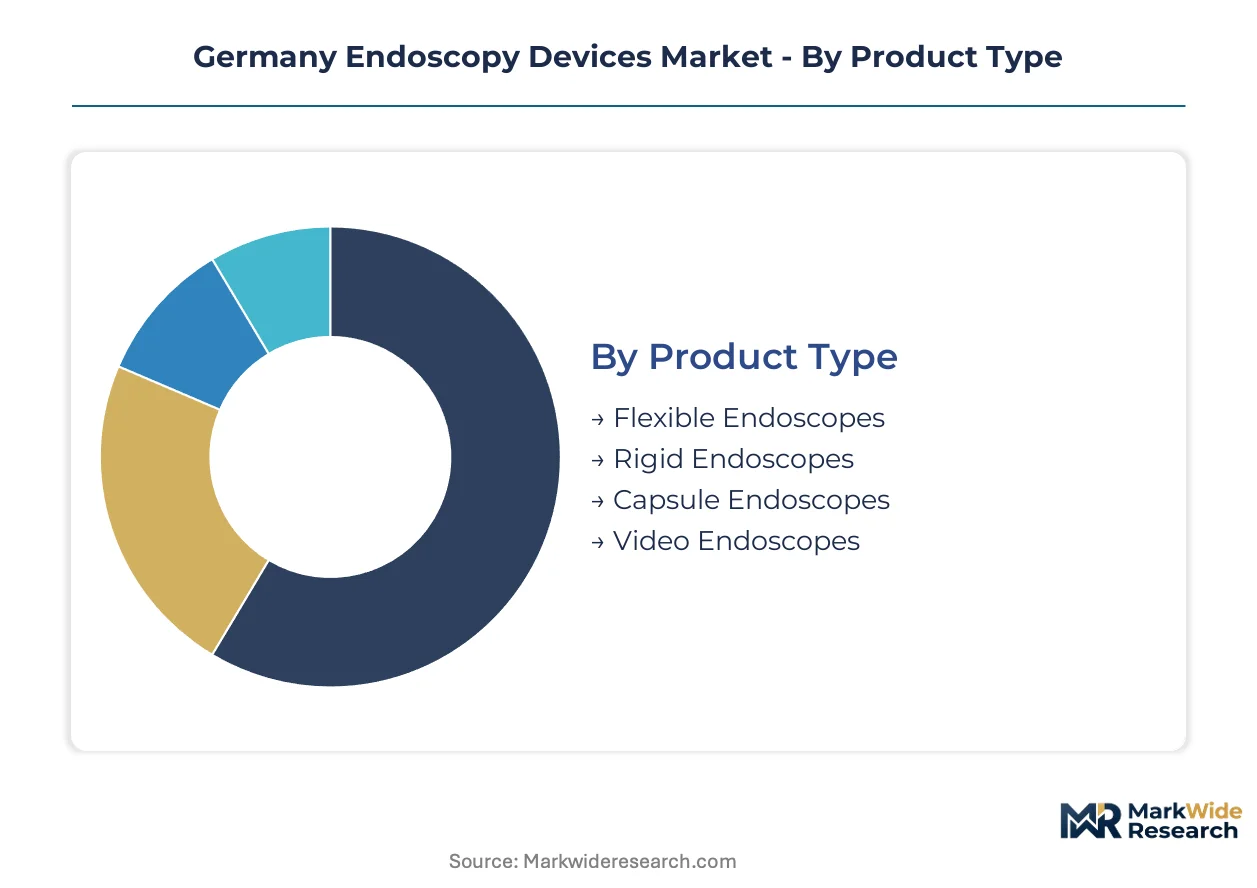
German endoscopy procurement patterns diverge sharply across product architectures and clinical settings. Hospital alliance purchasing decisions increasingly hinge on compatibility with existing visualization infrastructure and MDR compliance documentation rather than standalone device specifications.
Product Type:
Replacement cycles for installed-base systems are accelerating as Bavarian and North Rhine-Westphalian hospital groups consolidate vendor relationships around integrated platform upgrades.
- Flexible Endoscopes:Fiber-optic or video-based instruments with steerable distal tips navigate tortuous anatomical pathways during gastrointestinal and pulmonary procedures. Heidelberg University Hospital and Charité Berlin anchor procurement volumes for multi-channel systems with integrated irrigation and biopsy capabilities.
- Video Endoscopes:Digital CMOS/CCD sensor systems deliver high-definition output directly to processor units, eliminating fiber-optic image degradation. Municipal hospitals across Baden-Württemberg are phasing out analog inventories in favor of these platforms to meet narrow band imaging protocol requirements.
- Rigid Endoscopes:Rod-lens optical systems command premium positioning in orthopedic arthroscopy and urologic resection suites.
- Capsule Endoscopes:Ingestible wireless imagers target small-bowel diagnostics where conventional scope insertion proves challenging.
Flexible endoscopes sit at the top of the volume ranking, with video endoscopes climbing the fastest as digital migration accelerates across western German hospital networks.
Application:
Procedure reimbursement thresholds under Germany's statutory health insurance system concentrate capital investment in diagnostic accuracy improvements rather than volume expansion.
- Gastroenterology:Colonoscopy and esophagogastroduodenoscopy procedures dominate installed-base utilization, with oncology networks embedding narrow band imaging into standardized screening pathways. The Institute for Quality and Efficiency in Health Care shapes ambulatory versus inpatient reimbursement differentials that filter device adoption.
- Pulmonology:Bronchoscopic biopsy and interventional procedures drive demand for ultrathin flexible systems with compatible therapeutic channels. Saxony's expanding ambulatory surgery center network presents underpenetrated demand for mobile bronchoscopy units.
- Urology:Cystoscopic and resectoscopic interventions favor rigid endoscope systems with integrated electrosurgical compatibility.
- Gynecology:Hysteroscopic diagnostic and operative procedures require specialized distension media management.
- ENT:Sinonasal and laryngeal applications demand compact rigid systems with angled optics.
Gastroenterology captures the largest procedure volume, while pulmonology gains share fastest through outpatient diagnostic expansion.
End User:
Capital allocation patterns split between centralized university medical center procurement and distributed ambulatory facility investment.
- Hospitals:University medical centers in Munich, Berlin, and Hamburg consolidate procurement through purchasing cooperatives, demanding full OR integration capabilities and outcome-based service contracts. These facilities drive replacement cycles for 4K and 3D visualization systems.
- Ambulatory Surgical Centers:Outpatient endoscopy volumes in Thuringia and Saxony trail western German benchmarks, creating expansion targets for mobile and leased visualization equipment.
- Diagnostic Laboratories:Standalone pathology-focused facilities concentrate on capsule endoscopy interpretation services.
- Specialty Clinics:Single-specialty practices in private gastroenterology maintain analog fiber-optic inventories longer due to capital constraints.
Hospitals command the dominant capital expenditure share, with ambulatory surgical centers expanding most quickly through regional network development.
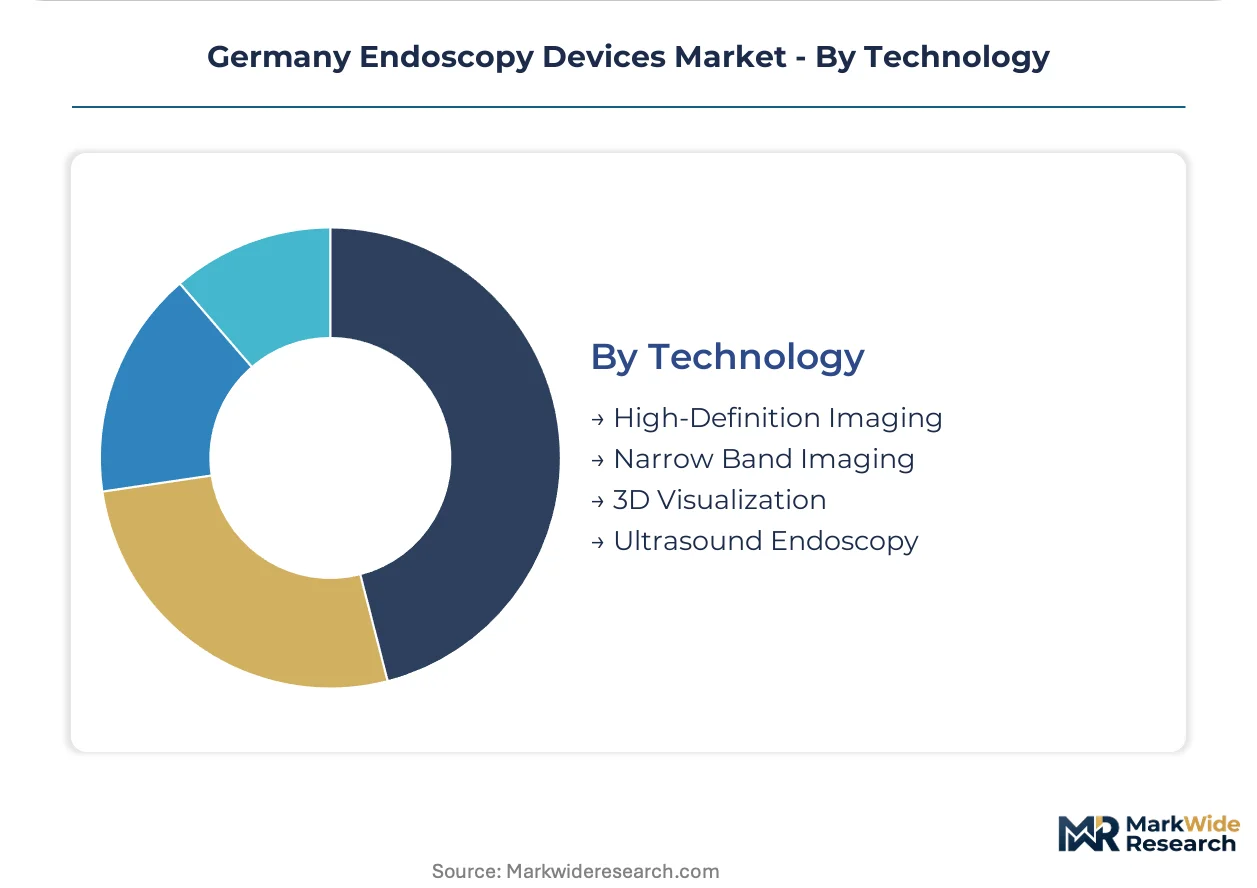
Technology:
Imaging modality selection increasingly ties to AI-assisted diagnostic algorithm compatibility and MDR clinical evidence requirements.
- High-Definition Imaging:1080p and 4K resolution standards now baseline for new installations across German surgical suites, with university hospitals completing compressed upgrade cycles.
- Narrow Band Imaging:Optical filter technology enhances mucosal vascular pattern visualization for early neoplasia detection, gaining traction across Baden-Württemberg oncology networks.
- 3D Visualization:Stereoscopic imaging systems command premium positioning in laparoscopic and robotic-assisted procedures.
- Ultrasound Endoscopy:EUS platforms integrate diagnostic imaging with fine-needle aspiration capabilities for pancreatic and biliary assessment.
High-definition imaging holds the largest installed base, with narrow band imaging gaining share fastest through screening protocol standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering talent clusters anchor endoscope manufacturing in Baden-Württemberg and Bavaria, while clinical demand concentrates in university hospital networks across western federal states.
Bavaria
Munich's university medical center drives procurement volumes for 4K visualization systems and integrated OR platforms. The Federal Institute for Drugs and Medical Devices enforces MDR post-market surveillance obligations that filter vendor selection toward established documentation portfolios. Erlangen and Nuremberg host manufacturing facilities for optical component production serving rigid endoscope assembly.
North Rhine-Westphalia
Cologne and Düsseldorf hospital alliances centralize purchasing decisions through cooperatives like Rhön-Klinikum, demanding outcome-based service contracts alongside capital equipment. DIN EN ISO 17664 sterilization validation requirements extend reprocessing infrastructure investment timelines. The Ruhr region maintains specialized technician training programs for sterile supply certification.
Baden-Württemberg
Heidelberg and Tübingen university hospitals anchor demand for narrow band imaging systems embedded in oncology screening protocols. The Institute for Quality and Efficiency in Health Care shapes reimbursement thresholds that prioritize diagnostic accuracy investments. Stuttgart's precision optics cluster supplies rod-lens systems to domestic rigid endoscope fabricators.
Berlin-Brandenburg
Charité Berlin consolidates procurement for multi-channel flexible systems with integrated therapeutic capabilities. MDR clinical evidence requirements compress manufacturer timelines for gastrointestinal device approvals. Potsdam's medical technology research institutes collaborate on AI-assisted polyp detection algorithm validation.
Hesse
Frankfurt's hospital networks phase out analog fiber-optic inventories in favor of digital video platforms. The statutory health insurance system filters ambulatory versus inpatient device adoption through reimbursement differentials. Darmstadt hosts reprocessing validation laboratories serving central German sterile supply departments.
Germany Endoscopy Devices Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with captive optical manufacturing capabilities. Consolidation pressures favor established players bearing MDR compliance costs across quality management system upgrades and clinical documentation portfolios. Three archetypes dominate: integrated conglomerates with full OR platform portfolios, rigid endoscope specialists with in-house optical production, and diversified therapeutics companies leveraging hospital contracting relationships. Competitive moves concentrate on backward integration into component supply and performance-guaranteed utilization contracts replacing traditional capital sales.
Among Germany-based fabricators, KARL STORZ SE & Co. KG and Richard Wolf GmbH exemplify the rigid endoscope specialist archetype through captive optical component production. Medtronic PLC represents the diversified therapeutics model with broad hospital contracting reach across federal states. These three companies anchor distinct competitive positions: KARL STORZ through in-house rod-lens manufacturing, Richard Wolf via integrated OR infrastructure combining instruments with visualization towers, and Medtronic through therapeutic endoscopy portfolio breadth sustaining multi-year procurement relationships.
| Leading Market Players |
|---|
| Medtronic PLC |
| B. Braun Melsungen AG |
| Olympus Medical Systems Corporation |
| Richard Wolf GmbH |
| Fujifilm Holdings Corporation |
| KARL STORZ SE & Co. KG |
| Stryker Corporation |
| Johnson & Johnson |
| Boston Scientific Corporation |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap specialists like KARL STORZ SE & Co. KG and Richard Wolf GmbH anchor German endoscope manufacturing through captive optical production, translating upstream control into pricing discipline that resists commoditization pressure from Asian competitors. Their in-house rod-lens fabrication insulates margin structures against component cost volatility while hospital procurement alliances extract concessions through outcome-based contracting.
Pricing Analysis
The bundled-vs-unbundled service split separates capital equipment sales from performance-guaranteed utilization contracts across North Rhine-Westphalian hospital alliances. Three-tier pricing structure across premium, standard, and economy levels tracks MDR certification grade and optical resolution specifications. Cost compression in mid-tier flexible endoscopes is intensifying because single-use substitutes eliminate reprocessing service revenue. Ambulatory surgical centers exhibit highest price sensitivity, while university medical centers prioritize integration capabilities over unit economics.
Supply Chain Analysis
Direct-to-hospital channels handle university medical center procurement volumes, while regional distributors serve municipal hospital networks across eastern federal states. Optical component fabrication concentrates in Germany and Japan, with CMOS sensor supply anchored in South Korean foundries. German manufacturers draw from captive rod-lens production, specialized glass suppliers, and precision machining subcontractors. Single-source vulnerability in high-precision optical glass creates exposure to input bottlenecks. Distribution runs through authorized service partners with DIN-certified reprocessing capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German endoscopy procurement has matured into a late-cycle quality story, with hospital alliances filtering vendor selection toward MDR-compliant documentation portfolios and 4K visualization specifications. Premium-tier demand now outpaces volume expansion as diagnostic accuracy reimbursement models displace procedure-based payment.
For Market Incumbents: Anchor hospital contracting relationships through backward integration into AI-assisted diagnostic algorithm development, countering displacement pressure from disposable bronchoscope substitutes. Prioritize DIN-certified reprocessing service contracts in Bavaria and North Rhine-Westphalia to lock in multi-year platform commitments. Defensive consolidation around optical component supply secures margin structure against Asian price competition. For New Entrants and Emerging Players: Enter via ambulatory surgery center networks in Saxony and Thuringia, where outpatient endoscopy volumes trail western German benchmarks by substantial margins. Target mobile visualization unit leasing models that circumvent capital expenditure barriers at smaller municipal hospitals. Partner with regional purchasing cooperatives on performance-guaranteed utilization contracts rather than capital sales approaches. For Investors and Strategic Acquirers: Valuations sit cheapest among rigid endoscope specialists with captive optical manufacturing but limited therapeutic portfolio breadth. Five-to-ten-year viability hinges on MDR compliance cost absorption and AI integration capabilities. Target acquisition archetype: mid-scale German fabricators with DIN-certified reprocessing infrastructure and university hospital installed base. Monitor CE marking timelines for computer-aided polyp detection algorithms as inflection indicator for premium positioning potential.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR clinical evidence requirements compress approval timelines for AI-integrated video processors. |
| Hospital System Partnership | Rhön-Klinikum and Sana cooperatives consolidate vendor panels around full OR integration capabilities. |
| Backward Integration | In-house rod-lens production insulates KARL STORZ and Richard Wolf against Japanese supplier bottlenecks. |
| Software Companion Development | AI-assisted polyp detection algorithms gain premium positioning through Institute for Quality and Efficiency validation. |
| Reimbursement Strategy | Narrow band imaging protocol adoption aligns with statutory health insurance diagnostic accuracy incentives. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with hospital procurement managers, biomedical engineers, GPO contracts managers, and sterile supply technicians with secondary validation. Primary fieldwork drew from hospital alliance purchasing committees, Federal Institute for Drugs and Medical Devices regulatory filings, DIN standards documentation, and Institute for Quality and Efficiency reimbursement determinations. Secondary sources encompassed EU MDR transition databases, hospital procurement registries, and medical technology trade flow records. Bottom-up installed-base modeling and top-down market sizing triangulated volume estimates across flexible, rigid, and video endoscope categories.
Historical reference periods anchored the projection horizon through segmented demand modeling that disaggregated gastroenterology, pulmonology, urology, gynecology, and ENT applications by technology tier and end-user setting. CAGRs derived from replacement cycle analysis, MDR compliance cost absorption rates, and AI integration adoption curves. Segmentation dimensions spanned product architecture, clinical application, end-user facility type, and imaging modality. Forecast inputs incorporated university medical center capital expenditure patterns, ambulatory surgery center network expansion timelines, and narrow band imaging protocol standardization rates across oncology networks.
Inputs from hospital procurement databases and GPO contract repositories were available through the study window; gaps in real-time reprocessing cost accounting at municipal hospitals introduce uncertainty bands around service revenue projections. Forecasts reflect assumptions regarding MDR transition timelines, AI algorithm validation pathways, and single-use substitution elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Endoscopy Visualization Systems Market
Endoscopy
North America Disposable Endoscopes Market
Endoscopy
Endoscope Optics Objective Lenses Market
Endoscopy
US Colonic Stents Market
Endoscopy
Chip-On-The-Tip Endoscopes Market
Endoscopy
North America Endoscopy Devices Market
Endoscopy
Endoscope Tracking Solutions Market
Endoscopy
Global Veterinary Endoscopes Market
Endoscopy
Endoscopy Video Systems Market
Endoscopy
Global Colonoscopy Devices Market
Endoscopy
Gastrointestinal Endoscopy Devices Market
Endoscopy
Rigid Endoscopes Market
Endoscopy
Australia Endoscopy Devices Market
Endoscopy
Global Veterinary Endoscopy Market
Endoscopy
Disposable Bronchoscopes Market
Endoscopy
Canada Endoscopy Devices Market