
 Global Flexible Endoscopes Market | 2026-2036
Global Flexible Endoscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flexible Endoscopes Market Foresight
Ambulatory surgery centers is rotating toward flexible endoscopy suites as hospitals defer capital expenditures on fixed installations. Olympus Corporation dominates the gastrointestinal flexible endoscope segment through its captive supply of imaging processors and proprietary connector architecture. FUJIFILM Holdings Corporation leverages its CMOS sensor foundry relationships to differentiate on image sensor integration. Ambu A/S competes with single-use flexible endoscopes that eliminate reprocessing liability for outpatient facilities.
Flexible endoscopes are elongated, steerable instruments incorporating fiber optic or digital image bundles, articulating distal tips with angulation ranges typically exceeding 180 degrees, and integrated working channels for biopsy or therapeutic tool passage; manufacturers extrude polymer jackets over braided stainless steel coil substrates to achieve torque stability and patient-safe flexibility. Video endoscopes lead the product type category as healthcare systems standardize on digital platforms that archive to PACS infrastructure. Narrow Band Imaging technology anchors the technology segment by enhancing mucosal vascular contrast without contrast dye administration. Capsule endoscopes represent the fastest-growing product type as patients with Crohn's disease seek non-sedated small bowel evaluation pathways.
FDA 510(k) clearance timelines and EU MDR technical documentation requirements shape product launch cadences and market access costs for manufacturers serving Western markets. Japan's PMDA enforces stringent biocompatibility testing protocols that filter out lower-tier suppliers from the world's second-largest endoscopy market. China's NMPA accelerates review pathways for domestically manufactured flexible endoscopes under its innovation device designation. Stakeholders must monitor how single-use reimbursement codes evolve across Medicare, NHS England, and Japan's MHLW fee schedules, as these decisions will determine whether disposable platforms capture meaningful volume from reprocessed instruments.
Market Dynamics
The transition from fiber optic to CMOS-based digital imaging architectures is compressing replacement cycles and redefining vendor lock-in mechanisms across procurement departments.
Growth Catalysts
- EU MDR compliance deadlines:Stricter biocompatibility and sterilization validation requirements are filtering out lower-tier suppliers and consolidating procurement toward established manufacturers with full technical documentation capabilities.
- Ambulatory surgery center expansion:Outpatient facilities in the United States, Germany, and Japan are investing in portable, reprocessable flexible endoscopy suites to capture shifted procedural volume from inpatient settings.
- Narrow Band Imaging diffusion:Vascular contrast enhancement without dye administration is becoming standard-of-care for mucosal lesion detection, pulling replacement demand across gastroenterology departments.
Market Restraints
- Stainless steel coil and polymer supply concentration:Braided substrate manufacturing clusters in Japan and Germany create input bottlenecks when medical-grade polymer extrusion capacity tightens.
- FDA 510(k) review timelines:Extended clearance durations for novel connector architectures delay product launches and compress revenue recognition windows for Western market entrants.
- Single-use endoscope cost premium:Per-procedure economics of disposable platforms remain unfavorable against reprocessed instruments where sterilization infrastructure is already amortized.
Strategic Opportunities
- China's NMPA innovation pathway:Accelerated review for domestically manufactured flexible endoscopes enables local production partnerships to bypass import tariff structures.
- Capsule endoscopy for Crohn's monitoring:Non-sedated small bowel evaluation is capturing patient preference in gastroenterology practices seeking to reduce anesthesia-related throughput constraints.
- CMOS sensor foundry integration:Direct relationships with semiconductor fabricators allow imaging pipeline optimization outside proprietary processor architectures.
Industry Challenges
- Reprocessing technician certification gaps:High-complexity flexible endoscope sterilization requires specialized training that outpaces workforce pipeline expansion in outpatient settings.
- PACS integration complexity:Digital video endoscope archives must interface with legacy hospital information systems, extending deployment timelines and technical validation requirements.
- EU MDR technical documentation burden:Clinical evidence requirements for legacy product line renewals are consuming regulatory affairs bandwidth and delaying next-generation submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flexible Endoscopes Market |
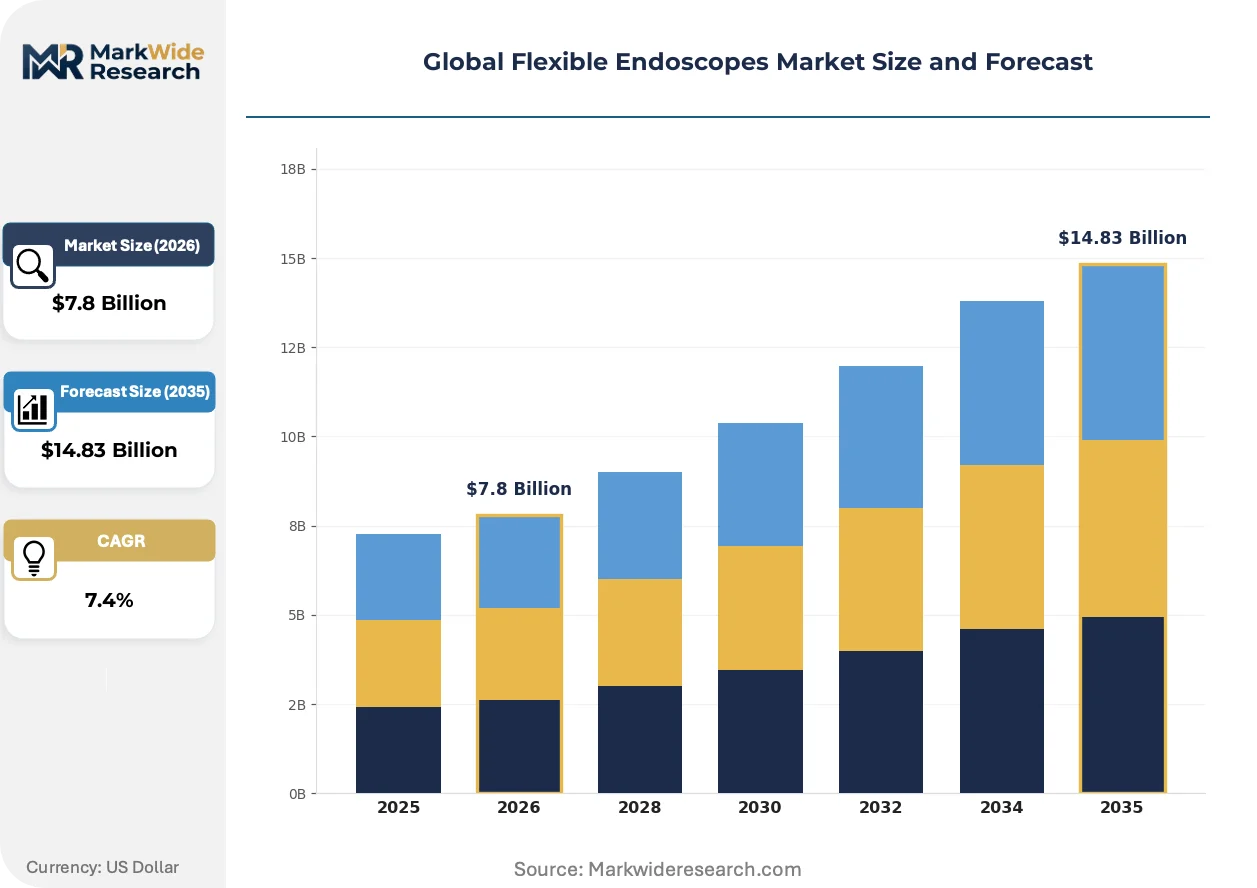
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $14.83 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Video Endoscopes, Fiberscopes, Capsule Endoscopes, Digital Endoscopes, High-Definition Endoscopes Application: Gastroenterology, Pulmonology, Urology, ENT Procedures, Gynecology, Orthopedics End User: Hospitals, Ambulatory Surgery Centers, Diagnostic Laboratories, Specialty Clinics, Research Institutes Technology: Optical Coherence Tomography, Narrow Band Imaging, Confocal Laser Endomicroscopy, Autofluorescence Imaging |
| Companies Covered | Olympus Corporation, FUJIFILM Holdings Corporation, Boston Scientific Corporation, KARL STORZ SE & Co. KG, Stryker Corporation, Medtronic Plc, Richard Wolf GmbH, Ambu A/S, Becton Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flexible Endoscopes Market Shifts & Advancements
Digital imaging pipelines are displacing fiber optic bundles as the dominant visualization architecture, while regulatory frameworks and procurement behaviors co-evolve around platform standardization.
CMOS-based video endoscopes is supplanting fiber optic bundles in gastrointestinal and pulmonary applications. Academic medical centers in the United States and Japan are completing fleet conversions within compressed 18-to-24-month procurement windows. This technology shift is collapsing the aftermarket for standalone light sources and forcing imaging processor vendors toward integrated platform strategies.
Japan's PMDA has tightened biocompatibility testing protocols for repeated sterilization cycles, elevating documentation requirements for polymer jacket materials. Domestic manufacturers with captive polymer formulation capabilities are capturing share from import-dependent competitors. Gastroenterology device submissions now face extended validation timelines that favor incumbents with established testing infrastructure.
Outpatient facilities are unbundling capital acquisition from service contracts, separating equipment purchase from preventive maintenance and reprocessing validation. Independent service organizations are capturing aftermarket revenue previously retained by original equipment manufacturers. This pattern is most pronounced in Germany's ambulatory surgery center network, where procurement autonomy from hospital group purchasing organizations has expanded.
Global Flexible Endoscopes Market Segmentation
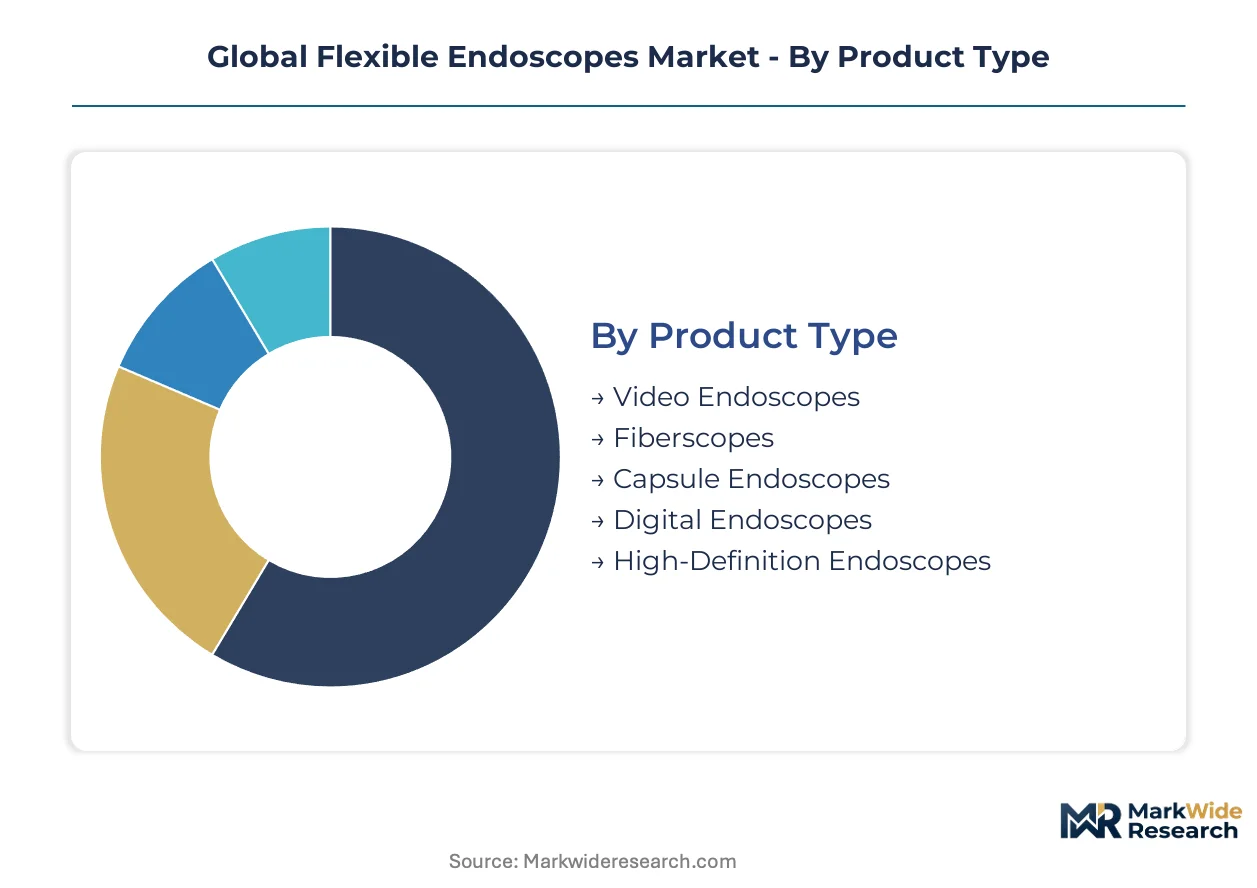
Flexible endoscope purchasing decisions fragment across imaging modality, procedural site, and sterilization infrastructure. Procurement committees weight capital amortization against per-procedure economics differently across hospital systems and outpatient networks.
Product Type:
Margin pools concentrate in platforms that integrate proprietary imaging processors with reusable instrument cycles.
- Video Endoscopes:CMOS sensor-based digital pipelines capture high-resolution mucosal visualization with direct PACS archive capability. United States academic medical centers are completing fleet conversions within compressed procurement windows to standardize digital platforms. Demand concentrates where hospitals seek to eliminate standalone light source maintenance and consolidate vendor relationships.
- Capsule Endoscopes:Ingestible wireless cameras transmit small bowel imagery without sedation or intubation. Patients with Crohn's disease in Germany and Japan are driving preference for non-sedated evaluation pathways that reduce anesthesia-related throughput constraints. This segment is expanding most quickly as gastroenterology practices seek to unblock procedural bottlenecks.
- Fiberscopes:Fiber optic bundles transmit illumination and image return through coherent glass fibers.
- Digital Endoscopes:Solid-state imaging chips replace fiber bundles entirely for enhanced durability.
- High-Definition Endoscopes:1080p or higher resolution sensors enable sub-millimeter lesion detection.
The dominant share belongs to Video Endoscopes, while Capsule Endoscopes is gaining share fastest.
Application:
Procedure volume distribution tracks chronic disease prevalence and screening program maturity across national healthcare systems.
- Gastroenterology:Colonoscopy and esophagogastroduodenoscopy procedures dominate flexible endoscope utilization. Screening program expansion in Japan and Germany sustains replacement demand for video endoscopy platforms. Reimbursement stability for colorectal cancer screening under Medicare and NHS England protects procurement budgets.
- Pulmonology:Bronchoscopy for lung nodule evaluation and interventional procedures requires smaller-diameter instruments with expanded working channels. United States thoracic surgery departments are investing in electromagnetic navigation bronchoscopy integration. Demand concentrates where lung cancer screening CT findings generate biopsy referral volume.
- Urology:Cystoscopy and ureteroscopy procedures employ flexible instruments for upper tract evaluation.
- ENT Procedures:Laryngoscopy and sinus examination utilize smaller-diameter flexible scopes.
- Gynecology:Hysteroscopy applications favor rigid instruments, limiting flexible scope penetration.
- Orthopedics:Arthroscopy remains predominantly rigid scope territory with limited flexible adoption.
Gastroenterology commands the largest procedure volume, though Pulmonology is climbing the fastest as lung screening programs mature.
End User:
Capital deployment patterns diverge between amortized infrastructure and per-procedure cost accounting.
- Hospitals:Integrated delivery networks leverage group purchasing organization contracts to standardize fleets across multiple campuses. United States health systems are extending replacement cycles to 7-10 years to defer capital expenditure. Demand concentrates where PACS integration requirements favor platform consolidation with established vendors.
- Ambulatory Surgery Centers:Outpatient facilities prioritize portable, reprocessable suites with lower sterilization infrastructure requirements. Germany's independent ambulatory network is unbundling equipment purchase from service contracts. These centers are capturing procedural volume shifted from inpatient settings.
- Diagnostic Laboratories:Reference labs employ endoscopy for specialized tissue acquisition protocols.
- Specialty Clinics:Gastroenterology and pulmonology single-specialty practices favor lease arrangements.
- Research Institutes:Academic research centers drive early adoption of novel imaging modalities.
Hospitals retain the dominant installed base, yet Ambulatory Surgery Centers is expanding most quickly as procedural migration accelerates.
Technology:
Imaging enhancement technologies differentiate on lesion detection sensitivity without workflow disruption.
- Narrow Band Imaging:Spectral filtering enhances mucosal vascular contrast without contrast dye administration. Japan's PMDA has recognized NBI as standard-of-care for Barrett's esophagus surveillance, pulling replacement demand across gastroenterology departments. Olympus Corporation and FUJIFILM Holdings Corporation compete on proprietary spectral band implementations.
- Optical Coherence Tomography:Cross-sectional tissue imaging enables subsurface architectural assessment. Academic medical centers in the United States and Germany are piloting OCT for pancreaticobiliary stricture evaluation. Demand concentrates where interventional endoscopists require real-time histology-equivalent feedback.
- Confocal Laser Endomicroscopy:Cellular-level resolution enables in vivo histopathology during ongoing procedures.
- Autofluorescence Imaging:Endogenous tissue fluorescence patterns highlight dysplastic mucosal changes.
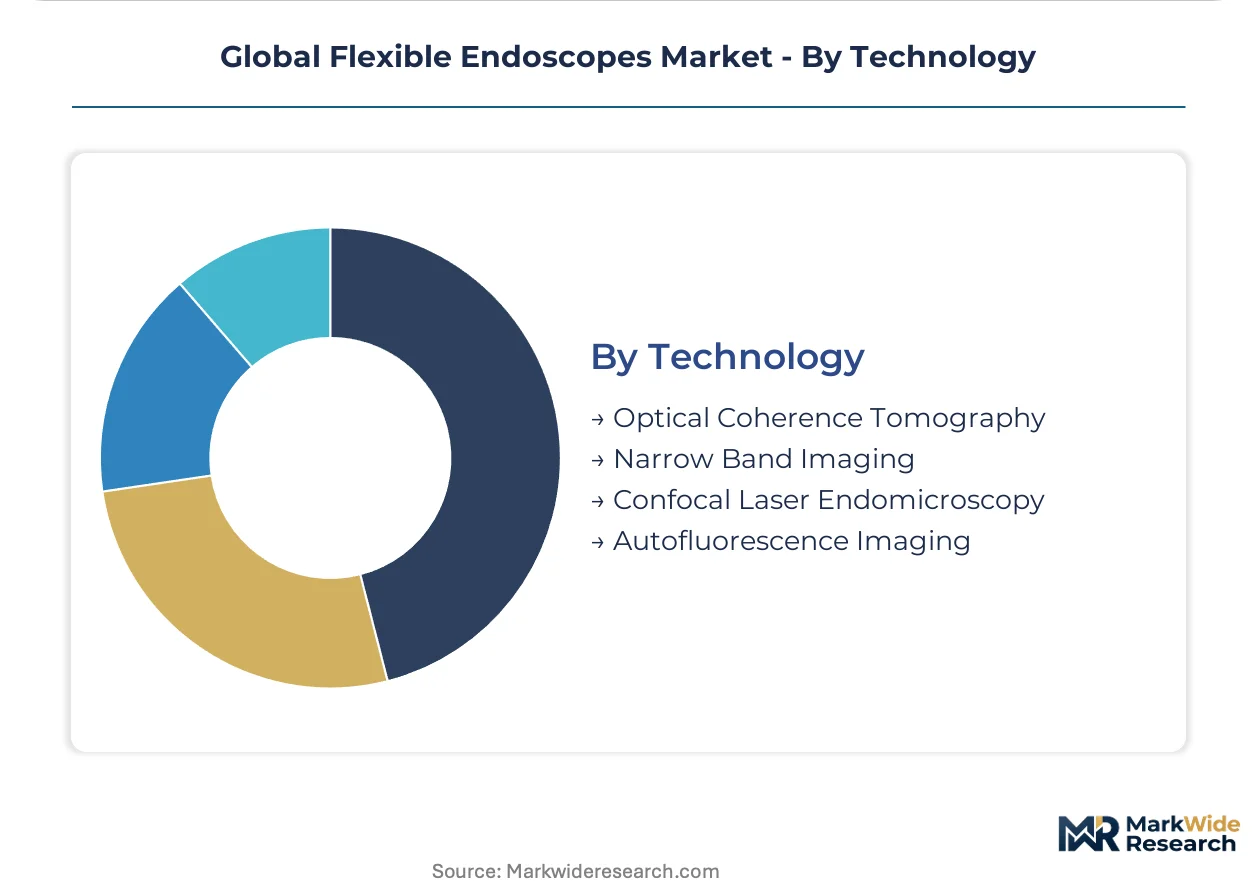
Narrow Band Imaging holds the dominant clinical position, while Optical Coherence Tomography shows the steepest expansion trajectory among advanced modalities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and German manufacturers control braided stainless steel coil substrates and polymer extrusion capacity, creating input bottlenecks that ripple through procurement timelines worldwide.
United States
Academic medical centers in Boston and the Research Triangle compress fleet conversion windows to 18-24 months for CMOS-based platforms. FDA 510(k) clearance timelines for novel connector architectures delay product launches and compress revenue recognition windows. Outpatient procedural volume concentrates in ambulatory surgery centers across Texas and Florida.
Germany
Independent ambulatory surgery centers in Bavaria and North Rhine-Westphalia unbundle equipment purchase from service contracts, expanding procurement autonomy. EU MDR technical documentation requirements filter lower-tier suppliers from Western European tenders. Stuttgart and Munich host polymer formulation clusters serving jacket extrusion needs.
Japan
PMDA biocompatibility testing protocols for repeated sterilization cycles elevate documentation requirements for polymer materials. Tokyo and Osaka gastroenterology departments drive Narrow Band Imaging standardization for Barrett's esophagus surveillance. Domestic manufacturers with captive polymer capabilities capture share from import-dependent competitors.
China
NMPA accelerates review pathways for domestically manufactured flexible endoscopes under innovation device designation, enabling local production partnerships to bypass import tariffs. Yangtze River Delta medical device clusters expand CMOS sensor integration capabilities. Shanghai and Suzhou concentrate reprocessing technician training programs.
Global Flexible Endoscopes Market Competitive Landscape
Concentration sits with diversified medical technology conglomerates that control imaging processor architectures and proprietary connector standards. The vendor base stratifies across three tiers: integrated platform owners with captive sensor supply, single-use specialists eliminating reprocessing liability, and regional fabricators serving price-sensitive procurement. Two dominant competitive moves reshape positioning: backward integration into CMOS sensor foundries and unbundling of equipment sales from service contract capture.
Within the integrated platform tier, Olympus Corporation and FUJIFILM Holdings Corporation anchor the gastrointestinal segment through imaging pipeline control. Ambu A/S occupies a distinct position with single-use architectures that eliminate sterilization infrastructure requirements for outpatient facilities. These three exemplify the strategic divergence between reusable platform consolidation and disposable model disruption.
| Leading Market Players |
|---|
| Olympus Corporation |
| FUJIFILM Holdings Corporation |
| Boston Scientific Corporation |
| KARL STORZ SE & Co. KG |
| Stryker Corporation |
| Medtronic Plc |
| Richard Wolf GmbH |
| Ambu A/S |
| Becton Dickinson and Company |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day lead times for medical-grade polymer extrusion from Stuttgart and Osaka concentrate pricing power with manufacturers holding captive jacket formulation capabilities, while outpatient buyers face compressed negotiation windows amid EU MDR compliance deadlines.
Pricing Analysis
EU MDR dictates the pricing tier structure across the flexible endoscope landscape. Three-tier pricing separates premium video endoscopes with integrated CMOS processors from standard fiber-optic bundles and economy-grade disposable alternatives. Price differentiation hinges on FDA 510(k) clearance tier and proprietary connector architecture exclusivity. Cost compression in the standard reusable tier is intensifying because independent service organizations now unbundle preventive maintenance from capital acquisition. Ambulatory surgery centers exhibit highest price sensitivity due to per-procedure accounting, while academic medical centers prioritize platform consolidation over unit economics.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for CMOS sensor shipments from Taiwanese foundries. Braided stainless steel coil manufacturing concentrates in Japan and Germany, while polymer jacket extrusion clusters in Stuttgart and Osaka. Raw material dependencies center on medical-grade silicone, polyether block amides, and cobalt-chromium alloys. Single-source vulnerability pervades the CMOS sensor layer where foundry capacity allocation favors consumer electronics. Distribution runs through original equipment manufacturer direct sales forces in hospital systems and independent distributors serving outpatient networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flexible endoscope market sits at a platform-economics inflection where CMOS-based digital architectures collapse standalone light source aftermarket value and force vendor lock-in around proprietary imaging processors.
For Market Incumbents: Secure backward integration into CMOS sensor foundries to bypass semiconductor allocation constraints from consumer electronics demand. Lock hospital systems into integrated platform contracts spanning imaging processors, connectors, and PACS archive compatibility before independent service organizations capture aftermarket revenue. The threat of single-use disposable alternatives from Ambu A/S and emerging entrants demands preemptive bundling of reprocessing validation services with capital equipment.
For New Entrants and Emerging Players: Differentiate on capsule endoscopy for Crohn's disease monitoring where patient preference for non-sedated pathways outpaces incumbent platform control. Target Germany's independent ambulatory surgery center network where procurement autonomy from hospital GPOs creates white-space access. Pursue NMPA innovation pathway partnerships in China's Yangtze River Delta to bypass import tariff structures and establish domestic manufacturing credibility.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because EU MDR technical documentation requirements and PMDA biocompatibility protocols filter out capital-constrained competitors. Acquisition targets should display captive polymer formulation capabilities and established sterilization validation infrastructure. Watch single-use reimbursement code decisions across Medicare, NHS England, and Japan's MHLW as the inflection signal determining whether disposable platforms capture meaningful volume from reprocessed instruments.
| Strategic Initiative | Industry Significance |
|---|---|
| CMOS Sensor Foundry Partnership | Direct semiconductor fabricator relationships bypass allocation constraints from consumer electronics demand. |
| EU MDR Technical Documentation Investment | Full clinical evidence capabilities filter lower-tier suppliers from Western European procurement tenders. |
| Single-Use Reimbursement Strategy | Medicare and MHLW fee schedule alignment determines disposable platform economics against reprocessing. |
| PACS Integration Certification | Legacy hospital information system compatibility extends deployment timelines and vendor stickiness. |
| NMPA Innovation Pathway Localization | Domestic manufacturing partnerships in Shanghai and Suzhou bypass import tariffs for China market access. |
Research Methodology
Initial hypotheses were tested against primary input from hospital purchasing committee members, biomedical engineers, GPO contracts managers, and ambulatory surgery center procurement directors and refined through secondary validation against FDA 510(k) clearance databases, EU MDR technical documentation filings, CMS Medicare reimbursement schedules, and hospital procurement contract repositories. Bottom-up demand modeling across gastroenterology and pulmonology procedure volumes triangulated with top-down manufacturer revenue analysis.
Variance decomposition across product type, application site, end-user facility scale, imaging technology tier, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from procedure volume elasticity to screening program expansion, replacement cycle compression from CMOS platform conversion, and single-use penetration scenarios. Forecast inputs incorporated PMDA biocompatibility testing timeline extensions and NMPA innovation pathway acceleration effects.
The analysis sits within stated boundaries; outcomes outside EU MDR compliance adherence, CMOS foundry capacity allocation stability, and single-use reimbursement code adoption would require recalibration. Forecasts reflect assumptions around sterilization infrastructure amortization rates and outpatient procedural volume migration patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Endoscopic Probe Disinfection Market
Endoscopy
China Arthroscopy Market
Endoscopy
Capsule Endoscopy Market
Endoscopy
Netherlands Endoscopy Devices Market
Endoscopy
Dermatology Endoscopy Devices Market
Endoscopy
Veterinary Video Endoscopy Market
Endoscopy
Global Endoscopes Market
Endoscopy
Endoscopy Fluid Management Systems Market
Endoscopy
Global Neuroendoscopy Market
Endoscopy
Endoscope Detergents and Disinfectants Market
Endoscopy
Endoscopy Operative Devices Market
Endoscopy
Disposable Bronchoscopes Market
Endoscopy
Saudi Arabia Endoscopy Devices Market
Endoscopy
Single Use Bronchoscopes Market
Endoscopy
Endoscopy Procedures Estimates Market
Endoscopy
Esophageal Stents Market