
 South Africa Endoscopy Devices Market | 2026-2036
South Africa Endoscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Endoscopy Devices Market Analytics
South African medical device distributors is broadening their endoscopy service networks across secondary cities. Medtronic leverages its established cardiac and surgical footprint to cross-sell visualization platforms into provincial hospitals. Olympus Corporation anchors the flexible endoscope segment through dedicated technician training programs in Durban and Cape Town. KARL STORZ competes on rigid endoscope specialization for orthopedic and ENT procedures in private hospital chains.
Endoscopy devices encompass optical and digital instrument systems designed for minimally invasive internal visualization, typically featuring image sensors with resolution parameters exceeding 1080p, fiber-optic or LED light delivery channels, and biopsy-compatible working channels measured in millimeters for tissue sampling during diagnostic or therapeutic procedures. These systems serve gastroenterology, pulmonology, urology, and gynecology by enabling direct mucosal inspection without open surgical access. Flexible endoscopes dominate procedure volume in South African public hospitals due to their adaptability through tortuous anatomical pathways, while robotic technology represents the fastest-growing segment as private facilities invest in precision-guided platforms. Visualization systems capture concentrated margin pools through recurring software licensing and proprietary image processing architectures.
The South African Health Products Regulatory Authority governs medical device registration and post-market surveillance, while the country's national health laboratory service standards influence infection control protocols for reusable endoscope reprocessing. BIS-equivalent conformity assessments and ISO 13485 quality management certifications shape which manufacturers gain public tender eligibility. Stakeholders must monitor National Health Insurance procurement framework developments and decide whether to align product portfolios with emerging centralized purchasing specifications or maintain direct relationships with private hospital groups.
Market Dynamics
The National Health Insurance procurement framework is restructuring buyer-seller relationships across South Africa's endoscopy device landscape, concentrating purchasing power within centralized tender mechanisms while fragmenting service delivery networks across provincial health systems.
Growth Catalysts
- SAHPRA Registration Alignment:Manufacturers achieving ISO 13485 certification alongside BIS-equivalent conformity assessments unlock public hospital tender eligibility, expanding addressable institutional demand.
- Robotic Platform Integration:Private hospital chains in Gauteng Province are integrating precision-guided visualization systems into orthopedic and urology service lines, creating premium procedure volume.
- Johannesburg-Pretoria Corridor Concentration:Healthcare infrastructure investment in this urban corridor concentrates diagnostic demand, enabling economies of scale in device deployment and technician training networks.
Market Restraints
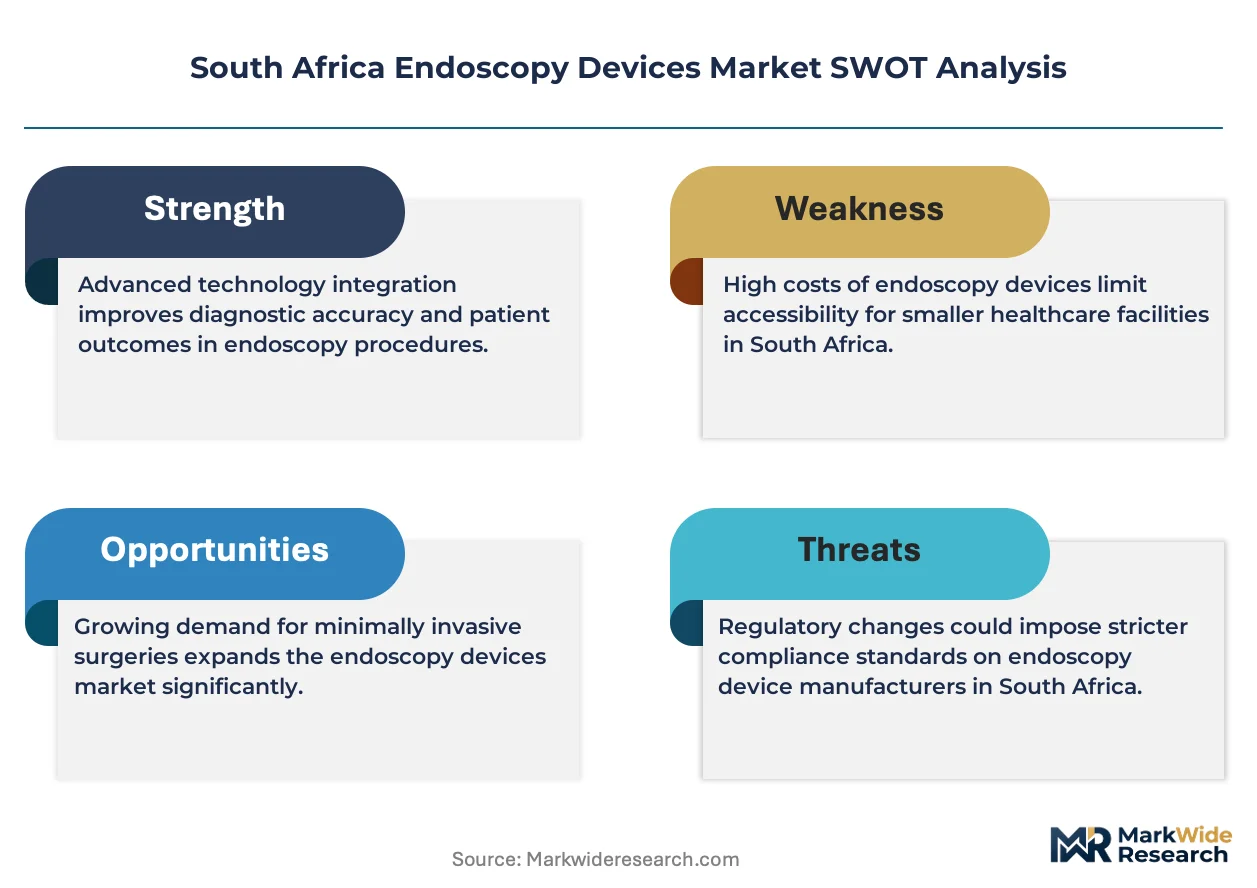
- Import Dependency:Fiber-optic component supply concentrates with Asian manufacturers, exposing South African distributors to currency volatility and extended lead times for critical replacement parts.
- Reprocessing Infrastructure Gaps:National Health Laboratory Service infection control protocols require capital-intensive sterilization systems that many secondary public hospitals cannot operationalize, limiting flexible endoscope utilization.
- Specialized Technician Scarcity:Durban and Cape Town anchor the nation's endoscope repair capacity, creating geographic bottlenecks for maintenance turnaround times in rural provinces.
Strategic Opportunities
- Eastern Cape Expansion:Secondary cities including Port Elizabeth and East London present underpenetrated demand for outpatient endoscopy services as provincial health budgets decentralize.
- AI-Enhanced Image Processing:Convergence of machine learning algorithms with proprietary visualization architectures enables automated polyp detection, differentiating premium system offerings.
- Leasing Model Penetration:Equipment-as-a-service contracts reduce upfront capital barriers for mid-tier private clinics, unlocking new customer segments beyond traditional hospital procurement.
Industry Challenges
- Biomedical Engineering Talent Pipeline:Universities produce insufficient graduates with combined optical-electronics expertise to service expanding device fleets across nine provinces.
- Legacy System Integration:Public hospitals operate mixed-generation endoscope fleets requiring adapters and software bridges that complicate standardization efforts and inflate total cost of ownership.
- SAHPRA Registration Timelines:Novel device categories face extended review periods that delay product launches and compress commercialization windows before technology obsolescence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Endoscopy Devices Market |
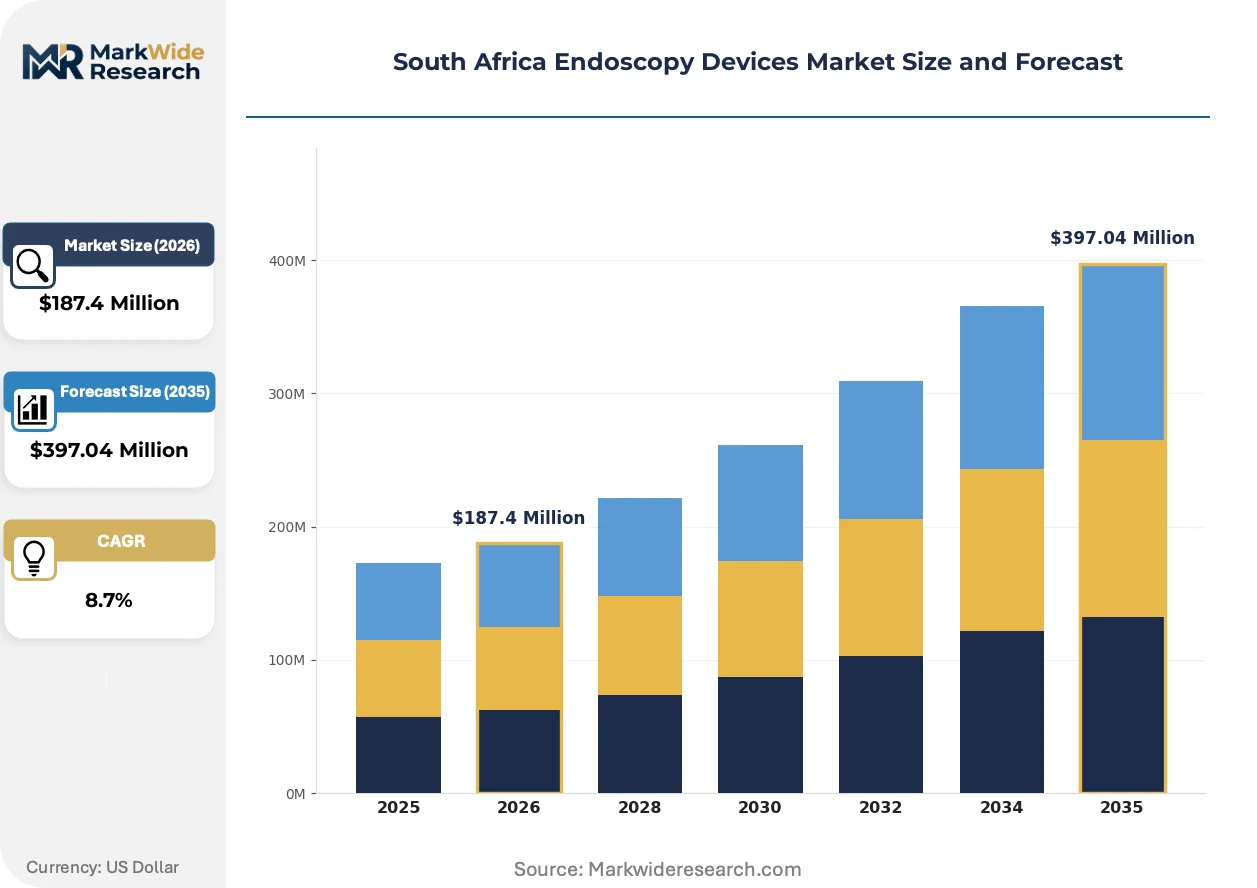
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsule Endoscopes, Rigid Endoscopes, Flexible Endoscopes, Visualization Systems Technology: Optical, Digital, Wireless, Robotic End User: Hospitals, Clinics, Outpatient Surgery Centers, Specialty Practices Application: Gastroenterology, Pulmonology, Urology, Gynecology |
| Companies Covered | FUJIFILM Holdings Corporation, Medtronic, Boston Scientific Corporation, Stryker Corporation, HOYA Corporation, Olympus Corporation, Johnson & Johnson, Richard Wolf GmbH, KARL STORZ, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Endoscopy Devices Market Evolving Landscape
Digital visualization architectures are displacing fiber-optic transmission across South African endoscopy suites, compressing equipment replacement cycles while elevating software licensing to a recurring revenue center for device suppliers.
Single-use endoscope technology is automating reprocessing compliance workflows in high-turnover public hospital settings. Gauteng Province's tertiary facilities are piloting disposable bronchoscope and cystoscope programs to eliminate cross-contamination risk. This automation is compressing capital allocation toward consumable supply chains rather than durable equipment maintenance infrastructure.
The South African Health Products Regulatory Authority's post-market surveillance requirements are intensifying adverse event reporting obligations for implantable and active diagnostic devices. Manufacturers must now maintain local vigilance capabilities with 24-hour response protocols. Flexible endoscope suppliers with established Johannesburg-based regulatory affairs teams are adapting faster than importers relying on distant headquarters.
Service unbundling is fragmenting traditional device-vendor relationships across private hospital chains. Purchasing departments are separating capital equipment acquisition from preventive maintenance contracts and software subscription renewals. This behavioral shift is most pronounced in Cape Town's consolidated private healthcare networks, where procurement teams negotiate each component through distinct tender processes.
South Africa Endoscopy Devices Market Segmentation
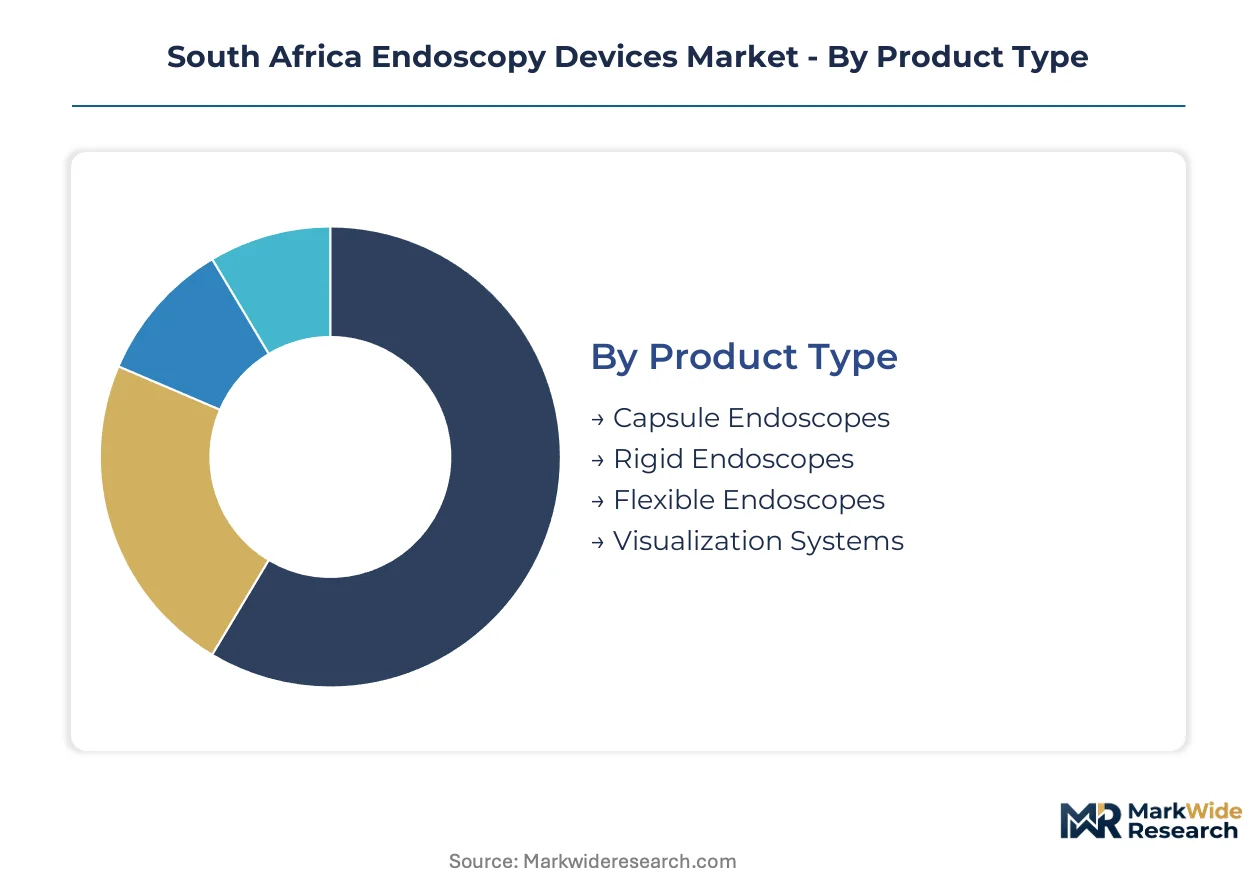
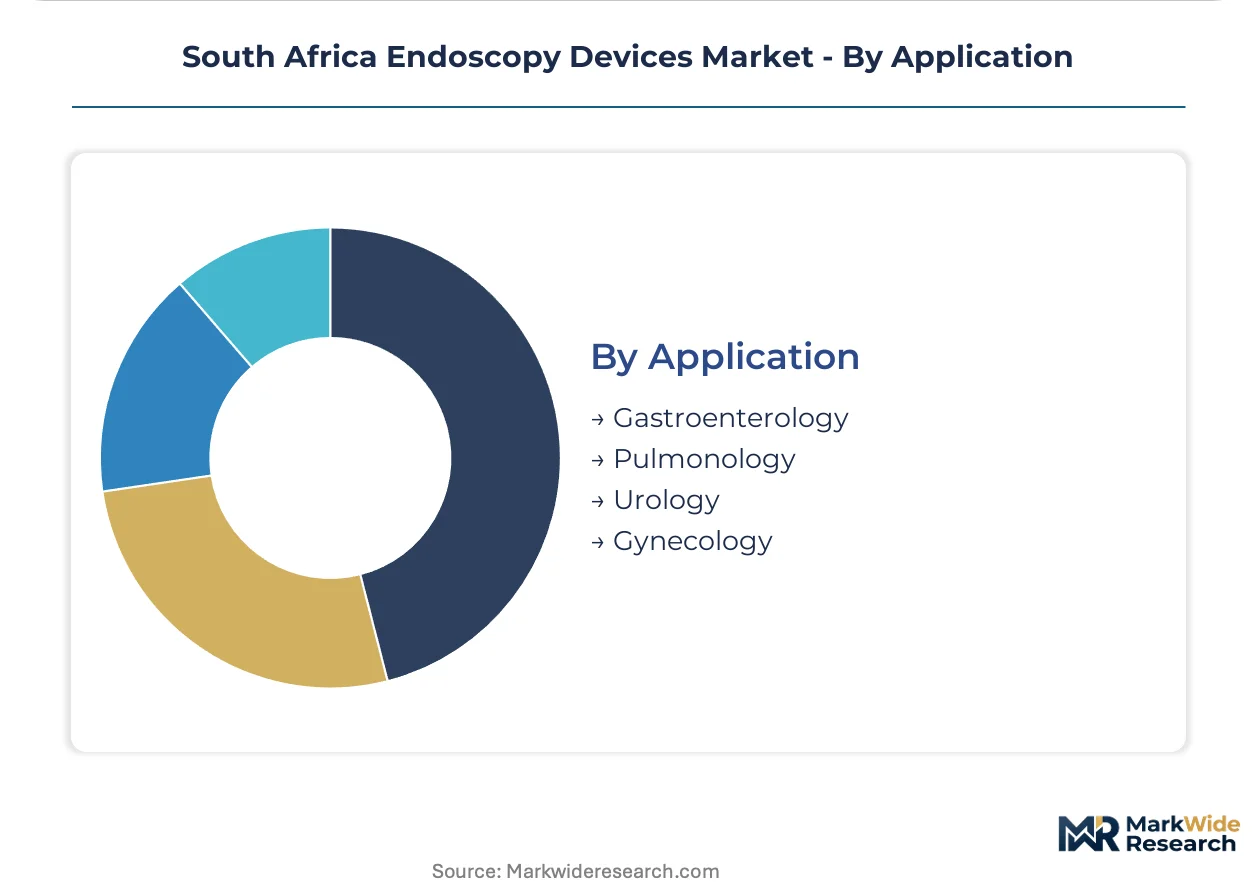
Endoscopy device segmentation in South Africa reveals distinct procurement patterns across public and private healthcare channels. Product type and technology choices directly correlate with capital availability and procedure volume at specific facility tiers.
Product Type:
Capital intensity varies sharply across product categories, with visualization systems and robotic platforms demanding multimillion-rand infrastructure commitments while capsule endoscopes operate on consumable-based models.
- Flexible Endoscopes:Fiber-optic or digital insertion tubes with articulating distal tips enable navigation through tortuous gastrointestinal and pulmonary anatomy. Gauteng Province's tertiary public hospitals concentrate demand for gastroscopy and colonoscopy units, though reprocessing infrastructure gaps in secondary facilities constrain deployment scale.
- Visualization Systems:Image processing hubs with proprietary software architectures and 4K display outputs anchor endoscopy suite investments. Private hospital chains in Johannesburg-Pretoria corridor prioritize these platforms for premium service differentiation and recurring licensing revenue capture.
- Rigid Endoscopes:Stainless steel optical systems with fixed lens configurations serve orthopedic arthroscopy and ENT procedures in surgical theaters.
- Capsule Endoscopes:Swallowable disposable imaging devices with wireless transmission capabilities address small bowel diagnostics without sedation requirements.
Flexible endoscopes absorb the bulk of installed capacity across South Africa's public health system; visualization systems are expanding most quickly in private capital deployment.
Technology:
Technology maturity determines replacement cycle timing and regulatory pathway complexity for SAHPRA registration.
- Digital:CMOS and CCD sensor-based imaging with integrated image enhancement algorithms. Public hospital procurement in KwaZulu-Natal favors digital platforms for compatibility with centralized archiving systems.
- Robotic:Precision-guided instrument positioning with haptic feedback and tremor filtration. Cape Town's private orthopedic centers drive adoption for arthroscopic and urologic applications requiring submillimeter accuracy.
- Optical:Conventional fiber-optic light transmission through coherent glass bundles.
- Wireless:Radiofrequency or Bluetooth-enabled data transmission eliminating tethered connections between scope and processor.
Digital technology dominates current procurement volumes; robotic platforms command the steepest expansion trajectory in premium private facilities.
End User:
Facility type dictates reimbursement mechanisms and equipment financing structures across South Africa's dual healthcare system.
- Hospitals:Acute care institutions with 24-hour surgical capabilities and dedicated endoscopy units. Eastern Cape provincial hospitals are expanding service capacity as health budget decentralization progresses.
- Specialty Practices:Gastroenterology and pulmonology-focused clinics with procedure-dedicated nursing staff. Durban's consolidated private specialist networks concentrate high-volume diagnostic throughput.
- Clinics:Primary care facilities with limited procedure rooms and basic sedation capabilities.
- Outpatient Surgery Centers:Ambulatory facilities optimized for same-day discharge protocols.
Hospitals maintain the largest installed device base; specialty practices are gaining share fastest as service unbundling fragments traditional procurement relationships.
Application:
Clinical specialty determines device specification requirements and procedure reimbursement rates under South Africa's evolving National Health Insurance framework.
- Gastroenterology:Upper and lower gastrointestinal tract examination with biopsy capability. Colorectal cancer screening programs in Western Cape public health districts drive flexible endoscope utilization.
- Urology:Cystoscopic and ureteroscopic examination of urinary tract structures. Robotic platform integration in Gauteng private hospitals creates premium procedure pricing power.
- Pulmonology:Bronchoscopic airway inspection and lavage sampling.
- Gynecology:Hysteroscopic uterine cavity examination and operative interventions.
Gastroenterology accounts for the majority of procedure volume; urology applications are climbing the fastest as precision-guided platforms penetrate private service lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical fiber feedstock and CMOS sensor supply chains concentrate in Gauteng Province's industrial corridor, anchoring South Africa's endoscopy device distribution networks across nine provinces.
Gauteng Province
Johannesburg-Pretoria corridor hospitals generate concentrated demand for flexible gastroscopes and colonoscopes as colorectal screening programs expand. SAHPRA registration requirements shape which visualization platforms gain tender eligibility in public procurement. Private hospital chains in Sandton and Centurion are integrating robotic surgical platforms for urologic precision procedures.
KwaZulu-Natal
Durban's consolidated specialist networks drive high-volume diagnostic throughput for pulmonology bronchoscopy applications. National Health Laboratory Service infection control protocols mandate capital-intensive sterilization infrastructure that constrains flexible endoscope deployment in secondary facilities. The city's technician training programs anchor regional repair capacity for fiber-optic instrument maintenance.
Western Cape
Cape Town's private healthcare networks exhibit pronounced service unbundling, with procurement teams negotiating equipment, maintenance, and software subscriptions through separate tender processes. Provincial health districts are expanding colorectal cancer screening programs that drive flexible endoscope utilization in public hospitals. Stellenbosch and Somerset West host emerging outpatient surgery centers targeting same-day endoscopy discharge protocols.
Eastern Cape
Port Elizabeth and East London present underpenetrated demand for outpatient endoscopy services as provincial health budgets decentralize. Reprocessing infrastructure gaps limit flexible endoscope utilization in secondary public hospitals despite rising diagnostic need. The province's biomedical engineering talent pipeline remains insufficient for expanding device fleet maintenance across rural service areas.
Free State
Bloemfontein's tertiary hospitals anchor endoscopy service capacity for the province's dispersed rural population. SAHPRA post-market surveillance requirements intensify adverse event reporting obligations that favor suppliers with established Johannesburg-based regulatory affairs teams. Equipment-as-a-service leasing models are penetrating mid-tier private clinics to reduce upfront capital barriers.
South Africa Endoscopy Devices Market Competitive Landscape
Global majors compete with regional champions across distribution networks and service capabilities, creating a tiered structure where multinational corporations anchor premium technology segments while specialized distributors capture mid-market procurement. The vendor base separates into three strategic archetypes: integrated visualization platform suppliers, rigid endoscope specialists, and flexible instrument service providers. Competitive positioning depends on SAHPRA registration speed and technician training network density. M&A activity concentrates on service capability acquisition, while geographic expansion targets Eastern Cape and Free State secondary cities.
Among Japanese-headquartered conglomerates, Olympus Corporation and FUJIFILM Holdings Corporation occupy positions exemplifying the integrated visualization platform archetype, leveraging established technician training infrastructure in Durban and Cape Town. German precision manufacturers KARL STORZ and Richard Wolf GmbH represent rigid endoscope specialization for orthopedic and ENT surgical applications. Boston Scientific Corporation sits within the flexible instrument tier, with service networks calibrated to public hospital reprocessing requirements. Medtronic exemplifies cross-selling leverage from cardiac and surgical footprints into provincial hospital visualization procurement.
| Leading Market Players |
|---|
| FUJIFILM Holdings Corporation |
| Medtronic |
| Boston Scientific Corporation |
| Stryker Corporation |
| HOYA Corporation |
| Olympus Corporation |
| Johnson & Johnson |
| Richard Wolf GmbH |
| KARL STORZ |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap distributors with generational presence in Johannesburg's medical device corridor anchor supply-side discipline, compressing margin flexibility for multinational entrants while sustaining premium pricing for ISO 13485-certified platforms through bundled service contracts.
Pricing Analysis
Warranty and preventive maintenance unbundling now separates capital equipment acquisition from recurring service revenue in Cape Town's consolidated private networks. Three-tier pricing structure across premium, standard, and economy levels stratifies by SAHPRA registration tier and technician training density. Cost compression in economy-tier flexible endoscopes intensifies because Eastern Cape provincial hospitals prioritize lowest upfront acquisition over total cost of ownership. Public procurement committees exhibit highest price sensitivity; Sandton private hospital chains absorb premium robotic platform pricing.
Supply Chain Analysis
ISO 13485 and BIS-equivalent certification gating restricts component sourcing to qualified Asian and European suppliers. CMOS sensors and fiber-optic bundles draw from Japan, Germany, and South Korea. LED illumination modules and proprietary image processing chipsets hinge on concentrated Taiwanese and South Korean foundry capacity. Single-source vulnerability runs through CMOS sensor supply from specific Japanese manufacturers. Distribution runs through Johannesburg-based master distributors with provincial sub-distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biomedical engineering talent scarcity props pricing power for maintenance-capable incumbents, constraining supply expansion regardless of capital availability.
For Market Incumbents: Deploy technician training network densification as the priority defensive lever. Expand Durban and Cape Town repair capacity into Port Elizabeth and Bloemfontein before single-use endoscope technology erodes reprocessing-dependent revenue streams. Deepen backward integration into LED and optical component supply to offset currency volatility exposure. For New Entrants and Emerging Players: Capture Eastern Cape outpatient surgery center demand through equipment-as-a-service leasing models that bypass upfront capital barriers. Target Free State mid-tier private clinics with visualization system subscriptions bundled with remote technical support. Lead with AI-enhanced image processing differentiation to bypass entrenched service relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor rigid endoscope specialists with established orthopedic surgeon training programs in Gauteng and Western Cape. Long-term viability centers on regulatory affairs capabilities with 24-hour SAHPRA response protocols. Watch National Health Insurance centralized procurement framework finalization as volume concentration inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| SAHPRA Registration Fast-Track Investment | Accelerates tender eligibility for public hospital procurement in Gauteng and KwaZulu-Natal. |
| Technician Training Network Expansion | Reduces maintenance turnaround bottlenecks in Eastern Cape and Free State rural provinces. |
| Single-Use Endoscope Portfolio Launch | Eliminates reprocessing infrastructure dependency for high-turnover public hospital settings. |
| AI-Enhanced Visualization Software Development | Creates automated polyp detection differentiation in Johannesburg-Pretoria private hospital chains. |
| Equipment-as-a-Service Leasing Model | Unlocks mid-tier private clinic segments beyond traditional hospital capital procurement cycles. |
Research Methodology
Multi-period observation of SAHPRA registration timelines, tender award patterns, and technician training program expansion anchored the trend analysis, supplemented by interviews with hospital procurement committee chairs, biomedical engineering directors, GPO contracts managers, and distributor operations heads. Secondary validation drew from SAHPRA medical device registration databases, National Health Laboratory service standards documentation, provincial health budget appropriations, and ISO 13485 certification registries. Bottom-up facility-level equipment counts triangulated against top-down import trade data for optical and electro-medical apparatus.
Segment-weighting across product type, technology tier, end-user facility class, and clinical application shaped volume and value projections throughout the forecast period. CAGRs derived from logistic growth curve fitting with saturation parameters calibrated to public health infrastructure investment cycles and private hospital capital expenditure patterns. Modeling incorporated National Health Insurance procurement framework scenario weights and robotic platform adoption elasticity estimates from Gauteng private facility surveys.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SAHPRA regulatory pathway changes, biomedical engineering graduate pipeline expansion, and single-use endoscope cost parity achievement. Forecasts reflect documented assumptions about procurement centralization velocity and currency stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Global Disposable Endoscope Market
Endoscopy
Global Colonoscopy Devices Market
Endoscopy
Global Endoscopic Stricture Management Device Market
Endoscopy
Sweden Endoscopy Devices Market
Endoscopy
Polyp Biopsy Market
Endoscopy
Chip-On-The-Tip Endoscopes Market
Endoscopy
Laryngeal Mirrors Market
Endoscopy
Italy Endoscopy Devices Market
Endoscopy
France Endoscopy Devices Market
Endoscopy
Hysteroscopic Endometrial Resection Procedures Market
Endoscopy
Endoscopy Equipment Market
Endoscopy
Global Flexible Endoscopes Market
Endoscopy
Endoscopy Procedures Estimates Market
Endoscopy
Endoscopy Visualization Systems Market
Endoscopy
Endoscopy Video Systems Market
Endoscopy
Spain Endoscopy Devices Market