
 Endoscope Washer Disinfector Market | 2026-2036
Endoscope Washer Disinfector Market Size, Share, and Industry Trends Forecast 2026-2036
Endoscope Washer Disinfector Market Foresight
Multi-source procurement for critical disinfection components is pivoting toward captive supply arrangements as OEMs seek buffer stock certainty. Steelco leverages its Italian manufacturing base to control European distribution of automated endoscope reprocessors. Olympus Medical Systems anchors the Asia-Pacific installed base through direct hospital service contracts. Getinge competes on thermal disinfection technology leadership with integrated washer-disinfector and sterilizer platforms.
An endoscope washer disinfector is a closed-cycle medical device that combines automated flushing, detergent cleaning, high-level chemical or thermal disinfection, and forced-air drying to eliminate bioburden from flexible endoscopes between patient procedures. Units typically process colonoscopes, gastroscopes, and bronchoscopes through validated A0 cycles exceeding 600 seconds at 90°C for thermal disinfection or peracetic acid immersion for chemical protocols. Floor-standing automated systems dominate hospital central sterile supply departments due to throughput requirements and traceability mandates, while bench-top units serve ambulatory surgical centers with lower procedure volumes. Chemical disinfection technology leads installed base share but faces margin compression from rising peracetic acid costs and waste disposal regulations.
FDA 510(k) clearance requirements and AAMI ST91 endoscope reprocessing standards shape product development timelines and validation costs for manufacturers seeking U.S. market access. The EU Medical Device Regulation and ISO 15883 washer-disinfector standards enforce biocompatibility testing and post-market surveillance obligations across European Economic Area countries. Stakeholders must monitor evolving hydrogen peroxide vapor disinfection protocols and single-use endoscope competitive displacement to calibrate long-term capacity planning and R&D allocation.
Market Dynamics
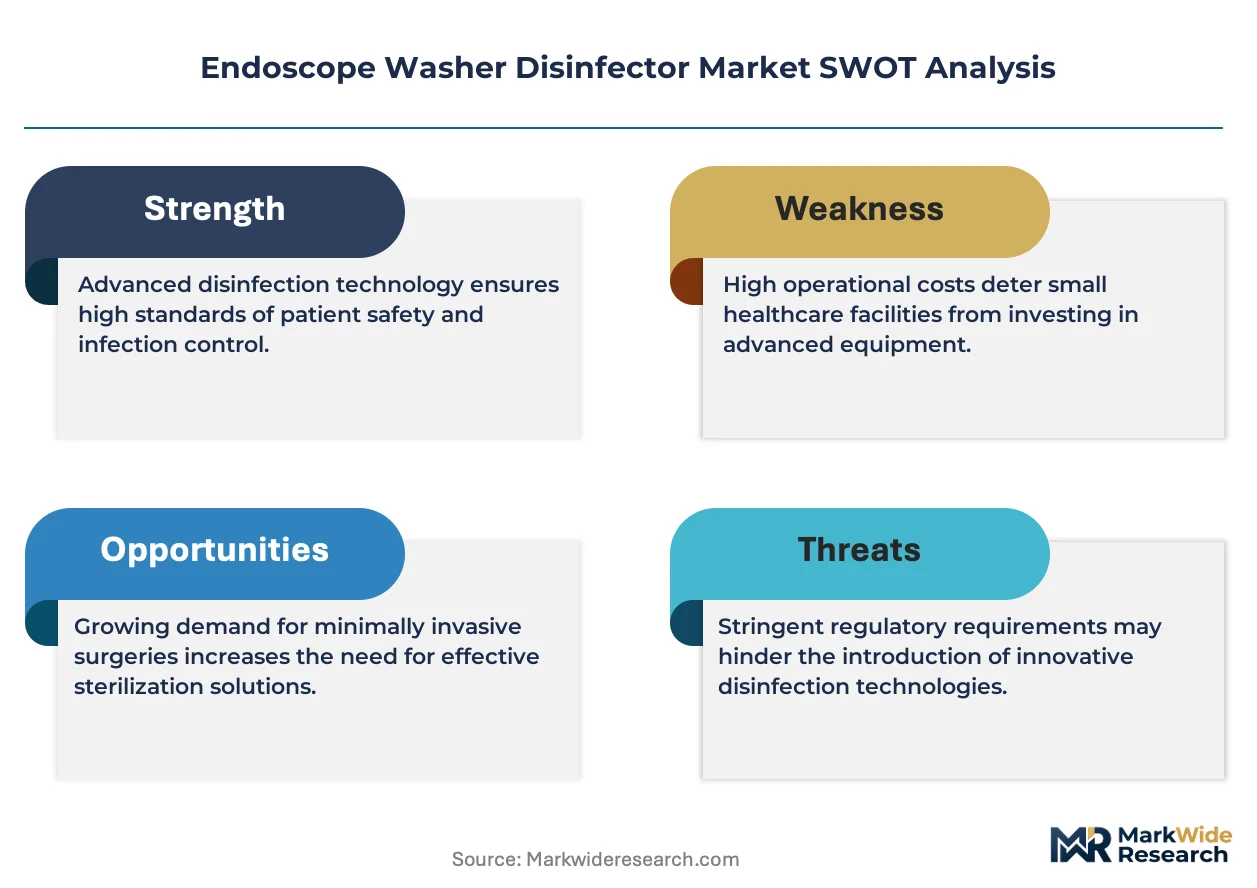
Automated thermal disinfection cycles are displacing chemical protocols as hospitals confront peracetic acid waste disposal costs and FDA validation documentation burdens. This shift compresses margins for chemical-dependent OEMs while rewarding integrated platform suppliers.
Growth Catalysts
- AAMI ST91 compliance mandates:United States hospitals must document high-level disinfection validation for every reprocessing cycle. Automated washer-disinfectors with embedded data logging capture this requirement directly.
- Centralized sterile processing departments:German hospital networks consolidate endoscope reprocessing into dedicated CSSD facilities. This concentration demands high-throughput floor-standing units with batch traceability.
- Single-use endoscope cost barriers:Bronchoscope and cystoscope procedures retain reusable instrument economics. Washer-disinfector utilization rates stay elevated where procedure volumes exceed single-use break-even thresholds.
Market Restraints
- Peracetic acid input volatility:Chemical disinfection protocols face margin compression from rising specialty biocide costs and hazardous waste disposal tariffs.
- European supply concentration:Automated endoscope reprocessor manufacturing clusters in northern Italy and southern Germany. Geographic concentration exposes procurement timelines to regional logistics disruptions.
- Thermal disinfection infrastructure gaps:Ambulatory surgical centers lack steam and drainage capacity for A0 cycle washer-disinfectors. These facilities remain tethered to chemical protocols despite operational drawbacks.
Strategic Opportunities
- India CSSD modernization:Private hospital chains in Maharashtra and Karnataka are building centralized reprocessing facilities. First-mover OEMs can anchor installed base before public tender standardization.
- Hydrogen peroxide vapor convergence:Low-temperature sterilization technology integration with washer-disinfector platforms enables heat-sensitive endoscope processing without chemical residue.
- Service contract unbundling:Direct technician dispatch models replace distributor-mediated maintenance. OEMs capture aftermarket revenue previously lost to third-party service networks.
Industry Challenges
- Biomedical validation engineering scarcity:A0 thermal cycle documentation and FDA 510(k) submission preparation require specialized regulatory affairs talent. Competition for experienced professionals intensifies.
- Legacy endoscope compatibility:Older flexible endoscope models lack channel dimensions and material ratings for validated automated reprocessing. Hospitals face premature instrument retirement costs.
- Cross-border certification synchronization:EU MDR technical documentation and FDA quality system inspection schedules rarely align. Dual-market manufacturers absorb extended timeline risk.
Report Scope
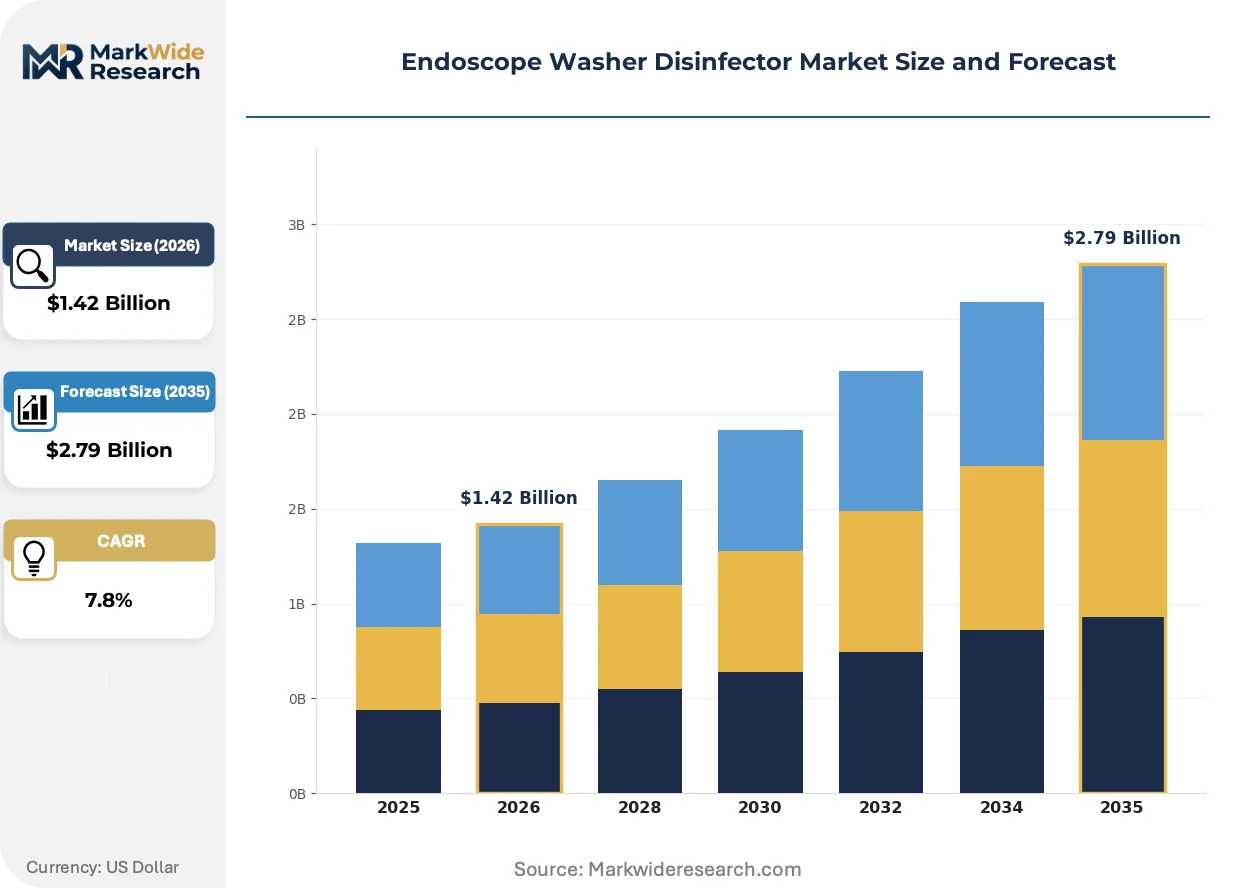
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoscope Washer Disinfector Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.79 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floor-Standing, Bench-Top, Automated, Manual End User: Hospitals, Clinics, Ambulatory Surgical Centers, Laboratories Technology: Heat Exchange, Steam Sterilization, Chemical Disinfection, Ultrasonic Cleaning Installation Type: Built-In, Portable, Modular, Integrated |
| Companies Covered | Steelco, Shinva Medical Instrument, Olympus Medical Systems, Belimed, Wassenburg Medical, STERIS, Ecolab, ASP, Getinge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoscope Washer Disinfector Market Shifts & Advancements
Digital traceability integration and low-temperature sterilization convergence are redefining competitive differentiation in automated endoscope reprocessing. Vendors now compete on data architecture and platform extensibility rather than cycle speed alone.
Thermal disinfection technology is overtaking chemical protocols in hospital central sterile supply departments. A0 cycles exceeding 600 seconds at 90°C eliminate peracetic acid handling and disposal burdens. Academic medical centers in the United States and university hospitals in Germany lead this transition, prioritizing staff safety documentation over capital cost minimization.
EU Medical Device Regulation post-market surveillance requirements are extending validation obligations throughout product lifecycle. Manufacturers must maintain clinical evidence portfolios and vigilance reporting systems. German notified bodies enforce this most stringently, delaying market access for documentation-deficient submissions.
Hospital procurement departments are consolidating reprocessing equipment purchasing into multi-year managed service agreements. Capital expenditure constraints favor operational expenditure models with guaranteed uptime clauses. This shift is most visible in National Health Service trusts in England and integrated delivery networks in the United States.
Endoscope Washer Disinfector Market Segmentation
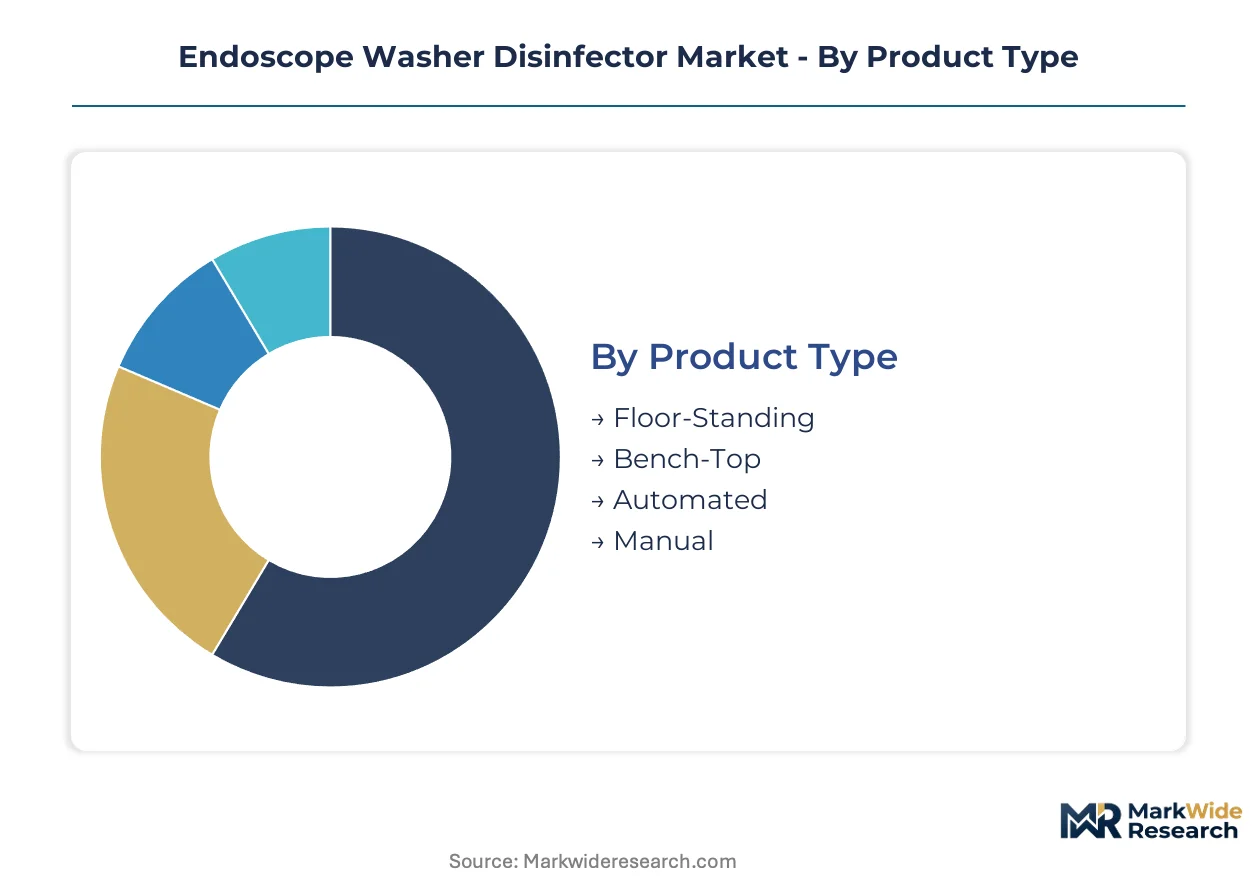
Endoscope washer disinfector procurement decisions pivot on throughput requirements, infrastructure constraints, and regulatory validation burdens. Buyers weigh capital expenditure against operational complexity, channeling demand toward configurations that minimize reprocessing risk documentation.
Product Type:
Hospital sterile processing departments prioritize throughput capacity and batch traceability when selecting physical form factors.
- Floor-Standing:These units process 6-12 endoscopes per cycle through validated A0 thermal protocols exceeding 600 seconds. German university hospitals and United States academic medical centers specify floor-standing systems for centralized CSSD facilities where procedure volumes exceed 50 cases daily.
- Automated:Closed-cycle systems integrate flushing, detergent cleaning, disinfection, and forced-air drying with embedded data logging for FDA compliance. Demand concentrates in United States hospital networks confronting AAMI ST91 documentation mandates.
- Bench-Top:Compact units serve ambulatory surgical centers with space constraints and lower procedure volumes.
- Manual:Basic disinfection stations persist in resource-constrained settings lacking capital for automated infrastructure.
Volume sits with Floor-Standing configurations; growth tilts toward Automated systems.
End User:
Facility scale and reimbursement structure determine reprocessing technology investment thresholds.
- Hospitals:Central sterile supply departments in tertiary facilities drive demand for high-throughput thermal disinfection platforms with integrated traceability systems.
- Ambulatory Surgical Centers:These facilities face infrastructure gaps for steam and drainage capacity, tethering them to chemical protocols despite peracetic acid waste disposal burdens.
- Clinics:Lower procedure volumes favor bench-top chemical units or third-party reprocessing services.
- Laboratories:Research endoscope reprocessing requires specialized validation protocols distinct from clinical standards.
Revenue concentrates in Hospitals; Ambulatory Surgical Centers present the steepest expansion trajectory as outpatient migration accelerates.
Technology:
Disinfection modality selection hinges on endoscope heat tolerance, waste disposal economics, and regulatory validation timelines.
- Chemical Disinfection:Peracetic acid immersion protocols dominate installed base share but face margin compression from rising biocide costs and hazardous waste tariffs in Germany and the United States.
- Heat Exchange:Thermal disinfection cycles at 90°C eliminate chemical handling burdens. United States academic medical centers and German university hospitals lead transition toward this protocol.
- Steam Sterilization:Saturated steam protocols suit rigid endoscopes and accessories rather than flexible instrument channels.
- Ultrasonic Cleaning:Pre-disinfection debris removal complements primary disinfection cycles in high-throughput settings.
Installed base favors Chemical Disinfection; Heat Exchange gains share fastest as waste disposal regulations tighten.
Installation Type:
Physical integration with hospital infrastructure shapes total cost of ownership and facility modification requirements.
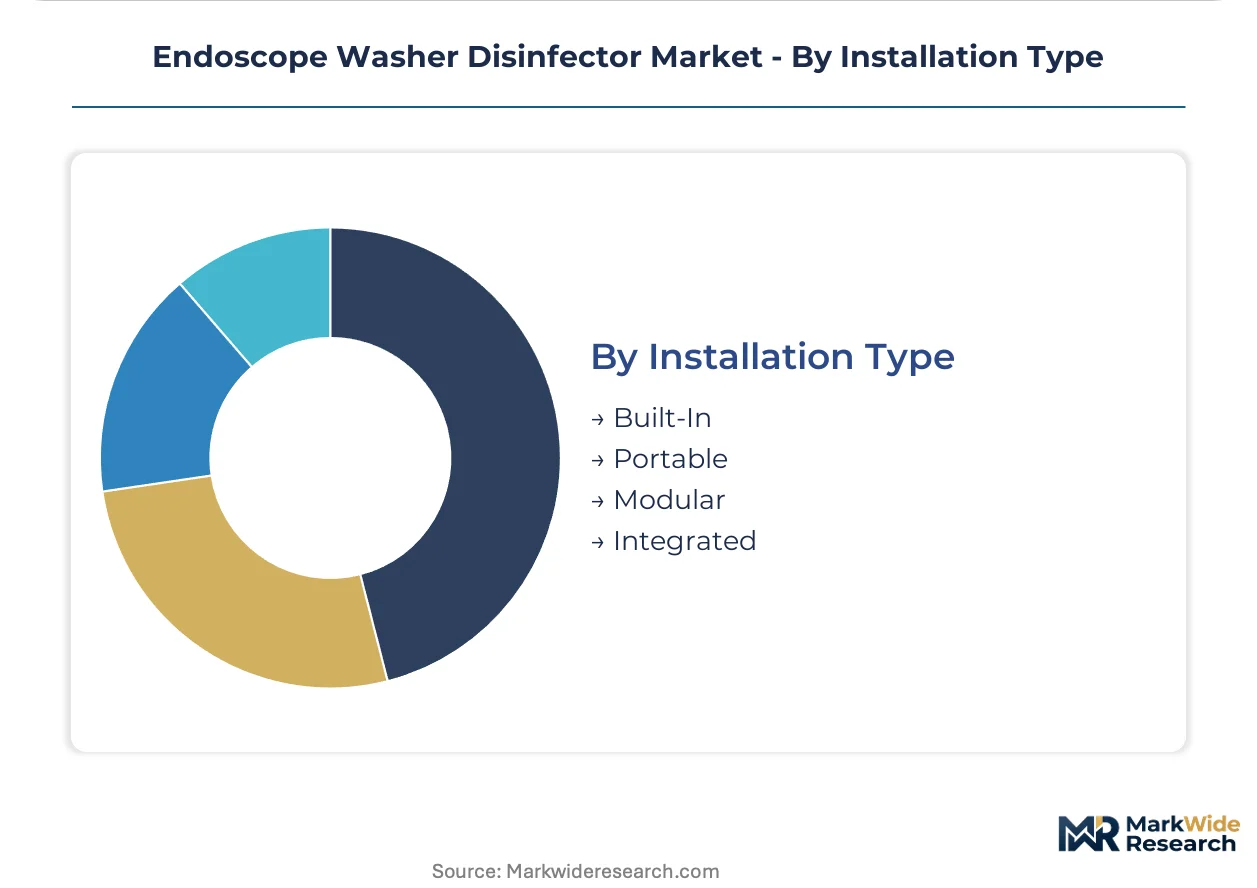
- Built-In:Fixed installations with dedicated utility connections serve permanent CSSD facilities in United States integrated delivery networks and England NHS trusts.
- Integrated:Washer-disinfector platforms combined with sterilizer systems enable single-vendor service contracts and unified traceability databases.
- Modular:Expandable configurations allow capacity scaling without full system replacement.
- Portable:Mobile units address temporary capacity needs and field deployment scenarios.
Deployment concentrates in Built-In systems; Integrated configurations climb fastest as procurement consolidates into multi-year managed service agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peracetic acid manufacturing clusters in northern Italy and southern Germany anchor European supply chains for chemical disinfection protocols. Hospital procurement networks in these zones prioritize proximity to biocide production when negotiating washer-disinfector service contracts.
United States
Academic medical centers in Boston and Baltimore drive thermal disinfection adoption as AAMI ST91 documentation burdens intensify. FDA 510(k) clearance timelines stretch validation costs for new market entrants. The Research Triangle Park corridor in North Carolina concentrates biomedical engineering talent for regulatory affairs specialization.
Germany
Centralized sterile processing departments in Bavarian university hospitals replace legacy washer-disinfector fleets at accelerated rates. EU MDR post-market surveillance obligations enforced by German notified bodies extend compliance timelines. The Stuttgart-Tübingen corridor hosts precision manufacturing for thermal disinfection heat exchange components.
China
Private hospital chains in Shanghai and Guangdong province expand endoscopy suites faster than single-use instrument cost curves allow. NMPA medical device registration requirements for washer-disinfectors tighten clinical evidence standards. The Yangtze River Delta concentrates domestic manufacturing of automated reprocessing platforms for hospital procurement tenders.
India
Corporate hospital networks in Maharashtra and Karnataka build dedicated CSSD facilities to capture medical tourism revenue. CDSCO import licensing requirements for automated reprocessors create first-mover advantages for established OEMs. The Mumbai-Pune corridor attracts sterilization equipment distributors targeting tier-2 city hospital expansions.
Japan
Metropolitan Tokyo hospitals confront aging endoscope fleets incompatible with validated automated reprocessing cycles. PMDA quality system inspections for washer-disinfector platforms emphasize post-market vigilance reporting. The Osaka-Kobe manufacturing zone supplies precision fluid control components for Asian-market reprocessing equipment.
Endoscope Washer Disinfector Market Competitive Landscape
Global majors compete with regional champions across thermal disinfection technology and chemical protocol legacy installed bases. The vendor base splits between integrated platform suppliers and specialized reprocessing equipment fabricators. Three archetypes dominate: European precision engineering houses, diversified medical technology conglomerates, and Asian cost-optimized manufacturers. Capacity expansion and strategic partnerships constitute the primary competitive vectors as hospitals consolidate procurement into multi-year managed service agreements.
Among diversified medical technology conglomerates, Olympus Medical Systems and Getinge occupy positions spanning endoscope manufacturing and reprocessing platform supply. Steelco exemplifies the European precision engineering archetype with manufacturing control over regional distribution networks. Shinva Medical Instrument represents Asian fabrication scale serving domestic hospital procurement tenders. These three anchors illustrate divergent strategic postures across geographic and technology vectors.
| Leading Market Players |
|---|
| Steelco |
| Shinva Medical Instrument |
| Olympus Medical Systems |
| Belimed |
| Wassenburg Medical |
| STERIS |
| Ecolab |
| ASP |
| Getinge |
| Others |
Supply & Pricing Matrix
Thermal disinfection certification tiers bifurcate procurement budgets between A0-validated hospital systems and chemical-dependent ambulatory facilities, with warranty bundling and service contract structures diverging sharply across these buyer archetypes. OEMs in Germany and the United States extract premium positioning through multi-year uptime guarantees embedded in managed service agreements, while price competition intensifies for bench-top chemical units serving cost-constrained clinics.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium thermal disinfection platforms from unbundled chemical protocol competitors. Three-tier pricing structure across premium, standard, and economy levels reflects validation documentation depth, with FDA 510(k)-cleared systems commanding service-inclusive premiums against CE-marked equivalents. Cost compression in chemical disinfection tiers stems from peracetic acid input volatility and hazardous waste disposal tariffs. Ambulatory surgical centers exhibit highest price sensitivity due to capital expenditure constraints, while German university hospitals prioritize compliance assurance over acquisition cost minimization.
Supply Chain Analysis
Dual-sourcing mandates from United States hospital procurement committees require qualified suppliers for heat exchange components and precision fluid control systems. Manufacturing concentrates in Germany, Italy, and Japan for thermal disinfection heat exchangers, with peracetic acid biocide production anchored in northern Italy. Supply chains draw from specialty steel alloys, medical-grade polymers, and precision sensor arrays. Single-source vulnerability concentrates in German heat exchange component fabrication. Distribution runs through direct OEM service contracts and sterilization equipment distributors targeting hospital central sterile supply departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where AAMI ST91 validation requirements in the United States erect regulatory moats protecting incumbent positions against undercapitalized challengers.
For Market Incumbents: To counter hydrogen peroxide vapor disinruption from sterilization platform integrators, thermal disinfection leaders should deepen backward integration into heat exchange component production and anchor capacity expansion in the Stuttgart-Tübingen corridor. Captive supply of precision fluid control systems defends margin position against specialty sensor cost inflation. For New Entrants and Emerging Players: EU MDR post-market surveillance obligations in Germany open a window for documentation-specialist entrants targeting mid-tier hospital networks with modular thermal disinfection platforms. Maharashtra and Karnataka corporate hospital chains in India present the most penetrable geography, with CDSCO import licensing complexity favoring first-mover OEMs willing to establish local technician dispatch capabilities. For Investors and Strategic Acquirers: Re-rating potential sits with European precision engineering houses given thermal disinfection protocol convergence across United States academic medical centers and German university hospitals. Acquisition targets should demonstrate embedded data logging architectures compatible with AAMI ST91 cycle documentation mandates. The signal to watch is hydrogen peroxide vapor sterilization technology integration announcements from established washer-disinfector platforms, which would compress standalone thermal disinfection valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Reduces validation timeline risk for thermal disinfection platform entrants targeting United States academic medical centers. |
| CE Marking Pathway Investment | Secures EU MDR technical documentation approval for modular configurations serving German CSSD consolidation. |
| Hospital System Partnership | Locks multi-year managed service agreements with England NHS trusts favoring operational expenditure models. |
| Software Companion Development | Enables embedded data logging architectures capturing AAMI ST91 compliance documentation directly. |
| Reimbursement Strategy | Aligns thermal disinfection platform positioning with CMS quality metrics driving hospital procurement priorities. |
Research Methodology
FDA 510(k) clearance databases, EU MDR technical documentation filings, and hospital procurement contract registries formed the secondary backbone, supplemented by primary interviews with biomedical validation engineers, central sterile supply department managers, and GPO contracts administrators. Bottom-up and top-down triangulation validated unit shipment estimates against installed base replacement cycles and procedure volume elasticity across the analysis window.
Bottom-up modeling aggregated country-level hospital endoscopy department expansion plans and CSSD modernization timelines, while top-down analysis cross-checked aggregate market expansion against macro healthcare infrastructure investment flows. Segmentation dimensions included product configuration, disinfection technology modality, end-user facility type, and regional regulatory cluster. CAGRs were derived from procedure volume trajectories and replacement cycle compression in mature installed bases, with thermal disinfection adoption curves and single-use endoscope cost crossover thresholds serving as critical sensitivity inputs.
The model assumes a particular technology adoption path; alternative pathways for hydrogen peroxide vapor sterilization convergence would alter the outlook if low-temperature protocols displace thermal disinfection in heat-sensitive endoscope processing. Deviation in peracetic acid waste disposal tariff trajectories or FDA validation documentation burden intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Nasopharyngoscope Market
Endoscopy
Chip-On-The-Tip Endoscopes Market
Endoscopy
Global Endoscopes Market
Endoscopy
Endoscopic Balloon Dilator Market
Endoscopy
Global Colonoscopes Market
Endoscopy
Endoscopic Tattooing Market
Endoscopy
Saudi Arabia Endoscopy Devices Market
Endoscopy
Endoscopic Insufflators Market
Endoscopy
Germany Endoscopy Devices Market
Endoscopy
Colonic Stents Market
Endoscopy
Endoscopy Video Systems Market
Endoscopy
Non-Invasive Colon Cancer Screening Market
Endoscopy
South Korea Endoscopy Devices Market
Endoscopy
Endoscopic Retrograde Cholangiopancreatography (ERCP) Devices Market
Endoscopy
Capsule Endoscopy Market
Endoscopy
Global Endoscopic Ultrasound Needles Market