
 Saudi Arabia Endoscopy Devices Market | 2026-2036
Saudi Arabia Endoscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Endoscopy Devices Market Analytics
A capital-intensity divergence between players is bifurcating the competitive landscape in Saudi Arabia. Olympus Corporation leverages its in-house optical manufacturing to control premium flexible endoscope supply chains. Karl Storz SE & Co. KG anchors its position through rigid endoscope specialization for surgical disciplines. Ambu A/S differentiates via single-use endoscopy, bypassing reprocessing infrastructure constraints that burden reusable competitors.
Endoscopy devices encompass optical or digital visualization instruments inserted through natural orifices or small incisions to diagnose and treat internal organs, typically employing fiber-optic bundles or CMOS sensors with working channels ranging from 1.2 mm to 6.0 mm for instrument passage. Their primary purpose is to enable minimally invasive procedures that reduce patient recovery time and surgical complications across gastrointestinal, pulmonary, and urological interventions. Flexible endoscopes command the dominant share of product type revenue due to their versatility across gastroenterology and pulmonology applications, while robot-assisted endoscopes represent the fastest-expanding category as Saudi hospitals invest in autonomous navigation platforms. Within end users, hospitals absorb the majority of device procurement volume, though surgical centers are gaining traction as the Kingdom diversifies care delivery sites under Vision 2030 health privatization targets.
SFDA governs medical device registration and post-market surveillance, enforcing conformity with Gulf Standardization Organization technical requirements for electromagnetic compatibility and biocompatibility. The Health Sector Transformation Program and NPHIES platform mandate interoperable digital infrastructure, directly stimulating demand for high-definition visualization systems and integrated digital imaging technologies. Stakeholders must monitor procurement localization thresholds and government preference policies that increasingly favor distributors with Saudi-based technical service capabilities.
Market Dynamics
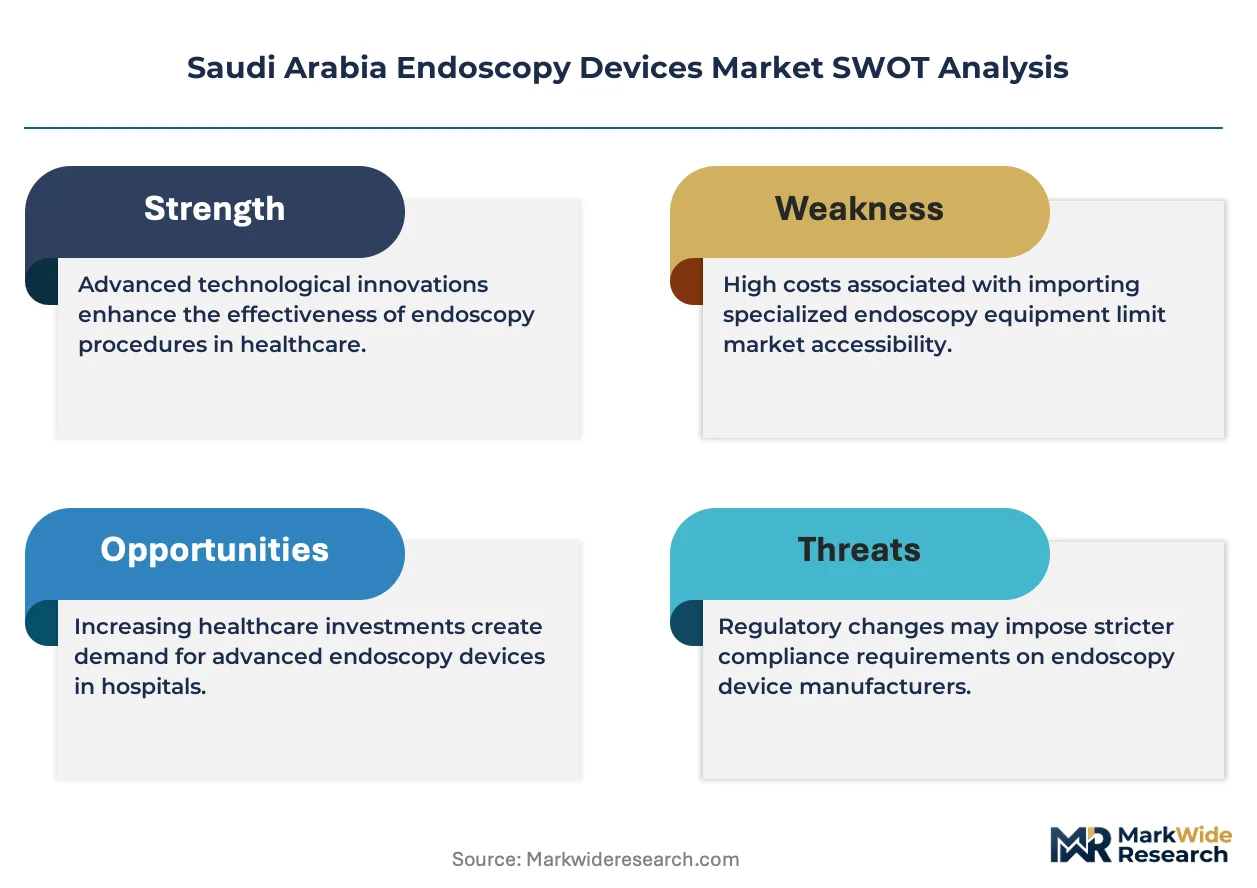
Localization mandates under the Health Sector Transformation Program are forcing international manufacturers to establish Saudi-based assembly and technical service operations, fundamentally restructuring how endoscopy supply chains penetrate the Kingdom.
Growth Catalysts
- SFDA Registration Acceleration:Streamlined medical device approval pathways are reducing time-to-market for novel visualization systems. The regulator's digital submission portal compresses review cycles for manufacturers with Gulf Standardization Organization pre-certification.
- Minimally Invasive Surgery Expansion:Tertiary hospitals in Riyadh and Jeddah are scaling laparoscopic and endoscopic suites. Capital deployment concentrates in gastroenterology and pulmonology departments.
- Single-Use Endoscopy Adoption:Elimination of reprocessing infrastructure requirements is lowering barriers for surgical centers entering diagnostic services. This technology bypasses sterilization capacity constraints that limit reusable device deployment.
Market Restraints
- Optical Component Import Dependency:CMOS sensors and fiber-optic bundles concentrate in East Asian manufacturing clusters. Supply disruptions propagate directly to Saudi assembly operations.
- SFDA Biocompatibility Testing Bottlenecks:Local laboratory capacity for ISO 10993 compliance verification remains limited. Extended validation timelines delay product launches.
- Capital Intensity of Robotic Platforms:Autonomous navigation systems require substantial upfront investment. Budget constraints at mid-tier hospitals restrict penetration beyond tertiary centers.
Strategic Opportunities
- Eastern Province Undersupply:Dammam and Khobar lack equivalent endoscopy infrastructure to Riyadh and Jeddah. Greenfield hospital construction creates first-mover positioning.
- NPHIES Interoperability Mandate:The national health information exchange platform requires integrated digital imaging. Vendors with native connectivity capture preference in public procurement.
- AI-Assisted Diagnostics Convergence:Machine learning algorithms paired with high-definition visualization enable real-time pathology detection. This pairing differentiates premium system offerings.
Industry Challenges
- Gastroenterologist Training Pipeline:Fellowship programs produce insufficient specialists to operate expanded endoscopy suites. Human capital constraints limit equipment utilization rates.
- Legacy PACS Integration Complexity:Hospital picture archiving systems use non-standard protocols. Bridging hardware adds cost and implementation risk.
- SFDA Post-Market Surveillance Compliance:Adverse event reporting and periodic safety updates demand dedicated regulatory affairs staffing. Mid-size distributors struggle with sustained compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Endoscopy Devices Market |
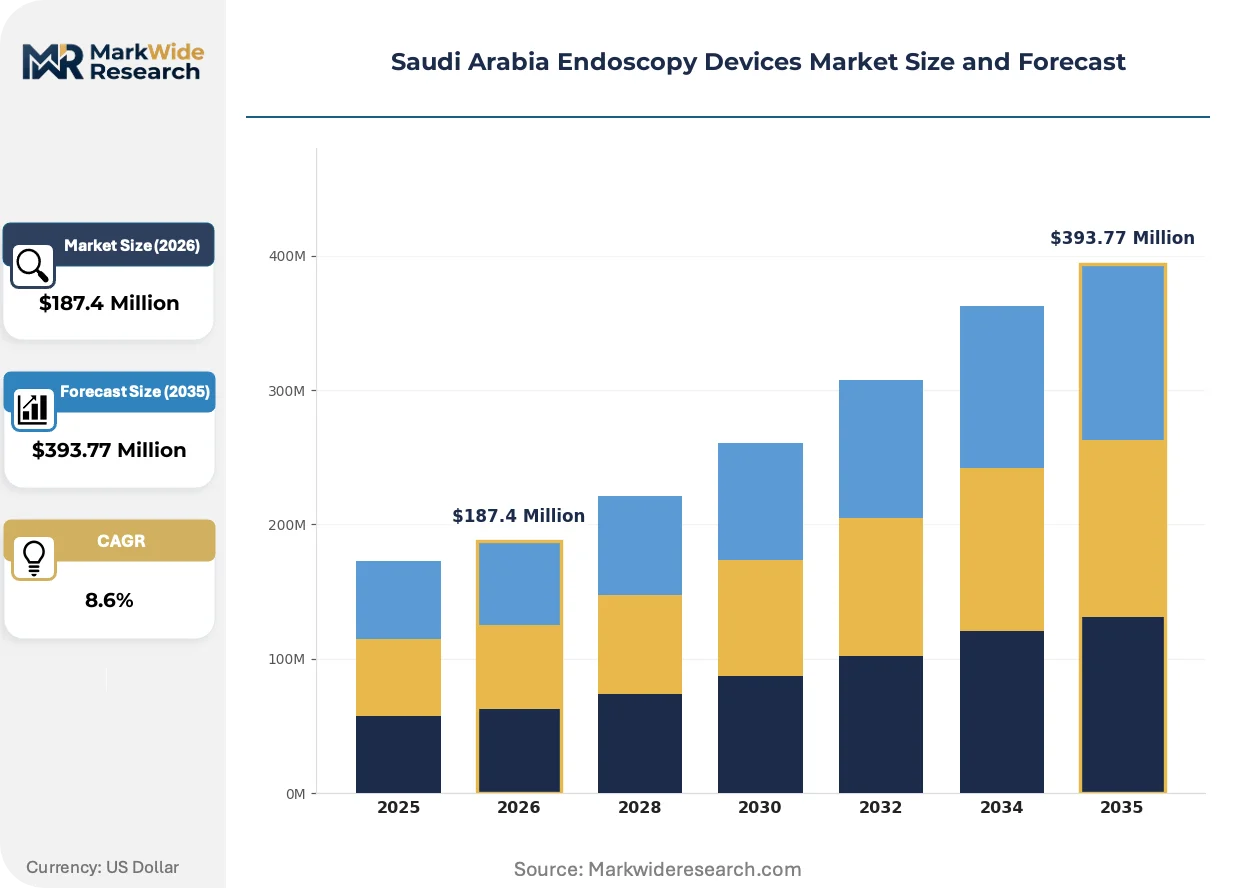
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Endoscopes, Flexible Endoscopes, Capsule Endoscopes, Robot-assisted Endoscopes End User: Hospitals, Clinics, Surgical Centers, Specialty Practices Therapy Area: Gastroenterology, Pulmonology, Urology, Gynecology Technology: Digital Imaging, Visualization Systems, High-definition Technology, Laser Systems |
| Companies Covered | Olympus Corporation, Karl Storz SE & Co. KG, Boston Scientific Corporation, Medtronic plc, Fujifilm Holdings Corporation, Stryker Corporation, Pentax Medical, CONMED Corporation, Ambu A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Endoscopy Devices Market Evolving Landscape
Digital visualization architectures are supplanting fiber-optic transmission, while regulatory pressure and procurement reform reshape how devices reach clinical settings across Saudi Arabia.
CMOS-based digital endoscopes are fragmenting the traditional flexible endoscope market. King Faisal Specialist Hospital and other tertiary centers are adopting these systems for gastroenterology suites at accelerating pace. The shift is compressing maintenance revenue streams tied to fiber-optic repairs while enabling software-upgradeable hardware platforms.
SFDA enforcement of Gulf Standardization Organization electromagnetic compatibility standards is tightening device certification requirements. Manufacturers must demonstrate shielding effectiveness and emission controls beyond prior thresholds. Rigid endoscope suppliers face particular pressure as surgical suites densify with RF-emitting equipment.
Public hospital procurement is consolidating through the National Unified Procurement Company. Single-tender frameworks are displacing hospital-level vendor relationships for high-value capital equipment. This concentration is most visible in Ministry of Health facilities transitioning to centralized acquisition under Vision 2030 privatization timelines.
Saudi Arabia Endoscopy Devices Market Segmentation
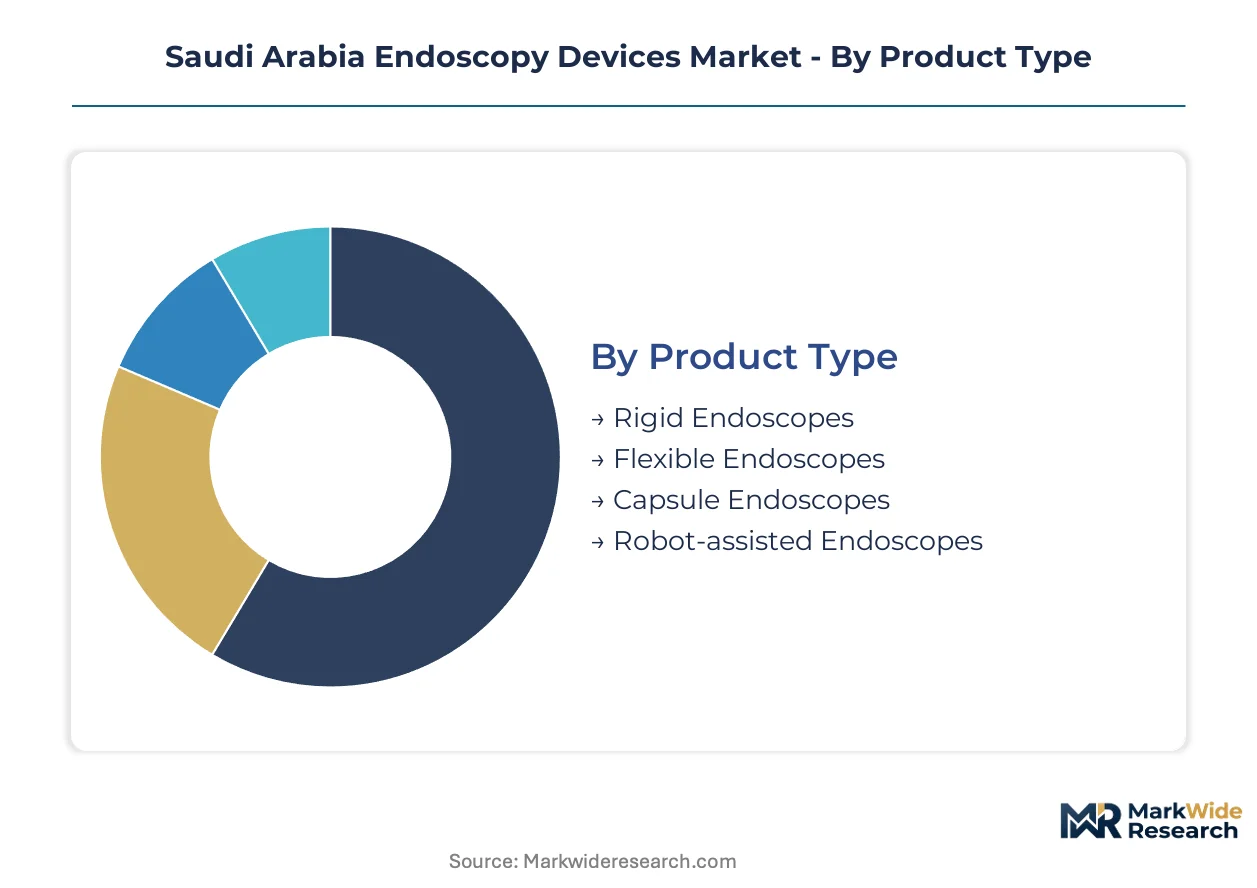
Segmentation in Saudi Arabia's endoscopy market reveals how procurement localization and NPHIES interoperability mandates reshape vendor priorities across product categories. Understanding where substitution pressure concentrates helps stakeholders allocate technical service investments and anticipate which device classes face compressed margins.
Product Type:
Substitution pressure runs strongest against reusable flexible systems as single-use alternatives and robotic platforms erode established maintenance revenue models.
- Rigid Endoscopes:Stainless steel or aluminum-bodied instruments with rod-lens optical systems deliver superior image clarity for arthroscopy and laparoscopy. Demand clusters in Riyadh's orthopedic and surgical suites where Karl Storz SE & Co. KG maintains entrenched relationships. SFDA electromagnetic compatibility enforcement complicates supply chains for non-compliant legacy inventory.
- Flexible Endoscopes:Fiber-optic bundles or CMOS-based distal chip architectures enable navigation through tortuous anatomical pathways. King Faisal Specialist Hospital and Johns Hopkins Aramco Healthcare anchor demand in gastroenterology and pulmonology departments. Digital CMOS variants are displacing fiber-optic systems at accelerating pace.
- Capsule Endoscopes:Ingestible wireless cameras with 8-12 hour battery life capture small bowel imagery without sedation.
- Robot-assisted Endoscopes:Autonomous navigation platforms with haptic feedback and AI-guided lesion detection.
Flexible endoscopes anchor the volume base while robot-assisted endoscopes gain share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive tertiary hospitals from price-sensitive surgical centers entering diagnostic services under Vision 2030 privatization.
- Hospitals:Ministry of Health facilities and military hospitals dominate procurement through National Unified Procurement Company frameworks. SFDA registration requirements and NPHIES interoperability mandates favor vendors with dedicated Saudi regulatory affairs staffing.
- Surgical Centers:Ambulatory facilities proliferating in Jeddah and Dammam prioritize single-use endoscopy to bypass sterilization infrastructure investments. Lower capital barriers enable rapid service line expansion.
- Clinics:Primary care and diagnostic clinics with limited procedure volumes.
- Specialty Practices:Gastroenterology and pulmonology group practices with procedure-focused operations.
Hospitals absorb the dominant procurement volume while surgical centers expand most quickly as care delivery diversifies.
Therapy Area:
Application concentration follows disease burden patterns and specialist availability across the Kingdom's urban centers.
- Gastroenterology:Colonoscopy and upper GI endoscopy procedures driven by colorectal cancer screening protocols and obesity intervention demand. Riyadh's King Saud Medical City and Dr. Sulaiman Al Habib Medical Group anchor equipment deployment.
- Pulmonology:Bronchoscopy and interventional pulmonology for lung cancer staging and COPD management. Specialist scarcity constrains suite utilization rates outside tertiary centers.
- Urology:Cystoscopy and ureteroscopy for stone disease and bladder cancer surveillance.
- Gynecology:Hysteroscopy and laparoscopy for fertility and oncologic procedures.
Gastroenterology commands the installed base while pulmonology climbs fastest on respiratory disease prevalence and screening expansion.
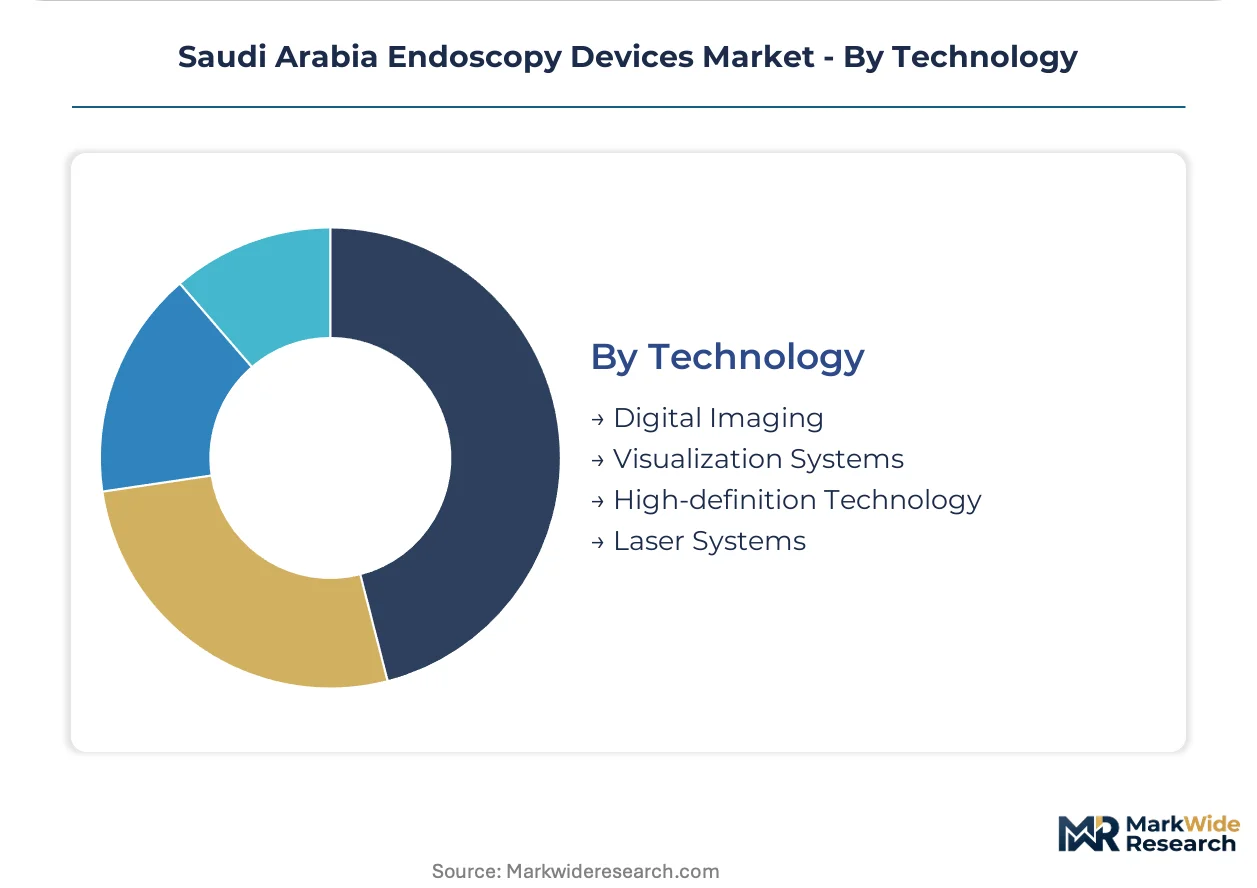
Technology:
Supply concentration in East Asian sensor manufacturing creates vulnerability for digital imaging-dependent segments.
- Digital Imaging:CMOS and CCD sensor arrays replacing fiber-optic transmission with direct-to-processor signal paths. King Faisal Specialist Hospital's gastroenterology suites are early adopters of software-upgradeable platforms.
- High-definition Technology:1080p and 4K resolution standards enabling pathology detection at earlier stages. SFDA biocompatibility testing bottlenecks delay launch timelines for upgraded systems.
- Visualization Systems:Integrated processor-monitor-tower configurations with PACS connectivity.
- Laser Systems:Nd:YAG and diode laser platforms for therapeutic endoscopy.
Digital imaging underpins current procurement standards while high-definition technology differentiates premium tier offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Saudi Arabia's healthcare geography. Riyadh and Jeddah tertiary hospitals absorb premium equipment with minimal budget friction, while emerging surgical centers in secondary cities prioritize capital-efficient single-use alternatives.
Riyadh
King Faisal Specialist Hospital and King Saud Medical City anchor gastroenterology and pulmonology suite expansion. SFDA registration requirements and NPHIES interoperability mandates favor vendors with dedicated Saudi regulatory affairs staffing. The Riyadh healthcare cluster concentrates Ministry of Health capital deployment and military hospital procurement through National Unified Procurement Company frameworks.
Jeddah
Dr. Sulaiman Al Habib Medical Group and Johns Hopkins Aramco Healthcare drive demand for high-definition visualization systems. Health Sector Transformation Program localization thresholds push international manufacturers toward Saudi-based technical service operations. Jeddah's private hospital construction pipeline outpaces public facility upgrades.
Eastern Province
Dammam and Khobar exhibit acute endoscopy infrastructure undersupply relative to Riyadh and Jeddah. Greenfield hospital construction creates first-mover positioning opportunities for equipment vendors. The Eastern Province lacks equivalent specialist density, constraining suite utilization rates despite capital inflows.
Western Region
Makkah and Madinah pilgrimage healthcare infrastructure prioritizes rapid-turnover diagnostic capacity. Single-use endoscopy adoption accelerates in these markets to bypass sterilization infrastructure investments. Religious tourism patient volumes create seasonal demand spikes for flexible endoscope deployment.
NEOM Northwest
The giga-project's healthcare district planning incorporates autonomous navigation platforms and AI-assisted diagnostic integration. Procurement frameworks for NEOM facilities remain under development, with localization requirements expected to mirror or exceed Health Sector Transformation Program mandates. Early equipment specifications favor software-upgradeable digital imaging architectures.
Saudi Arabia Endoscopy Devices Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Saudi market. The competitive structure bifurcates between premium integrated system vendors and single-use specialists. Three archetypes dominate: optical manufacturing incumbents with in-house supply chains, rigid endoscope specialists serving surgical disciplines, and disposable endoscopy innovators bypassing reprocessing constraints. Consolidation pressure concentrates through National Unified Procurement Company tender frameworks, while M&A activity targets regulatory affairs capabilities and Saudi-based technical service infrastructure.
Among Japanese-headquartered optical manufacturers, Olympus Corporation exemplifies the premium integrated systems archetype through captive control over fiber-optic and CMOS component supply. Karl Storz SE & Co. KG, a German GmbH-structured entity, anchors the rigid endoscope specialization tier for arthroscopy and laparoscopy applications. Danish limited company Ambu A/S occupies the single-use disruption position, eliminating sterilization infrastructure requirements that burden reusable competitors. These three entities represent distinct strategic vectors: upstream manufacturing control, surgical discipline focus, and capital-efficiency innovation.
| Leading Market Players |
|---|
| Olympus Corporation |
| Karl Storz SE & Co. KG |
| Boston Scientific Corporation |
| Medtronic plc |
| Fujifilm Holdings Corporation |
| Stryker Corporation |
| Pentax Medical |
| CONMED Corporation |
| Ambu A/S |
| Others |
Value Network & Pricing Analysis
CMOS sensor fabrication scale economies in East Asian manufacturing clusters concentrate optical component supply, compressing procurement costs for digital endoscope vendors while establishing price floors that exclude smaller assemblers from premium-tier competition. This concentration simultaneously empowers integrated manufacturers with captive component supply and forces distributors to absorb margin pressure from SFDA-mandated localization investments.
Pricing Analysis
After-sales service contracts and preventive maintenance subscriptions generate lifetime value multiples exceeding initial hardware margins for reusable flexible endoscope vendors. Pricing stratifies across premium, standard, and economy tiers based on CMOS sensor resolution grade and NPHIES interoperability certification level. Cost compression in the standard tier intensifies as single-use alternatives eliminate reprocessing revenue streams. Surgical centers exhibit acute price sensitivity, while tertiary hospitals in Riyadh absorb premium positioning with minimal procurement friction.
Supply Chain Analysis
Strait of Hormuz transit underwrites the majority of fiber-optic bundle and CMOS sensor shipments reaching Saudi assembly operations, exposing inventory cycles to regional logistics disruption. Component manufacturing concentrates in Japan, South Korea, and Taiwan, with sterilization-grade stainless steel sourcing anchored in German and Swiss specialty metalworks. Single-source vulnerability runs through East Asian sensor foundries with limited geographic diversification. Distribution runs through Ministry of Health National Unified Procurement Company frameworks for public hospitals, while private facilities maintain direct vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-use endoscopy substitution threatens reusable system incumbents with permanent revenue erosion unless defensive positioning hardens around irreplaceable service infrastructure. Incumbents must navigate this displacement while capturing value from emerging robotic platform categories.
For Market Incumbents: Shield installed base relationships through captive Saudi-based technical service operations that SFDA localization mandates now require. Deepen backward integration into CMOS sensor supply partnerships to secure component allocation during East Asian foundry constraints. Prioritize NPHIES interoperability certification as a procurement gatekeeper that locks out non-compliant challengers.
For New Entrants and Emerging Players: Anchor in Eastern Province greenfield hospital construction where Dammam and Khobar lack equivalent endoscopy infrastructure to Riyadh and Jeddah. Target surgical center expansion in Jeddah's privatizing healthcare delivery network, where single-use technology bypasses sterilization capital requirements. Pursue AI-assisted diagnostic integration as a differentiation lever against legacy visualization vendors.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with embedded Saudi regulatory affairs staffing and NPHIES-certified digital imaging platforms. Long-term viability favors acquisition targets with established SFDA registration pathways and localized technical service infrastructure. Watch for inflection when National Unified Procurement Company tender frameworks consolidate beyond Ministry of Health facilities into military and private hospital networks.
| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Acceleration | Streamlined approval pathways compress time-to-market for CMOS-based digital visualization systems. |
| NPHIES Interoperability Certification | Native connectivity integration captures preference in Ministry of Health centralized procurement frameworks. |
| Saudi-Based Technical Service Operations | Localization mandates under Health Sector Transformation Program force assembly and service infrastructure establishment. |
| Single-Use Endoscopy Portfolio Expansion | Elimination of reprocessing requirements lowers barriers for surgical center market entry under Vision 2030. |
| AI-Assisted Diagnostic Integration | Machine learning pairing with high-definition visualization enables real-time pathology detection differentiation. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SFDA registration databases, Gulf Standardization Organization technical filings, and hospital procurement records across the Kingdom. Primary interviews engaged biomedical engineering directors, GPO contracts managers, and SFDA regulatory affairs specialists. Secondary validation drew from Ministry of Health capital expenditure disclosures, National Unified Procurement Company tender documentation, and Vision 2030 healthcare privatization progress reports. Bottom-up demand modeling triangulated against top-down healthcare infrastructure investment trajectories.
Segmentation dimensions modeled include product type architecture, end-user facility tier, therapy area application, and technology generation across the projection horizon. CAGRs derived from procedure volume growth trajectories, equipment replacement cycles, and localization policy implementation timelines. Forecast inputs incorporated gastroenterologist fellowship pipeline constraints and NPHIES platform deployment schedules.
Underlying assumptions cover SFDA regulatory pathway stability and Health Sector Transformation Program localization enforcement continuity, with deviation risk concentrated in East Asian sensor supply disruption and specialist training pipeline expansion shortfalls. Practitioners should keep alternative scenarios live as Vision 2030 privatization timelines and NEOM healthcare district procurement frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Endoscopic Tattooing Market
Endoscopy
Global Endoscopic Clips Market
Endoscopy
Global Flexible Endoscopes Market
Endoscopy
Endoscopic Stricture Management Market
Endoscopy
Asia-Pacific Optical Fibers in Endoscopy Market
Endoscopy
Global Colonoscopy Devices Market
Endoscopy
Global Endoscope Leak Detection Device Market
Endoscopy
Global Neuroendoscopy Market
Endoscopy
Endoscopy Visualization Systems Market
Endoscopy
Endoscopic Retrograde Cholangiopancreatography (ERCP) Devices Market
Endoscopy
Disposable Bronchoscopes Market
Endoscopy
Rigid Endoscopes Market
Endoscopy
Polyp Biopsy Market
Endoscopy
Gastroscopes Market
Endoscopy
Global Disposable Endoscope Market
Endoscopy
Endoscope Detergents and Disinfectants Market