
 Global Safety Syringes Market | 2026-2036
Global Safety Syringes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Safety Syringes Market Foresight
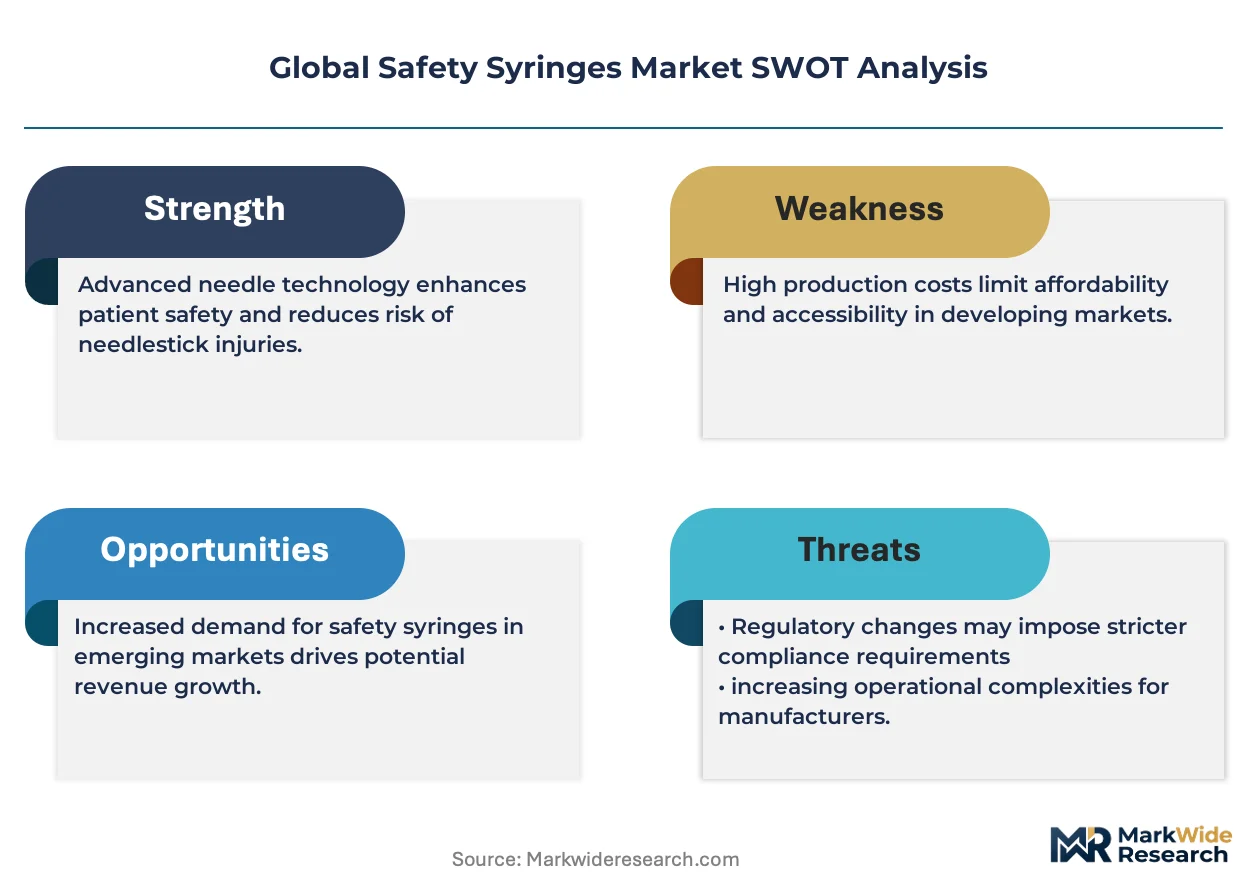
Project finance for large-scale syringe manufacturing is narrowing the competitive field to capital-intensive operators. Becton, Dickinson and Company leverages its integrated manufacturing footprint across multiple continents to sustain cost advantages. Terumo Corporation anchors its position through specialized polymer engineering capabilities in retractable needle platforms. Smiths Medical competes by controlling distribution networks within European hospital systems.
Safety syringes incorporate integrated needle-retraction or needle-shielding mechanisms, typically constructed from medical-grade polypropylene barrels with stainless steel or alloy needles bonded via adhesive or friction-fit processes, designed to prevent needlestick injuries and reuse after a single injection cycle. Retractable needle syringes dominate value pools due to premium pricing in institutional settings, while auto-disable syringes lead volume growth through WHO-prequalified procurement for vaccination campaigns. Prefilled syringes command margin concentration in biologics delivery, where pharmaceutical partnerships create captive demand.
The FDA enforces needlestick safety standards under the Bloodborne Pathogens Standard, while the EMA's Medical Device Regulation mandates clinical evidence for safety-engineered designs, and WHO prequalification governs access to developing-country tenders. These frameworks compel manufacturers to redesign products for regulatory multiplicity rather than single-market approval. Stakeholders must monitor how the EU AI Act's quality-system requirements intersect with smart-syringe traceability features to determine compliance investment priorities.
Market Dynamics
The WHO's smart syringe standardization push is compressing procurement cycles and forcing manufacturers to retool for dual-mechanism platforms capable of satisfying both needlestick prevention and reuse-prevention mandates simultaneously.
Growth Catalysts
- Immunization program scale-up:India's Universal Immunization Programme is expanding cold-chain infrastructure that pairs auto-disable syringes with temperature-stable delivery systems, creating bundled procurement demand.
- OSHA Bloodborne Pathogens Standard enforcement:US hospital systems face penalty exposure for needlestick incidents, accelerating replacement of conventional syringes with retractable-needle platforms in high-risk departments.
- Polymer engineering advances:Medical-grade cyclic olefin polymer barrels now enable thinner-wall construction without strength loss, reducing material costs for high-volume manufacturers.
Market Restraints
- Stainless steel needle supply concentration:Three Japanese and German metallurgical suppliers control premium hypodermic needle substrate, exposing manufacturers to alloying element price volatility.
- EMA MDR clinical evidence requirements:Safety-engineered designs now require biocompatibility testing documentation that adds 18-24 months to European market entry timelines.
- Glass prefilled syringe substitution:Biologics manufacturers increasingly specify borosilicate glass for protein stability, constraining polymer-based safety syringe penetration in high-margin therapeutic segments.
Strategic Opportunities
- Sub-Saharan Africa tender access:WHO prequalification pathways for auto-disable syringes remain underutilized by Asian manufacturers, creating first-mover potential in Gavi-funded campaigns.
- Home healthcare self-injection:Diabetes and obesity therapeutic pipelines are expanding patient-administered biologics, opening demand for passive needle-shielding designs with intuitive activation.
- EU AI Act traceability alignment:Smart syringes with embedded RFID or NFC authentication can satisfy both anti-counterfeiting mandates and quality-system documentation requirements.
Industry Challenges
- Tooling engineer scarcity:Precision mold design for retractable mechanisms requires expertise in multi-cavity hot-runner systems that few polymer processing specialists possess.
- ISO 7886-4 certification backlog:Testing laboratory capacity constraints are delaying auto-disable syringe validation for developing-country tenders.
- Legacy ERP integration:Smart-syringe serialization requirements force manufacturers to retrofit manufacturing execution systems with unit-level tracking capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Safety Syringes Market |
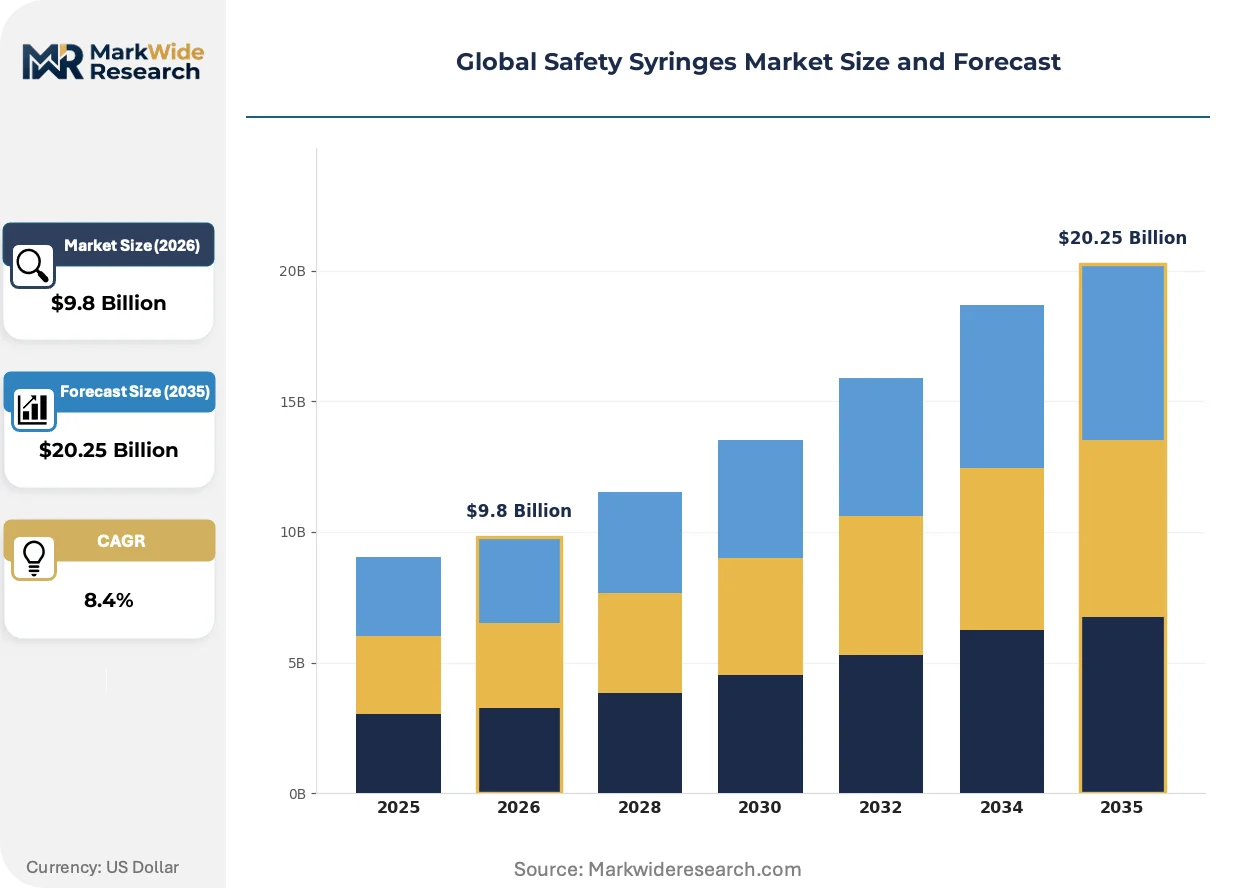
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Retractable Needle Syringes, Auto-Disable Syringes, Needle-Less Syringes, Prefilled Syringes, Insulin Syringes Application: Vaccination, Diabetes Management, Intravenous Therapy, Blood Sampling, Allergy Testing End User: Clinics, Laboratories, Home Care Settings, Immunization Centers, Dialysis Centers Deployment: Disposable, Reusable, Single-Use, Preloaded, Safety-Engineered Devices |
| Companies Covered | Becton, Dickinson and Company, Terumo Corporation, Smiths Medical, B. Braun Melsungen AG, Retractable Technologies, Inc., Cardinal Health, Medtronic plc, Nipro Corporation, Unilife Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Safety Syringes Market Shifts & Advancements
Mechanism miniaturization and connected-device integration are bifurcating the product landscape into cost-optimized disposable platforms and premium traceable systems for controlled-substance applications.
Spring-retracted needle systems with passive activation triggers are rendering obsolete manual needle-sheathing devices in US emergency departments. Hospital purchasing committees now specify single-handed activation as a minimum safety feature. The shift is compressing margins for manufacturers still dependent on add-on safety accessories.
EMA's Medical Device Regulation (MDR) Annex I general safety and performance requirements are forcing redesigns of legacy safety syringe platforms for European market access. Clinical evaluation reports must now demonstrate equivalence or superiority against predicate devices. German hospital procurement associations are consolidating supplier lists to vendors with MDR-certified portfolios.
Consolidated buying by US group purchasing organizations is concentrating contract awards among manufacturers with dual-site FDA-registered production. Smaller vendors without redundant manufacturing footprints are exiting institutional segments. The pattern is most visible in the Southeast, where Premier and Vizient members dominate hospital system membership.
Global Safety Syringes Market Segmentation
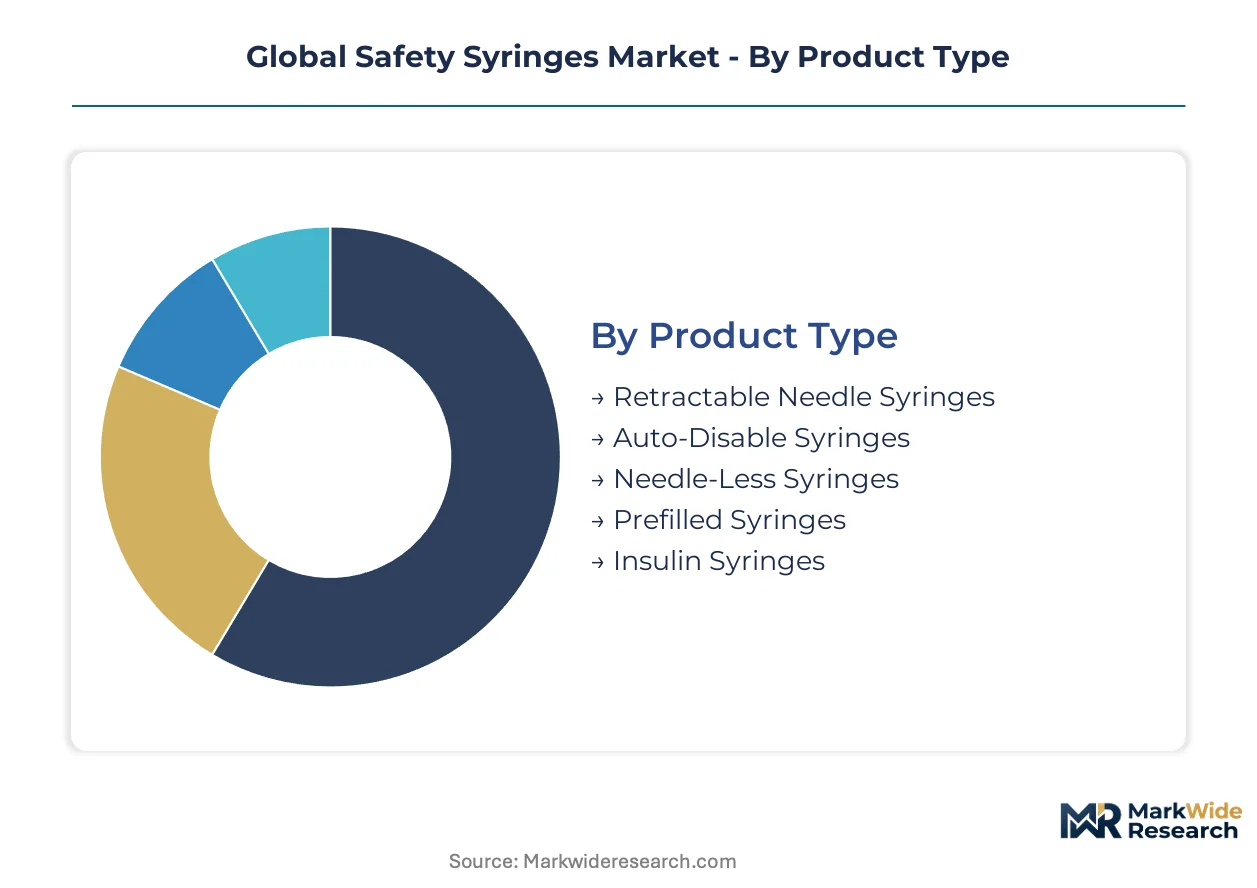
Safety syringe procurement varies sharply by clinical setting and mechanism type. Manufacturers must align product portfolios with distinct regulatory pathways and reimbursement codes that govern each segment's commercial viability.
Product Type:
Mature retractable platforms coexist with emerging needle-less delivery systems as hospitals balance proven safety records against novel administration technologies.
- Retractable Needle Syringes:Spring-loaded mechanisms draw needles into the barrel post-injection using stainless steel coils bonded to polypropylene housings. US emergency departments and surgical suites specify these for OSHA compliance, with procurement concentrated among GPO-contracted suppliers.
- Auto-Disable Syringes:Friction-lock or break-plunger designs render the device inoperable after single use. India's Universal Immunization Programme drives volume through bundled cold-chain tenders, while WHO prequalification governs access to Gavi-funded African campaigns.
- Needle-Less Syringes:Jet injectors and micro-needle arrays for vaccine and insulin delivery.
- Prefilled Syringes:Glass or polymer barrels preloaded with biologics for hospital and home settings.
- Insulin Syringes:Ultra-fine gauge needles with unit-dose calibration for diabetes self-administration.
Retractable needle syringes handle the majority of institutional throughput; auto-disable syringes are expanding most quickly through immunization scale-up.
Application:
Volume concentration in mass vaccination programs contrasts with margin-rich therapeutic delivery where device-pharma partnerships create captive demand.
- Vaccination:National immunization programs in India, Nigeria, and Indonesia specify auto-disable mechanisms for injectable vaccines. WHO prequalification requirements compress procurement cycles to 12-18 months, favoring manufacturers with validated sterilization tunnels and automated assembly lines.
- Diabetes Management:Daily insulin administration drives demand for 0.3ml to 1ml syringes with 31-gauge needles. US Medicare Part D reimbursement codes and European tender frameworks determine pricing floors for disposable platforms.
- Intravenous Therapy:Safety-engineered designs for medication and fluid administration in hospital settings.
- Blood Sampling:Vacuum-assisted and standard aspiration devices for diagnostic laboratories.
- Allergy Testing:Micro-volume delivery systems for subcutaneous allergen administration.
Vaccination absorbs the highest absolute unit volumes; diabetes management shows the steepest expansion trajectory as obesity-related therapeutic pipelines mature.
End User:
Institutional procurement through centralized tenders diverges from fragmented home-care purchasing where retail pharmacy networks and direct-to-patient channels compete.
- Clinics:Outpatient facilities in Germany's Kassenärztliche Vereinigung networks and US federally qualified health centers purchase through regional buying cooperatives. EMA MDR certification and FDA 510(k) clearance determine supplier eligibility for multi-year framework agreements.
- Laboratories:Diagnostic chains in Japan and the UK specify safety-engineered blood collection devices. Automated sample handling systems require syringe-barcode compatibility and robotic gripper dimensions that constrain vendor selection.
- Home Care Settings:Patient-administered therapies through retail and mail-order channels.
- Immunization Centers:Government-operated facilities for mass vaccination campaigns.
- Dialysis Centers:Specialized anticoagulant and medication delivery for renal therapy.
Clinics represent the largest addressable base; home care settings are gaining share fastest as self-injection therapies proliferate.
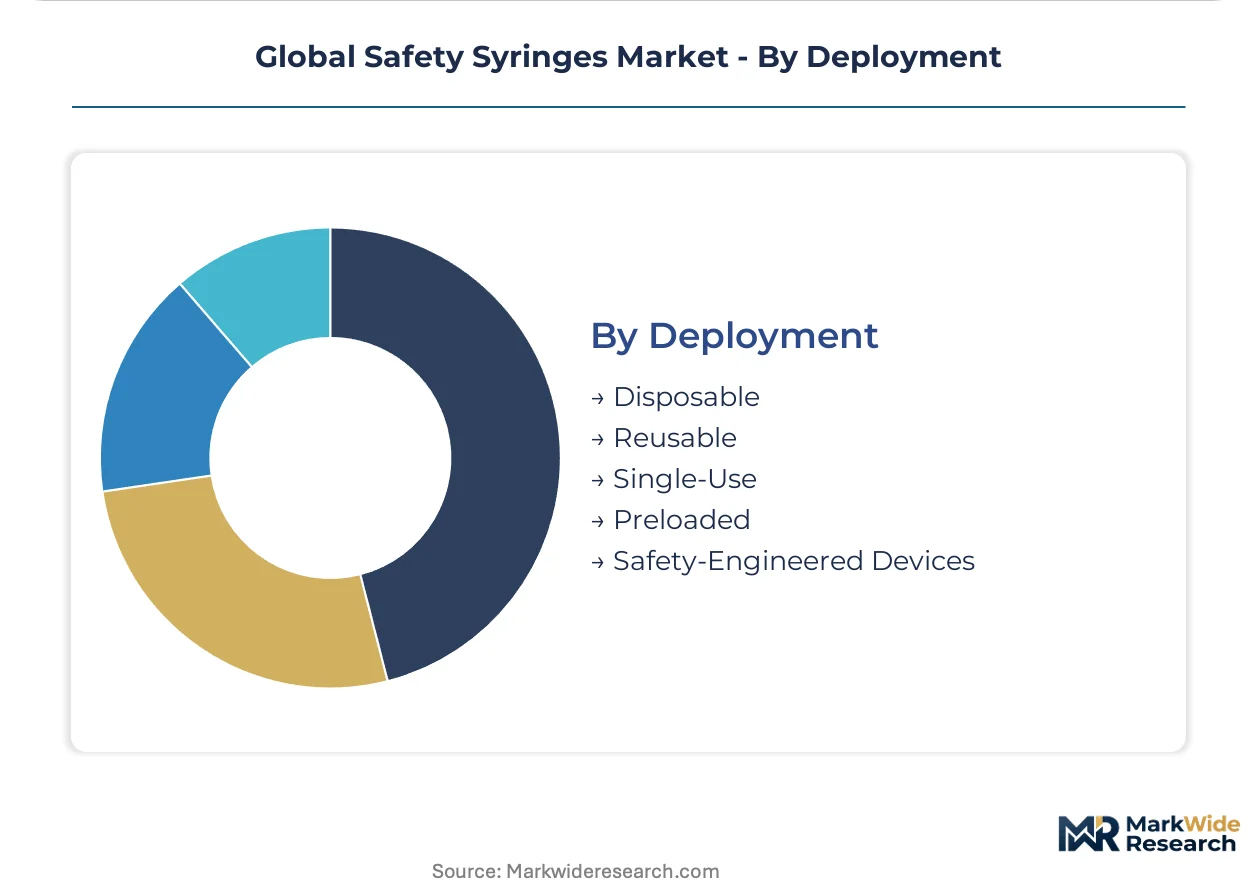
Deployment:
Single-use disposables dominate infectious disease applications while safety-engineered platforms command premium positioning in occupational health mandates.
- Disposable:Gamma-sterilized polypropylene devices for immediate disposal post-use. US hospital systems under Joint Commission accreditation face audit scrutiny for sharps container compliance, driving specification of integrated safety mechanisms rather than accessory add-ons.
- Single-Use:Identical technical specifications to disposable but with explicit regulatory labeling for one-time activation. India's CDSCO and Brazil's ANVISA require distinct packaging and instructions for use that add 8-12% to landed costs versus multi-use jurisdictions.
- Reusable:Autoclavable metal-and-glass assemblies for specialized therapeutic applications.
- Preloaded:Pharmaceutical-manufacturer-filled units for specific drug-device combinations.
- Safety-Engineered Devices:OSHA-compliant designs with passive or active needlestick protection.
Disposable platforms handle the majority of unit throughput; safety-engineered devices are climbing the fastest as regulatory mandates harden across OECD markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government immunization mandates and needlestick prevention regulations are redrawing procurement specifications across major healthcare markets. National tender frameworks now prioritize dual-mechanism safety platforms that satisfy both occupational safety and reuse-prevention requirements simultaneously.
United States
OSHA Bloodborne Pathogens Standard enforcement drives hospital system conversion to retractable-needle platforms in emergency departments and surgical suites. FDA 510(k) clearance pathways govern market entry timelines for new safety-engineered designs. Manufacturing concentration clusters in New Jersey and North Carolina, where dual-site FDA-registered production facilities serve Premier and Vizient group purchasing organization contracts.
Germany
EMA Medical Device Regulation Annex I requirements now mandate clinical evaluation reports demonstrating equivalence against predicate devices for safety syringe platforms. Kassenärztliche Vereinigung procurement networks consolidate supplier lists to vendors with MDR-certified portfolios. The Baden-Württemberg medical technology corridor hosts precision polymer processing specialists serving European hospital system tenders.
India
The Universal Immunization Programme expands cold-chain infrastructure pairing auto-disable syringes with temperature-stable delivery systems, creating bundled procurement demand. CDSCO regulations and domestic manufacturing incentives under the PLI scheme expand access to safety-engineered devices. Manufacturing hubs in Gujarat and Maharashtra scale automated assembly lines for WHO prequalification.
Japan
PMDA quality system requirements govern safety syringe approval pathways for domestic hospital procurement. METI industrial policy supports specialized polymer engineering capabilities in retractable needle platforms. The Kansai region maintains metallurgical supply chain concentration for premium hypodermic needle substrate production.
Brazil
ANVISA labeling requirements for single-use devices add regulatory compliance costs distinct from multi-use jurisdictions. National immunization program tenders specify auto-disable mechanisms for injectable vaccines distributed through public health networks. São Paulo state anchors regional distribution infrastructure serving Latin American procurement channels.
Global Safety Syringes Market Competitive Landscape
On the supply side, the industry is consolidating around capital-intensive operators with validated sterilization tunnels and automated assembly capabilities. The competitive field narrows to manufacturers possessing redundant manufacturing footprints and multi-continent regulatory registrations. Three strategic archetypes dominate: integrated global health conglomerates with diversified device portfolios, specialized polymer engineering firms focused on retractable mechanisms, and regional contract manufacturers serving tender-driven immunization programs. Dominant competitive moves include capacity expansion in low-cost manufacturing zones and strategic partnerships with pharmaceutical companies for prefilled drug-device combinations.
Among integrated device manufacturers, Becton, Dickinson and Company, Terumo Corporation, and Smiths Medical occupy positions representing distinct competitive vectors. Becton, Dickinson and Company exemplifies the scale-driven archetype with multi-continent manufacturing footprints. Terumo Corporation sits within the specialized engineering tier, anchored in precision polymer capabilities. Smiths Medical represents the European hospital system integration model, positioned through distribution network control. These three entities collectively illustrate how regulatory multiplicity favors operators with diversified geographic presence and redundant production capabilities.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Terumo Corporation |
| Smiths Medical |
| B. Braun Melsungen AG |
| Retractable Technologies, Inc. |
| Cardinal Health |
| Medtronic plc |
| Nipro Corporation |
| Unilife Corporation |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese polymer processing facilities is compressing margins for standard-grade safety syringes while tightening supply for ISO 7886-4 certified platforms. This utilization gap separates capital-intensive operators with validated sterilization tunnels from commodity assemblers locked in price competition.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers. Three-tier pricing structure across MDR-certified, FDA-cleared, and economy-grade products dominates contract negotiations. Cost compression in economy auto-disable syringes is intensifying because Indian PLI scheme beneficiaries are expanding automated assembly capacity. Hospital purchasing committees exhibit the highest price sensitivity for high-volume immunization tenders, while biologics manufacturers show minimal sensitivity for prefilled drug-device combinations.
Supply Chain Analysis
Contract manufacturing concentration rests with Foxconn Health Technology, Jabil Healthcare, and Flex Medical holding multi-site polymer molding capacity. Raw material dependencies draw from Japanese stainless steel needle substrate, German medical-grade polypropylene resin, and Malaysian rubber plunger components. Single-source vulnerability in hypodermic needle metallurgy exposes assemblers to nickel and chromium price volatility. Distribution runs through Premier and Vizient group purchasing organizations in the United States, Kassenärztliche Vereinigung networks in Germany, and UNICEF procurement channels for developing-country tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated procurement through US group purchasing organizations and European hospital system alliances. This consolidation fragments pricing leverage for smaller manufacturers lacking multi-year framework contracts.
For Market Incumbents: Insulate margin position by deepening backward integration into medical-grade polymer compounding and expanding redundant FDA-registered production in North Carolina or New Jersey. Needle-less jet injector platforms pose substitution risk in vaccination segments; counter through exclusive prefilled partnerships with obesity therapeutic developers. For New Entrants and Emerging Players: Sub-Saharan African WHO prequalification pathways represent the most penetrable entry point for auto-disable syringe specialists lacking legacy GPO relationships. India's CDSCO domestic manufacturing incentives offer secondary access through technology transfer partnerships with Gujarat-based sterilization facilities. Pursue Gavi-funded campaign tenders with bundled cold-chain packaging to differentiate from established suppliers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because EMA MDR certification timelines and FDA 510(k) clearance pathways create durable barriers against commoditization. Target acquisition profiles should emphasize European hospital system distribution relationships over pure manufacturing capacity. Monitor ISO 7886-4 testing laboratory capacity expansion as the signal for developing-country tender acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-mechanism platform development | Retooling for simultaneous needlestick and reuse prevention satisfies WHO smart syringe mandates. |
| MDR clinical evidence investment | Biocompatibility documentation accelerates European hospital system procurement eligibility. |
| RFID traceability integration | Embedded authentication satisfies EU AI Act quality-system requirements for smart devices. |
| Sub-Saharan tender prequalification | WHO pathway access unlocks Gavi-funded immunization campaign volumes. |
| Pharma partnership for prefilled combinations | Captive demand from biologics manufacturers insulates against commodity pricing pressure. |
Research Methodology
Initial hypotheses were tested against primary input from hospital purchasing committee directors, GPO contracts managers, biomedical engineers, and regulatory affairs leads at polymer processing firms, then refined through secondary validation. FDA 510(k) filings, EMA MDR technical documentation, WHO prequalification status reports, and UNICEF procurement tender databases anchored the quantitative foundation. Bottom-up capacity assessments at Gujarat and Maharashtra manufacturing clusters were triangulated against top-down demand modeling from national immunization program budgets.
Demand-supply balance dynamics across the analysis window were modeled through segmented adoption curves for retractable, auto-disable, and prefilled platforms. Mechanism type, end-user setting, certification tier, and regional regulatory cluster formed the core segmentation dimensions. CAGRs were derived from fitted growth curves calibrated to procurement cycle data and sterilization capacity expansion timelines. Polymer engineering advances in cyclic olefin polymer barrels and needle substrate alloying specifications informed supply-side elasticity assumptions.
Stress conditions across stainless steel price volatility, EMA MDR certification delays, and Gavi funding allocation shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding WHO smart syringe standardization adoption rates and OSHA enforcement intensity. Quarterly review of testing laboratory capacity utilization and group purchasing organization contract renewal patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Medical Swabs Market
Medical Supplies
Blood Processing Disposables Market
Medical Supplies
Global Dental Syringes Market
Medical Supplies
Nasal Oxygen Cannula Market
Medical Supplies
Dissolvable Stitches Market
Medical Supplies
Latex Medical Disposables Market
Medical Supplies
Nipple Shield Market
Medical Supplies
Hydrocolloid Sponges Market
Medical Supplies
Medical Procedure Tray Market
Medical Supplies
Global Hospital Supplies Market
Medical Supplies
Anesthesia Disposables Market
Medical Supplies
Global Dialysis Concentrate Market
Medical Supplies
Disposable Medical Gowns Market
Medical Supplies
India Feminine Hygiene Market
Medical Supplies
South America Syringe Market
Medical Supplies
Swabs Collection Kit Market