
 Pectus Bar System Market | 2026-2036
Pectus Bar System Market Size, Share, and Industry Trends Forecast 2026-2036
Pectus Bar System Market Analytics
Market Context with Strategic Players
Pediatric thoracic surgery is hardening as the dominant end-use vertical for pectus bar systems, displacing slower-growing adult correction segments. Zimmer Biomet leverages its orthopedic implant manufacturing scale to control supply relationships with major pediatric hospital networks. Stryker anchors its position through specialized sales forces trained in minimally invasive chest wall repair protocols. Ventura Medical Technologies differentiates by focusing exclusively on thoracic deformity correction devices.
Technical Definition and Structural Segments
A pectus bar system comprises curved metallic or non-metallic implant rods inserted substernally via minimally invasive techniques to correct congenital chest wall deformities, typically manufactured from medical-grade stainless steel or titanium alloys with specific tensile strength exceeding 800 MPa to withstand physiological loading. Titanium bars command premium positioning due to superior magnetic resonance imaging compatibility and reduced inflammatory response profiles. Stainless steel bars occupy the volume tier through established reimbursement codes and lower per-procedure costs. Hospitals represent the most concentrated end-user channel, with outpatient surgical centers representing the fastest-growing access point as ambulatory thoracic procedures expand.
Regulatory Frame and Forward-Looking Close
FDA 510(k) clearance pathways and CE marking under the EU Medical Device Regulation govern implantable pectus bar commercialization, with both frameworks intensifying post-market surveillance requirements for long-term biocompatibility data. Japan's PMDA maintains distinct clinical trial expectations for thoracic implants that delay market entry relative to Western timelines. Stakeholders must monitor evolving reimbursement decisions for minimally invasive chest wall reconstruction across public and private payor systems.
Market Dynamics
Pediatric thoracic surgery departments are consolidating minimally invasive pectus excavatum repair programs around titanium bar platforms, creating procurement concentration at tertiary hospital networks.
Growth Catalysts
- EU Medical Device Regulation:Post-market surveillance mandates for long-term biocompatibility data are accelerating hospital upgrades to next-generation implant systems with documented clinical histories.
- Titanium alloy platforms:Superior MRI compatibility and reduced inflammatory response profiles are pulling demand from stainless steel alternatives in pediatric correction procedures.
- United States reimbursement:Established CPT codes for minimally invasive chest wall reconstruction are stabilizing procedure economics at specialized surgical centers.
Market Restraints
- Titanium sponge supply:Concentrated mining and refining operations in Russia and China create raw material vulnerability for premium bar manufacturers.
- PMDA clinical trial requirements:Japan's distinct thoracic implant validation protocols extend market entry timelines by 18-24 months relative to FDA 510(k) pathways.
- External bracing systems:Non-surgical orthotic alternatives for mild pectus excavatum cases capture correction demand before surgical thresholds.
Strategic Opportunities
- Ambulatory surgical centers:Outpatient thoracic procedure expansion creates channel diversification beyond traditional hospital purchasing.
- Adult correction segment:Underpenetrated demand for pectus excavatum repair in patients over 18 years offers volume expansion outside pediatric saturation.
- 3D-printed patient-specific bars:Convergence of additive manufacturing and pre-surgical planning software enables customized implant geometries.
Industry Challenges
- Pediatric thoracic surgeon training:Limited fellowship programs in minimally invasive chest wall repair constrain procedure volume growth at mid-tier hospitals.
- ISO 13485 certification timelines:Quality management system audits for implantable device manufacturing extend supplier qualification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pectus Bar System Market |
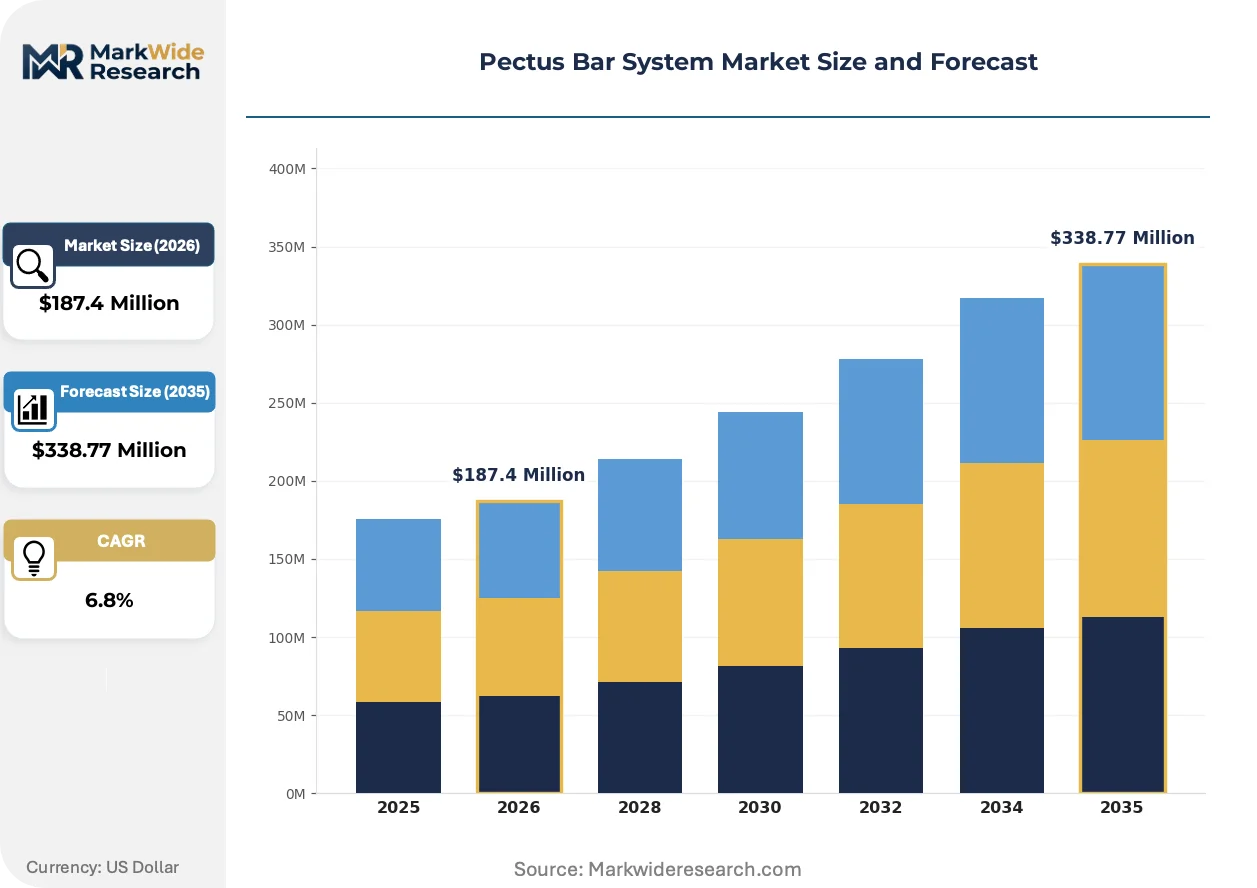
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel Bars, Titanium Bars, Non-Metal Bars, Hybrid Bars Application: Surgical Procedures, Non-Surgical Treatments, Clinical Trials, Research Studies End User: Hospitals, Outpatient Clinics, Surgical Centers, Academic Institutions Distribution Channel: Direct Sales, Online Platforms, Distributors, Medical Supply Stores |
| Companies Covered | Rultract, Biotech GmbH, Zimmer Biomet, Stryker, IDEAR, Johnson & Johnson, Ventura Medical Technologies, Medtronic, MedXpert, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pectus Bar System Market Evolving Landscape
Digital surgical planning tools and biocompatible material advances are compressing the gap between diagnostic imaging and personalized implant deployment.
Shape-memory nitinol pectus bars are unifying pre-operative bending and intra-operative adjustment into single-procedure workflows. Pediatric surgical teams at specialized chest wall centers are adopting these platforms for complex asymmetric deformities. The technology is unifying previously separate pre-surgical customization and operating room efficiency metrics into unified outcome measurements.
FDA 510(k) clearance pathways are tightening evidentiary requirements for predicate device comparisons in thoracic implant submissions. Manufacturers must now submit extended biocompatibility testing protocols for metallic ion release profiles. Titanium bar systems with five-year post-market surveillance data are navigating this transition more rapidly than newer alloy formulations.
Hospital procurement committees are consolidating vendor relationships around full-service implant programs that bundle bars, fixation hardware, and specialized instrumentation. Independent outpatient surgical centers lack capital budgets for multi-vendor instrument sterilization and are standardizing on single-source contracts. This concentration is most visible in Germany, where integrated hospital networks negotiate system-wide purchasing agreements.
Pectus Bar System Market Segmentation
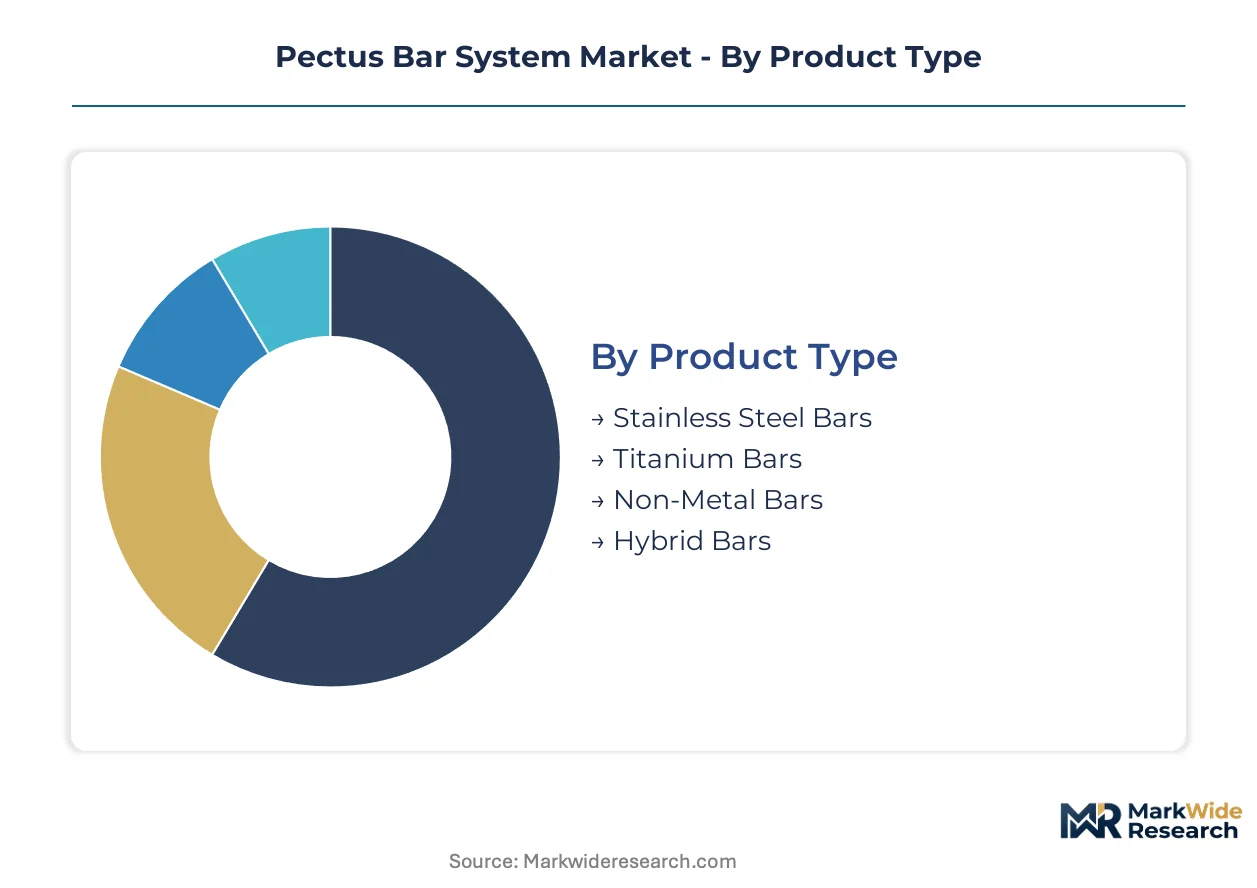
Material composition and access channel decisions determine reimbursement pathways and surgical outcomes in pectus bar procurement. Segmentation reveals where capital deployment concentrates across implant technologies and care delivery settings.
Product Type:
Titanium alloy platforms demand the highest upfront manufacturing investment due to specialized vacuum arc remelting equipment and extended biocompatibility testing protocols.
- Titanium Bars:Manufactured from Ti-6Al-4V ELI alloy with tensile strength exceeding 900 MPa and full MRI compatibility. Pediatric thoracic surgery departments at tertiary hospitals in the United States and Germany are standardizing procurement around these platforms despite premium pricing, driven by reduced revision rates and superior inflammatory response profiles.
- Stainless Steel Bars:Medical-grade 316L stainless steel construction with established CPT reimbursement codes and lower per-procedure costs. Volume concentration remains highest at mid-tier hospital networks where procurement committees prioritize capital efficiency over advanced imaging compatibility.
- Non-Metal Bars:Polyetheretherketone (PEEK) and carbon fiber composite alternatives targeting patients with documented metal hypersensitivity.
- Hybrid Bars:Multi-material constructs combining titanium surface layers with stainless steel cores for cost-optimized performance.
Most installed capacity flows through Stainless Steel Bars. Expansion is steepest in Titanium Bars.
Application:
Surgical correction absorbs the majority of clinical resource allocation, though research infrastructure is expanding fastest.
- Surgical Procedures:Minimally invasive Nuss and Ravitch techniques requiring substernal bar placement with thoracoscopic guidance. Demand concentrates at specialized chest wall reconstruction centers in Japan and Germany where fellowship-trained surgeons perform high-volume pediatric corrections.
- Non-Surgical Treatments:External bracing and vacuum bell protocols for mild deformity cases below surgical thresholds.
- Clinical Trials:PMDA-mandated long-term biocompatibility studies for novel alloy formulations.
- Research Studies:Biomechanical loading analysis and patient-reported outcome instrument development at academic medical centers.
Procedure volume concentrates in Surgical Procedures. Investment is climbing fastest in Research Studies.
End User:
Capital equipment requirements and sterilization infrastructure determine which care settings can support minimally invasive thoracic programs.
- Hospitals:Tertiary pediatric centers with dedicated thoracic surgery divisions and 24-hour emergency bar removal capabilities. These facilities capture the majority of complex asymmetric deformity cases requiring specialized instrumentation suites.
- Surgical Centers:Ambulatory facilities expanding into outpatient chest wall reconstruction with abbreviated length-of-stay protocols. Fastest-growing access point in the United States where payor pressure drives site-of-care migration.
- Outpatient Clinics:Diagnostic and follow-up settings without operative capabilities.
- Academic Institutions:Training programs and research infrastructure supporting fellowship expansion.
Revenue concentration sits with Hospitals. Patient volume is shifting fastest toward Surgical Centers.
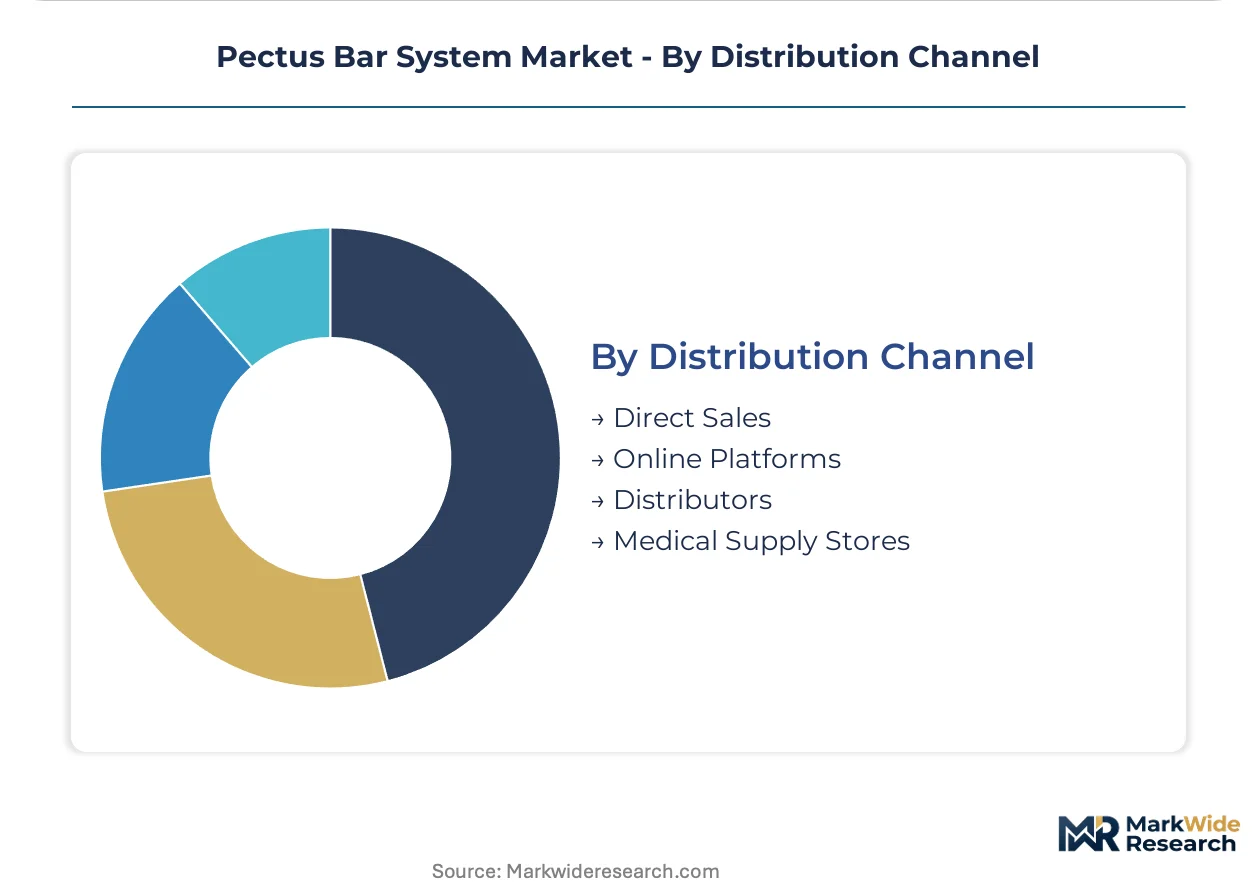
Distribution Channel:
Instrument sterilization logistics and surgeon training requirements favor relationship-based procurement over transactional purchasing.
- Direct Sales:Manufacturer field representatives providing operative training, case coverage, and instrument loaner programs. Dominant in Germany where integrated hospital networks negotiate system-wide purchasing agreements bundling bars, fixation hardware, and specialized tools.
- Distributors:Regional medical device specialists with local inventory and sterilization asset support.
- Online Platforms:Emerging procurement channel for commoditized fixation hardware and replacement components.
- Medical Supply Stores:Limited relevance for implantable devices due to regulatory custody requirements.
Transaction volume flows predominantly through Direct Sales. Channel diversification is advancing fastest through Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting titanium bar production toward jurisdictions with streamlined biocompatibility certification pathways. Manufacturers face divergent cost-of-compliance structures across FDA, CE marking, and PMDA jurisdictions.
United States
Pediatric thoracic surgery volume concentrates at tertiary centers in Boston, Philadelphia, and Houston where fellowship-trained surgeons perform high-volume Nuss procedures. FDA 510(k) clearance pathways for pectus bars require predicate device comparisons with extended metallic ion release testing. Cleveland Clinic and Children's Hospital of Philadelphia anchor procurement consolidation around titanium platforms with documented five-year surveillance data.
Germany
Integrated hospital networks in Bavaria and North Rhine-Westphalia negotiate system-wide purchasing agreements bundling bars, fixation hardware, and instrumentation. CE marking under EU Medical Device Regulation mandates post-market surveillance for long-term biocompatility data that favors established manufacturers. Berlin and Munich host specialized chest wall reconstruction centers driving standardization around full-service implant programs.
Japan
PMDA clinical trial requirements for thoracic implants extend market entry timelines by 18-24 months relative to Western regulators. Tokyo and Osaka medical centers maintain distinct validation protocols that delay adoption of novel alloy formulations. Domestic procurement favors suppliers with documented Japanese clinical histories over newer market entrants.
China
NMPA regulatory pathways for implantable thoracic devices are tightening material traceability requirements for titanium sponge sourcing. Shanghai and Beijing pediatric hospitals are expanding minimally invasive chest wall programs amid rising congenital deformity diagnosis rates. Local manufacturers face raw material vulnerability from concentrated Russian and Chinese titanium refining operations.
Pectus Bar System Market Competitive Landscape
Portfolio diversification dominates the current landscape as orthopedic conglomerates extend into specialized thoracic segments. The vendor base stratifies across three tiers: diversified implant manufacturers with pediatric sales infrastructure, dedicated chest wall device specialists, and regional fabricators serving price-sensitive hospital networks. Strategic archetypes include full-service bundlers, titanium alloy specialists, and stainless steel volume players. M&A activity and direct sales force expansion represent the primary competitive vectors.
Among diversified orthopedic manufacturers, Zimmer Biomet and Stryker exemplify scale-driven market presence through established hospital supply relationships. Ventura Medical Technologies occupies a specialist position focused exclusively on thoracic deformity correction devices. These three entities anchor the competitive structure through divergent strategic postures: conglomerate breadth versus dedicated specialization.
| Leading Market Players |
|---|
| Rultract |
| Biotech GmbH |
| Zimmer Biomet |
| Stryker |
| IDEAR |
| Johnson & Johnson |
| Ventura Medical Technologies |
| Medtronic |
| MedXpert |
| Others |
Value Network & Pricing Analysis
Titanium-stainless steel bifurcation in implant bar performance creates divergent cost structures across procurement tiers, with premium MRI-compatible platforms commanding specialized vacuum arc remelting capacity while volume-tier alternatives feed from standardized 316L rolling stock. This performance gap manifests in procurement committee decision matrices at tertiary pediatric centers versus mid-tier hospital networks, with each tier anchoring distinct supplier qualification pathways and inventory financing models.
Pricing Analysis
Distributor margins compress most severely at the stainless steel tier where commoditized 316L bar stock faces direct price competition from regional fabricators. Three-tier pricing structure across premium, standard, and economy levels separates titanium ELI alloy systems with five-year surveillance data from standard titanium platforms and medical-grade stainless steel alternatives. Pricing pressure stems from GPO-negotiated contract aggregation at integrated hospital networks. Pediatric thoracic surgery departments exhibit lowest price sensitivity due to revision-cost avoidance, while ambulatory surgical centers prioritize per-procedure capital efficiency.
Supply Chain Analysis
Workforce availability for vacuum arc remelting technicians constrains titanium alloy production expansion in Germany and the United States. Raw material supply draws from Russian and Chinese titanium sponge concentration for premium alloy feedstock, with medical-grade stainless steel sourcing from South Korean and Japanese rolling mills. Single-source vulnerability concentrates in titanium sponge refining operations subject to export licensing variability. Distribution runs through manufacturer direct sales forces with instrument loaner programs at specialized chest wall centers, supplemented by regional distributors with sterilization asset support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pectus bar system manufacturing arbitrage opportunities emerge between FDA 510(k) clearance timelines and PMDA extended validation protocols, with cost differentials favoring early-stage clinical data collection in Western jurisdictions before Japanese market entry.
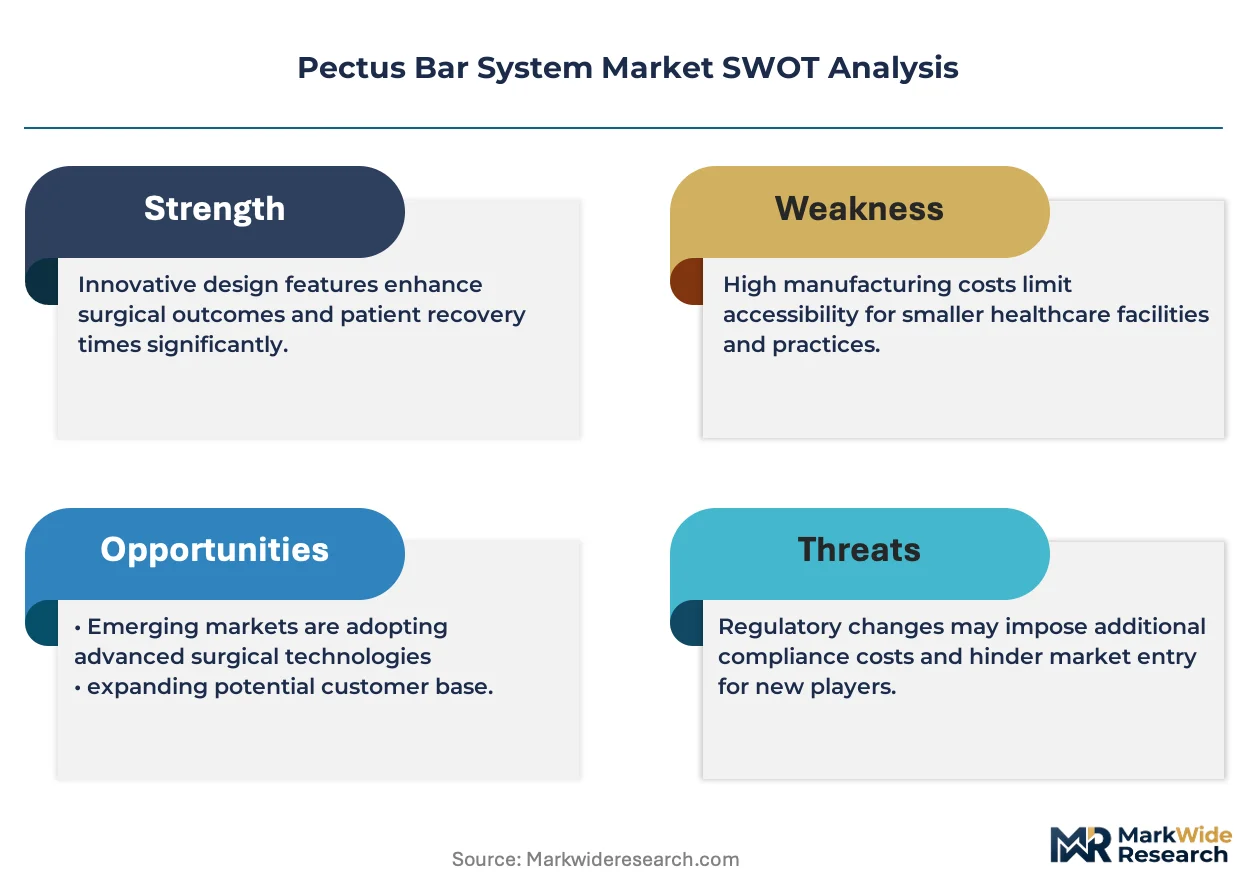
For Market Incumbents: To counter shape-memory nitinol platform disruption from specialized thoracic device firms, titanium alloy specialists should secure backward integration into vacuum arc remelting capacity and accelerate five-year post-market surveillance documentation for predicate device advantages. Stainless steel volume players must defend GPO contract renewals through bundled instrumentation programs that raise switching costs at mid-tier hospital networks. For New Entrants and Emerging Players: Launch via ambulatory surgical center distribution partnerships targeting outpatient chest wall reconstruction migration in the United States. Adult correction segments over 18 years present the most penetrable white-space target, with 3D-printed patient-specific bar platforms offering differentiation against standardized implant geometries. Reimbursement strategy development for novel alloy formulations should precede clinical trial investment. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 13485 certification timelines extend supplier qualification periods beyond typical private equity hold horizons. Long-term viability in this market hinges on capturing specialized thoracic surgeon training relationships and hospital system purchasing committee access. Acquisition targets should display established PMDA clinical histories or exclusive ambulatory surgery center contracts. The signal to watch is FDA evidentiary requirement tightening for metallic ion release testing, which favors incumbents with predicate device databases.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Extended metallic ion release testing requirements favor established manufacturers with predicate device histories. |
| CE Marking Under EU MDR | Post-market surveillance mandates for biocompatibility data accelerate hospital procurement of next-generation platforms. |
| Hospital System Partnership | Integrated network purchasing agreements in Germany consolidate vendor relationships around full-service implant programs. |
| Software Companion Development | Digital surgical planning tools compress diagnostic-to-implant deployment timelines at specialized chest wall centers. |
| Reimbursement Strategy | CPT code maintenance for minimally invasive chest wall reconstruction stabilizes procedure economics at surgical centers. |
Research Methodology
Multiple input streams — pediatric thoracic surgeon interviews, hospital procurement committee discussions, biomedical engineering assessments — were reconciled against secondary validation from FDA 510(k) filings, CE marking databases, and hospital GPO contract records. Primary engagement captured perspectives from clinicians at tertiary chest wall reconstruction centers, implant manufacturing quality directors, and ambulatory surgery center operations managers. Bottom-up procedure volume estimates and top-down implant shipment data were triangulated across the analysis window.
Historical implant adoption curves were cross-referenced against forward-looking surgeon panel inputs to model segment trajectories. The forecast framework disaggregated volume across material composition tiers, application settings, and end-user channels, with pediatric versus adult correction splits and regional regulatory cluster variations as additional dimensions. CAGRs were derived from installed base replacement cycles and ambulatory procedure migration rates, incorporating titanium alloy platform conversion assumptions and external bracing system competitive displacement factors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under PMDA regulatory timeline extensions or titanium sponge supply disruptions. Projections reflect assumptions regarding reimbursement stability for minimally invasive chest wall reconstruction and fellowship program expansion rates for specialized thoracic surgeons. Material deviation in FDA evidentiary requirements or EU MDR post-market surveillance enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Medical Display Monitors Market
Medical Devices
Pelvic Electro-Stimulators Market
Medical Devices
Implantable Defibrillators Market
Medical Devices
Rigid Laparoscope Market
Medical Devices
Dermal Allograft Market
Medical Devices
Argentina Respiratory Devices Market
Medical Devices
Italy Drug Delivery Devices Market
Medical Devices
Global Tracheal Tube and Airway Products Market
Medical Devices
Intracranial Stents Total Addressable Market
Medical Devices
Lacrimal Devices Market
Medical Devices
Mediastinoscope Market
Medical Devices
Kirschner Wires Market
Medical Devices
Ligament Augmentation Market
Medical Devices
Specimen Retrieval Nets Market
Medical Devices
North America IVD Regulatory Affairs Outsourcing Market
Medical Devices
Capnography Devices Market