
 High Flow Oxygen Therapy Devices Market | 2026-2036
High Flow Oxygen Therapy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
High Flow Oxygen Therapy Devices Market Foresight
Hospital procurement for high flow oxygen therapy devices is shifting toward home care and long-term care centers as payors push for reduced readmission costs. Fisher & Paykel Healthcare leverages its integrated humidification platforms to dominate the consumables-recurring revenue model. ResMed competes through its sleep-disordered breathing expertise that extends into respiratory insufficiency applications. Koninklijke Philips anchors the European installed base with wall-mounted systems designed for ICU-to-ward transitions.
High flow oxygen therapy devices deliver heated, humidified oxygen at flow rates exceeding 40 liters per minute through nasal cannulas, maintaining precise fractional inspired oxygen concentration while generating positive airway pressure. Bench-top systems occupy the highest margin tier due to their embedded sensor arrays and software-driven titration capabilities, whereas portable units represent the fastest-growing configuration as ambulatory and emergency services expand their fleet investments. Membrane separation technology leads the installed base, though electrolytic systems are gaining share in home care settings where noise reduction and energy efficiency command premium positioning.
The FDA's 510(k) pathway for respiratory devices shapes product development timelines, while ISO 80601-2-90 standards govern physical specifications for high flow nasal cannula equipment. The EU MDR recertification requirements are forcing manufacturers to rebuild clinical evidence portfolios, particularly for devices with software-controlled flow algorithms. Stakeholders must monitor how CMS reimbursement coding for home-based high flow therapy evolves, as coverage determinations will dictate whether the home care segment sustains its current trajectory or retreats toward institutional settings.
Market Dynamics
Hospital procurement departments are consolidating vendor relationships around single-source humidification platforms that bundle capital equipment with recurring consumables, compressing pricing power for standalone device manufacturers and favoring integrated system suppliers.
Growth Catalysts
- CMS reimbursement expansion:The US Centers for Medicare & Medicaid Services is evaluating dedicated billing codes for home-based high flow oxygen therapy, which would eliminate prior authorization barriers for ambulatory patients.
- Electrolytic oxygen generation:Noise-reduced, energy-efficient membrane alternatives are capturing share in residential installations where 24-hour operation is standard.
- India's PLI scheme for medical devices:Domestic manufacturing incentives are attracting component suppliers to establish regional hub operations for nasal cannula and humidifier chamber production.
Market Restraints
- Polymer supply concentration:Medical-grade silicone for nasal cannula tips sources predominantly from German and Japanese specialty chemical producers, creating input vulnerability.
- EU MDR recertification burden:The Medical Device Regulation's clinical evidence requirements are extending software-controlled flow algorithm approvals by 18-24 months.
- Stationary concentrator substitution:Low-flow oxygen systems with pulse-dose delivery satisfy mild hypoxemia cases at one-third the equipment cost.
Strategic Opportunities
- Brazil's ANVISA fast-track pathway:The regulator's priority review for respiratory devices addressing COPD burden opens accelerated market access for bench-top systems with embedded titration software.
- Emergency medical services fleet conversion:Ambulance operators are replacing oxygen cylinder inventories with portable high flow units that reduce refill logistics and extend on-scene treatment duration.
- Remote patient monitoring convergence:Integration of SpO2 telemetry with home-based high flow systems enables hospital-at-home programs to discharge ICU step-down patients earlier.
Industry Challenges
- ISO 80601-2-90 testing capacity:Limited accredited laboratories for high flow nasal cannula equipment verification are creating certification bottlenecks for new market entrants.
- Biomedical engineering talent scarcity:Hospitals lack specialists trained on heated humidifier maintenance, forcing manufacturers to absorb field service costs or extend warranty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Flow Oxygen Therapy Devices Market |
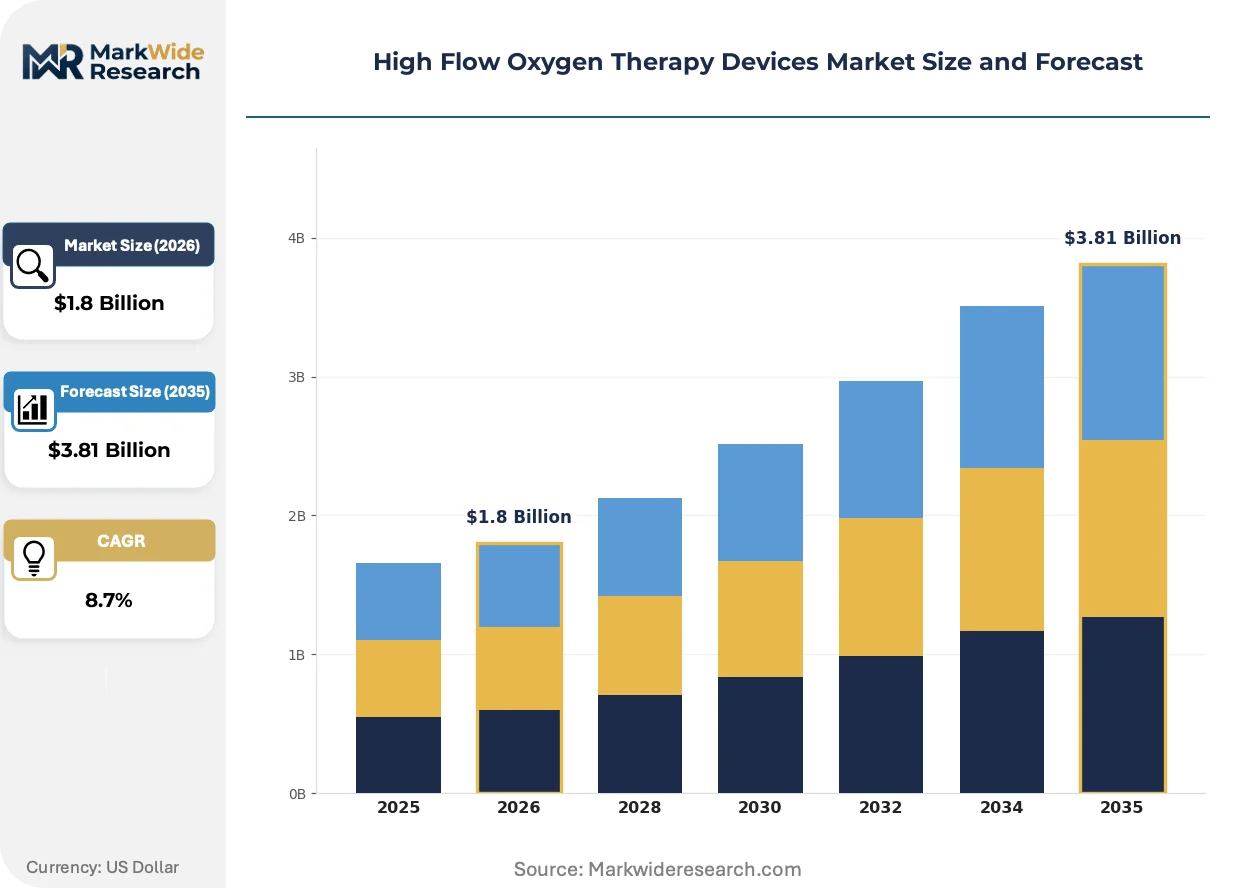
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bench-top, Portable, Wall-mounted, Hand-held Technology: Electrolytic, Membrane Separation, Cryogenic, Thermal End User: Home Care, Hospitals, Long-term Care Centers, Emergency Services Application: Respiratory Distress, Postoperative Care, Chronic Conditions, Preoperative Care |
| Companies Covered | Fisher & Paykel Healthcare, Koninklijke Philips, ResMed, Drägerwerk AG & Co. KGaA, Teleflex, Vapotherm, Hamilton Medical, Vyaire Medical, Smiths Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Flow Oxygen Therapy Devices Market Shifts & Advancements
Software-defined oxygen delivery is transforming device architecture, with sensor arrays and algorithmic titration replacing mechanical flow controls. This shift compresses hardware differentiation while elevating data platform competition.
Membrane-based oxygen separation is overtaking pressure-swing adsorption in portable device configurations. The technology extracts oxygen from ambient air through selective polymer permeability, eliminating compressor noise and vibration. Emergency medical services operators in Australia and the United Kingdom are standardizing fleet purchases around these units. The structural consequence is compressing maintenance revenue streams, as membrane systems require no sieve bed replacements.
The EU MDR's software classification rules are redefining regulatory boundaries for flow-control algorithms. Devices with closed-loop titration based on SpO2 feedback now face Class IIb certification requirements, elevating clinical evidence burdens. Manufacturers with legacy products lacking algorithm transparency documentation are rebuilding technical files. German notified bodies are processing these submissions at 40% of pre-MDR throughput, delaying product updates.
Hospital procurement teams are unbundling capital equipment from consumables contracts, reversing decade-long bundling strategies. Standalone device vendors gain access to accounts previously locked by integrated system suppliers. The shift is most visible in US academic medical centers where value analysis committees now separate humidifier chamber sourcing from flow generator selection. This fragmentation elevates price transparency but compresses vendor switching costs.
High Flow Oxygen Therapy Devices Market Segmentation
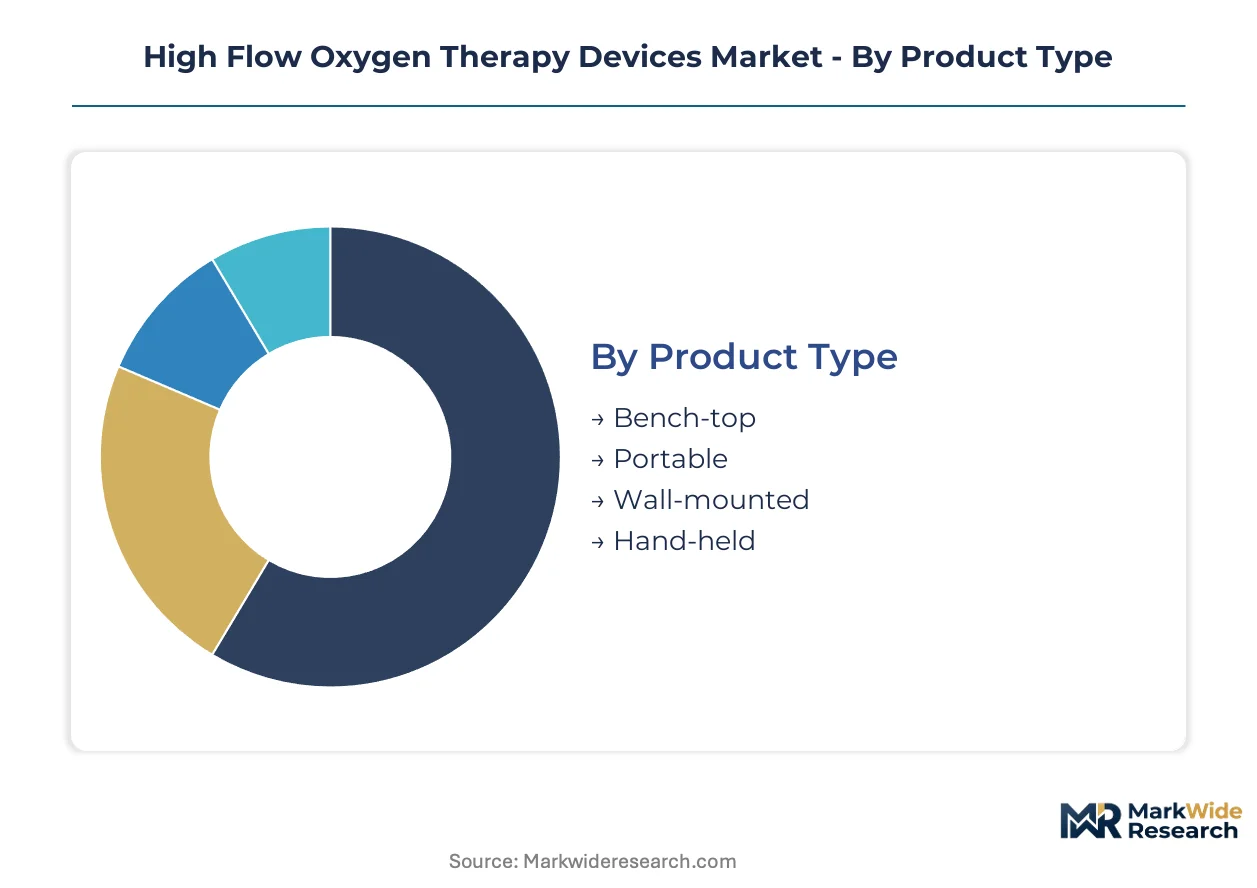
Device configuration and oxygen generation technology determine reimbursement eligibility, maintenance economics, and patient mobility profiles across the high flow oxygen therapy landscape. Procurement teams segment purchasing decisions by clinical setting acuity and ambulatory requirements rather than hardware specifications alone.
Product Type:
Customization intensity spans from fixed-installation ICU systems to battery-powered emergency units, with standardization rising as patient mobility increases.
- Bench-top:These stationary units integrate heated humidification chambers with precision flow controls and embedded sensor arrays for algorithmic oxygen titration. Demand concentrates in US academic medical centers where value analysis committees separate capital equipment from consumables procurement, favoring standalone devices with software-defined delivery capabilities.
- Portable:Battery-operated configurations weighing under 10 kilograms enable ambulance fleet conversion and hospital-at-home discharge programs. Emergency services operators in Australia and the United Kingdom are standardizing purchases around membrane-based units that eliminate compressor maintenance and extend on-scene treatment duration.
- Wall-mounted:Fixed-installation systems designed for ICU-to-ward transitions dominate European hospital infrastructure with integrated medical gas pipeline connections.
- Hand-held:Ultra-compact units serve prehospital emergency responders requiring single-operator deployment in confined spaces.
Leading the category by volume: Bench-top systems anchor hospital installed bases. Expanding most quickly: Portable units as home care and emergency services accelerate fleet investments.
Technology:
Cost tier separation is pronounced, with premium membrane systems commanding three to five times the equipment cost of thermal alternatives while delivering superior noise reduction and energy efficiency.
- Electrolytic:Water electrolysis generates oxygen through proton exchange membrane stacks, achieving near-silent operation critical for residential 24-hour use. Home care adoption in Germany and Japan is climbing fastest where energy efficiency premiums offset higher capital expenditure.
- Membrane Separation:Selective polymer permeability extracts oxygen from ambient air without mechanical compression, eliminating sieve bed replacements and compressing manufacturer maintenance revenue. The technology is displacing pressure-swing adsorption in portable configurations across Australian and UK emergency medical services.
- Cryogenic:Liquid oxygen storage systems serve high-volume institutional settings with centralized distribution infrastructure.
- Thermal:Zeolite-based pressure-swing adsorption dominates entry-level stationary concentrators where mild hypoxemia cases tolerate pulse-dose delivery.
Installed base leadership: Membrane separation. Steepest expansion trajectory: Electrolytic systems in residential settings.
End User:
Application maturity varies sharply, with hospital protocols standardized for decades while home care reimbursement pathways remain under CMS evaluation.
- Home Care:Patients with chronic respiratory insufficiency seek alternatives to prolonged hospitalization, driving demand for noise-reduced, energy-efficient systems. CMS dedicated billing code development would eliminate prior authorization barriers and sustain segment momentum.
- Hospitals:ICU and step-down wards maintain the highest device utilization rates with integrated humidification platforms bundling capital equipment and recurring consumables.
- Long-term Care Centers:Skilled nursing facilities represent emerging demand as payors push readmission cost reduction.
- Emergency Services:Ambulance operators are replacing oxygen cylinder inventories with portable high flow units to reduce refill logistics.
Revenue concentration: Hospitals. Gaining share fastest: Home care pending reimbursement clarity.
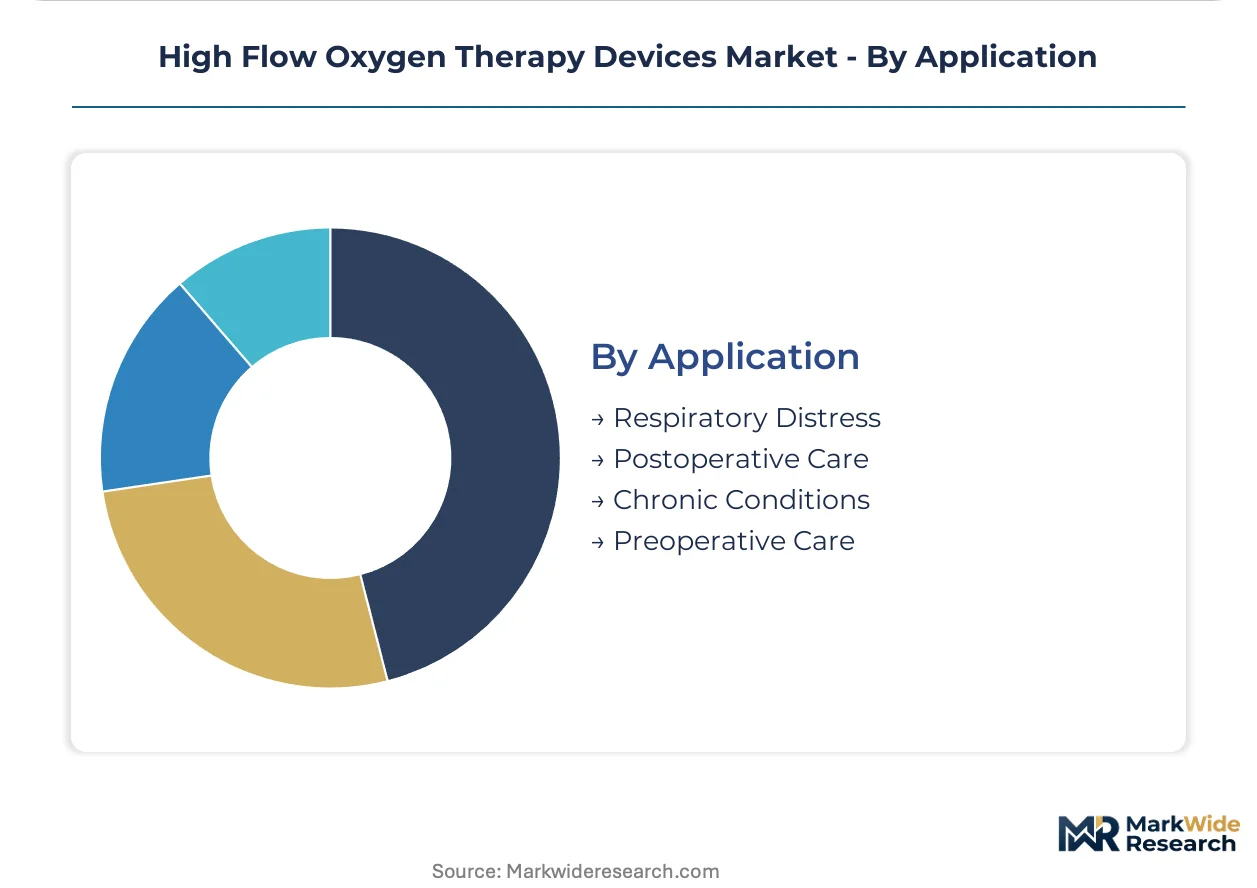
Application:
Customer type stratification separates acute episodic treatment from chronic disease management, with pricing power strongest in preoperative optimization protocols.
- Respiratory Distress:Acute hypoxemic failure requiring immediate high flow intervention represents the foundational use case with established clinical evidence and protocol standardization.
- Postoperative Care:Surgical recovery units deploy high flow therapy to reduce reintubation rates and accelerate ICU step-down, with SpO2 telemetry integration enabling earlier discharge.
- Chronic Conditions:COPD and interstitial lung disease patients require long-term home-based therapy where electrolytic noise reduction commands premium positioning.
- Preoperative Care:Optimization of at-risk surgical candidates represents the fastest-growing protocol application with documented length-of-stay reduction.
Protocol maturity leadership: Respiratory distress. Climbing fastest: Preoperative optimization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's medical device production-linked incentive zones are drawing component suppliers to establish nasal cannula and humidifier chamber manufacturing clusters near Hyderabad and Bengaluru. This tax-advantaged concentration is reshaping supply geography for high flow oxygen therapy devices.
United States
Aging demographics and chronic respiratory disease prevalence sustain device utilization across academic medical centers and home care programs. The FDA's 510(k) pathway for respiratory devices shapes product development timelines and clearance cycles. Value analysis committees in Boston and New York now separate humidifier chamber sourcing from flow generator selection.
Germany
Energy efficiency premiums in residential settings accelerate electrolytic system adoption for 24-hour home care operation. The EU MDR recertification requirements are forcing manufacturers to rebuild clinical evidence portfolios for software-controlled flow algorithms. German notified bodies in Munich and Tübingen process submissions at reduced throughput, delaying product updates.
Japan
Home care adoption climbs fastest where noise reduction commands premium positioning for residential 24-hour therapy. METI standards govern medical device quality management systems and post-market surveillance obligations. Osaka-based distributors are expanding service networks to support membrane-based portable unit maintenance.
Brazil
ANVISA's fast-track pathway for respiratory devices addressing COPD burden opens accelerated market access for bench-top systems. The regulator's priority review process compresses approval timelines for embedded titration software configurations. São Paulo hospital networks are piloting ICU-to-ward transition protocols using wall-mounted installations.
Australia
Emergency medical services operators are standardizing fleet purchases around membrane-based portable units that eliminate compressor maintenance. The TGA's medical device framework aligns with international standards while maintaining sovereign approval requirements. Melbourne and Sydney ambulance authorities are replacing oxygen cylinder inventories with high flow units to reduce refill logistics.
High Flow Oxygen Therapy Devices Market Competitive Landscape
Top-tier vendors anchor integrated humidification platforms, while mid-tier specialists compete on standalone flow generation and consumables innovation. The market structure favors suppliers bundling capital equipment with recurring revenue streams. Three archetypes dominate: diversified respiratory conglomerates with sleep-disordered breathing expertise, pure-play high flow device manufacturers, and emergency medical services fleet suppliers. Consolidation pressure is accelerating through vendor relationship consolidation and single-source procurement mandates.
Among diversified healthcare technology groups, Fisher & Paykel Healthcare, Koninklijke Philips, and ResMed occupy positions exemplifying distinct strategic vectors. Fisher & Paykel Healthcare represents the integrated platform archetype with consumables-recurring revenue dominance. Koninklijke Philips anchors European installed base penetration through ICU-to-ward transition systems. ResMed exemplifies sleep-disordered breathing expertise extension into respiratory insufficiency applications.
| Leading Market Players |
|---|
| Fisher & Paykel Healthcare |
| Koninklijke Philips |
| ResMed |
| Drägerwerk AG & Co. KGaA |
| Teleflex |
| Vapotherm |
| Hamilton Medical |
| Vyaire Medical |
| Smiths Medical |
| Others |
Supply & Pricing Matrix
US academic medical centers concentrate procurement authority through value analysis committees that unbundle humidifier chambers from flow generators, forcing standalone device vendors toward transparent spot pricing rather than bundled subscription models. This buyer consolidation reshapes how manufacturers structure equipment versus consumables contracts across hospital networks.
Pricing Analysis
Short lead-time premiums command fifteen to twenty percent markups over standard delivery schedules as hospital procurement teams face ICU capacity constraints. Three-tier pricing structure across premium bench-top systems, standard wall-mounted installations, and economy portable configurations stratifies by embedded sensor density and algorithmic titration capability. Cost compression in the portable tier is intensifying because membrane-based oxygen generation eliminates recurring sieve bed replacement revenue. Emergency medical services operators exhibit the highest price sensitivity due to fleet-scale purchasing volume, while German home care patients accept premium positioning for noise-reduced electrolytic systems.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific component hubs to North American assembly plants is compressing margins on portable device configurations where weight minimization conflicts with protective packaging requirements. Medical-grade silicone for nasal cannula tips draws from German and Japanese specialty chemical producers, while polymer membrane sheets for oxygen separation anchor in South Korean and US manufacturing facilities. Single-source vulnerability concentrates in proton exchange membrane stacks for electrolytic systems, where two suppliers control residential-grade production capacity. Distribution runs through hospital GPO contracts, emergency services fleet operators, and durable medical equipment dealers serving home care patients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as manufacturers pursue captive supply of humidification chambers and nasal cannula consumables to lock recurring revenue streams against unbundling procurement trends.
For Market Incumbents: Acquire membrane polymer production capabilities to secure cost advantages in portable device configurations and defend against pressure-swing adsorption substitution. Backward integration into medical-grade silicone compounding reduces exposure to German and Japanese supply concentration. Hospital GPO contract consolidation represents the primary threat to standalone device vendors lacking consumables attachment.
For New Entrants and Emerging Players: Skilled nursing facilities represent an underserved buyer archetype with minimal incumbent penetration and reimbursement clarity emerging ahead of home care coding finalization. Brazil's ANVISA fast-track pathway offers the most penetrable regulatory entry point for bench-top systems with embedded titration software. Direct contracting with ambulance fleet operators bypasses hospital GPO lock-in.
For Investors and Strategic Acquirers: The window for entry favors pure-play high flow device manufacturers with FDA 510(k) clearances and established hospital installed bases ahead of EU MDR recertification bottlenecks. Long-term viability hinges on software-defined oxygen delivery platforms that elevate data competition over hardware commoditization. CMS dedicated billing code publication serves as the critical inflection indicator for home care segment sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Acceleration | Shortens clearance timelines for algorithmic titration devices competing in US academic medical centers. |
| EU MDR Recertification Investment | Rebuilds clinical evidence portfolios for software-controlled flow algorithms before German notified body bottlenecks worsen. |
| Hospital System Partnership | Secures GPO contract access through integrated humidification platform bundling capital equipment with consumables. |
| Software Companion Development | Enables SpO2 telemetry integration for hospital-at-home programs discharging ICU step-down patients earlier. |
| Reimbursement Strategy | Positions for CMS dedicated billing code adoption that would eliminate prior authorization barriers for ambulatory patients. |
Research Methodology
Multi-period observation of FDA 510(k) clearance volumes, CMS reimbursement coding developments, and EU MDR submission throughput anchored the trend analysis, supplemented by interviews with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and emergency services fleet procurement officers. Secondary validation drew from FDA device classification databases, CMS Medicare claims data, German notified body processing statistics, and hospital procurement database extracts. Bottom-up patient population modeling triangulated against top-down manufacturer revenue segmentation.
Input-output matrices connected oxygen generation technology adoption rates to end-user setting expansion across the projection horizon, with segmentation dimensions spanning device configuration, technology type, end-user facility, and clinical application. CAGRs derived from logistic diffusion curves fitted to historical technology substitution patterns and reimbursement policy scenario weights. Industry-specific forecast inputs incorporated ISO 80601-2-90 certification pipeline status and India's PLI scheme participant commitments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CMS reimbursement determinations, EU MDR recertification delays, and polymer supply chain reconfigurations. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Electroceuticals Market
Medical Devices
Vagal Nerve Stimulation (VNS) Market
Medical Devices
Global Coagulation-Hemostasis Analyzer Market
Medical Devices
Global Acetabular Prostheses Market
Medical Devices
North America Invisible Orthodontics Market
Medical Devices
China Respiratory Devices Market
Medical Devices
Global Assistive Listening Device Market
Medical Devices
Global Medical Laser Systems Market
Medical Devices
Abdominal Closure Systems Market
Medical Devices
Portable Medical Electronic Products Market
Medical Devices
Global Stroke Assistive Devices Market
Medical Devices
Global Bone Tumor Ablation Devices Market
Medical Devices
United States Implantable Medical Devices Market
Medical Devices
Brazil Medical Devices Market
Medical Devices
Disabled and Elderly Assistive Technologies Market
Medical Devices
Below-The-Knee Implants Market