
 Decoy Flares Market | 2026-2036
Decoy Flares Market Size, Share, and Industry Trends Forecast 2026-2036
Decoy Flares Market Analysis
Defense procurement channels is reconfiguring as governments consolidate supplier bases under long-term framework agreements. Chemring Group leverages its integrated pyrotechnics supply chain to sustain cost advantages across NATO orders. Rheinmetall AG anchors German and broader European military demand through its domestic production footprint. Elbit Systems competes aggressively in Middle Eastern markets with customized countermeasure suites.
Decoy flares are pyrotechnic countermeasure devices composed of magnesium, Teflon, and Viton formulations that generate intense infrared signatures to divert heat-seeking missiles from aircraft. These devices typically burn at temperatures exceeding 2000 degrees Celsius and deploy via cartridge-based dispensers integrated into fixed-wing and rotary platforms. Infrared decoy flares dominate procurement volumes given the persistent threat profile of shoulder-launched and air-to-air missiles, while multi-spectral variants capture expanding margin pools as threats evolve toward dual-band seekers. Ground-launched deployment methods represent a mature segment with stable replacement cycles, whereas airborne applications drive growth through platform modernization programs across Western and allied air forces.
FAA regulations govern commercial aviation countermeasure certifications in the United States, while EASA enforces parallel airworthiness standards across European jurisdictions, and ISO frameworks address pyrotechnic safety in transport and storage. These regulatory layers shape product development timelines, testing expenditures, and market access conditions for both established suppliers and new entrants. Stakeholders must monitor evolving missile threat signatures and corresponding certification requirements to align R&D portfolios with operational demand.
Market Dynamics
Defense procurement consolidation under multi-year framework agreements is compressing supplier margins while elevating technical qualification barriers for pyrotechnic countermeasure providers.
Growth Catalysts
- NATO Airborne Survivability Programs:Alliance members are standardizing infrared countermeasure suites across rotary and fixed-wing fleets, creating pooled procurement volumes that favor qualified suppliers.
- FAA Certification Pathways:The administration's streamlined airworthiness protocols for commercial aircraft defense systems are accelerating civil aviation adoption of protective countermeasures.
- Magnesium-Teflon-Viton Formulation Advances:Next-generation pyrotechnic compositions are extending burn durations and spectral coverage, matching evolved missile seeker signatures.
Market Restraints
- Raw Material Concentration:Specialty magnesium and fluoropolymer supply chains concentrate in Chinese processing facilities, exposing Western manufacturers to export control volatility.
- Long-Lead Testing Cycles:EASA and FAA qualification protocols for new flare formulations impose 18-36 month certification timelines that freeze R&D returns.
- Laser-Based Directed Infrared Countermeasures:Solid-state laser systems for aircraft protection are capturing platform integration slots previously reserved for expendable decoys.
Strategic Opportunities
- Multi-Spectral Flare Development:Dual-band and tri-spectral decoys addressing ultraviolet-through-infrared seekers command premium positioning as threat signatures diversify.
- Ground-Based Vehicle Protection:Rotary-wing decoy dispensers are adapting to armored vehicle turret mounts, opening land force procurement channels.
- ISO Pyrotechnic Transport Harmonization:Standardized global safety frameworks for flare storage and shipment are reducing cross-border distribution friction.
Industry Challenges
- Skilled Pyrotechnic Workforce Scarcity:Experienced formulators and safety engineers with military-specification expertise are retiring faster than training pipelines replenish.
- Legacy Platform Integration Complexity:Retrofitting cartridge dispensers onto aging aircraft architectures requires custom mechanical and electrical interface engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decoy Flares Market |
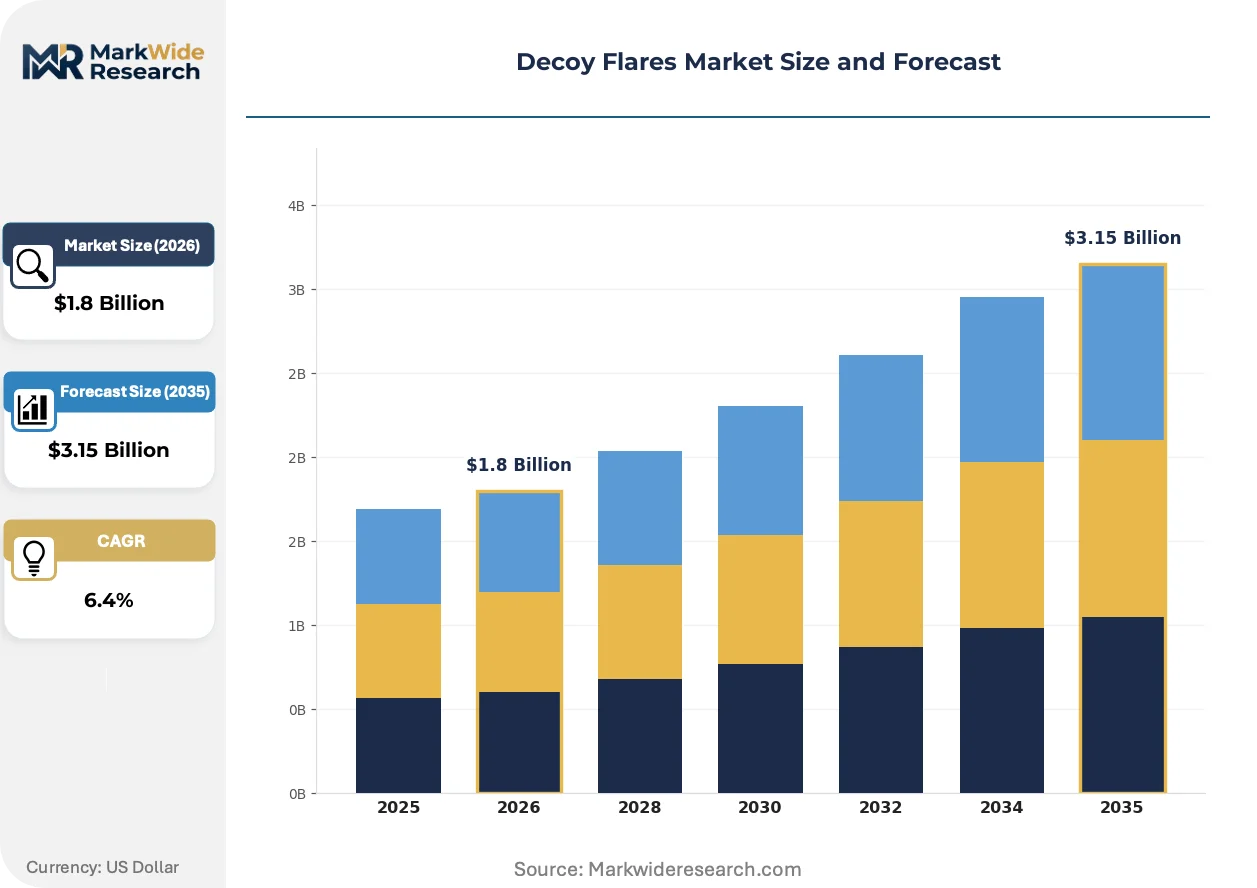
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Infrared, Acoustic, Visual, Multi-spectral Deployment Method: Ground-launched, Airborne, Naval, Other End User: Military, Homeland Security, Commercial Aviation, Private Sector Form Factor: Disposable, Reusable, Tactical, Strategic |
| Companies Covered | Chemring Group, Rheinmetall AG, Lacroix Defense, Elbit Systems, Leonardo S.p.A., MBDA, Armtec Defense Technologies, IMI Systems, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decoy Flares Market Emerging Trajectories
Digital manufacturing and spectral engineering are converging to reshape how decoy flares are formulated, tested, and fielded across military and emerging civil applications.
Advanced computational materials modeling is digitizing the traditional empirical development cycle for pyrotechnic compositions. Defense laboratories and prime contractors are adopting physics-based simulation platforms to predict burn characteristics and spectral output before physical prototyping. This shift is compressing formulation iteration cycles from years to months while reducing hazardous test quantities.
EASA's evolving airworthiness standards for civil aircraft countermeasures are mandating enhanced environmental safety profiles for flare compositions. The regulation is forcing manufacturers to eliminate perchlorate oxidizers and heavy-metal catalysts from commercial-aviation products. European suppliers are responding by accelerating clean-burn formulation programs to maintain platform certification eligibility.
Consolidated national procurement offices are displacing fragmented base-level purchasing for countermeasure resupply. The United Kingdom's Defence Equipment and Support organization and similar centralized buying entities in France and Germany are negotiating multi-year framework agreements that bundle flare procurement with platform sustainment contracts. This concentration is visible across NATO European air forces and is compressing the viable supplier base to vertically integrated pyrotechnics specialists.
Decoy Flares Market Segmentation
Decoy flare procurement patterns diverge sharply across threat environments, platform architectures, and regulatory jurisdictions. Manufacturers must align formulation chemistry, dispenser mechanics, and certification pathways to specific segment requirements or forfeit platform integration slots.
Type:
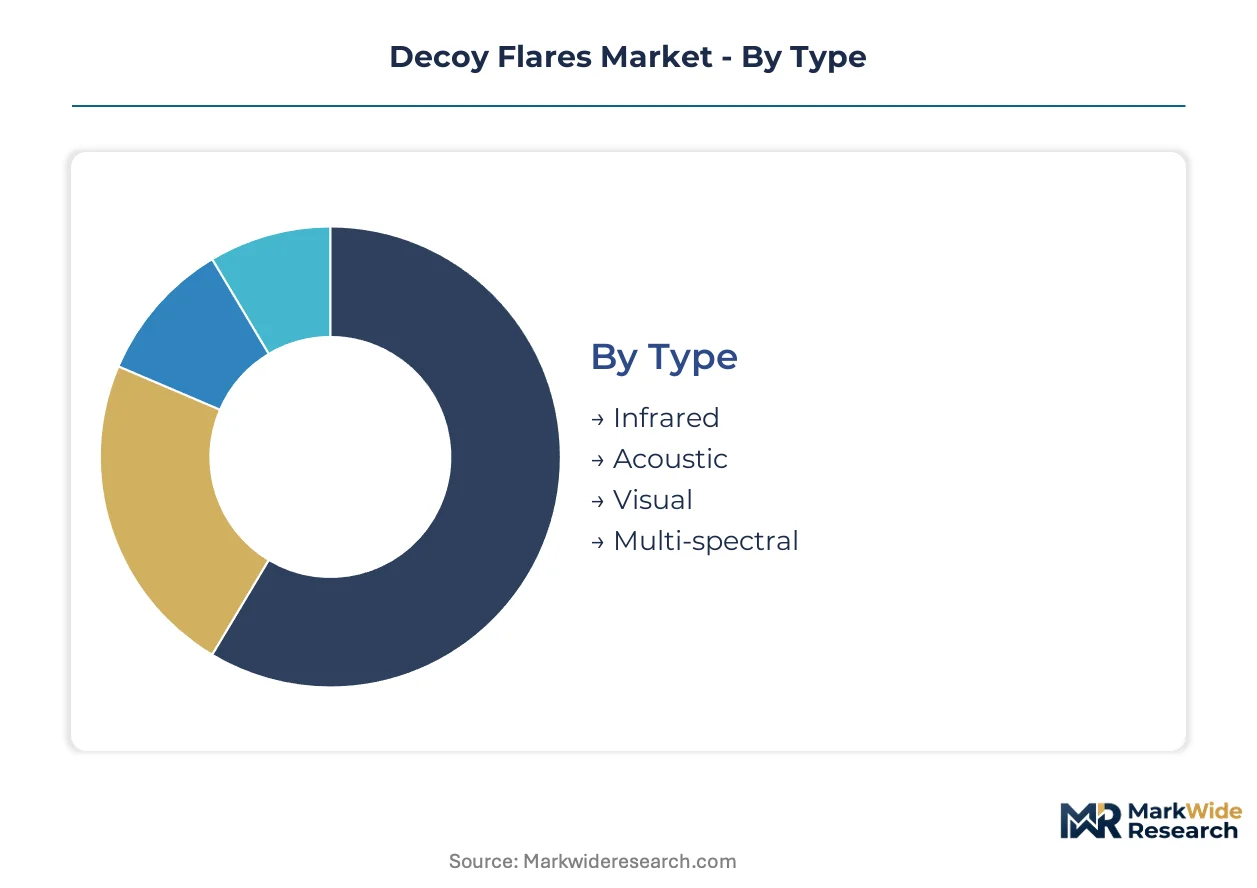
Use-case spectrum spans single-spectrum expendables for legacy rotary platforms through adaptive multi-spectral payloads addressing next-generation dual-band seekers.
- Infrared:Magnesium-Teflon-Viton compositions burn above 2000°C to simulate aircraft engine signatures. NATO rotary-wing fleets sustain procurement volumes as shoulder-launched threats persist in Eastern European theaters.
- Multi-spectral:Dual-band and tri-spectral variants combine ultraviolet-through-infrared emissions to defeat advanced imaging seekers. Premium positioning reflects R&D intensity and evolving threat diversification in Middle Eastern procurement.
- Acoustic:Underwater decoy systems generate false sonar returns for submarine and surface vessel protection. Naval applications concentrate in Pacific Rim defense modernization programs.
- Visual:Smoke and pyrotechnic obscurants disrupt electro-optical targeting for ground force protection. Demand clusters in armored vehicle turret integration programs.
Established volume favors Infrared; emerging adoption favors Multi-spectral.
Deployment Method:
Platform integration constraints dictate dispenser architecture, with airborne systems commanding the steepest expansion trajectory through fighter and transport modernization cycles.
- Airborne:Cartridge-based dispensers integrate into fixed-wing pylons and rotary fuselage stations. FAA and EASA airworthiness certifications govern civil aviation applications, while military variants follow MIL-STD-810 environmental testing protocols.
- Ground-launched:Vehicle-mounted launchers protect armored columns and forward operating bases. Replacement cycles follow ammunition resupply patterns rather than platform procurement timelines.
- Naval:Shipboard chaff and flare systems deploy from deck-mounted launchers against anti-ship missile threats. Integration complexity rises with vertical launch system compatibility requirements.
- Other:Man-portable dispensers and fixed-site protection systems address specialized force protection scenarios. Procurement fragments across special operations and critical infrastructure budgets.
Platform modernization drives Airborne; operational tempo sustains Ground-launched.
End User:
Budget authority concentration shapes contract structures, with military procurement offices consolidating multi-year framework agreements that compress supplier margins.
- Military:Defense ministries account for dominant procurement volumes across NATO and allied air forces. Chemring Group and Rheinmetall AG anchor European supply through integrated pyrotechnics capabilities.
- Commercial Aviation:Cargo operators and high-risk route carriers adopt protective countermeasures under FAA streamlined certification pathways. Environmental safety mandates eliminate perchlorate oxidizers from civil-aviation formulations.
- Homeland Security:Border patrol and maritime interdiction agencies deploy man-portable systems for low-intensity threat environments. Procurement scales remain constrained by domestic security budget allocations.
- Private Sector:Executive protection and critical infrastructure operators represent niche demand with limited standardization. Custom engineering requirements elevate unit costs relative to military procurement.
Contract consolidation favors Military; regulatory acceleration favors Commercial Aviation.
Form Factor:
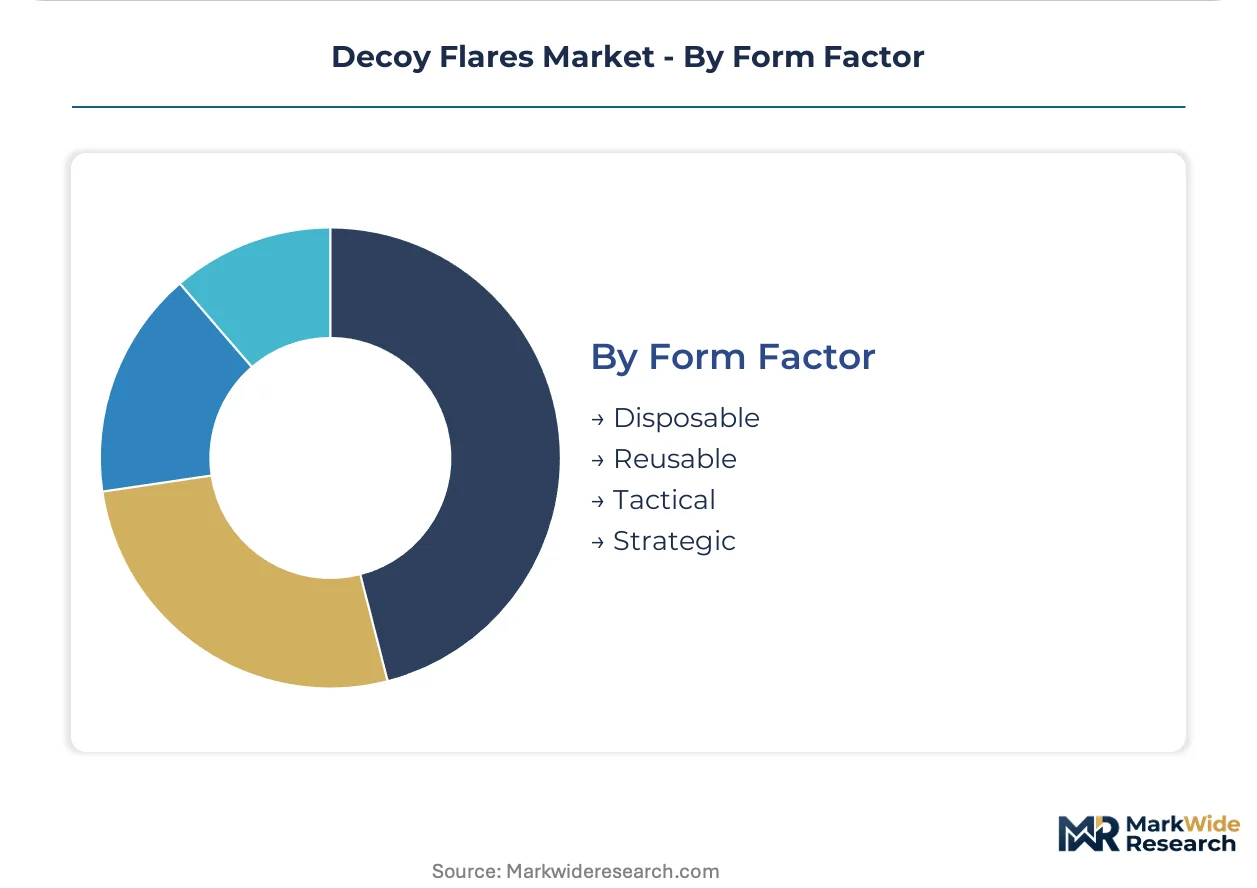
Lifecycle economics and mission profiles determine reusability trade-offs, with disposable architectures dominating high-threat saturation scenarios.
- Disposable:Single-use cartridges maximize payload density and minimize logistics burden. Rotary-wing platforms in contested airspace generate replacement demand through high expenditure rates.
- Tactical:Compact form factors prioritize rapid deployment and platform compatibility over burn duration. Special operations and unmanned aerial vehicle applications drive specification requirements.
- Strategic:Extended-burn payloads protect high-value assets through prolonged threat engagements. Heavy transport and tanker platforms integrate these systems against standoff missile threats.
- Reusable:Refillable dispenser magazines reduce per-mission logistics costs for training and low-threat operations. Adoption remains limited by mechanical complexity and maintenance overhead.
Operational intensity favors Disposable; cost optimization favors Reusable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA certification protocols in the United States anchor the regulatory framework governing commercial aviation countermeasures, while EASA standards in Europe and parallel agencies across allied nations create a multi-jurisdictional compliance landscape for decoy flare manufacturers.
United States
Defense modernization budgets prioritize airborne survivability systems across Air Force and Navy rotary-wing fleets. FAA streamlined airworthiness protocols accelerate civil aviation adoption of protective countermeasures for cargo operators. Industrial concentration clusters in Arizona and Florida around major aerospace primes and pyrotechnics specialists.
Germany
Rheinmetall AG anchors European military demand through domestic production footprint serving Bundeswehr and NATO allied forces. EASA environmental safety mandates eliminate perchlorate oxidizers from commercial-aviation formulations, forcing reformulation investments. Manufacturing gravity centers in Lower Saxony and Bavaria where integrated pyrotechnics capabilities sustain framework agreement competitiveness.
United Kingdom
Defence Equipment and Support organization consolidates multi-year framework agreements bundling flare procurement with platform sustainment contracts. REACH chemical regulations shape pyrotechnic composition standards for transport and storage safety. Chemring Group leverages integrated supply chain from its Fareham headquarters to sustain cost advantages across NATO orders.
Israel
Elbit Systems competes aggressively in Middle Eastern markets with customized countermeasure suites addressing regional threat signatures. National security doctrine emphasizes indigenous defense industrial base for airborne protection systems. R&D concentration in Haifa and Beersheba drives spectral engineering advances for multi-spectral decoy development.
Japan
Ministry of Defense procurement prioritizes interoperability with US-Japan alliance countermeasure standards for rotary and fixed-wing platforms. METI industrial policy supports domestic pyrotechnics capabilities through designated defense production base status. Manufacturing clusters in Aichi and Kanagawa prefectures integrate with regional aerospace supply chains.
Decoy Flares Market Vendor Landscape
Vertically integrated defense primes and specialized pyrotechnics houses split the market between framework agreement anchoring and technology differentiation. Supplier margins compress under consolidated national procurement offices displacing fragmented base-level purchasing. Three archetypes dominate: integrated aerospace conglomerates with captive countermeasure divisions, standalone pyrotechnics specialists with NATO qualification heritage, and regional system integrators serving non-aligned defense markets. Competitive moves concentrate on multi-year framework agreement capture and spectral formulation patent positioning.
Among European-anchored suppliers, Chemring Group and Rheinmetall AG exemplify the vertically integrated archetype with in-house pyrotechnics production sustaining NATO qualification advantages. Elbit Systems occupies a position within the regional specialist tier, representing Middle Eastern market adaptation capabilities. These three named entities anchor the competitive structure without exhausting the qualified supplier base.
| Leading Market Players |
|---|
| Chemring Group |
| Rheinmetall AG |
| Lacroix Defense |
| Elbit Systems |
| Leonardo S.p.A. |
| MBDA |
| Armtec Defense Technologies |
| IMI Systems |
| BAE Systems |
| Others |
Supply Flow & Price Mechanics
Chinese magnesium and fluoropolymer processing facilities concentrate upstream supply for Western flare manufacturers, anchoring margin pools in formulation chemistry and NATO qualification heritage rather than raw material sourcing. This concentration pattern forces pricing discipline downstream as procurement offices consolidate under multi-year framework agreements.
Pricing Analysis
Geographic price spreads widen between NATO framework contract rates and spot procurement in non-aligned defense markets, reflecting certification tier differentiation. Three-tier pricing structure across military-qualified, commercial-aviation certified, and uncertified industrial tiers segments buyer segments by compliance burden. Pricing pressure stems from consolidated national procurement offices bundling flare resupply with platform sustainment contracts. Military procurement offices exhibit lowest price sensitivity given mission-critical specifications, while private sector executive protection operators face highest cost compression.
Supply Chain Analysis
Tariff exposure between Chinese magnesium processors and Western formulation facilities dominates supply chain risk assessment for decoy flare manufacturers. Production gravity centers on Germany, the United Kingdom, and Israel for NATO-qualified suppliers, with Japan and South Korea anchoring Pacific Rim defense industrial bases. Specialty magnesium, Teflon fluoropolymers, and Viton binder formulations draw from concentrated chemical processing regions. Single-source vulnerability in Chinese rare earth and magnesium supply chains threatens formulation cost stability. Distribution runs through defense logistics channels and aerospace prime contractor integration programs rather than open commercial markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The decoy flares market exhibits cyclical recovery characteristics tied to NATO airborne survivability modernization waves and threat signature evolution in Eastern European theaters.
For Market Incumbents: Entrench qualification advantages through accelerated multi-spectral formulation R&D and backward integration into magnesium-Teflon-Viton raw material processing. Laser-based directed infrared countermeasures threaten expendable decoy platform slots; defend against substitution by deepening spectral engineering capabilities and securing long-term framework agreement renewals with Bundeswehr and UK Defence Equipment and Support. For New Entrants and Emerging Players: Commercial aviation cargo operators under FAA streamlined certification pathways represent the most penetrable entry point for non-traditional suppliers. Ground-based vehicle protection systems for armored turret mounts offer secondary white-space expansion. Target EASA environmental safety compliance as the go-to-market angle, eliminating perchlorate oxidizers to qualify for civil aviation procurement. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated pyrotechnics specialists with captive magnesium formulation capabilities and NATO qualification heritage. Long-term viability rests on spectral engineering patent positioning and multi-year framework agreement anchoring. Watch laser-based countermeasure platform integration rates as the critical inflection signal for expendable decoy demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Spectral Formulation Development | Dual-band decoy capabilities address evolving missile seeker signatures across Middle Eastern procurement. |
| Backward Integration into Raw Materials | Captive magnesium processing insulates Chemring Group and Rheinmetall AG from Chinese export control volatility. |
| EASA Environmental Compliance Program | Perchlorate-free formulations secure commercial aviation certification eligibility under evolving airworthiness standards. |
| Ground Vehicle Dispenser Adaptation | Rotary-wing countermeasure systems retrofit to armored turrets, opening Bundeswehr land force procurement channels. |
| Digital Manufacturing Implementation | Physics-based simulation platforms compress pyrotechnic development cycles from years to months for Elbit Systems. |
Methodological Framework
Initial hypotheses were tested against primary input from defense procurement officers, pyrotechnic safety engineers, aerospace platform integration specialists, and flare formulation chemists and refined through secondary validation. Defense ministry budget disclosures, FAA airworthiness certification databases, EASA regulatory filings, and NATO standardization agreements anchored quantitative triangulation. Bottom-up platform fleet analysis and top-down defense spending allocation models converged on segment sizing.
Demand-supply-balance framing governed the analytical framework across the projection horizon. Segmentation dimensions modeled include flare type spectrum, deployment method architecture, end-user budget authority, and form factor reusability tier. CAGRs derived from platform modernization cycle phasing and threat signature evolution patterns. Forecast inputs incorporated shoulder-launched missile proliferation indices and civil aviation route risk assessments.
Macroeconomic conditions sit as an overlay; deviation in defense budget allocation priorities or magnesium commodity pricing would shift the trajectory. Forecasts reflect documented assumptions about NATO procurement consolidation pace and laser countermeasure substitution rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
High Power Microwave Directed Energy Weapons Market
Weapons and Ammunition
Asia-Pacific Cruise Missile Market
Weapons and Ammunition
Man-Portable Anti-Armor Weapons Market
Weapons and Ammunition
Global Shoulder-Fired Weapons Market
Weapons and Ammunition
Next-Generation Assault Rifles Market
Weapons and Ammunition
Manned Anti-Tank Guided Missile System Market
Weapons and Ammunition
Weapons Carriage and Release System Market
Weapons and Ammunition
Large Caliber Ammunition Market
Weapons and Ammunition
Aircraft Weapons Market
Weapons and Ammunition
APAC Ballistic Missile Market
Weapons and Ammunition
Americas Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Sports Shotgun Market
Weapons and Ammunition
Global E Bomb Market
Weapons and Ammunition
US Small Caliber Ammunition Market
Weapons and Ammunition
NATO Ammunition Market
Weapons and Ammunition
Ballistic Composite Market