
 Programmable Ammunition Market | 2026-2036
Programmable Ammunition Market Size, Share, and Industry Trends Forecast 2026-2036
Programmable Ammunition Market Analysis
Modular warhead packaging is hardening as the dominant procurement format, with buyers favoring configurable fuse-and-guidance kits over fixed-configuration rounds. Rheinmetall leverages its integrated propulsion-and-guidance architecture to sustain long-term European defense contracts. Saab competes through specialized proximity-sensor modules that anchor Nordic and Baltic procurement pipelines.
Programmable ammunition comprises gun-launched projectiles incorporating electronic fusing, miniature guidance packages, and real-time trajectory adjustment capability, typically operating via pre-set detonation modes or in-flight reprogramming through induction coils or data links. These systems serve militaries seeking reduced collateral damage, higher single-round kill probability, and operational flexibility against moving or obscured targets. Guided Munitions and Tactical Missiles occupy the deepest margin pools due to software-intensive value chains and limited supplier bases for seeker electronics. Artillery Shells with GPS Guidance represent the fastest-expanding category as land forces retrofit existing 155mm inventories with precision kits rather than acquiring entirely new weapon systems.
The US Department of Defense, NATO's Standardization Office, and the EU's European Defence Agency collectively shape certification requirements for interoperability, export control, and electromagnetic compatibility in programmable rounds. REACH and RoHS frameworks in Europe restrict certain energetic materials and electronic component chemistries, forcing reformulation of fuse assemblies. Stakeholders must monitor how ITAR recalibrations and emerging autonomous-targeting policy debates reshape cross-border component flows and joint-development eligibility.
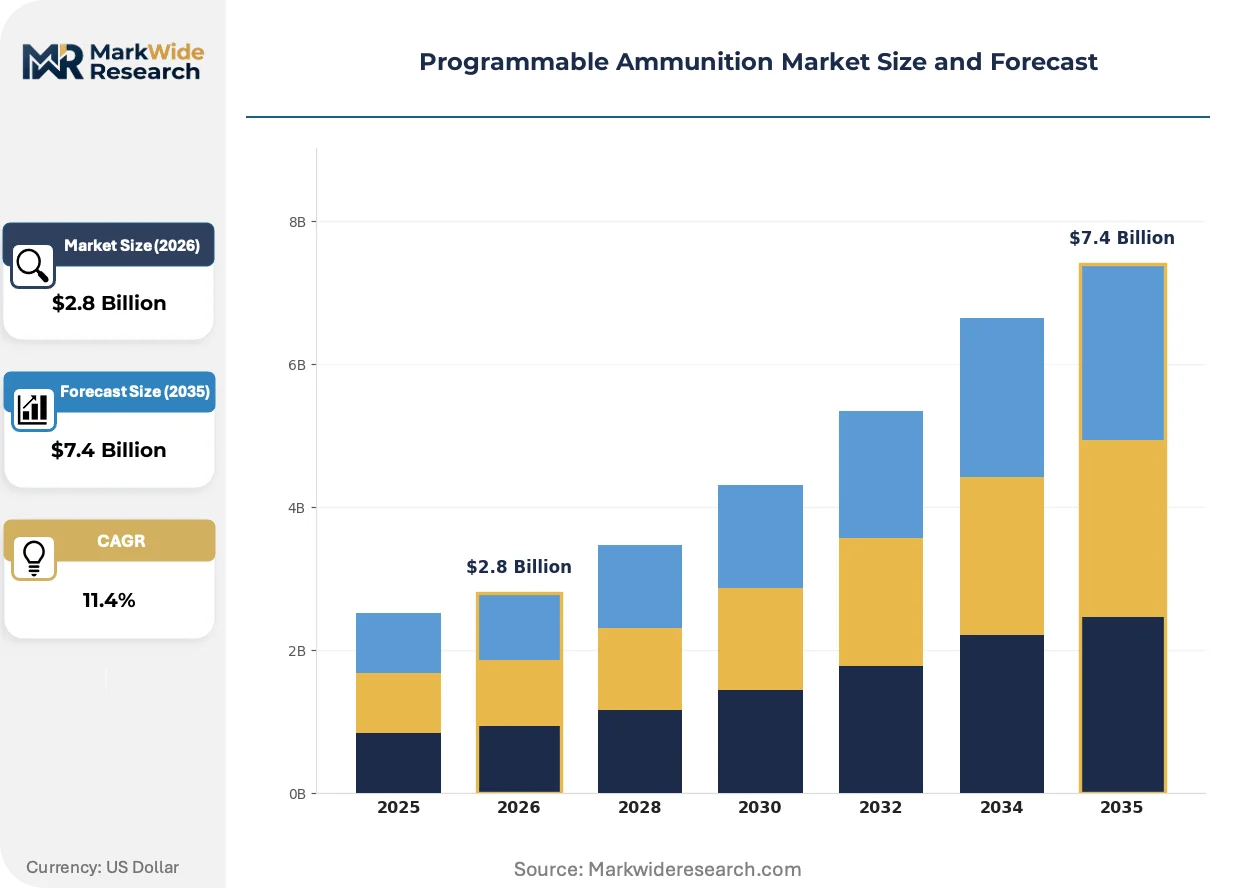
Market Dynamics
Defense procurement offices are consolidating fuse-and-guidance contracts under single-source frameworks, compressing supplier margins while elevating technical certification barriers for programmable ammunition systems.
Growth Catalysts
- Counter-battery modernization mandates:NATO allies are accelerating precision fires programs that require programmable fusing for rapid target engagement. Land forces in the Indo-Pacific theater drive demand for GPS-guided artillery retrofit kits.
- REACH and RoHS compliance deadlines:European energetic material restrictions are forcing fuse assembly reformulations that favor suppliers with advanced chemistry capabilities. This regulatory pressure is concentrating procurement among certified vendors.
- Induction coil programming:Wireless in-flight reprogramming technology is eliminating mechanical fuse-setting delays. Artillery units are adopting these systems for time-sensitive target scenarios.
Market Restraints
- Seeker electronics supply concentration:Miniature guidance component fabrication depends on a limited supplier base concentrated in East Asian semiconductor foundries. Disruption risks elevate procurement contingency costs.
- ITAR recalibration friction:US export control revisions are delaying cross-border joint development eligibility for programmable fuse architectures. European and Indo-Pacific partners face extended compliance timelines.
- Battery chemistry constraints:RoHS restrictions on cadmium and mercury compounds are forcing power source redesigns in miniature fuse assemblies. Alternative chemistries reduce shelf life and operational temperature ranges.
Strategic Opportunities
- Modular kit retrofit programs:Land forces in Poland, Australia, and Japan are prioritizing precision kit upgrades for existing 155mm inventories over new weapon system acquisitions. This creates aftermarket service contracts for guidance integration.
- AI-enabled target classification:Convergence of edge computing and millimeter-wave seekers is enabling autonomous proximity detonation against obscured targets. Development programs in Sweden and South Korea are advancing these capabilities.
- EU Defence Fund procurement pools:Collective European ammunition acquisition mechanisms are consolidating demand for interoperable programmable rounds. Standardized fusing specifications are creating volume opportunities for certified suppliers.
Industry Challenges
- Electromagnetic compatibility certification:Programmable rounds must demonstrate non-interference with platform fire control systems across multiple NATO member testing regimes. Validation cycles extend months beyond traditional ammunition qualification.
- Seeker integration talent scarcity:Defense contractors face recruitment gaps for engineers with combined expertise in RF electronics, energetic materials, and military environmental hardening. Compensation inflation is compressing program margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Programmable Ammunition Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Guided Munitions, Tactical Missiles, Artillery Shells, Smart Bombs Technology: Laser Guidance, GPS Guidance, Autonomous Targeting, Data Link End User: Military Forces, Law Enforcement, Special Operations, Defense Contractors Deployment: Land-Based Systems, Naval Vessels, Aerial Platforms, Mobile Launchers |
| Companies Covered | General Dynamics Ordnance & Tactical Systems, Saab, Rheinmetall, RTX (Raytheon), Nammo, BAE Systems, Thales Group, Elbit Systems, Northrop Grumman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Programmable Ammunition Market Emerging Trajectories
Electronic fusing architectures are displacing mechanical systems across artillery and mortar applications, with software-defined detonation modes enabling mission-specific payload optimization without physical round modification.
Millimeter-wave proximity sensors are automating target detection and detonation timing for moving or partially obscured targets. Armored brigades in Germany and the United States are fielding these seekers for urban and counter-battery operations. The technology is automating engagement decisions previously requiring manual fire adjustment, compressing sensor-to-shooter timelines.
EU REACH enforcement is accelerating substitution of lead-based primary explosives and restricted heavy metals in fuse initiators. Manufacturers are reformulating stab detonators and electric primers with diazo and tetrazene compounds. Artillery shell producers in France and Italy are absorbing higher material costs to maintain European Defence Agency certification eligibility.
Life-cycle service contracts are displacing transactional ammunition purchases for programmable systems. Defense ministries in Norway, Denmark, and the Netherlands are procuring fuse-and-guidance performance guarantees rather than unit volumes. This shift concentrates revenue with suppliers capable of predictive maintenance analytics and field software updates.
Programmable Ammunition Market Segmentation
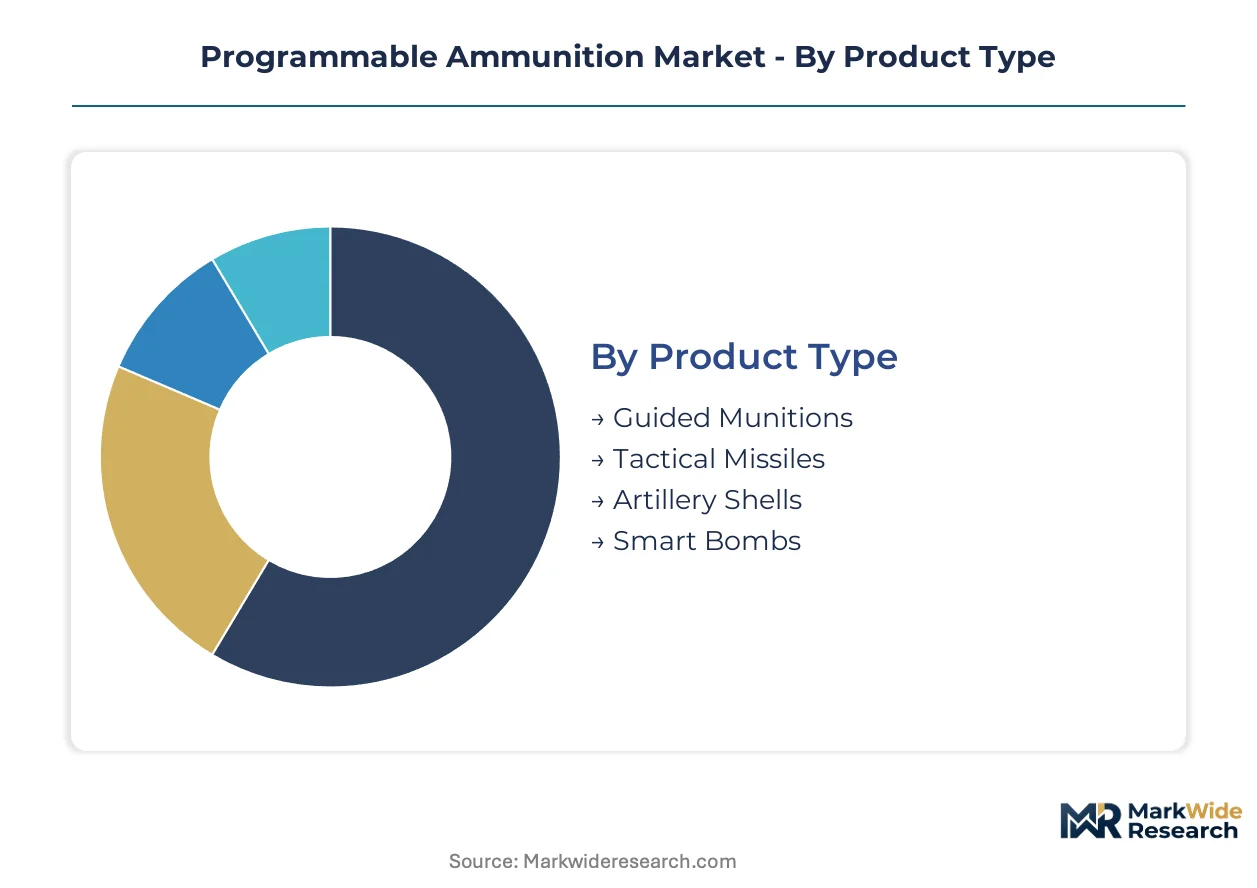
Programmable ammunition procurement divides sharply between retrofit precision kits for existing inventories and purpose-built guided systems. Segmentation patterns reveal where defense ministries prioritize software-defined flexibility over hardware replacement cycles.
Product Type:
Standardization pressures dominate artillery shell categories while guided munitions retain bespoke development pathways.
- Guided Munitions:These systems integrate miniature seeker electronics with real-time trajectory adjustment for moving targets. Demand concentrates in German and Australian armored brigades upgrading counter-battery capabilities, driven by NATO precision fires mandates requiring single-round kill probability against time-sensitive targets.
- Tactical Missiles:Larger-caliber platforms with embedded guidance packages serve deep-strike and anti-shipping roles. Indo-Pacific land forces in Japan and South Korea drive procurement for contested littoral environments, constrained by ITAR delays on seeker component transfers.
- Artillery Shells:GPS-guided retrofit kits for 155mm inventories.
- Smart Bombs:Air-delivered munitions with programmable fusing.
Most installed capacity flows through Artillery Shells. Expansion is steepest in Guided Munitions.
Technology:
Cost tiers separate mature guidance architectures from emerging autonomous systems requiring extensive certification.
- Laser Guidance:Semi-active seeker systems dependent on external designation. Demand clusters in US Marine Corps and British Army urban operations where man-in-the-loop control reduces collateral damage risk.
- GPS Guidance:Satellite-dependent navigation with anti-jam enhancements. Polish and Romanian land forces prioritize these kits for existing tube artillery, constrained by electromagnetic compatibility validation across multiple NATO testing regimes.
- Autonomous Targeting:Millimeter-wave and imaging infrared seekers with edge-classification algorithms.
- Data Link:Two-way communication for in-flight retargeting.
Volume concentrates in GPS Guidance. Autonomous Targeting climbs the fastest as Sweden and South Korea advance seeker integration programs.
End User:
Customer type determines software update frequency and life-cycle service contract structures.
- Military Forces:National armies and marine corps with standardized procurement frameworks. Norwegian and Danish defense ministries now purchase fuse performance guarantees rather than unit volumes.
- Law Enforcement:Specialized units requiring reduced-yield precision options.
- Special Operations:Small-unit forces needing rapid reprogramming via induction coils for time-sensitive targeting scenarios.
- Defense Contractors:System integrators and prime contractors assembling guidance kits for government clients.
Procurement volume concentrates with Military Forces. Special Operations represents the fastest-growing customer type as Indo-Pacific theater commands expand precision fires units.
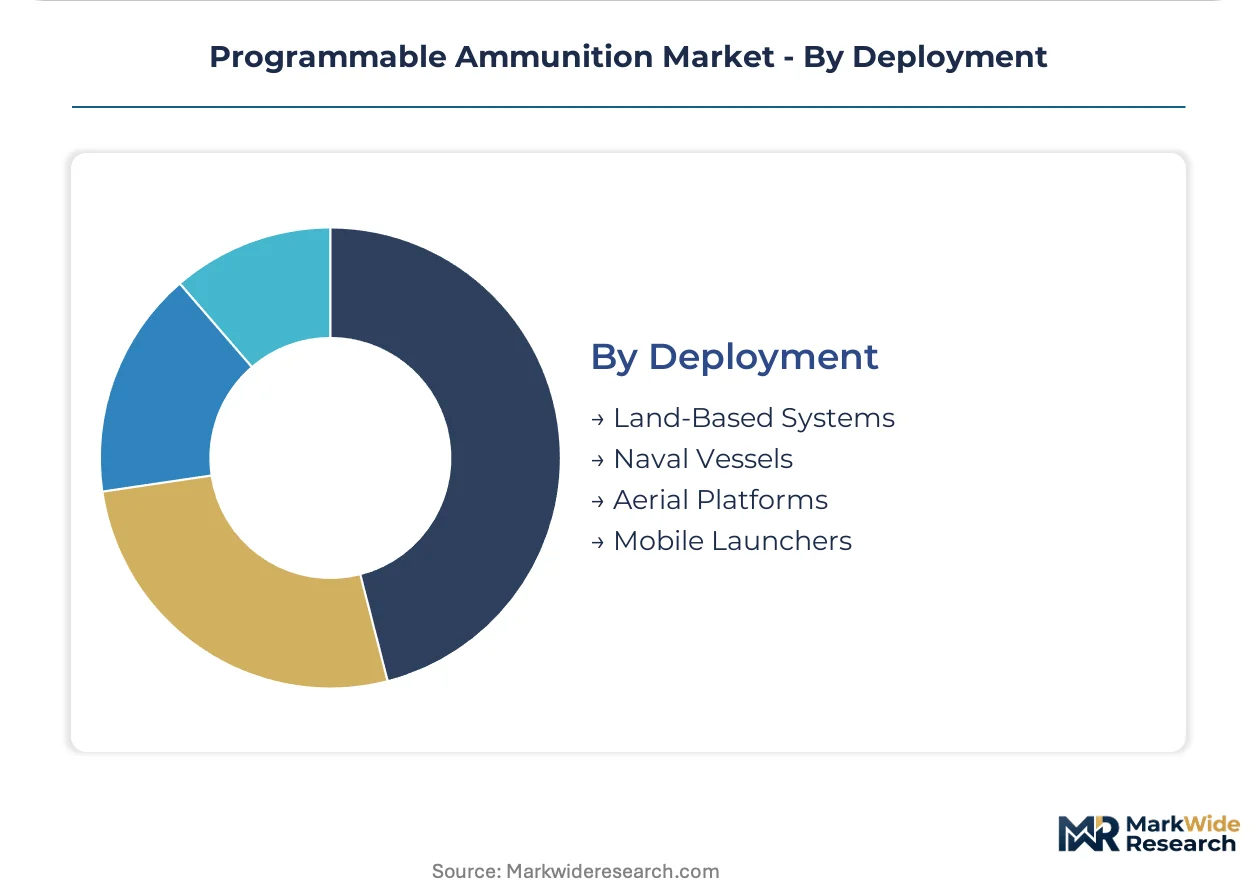
Deployment:
Platform environmental hardening requirements create distinct supplier qualification pathways.
- Land-Based Systems:Tube artillery and mortar platforms with muzzle-loading stress tolerance. German and US armored brigades field millimeter-wave proximity sensors for counter-battery operations.
- Naval Vessels:Deck-mounted launchers with corrosion-resistant guidance packaging.
- Aerial Platforms:Fixed-wing and rotary delivery with high-G launch survivability.
- Mobile Launchers:Ground-based systems with rapid displacement requirements.
Current procurement concentrates in Land-Based Systems. Naval Vessels gain share fastest as Indo-Pacific maritime disputes accelerate shipboard precision fires programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Programmable ammunition traces its industrial lineage to German precision engineering traditions and US defense electronics integration during the Cold War. These twin foundations established the segmented supplier base visible today. Current procurement patterns reflect territorial flashpoints and alliance standardization pressures across five dominant national markets.
United States
The US Department of Defense drives counter-battery modernization through precision fires programs requiring GPS-guided artillery retrofit kits. ITAR regulations constrain cross-border component flows and joint-development eligibility for programmable fuse architectures. Defense contractors cluster around Huntsville, Alabama, where Army Materiel Command coordinates electromagnetic compatibility certification across NATO testing regimes.
Germany
German armored brigades field millimeter-wave proximity sensors for urban and counter-battery operations, automating engagement decisions previously requiring manual fire adjustment. REACH enforcement accelerates substitution of lead-based primary explosives in fuse initiators. Industrial concentration in Bavaria and Baden-Württemberg hosts reformulation programs for diazo and tetrazene compounds in stab detonators.
Japan
Japan's Defense Ministry prioritizes shipboard precision fires programs amid Indo-Pacific maritime disputes, accelerating naval vessel deployment categories. METI coordinates domestic semiconductor foundry capacity to reduce seeker electronics supply concentration risks. Manufacturing clusters in the Kanto region around Tokyo specialize in corrosion-resistant guidance packaging for deck-mounted launchers.
Australia
Australian land forces prioritize precision kit upgrades for existing 155mm inventories over new weapon system acquisitions, creating aftermarket service contracts for guidance integration. The country's defense procurement office consolidates fuse-and-guidance contracts under single-source frameworks. Industrial activity concentrates in South Australia where shipbuilding and ordnance facilities overlap.
Poland
Polish land forces drive demand for GPS-guided artillery retrofit kits as NATO's eastern flank accelerates defense modernization. EU Defence Fund procurement pools consolidate demand for interoperable programmable rounds with standardized fusing specifications. Warsaw anchors regional distribution for guidance kit integration services serving Baltic and Nordic procurement pipelines.
Programmable Ammunition Market Vendor Landscape
The competitive structure tilts toward systems integrators with captive fuse-and-guidance capabilities rather than component specialists. Prime contractors consolidate positions through long-term service contracts displacing transactional ammunition purchases. Three archetypes dominate: European defense conglomerates with integrated propulsion-and-guidance architectures, Nordic specialists in proximity-sensor modules, and US primes leveraging ITAR-controlled seeker electronics. Dominant competitive moves include vertical integration into miniature guidance component fabrication and strategic partnerships for electromagnetic compatibility certification across multiple NATO testing regimes.
Within the integrated-systems tier, Rheinmetall and Saab occupy distinct positions. Rheinmetall exemplifies the European conglomerate archetype with sustained long-term defense contracts. Saab represents Nordic specialization in sensor modules anchoring regional procurement pipelines. RTX (Raytheon) sits within the US prime category where ITAR-controlled component flows create structural advantages in seeker electronics integration.
| Leading Market Players |
|---|
| General Dynamics Ordnance & Tactical Systems |
| Saab |
| Rheinmetall |
| RTX (Raytheon) |
| Nammo |
| BAE Systems |
| Thales Group |
| Elbit Systems |
| Northrop Grumman |
| Others |
Supply Flow & Price Mechanics
Captive fuse-and-guidance integration anchors both supply security and pricing power for prime contractors serving NATO procurement frameworks. Defense ministries in Germany and Poland now bundle long-term service guarantees with hardware purchases, compressing margins for component specialists while elevating returns for systems integrators with in-house seeker production.
Pricing Analysis
Three-tier pricing structure across mission-certified, interoperable-standard, and legacy-surplus levels governs programmable ammunition contracts. Certification grade against NATO Standardization Office specifications and electromagnetic compatibility validation costs drive price differentiation between tiers. Pricing pressure stems from single-source consolidation of fuse-and-guidance contracts by defense procurement offices in Australia and Norway. Law enforcement and special operations units exhibit highest price sensitivity due to limited procurement volumes, while armored brigades in Germany and the United States prioritize performance guarantees over unit cost.
Supply Chain Analysis
Engineer scarcity in RF electronics and energetic materials chemistry concentrates manufacturing capacity in Huntsville, Alabama, Kanto region around Tokyo, and Bavaria. Miniature seeker fabrication draws from East Asian semiconductor foundries, diazo compound production in France and Italy, and corrosion-resistant guidance packaging from Japanese coastal manufacturing clusters. Single-source vulnerability in millimeter-wave sensor modules elevates procurement contingency costs for Indo-Pacific land forces. Distribution runs through prime contractor integration facilities serving national armament directorates with direct-to-military logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Programmable ammunition functions as a defense compounder where NATO precision fires mandates generate steady procurement visibility across multi-year modernization cycles.
For Market Incumbents: Cement long-term service contract positions by acquiring predictive maintenance analytics capabilities and field software update infrastructure. Lock in electromagnetic compatibility certification across multiple NATO testing regimes before REACH reformulation deadlines concentrate procurement among certified vendors. Prioritize backward integration into miniature guidance component fabrication to offset seeker electronics supply concentration risks from East Asian foundries. For New Entrants and Emerging Players: Capture aftermarket guidance integration contracts for 155mm artillery retrofit programs in Poland, Australia, and Japan where land forces prioritize precision kit upgrades over new weapon system acquisitions. Target AI-enabled target classification development partnerships with Swedish and South Korean defense research institutes as the most penetrable technology pathway. Lead with induction coil programming expertise to differentiate against established mechanical fuse suppliers. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap guidance specialists because EU Defence Fund procurement pools are consolidating demand for interoperable programmable rounds with standardized fusing specifications. Five-to-ten-year viability hinges on captive seeker production and NATO certification breadth rather than transactional ammunition volume. Watch ITAR recalibration timelines as the signal for cross-border joint-development eligibility inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Kit Retrofit Program | Polish and Australian land forces extend 155mm inventory service life without new weapon system capital expenditure. |
| Millimeter-Wave Seeker Integration | German armored brigades automate proximity detonation for urban counter-battery operations previously requiring manual adjustment. |
| REACH-Compliant Fuse Reformulation | French and Italian manufacturers absorb diazo compound costs to maintain European Defence Agency certification eligibility. |
| Induction Coil Programming Deployment | Artillery units eliminate mechanical fuse-setting delays for time-sensitive target engagement scenarios. |
| Life-Cycle Service Contract Transition | Norwegian and Danish defense ministries shift from unit volume purchases to fuse performance guarantees with predictive analytics. |
Methodological Framework
Multiple input streams — senior procurement officers at national armament directorates, fuse assembly engineers at prime contractors, electromagnetic compatibility testing leads, and energetic materials chemists — were reconciled against NATO Standardization Office documentation, EU Defence Fund procurement records, REACH enforcement notices, and national defense budget appropriations. Bottom-up volume estimates from guidance kit production capacity were cross-referenced with top-down expenditure flows from defense ministry precision fires program allocations.
Historical procurement trajectories were cross-referenced against expert panel assessments of counter-battery modernization timelines across the projection horizon. Segmentation modeling covered product type, guidance technology architecture, end-user category, and deployment platform with regional regulatory cluster overlays. CAGRs were derived from expenditure commitment patterns and inventory retrofit cycle analysis, incorporating ITAR recalibration friction and semiconductor foundry capacity constraints as industry-specific forecast modifiers.
ITAR revision delays, East Asian foundry disruption events, and REACH enforcement acceleration are the dominant revision risks that could compress or extend procurement timelines. Forecasts reflect documented assumptions about alliance standardization coherence and energetic materials substitution progress. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Ammunition Storage Market
Weapons and Ammunition
Mortar Ammunition Market
Weapons and Ammunition
NIJ III Ballistic Bullet Resistant Panel Market
Weapons and Ammunition
Shotgun and Rifles Market
Weapons and Ammunition
Americas Ballistic Missile Market
Weapons and Ammunition
Man-Portable Anti-Armor Weapons Market
Weapons and Ammunition
Guided Munitions Market
Weapons and Ammunition
Particle Beam Directed Energy Weapon Market
Weapons and Ammunition
Small Caliber Ammunition Market
Weapons and Ammunition
Shotgun Shell Market
Weapons and Ammunition
Light Weapons Market
Weapons and Ammunition
Man-Portable Rocket Launcher Market
Weapons and Ammunition
US Small Caliber Ammunition Market
Weapons and Ammunition
Supersonic and Hypersonic Weapons Market
Weapons and Ammunition
Guns and Accessories Market
Weapons and Ammunition
Intercontinental Ballistic Missile Market