
 Roast Flavoring Market | 2026-2036
Roast Flavoring Market Size, Share, and Industry Trends Forecast 2026-2036
Roast Flavoring Market Analytics
Project finance for captive extraction facilities is reconfiguring competitive entry barriers in roast flavoring. Givaudan SA leverages backward integration into botanical sourcing to secure supply continuity for natural extracts. Kerry Group plc anchors its position through manufacturing scale across multiple liquid and powder form factors. Sensient Technologies Corporation specializes in heat-stable roast flavor systems for high-temperature bakery applications.
Roast flavoring comprises thermally derived aromatic compounds, pyrazines, furans, and thiazoles formulated to replicate or enhance Maillard reaction profiles in food and beverage matrices. These formulations typically deliver targeted flavor intensity measured in parts per million and serve to standardize sensory outcomes across industrial production batches. Liquid concentrates dominate current volume flows due to their dosing precision in automated beverage lines, while natural extracts command premium positioning as clean-label formulations expand across retail channels. Powder forms sustain growth in dry seasoning blends for snack and savory applications where moisture control remains critical.
The FDA's Food Safety Modernization Act and the EPA's chemical substance reporting requirements under TSCA jointly elevate compliance costs for domestic and imported roast flavoring ingredients. ISO 22000 and FSSC 22000 certifications increasingly function as baseline qualifications for supplier qualification programs at major food manufacturers. Stakeholders must monitor evolving clean-label thresholds and extraction method disclosures as procurement teams reformulate around consumer transparency expectations.
Market Dynamics
The roast flavoring market is being fundamentally restructured by the FDA's Food Safety Modernization Act traceability mandates, which are forcing ingredient suppliers to rebuild supply chain documentation systems and pushing smaller compounders toward consolidation or exit.
Growth Catalysts
- Clean-label procurement mandates:Major beverage manufacturers now require natural extraction method disclosures, pulling demand toward botanical-derived roast notes and away from synthetic pyrazine formulations.
- India:FSSAI enforcement of additive labeling standards is accelerating domestic adoption of imported natural roast extracts in packaged snack and instant coffee categories.
- Precision fermentation:Biosynthesis of Maillard-reactive compounds without thermal processing is opening new formulation pathways for heat-sensitive applications.
Market Restraints
- Vanilla and cocoa bean price volatility:Natural roast flavor precursors depend on these commodity inputs, with weather-driven supply shocks transmitting directly to extract costs.
- Supplier concentration in Madagascar and Indonesia:Over 60% of global natural vanilla extraction capacity sits in these two origins, creating single-point-of-failure risk for clean-label roast flavor supply.
- EPA TSCA reporting thresholds:New chemical substance notifications for modified pyrazine molecules are extending product development timelines by 18-24 months.
Strategic Opportunities
- Brazil:ANVISA's streamlined food additive approval pathways and underdeveloped craft beverage infrastructure create first-mover potential for premium roast flavor suppliers.
- Cell-cultured meat:This emerging protein category requires bespoke roast flavor systems to replicate cooked meat aromatics without traditional Maillard processing.
- EU Green Deal sustainable extraction incentives:Supercritical CO2 processing equipment investments now qualify for favorable financing terms, accelerating solvent-free extract production scale-up.
Industry Challenges
- Flavor chemist talent scarcity:The specialized knowledge bridging pyrolysis chemistry and food safety compliance is concentrating at a handful of technical universities and legacy suppliers.
- ISO 22000 certification timelines:New facility qualification for major food manufacturer supplier programs requires 14-18 months of documentation and third-party audit cycles.
- Legacy ERP integration:Batch-level traceability systems mandated by the FDA are forcing mid-tier compounders to replace decades-old manufacturing execution software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roast Flavoring Market |
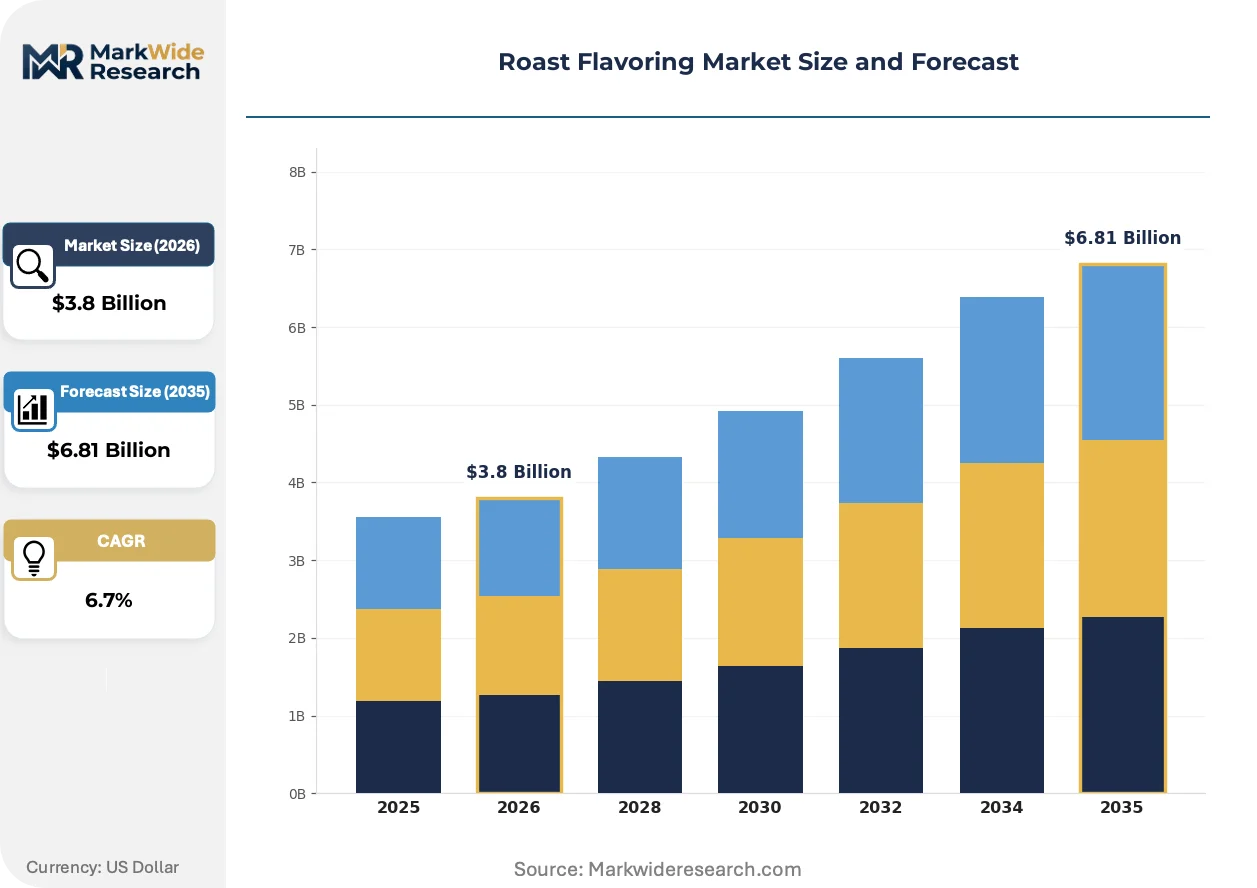
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Extracts, Flavor Concentrates, Spices, Seasonings Application: Food Processing, Beverage Manufacturing, Cooking, Bakery Products Form: Liquid, Powder, Granule, Paste End User: Restaurants, Retailers, Confectioneries, Catering Services |
| Companies Covered | Givaudan SA, International Flavors and Fragrances, Symrise AG, Kerry Group plc, Sensient Technologies Corporation, Firmenich SA, Archer Daniels Midland Company, Takasago International Corporation, DSM-Firmenich AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roast Flavoring Market Evolving Landscape
Bioprocessing technologies and regulatory disclosure requirements are converging to redefine how roast flavors are synthesized, documented, and procured across food and beverage value chains.
Supercritical CO2 extraction systems are capturing thermally labile aromatic compounds at ambient temperatures, preserving volatile thiazole and furan profiles that conventional solvent methods degrade. Artisanal roasteries and specialty coffee chains are adopting these systems for in-house flavor development. The technology is rendering obsolete traditional steam distillation infrastructure for high-value natural extract production.
REACH registration requirements for flavor substance imports into the European Union are forcing non-EU suppliers to establish EU-based legal entities and submit full toxicological dossiers. This regulatory burden is compressing the supplier base to firms with dedicated regulatory affairs capacity. Powder roast flavor formulations containing novel pyrazine derivatives face the steepest compliance cost escalation.
Beverage manufacturers are consolidating supplier relationships around full-service flavor houses capable of delivering integrated sensory profiling, regulatory documentation, and application technical support. This buying-pattern shift is displacing transactional spot purchasing of commodity roast flavor concentrates. The United States craft brewing sector exhibits the most pronounced consolidation, with regional brewers now sourcing through approved vendor lists of three to four strategic partners.
Roast Flavoring Market Segmentation
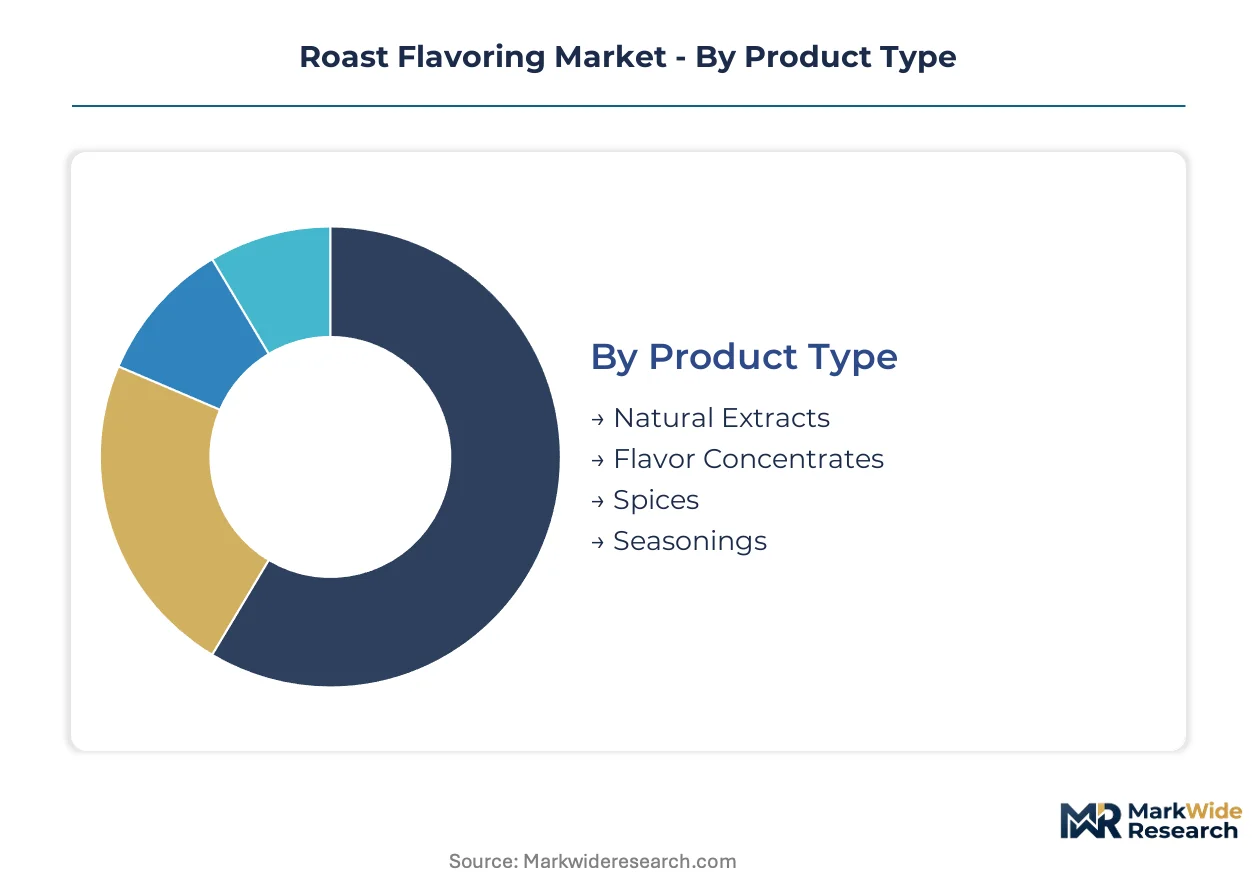
Roast flavoring procurement patterns diverge sharply across product architectures and use environments. Formulation chemistry and thermal stability requirements create distinct supply chain rhythms that suppliers must synchronize against.
Product Type:
Flavor Concentrates rotate through formulation cycles fastest as beverage manufacturers iterate seasonal profiles, while Natural Extracts move slowest due to agricultural lead times and extraction batch complexity.
- Natural Extracts:Botanical-derived aromatic compounds captured through supercritical CO2 or steam distillation methods preserve volatile thiazole and furan structures. Demand clusters in United States craft beverage channels where clean-label procurement mandates now require extraction method disclosures on supplier certificates.
- Flavor Concentrates:Thermally synthesized pyrazine and pyridine formulations deliver standardized Maillard reaction intensity measured in parts per million. United States specialty coffee chains and artisanal roasteries drive volume for these precision-dosed liquid systems in automated production lines.
- Spices:Whole and ground botanical precursors including cinnamon, nutmeg, and clove that undergo secondary roasting for flavor development.
- Seasonings:Pre-blended dry formulations combining roast flavor compounds with salt, sugar, and carrier agents for direct application.
Flavor Concentrates dominate installed base. Natural Extracts are where expansion concentrates.
Application:
Cost tier stratification separates commodity-grade thermal process flavors from premium-positioned clean-label extracts across manufacturing verticals.
- Food Processing:Industrial-scale thermal processing of savory snacks, ready meals, and protein alternatives requires heat-stable roast flavor systems that withstand retort and extrusion temperatures exceeding 120°C. United States snack manufacturers anchor demand for powder form factors where moisture control remains critical.
- Beverage Manufacturing:Coffee, tea, and malt-based drink production depends on liquid concentrate dosing precision in high-speed filling lines. United States craft brewing sector procurement has consolidated around approved vendor lists of three to four strategic flavor houses.
- Cooking:Direct-use formulations for foodservice pan roasting and finishing applications.
- Bakery Products:Heat-stable systems for bread, pastry, and cracker matrices where Maillard enhancement must survive oven cycling.
Food Processing commands the largest revenue pool. Beverage Manufacturing shows the steepest expansion trajectory.
Form:
Volume concentration favors liquid systems in automated manufacturing, while powder and granule forms sustain growth in moisture-sensitive applications.
- Liquid:Pumpable concentrates with defined viscosity profiles for metered injection in continuous beverage and sauce production lines.
- Powder:Spray-dried or plated formulations with extended shelf stability for dry seasoning blends and bakery premixes.
- Granule:Agglomerated particles combining rapid dispersibility with reduced dusting for foodservice and retail cooking segments.
- Paste:High-solids suspensions for artisanal and small-batch applications requiring spoonable consistency.
Liquid anchors manufacturing throughput. Powder is gaining share fastest in snack and savory channels.
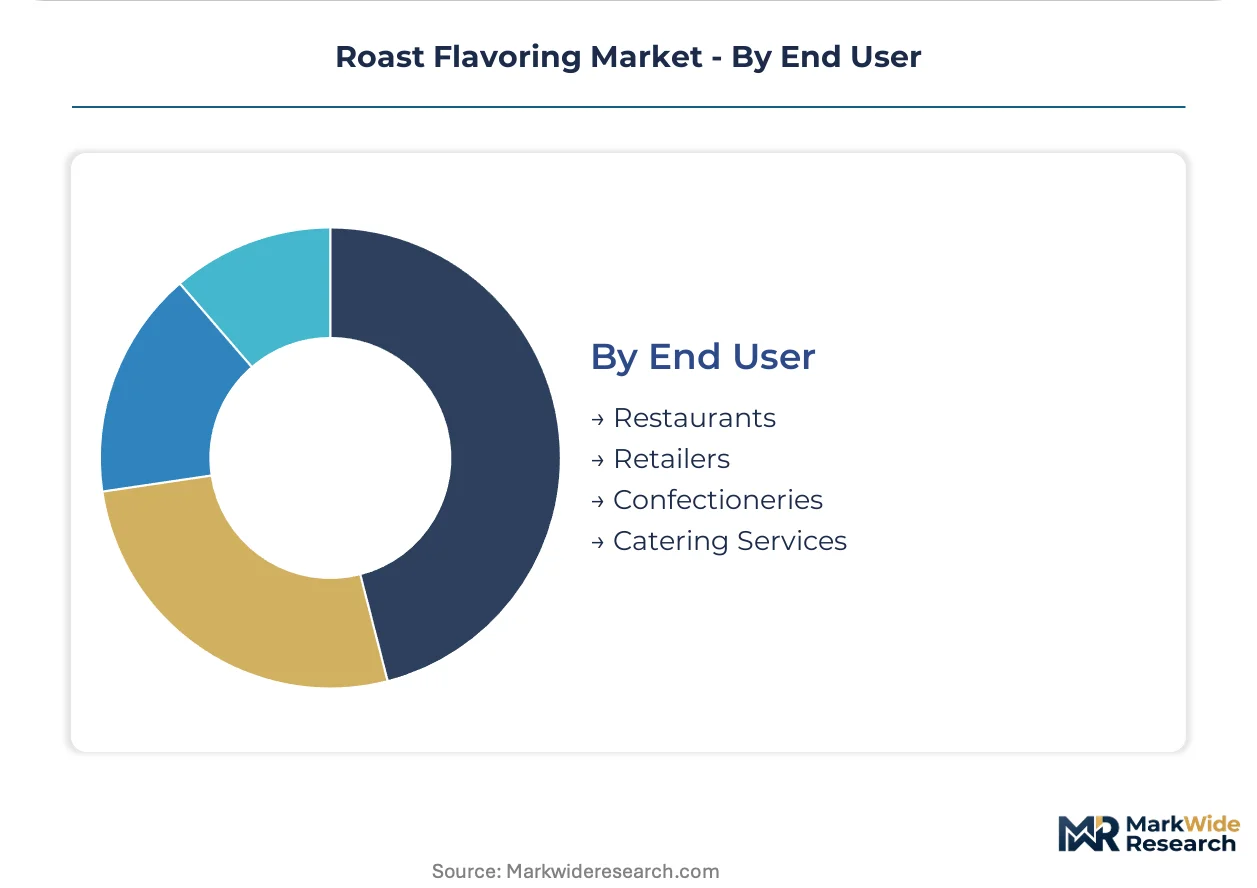
End User:
Customer type determines formulation complexity, with institutional buyers demanding full regulatory documentation and retail channels prioritizing label-friendly ingredient statements.
- Restaurants:Foodservice operators source roast flavor systems for consistent execution across kitchen brigades and franchise locations.
- Retailers:Private-label and branded product development teams specify clean-label extracts for shelf-ready consumer goods.
- Confectioneries:Chocolate and candy manufacturers apply roast notes to offset dairy sweetness and enhance cocoa depth profiles.
- Catering Services:Event and institutional feeding operations require bulk-format concentrates for volume production with minimal labor.
Retailers drive premium extract adoption. Restaurants remain the volume anchor for standard concentrate formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal sustainable extraction incentives are redirecting capital toward supercritical CO2 processing infrastructure in key manufacturing clusters. The FDA's Food Safety Modernization Act traceability mandates are simultaneously reshaping supplier qualification requirements in North American procurement channels.
United States
Craft beverage culture drives premium roast flavor adoption across coffee, brewing, and ready-to-drink categories. The FDA's FSMA traceability mandates force ingredient suppliers to rebuild documentation systems for batch-level tracking. Specialty coffee chains in Seattle and Portland anchor demand for precision-dosed liquid concentrate systems.
Germany
Industrial bakery and savory snack manufacturers require heat-stable roast flavor systems for high-temperature processing applications. REACH registration requirements for flavor substance imports compress the supplier base to firms with dedicated regulatory affairs capacity. The Cologne-Düsseldorf corridor concentrates flavor house technical centers serving Central European manufacturing.
Brazil
Underdeveloped craft beverage infrastructure creates first-mover potential for premium roast flavor suppliers entering packaged coffee and malt-based drinks. ANVISA's streamlined food additive approval pathways reduce regulatory friction for new ingredient introductions. São Paulo-state food processing clusters are expanding flavor portfolios for domestic snack and instant coffee categories.
India
Packaged snack and instant coffee categories accelerate adoption of imported natural roast extracts as FSSAI enforces additive labeling standards. Domestic procurement teams reformulate around consumer transparency expectations for extraction method disclosures. Maharashtra-based food manufacturers lead clean-label extract adoption in Western India manufacturing corridors.
China
Beverage manufacturers consolidate supplier relationships around full-service flavor houses capable of integrated sensory profiling and regulatory documentation. SAMR food safety standards elevate compliance costs for imported roast flavoring ingredients. Yangtze River Delta processing clusters dominate liquid concentrate production for automated filling lines.
Roast Flavoring Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct value capture tiers. The supplier base concentrates around full-service flavor houses with integrated regulatory documentation capabilities and manufacturing-scale compounders serving commodity thermal process applications. Three archetypes dominate: botanical sourcing integrators securing supply continuity for natural extracts, application-technical specialists engineering heat-stable systems for high-temperature matrices, and scale-driven liquid concentrate suppliers anchoring automated beverage line procurement. Competitive moves center on backward integration into botanical sourcing and consolidation of manufacturing scale across multiple form factors.
Among Swiss-headquartered flavor houses, Givaudan SA and Firmenich SA occupy positions emphasizing supply chain control over botanical inputs. Kerry Group plc anchors the manufacturing-scale tier with liquid and powder form factor breadth. Sensient Technologies Corporation exemplifies the application-technical specialist archetype focused on heat-stable system engineering.
| Leading Market Players |
|---|
| Givaudan SA |
| International Flavors and Fragrances |
| Symrise AG |
| Kerry Group plc |
| Sensient Technologies Corporation |
| Firmenich SA |
| Archer Daniels Midland Company |
| Takasago International Corporation |
| DSM-Firmenich AG |
| Others |
Value Network & Pricing Analysis
Undercapacity in supercritical CO2 extraction infrastructure across European processing clusters is compressing natural extract availability and amplifying price premiums for clean-label roast flavor formulations. This utilization squeeze simultaneously accelerates backward integration investments by major flavor houses and widens the bid-ask spread between commodity thermal process concentrates and certified botanical-derived systems.
Pricing Analysis
Certification level creates the primary spread between FSSC 22000-qualified natural extracts and standard-grade thermal process concentrates. Three-tier pricing structure across premium, standard, and economy levels reflects extraction method transparency, with supercritical CO2-derived compounds commanding substantial premiums over solvent-based alternatives. Cost compression in synthetic pyrazine formulations is intensifying because EPA TSCA notification timelines extend product development cycles. Beverage manufacturers exhibit the highest price sensitivity due to volume scale, while artisanal roasteries absorb premium pricing for extraction method disclosure compliance.
Supply Chain Analysis
Export-control restrictions on supercritical CO2 processing equipment from German and Swiss manufacturers are constraining capacity expansion timelines for natural extract producers in India and Brazil. Raw material flows concentrate in Madagascar and Indonesia for vanilla precursors, with Vietnam and Guatemala anchoring cinnamon and clove sourcing for secondary roast development. Single-source vulnerability in Madagascar vanilla extraction creates acute disruption risk for clean-label supply continuity. Distribution runs through full-service flavor houses with integrated regulatory documentation capabilities rather than transactional spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation biosynthesis represents a technological inflection capable of decoupling roast flavor production from agricultural commodity cycles and thermal processing constraints. The FDA's Food Safety Modernization Act traceability mandates are simultaneously restructuring supplier qualification requirements and accelerating consolidation among mid-tier compounders.
For Market Incumbents: Build regulatory documentation moats by investing in batch-level ERP integration and ISO 22000 certification expansion across multiple production sites. Kerry Group plc's manufacturing scale across liquid and powder form factors exemplifies the capacity breadth required to anchor approved vendor lists at major beverage manufacturers. Defensive positioning demands backward integration into botanical sourcing to secure supply continuity against Madagascar vanilla supply shocks. For New Entrants and Emerging Players: Establish a beachhead in Brazil's underdeveloped craft beverage infrastructure where ANVISA's streamlined additive approval pathways reduce regulatory friction. Cell-cultured meat applications offer a white-space target requiring bespoke roast flavor systems without incumbent legacy constraints. A precision fermentation go-to-market angle bypasses agricultural commodity dependencies and appeals to clean-label procurement mandates. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across supercritical CO2 extraction infrastructure due to EU Green Deal sustainable processing incentives. Five-to-ten year viability favors acquisition targets with captive botanical sourcing and established FSSC 22000 certification rather than synthetic compound specialists facing EPA TSCA timeline extensions. The signal to watch is FSSAI enforcement intensity in India, which would accelerate imported natural extract adoption and validate premium extraction infrastructure investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Botanical Sourcing | Givaudan SA's supply continuity model secures Madagascar vanilla extraction capacity against weather-driven shocks. |
| Supercritical CO2 Capacity Expansion | EU Green Deal financing terms accelerate solvent-free extract production scale-up in Cologne-Düsseldorf corridor. |
| Precision Fermentation Biosynthesis | Heat-sensitive Maillard-reactive compound production opens formulation pathways for cell-cultured meat applications. |
| Full-Service Flavor House Consolidation | Beverage manufacturers now demand integrated sensory profiling and regulatory documentation from three-to-four strategic partners. |
| ERP System Modernization | FDA FSMA batch-level traceability mandates force replacement of decades-old manufacturing execution software. |
Research Methodology
Initial hypotheses were tested against primary input from flavor chemists at technical universities, procurement leads at specialty coffee chains, regulatory affairs directors at multinational flavor houses, and plant managers at supercritical CO2 extraction facilities, then refined against secondary validation from FDA FSMA guidance documents, EPA TSCA chemical substance notifications, FSSAI additive labeling standards, ANVISA food additive approval pathways, and EU REACH registration dossiers. Bottom-up volume modeling across extraction method categories and top-down value reconciliation against manufacturing capacity disclosures were cross-referenced for triangulation.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product architecture (natural extracts versus thermal concentrates versus spices), application vertical (beverage manufacturing versus food processing versus bakery), form factor (liquid versus powder versus granule), and end-user type (retailers versus restaurants versus confectioneries). CAGRs were derived from installed base growth rates and replacement cycle analysis, incorporating precision fermentation technology diffusion curves and clean-label procurement mandate adoption timelines as industry-specific inputs.
Sensitivities concentrate around vanilla and cocoa bean price volatility, EPA TSCA reporting threshold modifications, and FSSAI enforcement intensity escalation. Forecasts reflect assumptions regarding supercritical CO2 equipment financing availability and artisanal roastery expansion rates. Material shifts in Madagascar vanilla supply continuity or FDA traceability mandate implementation timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Global Ginger Extract Market
Flavorings and Food Additives
Global Syrup Market
Flavorings and Food Additives
Feed Flavors and Sweeteners Market
Flavorings and Food Additives
Lecithin Oleoresin Market
Flavorings and Food Additives
Seaweed Flavor Market
Flavorings and Food Additives
Smoke Flavorings Market
Flavorings and Food Additives
Citrus Extract Market
Flavorings and Food Additives
Grapefruit Oil Market
Flavorings and Food Additives
Farnesol Market
Flavorings and Food Additives
Synthetic Food Colors Market
Flavorings and Food Additives
Flavored Salt Market
Flavorings and Food Additives
Clean Label Flavors Market
Flavorings and Food Additives
Orange Terpenes Market
Flavorings and Food Additives
Sea Urchin and Roe Flavor Ingredients Market
Flavorings and Food Additives
Russia Food Colorants Market
Flavorings and Food Additives
Japan Food Colorants Market