
 North America Saffron Supplements Market | 2026-2036
North America Saffron Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
North America Saffron Supplements Market Analytics
The gap between premium and commodity saffron supplement tiers is shifting from packaging differentiation toward verifiable sourcing and standardized crocin content. NOW Health Group leverages its vertically integrated supply chain to sustain price competitiveness across mass-market capsules. Life Extension differentiates through third-party potency testing and clinical-strength formulations. Epicure Garden competes in the artisan segment with single-origin Iranian saffron extracts and transparent batch traceability.
North America saffron supplements are concentrated preparations derived from Crocus sativus stigmas, typically standardized to crocin, safranal, and picrocrocin content for consistent bioactive delivery. Manufacturers employ cold-extraction or hydroalcoholic processes to preserve volatile compounds, with primary commercial purpose centered on mood regulation, ocular health, and cognitive support applications. Capsules dominate volume through pharmacy and online channels, while liquid extracts capture premium margins among nutritionist-guided patient segments. Organic and standardized formulations lead growth as consumers cross-reference USDA Organic seals with USP or NSF certification marks.
The FDA's Current Good Manufacturing Practice regulations and Canada's Natural and Non-prescription Health Products Directorate enforce identity, purity, and composition standards that filter marginal entrants from compliant suppliers. California's Proposition 65 warning requirements and New York's agricultural labeling statutes add state-level compliance layers affecting distribution economics. Stakeholders must monitor evolving adulteration detection protocols and country-of-origin disclosure mandates as supply chain transparency becomes a decisive purchase criterion.
Market Dynamics
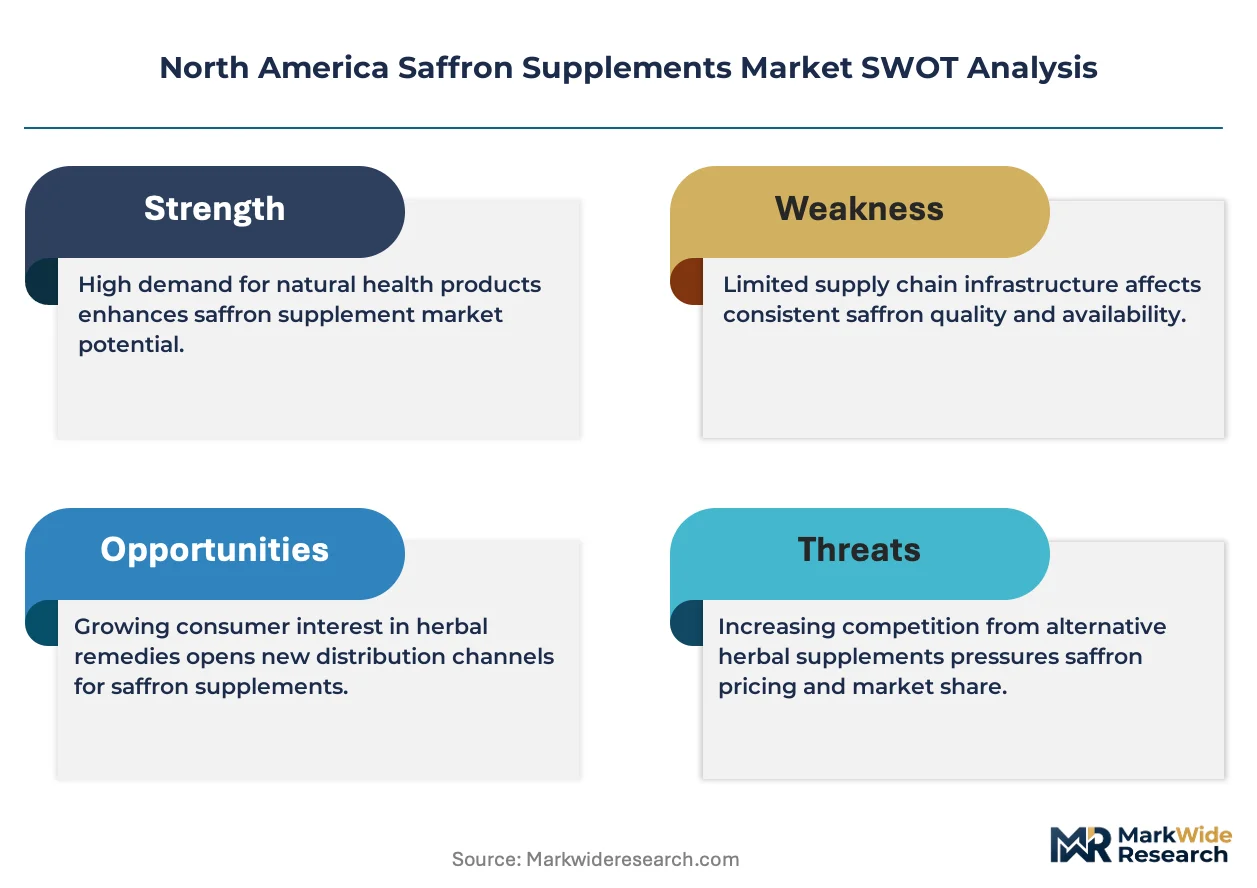
Standardization of crocin and safranal content is compressing price premiums across the North America saffron supplements market, forcing suppliers to demonstrate bioactive equivalence through third-party certification rather than origin claims alone.
Growth Catalysts
- FDA Current Good Manufacturing Practice enforcement:Compliance requirements filter marginal suppliers, concentrating shelf space among certified manufacturers in pharmacy and direct-to-consumer channels.
- California wellness retail clusters:Premium health stores in Los Angeles and San Francisco generate disproportionate trial volume for mood-support formulations targeting stress-management consumers.
- Cold-extraction process adoption:Preservation of volatile safranal compounds enables potency claims that hydroalcoholic extracts cannot match, differentiating premium tier offerings.
Market Restraints
- Iranian saffron supply concentration:Over eighty percent of global stigma sourcing originates from Khorasan province, exposing North American importers to geopolitical disruption and currency volatility.
- California Proposition 65 compliance costs:Warning label requirements for trace heavy metals add per-SKU regulatory overhead that disproportionately burdens small-batch artisan producers.
- Synthetic carotenoid substitution:Laboratory-derived crocin analogs at one-tenth the input cost threaten price positioning of botanical extracts in mass-market capsule segments.
Strategic Opportunities
- USDA Organic certification expansion:Organic acreage in Ontario and Quebec is scaling domestic stigma cultivation, reducing import dependency for Canadian natural health product manufacturers.
- Practitioner channel penetration:Naturopathic and functional medicine clinics in New York and Texas represent underdeveloped prescription-adjacent distribution for clinical-strength liquid extracts.
- USP verification adoption:Third-party potency certification creates shelf differentiation in pharmacy chains where consumers cross-reference supplement seals against smartphone databases.
Industry Challenges
- Adulteration detection capability gaps:Chromatographic testing for saffron authenticity requires capital equipment that mid-tier contract manufacturers lack, creating quality assurance blind spots.
- Batch-to-batch bioactive variance:Natural harvest variation in crocin content forces reformulation cycles that compress production planning windows and inflate working capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Saffron Supplements Market |
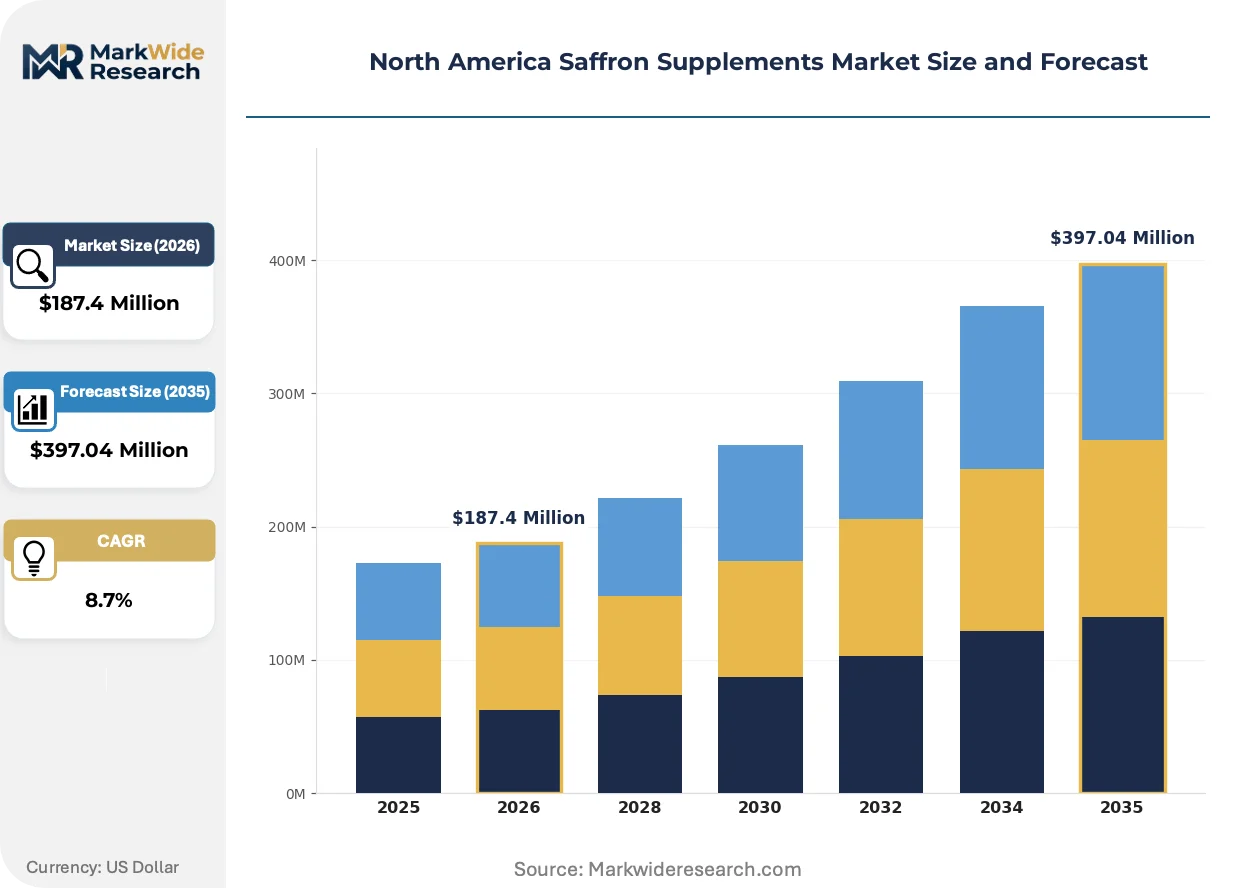
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powders, Liquid Extracts, Blends End User: Health Enthusiasts, Patients, Nutritionists, Fitness Trainers Distribution Channel: Online Retailers, Pharmacies, Health Food Stores, Direct Sales Formulation: Organic, Non-GMO, Vegan, Standardized |
| Companies Covered | Nature's Way, Swanson Health Products, NOW Health Group, Life Extension, GNC Holdings, Epicure Garden, Lean Nutraceuticals, LUMA Nutrition, Persavita, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Saffron Supplements Market Evolving Landscape
Digital traceability infrastructure is reshaping how North American consumers authenticate saffron provenance, converting supply chain transparency from a niche premium feature into a baseline purchase qualifier across retail channels.
HPLC-UV fingerprinting is unifying quality assurance protocols across Iranian, Afghan, and emerging North American cultivation sources. Contract laboratories in California and New York are adopting standardized methods that enable cross-batch comparability. This analytical convergence is compressing the information asymmetry that previously separated artisan and mass-market tiers.
Health Canada's Natural and Non-prescription Health Products Directorate is tightening site license requirements for foreign manufacturing facilities. Iranian and Spanish extractors now face mandatory pre-approval inspections before Canadian import authorization. US suppliers with existing Health Canada registrations are capturing shelf space as competitors navigate extended compliance timelines.
Subscription-direct models are displacing pharmacy impulse purchases among repeat buyers seeking cognitive support regimens. Nutritionist-guided patients in Ontario and Texas are consolidating procurement through practitioner-portal ordering systems that bundle saffron with complementary adaptogens. This channel migration is most visible in urban clusters where telehealth platforms integrate supplement recommendations with prescription management workflows.
North America Saffron Supplements Market Segmentation
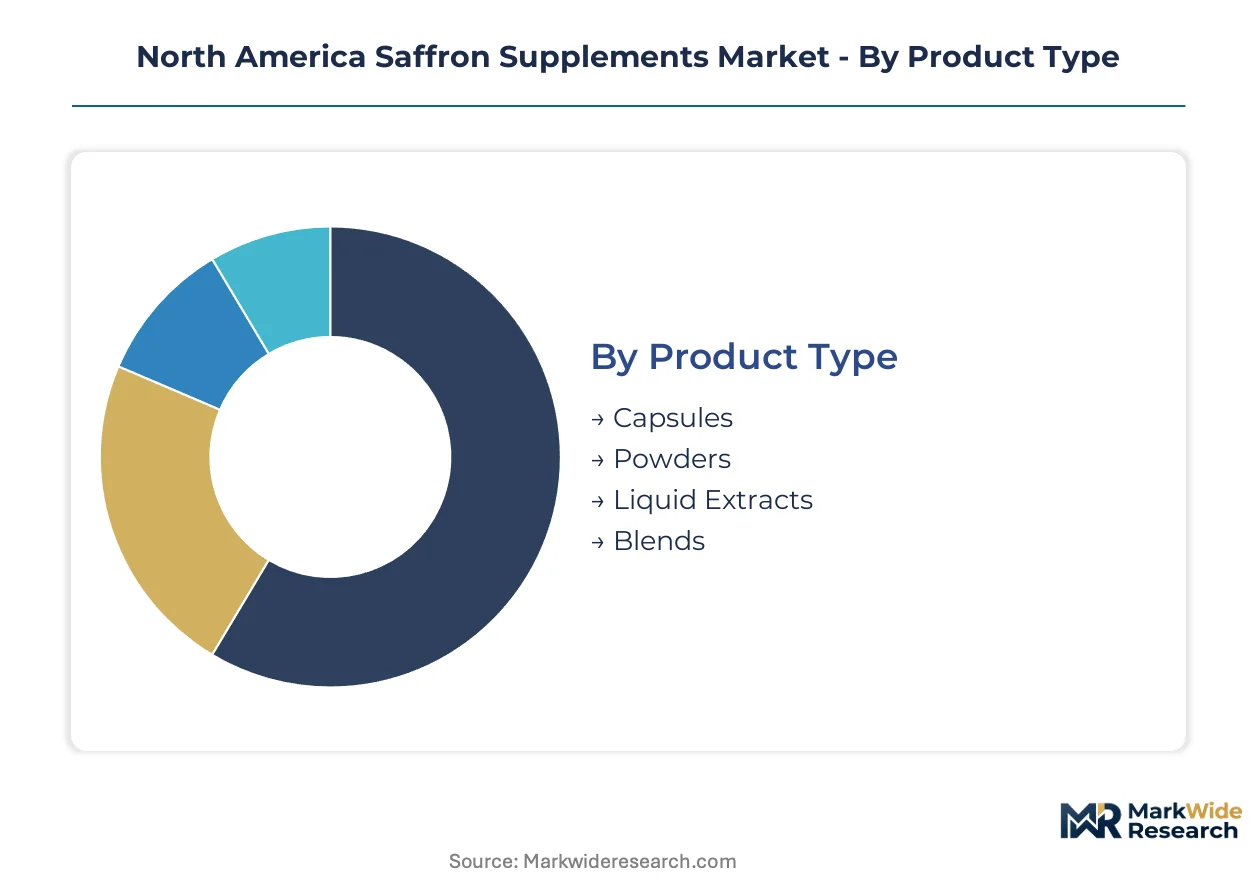
Saffron supplement purchasing patterns diverge sharply across delivery formats and buyer sophistication levels. Manufacturers align product architectures with distinct compliance requirements and consumption rituals that separate pharmacy shoppers from direct-to-consumer subscribers.
Product Type:
Capsule users upgrade toward liquid formats as bioavailability science penetrates wellness-conscious segments, while powder adoption accelerates among functional food formulators seeking ingredient flexibility.
- Capsules:Gelatin and vegetable-shell variants dominate pharmacy and mass-market channels through standardized dosing convenience. California and New York health food retailers report concentrated demand for enteric-coated formulations that protect crocin from gastric degradation.
- Liquid Extracts:Hydroalcoholic and glycerin-based tinctures deliver faster absorption kinetics prized by naturopathic practitioners. Texas functional medicine clinics drive volume for sublingual drops with measured safranal potency.
- Powders:Bulk stigma granules serve smoothie additive and culinary crossover applications.
- Blends:Saffron-adaptogen combinations target mood-stack consumers seeking multi-ingredient convenience.
Capsules sit at the top of the volume ranking, with Liquid Extracts climbing the fastest.
End User:
Cost tiers separate self-directed health enthusiasts from clinician-supervised patients, with nutritionists occupying a consultative middle ground that demands batch documentation.
- Health Enthusiasts:Self-directed consumers cross-reference USDA Organic seals with USP verification marks before purchase. Ontario telehealth platforms bundle saffron subscriptions with biometric tracking apps.
- Patients:Physician-referred individuals seek clinical-strength formulations with documented crocin standardization. New York integrative medicine practices prescribe specific brands with third-party Certificates of Analysis.
- Nutritionists:Registered dietitians curate professional-grade extracts for client protocols.
- Fitness Trainers:Performance-oriented coaches recommend saffron for recovery and sleep optimization stacks.
Health Enthusiasts command the largest addressable base, while Patients show the steepest expansion trajectory.
Distribution Channel:
Volume concentration favors pharmacy chains with established supplement aisles, though margin structures reward direct relationships that bypass retail markup layers.
- Online Retailers:Amazon and specialized wellness platforms capture subscription-driven repeat purchases with auto-ship incentives. California-based direct-to-consumer brands leverage influencer partnerships for trial conversion.
- Pharmacies:CVS and Walgreens shelf placement depends on USP or NSF certification compliance. Pharmacist recommendations drive initial trial among prescription-adjacent shoppers.
- Health Food Stores:Whole Foods and regional cooperatives prioritize organic and single-origin provenance claims.
- Direct Sales:Practitioner portals and brand-owned websites retain highest margins per unit.
Online Retailers lead absolute volume, with Direct Sales gaining share fastest.
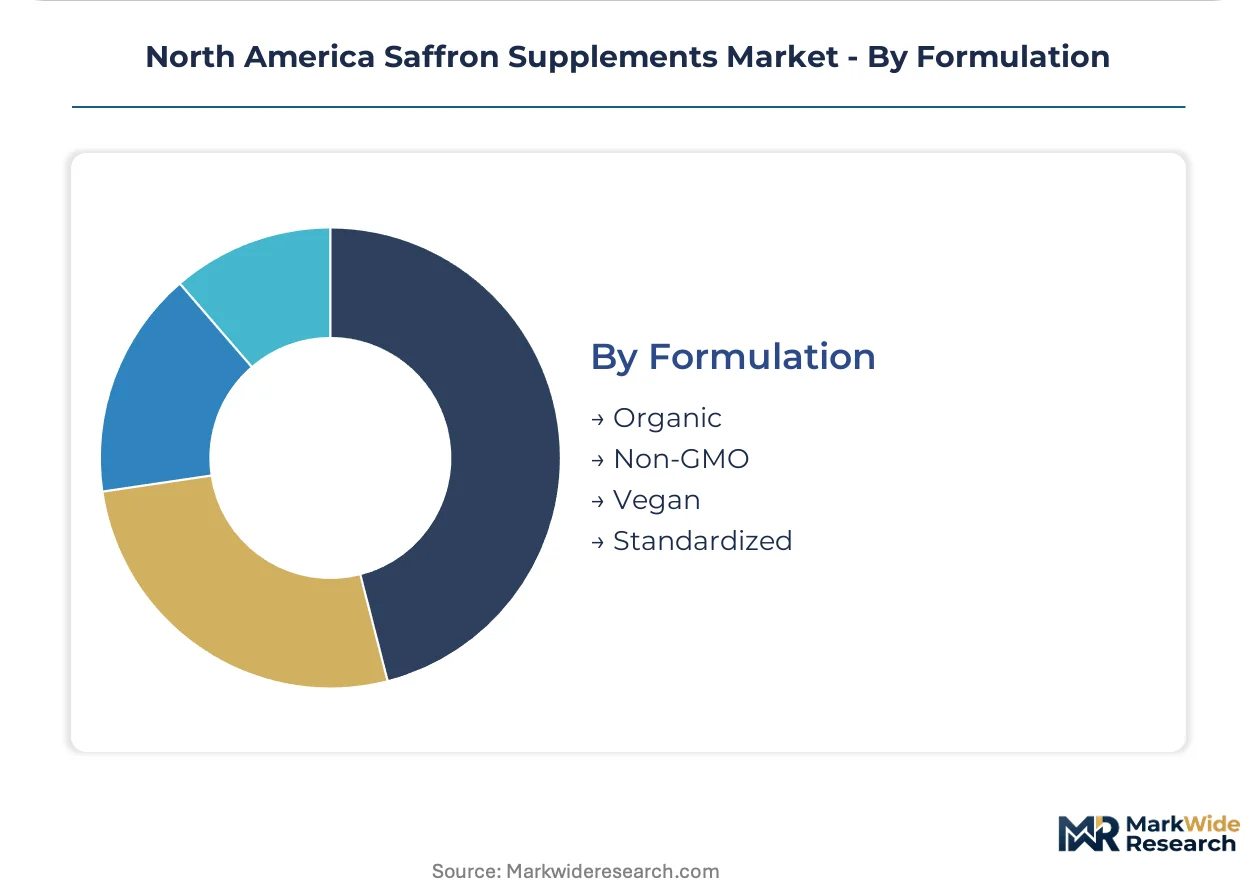
Formulation:
Supply concentration in Iranian sourcing shapes certification hierarchies, with organic acreage expansion in Ontario and Quebec creating domestic alternatives for Canadian manufacturers.
- Organic:USDA-certified stigma cultivation meets Prop 65 compliance thresholds that conventional extracts often breach. Quebec agricultural extension programs support domestic organic transitions.
- Standardized:HPLC-verified crocin and safranal content enables potency claims that justify premium positioning. USP verification programs filter non-compliant suppliers from pharmacy distribution.
- Non-GMO:Project Verified seals address consumer skepticism toward adulterated botanicals.
- Vegan:Plant-based capsule shells replace gelatin for ethically motivated purchasers.
Standardized formulations anchor current revenue, with Organic certification expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Naturopathic practitioners in Vancouver and Toronto anchor Canadian demand for clinical-grade extracts, while functional medicine networks in Texas and California drive US volume for mood-support formulations.
United States
California wellness retail clusters in Los Angeles and San Francisco generate disproportionate trial volume for stress-management saffron stacks. The FDA's Current Good Manufacturing Practice regulations filter marginal suppliers from pharmacy distribution channels. New York integrative medicine practices in Manhattan and Brooklyn prescribe specific brands with third-party Certificates of Analysis.
Canada
Ontario telehealth platforms bundle saffron subscriptions with biometric tracking apps for health-conscious consumers in Toronto and Ottawa. Health Canada's Natural and Non-prescription Health Products Directorate enforces site license requirements for foreign manufacturing facilities. Quebec agricultural extension programs support domestic organic stigma cultivation transitions near Montreal.
Mexico
Mexico City metro area health food retailers report rising interest in adaptogen blends containing standardized saffron extracts among middle-class wellness consumers. The country's national pharmaceutical regulator maintains import documentation requirements for botanical dietary supplements. Guadalajara-based distributors serve as consolidation points for US-manufactured products entering central Mexican pharmacy chains.
North America Saffron Supplements Market Competitive Landscape
Capital-heavy producers with captive supply chains compete with asset-light formulators outsourcing extraction and encapsulation. The vendor base stratifies across three tiers: mass-market retailers with private-label capacity, clinical-strength specialists with third-party certification, and artisan single-origin importers with transparent batch traceability. Dominant competitive moves include USP verification adoption for pharmacy shelf differentiation and backward integration into stigma sourcing to reduce Iranian supply dependency.
Within the mass-market tier, NOW Health Group and Nature's Way represent scale-driven players with vertically integrated manufacturing infrastructure. Life Extension occupies a position among clinical-strength specialists emphasizing third-party potency testing. Epicure Garden exemplifies the artisan segment with transparent batch traceability claims. These three anchors demonstrate how certification hierarchies and sourcing transparency separate competitive positions in a market where bioactive standardization is compressing pure origin premiums.
| Leading Market Players |
|---|
| Nature's Way |
| Swanson Health Products |
| NOW Health Group |
| Life Extension |
| GNC Holdings |
| Epicure Garden |
| Lean Nutraceuticals |
| LUMA Nutrition |
| Persavita |
| Others |
Value Network & Pricing Analysis
Cold-extraction process adoption is simultaneously elevating production costs for premium-tier suppliers and concentrating margin capture among manufacturers with in-house encapsulation capabilities. This technical bifurcation rewards backward-integrated players while forcing contract-dependent brands into commodity positioning.
Pricing Analysis
Subscription-direct models versus pharmacy impulse purchases split the pricing architecture. Three-tier pricing structure across premium, standard, and economy levels separates USP-verified clinical extracts from mass-market capsules and unbranded bulk powders. Price differentiation hinges on certification grade and volume scale. Cost compression in the standard tier is intensifying because synthetic carotenoid substitutes undercut botanical input costs. Health enthusiasts show highest price sensitivity, while clinician-referred patients accept premium positioning for batch-documented potency.
Supply Chain Analysis
Regional distribution centers in Los Angeles, Toronto, and New York anchor hub-and-spoke patterns for finished goods fulfillment. Geographic supply concentration centers on Iran, Afghanistan, and emerging domestic cultivation in Ontario and Quebec. Raw material dependencies include Crocus sativus stigmas, hydroalcoholic extraction solvents, and vegetable-based capsule shells. Single-source vulnerability from Iranian Khorasan province concentration exposes importers to geopolitical disruption. Distribution runs through pharmacy chains, direct-to-consumer platforms, and practitioner portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American saffron supplements constitute a late-cycle quality story where wellness consumers now demand verifiable bioactive standardization over origin marketing. This specification shift favors suppliers with captive laboratory infrastructure and third-party certification relationships.
For Market Incumbents: To counter synthetic carotenoid substitution in mass-market capsules, secure upstream stigma sourcing through cultivation partnerships in Ontario and Quebec while expanding USP verification coverage across pharmacy distribution. Channel control through practitioner portal development represents the priority defensive investment. For New Entrants and Emerging Players: Health Canada's Natural and Non-prescription Health Products Directorate site license requirements open a window for US-registered suppliers with existing compliance infrastructure to capture Canadian pharmacy shelf space. Target the naturopathic clinic channel in Texas and New York with clinical-strength liquid extracts. Practitioner-guided subscription models offer the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier contract manufacturers lacking chromatographic testing capabilities. Long-term viability favors acquisition targets with Health Canada registrations and organic certification pathways. Watch for Iranian supply disruption signals as the primary inflection indicator for domestic cultivation premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| USP Verification Adoption | Third-party potency certification enables pharmacy shelf differentiation against uncertified competitors. |
| Backward Integration into Cultivation | Ontario and Quebec organic acreage expansion reduces import dependency for Canadian manufacturers. |
| Practitioner Portal Development | Telehealth-integrated ordering systems capture nutritionist-guided patient segments with highest retention. |
| Cold-Extraction Capacity Expansion | Preservation of volatile safranal compounds justifies premium positioning in mood-support formulations. |
| Digital Traceability Infrastructure | Batch-level provenance authentication converts supply chain transparency into baseline purchase qualifier. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each market gathered through structured interviews with supplement brand executives, contract manufacturing facility managers, naturopathic practitioners, and pharmacy category buyers. Secondary validation draws from FDA Current Good Manufacturing Practice enforcement records, Health Canada Natural and Non-prescription Health Products Directorate licensing databases, USDA organic certification registries, and California Proposition 65 settlement disclosures. Bottom-up demand modeling triangulates against top-down supply-side capacity assessments.
Granularity-level modeling applies product type, end user sophistication tier, distribution channel, and formulation certification dimensions at the country-subregion level. Value projections across the analysis window compound annual growth rates derived from historical price trajectory analysis and penetration rate assumptions for subscription-direct channels. Industry-specific forecast inputs include Iranian harvest yield variability patterns and USP verification program adoption curves.
Revisions become necessary when Iranian supply disruption, synthetic substitute regulatory reclassification, or major retailer certification requirement changes materialize. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Phytoceramide Supplement Market
Nutritional Supplements
Fiber Supplements Market
Nutritional Supplements
Andro Supplements Market
Nutritional Supplements
Japan Whey Protein Market
Nutritional Supplements
Fitness Cookies Market
Nutritional Supplements
Tocotrienol Market
Nutritional Supplements
Asia-Pacific Amino Acid in Dietary Supplements Market
Nutritional Supplements
Spirulina Powder Market
Nutritional Supplements
Asia-Pacific Digestive Health Supplements Market
Nutritional Supplements
Vegan Vitamins and Supplements Market
Nutritional Supplements
Microencapsulated Omega-3 Powders Market
Nutritional Supplements
Activated Charcoal Supplement Market
Nutritional Supplements
Vegetable Capsules Market
Nutritional Supplements
Middle-East and Africa Dietary Supplement Market
Nutritional Supplements
Human Milk Oligosaccharides (HMO) Market
Nutritional Supplements
Nutritional Supplements Market