
 North America Protein Ingredients Market | 2026-2036
North America Protein Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
North America Protein Ingredients Market Intelligence
Subscription-based personalized protein dosing platforms is decoupling bulk commodity sales from recurring revenue models across the North American supply chain. Cargill, Incorporated leverages its captive soy processing infrastructure to anchor ingredient consistency for co-manufacturers. DuPont sustains R&D intensity in microbial fermentation pathways for novel protein expression. Glanbia plc dominates the whey protein isolate segment through its Cheese & Whey division's vertical integration into dairy cooperative networks.
North America protein ingredients encompass nitrogenous macromolecules derived from animal, plant, and microbial sources, typically standardized to minimum protein content thresholds of 80-90% on a dry-weight basis for isolates, with functional attributes including emulsification, gelation, and water-binding capacity that enable texture engineering in processed foods. Whey protein commands the largest revenue pool due to its complete amino acid profile and rapid absorption kinetics favored by sports nutrition formulators, while pea protein exhibits the fastest volume trajectory as sustainability-conscious brands reformulate away from allergen-containing alternatives. Powder forms occupy the dominant share of commercial shipments owing to superior shelf stability and freight economics, though liquid concentrates are gaining traction in ready-to-drink manufacturing channels.
The FDA's evolving stance on protein quality labeling, USDA's oversight of organic protein certification pathways, and Health Canada's novel food regulations for alternative proteins collectively shape product development timelines and cross-border market access protocols. State-level clean-label mandates in California and New York further constrain permissible processing aids and extraction solvents. Stakeholders must monitor pending regulatory determinations on precision-fermented protein classification to align capital deployment with anticipated compliance frameworks.
Market Dynamics
The FDA's transition from PDCAAS to DIAAS scoring standards is compressing formulation timelines while forcing manufacturers to rebuild analytical capabilities around ileal digestibility assays rather than fecal protein recovery methods.
Growth Catalysts
- Precision Fermentation Scale-Up:Microbial expression platforms for whey-equivalent proteins are attracting California-based venture capital into Canadian biomanufacturing facilities.
- USDA Organic Certification Pathways:Expanded organic protein acreage across the Midwest agricultural belt is securing non-GMO supply contracts for infant nutrition formulators.
- Health Canada Novel Food Stream:Accelerated approval timelines for alternative protein sources are enabling faster cross-border product launches between Ontario and US Great Lakes markets.
Market Restraints
- Input Cost Volatility:Yellow pea protein concentrate pricing fluctuates with Canadian prairie drought cycles and rail freight bottlenecks through Calgary-Minneapolis corridors.
- Supply Concentration Risk:Three processors control over seventy percent of US whey protein isolate capacity, creating single-source vulnerability for sports nutrition brands.
- Technical Limitation:Current extraction solvents fail to achieve comparable functional properties between organic and conventional soy protein isolates.
Strategic Opportunities
- Mexico Market Underpenetration:Functional food brands are establishing Monterrey distribution hubs to capture emerging middle-class protein supplementation demand.
- Subscription Direct-to-Consumer Channels:Personalized dosing algorithms are displacing bulk commodity purchasing among endurance athlete segments.
- Biomanufacturing Tax Incentives:California's clean technology credits are offsetting capital costs for precision fermentation facility construction in Sacramento Valley industrial parks.
Industry Challenges
- Analytical Talent Scarcity:DIAAS assay expertise remains concentrated among a handful of contract research organizations, extending third-party validation timelines.
- Legacy Equipment Retrofit Costs:Existing spray-drying infrastructure requires six-figure modifications to handle novel protein rheologies without denaturation.
- Cross-Border Label Harmonization:Divergent protein quality declaration requirements between FDA and Health Canada force dual-SKU inventory strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Protein Ingredients Market |
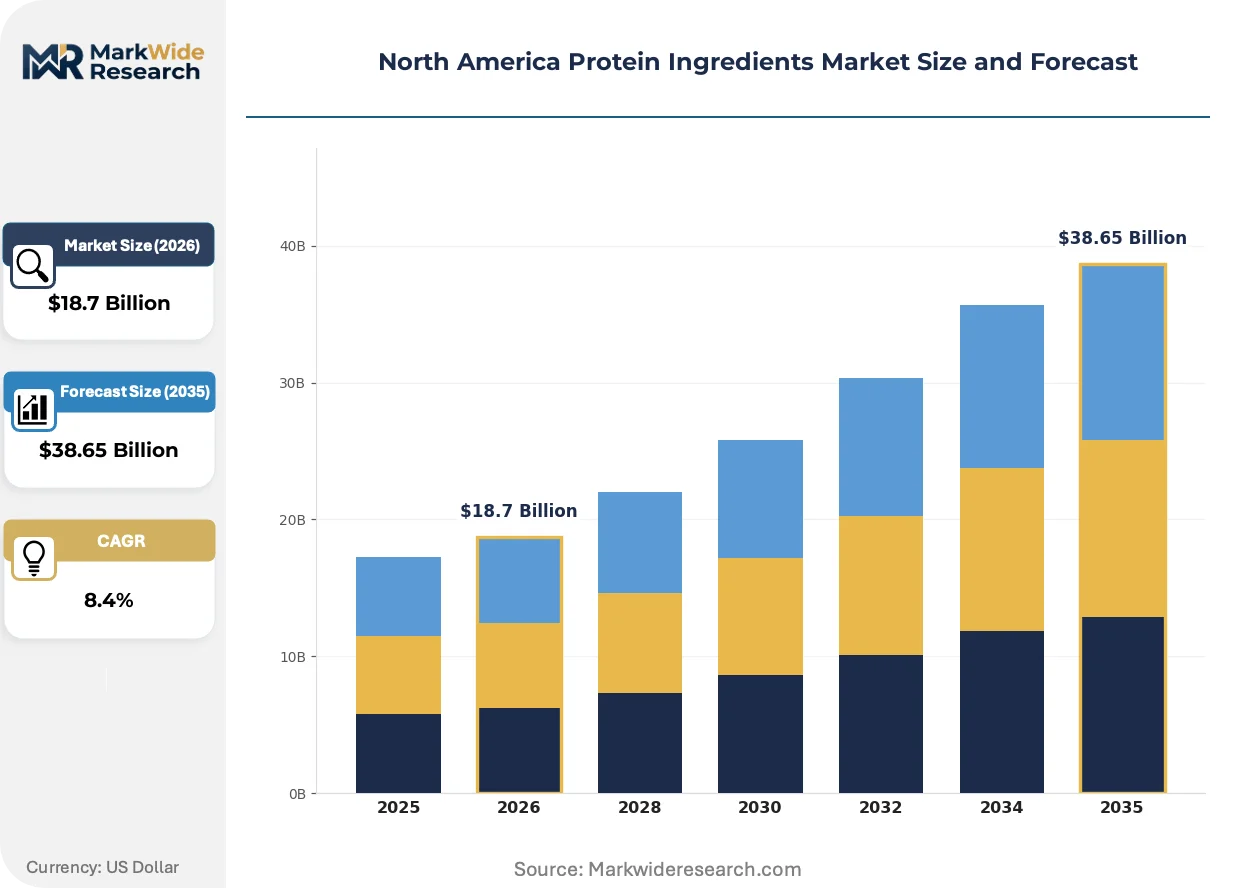
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Soy Protein, Casein Protein, Pea Protein Application: Nutrition Bars, Protein Drinks, Supplements, Bakery Products Form: Powder, Liquid, Granulated, Isolate Customer Type: Fitness Enthusiasts, Bodybuilders, Health-conscious Consumers, Athletes |
| Companies Covered | The Scoular Company, DuPont, Ingredion, Glanbia plc, Burcon, Archer Daniels Midland Company, International Flavors & Fragrances Inc., CHS Inc., Cargill, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Protein Ingredients Market Strategic Shifts & Innovations
Hybrid protein matrices combining animal-derived and microbial sources are collapsing traditional category boundaries while forcing reformulation of established sensory testing protocols across North American manufacturing networks.
Cell-cultured dairy protein expression is unifying amino acid completeness with sustainability credentials previously associated exclusively with plant sources. Sports nutrition formulators in Utah and Colorado are piloting these ingredients at commercial scale. This convergence is unifying supply chain transparency requirements that previously separated conventional and alternative protein procurement teams.
The FDA's updated nutrition labeling requirements for protein quality scoring are mandating DIAAS disclosure on packaged foods by 2026. Food manufacturers are rebuilding analytical workflows around true ileal digestibility rather than crude protein measurement. Infant formula producers face the steepest compliance curve given existing PDCAAS-optimized formulation libraries.
Direct-to-consumer subscription models are compressing traditional distributor margins while capturing recurring revenue from performance-oriented consumers. Bulk commodity purchasing through co-manufacturing networks is losing share to algorithm-driven personalized dosing platforms. California's functional food corridor exhibits the fastest channel migration as digitally native brands bypass conventional retail slotting fee structures.
North America Protein Ingredients Market Segmentation
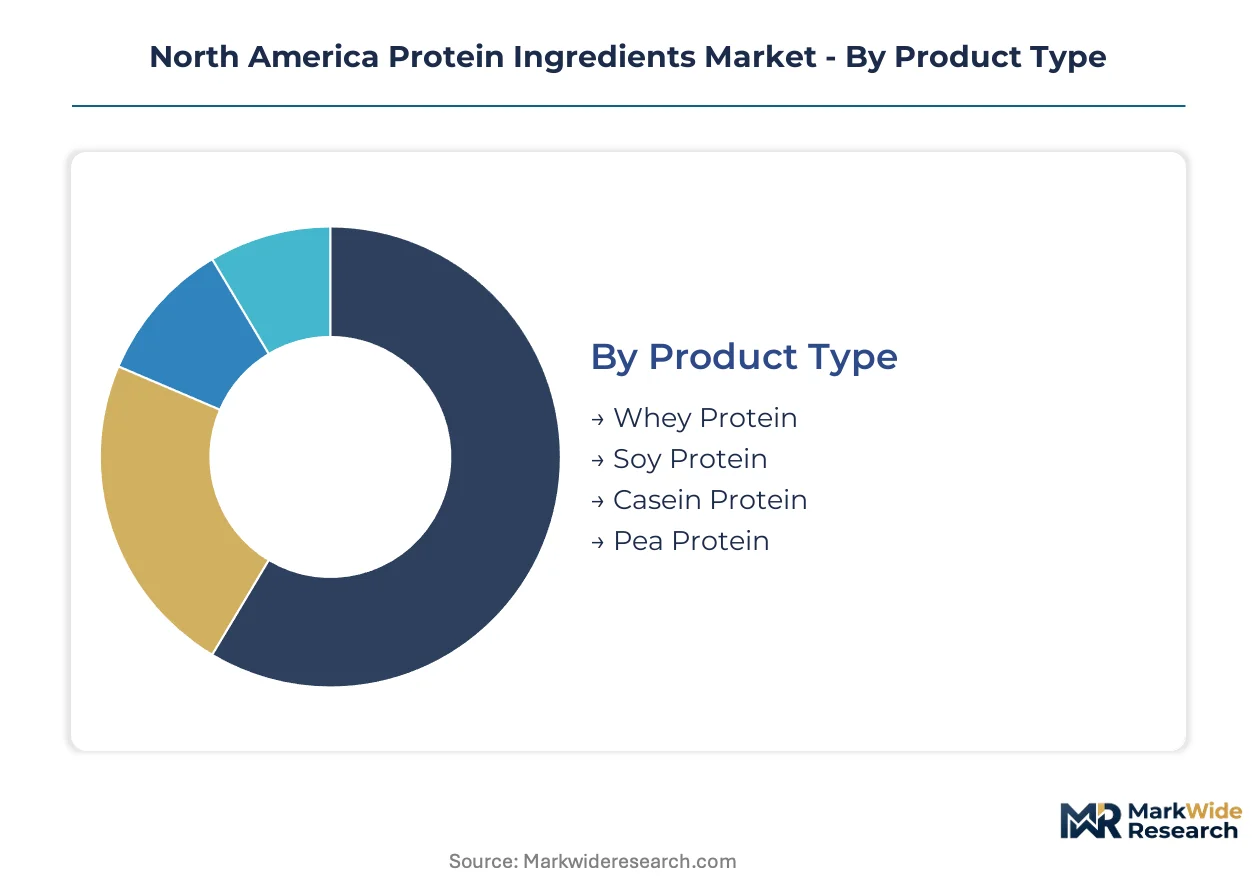
Protein ingredient procurement strategies diverge sharply across segment boundaries in North America, with certification requirements and functional specifications dictating supplier qualification protocols. Formulators must align R&D pipelines with distinct regulatory pathways that vary by protein source and end-use application.
Product Type:
FDA's novel food determinations and USDA organic certification burdens fall unevenly across protein sources, with microbial and plant-derived categories facing steeper compliance curves than established dairy fractions.
- Whey Protein:Complete amino acid profile with rapid absorption kinetics standardized to 80-90% protein content on dry-weight basis. Sports nutrition formulators in Utah and Colorado concentrate demand here, though three processors control over seventy percent of US isolate capacity, creating procurement vulnerability.
- Soy Protein:Functional isolates and concentrates derived from defatted soybean flakes with established emulsification properties. Infant nutrition contracts across the Midwest agricultural belt drive organic certification investments, though extraction solvent limitations constrain clean-label positioning versus conventional grades.
- Casein Protein:Slow-digesting micellar structures favored by overnight recovery formulations.
- Pea Protein:Hypoallergenic alternative gaining traction in allergen-free reformulations.
Whey protein sits at the top of the volume ranking, with pea protein climbing the fastest.
Application:
End-use categories separate by moisture activity requirements, shelf stability demands, and the intensity of Health Canada versus FDA labeling obligations.
- Nutrition Bars:Intermediate moisture systems requiring protein binding and texture engineering through controlled denaturation. California's functional food corridor dominates innovation here, with digitally native brands bypassing conventional retail slotting structures through direct-to-consumer channels.
- Protein Drinks:Ready-to-drink formulations demanding cold-chain distribution or aseptic processing capabilities. Liquid concentrate forms are gaining manufacturing traction in this segment, though powder formats retain freight economics advantages for shelf-stable variants.
- Supplements:Powder-based delivery systems with minimal processing aid tolerance.
- Bakery Products:Heat-stable fractions required for Maillard reaction compatibility.
Supplements capture the largest revenue pool, with protein drinks expanding most quickly.
Form:
Physical presentation determines logistics infrastructure requirements and co-manufacturing compatibility across the North American supply chain.
- Powder:Dominant commercial format with superior shelf stability and bulk freight economics. Spray-drying infrastructure across the Midwest agricultural belt requires six-figure retrofit investments to handle novel protein rheologies without denaturation.
- Liquid:Concentrated suspensions for ready-to-drink manufacturing integration. Sports nutrition brands in Canada and the United States are expanding formulation trials here, though cold-chain requirements constrain distribution reach.
- Granulated:Agglomerated particles for improved dispersibility in beverage systems.
- Isolate:Refined fractions exceeding 90% protein content with minimal lipid and carbohydrate carryover.
Powder commands the volume lead, with liquid concentrates gaining share fastest.
Customer Type:
Consumer segments separate by dosing precision requirements, subscription propensity, and sensitivity to protein quality scoring methodology transitions.
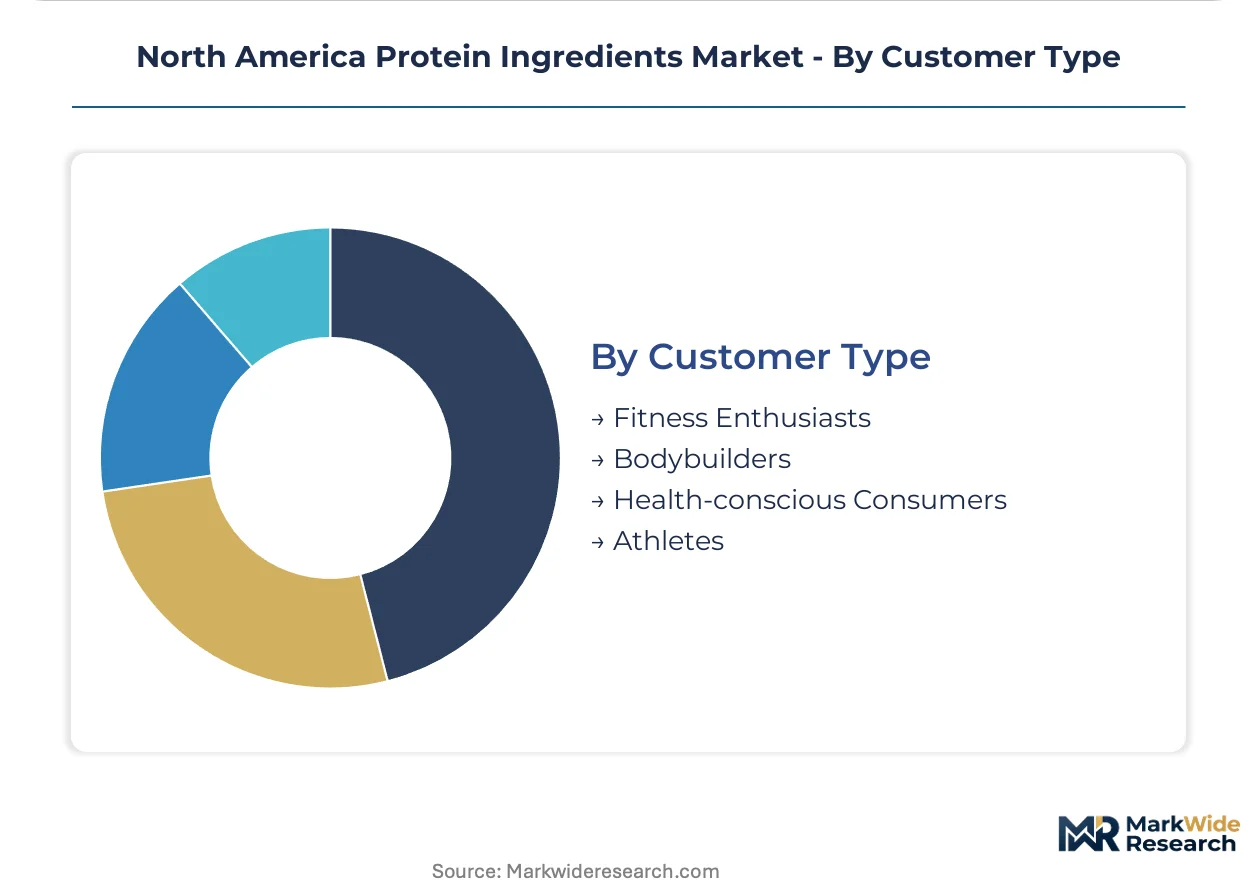
- Fitness Enthusiasts:Recreational athletes seeking convenient protein supplementation without competitive dosing protocols. Algorithm-driven personalized dosing platforms are displacing bulk commodity purchasing among this segment, compressing traditional distributor margins.
- Bodybuilders:High-volume consumers prioritizing leucine content and absorption kinetics. PDCAAS-to-DIAAS measurement transitions force reformulation of existing product libraries for this precision-oriented group.
- Health-conscious Consumers:Clean-label seekers prioritizing organic certification and allergen avoidance.
- Athletes:Endurance and team sport competitors with regulated substance testing requirements.
Fitness enthusiasts represent the broadest addressable base, with health-conscious consumers showing the steepest channel migration toward subscription models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's protein ingredient infrastructure outpaces Mexico's emerging capacity, while the United States concentrates the bulk of precision fermentation investment and whey processing scale across the continent.
United States
California's functional food corridor drives demand for plant-based and microbial proteins, with Utah and Colorado sports nutrition clusters expanding formulation trials. FDA's DIAAS scoring mandate by 2026 compresses analytical workflow rebuilds for infant formula producers. The Midwest agricultural belt anchors soy and whey processing infrastructure, though three processors control over seventy percent of isolate capacity.
Canada
Prairie provinces supply yellow pea protein concentrate to cross-border formulators, with Ontario biomanufacturing facilities attracting California venture capital for precision fermentation scale-up. Health Canada's novel food regulations enable accelerated approval timelines for alternative proteins. Rail freight bottlenecks through Calgary-Minneapolis corridors create input cost volatility during drought cycles.
Mexico
Monterrey distribution hubs capture emerging middle-class protein supplementation demand as functional food brands establish southern supply chain nodes. The country's national food safety regulator oversees import protocols for US and Canadian ingredient shipments. Northern border states concentrate maize-derived protein processing for regional bakery and beverage applications.
North America Protein Ingredients Market Key Industry Players
Top-tier vendors anchor whey and soy commodity supply, while mid-tier specialists and precision fermentation startups compete on novel protein expression and clean-label positioning. Supply concentration risk pervades the whey protein isolate segment where limited processing capacity creates procurement vulnerability. Strategic archetypes include captive agricultural processors, dairy cooperative-integrated nutrition houses, and venture-backed microbial expression platforms. Dominant competitive moves center on backward integration into raw material supply and biomanufacturing facility construction leveraging state-level tax incentives.
Among agricultural processors with captive infrastructure, Cargill, Incorporated and Archer Daniels Midland Company exemplify the scale-driven archetype through their Midwest soy processing networks. DuPont occupies a position within the innovation tier, representing R&D-intensive players exploring microbial fermentation pathways. Glanbia plc anchors the dairy-integrated segment through its Cheese & Whey division's upstream control over cooperative supply networks.
| Leading Market Players |
|---|
| The Scoular Company |
| DuPont |
| Ingredion |
| Glanbia plc |
| Burcon |
| Archer Daniels Midland Company |
| International Flavors & Fragrances Inc. |
| CHS Inc. |
| Cargill, Incorporated |
| Others |
Cost & Logistics Intelligence
Sports nutrition brands concentrated in Utah and Colorado operate on contract-based long-term offtake agreements that anchor pricing stability against spot-market volatility in whey protein isolates. Their procurement power compresses margins for mid-tier suppliers while rewarding processors with captive dairy cooperative networks.
Pricing Analysis
Capacity additions in Canadian prairie provinces are reshaping price floors for yellow pea protein concentrate as drought cycles and rail freight bottlenecks through Calgary-Minneapolis corridors inject volatility. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified isolates from conventional grades and commodity concentrates. Cost compression in economy-tier soy protein is intensifying because extraction solvent limitations constrain clean-label positioning. Fitness enthusiasts show highest price sensitivity through algorithm-driven subscription platforms, while infant nutrition formulators exhibit lowest sensitivity due to regulatory compliance burdens.
Supply Chain Analysis
USDA organic certification and FDA novel food determinations gate supplier qualification, extending procurement timelines for microbial and plant-derived categories relative to established dairy fractions. Supply concentrates in the United States, Canada, and Mexico, with the Midwest agricultural belt anchoring soy and whey processing infrastructure. Raw material dependencies include defatted soybean flakes, yellow pea cultivars from prairie provinces, and dairy cooperative milk supplies. Single-source vulnerability pervades whey protein isolate procurement where three processors control dominant capacity. Distribution runs through co-manufacturing networks and direct-to-consumer subscription platforms with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as DIAAS scoring mandates force reformulation investments that favor processors with analytical capabilities and certified supply chains over commodity traders.
For Market Incumbents: Extend backward integration into dairy cooperative networks and organic protein acreage across the Midwest agricultural belt to defend against precision fermentation startups capturing sustainability-conscious brand relationships. Anchor ingredient consistency through captive soy processing infrastructure that co-manufacturers depend upon. Prioritize R&D intensity in microbial fermentation pathways before venture-backed competitors achieve commercial scale. For New Entrants and Emerging Players: The premium-economy price gap in organic soy protein isolates creates white-space opportunity as extraction solvent limitations constrain incumbent clean-label positioning. Target Mexico's emerging middle-class protein supplementation demand through Monterrey distribution hubs with functional food formulations bypassing saturated US retail channels. Pursue Health Canada novel food approval pathways to enable faster cross-border product launches between Ontario and US Great Lakes markets. For Investors and Strategic Acquirers: Agricultural processors with captive infrastructure are the most active acquirer in this space, consolidating Midwest soy processing networks and dairy cooperative relationships. Five-to-ten year viability hinges on positioning against precision fermentation scale-up and DIAAS analytical capability concentration. Monitor California venture capital deployment into Canadian biomanufacturing facilities as the signal indicating microbial expression platform maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dairy Cooperative Networks | Glanbia plc's Cheese & Whey division secures upstream control over milk supply quality and volume commitments. |
| Precision Fermentation Facility Construction | DuPont leverages California clean technology credits to offset capital costs in Sacramento Valley industrial parks. |
| Organic Certification Pathway Investment | Midwest agricultural belt acreage expansion secures non-GMO supply contracts for infant nutrition formulators. |
| Direct-to-Consumer Subscription Platform Launch | Digitally native brands in California's functional food corridor bypass conventional retail slotting fee structures. |
| DIAAS Analytical Capability Buildout | Contract research organizations with ileal digestibility expertise extend validation timelines and pricing power. |
Research Approach
Coverage spans the United States, Canada, and Mexico, with primary inputs from each market combining executive interviews with sports nutrition formulators, dairy cooperative procurement leads, plant protein extraction engineers, infant nutrition regulatory affairs directors, and precision fermentation startup founders. Secondary validation draws from FDA filings, USDA organic certification databases, Health Canada novel food determinations, and SEC disclosures from listed ingredient processors. Bottom-up volume modeling triangulates against top-down protein consumption trend analysis.
Rate-of-change decomposition separates volume trajectory from value expansion across the projection horizon, with segmentation modeling across protein source, application, physical form, and customer archetype. CAGRs derive from regression analysis against historical pricing volatility in yellow pea protein concentrate and whey isolate capacity utilization rates. Industry-specific forecast inputs include prairie province drought frequency indices and California venture capital deployment into biomanufacturing.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation scale-up would alter the outlook if microbial expression achieves cost parity with dairy-derived isolates faster than projected. Forecasts reflect assumptions around regulatory harmonization timelines and organic acreage expansion rates. A model refresh is warranted upon material change in FDA protein quality scoring implementation schedules or Health Canada novel food approval velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Soy and Milk Protein Ingredients Market
Ingredients
North America Sodium Reduction Ingredients Market
Ingredients
North America Rice Bran Oil Market
Ingredients
Dried Tomato Lycopene-Rich Flake Ingredients Market
Ingredients
Global Infant Nutrition Ingredients Market
Ingredients
South America Soy Protein Ingredients Market
Ingredients
Pea Protein Ingredients Industry Status and Prospects Professional Market
Ingredients
Global Vitamin Ingredients Market
Ingredients
Corn Oil Market
Ingredients
Low Calorie Oil Market
Ingredients
Encapsulated Salt Market
Ingredients
L-Arabinose Market
Ingredients
Industrial Sugar Market
Ingredients
Amylase Market
Ingredients
Vegetable Powder Market
Ingredients
Carotenoids Market