
 Hydrolyzed Animal Protein Market | 2026-2036
Hydrolyzed Animal Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrolyzed Animal Protein Market Analysis
Enzyme engineering talent is bifurcating the competitive landscape as specialized biochemists become scarce across fermentation hubs. Novozymes A/S leverages its Danish R&D base to sustain enzymatic hydrolysis leadership. GELITA anchors European gelatin-derived protein capacity through controlled manufacturing scale. Kerry, Inc. competes by extending flavor-masked protein systems into functional beverage formulations.
Hydrolyzed animal protein denotes polypeptide mixtures derived from collagen, gelatin, or muscle tissue via acid, alkaline, or enzymatic cleavage, typically achieving molecular weights below 10 kDa for enhanced bioavailability and solubility. These ingredients serve primarily as nitrogen sources in clinical nutrition, texture modifiers in processed foods, and bioactive precursors in dermal formulations. Hydrolyzed collagen occupies the largest revenue pool among product types due to established nutraceutical channel penetration. Functional foods represents the fastest-growing application segment as manufacturers seek protein fortification without sensory compromise. Powder form dominates current production volumes, though liquid concentrates gain traction in ready-to-drink formulations.
EFSA novel food classifications determine market access timelines for new hydrolyzed protein sources entering European commerce. FDA GRAS self-determination pathways govern U.S. ingredient introductions, while USDA oversight applies to protein destined for animal feed applications. Brazil's ANVISA regulates pharmaceutical-grade hydrolysates through bioequivalence requirements that diverge from food-grade standards. Stakeholders must monitor evolving enzymatic processing claims as regulators scrutinize hydrolysis method disclosures on consumer labels.
Market Dynamics
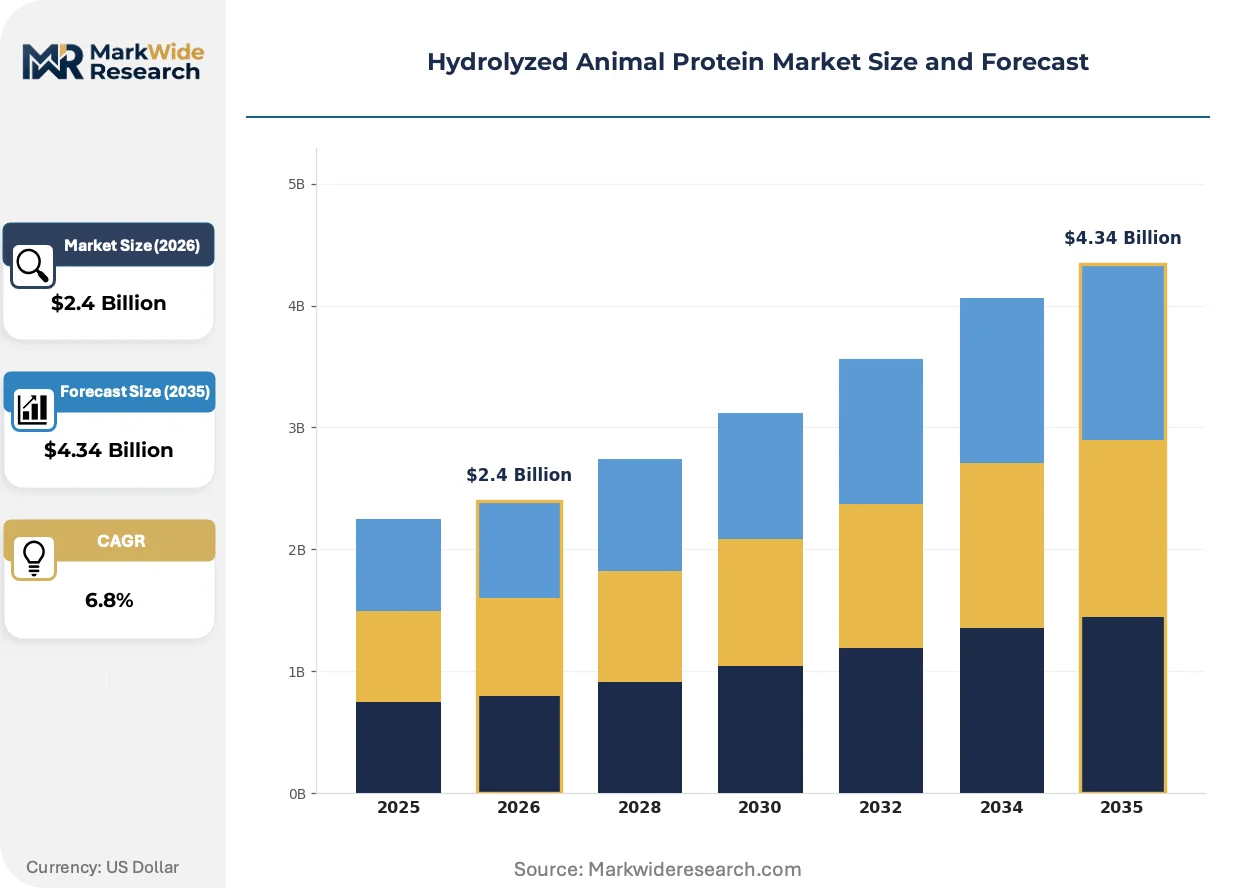
Enzyme engineering talent scarcity is concentrating competitive advantage among fermentation hubs that retain specialized biochemists, while EFSA novel food pathways reshape ingredient approval timelines for entrants seeking European market access.
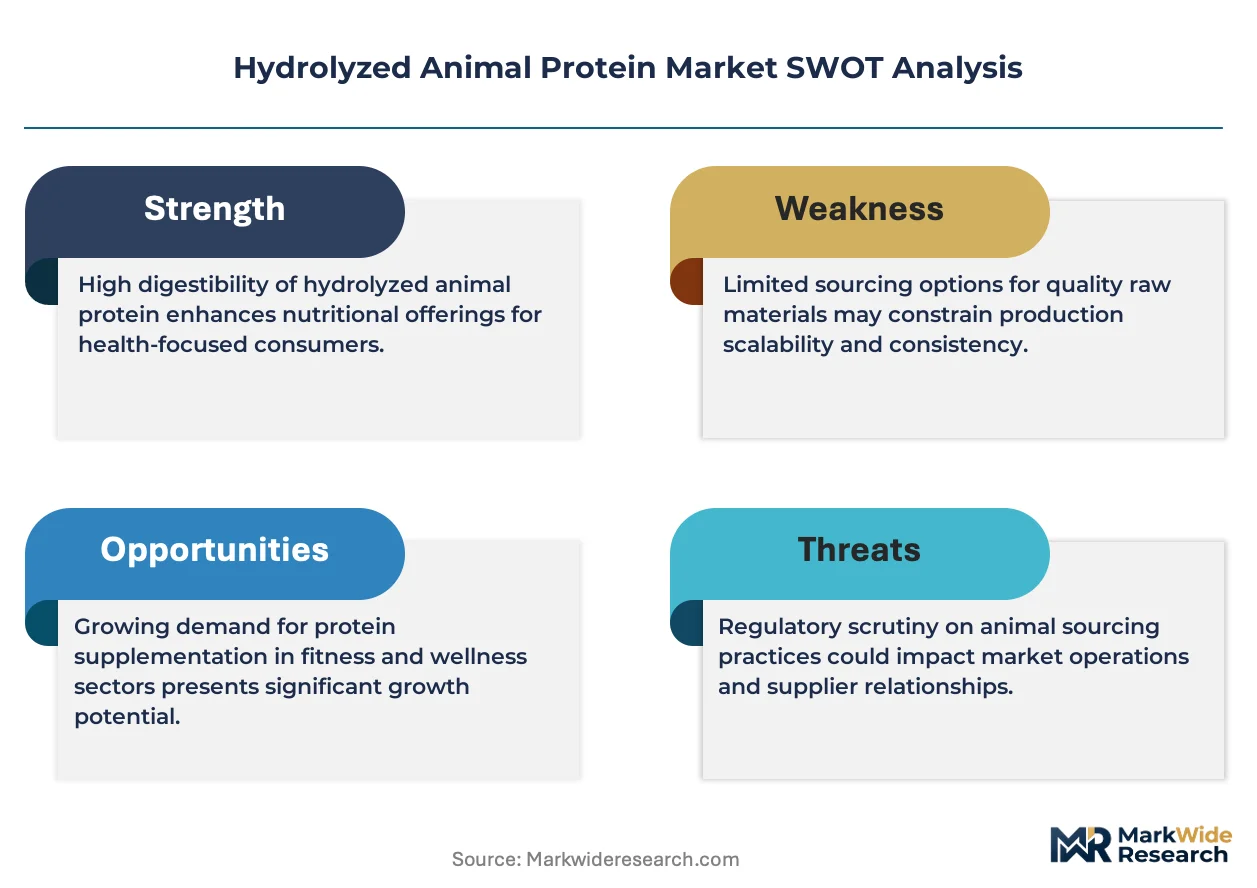
Growth Catalysts
- EFSA Novel Food Classifications:The European framework accelerates approval for hydrolyzed collagen sources with established safety dossiers, reducing time-to-market for compliant entrants.
- Brazil Aquaculture Expansion:ANVISA bioequivalence requirements for pharmaceutical-grade hydrolysates create dual-grade manufacturing incentives serving both feed and clinical nutrition channels.
- Clean-Label Pet Food Reformulation:North American manufacturers are displacing synthetic nitrogen sources with hydrolyzed protein systems in premium kibble and wet food lines.
Market Restraints
- Gelatin Feedstock Volatility:Bovine hide and porcine skin supply fluctuations in Brazil and Argentina create input cost instability for collagen-derived hydrolysates.
- Enzymatic Process Concentration:Danish and German fermentation clusters control specialty protease supply, creating geographic single-source risk for acid-to-enzyme conversion adopters.
- Alkaline Hydrolysis Substitution:Lower-capital acid and alkaline methods persist in commodity markets, compressing price realization for enzymatic premium grades.
Strategic Opportunities
- Functional Beverage Fortification:Flavor-masked protein concentrates enable clean-label protein waters and sports drinks without sensory compromise.
- USDA Animal Feed Pathway:Self-affirmed GRAS status for hydrolyzed feather and blood meal opens bypass routes around FDA novel food scrutiny for non-human applications.
- Dermal Bioactive Precursors:Cosmetic formulators in South Korea and Japan are integrating sub-3 kDa collagen peptides into topical delivery systems.
Industry Challenges
- Bioprocess Engineering Talent Gap:Fermentation scale-up expertise resides in legacy pharmaceutical hubs, forcing protein specialists to compete for constrained hiring pools.
- Dual-Grade Certification Complexity:Manufacturers serving both food and pharmaceutical channels must maintain parallel ANVISA and FDA compliance systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrolyzed Animal Protein Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Gelatin, Whey Protein, Fish Protein Application: Nutraceuticals, Functional Foods, Animal Feed, Cosmetics End User: Food Industry, Pharmaceutical Companies, Cosmetic Manufacturers, Pet Care Form: Powder, Liquid, Granules, Tablets |
| Companies Covered | Fonterra Co-operative Group, Kemin Industries, Inc., Arla Foods Ingredients Group P/S, Lactalis Ingredients, Kerry, Inc., BRF S.A., GELITA, Novozymes A/S, Cargill, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrolyzed Animal Protein Market Emerging Trajectories
Processing technology divergence and regulatory pathway fragmentation are actively reconfiguring how hydrolyzed animal proteins achieve commercial scale and geographic access.
Precision enzymatic hydrolysis is bifurcating the competitive landscape between high-bioavailability nutraceutical grades and commodity feed applications. Pet food manufacturers and clinical nutrition formulators are adopting molecular-weight-controlled systems at divergent investment thresholds. This technology compression is enabling mid-scale entrants to bypass acid-hydrolysis incumbents in premium segments.
EFSA's 2023 updated guidance on collagen peptide novel food dossiers is extending approval timelines for non-bovine sources. The industrial consequence is a qualification backlog for porcine and marine-derived entrants seeking European distribution. Hydrolyzed fish collagen suppliers are responding by prioritizing Asian regulatory pathways ahead of European submissions.
Ingredient buyers are consolidating supplier relationships around vertically integrated producers with captive raw material streams. Distributors serving small-batch cosmetic and sports nutrition formulators are being displaced by direct procurement contracts. This concentration is most visible in German and French markets where clean-label certification requirements favor traceable supply chains.
Hydrolyzed Animal Protein Market Segmentation
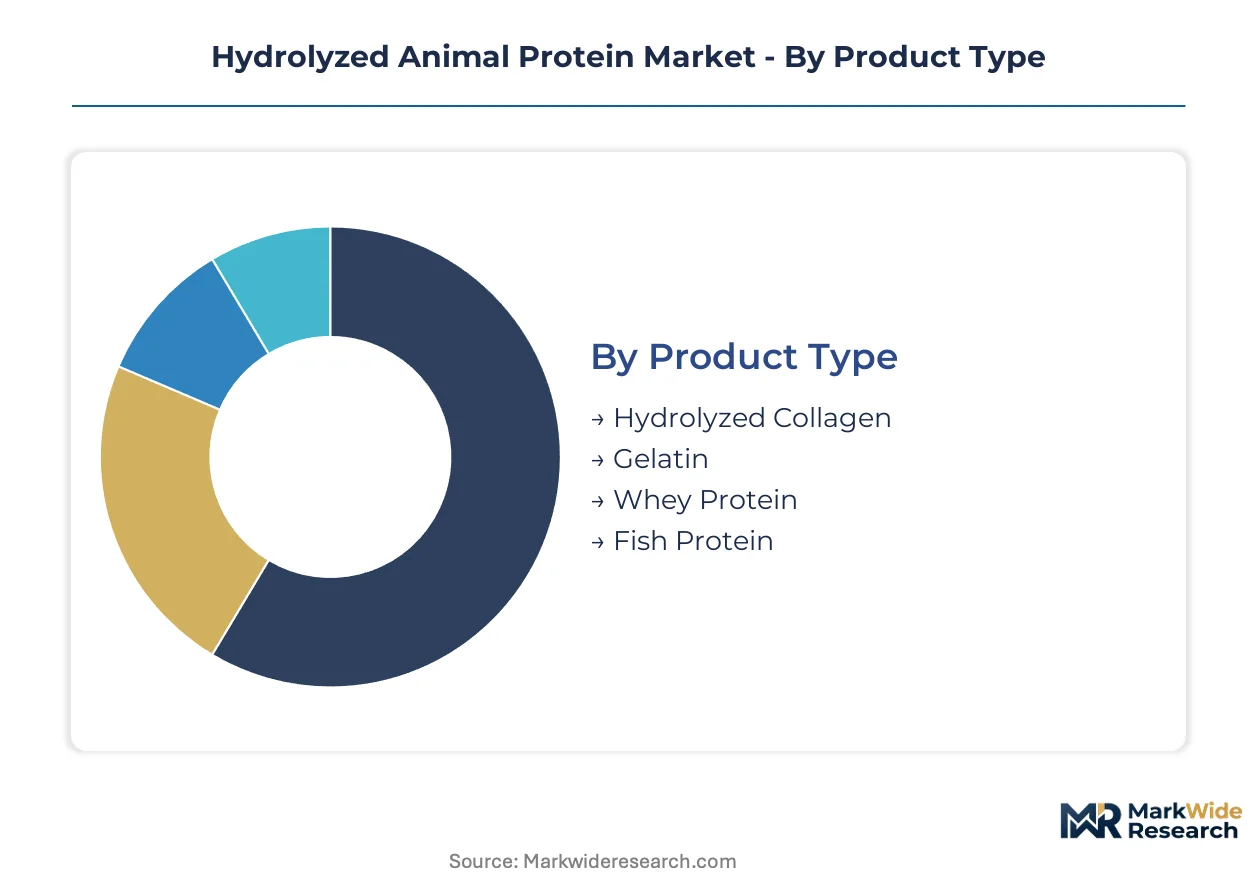
Segmentation in hydrolyzed animal proteins reveals divergent margin structures across molecular weight grades and end-use certifications. Nutraceutical buyers command premium pricing for bioactive peptide fractions, while feed applications compete on nitrogen content density.
Product Type:
Margin pools concentrate in enzymatically processed grades where molecular weight control commands certification premiums over acid-hydrolyzed commodity streams.
- Hydrolyzed Collagen:Peptide mixtures derived from bovine hide or porcine skin achieving sub-10 kDa molecular weights for enhanced bioavailability. Demand concentrates in German and French nutraceutical channels where EFSA novel food dossiers favor established bovine sources with complete toxicology profiles.
- Gelatin:Partially hydrolyzed collagen retaining gelling functionality at higher molecular weight ranges. Brazilian and Argentinian tannery byproduct supply volatility creates input cost instability for European hydrolysate manufacturers dependent on South American feedstock.
- Whey Protein:Lactalbumin and lactoglobulin fractions hydrolyzed via microbial proteases for reduced allergenicity.
- Fish Protein:Marine collagen and muscle tissue hydrolysates processed for cosmetic and clinical nutrition applications.
Hydrolyzed collagen holds installed capacity. Fish protein is rotating up the share rankings.
Application:
Application tiering separates pharmaceutical-grade bioequivalence requirements from feed-grade nitrogen specifications, with functional foods occupying the intermediate certification bandwidth.
- Nutraceuticals:Capsule and tablet formulations delivering sub-3 kDa collagen peptides for dermal and joint health positioning. South Korean and Japanese cosmetic formulators are integrating these fractions into topical delivery systems with documented percutaneous absorption.
- Functional Foods:Flavor-masked protein concentrates enabling clean-label fortification in ready-to-drink beverages and sports nutrition. North American manufacturers are reformulating protein waters and recovery drinks without sensory compromise through advanced enzymatic masking technologies.
- Animal Feed:Feather meal and blood meal hydrolysates serving aquaculture and livestock nitrogen requirements.
- Cosmetics:Bioactive precursors in dermal formulations targeting anti-aging and barrier repair positioning.
Nutraceuticals holds installed capacity. Functional foods is climbing the fastest.
End User:
Customer concentration patterns track regulatory pathway complexity, with pharmaceutical and pet care channels demanding parallel compliance systems that raise supplier switching costs.
- Food Industry:Processed meat, dairy, and bakery applications requiring texture modification and protein fortification. Brazilian ANVISA food-grade standards govern hydrolysate incorporation into shelf-stable formulations for domestic consumption and export.
- Pharmaceutical Companies:Clinical nutrition and enteral feeding applications requiring bioequivalence documentation and batch-level traceability. Dual-grade manufacturers serving this channel must maintain separate ANVISA and FDA compliance systems with divergent documentation protocols.
- Cosmetic Manufacturers:Topical and dermal formulation houses in East Asian markets.
- Pet Care:Premium kibble and wet food reformulation displacing synthetic nitrogen sources.
Food industry holds installed capacity. Pet care is rotating up the share rankings.
Form:
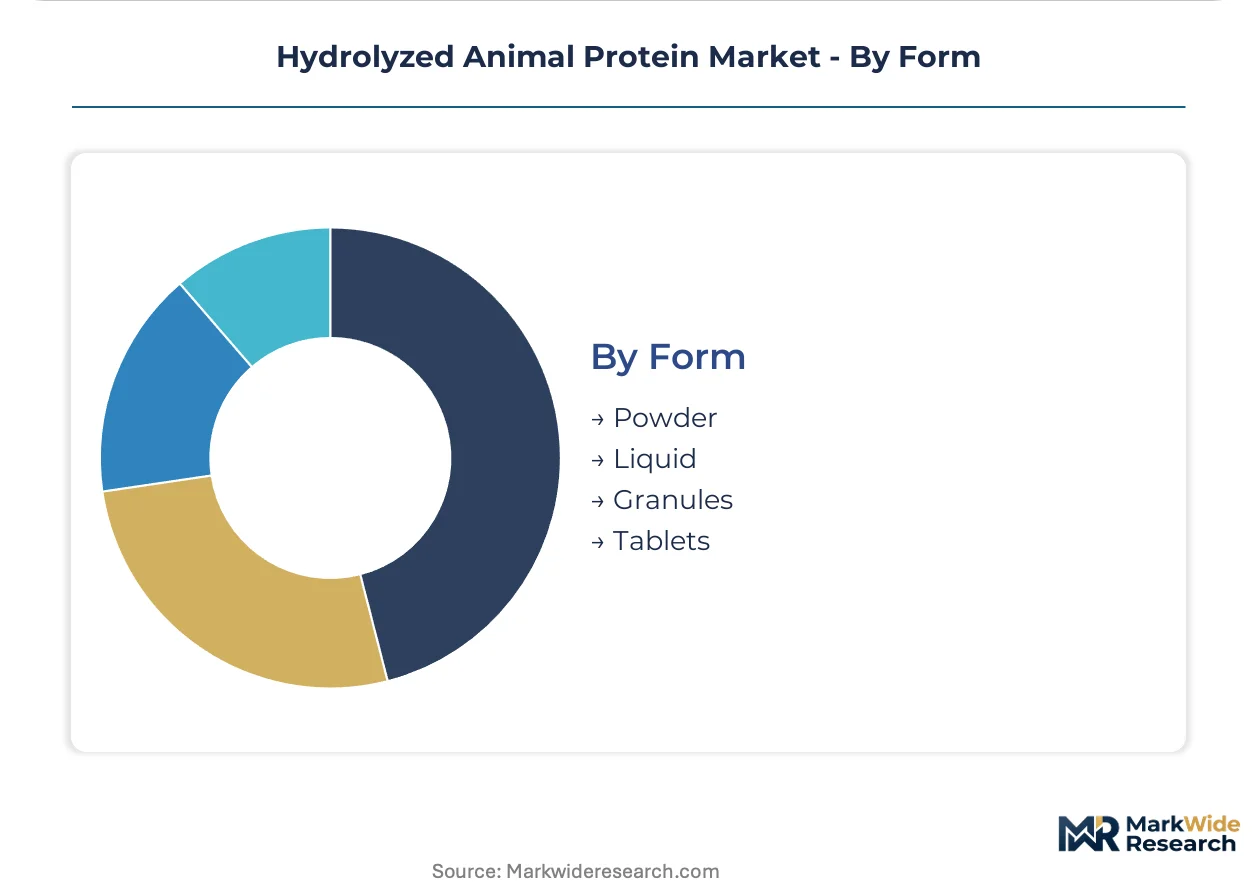
Physical format selection determines distribution economics and application flexibility, with powder maintaining scale advantages while liquid concentrates capture ready-to-drink formulation growth.
- Powder:Spray-dried hydrolysates with extended shelf stability and lower logistics costs per unit protein. Current production volumes dominate across Brazilian aquaculture feed mills and European nutraceutical contract manufacturers.
- Liquid:Concentrated protein solutions gaining traction in North American functional beverage co-packing networks.
- Granules:Agglomerated powders for improved flow characteristics in high-speed tableting operations.
- Tablets:Direct-compression formats for retail nutraceutical channels requiring dose standardization.
Powder holds installed capacity. Liquid is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. North American buyers prioritize clean-label pet food reformulation, while European demand concentrates on EFSA-compliant nutraceutical grades. Asian markets split between South Korean cosmetic applications and Chinese functional beverage scale.
United States
Pet food manufacturers in Kansas and Missouri drive demand for hydrolyzed collagen in premium kibble lines. FDA GRAS self-determination pathways allow rapid ingredient introductions without pre-market approval. Chicago-area co-packers are expanding liquid concentrate capacity for ready-to-drink protein waters.
Germany
Nutraceutical contract manufacturers in Bavaria command premium pricing for sub-3 kDa collagen peptides. EFSA novel food dossiers favor established bovine sources with complete toxicology profiles. Frankfurt distribution hubs consolidate supplier relationships around vertically integrated producers with captive raw material streams.
Brazil
ANVISA bioequivalence requirements for pharmaceutical-grade hydrolysates create dual-grade manufacturing incentives. Tannery byproduct supply from São Paulo and Minas Gerais feeds collagen-derived protein capacity. Aquaculture nutrition formulators in Rio Grande do Sul displace synthetic nitrogen sources with hydrolyzed feather meal.
South Korea
Cosmetic formulators in Seoul integrate sub-3 kDa collagen peptides into topical delivery systems with documented percutaneous absorption. MFDS regulates functional food claims for hydrolyzed protein fortification. Busan-based ingredient distributors are being displaced by direct procurement contracts from German suppliers.
Japan
Enteral feeding applications in Osaka and Nagoya require batch-level traceability exceeding food-grade standards. METI guidelines on bioactive peptide labeling influence regional procurement specifications. Tokyo cosmetic houses source marine collagen hydrolysates through prioritized Asian regulatory pathways ahead of European submissions.
Hydrolyzed Animal Protein Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with fermentation-derived enzyme capabilities creating the primary stratification. Danish and German clusters control specialty protease supply, while gelatin-derived protein manufacturers anchor European capacity. Two strategic archetypes dominate: enzymatic process specialists with molecular-weight control systems, and raw-material-integrated processors with captive tannery or dairy streams. Competitive moves concentrate on backward integration into hide and skin supply, and geographic expansion into Brazilian aquaculture channels.
Among enzyme technology specialists, Novozymes A/S represents the fermentation hub archetype with Danish R&D concentration. GELITA and Kerry, Inc. occupy positions within the integrated processor tier, with GELITA exemplifying gelatin-derived capacity control and Kerry anchoring flavor-masked protein system development for beverage applications. These three companies illustrate how capability scarcity in bioprocess engineering is concentrating advantage among established fermentation clusters.
| Leading Market Players |
|---|
| Fonterra Co-operative Group |
| Kemin Industries, Inc. |
| Arla Foods Ingredients Group P/S |
| Lactalis Ingredients |
| Kerry, Inc. |
| BRF S.A. |
| GELITA |
| Novozymes A/S |
| Cargill, Inc. |
| Others |
Supply Flow & Price Mechanics
EFSA novel food dossier requirements gate both supply qualification timelines and price differentiation tiers for hydrolyzed collagen entrants seeking European market access. Certification bandwidth separates pharmaceutical-grade bioequivalence premiums from commodity feed-grade nitrogen pricing, with enzymatic processing investments commanding tiered returns based on molecular weight control precision.
Pricing Analysis
Contract structures bifurcate between long-term offtake agreements with German nutraceutical contract manufacturers and spot-market transactions for Brazilian aquaculture feed applications. Price differentiation rests on enzymatic certification grade and EFSA novel food approval status, with sub-3 kDa peptide fractions capturing premiums over acid-hydrolyzed commodity streams. Pricing pressure intensifies in feed-grade segments as alkaline hydrolysis methods persist in commodity markets. Pet food manufacturers in North America demonstrate lowest price sensitivity, prioritizing clean-label certification over unit cost.
Supply Chain Analysis
Port congestion on Hamburg-Rotterdam trade lanes elevates inbound logistics costs for South American tannery byproducts destined for European hydrolysate capacity. Supply concentrates in Brazil, Argentina, and Germany, with bovine hide and porcine skin feedstocks anching collagen-derived protein production. Raw material dependencies encompass specialty proteases from Danish fermentation clusters, gelatin intermediates, and ANVISA-certified pharmaceutical-grade inputs. Single-source vulnerability runs through enzymatic process supply controlled by German and Danish bioprocess engineering hubs. Distribution runs through Frankfurt consolidation hubs serving nutraceutical channels and São Paulo distribution nodes feeding aquaculture nutrition formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive-moat structure anchored in regulatory entrenchment. EFSA novel food approval timelines and ANVISA dual-grade certification requirements create switching costs that protect incumbent positions.
For Market Incumbents: Shield market position by deepening captive tannery feedstock relationships in Brazil and Argentina against gelatin supply volatility. Expand enzymatic processing capacity in Bavaria to capture functional beverage formulation growth. Prioritize EFSA dossier maintenance for established bovine sources as porcine and marine entrants face extended approval timelines.
For New Entrants and Emerging Players: Lead with molecular-weight-controlled enzymatic systems targeting South Korean cosmetic formulators seeking sub-3 kDa collagen peptides for topical delivery. Brazilian aquaculture nutrition offers the most penetrable channel given ANVISA feed-grade pathway flexibility. Pursue direct procurement relationships displacing Busan-based distributors serving East Asian cosmetic houses.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed gelatin-derived processors lacking enzymatic hydrolysis capabilities. Long-term viability favors integrated producers with captive raw material streams and fermentation-derived enzyme access. Watch for EFSA guidance revisions on non-bovine collagen sources as inflection indicators for qualification backlog resolution.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tannery Feedstock | Captive bovine hide supply from São Paulo tanneries insulates GELITA against Argentine price volatility. |
| Enzymatic Process Capacity Expansion | Bavaria-based molecular-weight control systems enable Kerry's flavor-masked protein concentrate penetration of North American beverage networks. |
| EFSA Novel Food Dossier Investment | Complete toxicology profiles for bovine collagen accelerate German nutraceutical channel access versus porcine alternatives. |
| Dual-Grade Certification Parallel Systems | Simultaneous ANVISA and FDA compliance opens pharmaceutical and feed revenue streams for Brazilian manufacturers. |
| Direct Procurement Channel Development | Bypassing Busan distributors reduces cost-to-serve for German suppliers targeting Seoul cosmetic formulators. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA GRAS notifications, EFSA novel food register entries, ANVISA pharmaceutical-grade filings, and Brazilian customs trade data. Conversations with enzymatic process engineers, nutraceutical contract manufacturing procurement leads, pet food formulation directors, and aquaculture nutrition specialists informed supply-side and demand-side assessments. Bottom-up capacity modeling triangulates against top-down consumption estimates across enzymatic and acid-hydrolysis process tiers.
Segmentation dimensions modeled encompass hydrolysis method, molecular weight grade, application certification tier, and geographic regulatory cluster across the projection horizon. CAGRs derive from production capacity expansion schedules, EFSA approval timeline assumptions, and channel penetration rates for functional beverage and pet care applications. Forecast inputs incorporate tannery byproduct availability projections and specialty protease supply constraints from Danish fermentation hubs.
The analysis sits within stated boundaries; outcomes outside EFSA regulatory stability, Brazilian tannery supply continuity, or enzymatic process technology diffusion would require recalibration. Forecasts reflect documented assumptions regarding approval pathway timelines and feedstock cost trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
North America Brewing Enzymes Market
Ingredients
Asia-Pacific Food Coating Ingredients Market
Ingredients
Global Dairy Protein Ingredients Market
Ingredients
Hops Market
Ingredients
Soluble Fibers Market
Ingredients
China Protein Market
Ingredients
Roasted Grain Ingredients Market
Ingredients
Chickpea Flour Market
Ingredients
Egg Yolk Lecithin Market
Ingredients
Salad Oil Market
Ingredients
All Purpose Flour Market
Ingredients
North America Protein Ingredients Market
Ingredients
Europe Brewers Spent Yeast Market
Ingredients
Eucalyptus Oil Market
Ingredients
Cooking Oils and Fats Market
Ingredients
Broccoli Powder Market