
 Cocoa Derivatives Market | 2026-2036
Cocoa Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Cocoa Derivatives Market Outlook
Direct procurement partnerships between processors and origin-country cooperatives is reshaping how cocoa derivatives move from farm to factory. Cargill, Incorporated leverages its integrated supply chain across West Africa and Southeast Asia to secure bean throughput. The Barry Callebaut Group anchors European confectionery demand through specialized cocoa liquor and butter facilities. Olam Group Limited competes on sustainability certification density, differentiating its offerings for premium chocolate manufacturers.
Cocoa derivatives comprise processed intermediate products extracted from fermented and dried cacao beans through roasting, winnowing, grinding, and pressing stages, yielding cocoa butter with characteristic fat content near 50-57% in whole beans alongside cocoa solids. These inputs serve as functional building blocks for chocolate confectionery, baked goods, and beverage formulations where fat crystallization behavior and flavor precursors determine finished product quality. Cocoa butter commands the highest value pool among product types due to its irreplaceable role in tempering and mouthfeel engineering, while cocoa powder generates volume throughput from press cake residuals. Confectionery applications absorb the largest share of derivative output, though dairy and beverage segments are expanding fastest as cocoa powder integrates into protein-fortified and plant-based formulations.
The EU Deforestation Regulation and EFSA food contact standards are tightening due diligence and residue limits across European cocoa derivative imports, forcing processors to deploy geolocation verification and mass-balance certification systems. FDA food safety modernization rules and ISO 22000 frameworks govern US-bound shipments, adding compliance layers for foreign supplier verification. Stakeholders must decide whether to absorb certification costs or pass them downstream, as traceability investments become the baseline for market access rather than a premium differentiator.
Market Dynamics
The EU Deforestation Regulation is forcing cocoa derivative processors to rebuild traceability infrastructure from farm gate to finished product, converting compliance from voluntary certification into mandatory market access condition.
Growth Catalysts
- Mass-balance certification systems:Food contact standards from EFSA are driving adoption of segregated supply chains among European confectionery manufacturers. Premium chocolate brands now require verified origin documentation as table stakes.
- Plant-based beverage formulations:Cocoa powder is displacing synthetic flavoring in protein-fortified drinks across North American functional food segments. Dairy alternatives are absorbing press cake derivatives at accelerating rates.
- Côte d'Ivoire and Ghana sourcing corridors:Direct procurement partnerships between processors and origin-country cooperatives are compressing intermediary layers. Traceability investments are unlocking preferential financing from development institutions.
Market Restraints
- Cocoa bean price volatility:Input cost swings from weather-driven supply shocks in West African growing regions transmit directly to derivative margins. Processors lack pricing power to pass through commodity spikes.
- Butter extraction yield ceiling:Technical limitation of pressing efficiency caps cocoa butter output at roughly 50-57% of nib weight. No commercial enzymatic or solvent alternatives match natural fat crystallization properties.
- EU Deforestation Regulation compliance timeline:Geolocation verification requirements for every farm plot create documentation bottlenecks. Smallholder cooperatives lack capital for GPS mapping equipment.
Strategic Opportunities
- Indian confectionery expansion:Underpenetrated geography offers white space as domestic chocolate consumption per capita remains a fraction of European levels. Local processing capacity is insufficient to meet projected demand.
- Dual carbon goals in China:Regulatory tailwind from NMPA and MIIT efficiency mandates favors processors with renewable energy credentials in cocoa butter refining. Carbon-border adjustments will penalize high-emission imports.
- E-commerce ingredient channels:Distribution innovation is opening direct-to-kitchen sales of cocoa powder and specialty butters to artisan bakers. Platform algorithms are fragmenting traditional foodservice procurement.
Industry Challenges
- Geolocation data integration:Certification compliance requires marrying satellite imagery with farm-level transaction records. Legacy ERP systems at mid-sized processors cannot ingest unstructured spatial data.
- Flavor chemist scarcity:Talent gap in lipid crystallization science limits product development for premium tempering applications. Universities have shuttered specialized confectionery technology programs.
- Press equipment lead times:Capex intensity for hydraulic butter extraction machinery has extended to 18-24 months. Supply chain reconfiguration friction delays capacity expansion in origin countries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cocoa Derivatives Market |
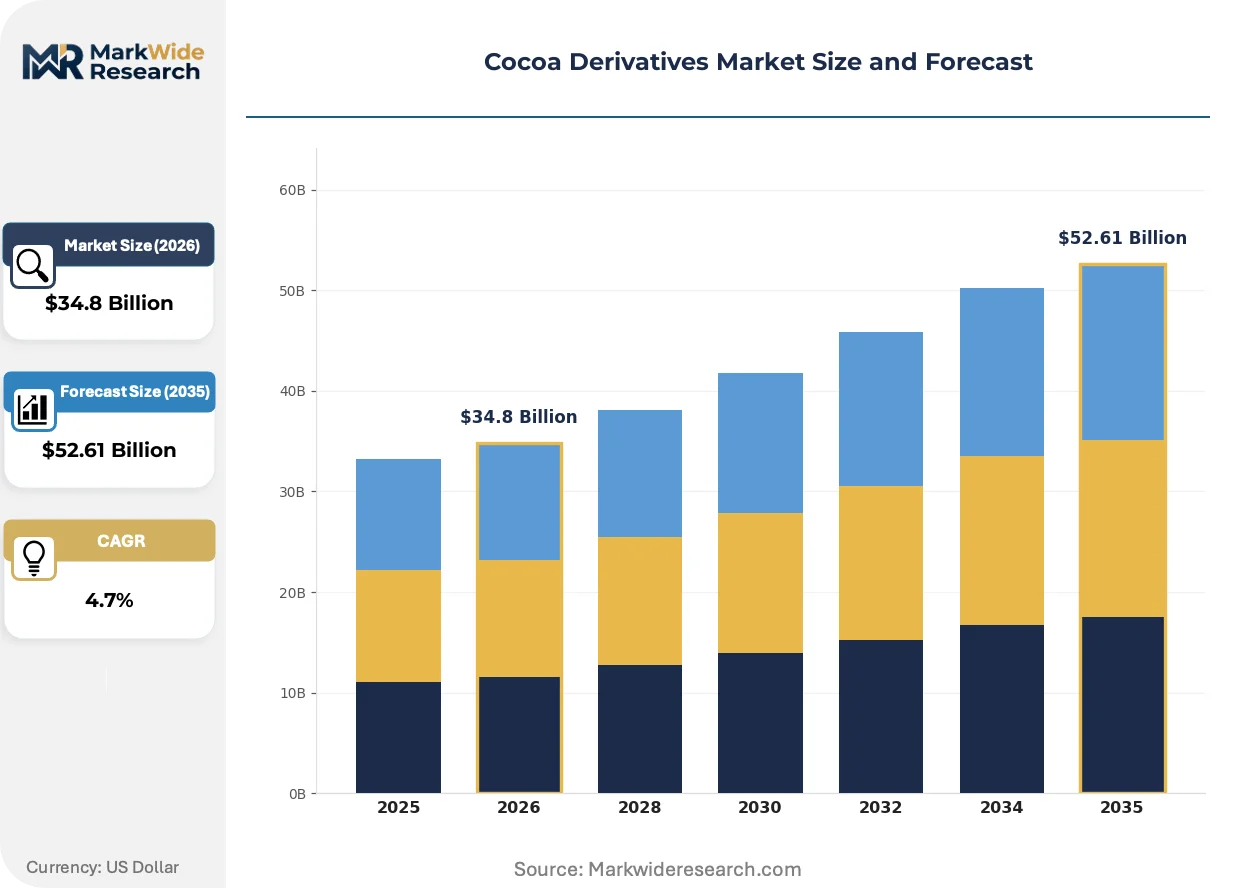
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $52.61 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cocoa Butter, Cocoa Powder, Cocoa Liquor, Cocoa Cake Form: Powdered, Solid, Liquid, Granulated Application: Confectionery, Bakery, Beverages, Dairy Products Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | JB Foods Limited, Moner Cocoa, S.A., Olam Group Limited, Ecuakao Group Ltd, Natra SA, Cargill, Incorporated, Indcre, S.A., United Cocoa Processor Inc., The Barry Callebaut Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cocoa Derivatives Market Strategic Shifts
Digital traceability infrastructure is virtualizing how cocoa derivatives move from fermentation to finished chocolate, compressing documentation cycles and enabling real-time compliance verification.
Blockchain-enabled farm-to-factory tracking is virtualizing custody records across West African cooperatives and European processors. Mid-sized chocolate manufacturers in Switzerland and Belgium are piloting these systems to preempt EUDR audit requirements. The technology is virtualizing the role of traditional certification bodies by embedding compliance into transactional data.
EFSA is tightening maximum residue limits for cadmium and lead in cocoa derivatives, forcing processors to remap sourcing from specific volcanic-soil regions. The industrial consequence is accelerated investment in soil testing and bean blending protocols. Dark chocolate formulations with elevated cocoa solid content are most affected, with manufacturers reformulating recipes or switching origin mixes.
Buyer concentration among certified-sustainable chocolate brands is compressing switching options for derivative suppliers. Direct contracting between processors and retail private-label programs is replacing spot market purchasing in Germany and France. This pattern is most visible in the organic and fair-trade segments where volume commitments now span multi-year horizons.
Cocoa Derivatives Market Segmentation
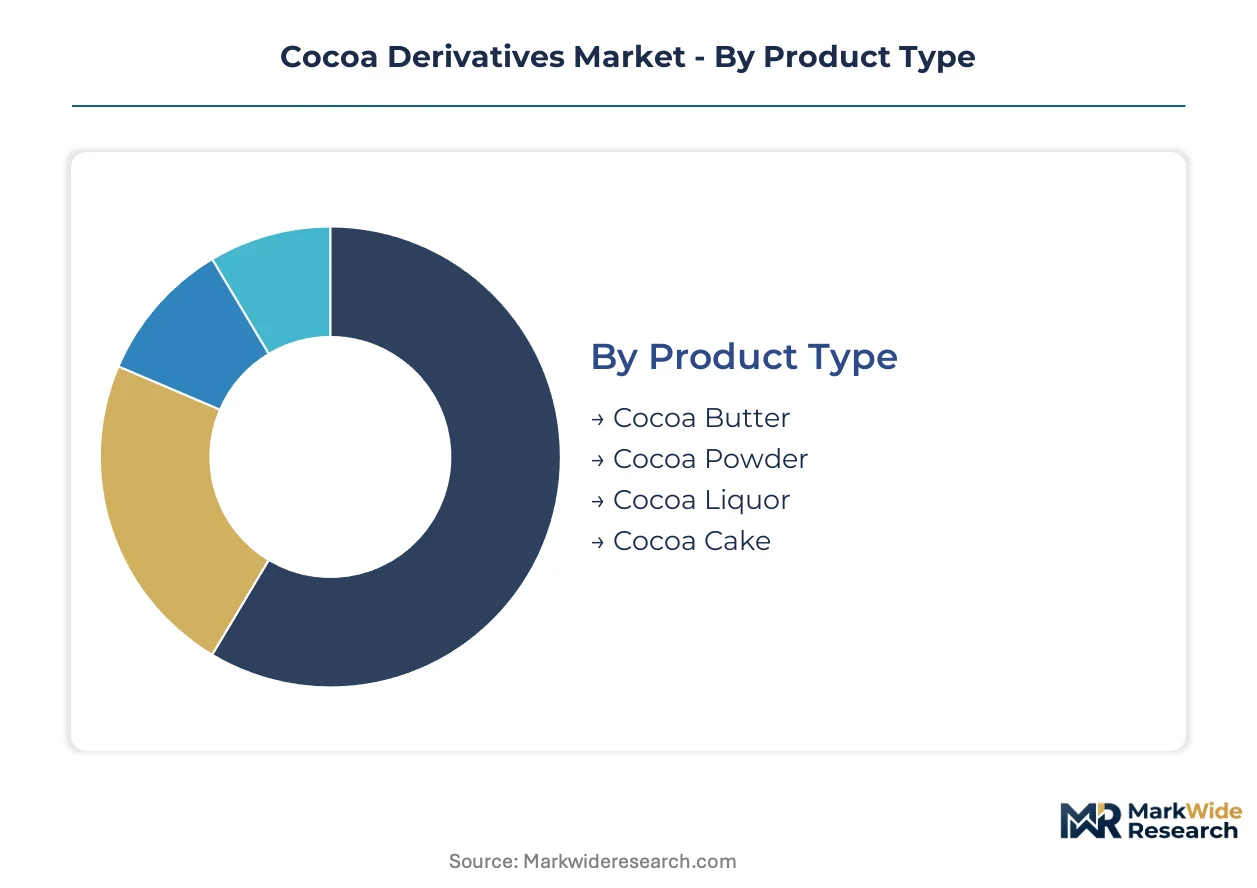
Cocoa derivatives fragment across functional specifications that determine crystallization behavior, flavor delivery, and shelf stability in finished formulations. Processors and confectionery manufacturers align procurement strategies to these technical boundaries, as fat content and particle size directly constrain recipe engineering possibilities.
Product Type:
Use-case spectrum spans tempering-critical applications through bulk flavoring, with fat crystallization properties dictating segment selection.
- Cocoa Butter:Natural fat extracted from nib pressing carries characteristic triglyceride structures enabling polymorphic crystallization essential for chocolate tempering. German and Swiss confectionery manufacturers absorb premium grades for molded chocolate shells, constrained by extraction yield ceilings near 50-57% of nib weight.
- Cocoa Powder:Press cake residuals ground to specified particle sizes deliver concentrated cocoa solids for color and flavor in baked goods and beverages. North American functional food segments are displacing synthetic flavoring with alkalized powder in protein-fortified formulations.
- Cocoa Liquor:Ground nibs in liquid or semi-solid form serve as the foundational intermediate for chocolate manufacturing, combining cocoa solids and butter in native proportions.
- Cocoa Cake:Compressed solids remaining after butter extraction feed bulk powder production or animal feed applications, generating lowest value per kilogram across the product spectrum.
The dominant share belongs to Cocoa Butter, while Cocoa Powder is closing the gap fastest.
Form:
Processing economics and logistics requirements concentrate volume around physical states that minimize handling complexity and contamination risk.
- Powdered:Fine-milled particles below 75 microns enable homogeneous dispersion in dry mixes and liquid suspensions, dominating beverage and bakery applications where hydration behavior determines texture outcomes.
- Solid:Molded blocks or chips of cocoa butter and liquor simplify tempering workflows for artisan and industrial chocolate manufacturers, with stability during ambient transport reducing cold chain dependency.
- Liquid:Tanker-delivered cocoa liquor and melted butter serve high-volume confectionery operations with continuous processing lines, requiring heated storage infrastructure.
- Granulated:Agglomerated powder particles improve flow properties for automated dosing systems in dairy and ice cream manufacturing.
Powdered forms command the largest volume position, though Solid formats are gaining share fastest in craft chocolate segments.
Application:
End-use requirements for fat crystallization control, flavor intensity, and cost positioning segment demand across food manufacturing verticals.
- Confectionery:Chocolate bar, praline, and coating applications demand precise tempering behavior and mouthfeel engineering, absorbing the highest-value butter grades.
- Bakery:Cocoa powder dominates for color and flavor in cakes, cookies, and pastries, with fat content specifications varying by recipe type.
- Beverages:Instant drink mixes and dairy alternatives are expanding powder absorption fastest as plant-based formulations displace synthetic flavoring.
- Dairy Products:Ice cream, yogurt, and flavored milk applications utilize low-fat cocoa powder for color without excessive fat interference in freezing and fermentation processes.
Confectionery retains the dominant value share, while Beverages are expanding most quickly.
Distribution Channel:
Customer scale and certification requirements are compressing intermediary layers in favor of direct contractual relationships.
- Wholesale:Volume aggregation through commodity traders and regional distributors serves mid-sized manufacturers without direct origin relationships.
- Retail:Packaged consumer formats of cocoa powder and specialty butters reach artisan bakers and small confectioners through foodservice distributors.
- Online:Platform algorithms are fragmenting traditional procurement patterns, enabling direct-to-kitchen sales of specialty grades to craft producers.
- Direct Sales:Processors are building captive supply relationships with major chocolate manufacturers, embedding traceability compliance into multi-year contracts.
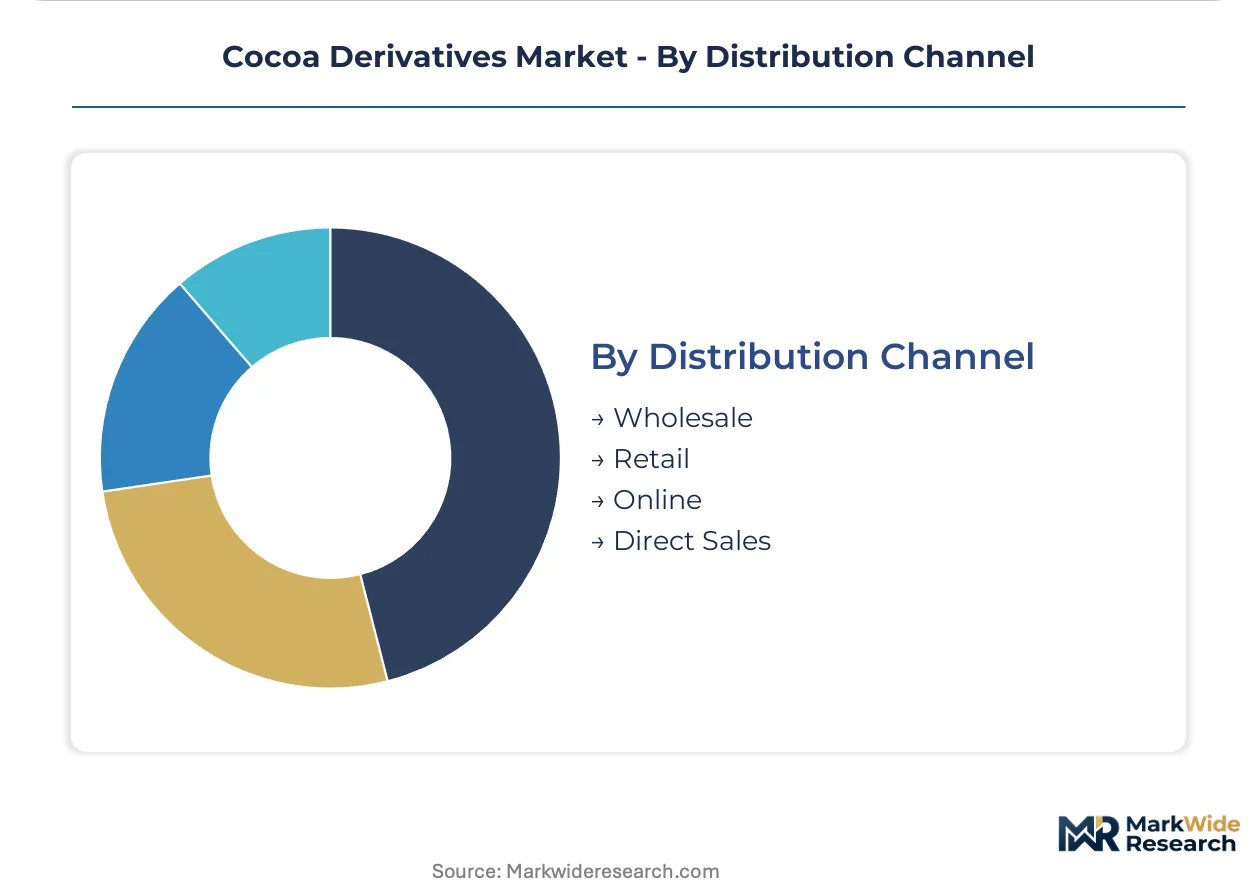
Wholesale channels still handle the greatest volume throughput, though Direct Sales are climbing the fastest as traceability mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA food contact standards anchor European demand for certified cocoa derivatives, while FDA modernization rules and dual carbon mandates in China reshape procurement geography. Côte d'Ivoire and Ghana processing corridors concentrate upstream supply, with downstream confectionery clusters in Germany, Switzerland, and Belgium absorbing premium butter grades.
Germany
Confectionery manufacturers in Cologne and Hamburg drive certified sustainable cocoa butter procurement for premium chocolate shells. The EU Deforestation Regulation forces geolocation verification across all farm-gate transactions. The Cologne-Chocolate-Cluster anchors specialized tempering operations for molded praline production.
Switzerland
Premium chocolate brands in Zurich and Vevey require mass-balance certification as baseline market access. Swissmedic-aligned food safety protocols exceed baseline EFSA requirements for heavy metal residue limits. The Lake Geneva corridor concentrates cocoa liquor refining capacity serving artisan and industrial manufacturers.
United States
Functional beverage formulators in California and New York displace synthetic flavoring with alkalized cocoa powder in protein-fortified applications. FDA foreign supplier verification rules add compliance layers for West African bean imports. The New Jersey-Philadelphia processing belt handles bulk butter refining for national confectionery distribution.
China
Dairy alternative manufacturers in Shanghai and Guangzhou accelerate press cake derivative absorption for plant-based formulations. NMPA and MIIT dual carbon goals favor processors with renewable energy credentials in cocoa butter refining. The Yangtze River Delta hosts expanding chocolate manufacturing capacity targeting domestic premium consumption.
India
Domestic chocolate consumption per capita remains underpenetrated versus European benchmarks, creating white space for derivative demand expansion. FSSAI food safety standards tighten import documentation for cocoa powder and butter shipments. Maharashtra and Gujarat processing hubs lack sufficient capacity to meet projected confectionery growth.
Cocoa Derivatives Market Competitive Environment
Integrated processors and specialized confectionery ingredient suppliers split the market along traceability and scale vectors. The vendor base concentrates around three strategic archetypes: West African-integrated processors with direct cooperative partnerships, European-based specialists in premium tempering grades, and Asian-origin traders competing on volume throughput. Dominant competitive moves include backward integration into origin-country pressing facilities and multi-year direct contracting with retail private-label programs.
Within the integrated-processor tier, Cargill, Incorporated and The Barry Callebaut Group exemplify contrasting geographic anchoring strategies. Olam Group Limited occupies a position emphasizing sustainability certification density for premium chocolate manufacturers. These three entities represent the dominant competitive archetypes shaping procurement relationships across European and North American confectionery markets.
| Leading Market Players |
|---|
| JB Foods Limited |
| Moner Cocoa, S.A. |
| Olam Group Limited |
| Ecuakao Group Ltd |
| Natra SA |
| Cargill, Incorporated |
| Indcre, S.A. |
| United Cocoa Processor Inc. |
| The Barry Callebaut Group |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Maharashtra and Gujarat processing corridors is compressing margins for Indian confectionery manufacturers while concentrating pricing power among West African-integrated processors with direct cooperative partnerships.
Pricing Analysis
Geographic price spreads between European mass-balance certified grades and spot-market Asian origins are widening as EUDR compliance costs embed into contract structures. Three-tier pricing structure across premium certified, standard commercial, and economy bulk grades dominates procurement negotiations, with certification density and traceability documentation as the primary differentiation drivers. Pricing pressure stems from butter extraction yield ceilings that cap output regardless of bean input costs. Smallholder cooperatives exhibit highest price sensitivity due to working capital constraints, while Swiss premium chocolate manufacturers demonstrate lowest sensitivity given formulation lock-in requirements.
Supply Chain Analysis
Tariff exposure between Côte d'Ivoire and European Union member states dominates supply chain risk calculus as the EU Deforestation Regulation triggers documentary compliance costs. Geographic supply concentrates in Côte d'Ivoire, Ghana, and Indonesia, with bean quality and fermentation protocols as critical input dependencies. Single-source vulnerability persists in specialized tempering-grade butter supplies where Swiss and Belgian processors control refining capacity. Distribution runs through direct processor-manufacturer contracting for certified grades, with commodity traders handling residual spot-market volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cocoa derivatives market functions as a defensive-moat arena where regulatory entrenchment around EUDR traceability infrastructure creates durable switching costs for incumbent processors with deployed geolocation systems.
For Market Incumbents: Harden compliance infrastructure through GPS mapping equipment deployment at cooperative partners in West African sourcing corridors. Deepen upstream control over pressing facilities in Côte d'Ivoire and Ghana to secure bean throughput against emerging Asian traders. Certification investment in mass-balance systems represents the critical defensive lever against margin compression from regulatory documentation requirements.
For New Entrants and Emerging Players: Pursue white-space expansion in Indian confectionery markets where domestic processing capacity lags projected demand growth. Target beverage-grade cocoa powder segments in North American functional food applications as the most penetrable entry point. E-commerce ingredient channels offer direct-to-kitchen go-to-market positioning for specialty butter grades targeting artisan bakers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among processors with multi-year direct contracting relationships to retail private-label programs in Germany and France. Long-term viability over the next decade hinges on traceability infrastructure deployment completion ahead of regulatory enforcement windows. Acquisition focus should center on mid-sized European specialists with EFSA-aligned food safety protocols. The signal to watch is cadmium and lead residue limit tightening by EFSA, which will force origin mix reconfiguration and favor processors with diversified sourcing portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Origin-Country Pressing | Cargill and Barry Callebaut deployments in Côte d'Ivoire secure bean throughput against Asian trader competition. |
| Mass-Balance Certification System Deployment | Swiss and Belgian manufacturers pilot blockchain-enabled tracking to preempt EUDR audit documentation requirements. |
| Direct-to-Kitchen E-Commerce Channel Launch | Platform algorithms fragment traditional foodservice procurement for specialty cocoa butter grades targeting artisan bakers. |
| Renewable Energy Credentials in Refining | NMPA and MIIT dual carbon mandates in China penalize high-emission cocoa butter imports from conventional processors. |
| Soil Testing and Bean Blending Protocol Investment | EFSA cadmium limit tightening forces remapping of sourcing from volcanic-soil regions in specific origin countries. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cocoa processing plant managers, confectionery procurement leads at European manufacturers, sustainability certification directors, and cooperative agronomists in West Africa. Secondary validation drew from EFSA food contact standard filings, EU Deforestation Regulation implementation guidance, customs and trade data for cocoa bean and derivative flows, and SEC 10-K disclosures from publicly traded processors. Bottom-up volume modeling and top-down market sizing triangulation anchored value estimates.
Calibration against historical price spreads between certified and conventional grades, extraction yield benchmarks, and regional processing capacity utilization informed trajectory assumptions across the projection horizon. Segmentation dimensions modeled include product type, form, application, distribution channel, and regional regulatory cluster. CAGRs were derived from regression analysis of input-output ratios and demand elasticity parameters, with cocoa bean price volatility and EUDR compliance timeline as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in euro-dollar exchange rates, West African rainfall patterns, or European consumer confectionery expenditure would shift the trajectory. Forecasts embed assumptions regarding regulatory enforcement intensity and certification adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Vitamin C Ingredients Market
Ingredients
Hydrolyzed Pork Protein Market
Ingredients
Hydrogenated Palm Oil Market
Ingredients
Brewer's Yeast Market
Ingredients
Anhydrous Caffeine Market
Ingredients
Citrus Pectin Market
Ingredients
Baobab Powder Market
Ingredients
Soy Lecithin Market
Ingredients
Global Malt Extracts and Ingredients Market
Ingredients
Ingredients Market
Ingredients
Algae Omega-3 Ingredients Market
Ingredients
Asia-Pacific Potato Protein Market
Ingredients
Potato & Yam Derivatives Market
Ingredients
Africa Soy Protein Ingredients Market
Ingredients
Europe Plant Protein Ingredients Market
Ingredients
Instant Dry Yeast Market