
 Agar Agar Flakes Market | 2026-2036
Agar Agar Flakes Market Size, Share, and Industry Trends Forecast 2026-2036
Agar Agar Flakes Market Analytics
The gap between premium and commodity tiers is broadening as pharmaceutical-grade agar agar flakes command purity standards that food-grade variants do not require. Meron leverages its coastal sourcing infrastructure to sustain cost advantages in bulk supply. GELITA AG differentiates through ISO-certified extraction protocols that occupy the high-margin life-science segment. ROKO competes on volume scale across Eastern European confectionery channels.
Agar agar flakes are dried, purified polysaccharide fragments extracted primarily from red algae of the Gelidium and Gracilaria genera, with gel strength typically measured in grams per square centimeter to determine functional grade. The material serves as a thermoreversible gelling agent, stabilizer, and vegetarian substitute for gelatin across food, pharmaceutical, and microbiological applications. Flakes retain texture advantages in slow-hydration recipes where powder would clump, though powder dominates total volume due to faster dissolution rates in industrial processing. Biotechnology applications represent the fastest-growing demand pool as cell-culture media formulations shift toward animal-free substrates. Food Industry demand remains mature in volume terms but generates thinner margins than pharmaceutical or cosmetics applications where endotoxin limits tighten.
FDA food additive regulations under 21 CFR 172.620 maintain specific identity standards for agar that shape import testing requirements for non-US suppliers. EFSA and Japan's Ministry of Health, Labour and Welfare enforce divergent heavy-metal thresholds that force manufacturers to maintain parallel certification streams. China's GB standards for food-grade seaweed extracts add another compliance layer for exporters serving Asian processing hubs. Stakeholders must monitor regulatory divergence on residual sulfur dioxide limits, as tightening rules in one jurisdiction typically propagate through supply chain audit requirements within eighteen to twenty-four months.
Market Dynamics
Clean-label formulation mandates across food and pharmaceutical sectors are compressing gelatin demand while elevating agar agar flakes as the default vegetarian gelling standard, forcing suppliers to recalibrate purity thresholds and extraction protocols simultaneously.
Growth Catalysts
- EFSA purity mandates:Tightened heavy-metal thresholds for food-grade seaweed extracts are disqualifying commodity suppliers and rewarding certified producers with shelf-space access in European retail channels.
- Cell-culture media:Biotechnology laboratories are adopting animal-free substrates for stem-cell propagation, with agar agar flakes replacing gelatin in hydrogel formulations for 3D tissue scaffolding.
- South Korea functional food corridor:Domestic formulators are integrating agar-derived prebiotic fibers into digestive health products, creating sustained procurement volume for high-gel-strength grades.
Market Restraints
- Red algae supply concentration:Harvesting rights for Gelidium and Gracilaria species concentrate along Morocco's Atlantic coast and Indonesia's archipelagic waters, exposing processors to climate-driven yield volatility.
- Carrageenan substitution:Food manufacturers in cost-sensitive confectionery segments are substituting lower-priced carrageenan for agar in soft-gel applications where thermoreversibility is non-critical.
- Residual sulfur dioxide limits:Divergent caps between FDA 21 CFR 172.620 and China's GB standards force exporters to maintain dual certification streams, elevating compliance overhead.
Strategic Opportunities
- Precision fermentation cluster Germany:Cultured-meat startups in Bavaria and Baden-Württemberg require pharmaceutical-grade agar for scaffolding media, creating premium pricing potential outside traditional food channels.
- ISO 10993 biocompatibility certification:Medical-device manufacturers seeking hydrogel wound dressings are screening suppliers against endotoxin limits that food-grade flakes fail, opening life-science margins.
- Direct-to-manufacturer e-procurement:Specialty chemical platforms are disintermediating traditional import distributors for mid-volume buyers in cosmetics compounding, compressing lead times from 12 weeks to 4 weeks.
Industry Challenges
- Phycocolloid extraction expertise:Skilled technicians capable of optimizing gel-strength recovery from seasonal algae biomass variations are concentrated in legacy Japanese and Spanish processing centers, constraining capacity expansion.
- Parallel audit timelines:Simultaneous certification against EFSA heavy-metal protocols, FDA food additive identity standards, and Japan's Ministry of Health, Labour and Welfare specifications extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agar Agar Flakes Market |
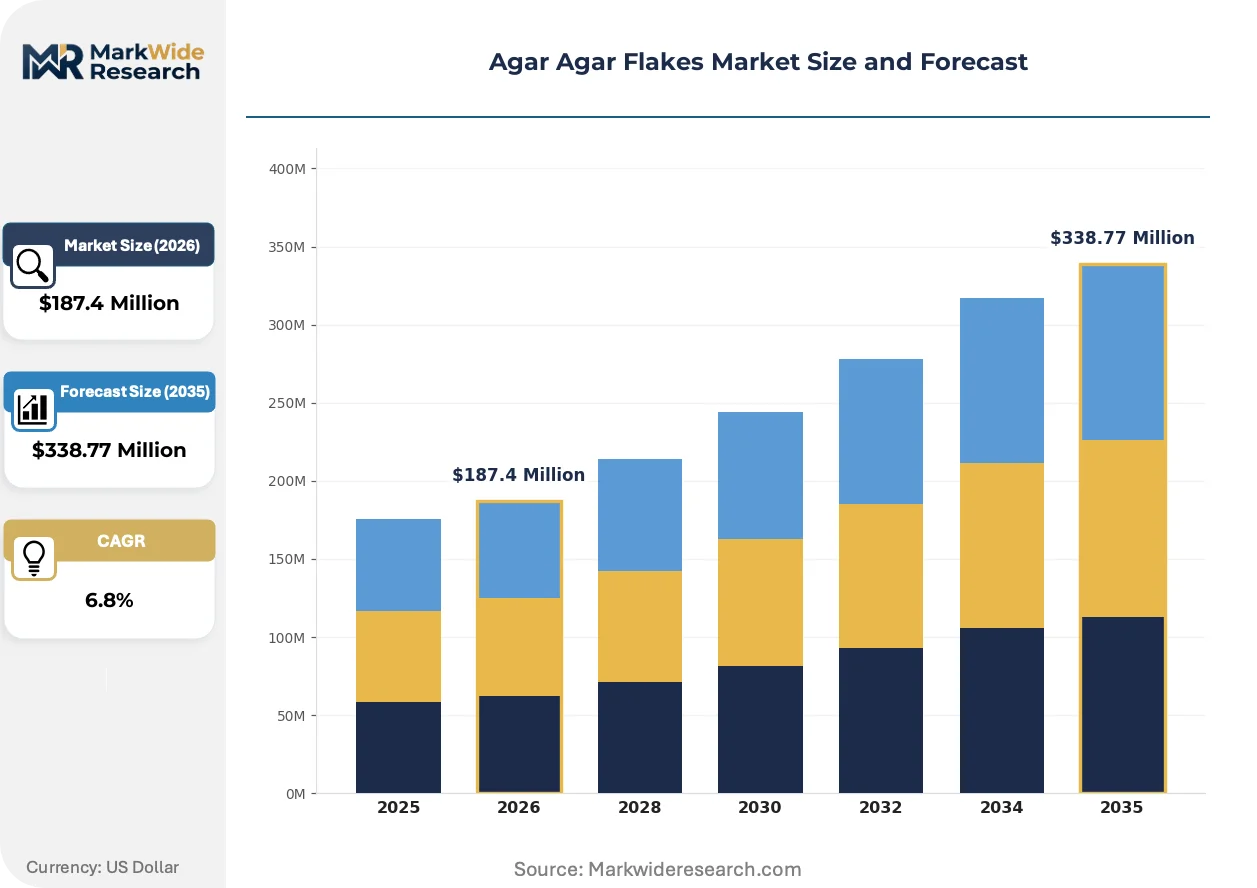
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flakes, Powder, Sheets, Capsules Application: Food Industry, Pharmaceuticals, Cosmetics, Biotechnology End User: Food Manufacturers, Cosmetic Companies, Research Institutions, Laboratories Distribution Channel: Online Retail, Offline Stores, Wholesale, Distributors |
| Companies Covered | Selt Marine Group, ROKO, Meron, B&V, GELITA AG, DEKOBACK GmbH, Penn Herb Company, Eden Foods, TIC Gums, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agar Agar Flakes Market Evolving Landscape
Extraction technology and regulatory fragmentation are jointly reshaping competitive advantage, with differentiation migrating from raw material access toward certified process control and application-specific functionalization.
Enzyme-assisted extraction protocols are expanding into pharmaceutical-grade agar production, replacing traditional alkali boiling with targeted cellulase treatments that preserve gel-strength integrity while reducing residual sulfur dioxide burdens. German and Japanese life-science suppliers are adopting these methods fastest, compressing the certification timeline for endotoxin-compliant flakes by approximately one-third. This technology is expanding into cosmetics-grade supply chains where preservative-free claims command shelf-price premiums.
REACH registration requirements for seaweed-derived polysaccharides are tightening substance identity documentation, forcing non-European exporters to commission full toxicological dossiers that previously qualified under mutual recognition agreements. The industrial consequence is consolidation among importers capable of underwriting registration costs exceeding six figures per substance variant. Pharmaceutical and medical-device segments are most affected, with formulators now requiring chain-of-custody documentation from harvest through extraction.
Long-term supply agreements with fixed volume commitments are displacing spot-market purchasing for food manufacturers above mid-scale volume thresholds, compressing working-capital flexibility in exchange for price stability. This procurement evolution is most visible in German confectionery and South Korean functional-food channels, where buyers are trading annual contract coverage ratios above 70 percent for preferential allocation during seasonal algae harvest shortfalls.
Agar Agar Flakes Market Segmentation
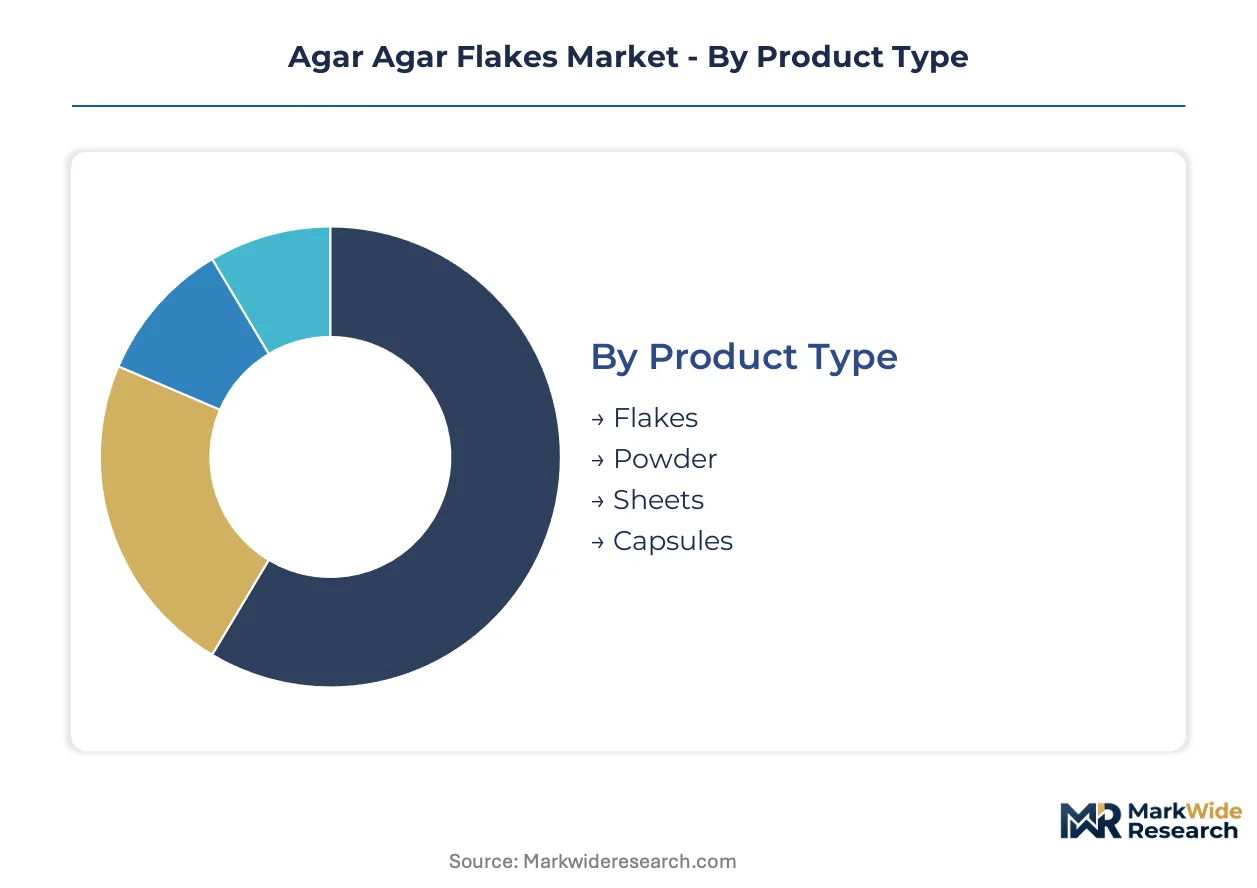
Segmentation in agar agar flakes reveals how capital deployment, regulatory burden, and technical specification divide procurement behavior across end-use verticals. Manufacturers configure extraction protocols and certification streams differently for each tier, creating distinct margin architectures.
Product Type:
Capital intensity concentrates in flake and powder processing, where alkali extraction infrastructure and ISO-certified clean rooms demand seven-figure facility investments that sheet and capsule finishing operations avoid.
- Flakes:Dried polysaccharide fragments with controlled particle size distribution, typically 2-5mm, optimized for slow-hydration recipes where thermoreversible gel formation requires gradual dispersion. South Korean functional food formulators specify high-gel-strength grades exceeding 800 g/cm² for digestive health products, absorbing premium pricing for certified supply.
- Powder:Milled agar with sub-100 micron particle size enabling rapid dissolution in industrial batch processing, dominating total volume through confectionery and beverage applications. German precision fermentation clusters specify pharmaceutical-grade powder for cell-culture media, tightening endotoxin limits below food-grade thresholds.
- Sheets:Compressed agar films used in traditional East Asian dessert preparation and specialty culinary applications, requiring minimal processing capital.
- Capsules:Pre-measured single-serve units targeting home bakers and small-scale foodservice, distributed through online retail channels with convenience markup.
Flakes absorb the bulk of installed capacity; powder is expanding most quickly.
Application:
Margin stratification separates food-grade commodity supply from pharmaceutical and biotechnology segments where certification overhead creates pricing power.
- Food Industry:Mature volume base spanning confectionery gelling, dairy stabilization, and vegetarian gelatin substitution, with EFSA heavy-metal mandates disqualifying uncertified suppliers from European retail channels.
- Pharmaceuticals:Hydrogel formulations for wound dressings and drug delivery systems requiring ISO 10993 biocompatibility certification, with endotoxin limits that food-grade flakes fail.
- Cosmetics:Thickening and stabilizing agent for creams and masks, particularly in preservative-free product lines where enzyme-assisted extraction commands shelf-price premiums.
- Biotechnology:Animal-free substrate for 3D tissue scaffolding and stem-cell propagation, representing the steepest expansion trajectory as laboratories shift from gelatin-based hydrogels.
Food Industry commands volume leadership; biotechnology posts the steepest expansion trajectory.
End User:
Procurement sophistication divides buyers by technical specification capability and audit tolerance.
- Food Manufacturers:Large-scale confectionery and dairy processors negotiating annual contracts above 70 percent coverage ratios, trading working-capital flexibility for price stability during seasonal algae harvest shortfalls.
- Cosmetic Companies:Mid-volume buyers increasingly disintermediating traditional import distributors through specialty chemical e-procurement platforms, compressing lead times from 12 weeks to 4 weeks.
- Research Institutions:Academic laboratories prioritizing batch consistency and documentation over unit cost, with purchasing fragmented across grant-funded project timelines.
- Laboratories:Biotechnology and pharmaceutical testing facilities requiring chain-of-custody documentation from harvest through extraction for regulatory submission packages.
Food Manufacturers anchor procurement volume; cosmetic companies are migrating fastest to direct e-procurement channels.
Distribution Channel:
Channel economics reflect buyer scale and specification complexity, with certification burden determining viable intermediation.
- Online Retail:Direct-to-manufacturer platforms and B2B marketplaces capturing mid-volume cosmetics and specialty food buyers, with REACH registration requirements forcing consolidation among importers capable of underwriting six-figure substance dossiers.
- Offline Stores:Traditional brick-and-mortar chemical supply serving small-batch foodservice and artisan producers with immediate availability needs.
- Wholesale:Volume aggregation for food manufacturers with predictable annual demand, integrating inventory financing and preferential allocation clauses.
- Distributors:Import specialists maintaining parallel certification streams against FDA, EFSA, and Japan's Ministry of Health, Labour and Welfare specifications, extending product launch cycles by 8-14 months.
Wholesale channels lock in the majority of committed volume; online retail is gaining share fastest among mid-scale buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Busan-Ulsan's functional food corridor anchors procurement volume for high-gel-strength agar grades, while Germany's precision fermentation cluster in Bavaria and Baden-Württemberg drives pharmaceutical-grade demand for cell-culture scaffolding applications.
South Korea
Domestic formulators in the Busan-Ulsan corridor integrate agar-derived prebiotic fibers into digestive health products, creating sustained procurement for grades exceeding 800 g/cm². The Ministry of Food and Drug Safety enforces purity thresholds that align with EFSA heavy-metal mandates. Seoul-based manufacturers negotiate annual contract coverage ratios above 70 percent to secure preferential allocation during seasonal harvest shortfalls.
Germany
Cultured-meat startups in Bavaria and Baden-Württemberg require pharmaceutical-grade agar for scaffolding media, generating premium pricing outside traditional food channels. REACH registration requirements for seaweed-derived polysaccharides force consolidation among importers capable of underwriting six-figure substance dossiers. ECHA substance identity documentation now extends product launch cycles by 8-14 months for non-European suppliers.
Japan
Legacy processing centers in Kansai and Chubu maintain concentrated expertise in phycocolloid extraction, constraining capacity expansion despite biotechnology demand acceleration. METI and the Ministry of Health, Labour and Welfare enforce divergent heavy-metal thresholds that require parallel certification streams. Tokyo-based life-science suppliers adopt enzyme-assisted extraction protocols fastest, compressing endotoxin-compliant certification timelines.
China
Qingdao and Dalian processing hubs serve as export gateways to Asian markets, with GB standards for food-grade seaweed extracts adding compliance layers for international shipments. NMPA updated guidance on natural additive purity thresholds in alignment with tightening clean-label formulation standards. The dual carbon goals framework pressures coastal processors to adopt lower-residual sulfur dioxide extraction methods.
United States
FDA food additive regulations under 21 CFR 172.620 shape import testing requirements for non-US suppliers, with Boston and San Diego biotechnology clusters driving demand for animal-free cell-culture substrates. EPA oversight intersects with coastal harvesting rights disputes involving imported red algae biomass. Chicago-based confectionery manufacturers maintain spot-market purchasing flexibility below mid-scale volume thresholds.
Agar Agar Flakes Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and application-specific dimensions, with pharmaceutical and life-science suppliers commanding structural advantages over food-grade bulk processors. The vendor base stratifies into three archetypes: coastal sourcing specialists leveraging harvest proximity, ISO-certified extraction protocol operators serving high-margin segments, and volume-scale distributors dominating cost-sensitive confectionery channels. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as players seek to secure algae harvesting rights and biotechnology application credentials simultaneously.
Within the certified-extraction tier, GELITA AG and Meron occupy positions reflecting divergent strategic emphases—German life-science certification against coastal sourcing infrastructure—while ROKO exemplifies the volume-scale archetype across Eastern European distribution networks. Selt Marine Group anchors the coastal-sourcing category through Atlantic and archipelagic harvest proximity. These four entities collectively illustrate how competitive advantage migrates from raw material access toward certified process control and application-specific functionalization.
| Leading Market Players |
|---|
| Selt Marine Group |
| ROKO |
| Meron |
| B&V |
| GELITA AG |
| DEKOBACK GmbH |
| Penn Herb Company |
| Eden Foods |
| TIC Gums |
| Others |
Value Network & Pricing Analysis
EFSA heavy-metal mandates for food-grade seaweed extracts are forcing European buyers to disqualify uncertified suppliers and absorb premium pricing for compliant agar agar flakes, compelling processors to recalibrate extraction protocols and dual-source from certified harvest zones to maintain shelf-space access.
Pricing Analysis
Gel-strength yield per unit of red algae biomass anchors value-based pricing across pharmaceutical and food-grade tiers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-certified life-science supply from EFSA-compliant food-grade and uncertified commodity bulk. Pricing pressure stems from carrageenan substitution in cost-sensitive confectionery segments where thermoreversibility is non-critical. Food manufacturers above mid-scale volume thresholds exhibit lowest price sensitivity through long-term offtake contracts, while artisan producers and small-batch cosmetics compounders face highest cost elasticity.
Supply Chain Analysis
Dual-sourcing requirements from German and South Korean biotechnology buyers mandate parallel qualification of Moroccan and Indonesian harvest zones to mitigate climate-driven yield volatility. Supply draws from Gelidium and Gracilaria biomass concentrated along Morocco's Atlantic coast and Indonesia's archipelagic waters, with alkali extraction infrastructure and ISO-certified clean rooms as critical processing inputs. Single-source vulnerability concentrates in legacy Japanese and Spanish phycocolloid extraction expertise. Distribution runs through wholesale channels locking in committed volume for food manufacturers, with specialty chemical e-procurement platforms gaining share among mid-scale cosmetics buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH registration requirements for seaweed-derived polysaccharides create six-figure dossier barriers that consolidate importer networks and protect certified incumbents from commodity competition.
For Market Incumbents: Cement defensive positioning through backward integration into Moroccan and Indonesian harvesting rights to secure preferential algae biomass allocation during seasonal shortfalls. Invest in enzyme-assisted extraction capacity to compress endotoxin-compliant certification timelines for pharmaceutical-grade supply, insulating margins from carrageenan substitution pressure in food-grade channels. For New Entrants and Emerging Players: Capture white-space opportunity in direct-to-manufacturer e-procurement for mid-volume cosmetics compounders seeking compressed lead times, bypassing traditional import distributor networks. Target South Korea's functional food corridor with high-gel-strength grades exceeding 800 g/cm², leveraging the country's prebiotic fiber formulation trend and aligned regulatory thresholds with EFSA mandates. For Investors and Strategic Acquirers: The window for entry favors ISO-certified extraction protocol operators with existing pharmaceutical-grade credentials and coastal sourcing infrastructure. Long-term viability hinges on biotechnology application exposure as cell-culture media demand accelerates. Watch for tightening residual sulfur dioxide limits propagating through supply chain audit requirements as the inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Harvesting Rights | Secures preferential biomass allocation from Morocco's Atlantic coast and Indonesian waters during seasonal shortfalls. |
| Enzyme-Assisted Extraction Capacity Addition | Compresses endotoxin-compliant certification timelines for pharmaceutical-grade supply to German life-science buyers. |
| ISO 10993 Biocompatibility Certification Investment | Unlocks medical-device hydrogel wound dressing margins inaccessible to food-grade flake competitors. |
| Long-Term Supply Agreement with Fixed Volume Commitments | Locks in annual contract coverage ratios above 70 percent from South Korean functional food formulators. |
| Direct E-Procurement Platform Partnership | Disintermediates traditional import distributors for mid-volume cosmetics buyers in compressed lead time segments. |
Research Methodology
Trade databases, regulatory filings from EFSA and FDA, and industry association reports formed the secondary backbone, cross-referenced with primary interviews involving phycocolloid extraction technicians, procurement leads at German precision fermentation clusters, cosmetics compounding R&D directors, and import distributor regulatory affairs managers. Bottom-up volume modeling from algae harvest yields through extraction recovery rates combined with top-down market sizing across application segments to establish demand estimates.
Historical trendline analysis of gel-strength pricing spreads and certification premium trajectories informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application vertical, end-user procurement sophistication, and distribution channel structure. CAGRs were derived from elasticity-adjusted demand curves incorporating biotechnology substrate substitution rates and clean-label formulation mandate propagation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory divergence on residual sulfur dioxide limits and climate-driven yield volatility in Moroccan and Indonesian harvest zones. Deviation in EFSA heavy-metal threshold tightening velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Hydrolyzed Egg Market
Ingredients
Bulk Food Ingredients Market
Ingredients
Non-PHO Ingredients Market
Ingredients
Mastic Gum Market
Ingredients
Oat Ingredients Market
Ingredients
Psyllium Products Market
Ingredients
North America Algae Omega-3 Ingredients Market
Ingredients
Soy Protein Hydrolysate Market
Ingredients
Alginate Market
Ingredients
Sea Salt Market
Ingredients
North America Potato Starch Market
Ingredients
North America Phytosterols Market
Ingredients
Fruit Pectin Market
Ingredients
France Soy Protein Market
Ingredients
Passion Fruit Powder Market
Ingredients
Bean Ingredients Market