
 GCC Bakery Ingredients Market | 2026-2036
GCC Bakery Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Bakery Ingredients Market Analysis
Skilled food technologist availability is reorganizing how regional manufacturers scale clean-label and enzyme-based product lines. Cargill Inc. leverages its regional oilseed processing footprint to secure localized emulsifier and fat supply for GCC bakers. Lesaffre anchors fermentation science capabilities through technical service centers in Dubai and Riyadh, while Puratos Group specializes in sourdough and patisserie ingredient systems tailored to Middle Eastern palate preferences.
Bakery ingredients comprise formulated and commodity inputs—flours, yeasts, fats, emulsifiers, enzymes, and sweeteners—whose functional parameters such as protein content, amylograph viscosity, and oxidative stability determine dough handling, volume yield, and shelf life extension in finished baked goods. Flour and fats occupy the largest value pools given their irreplaceable volume share in every formula, though yeast and enzyme blends represent the fastest-growing margin segment as industrial bakers seek fermentation consistency and clean-label alternatives to chemical conditioners. Breads and pastries dominate application demand, with cookies and cakes gaining traction through premium gifting and café culture expansion across Gulf cities.
Saudi Food and Drug Authority and UAE Ministry of Climate Change and Environment enforce labeling, fortification, and import standards that dictate formulation compliance and cross-border ingredient registration timelines. Emirates Authority for Standardization and Metrology and Gulf Standardization Organization harmonize technical regulations across member states, reducing fragmentation but requiring multi-jurisdictional certification investments from suppliers. Stakeholders must monitor evolving halal certification requirements and sugar-reduction targets as Gulf health ministries tighten nutritional governance without diluting product sensory profiles.
Market Dynamics
Industrial bakeries across Saudi Arabia and the UAE face mounting pressure to reformulate around Gulf Standardization Organization fortification mandates while maintaining dough consistency at scale. This tension between regulatory compliance and operational continuity defines current strategic positioning.
Growth Catalysts
- SFDA vitamin-enrichment mandates:Saudi Food and Drug Authority requirements for iron and folic acid fortification in wheat flour are accelerating demand for premix and micro-nutrient systems among industrial millers.
- Quick-service restaurant expansion:Burger King, McDonald's, and regional chains are commissioning centralized commissary bakeries in Riyadh and Jeddah, pulling specialized fats and emulsifiers through the supply chain.
- Enzyme-based dough conditioning:Transglutaminase and xylanase blends are displacing chemical conditioners as clean-label priorities reshape ingredient procurement criteria across UAE commercial baking facilities.
Market Restraints
- Palm oil price volatility:Regional bakery fat formulations remain tethered to Malaysian and Indonesian palm oil futures, compressing margin predictability for emulsifier suppliers.
- Import dependency for specialty enzymes:GCC production of amylase and protease systems is negligible, concentrating supply risk with European and North American fermentation technology providers.
- Halal certification timeline friction:Emirates Authority for Standardization and Metrology registration protocols for novel ingredients extend commercialization cycles by 8-14 months versus conventional approvals.
Strategic Opportunities
- Kuwait and Bahrain underpenetration:These markets lack industrial baking clusters comparable to Saudi Arabia's Riyadh-Jeddah corridor, creating first-mover advantage for ingredient suppliers establishing technical service presence.
- Sourdough fermentation systems:Puratos-style customized cultures for Arabic bread applications represent a white space distinct from European-style artisan positioning.
- Reduced-sodium leavening innovation:UAE Ministry of Climate Change and Environment salt-reduction targets are creating procurement pull for potassium bicarbonate and alternative leavening acid systems.
Industry Challenges
- Food technologist scarcity:GCC universities produce limited graduates with bakery science specialization, forcing manufacturers to recruit from Egypt, India, and Southeast Asia at premium compensation.
- Multi-jurisdictional certification burden:Suppliers must maintain separate halal, SFDA, and ESMA registrations despite Gulf Standardization Organization harmonization efforts, duplicating compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Bakery Ingredients Market |
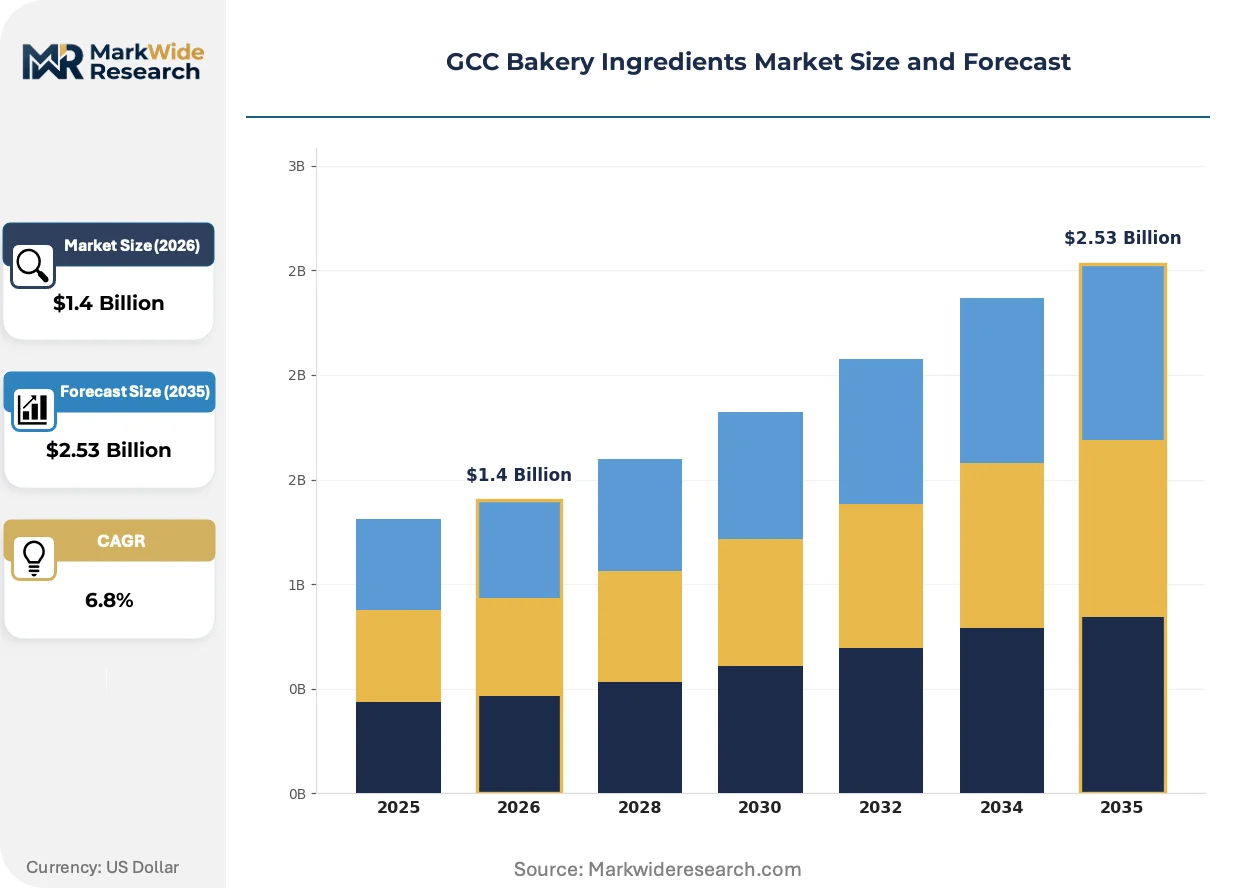
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flour, Sugar, Yeast, Fats Application: Breads, Pastries, Cakes, Cookies Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesalers End User: Commercial Bakeries, Retail Bakeries, Home Bakers, Foodservice |
| Companies Covered | Lesaffre, IFFCO Group, Cargill Inc., Agthia, Almarai, Archer Daniels Midland, Puratos Group, Corbion, Kerry Group, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Bakery Ingredients Market Emerging Trajectories
Clean-label fermentation science and precision enzyme engineering are displacing decades-old chemical conditioning protocols across Gulf industrial baking. This technological transition intersects with tightening nutritional governance and evolving foodservice procurement models.
Enzyme-based dough conditioning is bifurcating the ingredient supply landscape. Transglutaminase, xylanase, and lipase systems strengthen gluten networks and extend shelf life without E-number declarations. Saudi industrial bakeries serving retail chains are adopting these systems at 18-24 month replacement cycles, while smaller UAE facilities lag. The technology is bifurcating supplier relationships: ingredient houses with in-house fermentation science capabilities capture formulation partnerships, while commodity traders lose share in premium segments.
Gulf Standardization Organization harmonization of fortification standards is compressing cross-border formulation variance. The GSO 2698 standard for wheat flour enrichment now applies across Saudi Arabia, UAE, Kuwait, Bahrain, Qatar, and Oman, reducing the prior patchwork of national specifications. Industrial millers must maintain single premix formulations for multi-country distribution, simplifying supply chain complexity but raising compliance stakes for deviation. Bahrain and Qatar importers report faster clearance times under unified documentation protocols.
Centralized procurement by quick-service restaurant chains is consolidating supplier relationships at the expense of traditional distributor networks. KFC, Hardee's, and regional players like Al Baik are negotiating direct supply agreements with Cargill and regional fat processors for their commissary operations. This bypasses the legacy wholesale channel that historically fragmented purchasing across independent bakeries. The shift is most visible in Dubai's Jebel Ali industrial zone, where dedicated foodservice ingredient terminals now operate adjacent to cold-chain logistics hubs.
GCC Bakery Ingredients Market Segmentation
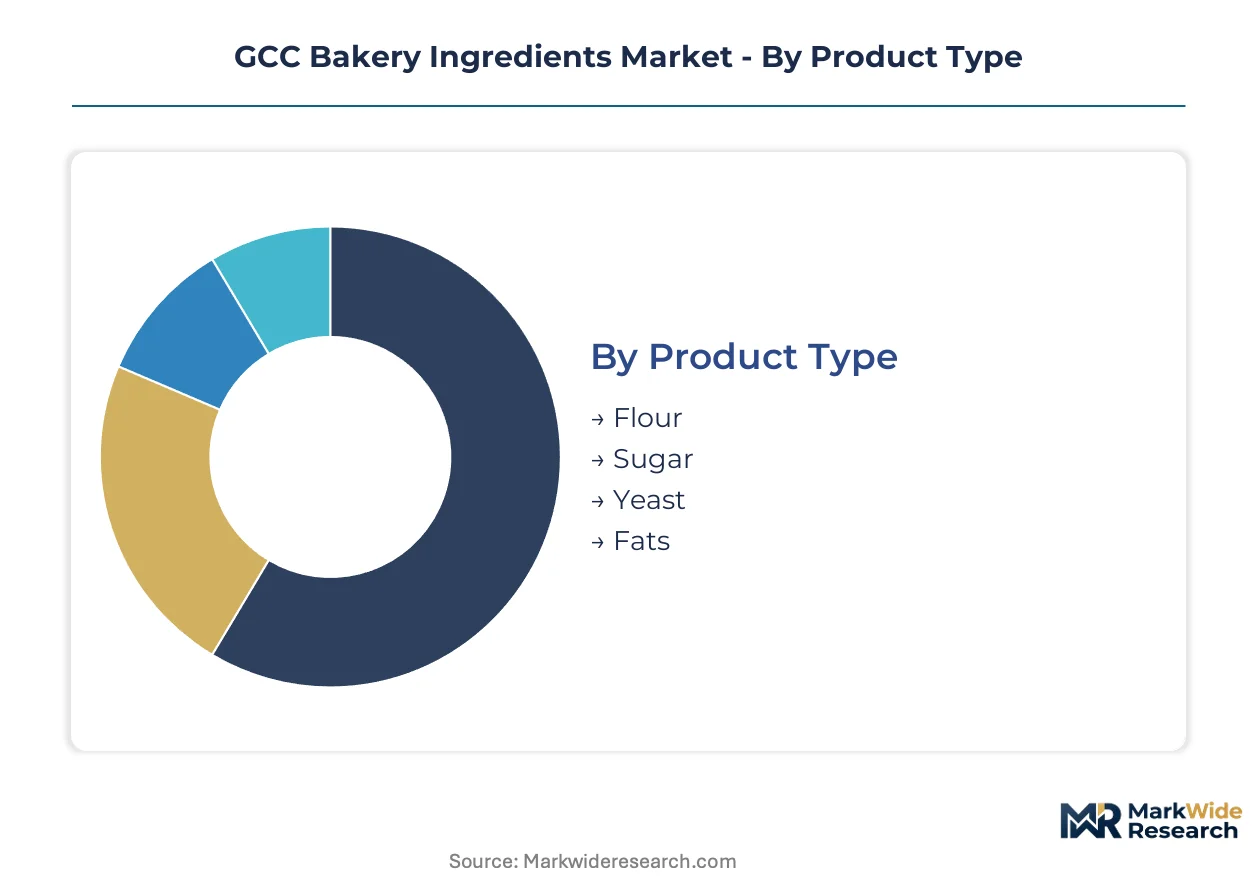
Ingredient segmentation in the GCC bakery market reveals how procurement priorities diverge between industrial scale operations and artisanal producers. Category boundaries increasingly blur as manufacturers bundle functional systems rather than selling commodities in isolation.
Product Type:
Margin pools concentrate in enzyme-enhanced flour systems and specialized fat emulsifiers where technical differentiation commands pricing power.
- Flour:Wheat flour dominates volume, with protein content specifications ranging from 9.5% for Arabic flatbreads to 12.5% for European-style pan breads. Saudi industrial millers in the Riyadh-Jeddah corridor are consolidating procurement of vitamin-premixed flour to meet SFDA fortification mandates while reducing in-house blending complexity.
- Fats:Shortening and margarine formulations incorporate palm oil fractions with tailored melting profiles for Gulf climate stability. UAE commercial bakeries serving quick-service restaurant commissaries specify oxidative stability above 20 hours to withstand extended supply chain holding periods.
- Sugar:Refined cane sugar from Brazilian and Indian origins supplies sweetness and browning functionality across all bakery categories.
- Yeast:Compressed and instant dried yeast strains optimized for high-osmotic dough environments characteristic of regional sweet bread preferences.
The dominant share belongs to flour, while fats is closing the gap fastest through emulsifier-enhanced premium formulations.
Application:
Volume throughput and formulation complexity separate commodity bread production from premium pastry lines requiring precise aeration control.
- Breads:Arabic flatbreads and sliced pan breads consume the largest ingredient tonnage, with industrial lines in Riyadh and Jeddah operating at continuous throughput. SFDA-mandated folic acid and iron fortification has standardized premix inclusion rates across Saudi production facilities.
- Pastries:Croissants, Danish, and laminated dough applications demand specialized fat-in-water emulsifiers and controlled-release leavening acids. Dubai's hotel and café sector expansion is pulling European-style laminated dough ingredient systems through Puratos and regional distributors.
- Cakes:Aerated sponge and pound cake formulations rely on emulsifier-sugar-fat synergy for volume and crumb structure.
- Cookies:Biscuit and shortbread applications favor low-protein flours with precise granulation for spread control and snap texture.
Breads commands absolute volume leadership, though pastries demonstrates the steepest expansion trajectory as Gulf foodservice premiumization accelerates.
Distribution Channel:
Channel selection reflects customer scale, with large commercial bakeries bypassing traditional wholesale intermediaries.
- Wholesalers:Traditional distribution networks serving independent retail bakeries across smaller GCC markets like Bahrain and Oman. These channels bundle commodity flour, sugar, and fats with credit terms and small-lot delivery flexibility.
- Supermarkets:Retail ingredient packs targeting home bakers and small commercial operations in UAE and Saudi urban centers.
- Specialty Stores:Professional bakery supply outlets concentrating in Dubai's Deira and Riyadh's Al-Batha districts, stocking premium chocolate, specialty fats, and decorating ingredients.
- Online:E-procurement platforms gaining traction among mid-sized UAE bakeries seeking direct manufacturer pricing on enzyme systems and clean-label ingredients.
Wholesalers retains the largest transaction volume, while online is gaining share fastest among technically sophisticated buyers seeking formulation support.
End User:
User type determines ingredient specification rigor, from commodity buying at scale to precision formulation for consistency-critical chains.
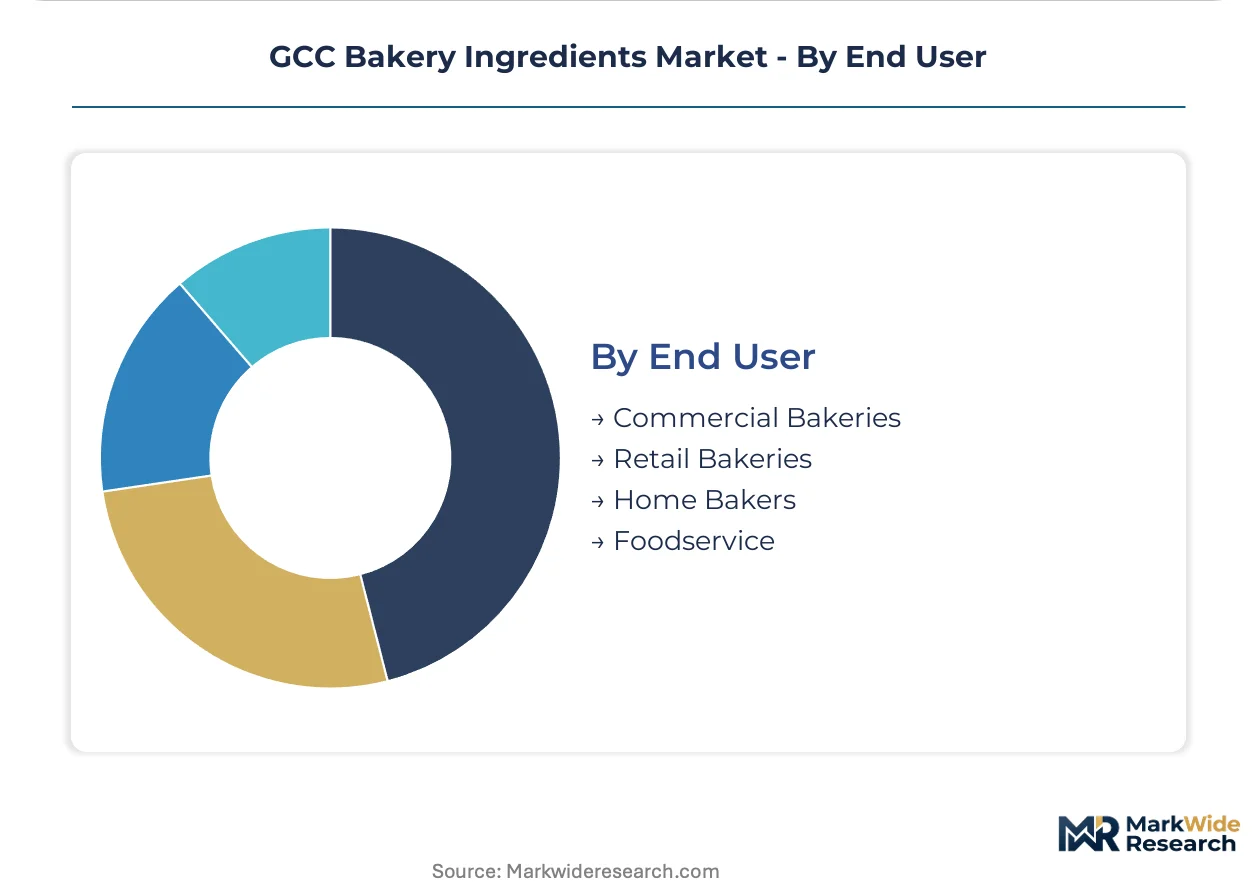
- Commercial Bakeries:Industrial facilities supplying retail chains and foodservice accounts across Saudi Arabia's Central and Western provinces. These operations specify enzyme-based dough conditioners and pre-fortified flour streams to minimize process variation at high throughput.
- Foodservice:Quick-service restaurant commissaries and hotel central kitchens in Dubai and Jeddah demanding ingredient systems with guaranteed performance across multiple outlet locations.
- Retail Bakeries:Independent shops and small chains producing fresh daily for neighborhood catchments in Kuwait City and Manama.
- Home Bakers:Consumer segment purchasing pre-mixes and specialty ingredients through retail channels, particularly active during Ramadan and Eid gifting seasons.
Commercial bakeries holds the dominant procurement position, yet foodservice is expanding most quickly as chain commissary centralization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA fortification mandates and industrial baking cluster expansion define the GCC bakery ingredients landscape. Saudi Arabia anchors regional demand through centralized production corridors serving retail and foodservice channels. National health authorities across member states are tightening nutritional governance without diluting sensory performance.
Saudi Arabia
Commercial bakeries in the Riyadh-Jeddah corridor are scaling capacity to supply quick-service restaurant chains and hotel networks. SFDA mandates for iron and folic acid fortification in wheat flour are accelerating premix procurement among industrial millers. Centralized industrial baking clusters now supply both domestic retail channels and cross-border foodservice accounts.
United Arab Emirates
Dubai's hotel and café sector expansion is pulling European-style laminated dough ingredient systems through specialized distributors. MOCCAE salt-reduction targets are creating procurement demand for potassium bicarbonate and alternative leavening acid systems. Jebel Ali industrial zone hosts dedicated foodservice ingredient terminals adjacent to cold-chain logistics hubs.
Kuwait
Retail bakeries in Kuwait City operate without comparable industrial clustering to Saudi Arabia's centralized corridors. The country's national food regulator enforces GSO 2698 fortification standards through import clearance protocols. Independent baking operations rely on traditional wholesale channels bundling commodity flour, sugar, and fats with credit terms.
Bahrain
Industrial baking infrastructure remains underdeveloped relative to larger GCC economies, creating whitespace for technical service presence. GSO harmonization has accelerated clearance times for fortified flour imports under unified documentation protocols. Manama-based retail bakeries serve neighborhood catchments with limited scale for direct manufacturer procurement.
Qatar
Foodservice procurement for hospitality and event catering drives demand for premium patisserie ingredient systems. National standards alignment with GSO 2698 has streamlined cross-border formulation compliance for multi-country suppliers. Doha-based central kitchens for hotel chains specify ingredient performance guarantees across multiple outlet locations.
GCC Bakery Ingredients Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the GCC bakery ingredients market. Multinational fermentation science houses and regional agribusiness conglomerates occupy distinct competitive positions. Three archetypes dominate: global ingredient technology providers with technical service centers, regional oilseed processors leveraging localized supply, and specialized patisserie system formulators. Capacity expansion in emulsifier production and strategic partnerships for enzyme distribution represent the dominant competitive moves.
Within the integrated multinational tier, Lesaffre and Cargill Inc. anchor regional positioning through established technical infrastructure. Cargill leverages its oilseed processing footprint to secure localized emulsifier and fat supply for GCC bakers. Lesaffre represents the fermentation science archetype with technical service capabilities in Dubai and Riyadh. Puratos Group occupies the specialized patisserie system position, focusing on sourdough and ingredient systems adapted to Middle Eastern palate preferences.
| Leading Market Players |
|---|
| Lesaffre |
| IFFCO Group |
| Cargill Inc. |
| Agthia |
| Almarai |
| Archer Daniels Midland |
| Puratos Group |
| Corbion |
| Kerry Group |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles for specialty enzymes from European fermentation houses concentrate pricing power with a handful of North American and European suppliers serving GCC industrial bakeries. This lead-time band creates asymmetric cost pass-through where regional formulators absorb palm oil volatility while enzyme premix costs track supplier currency and energy exposures.
Pricing Analysis
Price spreads between Dubai and Riyadh for emulsifier-enhanced shortening formulations run 8-12 percent above landed costs from Jebel Ali terminals. Three-tier pricing structure across premium enzyme systems, standard fortified flours, and economy commodity fats separates formulation complexity tiers. Cost compression in palm-derived fat categories is intensifying because Malaysian futures volatility feeds directly into regional margarine pricing. Quick-service restaurant commissaries demonstrate lowest price sensitivity due to performance guarantees, while independent retail bakeries in Bahrain and Oman negotiate aggressively on volume rebates.
Supply Chain Analysis
Specialty enzyme inventories stretching 60-90 days from European fermentation centers expose GCC formulators to euro-denominated cost shifts and maritime schedule reliability. Supply concentration rests on Belgium, the Netherlands, and Denmark for amylase and lipase systems, while palm oil fractions draw from Malaysia and Indonesia. Single-source vulnerability characterizes transglutaminase supply where two global houses control fermentation IP. Distribution runs through Jebel Ali consolidated terminals for UAE and Saudi industrial corridors, with break-bulk operations serving Kuwait and Bahrain via Dammam transshipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
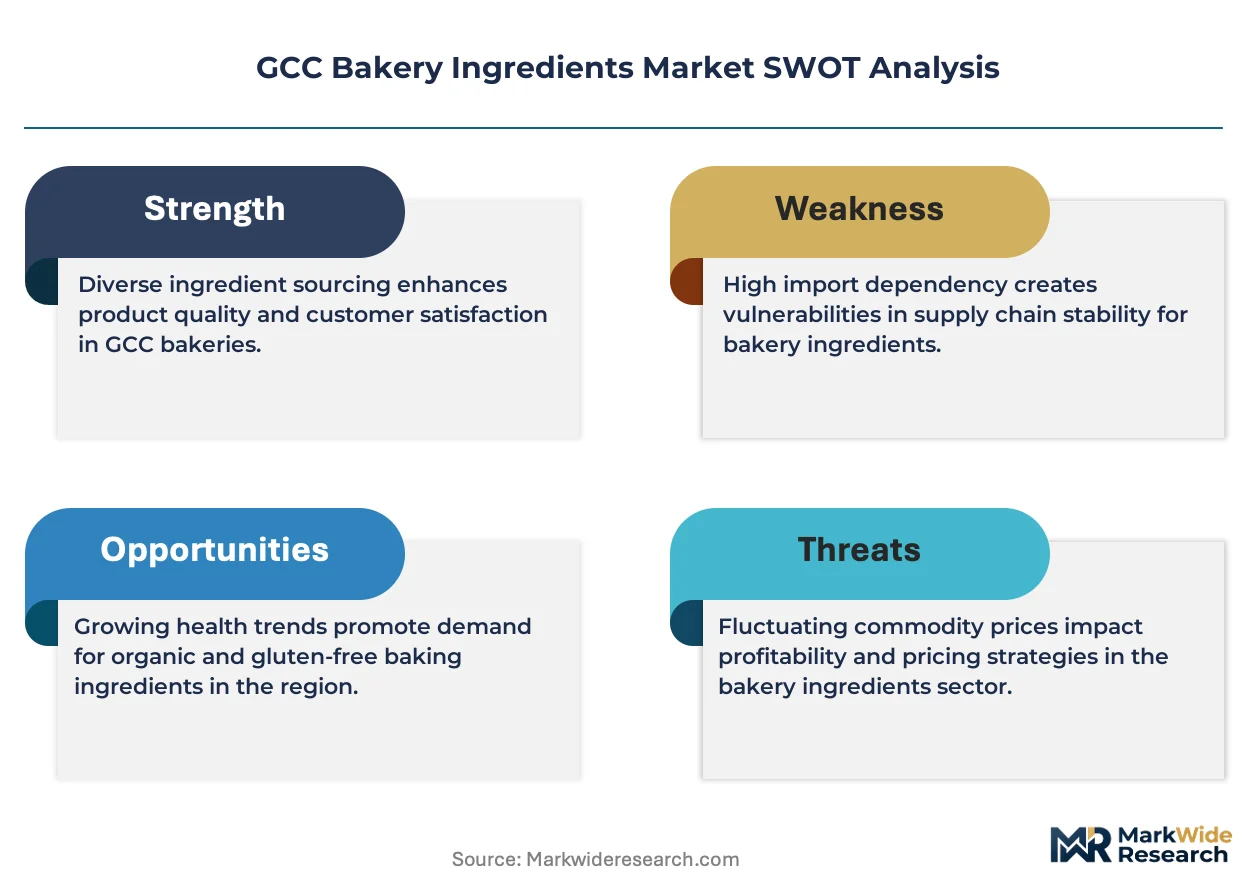
Fragmentation across national regulatory implementations and uneven industrial baking infrastructure creates multiple entry points for specialized ingredient suppliers. Clean-label reformulation mandates are splintering procurement criteria in ways that favor technical service capabilities over commodity scale.
For Market Incumbents: Compound technical service density in Dubai and Riyadh to capture enzyme-based dough conditioning transitions displacing chemical conditioners. Deepen backward integration into regional oilseed processing to defend margin position against palm price volatility. Prioritize multi-jurisdictional halal certification investments to reduce approval timeline friction for novel fermentation-derived ingredients. For New Entrants and Emerging Players: ESMA fast-track registration protocols for GSO-harmonized premix formulations offer accelerated market access versus conventional 8-14 month cycles. Kuwait and Bahrain industrial baking infrastructure gaps represent the most penetrable whitespace, particularly for sourdough culture systems adapted to Arabic bread applications. Lead with technical service partnerships rather than commodity pricing to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across enzyme distribution and formulation blending sub-segments as fermentation science commoditizes. Five-to-ten year viability favors acquisition targets with captive halal certification capabilities and established technical service relationships with Saudi industrial millers. Watch for GSO fortification mandate expansion beyond wheat flour into yeast and fat categories as inflection signal for premix supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Technical Service Center Expansion | Lesaffre-style fermentation science capabilities in Riyadh anchor formulation partnerships with industrial millers. |
| Backward Integration into Oilseed Processing | Cargill leverages regional crushing assets to secure localized emulsifier supply for quick-service restaurant commissaries. |
| Multi-Jurisdictional Halal Certification Investment | Unified SFDA-ESMA registration reduces commercialization cycles for novel enzyme systems across Saudi and UAE markets. |
| Sourdough Culture System Localization | Puratos-style customized fermentation cultures for Arabic bread applications address unmet Middle Eastern palate preferences. |
| Reduced-Sodium Leavening R&D Partnership | Potassium bicarbonate innovation aligns with MOCCAE salt-reduction targets in UAE hotel and café supply chains. |
Methodological Framework
A standing panel of industrial bakery operations managers, food technology procurement leads, and SFDA regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from GSO technical standards documentation, Saudi customs import clearance records, Emirates Authority for Standardization and Metrology registration filings, and Gulf food industry trade publications. Bottom-up volume estimates from flour miller and fat processor throughput data were triangulated against top-down spending patterns from quick-service restaurant supply chain disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated product type tiers, application complexity levels, distribution channel structures, and end-user scale categories. CAGRs were derived from trend extrapolation of industrial baking capacity expansion announcements and regulatory mandate implementation schedules. Forecast inputs included enzyme substitution rates for chemical conditioners and fortification premix adoption curves tied to SFDA compliance deadlines.
The analysis sits within stated boundaries; outcomes outside sustained Gulf Standardization Organization harmonization progress or abrupt palm oil supply disruptions would require recalibration. Forecasts reflect documented assumptions regarding industrial baking cluster expansion timelines and regulatory enforcement consistency. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Europe Protein Market
Ingredients
India Bakery Ingredients Market
Ingredients
Bean Ingredients Market
Ingredients
APAC Savoury Ingredients Market
Ingredients
Corn Starch Market
Ingredients
North America Cheese Powder Market
Ingredients
Confectionery Ingredients Market
Ingredients
United Kingdom Gelatin Market
Ingredients
Xylooligosaccharide Market
Ingredients
Dried Beet Pulp Market
Ingredients
United States Wheat Protein Market
Ingredients
United States Corn Glucose Market
Ingredients
Potato Protein Market
Ingredients
North America Algae Omega-3 Ingredients Market
Ingredients
Global Dietary Fibers Market
Ingredients
Grapeseed Oil Market