
 Colombia Food Ingredients Market | 2026-2036
Colombia Food Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Food Ingredients Market Outlook
Consolidation among Colombia's large bakery and dairy processors is restructuring upstream ingredient procurement, pushing suppliers toward longer-term volume contracts and technical service partnerships. Cargill Incorporated anchors its position through extensive oilseed processing infrastructure near Cali and Barranquilla. Ingredion Incorporated specializes in native starch and texturizer solutions tailored to tropical formulation challenges. BASF SE competes on vitamin and micronutrient premixes for fortification programs mandated by Colombian public health policy.
Food ingredients encompass functional additives, flavor compounds, nutritional enhancers, and texturizing agents that modify shelf stability, sensory profile, or micronutrient density in processed and prepared foods; these inputs typically comply with Codex Alimentarius specifications and local purity standards enforced by INVIMA. Sweeteners and preservatives command substantial volume share as beverage and snack processors seek cost-optimized stability solutions. Emulsifiers and thickeners attract accelerated interest from dairy innovators developing ambient-stable, clean-label products for Colombia's expanding retail chilled and UHT segments.
Colombia's INVIMA, the Ministry of Health and Social Protection, and the National Food and Drug Surveillance Institute collectively govern additive maximum limits, labeling disclosures, and import registration requirements for food ingredient inputs. FSSAI-aligned technical standards and Mercosur technical regulations additionally influence cross-border formulation norms for exporters serving Andean and Southern Cone markets. Stakeholders must monitor pending INVIMA consultations on revised preservative thresholds and traceability mandates that will determine qualification costs for domestic and imported ingredient portfolios.
Market Dynamics
INVIMA's pending traceability mandates and revised preservative thresholds are compressing reformulation timelines for Colombian processors, forcing ingredient suppliers to accelerate technical service deployment and pre-qualify alternative formulations ahead of enforcement windows.
Growth Catalysts
- Clean-label dairy expansion:Sabana de Bogotá processors are retrofitting UHT lines to accommodate native starch and plant-based emulsifiers, creating pull-through demand for texturizer portfolios.
- INVIMA fortification alignment:Public health mandates on micronutrient density in processed foods are expanding premix volumes for vitamin D, iron, and folic acid across bakery and beverage categories.
- Andean export corridor development:Mercosur technical regulation convergence is enabling Colombian ingredient formulators to qualify single SKUs for cross-border sale into Ecuador, Peru, and Chile.
Market Restraints
- Palm oil price volatility:Emulsifier and shortening costs fluctuate with Malaysian and Indonesian crude palm oil benchmarks, compressing margin visibility for Colombian bakery processors.
- Import registration bottlenecks:INVIMA's single-window system creates 90-120 day qualification delays for novel additives, favoring incumbent suppliers with approved dossiers.
- Natural preservative performance gaps:Clean-label antimicrobials such as cultured dextrose and vinegar derivatives fail to match synthetic shelf-life extension in tropical ambient distribution.
Strategic Opportunities
- Pacific coast oilseed infrastructure:Cali-Buenaventura logistics clusters offer captive crushing and refining capacity for non-GMO lecithin and specialty lipid production.
- Amazonian bioactive sourcing:Untapped supply of camu camu, açaí, and sacha inchi proteins supports functional ingredient positioning for export markets.
- E-commerce ingredient distribution:Direct-to-kitchen sales channels for artisanal bakers and small-batch processors bypass traditional distributor markups in Medellín and Barranquilla.
Industry Challenges
- Reformulation technical capacity:Bogotá and Medellín R&D centers face shortages of food chemists trained in tropical stability modeling and accelerated shelf-life testing protocols.
- Legacy ERP integration:Mid-tier processors struggle to align batch records with INVIMA's forthcoming digital traceability platform, requiring capex outlays for MES upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Food Ingredients Market |
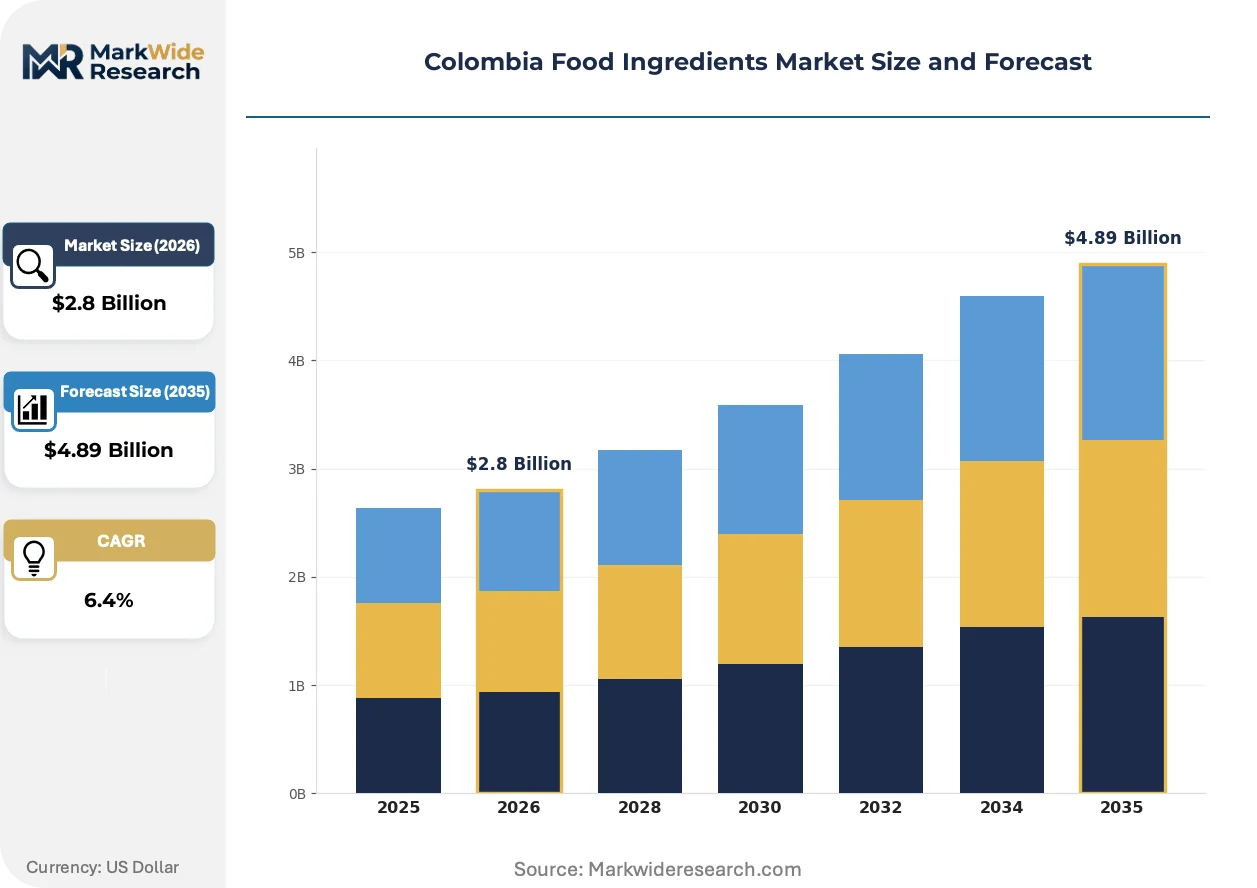
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsifiers, Thickeners, Sweeteners, Preservatives End User: Bakery, Dairy, Snacks, Beverages Application: Food Processing, Nutraceuticals, Flavoring, Organic Products Distribution Channel: Online Sales, Retail, Wholesale, Direct Sales |
| Companies Covered | Archer Daniels Midland Company, Firmenich SA, Cargill Incorporated, Associated British Foods PLC, BASF SE, Ingredion Incorporated, DuPont, Aceites y Grasas Vegetales S.A., DSM, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Food Ingredients Market Strategic Shifts
Enzymatic processing and fermentation-derived ingredients are displacing chemical synthesis across Colombia's ingredient supply base, with tropical-adapted strains and ambient-stable formats commanding premium positioning in dairy and beverage applications.
Precision fermentation for dairy protein analogs is rewriting the competitive map for emulsifier and texturizer suppliers. Cali-based pilot facilities are scaling whey and casein alternatives using Colombian sugarcane feedstock. Sabana de Bogotá dairy innovators are reformulating ambient-stable desserts around these inputs, compressing reliance on imported milk solids and creating captive demand for locally produced fermentation bases.
INVIMA's consultation on revised preservative maximum limits is forcing accelerated clean-label migration across the snack and sauce categories. Processors are pre-qualifying cultured celery powder and high-pressure processing combinations to maintain shelf stability. The beverage segment, particularly ambient juices in Cartagena and Barranquilla distribution zones, faces the steepest compliance cliff and is consolidating supplier relationships around technical service-capable partners.
Direct sourcing contracts between Medellín snack manufacturers and Amazonian fruit pulp suppliers are shortening ingredient provenance chains. Small-batch processors are bypassing traditional Bogotá-based distributors, negotiating volume commitments with cooperatives in Putumayo and Caquetá. This disintermediation is most visible in the premium chocolate and functional beverage verticals, where single-origin claims command shelf price premiums in domestic and export markets.
Colombia Food Ingredients Market Segmentation
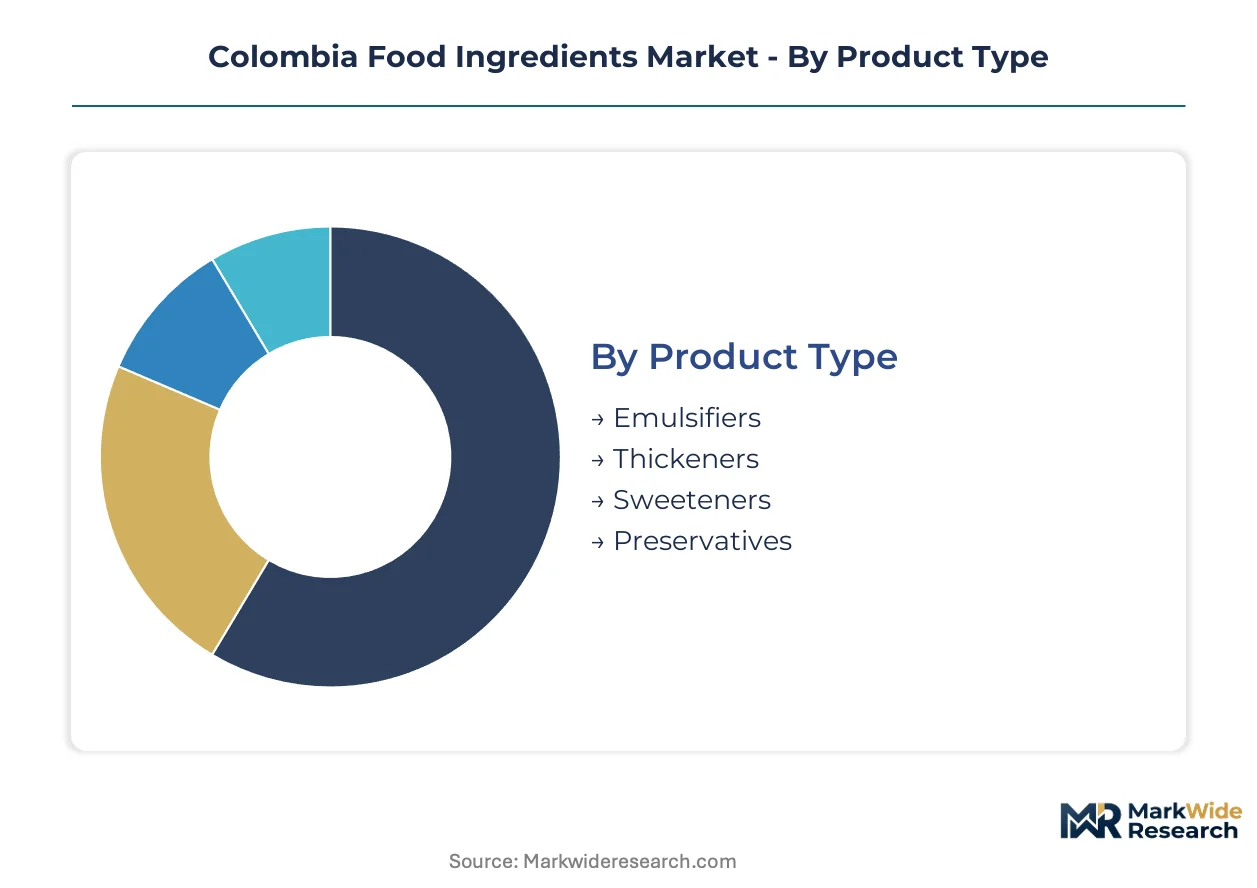
Ingredient procurement patterns across Colombia diverge sharply by functional category and end-use sophistication. Sabana de Bogotá dairy processors and Medellín snack manufacturers drive divergent specification requirements that reshape supplier priorities.
Product Type:
Capital intensity peaks with emulsifier manufacturing, where spray-drying towers and lipid fractionation equipment dominate upfront investment. Sweetener and preservative segments require less specialized infrastructure but face steeper regulatory qualification costs.
- Emulsifiers:Lecithin, mono- and diglycerides, and polysorbates stabilize oil-water interfaces in UHT dairy and ambient sauces. Sabana de Bogotá processors retrofitting clean-label lines are pulling native starch-emulsifier blends to replace synthetic alternatives ahead of INVIMA threshold revisions.
- Thickeners:Starches, hydrocolloids, and proteins build viscosity and mouthfeel in reduced-fat formulations. Demand concentrates in tropical-adapted dairy desserts where ambient distribution stress-tests stability performance.
- Sweeteners:Sucrose, high-fructose syrups, and polyols balance cost and glycemic positioning across beverage and bakery portfolios.
- Preservatives:Sorbates, benzoates, and emerging cultured dextrose solutions extend shelf life under tropical humidity. Clean-label migration is compressing synthetic volumes as processors pre-qualify natural alternatives.
Most installed capacity flows through emulsifiers and sweeteners. Expansion is steepest in preservative alternatives as reformulation timelines accelerate.
End User:
Customer scale and technical service expectations segment the supplier landscape, with multinational dairy processors demanding integrated R&D partnerships that artisanal bakeries cannot justify.
- Bakery:Large processors in Bogotá and Cali consolidate procurement around volume contracts for emulsifiers and shortenings. Margins compress when palm oil benchmarks spike.
- Dairy:UHT and chilled segment innovators in Sabana de Bogotá drive native starch and fermentation-derived texturizer demand. Fortification mandates expand premix volumes.
- Snacks:Medellín manufacturers prioritize shelf-life extension and clean-label positioning in export-bound portfolios.
- Beverages:Ambient juice processors in Cartagena and Barranquilla face the steepest preservative compliance pressure.
Dairy commands the deepest technical integration with suppliers. Snack and beverage segments are gaining share fastest through clean-label retrofit investments.
Application:
Application complexity determines qualification depth, with nutraceutical and organic categories demanding traceability documentation that commodity food processing often bypasses.
- Food Processing:Mass-market stability and sensory modification for packaged goods. Volume concentrates in dairy and snack verticals with established INVIMA dossiers.
- Nutraceuticals:Vitamin, mineral, and bioactive fortification aligned with public health mandates. Premix suppliers compete on micronutrient density certification.
- Flavoring:Natural extracts and synthetic compounds for taste modulation. Amazonian sourcing is shortening provenance chains for premium positioning.
- Organic Products:Certified inputs for domestic and export markets requiring full supply chain segregation. Registration bottlenecks favor incumbent suppliers with approved organic dossiers.
Food processing absorbs the largest ingredient volumes. Nutraceutical applications are climbing the fastest as fortification mandates expand across categories.
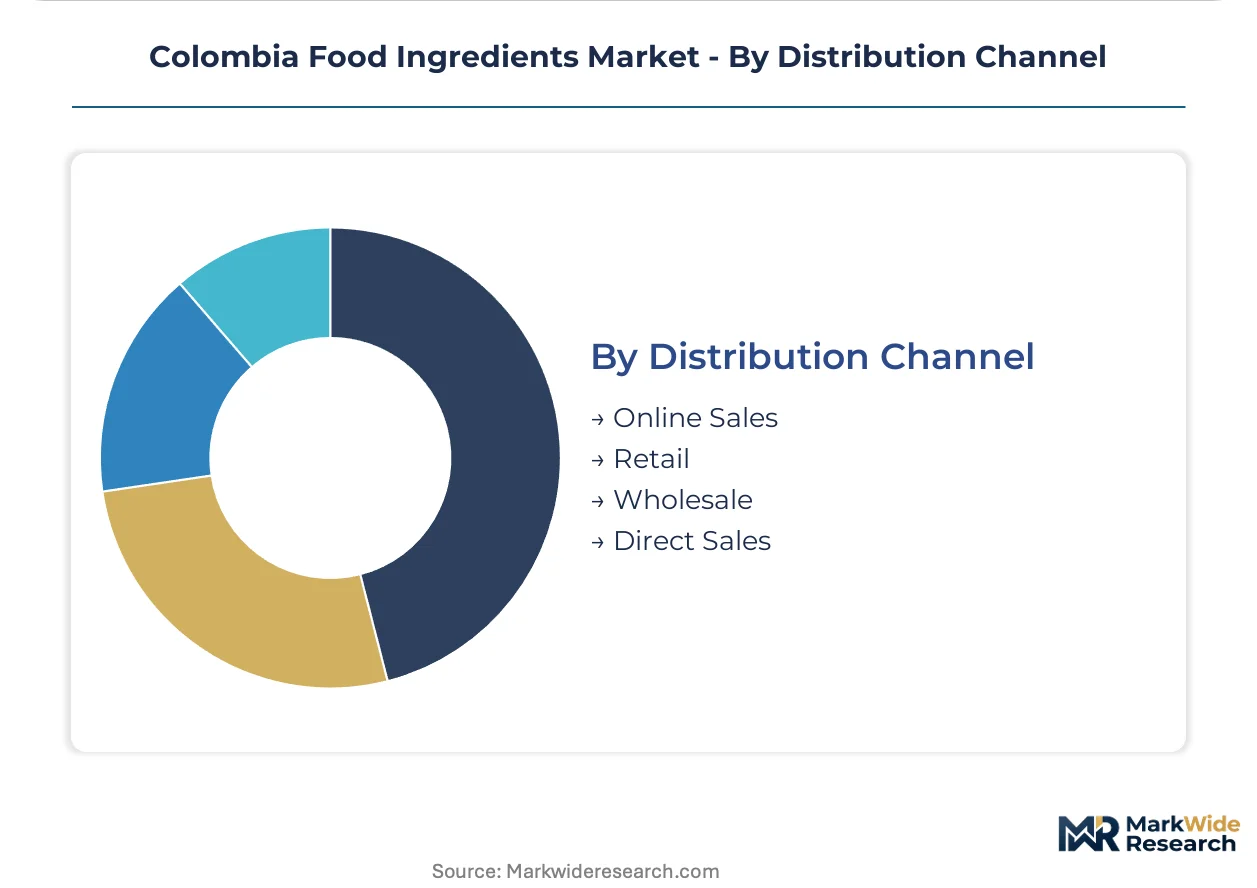
Distribution Channel:
Channel selection reflects customer scale and technical support requirements, with bulk processors bypassing intermediaries while small-batch buyers fragment across multiple access points.
- Online Sales:Direct-to-kitchen platforms serving artisanal bakers and small-batch processors in Medellín and Barranquilla. Disintermediation is compressing traditional distributor markups.
- Retail:Packaged ingredient sales through cash-and-carry and specialized food service suppliers. Limited to lower-volume, higher-SKU portfolios.
- Wholesale:Traditional Bogotá-based distributors serving regional processors with consolidated logistics and credit terms.
- Direct Sales:Technical service partnerships between multinational suppliers and large dairy and bakery processors. Long-term contracts lock in volume and formulation support.
Direct sales and wholesale dominate current volumes. Online channels are expanding most quickly as small-processor digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Colombia's ingredient demand patterns diverge from Peru's export-oriented fortification focus, creating distinct procurement corridors across the Andean region. Regulatory harmonization pressures from Mercosur technical regulations are reshaping cross-border formulation standards.
Sabana de Bogotá
UHT dairy processors drive native starch and plant-based emulsifier procurement as INVIMA threshold revisions accelerate reformulation timelines. Public health mandates on micronutrient density expand vitamin premix volumes across bakery and beverage categories. Bogotá-based R&D centers face shortages of food chemists trained in tropical stability modeling.
Medellín
Snack manufacturers prioritize shelf-life extension solutions and clean-label positioning for export-bound portfolios. Direct sourcing contracts with Amazonian fruit pulp suppliers shorten provenance chains for premium chocolate verticals. Small-batch processors bypass traditional distributors through e-commerce ingredient platforms.
Cali-Buenaventura Corridor
Oilseed crushing infrastructure anchors non-GMO lecithin and specialty lipid production for domestic emulsifier supply. Cargill Incorporated maintains extensive processing capacity near Cali. Pacific coast logistics clusters offer captive refining capacity that reduces import dependency for bakery shortenings.
Barranquilla-Cartagena
Ambient juice processors face steep preservative compliance pressure as INVIMA consultations revise maximum limits. Beverage innovators pre-qualify cultured celery powder and high-pressure processing combinations. Distribution zones concentrate demand for tropical-stable clean-label antimicrobials.
Colombia Food Ingredients Market Competitive Environment
North American multinationals anchor one tier through integrated oilseed and starch processing infrastructure; European specialists hold formulation technology leadership in micronutrient premixes. Market structure tilts toward consolidated procurement relationships with large dairy and bakery processors. Three archetypes dominate: integrated agribusiness operators with captive crushing capacity, technical service-focused ingredient innovators, and regional distributors with INVIMA-approved import dossiers. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers pre-qualify alternative formulations ahead of enforcement windows.
Within the integrated agribusiness tier, Cargill Incorporated and Archer Daniels Midland Company occupy positions defined by upstream oilseed control and extensive processing infrastructure near Cali and Barranquilla. Among formulation technology specialists, BASF SE and DSM exemplify the micronutrient premix archetype serving fortification mandates. Ingredion Incorporated represents the native starch and texturizer specialization tailored to tropical dairy challenges.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Firmenich SA |
| Cargill Incorporated |
| Associated British Foods PLC |
| BASF SE |
| Ingredion Incorporated |
| DuPont |
| Aceites y Grasas Vegetales S.A. |
| DSM |
| Others |
Value Chain & Pricing Dynamics
Multinational dairy processors in Sabana de Bogotá anchor procurement volumes and compress supplier margins through consolidated long-term contracts tied to palm oil benchmarks. Their scale dominance forces ingredient vendors into technical service bundling that obscures pure price competition.
Pricing Analysis
Capacity additions in Malaysia and Indonesia are reshaping price floors for lecithin and specialty lipid inputs. Three-tier pricing structure across premium, standard, and economy levels separates INVIMA-certified clean-label grades from conventional synthetic alternatives. Cost compression in bakery emulsifiers is intensifying because Malaysian crude palm oil volatility transmits directly into shortening costs. Small-batch processors in Medellín exhibit the highest price sensitivity, while UHT dairy innovators in Bogotá prioritize stability performance over unit cost.
Supply Chain Analysis
Emulsifier supply rests on Malaysian and Indonesian crude palm oil extraction, Colombian non-GMO soybean crushing near Cali, and Brazilian specialty lipid refining. Key inputs include crude palm oil, degummed soybean oil, and fractionated coconut oil. Single-source vulnerability concentrates in Southeast Asian oleochemical feedstock where geopolitical disruption risks cascade into Colombian bakery input costs. Distribution runs through Bogotá-based wholesale distributors for mid-tier processors and direct technical service partnerships for multinational dairy accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
INVIMA's pending traceability mandates and revised preservative thresholds compound regulatory-driven demand for pre-qualified clean-label formulations. This regulatory compounding accelerates supplier consolidation around dossier-capable incumbents.
For Market Incumbents: Deploy backward integration into Amazonian bioactive sourcing to secure camu camu and açaí supply chains before cooperatives consolidate bargaining power. Accelerate technical service headcount in Bogotá R&D centers to capture reformulation timelines from processors facing INVIMA compliance cliffs. Threat substitution from precision fermentation-derived dairy proteins demands native starch-emulsifier blend innovation to maintain texturizer relevance. For New Entrants and Emerging Players: INVIMA's revised preservative maximum limits in Colombia opens a window for cultured dextrose and high-pressure processing solution providers to penetrate ambient juice processors in Cartagena and Barranquilla. White-space concentrates in e-commerce direct-to-kitchen platforms serving artisanal bakers in Medellín, plus Amazonian single-origin functional ingredients for export-bound premium chocolate. Go-to-market leverage disintermediation economics against traditional Bogotá distributor markups. For Investors and Strategic Acquirers: Integrated agribusiness operators with captive oilseed crushing capacity are the most active acquirer in this space, targeting technical service-focused ingredient innovators with INVIMA-approved dossiers. Long-term viability hinges on regulatory qualification moats deepening through enforcement window timing. Acquisition target archetype: regional distributors with established import registration pipelines and Amazonian cooperative sourcing relationships. Watch INVIMA's digital traceability platform launch timeline as inflection indicator for MES upgrade capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amazonian Sourcing | Captive supply of camu camu and açaí secures premium functional ingredient positioning for export markets. |
| Technical Service Partnership Expansion | Dedicated Bogotá R&D support locks in long-term volume contracts with UHT dairy retrofit programs. |
| INVIMA Dossier Pre-qualification | Accelerated alternative formulation approval compresses competitor response windows ahead of enforcement. |
| E-commerce Platform Development | Direct-to-kitchen sales bypass traditional distributor markups in Medellín artisanal baker segments. |
| Precision Fermentation Pilot Scale-up | Cali-based whey and casein alternatives reduce import dependency for Sabana de Bogotá dairy innovators. |
Study Parameters
Bottom-up dairy and snack processor modeling reconciled against top-down oilseed and starch supply tracking forms the analytical core. Primary interviews with INVIMA regulatory affairs leads, Bogotá-based food chemists, procurement directors at multinational dairy processors, Amazonian cooperative managers, and Cali oilseed plant operators combined with secondary validation from INVIMA consultation documents, Colombian customs trade data, FSSAI-aligned technical standards, and Mercosur regulatory filings. Triangulation across these sources ensures segmentation integrity.
Historical trendline analysis of emulsifier and texturizer procurement patterns informed projection modeling across the analysis window. Segmentation dimensions include functional category, end-use sophistication tier, application complexity, and distribution channel type. CAGRs derived from volume-weighted trajectory fitting adjusted for regulatory enforcement timing and palm oil benchmark volatility. Industry-specific forecast inputs incorporate INVIMA consultation outcome probabilities and tropical stability performance thresholds.
Revisions become necessary when INVIMA enforcement windows shift, palm oil benchmarks experience sustained volatility, or Mercosur technical regulations diverge from Colombian standards. Forecasts reflect documented assumptions about regulatory timeline adherence and cooperative supply chain scaling. A small set of named triggers warrants ongoing watch: INVIMA digital traceability platform launch, Malaysian crude palm oil export policy changes, and Amazonian cooperative consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Quark Powder Market
Ingredients
Vitamin C Ingredients Market
Ingredients
South America Insoluble Dietary Fibers Market
Ingredients
Soy and Milk Protein Ingredients Market
Ingredients
Drum to Hopper Blends Market
Ingredients
Global Malt Extracts and Ingredients Market
Ingredients
Non-GMO Soya Market
Ingredients
Fucoidan Extract Market
Ingredients
Casein Market
Ingredients
Mineral Premix Market
Ingredients
Oyster Peptide Market
Ingredients
Canada Sodium Reduction Ingredients Market
Ingredients
Phytogenic Market
Ingredients
Europe Malt Extract Market
Ingredients
Organic Edible Oil Market
Ingredients
Starch-Derived Fiber Market