
 Oak Extract Market | 2026-2036
Oak Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Oak Extract Market Analytics
A shift from single-source French oak procurement toward multi-origin sourcing is pivoting how extract houses manage supply security and cost volatility. Givaudan leverages its Grasse-based botanicals network to secure consistent raw material flows across seasons. Kerry Group anchors its extract portfolio through backward integration into sustainable forestry partnerships in Eastern Europe. Symrise AG competes on analytical standardization, publishing detailed ellagitannin and gallic acid profiles that match pharmaceutical-grade specifications.
Oak extract comprises hydrolyzable tannins, ellagitannins, and volatile phenolics derived from Quercus species heartwood and bark, typically recovered through aqueous-ethanol maceration or supercritical CO2 extraction for use as natural antioxidants, flavor precursors, and active cosmetic ingredients. Liquid extract maintains the largest volume position due to its direct incorporation into beverage and skincare formulations, while powder extract captures the fastest expansion as nutraceutical brands seek shelf-stable, high-concentration inputs for capsule and tablet applications. Cosmetics represents a concentrated margin pool where brands pay premiums for COSMOS-certified oak derivatives with documented anti-inflammatory activity.
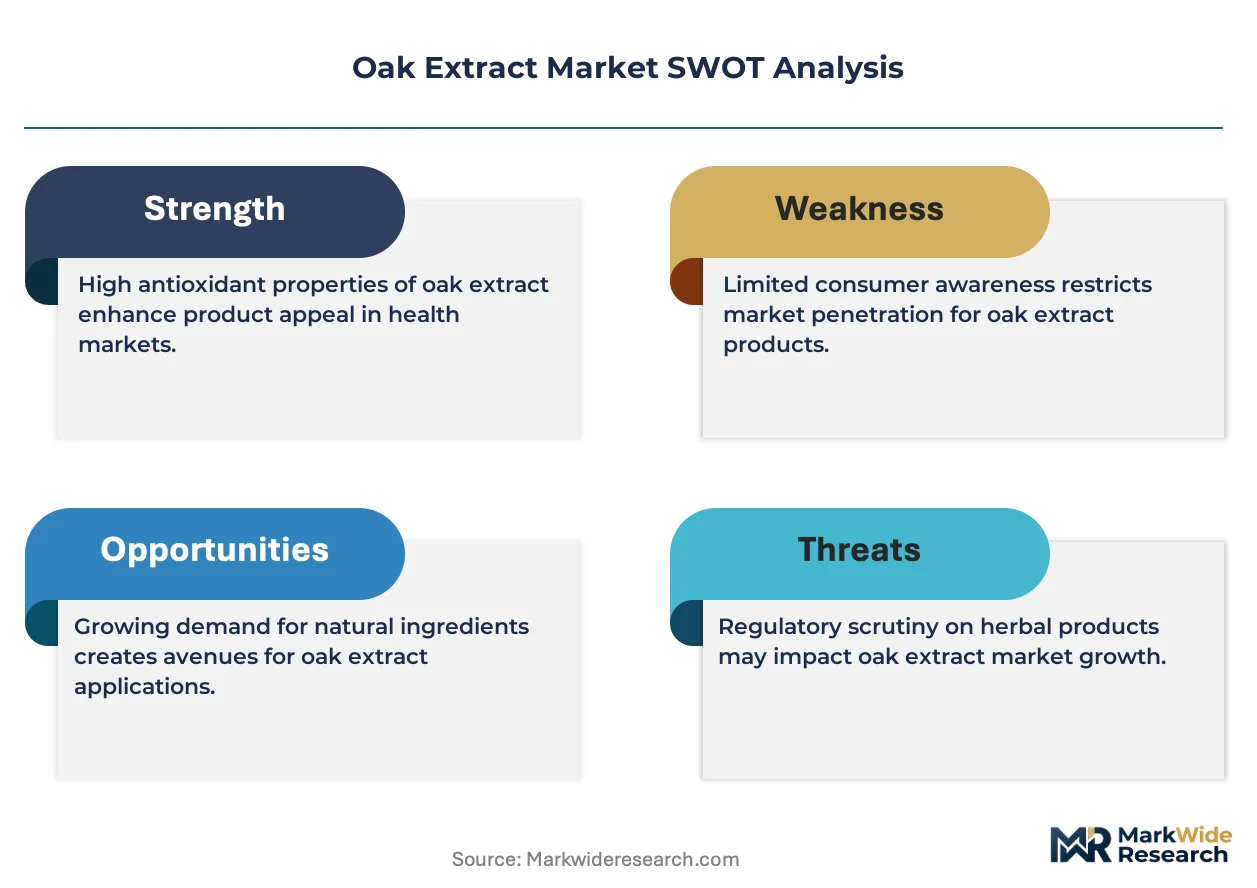
REACH registration requirements in Europe and FDA New Dietary Ingredient notifications in the United States impose substantial analytical documentation burdens on oak extract suppliers seeking novel food or supplement positioning. EFSA health claim evaluations further constrain how European marketers communicate cardiovascular benefits from oak polyphenols. Stakeholders must monitor regulatory divergence between jurisdictions while building dual-compliant dossiers that preempt market access friction.
Market Dynamics
REACH registration requirements and FDA dietary supplement guidelines are compressing supplier margins while concentrating procurement among extract houses with dual-compliant dossiers. This regulatory tightening is accelerating backward integration strategies across the value chain.
Growth Catalysts
- EFSA health claim pathways:European nutraceutical brands are investing in clinical substantiation for cardiovascular positioning of oak polyphenols, creating pull-through for standardized extract volumes.
- Supercritical CO2 extraction:Cosmetic formulators in France are adopting this solvent-free recovery method to meet COSMOS certification thresholds for volatile phenolic content.
- Loire Valley cooperatives:Barrel-aged oak derivative supply from this cluster is securing long-term offtake agreements with flavor houses seeking consistent organoleptic profiles.
Market Restraints
- Raw material concentration:Premium heartwood supply concentrates in French forestry cooperatives, exposing extract houses to seasonal harvest volatility and price spikes.
- Quercus species substitution:Cheaper tannin sources including chestnut and quebracho are displacing oak in industrial antioxidant applications where certification is not mandated.
- REACH analytical documentation:European suppliers face six-figure registration costs for novel extract positioning, freezing smaller processors out of pharmaceutical-grade segments.
Strategic Opportunities
- Eastern European forestry partnerships:Sustainable oak plantations in Romania and Bulgaria offer untapped feedstock for extract houses seeking supply security beyond French sources.
- Capsule and tablet nutraceuticals:Powder extract formats are capturing new shelf-stable applications as brands reformulate liquid-dependent portfolios for e-commerce distribution.
- EU Green Deal bioproduct mandates:Public procurement preferences for bio-based cosmetic ingredients are creating tender opportunities for certified oak derivative suppliers.
Industry Challenges
- Ellagitannin standardization expertise:Analytical chemists capable of validating pharmaceutical-grade polyphenol profiles command premium compensation, constraining mid-tier extract houses.
- Dual-compliant dossier construction:Suppliers must simultaneously satisfy REACH purity thresholds and FDA New Dietary Ingredient notification requirements, extending product launch timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oak Extract Market |
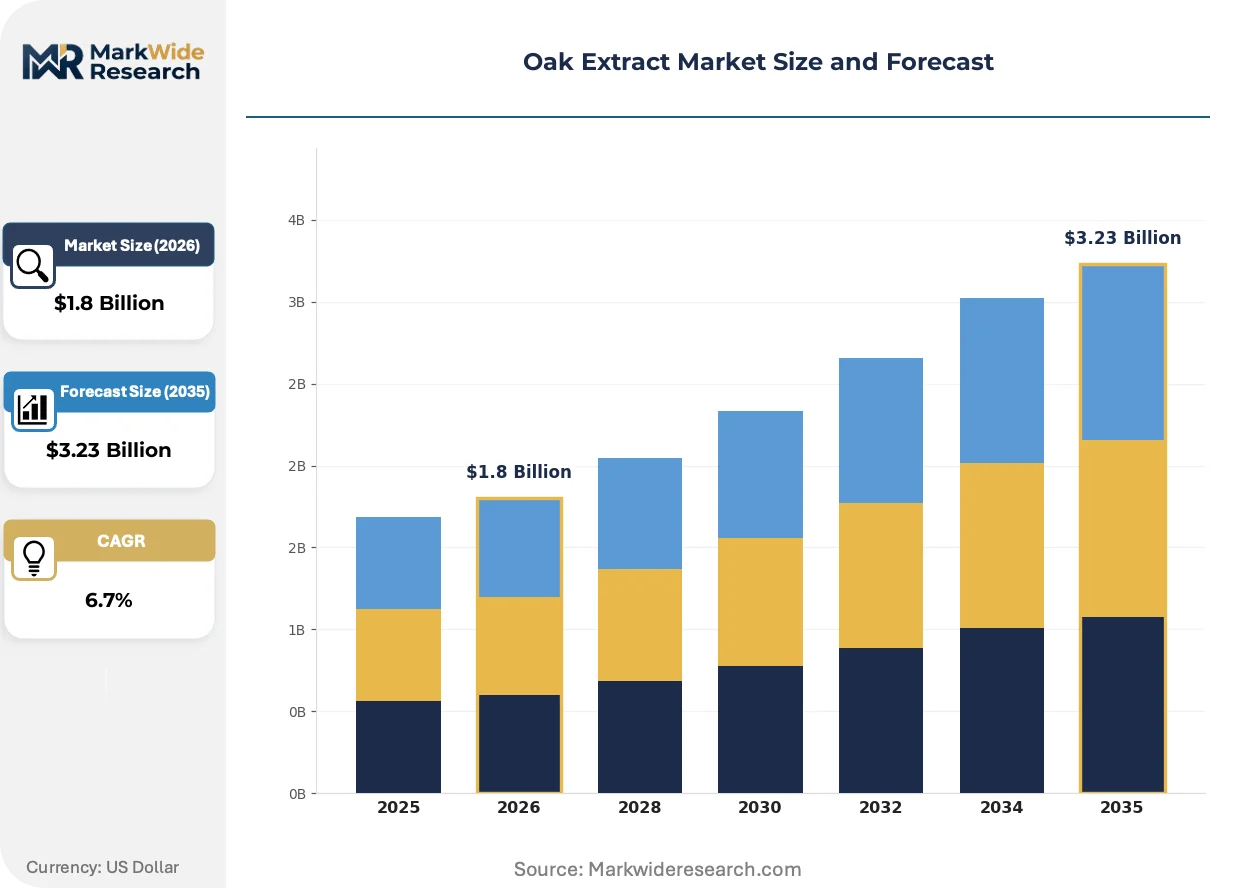
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extract, Powder Extract, Tinctures, Capsules Application: Healthcare, Nutraceuticals, Cosmetics, Food & Beverages End User: Manufacturers, Retailers, Online Stores, Distributors Distribution Channel: Direct Sales, E-commerce, Wholesale, Specialty Stores |
| Companies Covered | Givaudan, International Flavors & Fragrances Inc., Horphag Research, Indena S.p.A., Symrise AG, dsm-firmenich, Cargill Incorporated, Kerry Group, Oak Solutions Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oak Extract Market Evolving Landscape
Extraction technology convergence and regulatory documentation automation are compressing the gap between raw material recovery and finished ingredient qualification. These shifts are redrawing competitive boundaries between commodity suppliers and specification-grade producers.
Supercritical CO2 extraction systems are integrating into mid-scale processing facilities previously limited to aqueous-ethanol maceration. Cosmetic labs in Grasse are adopting these units to capture volatile phenolics without thermal degradation. This technology is integrating solvent-free recovery with real-time compositional monitoring, enabling batch-level certification documentation that aqueous methods cannot match.
REACH registration deadlines for existing oak extract substances are forcing portfolio rationalization among European suppliers. ECHA dossier requirements for toxicological endpoints and environmental fate data are absorbing technical resources previously allocated to product development. Small and mid-sized extract houses are responding by withdrawing from novel food applications and retreating to established flavor and fragrance segments with simpler regulatory pathways.
Direct procurement relationships between nutraceutical brands and forestry cooperatives are disintermediating traditional extract distributors. Buyers in the cardiovascular supplement segment are establishing captive supply agreements with Loire Valley cooperatives, specifying harvest age and barrel-aging protocols. This pattern is most visible in France, where brands with COSMOS-certified lines are paying 15-30% premiums for documented chain-of-custody from forest to formulation.
Oak Extract Market Segmentation
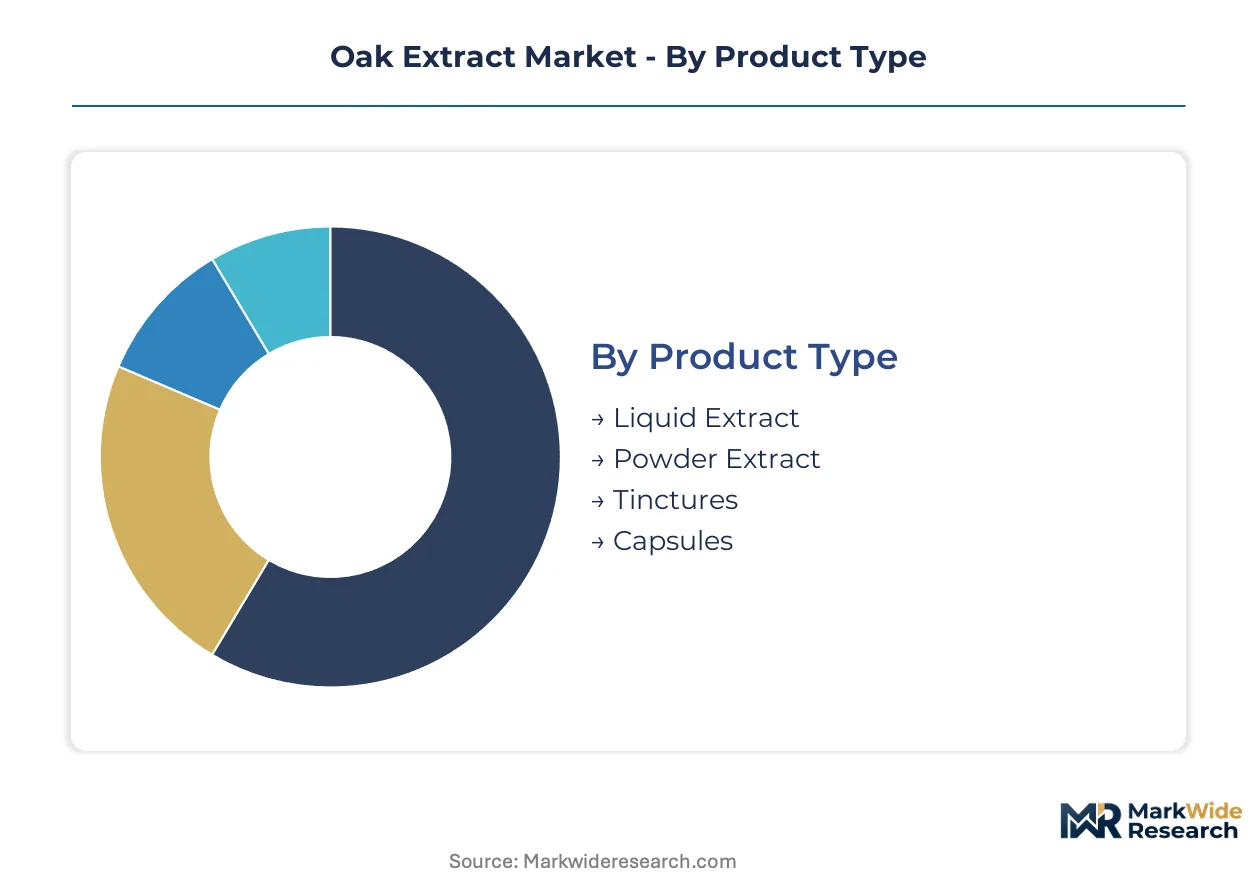
Oak extract suppliers must align product formats with divergent compliance burdens across pharmaceutical, cosmetic, and food-grade channels. Segmentation strategy determines which regulatory dossiers extract houses must maintain and which margin pools they can access.
Product Type:
REACH registration thresholds and FDA New Dietary Ingredient notification requirements split this category into pharmaceutical-grade and commodity-grade compliance tracks.
- Liquid Extract:Aqueous-ethanol maceration yields hydrolyzable tannins and volatile phenolics in solution form. Beverage formulators in France specify this format for direct incorporation into functional drinks and barrel-aged flavor systems.
- Powder Extract:Spray-dried or freeze-dried concentrates achieve shelf stability for nutraceutical capsules. E-commerce distribution is pulling brands toward this format as liquid shipping costs escalate.
- Tinctures:Alcohol-based preparations serve artisanal cosmetic labs and traditional medicine practitioners with minimal regulatory overhead.
- Capsules:Pre-filled dosage forms bypass formulation complexity for supplement brands lacking in-house encapsulation capability.
Leading the category by volume: Liquid Extract. Growing fastest: Powder Extract.
Application:
Margin structure varies sharply across these end-uses, with certification premiums concentrated in segments where EFSA health claims or COSMOS standards apply.
- Healthcare:Pharmaceutical-grade ellagitannin extracts target cardiovascular and metabolic indications. EMA qualification pathways demand clinical substantiation that only specialized extract houses can fund.
- Nutraceuticals:Dietary supplement brands source standardized polyphenol inputs for capsule and tablet portfolios. FDA notification requirements for novel ingredients compress supplier margins while concentrating procurement among dual-compliant vendors.
- Cosmetics:COSMOS-certified oak derivatives command substantial premiums from anti-inflammatory skincare lines. Grasse-based formulators specify supercritical CO2-extracted volatile phenolics for fragrance-free positioning.
- Food & Beverages:Natural antioxidant applications in wine, spirits, and functional beverages face substitution pressure from cheaper tannin sources where organic certification is not mandated.
Highest margin concentration: Cosmetics. Steepest expansion trajectory: Nutraceuticals.
End User:
Procurement sophistication determines whether extract houses sell through distributors or establish direct relationships with specification-setting buyers.
- Manufacturers:Nutraceutical and cosmetic formulators with in-house analytical capabilities impose stringent ellagitannin standardization requirements.
- Retailers:Private-label supplement brands and natural product chains seek turnkey capsule and tincture formats with minimal technical interface.
- Online Stores:Direct-to-consumer brands prioritize powder extract for fulfillment economics and extended shelf life in warehouse environments.
- Distributors:Traditional extract traders are losing share as manufacturers build captive supply agreements with Loire Valley cooperatives.
Dominant procurement volume: Manufacturers. Most rapidly evolving channel: Online Stores.
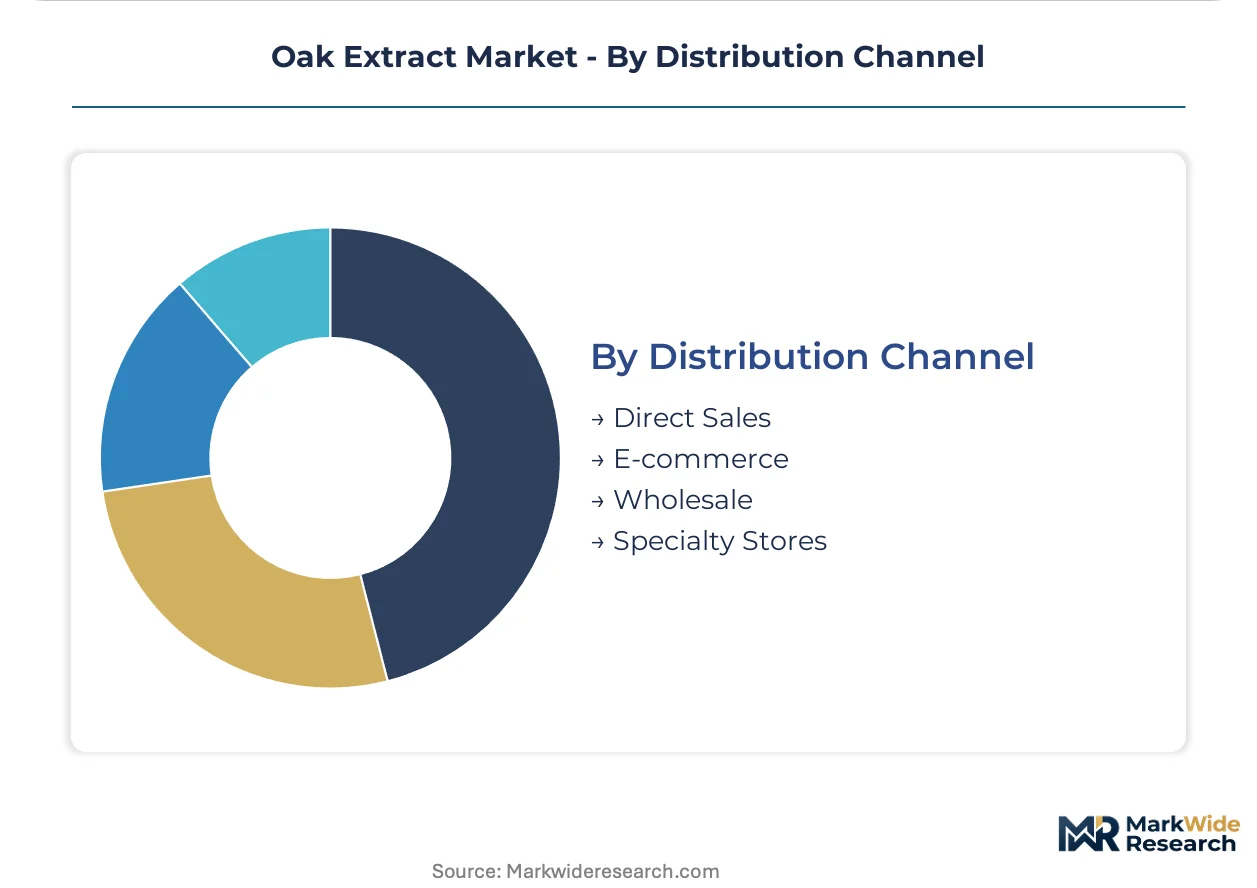
Distribution Channel:
Channel selection determines documentation depth, with direct sales requiring full regulatory dossiers and wholesale minimizing compliance exposure.
- Direct Sales:Long-term offtake agreements between nutraceutical brands and forestry cooperatives specify harvest age, barrel-aging protocols, and chain-of-custody documentation.
- E-commerce:Powder extract formats dominate this channel as brands optimize for shipping weight and shelf stability in direct-to-consumer fulfillment.
- Wholesale:Commodity-grade liquid extracts move through flavor and fragrance distributors serving industrial antioxidant applications with minimal certification requirements.
- Specialty Stores:Artisanal tinctures and small-batch cosmetic ingredients reach formulators through botanicals retailers in Grasse and similar clusters.
Largest volume flow: Wholesale. Fastest channel expansion: E-commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Loire Valley cooperatives anchor French oak heartwood supply, while procurement diversification accelerates across Eastern European plantations and North American extraction facilities.
France
COSMOS-certified cosmetic demand and barrel-aged flavor systems drive premium extract consumption. REACH registration through ECHA tightens purity documentation for novel food positioning. Grasse-based formulators specify supercritical CO2 methods to capture volatile phenolics without thermal degradation.
Germany
Nutraceutical brands seek pharmaceutical-grade ellagitannin inputs for cardiovascular supplement lines. The EU Green Deal bioproduct mandates create public procurement preferences for certified oak derivatives. Bavarian extraction houses build analytical standardization capabilities to match EMA qualification pathways.
United States
FDA New Dietary Ingredient notifications compress supplier margins while concentrating procurement among dual-compliant vendors. Dietary supplement brands establish direct supply relationships with forestry cooperatives to secure chain-of-custody documentation. Pacific Northwest processors explore aqueous-ethanol maceration for beverage antioxidant applications.
Romania
Sustainable oak plantations offer untapped feedstock for extract houses seeking supply security beyond French sources. National forestry certification programs align with EU sustainability frameworks. Transylvanian cooperatives negotiate long-term offtake agreements with Western European flavor houses.
Italy
Artisanal cosmetic labs in Tuscany and Piedmont demand small-batch tinctures with minimal regulatory overhead. Indena S.p.A. anchors pharmaceutical-grade botanical extraction expertise in the Milan corridor. Italian processors specialize in hydrolyzable tannin recovery for wine and spirits applications.
Oak Extract Market Competitive Landscape
Backward integration dominates the current landscape as extract houses secure captive forestry supply. The vendor base stratifies across three tiers: multinational flavor houses with Grasse-based botanical networks, mid-scale processors with Eastern European plantation partnerships, and regional specialists serving artisanal cosmetic labs. Two strategic archetypes have emerged: specification-grade producers publishing detailed polyphenol profiles, and commodity suppliers competing on volume throughput. Capacity expansion in supercritical CO2 systems and strategic partnerships with Loire Valley cooperatives represent the dominant competitive moves.
Among Swiss-anchored specialists, Givaudan exemplifies the integrated botanicals archetype through its Grasse-based supply network. Kerry Group occupies a position representing the Eastern European plantation partnership model. Symrise AG sits within the analytical standardization tier, publishing detailed ellagitannin and gallic acid profiles that match pharmaceutical-grade specifications.
| Leading Market Players |
|---|
| Givaudan |
| International Flavors & Fragrances Inc. |
| Horphag Research |
| Indena S.p.A. |
| Symrise AG |
| dsm-firmenich |
| Cargill Incorporated |
| Kerry Group |
| Oak Solutions Group |
| Others |
Value Network & Pricing Analysis
Family-owned forestry cooperatives in the Loire Valley anchor premium oak heartwood supply, translating concentrated ownership into disciplined pricing power for barrel-aged derivatives while extract houses absorb REACH registration costs that smaller processors cannot fund.
Pricing Analysis
Warranty of analytical standardization separates pharmaceutical-grade from commodity-tier supply, with Symrise AG and similar houses bundling validated ellagitannin profiles into long-term offtake agreements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with COSMOS-certified cosmetic inputs commanding substantial premiums over industrial antioxidant applications. Cost compression in commodity liquid extracts is intensifying because chestnut and quebracho substitution erodes oak's position where certification is not mandated. Nutraceutical capsule manufacturers demonstrate highest price sensitivity, while Grasse-based cosmetic formulators show least sensitivity due to fragrance-free positioning requirements.
Supply Chain Analysis
Single-source vulnerability sits with French forestry cooperatives for premium heartwood, exposing extract houses to seasonal harvest volatility and price spikes when barrel-aging protocols specify Loire Valley provenance. Raw material flows draw from France, Romania, and Bulgaria, with Eastern European plantations offering supply security alternatives. Hydrolyzable tannins, ellagitannins, and volatile phenolics constitute critical input dependencies. Tariff exposure on cross-border oak shipments between EU member states remains minimal, though Brexit-related customs friction affects UK-bound cosmetic ingredients. Distribution runs through direct sales for specification-grade producers and wholesale channels for commodity liquid extracts serving flavor houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where REACH registration costs and dual-compliant dossier requirements force smaller processors to retreat from novel food applications, concentrating procurement among extract houses with EMA qualification capabilities.
For Market Incumbents: Anchor defensive positioning through captive supply agreements with Loire Valley cooperatives specifying harvest age and barrel-aging protocols, while building analytical standardization capabilities to match pharmaceutical-grade specifications that emerging Eastern European entrants cannot yet fund. Threat of chestnut and quebracho substitution in industrial applications demands certification investment as the primary differentiation lever. For New Entrants and Emerging Players: Enter via Romanian and Bulgarian sustainable oak plantations where national forestry certification programs align with EU sustainability frameworks but Western European extract houses have not yet established dominant offtake relationships. White-space targets include powder extract formats for e-commerce nutraceutical distribution and supercritical CO2 extraction capacity for COSMOS-certified cosmetic supply. Go-to-market angle should emphasize chain-of-custody documentation from forest to formulation. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale processors with existing REACH dossiers in France and Germany where ECHA registration deadlines have frozen smaller competitors out of novel food positioning. Long-term viability over the next decade hinges on backward integration into plantation assets rather than tolling arrangements. Signal to watch is acceleration of direct procurement relationships between nutraceutical brands and forestry cooperatives disintermediating traditional extract distributors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forestry Assets | Captive supply from Romanian cooperatives reduces exposure to Loire Valley price volatility. |
| Supercritical CO2 Capacity Expansion | Grasse-based cosmetic labs specify this method for COSMOS-certified volatile phenolic recovery. |
| Dual-Compliant Dossier Investment | Simultaneous REACH and FDA New Dietary Ingredient positioning unlocks pharmaceutical-grade margins. |
| Direct Sales Channel Development | Long-term offtake agreements with nutraceutical brands bypass wholesale margin compression. |
| E-Commerce Format Optimization | Powder extract shelf stability aligns with direct-to-consumer fulfillment economics. |
Research Methodology
EMA qualification pathway documentation, ECHA REACH registration databases, and French forestry cooperative harvest records formed the secondary backbone, supplemented by primary interviews with extract house technical directors, cosmetic formulators in Grasse, nutraceutical brand procurement leads, and Loire Valley cooperative managers. Bottom-up volume modeling across liquid extract, powder extract, tincture, and capsule formats triangulated against top-down value estimates from trade flow analysis.
Historical trendline analysis of oak-derived polyphenol pricing and volume trajectories informed the projection framework, with segmentation across product type, application, end user, and distribution channel dimensions modeled throughout the forecast period. CAGRs were derived from curve-fitting approaches calibrated to EFSA health claim investment cycles and supercritical CO2 technology adoption patterns in French cosmetic labs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory divergence scenarios between REACH and FDA notification requirements or accelerated substitution by chestnut tannins in industrial antioxidant applications. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Bromelain Ingredient Market
Ingredients
Modified Maize Starch Market
Ingredients
Coconut Derivatives Market
Ingredients
Clean Label Flour Market
Ingredients
Fish Feed Ingredients Market
Ingredients
Dried Beet Pulp Market
Ingredients
Low-Odor Fish Protein Hydrolysates from Med Species Market
Ingredients
United States Avocado Oil Market
Ingredients
India Sodium Reduction Ingredients Market
Ingredients
US Ingredients Market
Ingredients
US Choline Bitartrate Market
Ingredients
Algae Omega-3 Ingredients Market
Ingredients
Global Edible Oil Market
Ingredients
Asia-Pacific Fats and Oil Market
Ingredients
Cold-Pressed Coconut Oil Market
Ingredients
North America Collagen Ingredients Market