
 Centella Asiatica Extract Market | 2026-2036
Centella Asiatica Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Centella Asiatica Extract Market Outlook
Gotu kola-derived actives is pivoting toward synthetic biology alternatives in mid-tier cosmetic formulations, yet premium segments retain whole-plant extraction for traceability claims. Givaudan S.A. anchors its position through captive cultivation partnerships in Madagascar. Croda International differentiates via lipid-encapsulation delivery systems that improve bioavailability. Sabinsa Corporation leverages its Sub-Saharan African sourcing network to secure consistent raw material supply.
Centella asiatica extract comprises triterpenoid saponins—principally asiaticoside, madecassoside, asiatic acid, and madecassic acid—typically standardized to 40-90% total triterpenes by HPLC analysis, extracted through hydroalcoholic maceration or supercritical CO2 processing for use in wound healing, collagen synthesis stimulation, and neuroprotective applications. Powder formulations dominate pharmaceutical compounding due to dosage precision and extended shelf stability, while liquid extracts lead cosmetics manufacturing for ease of emulsion incorporation. The nutraceuticals channel is expanding fastest as encapsulated formats gain traction among supplement brands seeking cognitive health positioning.
FDA oversight of cosmetic ingredient safety through the Modernization of Cosmetics Regulation Act (MoCRA) is elevating documentation burdens for botanical extract suppliers seeking US market access, while the EU's REACH framework and ECHA guidance on natural complex substances constrain allowable solvent residues and heavy metal thresholds. China's NMPA and SAMR are tightening registration requirements for imported botanical actives in functional cosmetics, creating divergent compliance pathways. Stakeholders must monitor regulatory harmonization gaps between major markets to avoid formulation lock-in that limits geographic flexibility.
Market Dynamics
Korean beauty brands are consolidating procurement around standardized asiaticoside extracts, forcing suppliers to choose between premium whole-plant positioning and mid-tier synthetic biology alternatives. This demand bifurcation is compressing margin structures for undifferentiated extractors while rewarding traceability investments.
Growth Catalysts
- REACH purity thresholds:The European Union's tightening heavy metal and solvent residue limits are accelerating supplier consolidation toward GMP-certified facilities capable of batch-level documentation.
- Seoul-Incheon manufacturing corridor:Contract manufacturers serving both domestic Korean brands and export markets are standardizing 70-90% asiaticoside specifications for anti-aging serum formulations.
- Supercritical CO2 processing:This extraction technology eliminates thermal degradation of triterpenoid saponins, enabling cleaner label claims that command premium positioning in functional cosmetics.
Market Restraints
- Madagascar cultivation concentration:Givaudan S.A.'s captive partnerships control a disproportionate share of premium wild-harvested material, creating supply vulnerability for second-tier formulators.
- MoCRA documentation burdens:FDA's Modernization of Cosmetics Regulation Act is elevating compliance costs for botanical extract suppliers seeking US market access without equivalent revenue upside.
- Synthetic biology substitution:Fermentation-derived asiaticoside precursors are capturing mid-tier cosmetic formulations where traceability claims hold less value.
Strategic Opportunities
- Indian nutraceutical expansion:CDSCO's evolving framework for botanical health claims is opening encapsulated cognitive health positioning for supplement brands targeting domestic and export markets.
- Lipid-encapsulation delivery systems:Croda International's technology pathway demonstrates bioavailability improvement that could extend into pharmaceutical wound-healing applications.
- SAMR functional cosmetics registration:China's tightened requirements for imported botanical actives create first-mover advantage for suppliers investing in NMPA-compliant dossier preparation.
Industry Challenges
- HPLC standardization expertise:The analytical chemistry talent required for 40-90% total triterpene certification remains concentrated among specialized contract laboratories, extending quality control timelines.
- Dual carbon compliance:China's MEE enforcement of energy intensity targets is forcing processing facility relocations or retrofits that compress near-term capacity utilization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Centella Asiatica Extract Market |
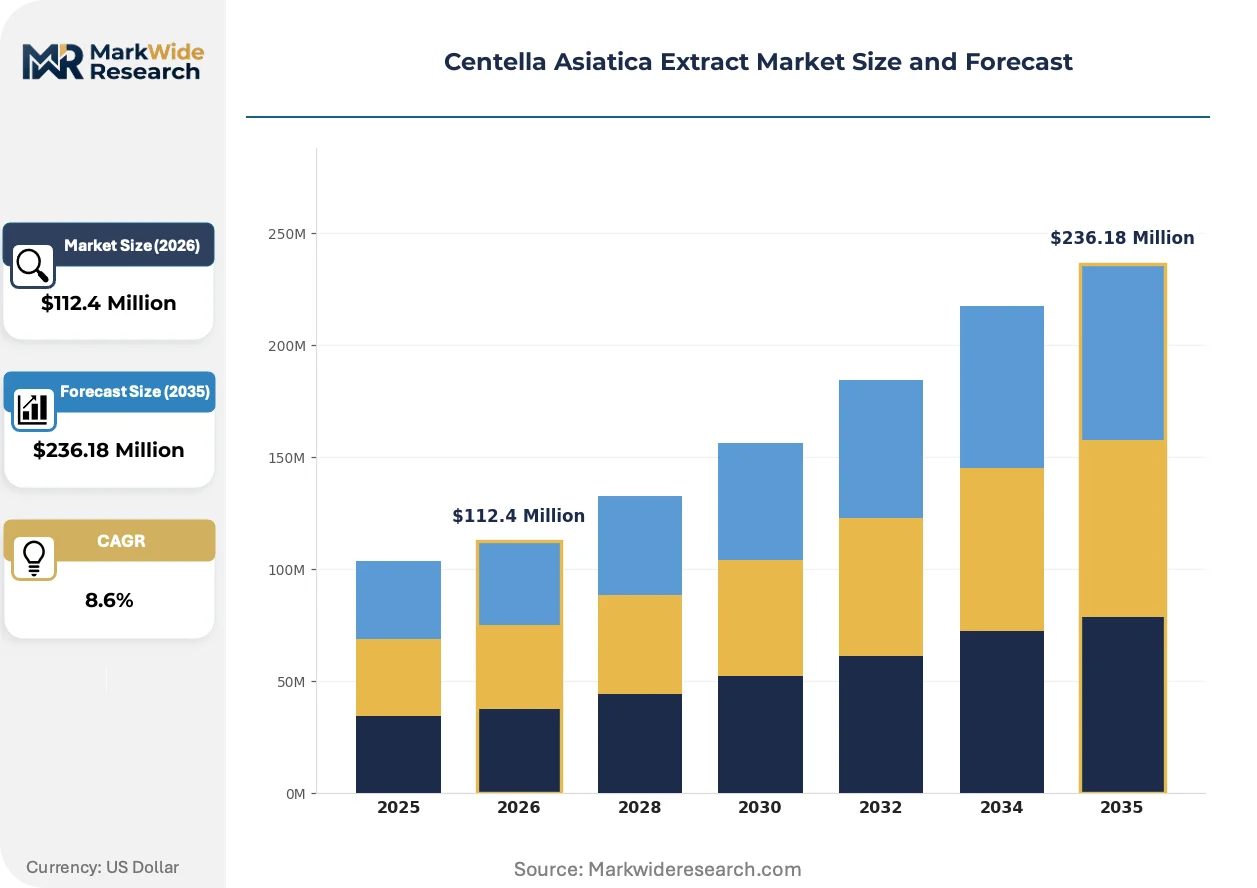
| Market Size in 2026 | $112.4 Million |
| Market Size in 2035 | $236.18 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsule, Cream Application: Cosmetics, Pharmaceuticals, Nutraceuticals, Food Industry End User: Manufacturers, Retailers, Distributors, Wholesalers Form: Ointment, Serum, Extract, Tincture |
| Companies Covered | Givaudan S.A., Croda International, BASF SE, Sabinsa Corporation, Indena S.P.A., L'Oréal S.A., Amorepacific Corporation, Botanic Healthcare Pvt. Ltd., Estee Lauder Companies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Centella Asiatica Extract Market Strategic Shifts
Bioprocessing advances and regulatory documentation requirements are reshaping competitive advantage away from raw material access toward delivery system engineering and compliance infrastructure. Suppliers must now integrate extraction technology with formulation science.
Supercritical CO2 extraction is overtaking hydroalcoholic maceration in premium cosmetic applications due to superior preservation of heat-sensitive asiaticoside and madecassoside compounds. Seoul-based formulators are specifying this method for export-bound anti-aging serums requiring clean-label positioning. The technology is compressing margins for conventional solvent-based processors unable to justify capital upgrades.
REACH guidance on natural complex substances is tightening allowable heavy metal thresholds for botanical extracts entering European personal care supply chains. This regulatory pressure is disqualifying smaller Madagascar and Sub-Saharan African wild-harvesting operations lacking laboratory testing infrastructure. Korean and German contract manufacturers are responding by mandating third-party certification from all raw material suppliers.
Direct procurement relationships between Korean beauty brands and Madagascar cultivation partnerships are displacing traditional trading house intermediaries. This channel compression is most visible among mid-sized Seoul-Incheon contract manufacturers seeking margin recovery through volume commitments. The shift is fragmenting supplier bases while concentrating traceability documentation burdens on fewer, larger extraction facilities.
Centella Asiatica Extract Market Segmentation
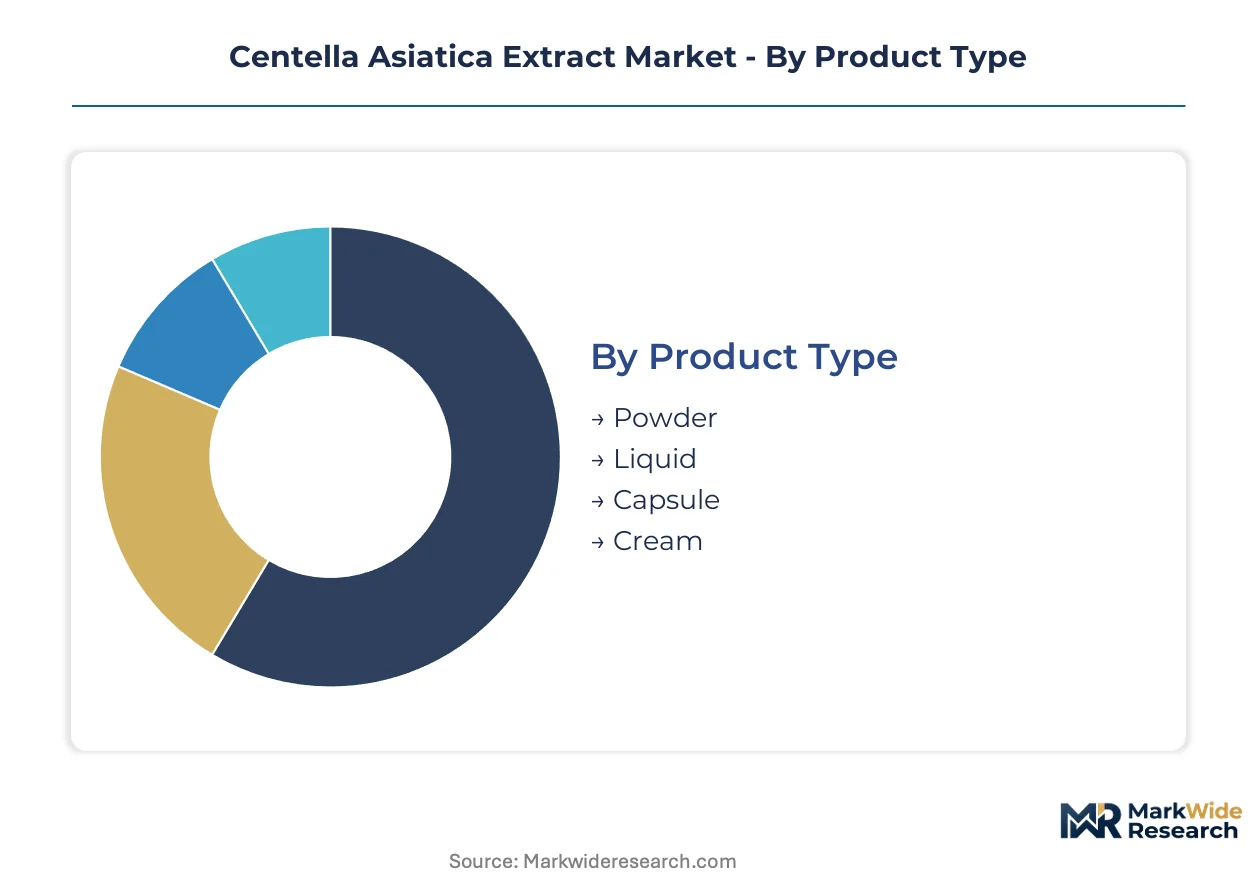
Centella asiatica extract procurement patterns diverge sharply across product formats and end-use channels, with Korean contract manufacturers driving standardization in cosmetics while pharmaceutical compounders demand batch-level HPLC documentation. Suppliers must configure extraction capacity around these incompatible specification regimes.
Product Type:
Powder formulations concentrate capacity in GMP-certified facilities serving pharmaceutical and nutraceutical channels, while liquid extracts dominate cosmetics manufacturing corridors.
- Powder:Standardized to 40-90% total triterpenes by HPLC analysis, powder formats enable precise dosage control in wound-healing compounds and collagen-stimulating supplements. Seoul-Incheon contract manufacturers specify powder inputs for encapsulated cognitive health products targeting export markets.
- Liquid:Hydroalcoholic or supercritical CO2-derived liquid extracts facilitate emulsion incorporation in anti-aging serums. Korean beauty brands mandate liquid formats for clean-label positioning in premium skincare lines, with specifications tightening around asiaticoside purity thresholds.
- Capsule:Pre-measured encapsulated formats serve supplement brands seeking cognitive health claims under evolving CDSCO and FDA frameworks.
- Cream:Emulsion-ready cream bases incorporate lipid-encapsulated actives for topical wound-healing applications in clinical settings.
Powder absorbs the bulk of installed capacity; liquid is expanding most quickly.
Application:
Channel selection determines regulatory pathway complexity, with cosmetics facing REACH and MoCRA documentation burdens while nutraceuticals navigate divergent health claim frameworks.
- Cosmetics:Anti-aging serums and functional skincare drive procurement of 70-90% asiaticoside specifications. Seoul-based formulators specify supercritical CO2 extraction for export-bound products requiring EU-compliant heavy metal thresholds.
- Pharmaceuticals:Wound-healing and collagen synthesis applications demand batch-level triterpene certification from GMP facilities. Madagascar-sourced whole-plant material retains premium positioning for traceability-dependent clinical formulations.
- Nutraceuticals:Encapsulated cognitive health formats are climbing the fastest as supplement brands target domestic Indian and export markets under CDSCO's evolving botanical claims framework.
- Food Industry:Functional food applications remain nascent, constrained by EFSA and FDA GRAS determination timelines for novel botanical ingredients.
Cosmetics commands current revenue concentration; nutraceuticals shows steepest expansion trajectory.
End User:
Procurement authority is shifting downstream as Korean beauty brands consolidate direct Madagascar sourcing relationships, compressing traditional trading house margins.
- Manufacturers:Contract manufacturers in the Seoul-Incheon corridor standardize specifications across domestic and export production runs, concentrating volume commitments on fewer extraction facilities capable of dual REACH-MoCRA documentation.
- Retailers:Direct-to-consumer supplement brands are gaining share fastest in nutraceutical channels, bypassing wholesale intermediaries through encapsulated private-label arrangements.
- Distributors:Traditional trading houses face margin pressure as traceability requirements disqualify smaller Madagascar wild-harvesting operations lacking laboratory infrastructure.
- Wholesalers:Bulk ingredient wholesalers serve mid-tier cosmetic formulators seeking synthetic biology alternatives where whole-plant traceability holds less value.
Manufacturers absorb the bulk of procurement volume; retailers are gaining share fastest in direct-to-consumer channels.
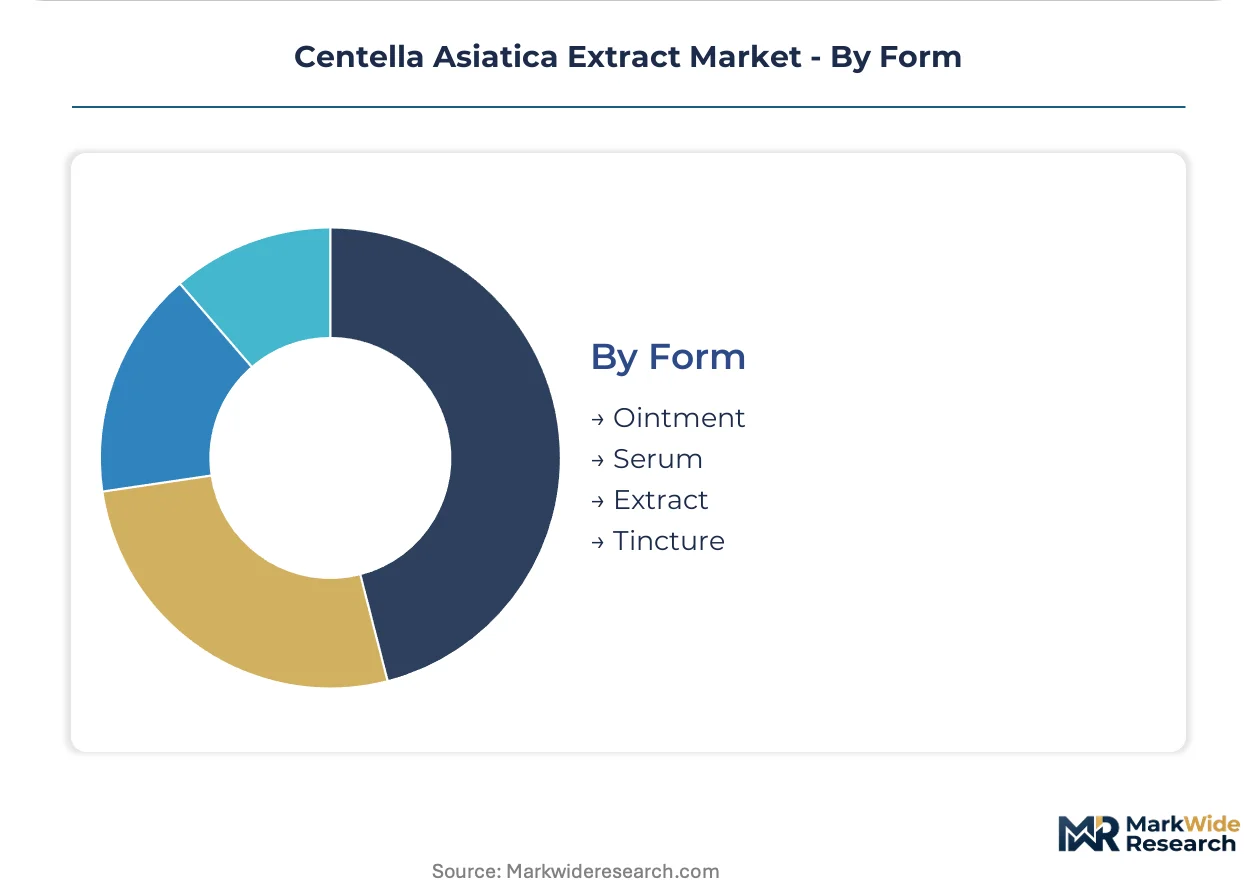
Form:
Delivery system engineering now differentiates competitive positioning, with lipid-encapsulation technologies improving bioavailability for pharmaceutical applications.
- Serum:Lightweight, fast-absorbing serum formats dominate Korean anti-aging export formulations, with supercritical CO2 extraction preserving heat-sensitive asiaticoside compounds for clean-label positioning.
- Ointment:Occlusive ointment bases serve clinical wound-healing applications requiring sustained triterpene release, typically compounded from powder inputs in pharmaceutical manufacturing settings.
- Extract:Unformulated bulk extracts supply contract manufacturers configuring proprietary delivery systems for brand-specific specifications.
- Tincture:Alcohol-based tinctures retain niche positioning in traditional medicine channels, constrained by solvent residue limits under REACH natural complex substances guidance.
Serum captures the bulk of cosmetics-formulation capacity; ointment is expanding most quickly in pharmaceutical wound-care applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement gravity concentrates in South Korea's cosmetics manufacturing belt, with secondary demand nodes emerging in India's nutraceutical compounding corridors and China's processing zones serving export markets.
South Korea
Seoul-Incheon contract manufacturers drive standardized asiaticoside specifications for anti-aging serums targeting export markets. MFDS cosmetic safety assessments mandate heavy metal documentation that disqualifies smaller raw material suppliers. Busan-Ulsan processing facilities are upgrading supercritical CO2 capacity to preserve heat-sensitive triterpenoid compounds for premium formulations.
China
Yangtze River Delta extraction facilities serve both domestic functional cosmetics brands and re-export processing for Korean beauty houses. NMPA and SAMR registration requirements for imported botanical actives are tightening dossier standards for foreign suppliers. Shandong Peninsula processors face MEE dual carbon enforcement compressing near-term energy-intensive capacity.
India
Maharashtra and Gujarat nutraceutical compounders are expanding encapsulated cognitive health production under CDSCO's evolving botanical claims framework. FSSAI safety standards for novel ingredients are extending quality control timelines for extract imports. Karnataka's Bangalore-Tumkur corridor is attracting contract manufacturing investment for export-oriented supplement brands.
United States
California and New Jersey formulation houses navigate FDA MoCRA documentation burdens for botanical cosmetic ingredients without equivalent revenue recovery. EPA solvent residue guidance intersects with state-level Proposition 65 enforcement on heavy metal disclosures. New York Metro distribution channels are consolidating procurement around GMP-certified suppliers capable of batch-level HPLC certification.
Germany
REACH natural complex substances guidance is tightening allowable thresholds for botanical extracts entering personal care supply chains. Bavaria and North Rhine-Westphalia cosmetic compounders are mandating third-party certification from all raw material suppliers. Hamburg trading houses face margin compression as Korean brands establish direct Madagascar sourcing relationships.
Centella Asiatica Extract Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with fragrance houses and ingredient suppliers controlling upstream extraction while beauty conglomerates dominate downstream formulation. The vendor base organizes around three archetypes: captive cultivation operators securing raw material access, delivery system engineers differentiating on bioavailability, and trading intermediaries facing channel compression. Consolidation is accelerating among GMP-certified extraction facilities capable of dual REACH-MoCRA documentation. Strategic partnerships between Korean beauty brands and Madagascar cultivation operators are displacing traditional procurement intermediaries.
Within the captive supply tier, Givaudan S.A. and Sabinsa Corporation exemplify divergent geographic anchoring strategies for raw material security. Croda International occupies a position among delivery system specialists leveraging lipid-encapsulation technologies. Among diversified chemical conglomerates, BASF SE represents scale-driven participation across multiple botanical extract categories. These three archetypes—cultivation-anchored, technology-differentiated, and scale-integrated—capture distinct margin pools based on traceability claims and formulation performance specifications.
| Leading Market Players |
|---|
| Givaudan S.A. |
| Croda International |
| BASF SE |
| Sabinsa Corporation |
| Indena S.P.A. |
| L'Oréal S.A. |
| Amorepacific Corporation |
| Botanic Healthcare Pvt. Ltd. |
| Estee Lauder Companies Inc. |
| Others |
Value Chain & Pricing Dynamics
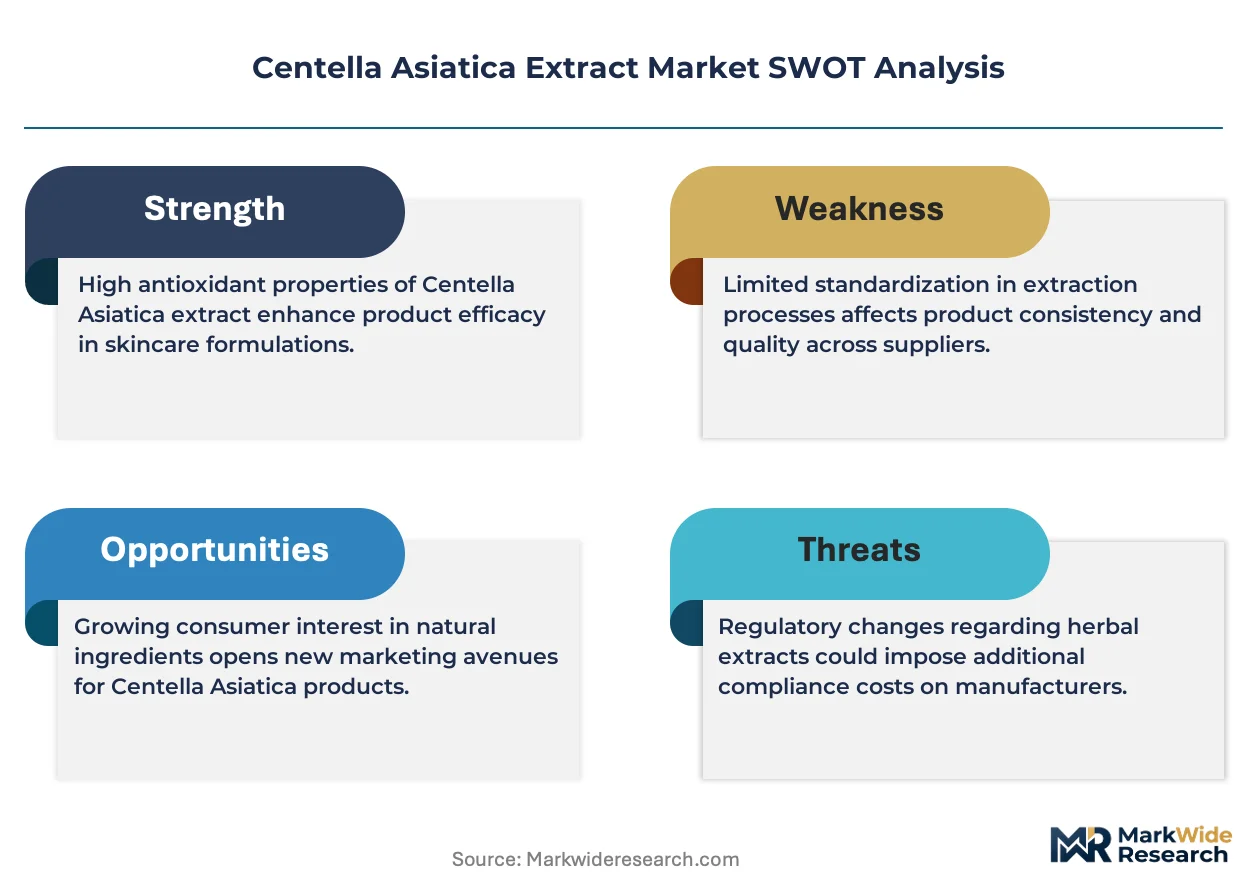
Family-owned mid-cap extraction specialists in Madagascar and Sub-Saharan Africa anchor upstream supply, yet their inability to finance GMP laboratory infrastructure leaves pricing power concentrated among consolidated processors capable of REACH-compliant documentation. This ownership pattern forces a bifurcation where traceability-premium positioning commands substantial markups while undifferentiated bulk extracts face relentless cost compression.
Pricing Analysis
Volume buyers in mid-tier cosmetics procurement squeeze margins on standardized asiaticoside extracts, while premium serum formulations sustain healthier returns through supercritical CO2 certification. Price differentiation rests on HPLC batch documentation and heavy metal compliance thresholds rather than raw material grades alone. Cost compression in conventional solvent-based extraction is intensifying because Korean contract manufacturers are consolidating procurement around fewer dual-certified suppliers. Small-scale wild-harvesting cooperatives exhibit highest price sensitivity, whereas Seoul-Incheon formulators with export-bound clean-label lines demonstrate lowest sensitivity.
Supply Chain Analysis
Direct-to-brand channels displace traditional trading house intermediaries as Korean beauty houses establish captive Madagascar cultivation partnerships. Raw material supply draws from Madagascar wild-harvesting zones, Indian contract cultivation plots, and Chinese Yangtze River Delta processing facilities. Supply chain vulnerability centers on single-source dependence for premium whole-plant material controlled through Givaudan's captive partnerships. Distribution runs through Seoul-Incheon contract manufacturers serving both domestic brands and re-export markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream cultivation control and downstream delivery-system engineering represent the primary levers separating margin capture from commodity exposure.
For Market Incumbents: Extend GMP-certified extraction capacity into India's Maharashtra and Gujarat corridors to capture nutraceutical encapsulation demand before CDSCO framework crystallization. Deepen captive cultivation partnerships in Madagascar beyond current wild-harvesting arrangements to defend against synthetic biology substitution in mid-tier cosmetic formulations. Lock in long-term volume commitments with Seoul-Incheon contract manufacturers facing REACH-MoCRA dual documentation requirements. For New Entrants and Emerging Players: SAMR in China opens a window for first-mover advantage among foreign suppliers investing in NMPA-compliant dossier preparation for functional cosmetics registration. Target India's Bangalore-Tumkur corridor for contract manufacturing partnerships serving export-oriented supplement brands seeking cognitive health positioning. Enter through lipid-encapsulation delivery system technology licensing rather than commodity extraction capacity. For Investors and Strategic Acquirers: Distressed-cycle entries favor GMP-certified extraction facilities in Germany and South Korea facing margin pressure from regulatory compliance investments without equivalent revenue recovery. Long-term viability hinges on positioning for post-consolidation supply concentration where documentation infrastructure becomes non-negotiable. Watch for inflection when Korean beauty brands complete direct Madagascar sourcing transitions and trading house intermediaries exit en masse.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Cultivation Partnerships | Madagascar wild-harvesting control secures premium whole-plant traceability claims against synthetic biology substitution. |
| Supercritical CO2 Capacity Expansion | Busan-Ulsan processing upgrades preserve heat-sensitive asiaticoside compounds for EU-compliant clean-label positioning. |
| GMP Certification Investment | Dual REACH-MoCRA documentation capability qualifies suppliers for Korean contract manufacturer consolidation. |
| Lipid-Encapsulation Technology Licensing | Croda International's bioavailability pathway extends into pharmaceutical wound-healing applications beyond cosmetics. |
| NMPA Dossier Preparation | SAMR functional cosmetics registration creates first-mover advantage for imported botanical actives in China. |
Study Parameters
Trade databases, ECHA REACH guidance documents, and MFDS cosmetic safety assessments formed the secondary backbone, cross-referenced against primary interviews with extraction facility technical directors, Seoul-Incheon contract manufacturing procurement leads, and CDSCO regulatory affairs specialists. Bottom-up and top-down triangulation validated volume estimates across powder, liquid, capsule, and cream format segments.
Bottom-up modeling anchored on asiaticoside purity specifications, extraction technology adoption curves, and channel-specific documentation requirements, while top-down constraints drew from customs trade flows and beauty conglomerate procurement disclosures. Segmentation dimensions spanned product type, application channel, end-user procurement authority, and delivery system form. CAGRs derived from regression analysis against Korean beauty export growth trajectories and nutraceutical encapsulation investment cycles.
The model assumes a particular technology adoption path; alternative pathways for fermentation-derived asiaticoside precursors would alter the outlook if synthetic biology achieves cost parity with whole-plant extraction. Forecasts reflect assumptions about regulatory harmonization gaps between REACH, MoCRA, and SAMR frameworks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Food Grade L-Arabinose Market
Ingredients
Pet Food Premix Market
Ingredients
Hydrolyzed Pork Protein Market
Ingredients
Horehound Extract Market
Ingredients
Tomato Concentrate Market
Ingredients
Psyllium Products Market
Ingredients
Cheese Powder Market
Ingredients
Casein Market
Ingredients
United States Protein Market
Ingredients
Plant Based Thickener Market
Ingredients
Fiber Rich Flours Market
Ingredients
Hexane-Free Protein Market
Ingredients
Africa Soy Protein Ingredients Market
Ingredients
Licorice Root Market
Ingredients
Textured Soy Flour Market
Ingredients
US Plant-Based Oils Market