
 Hydrogen Fluoride Pyridine Market | 2026-2036
Hydrogen Fluoride Pyridine Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Fluoride Pyridine Market Analytics
Pharmaceutical fluorination is realigning demand toward higher-purity grades of hydrogen fluoride pyridine complexes. Sigma-Aldrich leverages its catalog breadth to serve contract research organizations across North America and Europe. Honeywell anchors industrial-scale supply through its fluorine derivatives infrastructure, while Fluorochem specializes in niche halopyridine intermediates for agrochemical clients.
Hydrogen fluoride pyridine denotes a complex formed from anhydrous hydrogen fluoride and pyridine base, typically comprising 60-70% HF by weight and functioning as a selective fluorinating agent in electrophilic aromatic substitution. The compound enables safer handling of fluorine equivalents versus neat hydrogen fluoride in pharmaceutical and agrochemical synthesis. Pyridine-base formulations dominate current volume given their established compatibility with glass-lined reactor systems, while 2-methylpyridine variants command premium positioning for sterically demanding fluorinations. Agricultural applications represent the fastest-expanding consumption pool as crop protection manufacturers adopt fluorinated active ingredients to meet resistance-management protocols.
EPA and OSHA frameworks govern workplace exposure limits and shipping classifications for hydrogen fluoride pyridine in the United States, while REACH registration requirements in Europe mandate comprehensive toxicity dossiers for commercial volumes. India's CDSCO and BIS standards increasingly influence import specifications for fluorinated intermediates used in domestic generic drug production. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as regulatory scope expansion could redirect fluorination chemistry toward alternative reagent platforms.
Market Dynamics
Pharmaceutical fluorination chemistry is pivoting toward higher-purity reagent grades as regulatory agencies tighten impurity thresholds for active pharmaceutical ingredients. This structural shift compresses margins for commodity-grade suppliers while rewarding specialty chemical producers with advanced purification capabilities.
Growth Catalysts
- REACH registration mandates:European ECHA dossier requirements for commercial volumes force manufacturers to upgrade toxicity documentation, consolidating supply among compliant producers capable of sustaining regulatory investment.
- Agrochemical resistance management:Crop protection manufacturers in Brazil and India adopt fluorinated actives to combat herbicide-resistant weeds, expanding addressable demand beyond traditional pharmaceutical channels.
- Glass-lined reactor compatibility:Pyridine-base formulations integrate seamlessly with existing pharmaceutical manufacturing infrastructure, reducing capital barriers for fluorination adoption among mid-scale API producers.
Market Restraints
- Anhydrous hydrogen fluoride volatility:Feedstock price swings tied to phosphate fertilizer co-production economics transmit directly to complex pricing, squeezing formulator margins during supply tightness.
- Concentrated fluorine supply:Five producers control bulk HF capacity in China and Mexico, creating geographic chokepoints that amplify disruption risk from trade policy or environmental enforcement actions.
- Per- and polyfluoroalkyl substance restrictions:Expanding EPA and EU F-Gas regulatory scope threatens to reclassify certain fluorination chemistries, redirecting R&D budgets toward alternative reagent platforms before scientific consensus stabilizes.
Strategic Opportunities
- Indian generic API expansion:CDSCO import specification alignment with ICH standards creates openings for qualified hydrogen fluoride pyridine suppliers to replace informal channels in domestic fluorinated intermediate production.
- Continuous flow fluorination:Microreactor technology convergence with cryogenic processing enables safer handling at elevated throughputs, attracting contract manufacturing investment from specialty chemical firms.
- 2-methylpyridine premium positioning:Sterically demanding fluorinations for complex heterocycles command price premiums of 40-60% above standard pyridine complexes, rewarding producers with differentiated product portfolios.
Industry Challenges
- Fluorine chemist scarcity:Specialized expertise in electrophilic aromatic substitution safety protocols remains concentrated among legacy pharmaceutical hubs in Germany and Switzerland, constraining capacity expansion timelines.
- Corrosive materials handling certification:OSHA process safety management compliance for hydrogen fluoride operations requires 18-24 month facility qualification cycles, delaying new entrant market access.
- Legacy batch reactor integration:Pharmaceutical manufacturers face retrofit complexity when adapting continuous fluorination modules to existing quality management systems validated for traditional vessel operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Fluoride Pyridine Market |
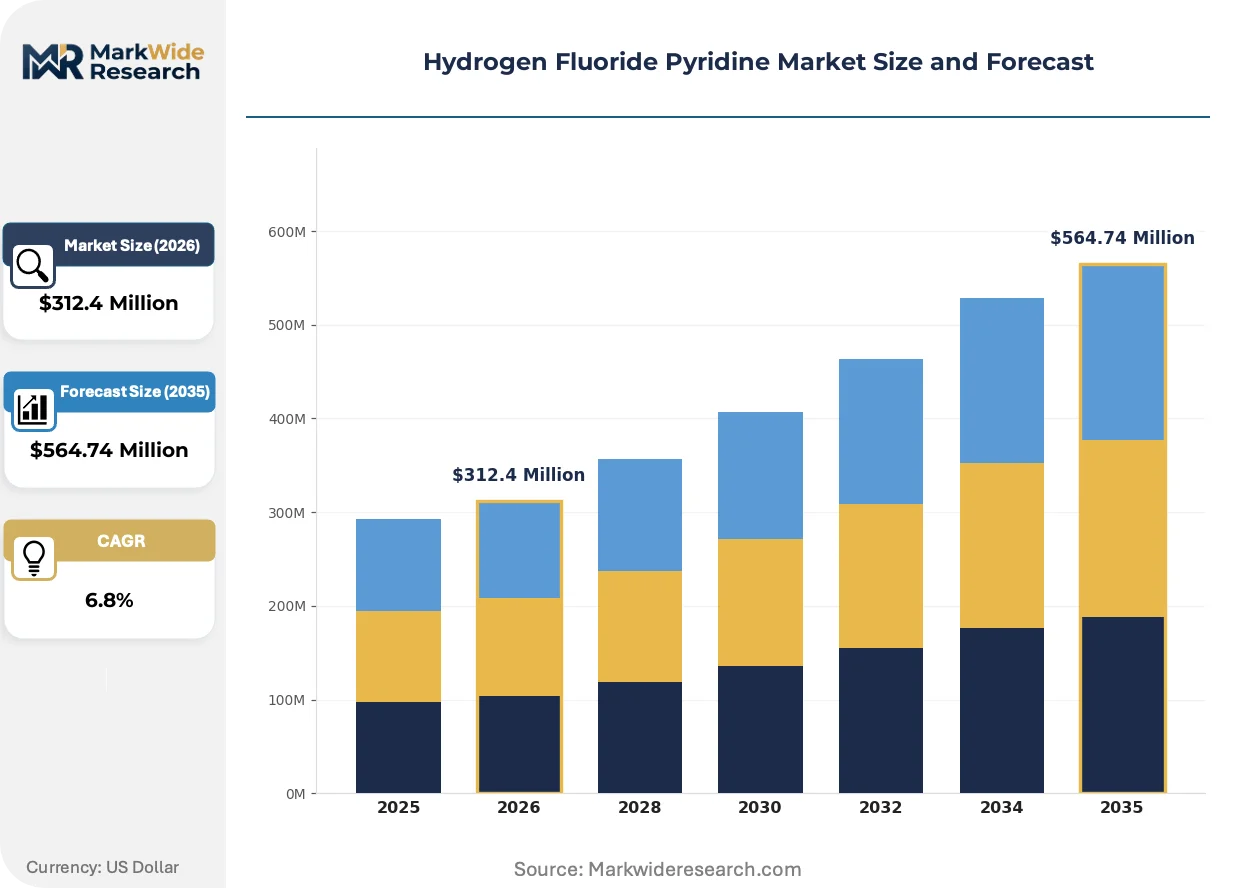
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pyridine, 2-Methylpyridine, 3-Methylpyridine, 4-Methylpyridine Application: Agriculture, Pharmaceuticals, Dyes, Chemicals End User: Chemical Manufacturers, Agricultural Companies, Pharma Companies, Research Institutions Delivery Mode: Bulk Supply, Retail Supply, Online Distribution, Direct Sales |
| Companies Covered | Sigma-Aldrich, Acros Organics, Alfa Aesar, Thomas Scientific, Oakwood Chemical, Cen-Med Enterprises, Iofina, Fluorochem, Honeywell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Fluoride Pyridine Market Evolving Landscape
Fluorination chemistry is bifurcating between commodity-scale agricultural applications and precision pharmaceutical synthesis, with technology investment clustering around safety and selectivity rather than throughput alone.
Continuous flow microreactor systems for hydrogen fluoride pyridine deployment are converging with inline spectroscopic monitoring to enable real-time reaction control. Pharmaceutical contract manufacturers in the Netherlands and Switzerland adopt these platforms to reduce hold-up volumes of corrosive reagents. The technology is compressing batch cycle times from hours to minutes while improving fluorination regioselectivity for complex heterocyclic substrates.
ECHA's expanding restriction proposal for undetected polyfluoroalkyl substances is forcing reagent suppliers to document fluorine mass balance through synthesis pathways. European agrochemical registrants now face additional environmental fate testing requirements for fluorinated actives. German and French manufacturers are responding by qualifying alternative fluorinating agents with more favorable biodegradation profiles ahead of anticipated regulatory deadlines.
Specialty chemical distributors are consolidating procurement for mid-tier pharmaceutical API producers under long-term supply agreements with embedded technical service components. This channel shift displaces spot-market purchasing for hydrogen fluoride pyridine in North America and Western Europe. Japanese and South Korean generic drug manufacturers exhibit the strongest preference for bundled reagent-analytical support contracts, reflecting quality assurance staffing constraints.
Hydrogen Fluoride Pyridine Market Segmentation
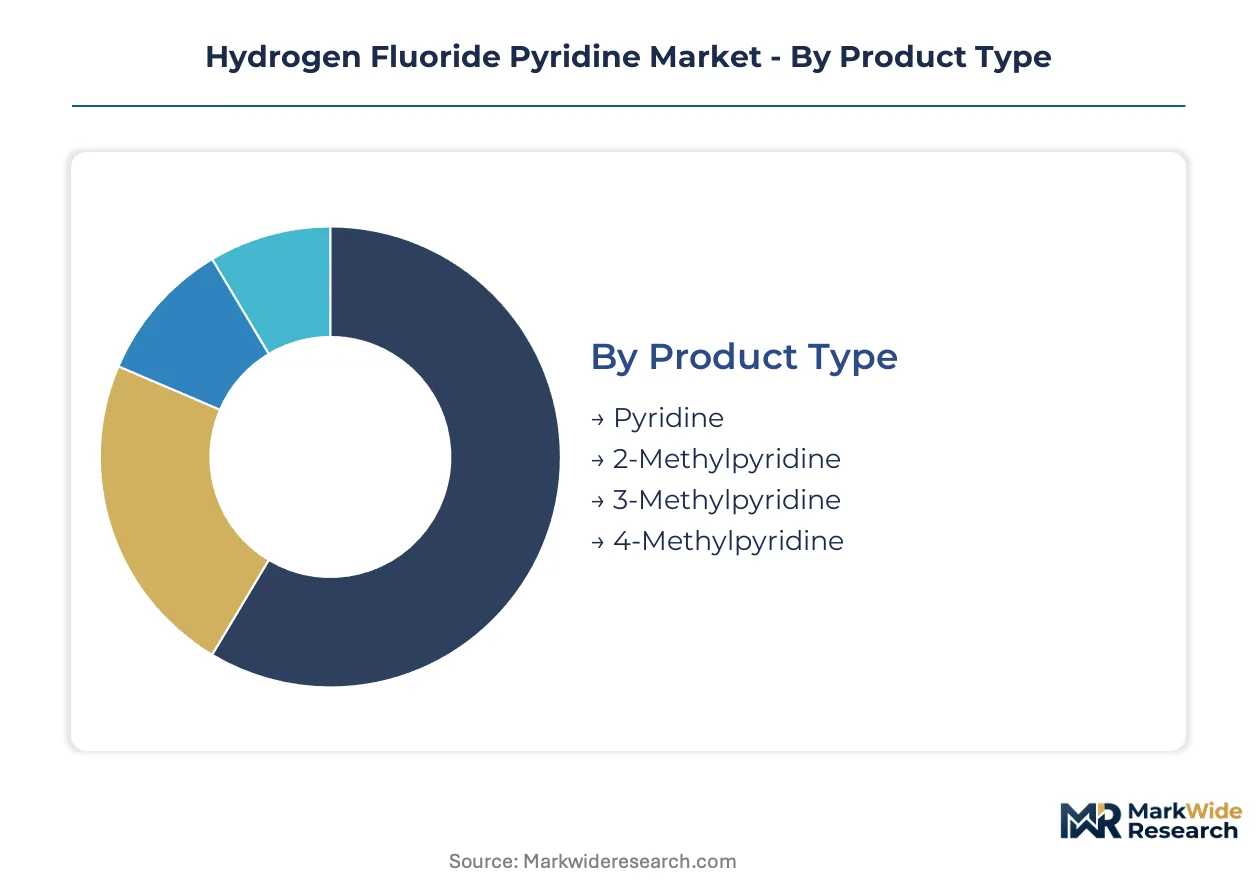
Hydrogen fluoride pyridine formulations vary sharply in purity, base composition, and handling protocols. Segmentation reveals how supply chain configuration aligns with end-use risk tolerance and regulatory stringency across pharmaceutical and agricultural channels.
Product Type:
Supply concentration for hydrogen fluoride pyridine complexes tilts heavily toward pyridine-base formulations, with methylated variants commanding specialized production infrastructure.
- Pyridine:The standard 60-70% HF complex dominates commercial volumes through established compatibility with glass-lined pharmaceutical reactors. Demand clusters in Germany and Switzerland around legacy electrophilic fluorination facilities serving innovator drug programs.
- 2-Methylpyridine:Steric bulk from the ortho-methyl substituent enables selective fluorination of congested aromatic substrates. Agricultural chemistry divisions in Brazil and India pay 40-60% premiums for this grade when synthesizing fluorinated herbicide actives.
- 3-Methylpyridine:Meta-substitution delivers intermediate steric and electronic properties for niche heterocycle fluorinations.
- 4-Methylpyridine:Para-methyl positioning suits specific regioselectivity requirements in dye intermediate synthesis.
Today's leader: Pyridine. Tomorrow's challenger: 2-Methylpyridine.
Application:
Cost tier differentiation separates commodity-scale agricultural consumption from precision pharmaceutical synthesis with divergent purity specifications.
- Agriculture:Crop protection manufacturers deploy standard-grade complexes for fluorinated herbicide and fungicide production. Resistance-management protocols in Brazilian soybean and Indian rice cultivation are expanding offtake volumes fastest.
- Pharmaceuticals:API producers demand sub-ppm metal specifications for fluorinated active ingredients under FDA and EMA impurity guidelines. CDSCO-aligned Indian generic manufacturers represent the steepest demand trajectory as domestic fluorination capacity scales.
- Dyes:Fluorinated azo and anthraquinone intermediates utilize technical-grade formulations with relaxed moisture specifications.
- Chemicals:Specialty fluorination reagents and analytical standards consume small volumes of ultra-high-purity lots.
Volume concentration: Agriculture. Margin concentration: Pharmaceuticals.
End User:
Customer type determines procurement modality, with integrated chemical manufacturers favoring bulk contracts and research institutions driving spot-market volatility.
- Chemical Manufacturers:Integrated fluorine derivatives producers in China and Mexico consume largest volumes through backward integration into phosphate fertilizer HF co-production.
- Agricultural Companies:Bayer CropScience and Syngenta procurement teams negotiate multi-year supply agreements with embedded technical service for resistance-management compound pipelines.
- Pharma Companies:Contract development and manufacturing organizations in the Netherlands and Switzerland prefer bundled reagent-analytical support contracts reflecting quality assurance staffing constraints.
- Research Institutions:Academic and government laboratories generate fragmented demand for gram-scale lots with expedited delivery.
Procurement scale: Chemical Manufacturers. Procurement sophistication: Pharma Companies.
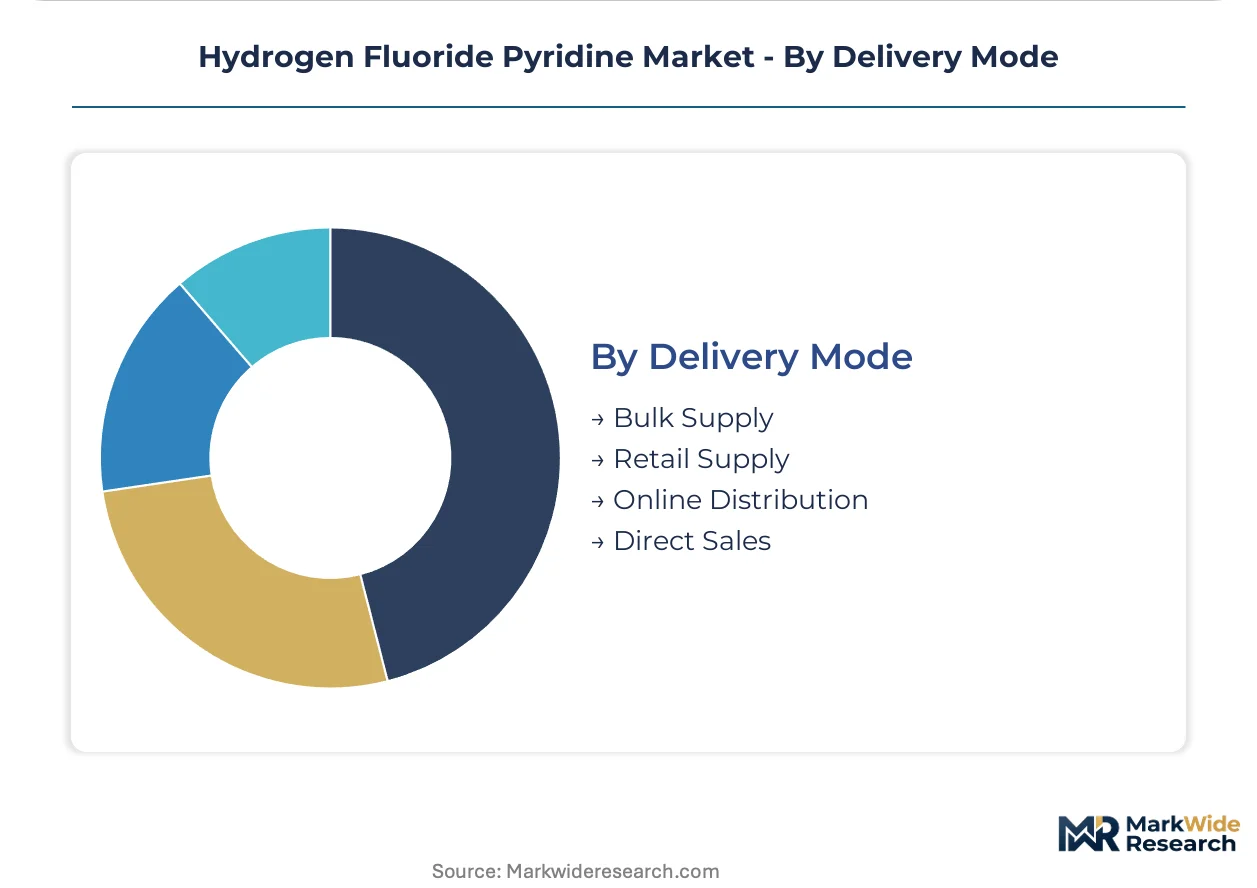
Delivery Mode:
Geography and volume scale dictate channel selection, with hazardous material shipping regulations fragmenting distribution economics.
- Bulk Supply:Tanker and ISO-container deliveries serve integrated chemical manufacturers with dedicated unloading infrastructure. OSHA and DOT classification requirements limit viable carrier pools.
- Retail Supply:Drum and pail formats reach mid-scale pharmaceutical API producers through specialty chemical distributors with hazmat warehousing.
- Online Distribution:E-procurement platforms capture research institution and small-lot demand with automated compliance documentation.
- Direct Sales:Producer-to-manufacturer relationships dominate agricultural and large pharmaceutical accounts with embedded technical service.
Channel efficiency: Direct Sales. Channel expansion: Online Distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical manufacturing clusters in Ludwigshafen and Leverkusen anchor hydrogen fluoride pyridine procurement for electrophilic fluorination campaigns serving European innovator drug programs.
Germany
Bayer and BASF pharmaceutical divisions drive demand for high-purity 2-methylpyridine complexes in crop protection synthesis. REACH registration mandates through ECHA enforce comprehensive toxicity documentation for commercial volumes above one tonne annually. The Rhine-Ruhr chemical corridor concentrates backward-integrated fluorine derivatives production with dedicated HF handling infrastructure.
United States
Specialty chemical distributors in New Jersey and Pennsylvania manage drum-format supply to mid-scale API producers expanding fluorination capabilities. EPA and OSHA frameworks govern workplace exposure limits and DOT shipping classifications for corrosive reagent transport. Greater Boston biotech clusters generate fragmented gram-scale demand for early-stage medicinal chemistry programs.
China
Integrated phosphate fertilizer producers in Guizhou and Yunnan provinces supply anhydrous hydrogen fluoride feedstock through captive co-production economics. The national pharmaceutical regulator enforces GMP alignment with ICH Q3D elemental impurity guidelines for fluorinated API exports. Yangtze River Delta contract manufacturers scale fluorination capacity for Western generic drug clients.
India
CDSCO import specification tightening for fluorinated intermediates redirects procurement from informal channels toward qualified suppliers with ICH-aligned documentation. Maharashtra and Gujarat pharmaceutical manufacturing zones expand domestic fluorination capacity for export-oriented generic API production. BIS standards increasingly influence technical specifications for reagent-grade complexes used in domestic drug synthesis.
Switzerland
Novartis and Roche legacy facilities in Basel maintain specialized electrophilic fluorination expertise concentrated among veteran process chemist cohorts. Swissmedic pharmacovigilance requirements extend to starting material quality agreements for fluorinated active ingredients. The country's precision chemical sector commands premium positioning for sterically demanding fluorination reagents.
Hydrogen Fluoride Pyridine Market Competitive Landscape
Portfolio diversification dominates the current landscape as legacy chemical conglomerates and specialty distributors reposition around fluorination chemistry safety requirements. The vendor base separates into three functional tiers: integrated fluorine derivatives producers with captive HF supply, catalog-based specialty chemical distributors serving research-scale demand, and regional formulators with localized hazmat logistics capabilities. Strategic archetypes include backward-integrated phosphate-derived HF suppliers, research-focused reagent catalog operators, and contract manufacturing organizations with continuous flow fluorination expertise. Capacity expansion and strategic partnerships represent the dominant competitive moves, with producers securing long-term base chemical supply agreements and distributors embedding technical service components into procurement contracts.
Among research-scale reagent specialists, Sigma-Aldrich exemplifies the catalog breadth archetype serving contract research organizations across North America and Europe. Honeywell occupies a position representing industrial-scale supply through fluorine derivatives infrastructure with phosphate-chemical backward integration. Fluorochem sits within the niche intermediate tier, anchoring specialized halopyridine positioning for agrochemical synthesis applications. These three entities collectively illustrate how geographic origin and corporate structure correlate with strategic emphasis—American conglomerate diversification, German catalog precision, and British specialty chemical focus.
| Leading Market Players |
|---|
| Sigma-Aldrich |
| Acros Organics |
| Alfa Aesar |
| Thomas Scientific |
| Oakwood Chemical |
| Cen-Med Enterprises |
| Iofina |
| Fluorochem |
| Honeywell |
| Others |
Value Network & Pricing Analysis
Anhydrous hydrogen fluoride spot pricing on the US Gulf Coast and Chinese phosphate fertilizer co-production economics cascade through hydrogen fluoride pyridine value chains, compressing margins for standard-grade suppliers while rewarding producers with captive feedstock or advanced purification capabilities. Contract manufacturers in Germany and Switzerland absorb volatility through long-term offtake agreements with base-chemical suppliers, whereas spot-market buyers in research channels face amplified exposure during supply tightness.
Pricing Analysis
Input-cost pass-through from concentrated fluorine supply dominates pricing formation, with phosphate-derived HF volatility transmitting directly to pyridine complex quotations. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade specifications with sub-ppm metal limits from agricultural technical grades and research-scale gram lots. Cost compression in standard pyridine formulations is intensifying because Brazilian and Indian agrochemical buyers consolidate procurement volumes under multi-year supply agreements. Research institutions exhibit highest price sensitivity due to fragmented demand and expedited delivery requirements, while integrated pharmaceutical manufacturers in Basel and Ludwigshafen prioritize quality assurance over unit economics.
Supply Chain Analysis
Workforce availability constraints for fluorine chemist expertise in Germany and Switzerland anchor specialized production capacity, limiting geographic diversification despite feedstock abundance elsewhere. Supply concentrates in China for phosphate-derived HF feedstock, in Germany for legacy electrophilic fluorination infrastructure, and in India for emerging generic API fluorination capacity. The supply chain draws from anhydrous hydrogen fluoride, pyridine base chemicals, and specialized glass-lined reactor systems as critical inputs. Single-source vulnerability around Chinese phosphate fertilizer co-production creates structural risk during environmental enforcement actions or export licensing shifts. Distribution runs through specialty chemical distributors with hazmat warehousing for drum-format deliveries, direct producer relationships for bulk agricultural accounts, and e-procurement platforms for research-scale fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydrogen fluoride pyridine markets offer margin expansion through premium-grade purification capabilities and continuous flow manufacturing cost-down trajectories. Producers capturing 2-methylpyridine steric-selectivity premiums or embedding technical service into supply contracts capture disproportionate value.
For Market Incumbents: Hedge against per- and polyfluoroalkyl substance regulatory expansion by qualifying alternative fluorinating agents with favorable biodegradation profiles ahead of ECHA restriction deadlines. Deepen backward integration into phosphate-derived HF supply or secure long-term base-chemical offtake agreements with Guizhou and Yunnan producers to defend margin position against feedstock volatility. Invest in continuous flow microreactor capabilities to reduce hold-up volumes and attract contract manufacturing demand from Netherlands-based pharmaceutical CDMOs. For New Entrants and Emerging Players: Continuous flow fluorination technology convergence with cryogenic processing offers a technology-first wedge into mid-scale pharmaceutical API production, where legacy batch reactor integration constraints delay incumbent adaptation. Target Indian generic manufacturers in Maharashtra and Gujarat pharmaceutical zones, where CDSCO specification tightening redirects procurement from informal channels toward qualified suppliers with ICH-aligned documentation. Lead with bundled reagent-analytical support contracts mirroring Japanese and South Korean buyer preferences for embedded quality assurance staffing. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty chemical distributors consolidating procurement for mid-tier pharmaceutical API producers under long-term supply agreements with technical service components. Long-term viability hinges on regulatory compliance sustainability and fluorination chemistry substitution risk across the projection horizon. Acquisition focus should center on regional formulators with localized hazmat logistics capabilities and established ECHA dossier documentation. Monitor EPA and EU F-Gas regulatory scope expansion as the critical inflection signal for fluorination chemistry platform shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into HF Feedstock | Captive phosphate-derived supply from Guizhou producers insulates margin from spot volatility. |
| Continuous Flow Technology Deployment | Microreactor convergence with inline spectroscopy attracts Netherlands pharmaceutical CDMO contracts. |
| 2-Methylpyridine Capacity Addition | Steric-selectivity premium positioning serves Brazilian agrochemical resistance-management pipelines. |
| Long-term Supply Agreement | Multi-year contracts with embedded technical service displace spot-market purchasing in North America. |
| Alternative Fluorinating Agent Qualification | Favorable biodegradation profiles ahead of ECHA deadlines mitigate PFAS regulatory reclassification risk. |
Research Methodology
Bottom-up pharmaceutical and agrochemical end-use modeling reconciled against top-down fluorine derivatives supply tracking forms the analytical core. Primary interviews with plant managers at integrated HF producers, procurement leads at agricultural chemical divisions, distribution channel partners with hazmat warehousing capabilities, and technical R&D directors specializing in electrophilic fluorination generated demand-side intelligence. Secondary validation drew from ECHA REACH registration databases, CDSCO import specification filings, SEC 10-K disclosures from listed chemical conglomerates, and customs trade data for hydrogen fluoride pyridine HS code movements. Triangulation between stakeholder interview insights and documentary evidence established volume and value estimates.
Historical trendline analysis across pharmaceutical fluorination adoption curves and agrochemical active ingredient pipelines informed projection frameworks. Segmentation dimensions modeled include pyridine base composition, application end-use, purity grade tier, and regional production hub concentration. CAGRs were derived from slope analysis of segment-specific growth trajectories adjusted for regulatory inflection points. Industry-specific forecast inputs incorporated REACH registration compliance timelines, CDSCO specification alignment progress, and continuous flow technology adoption rates among contract manufacturers.
The model holds under stable regulatory scope for fluorination chemistry and intact phosphate fertilizer co-production economics; deviation in PFAS restriction expansion or Chinese environmental enforcement intensity would shift trajectory. Forecasts reflect documented assumptions regarding ECHA dossier sustainability and ICH Q3D alignment adoption across Indian generic manufacturers. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
India Ethoxylates Market
Chemicals
Global Aldehyde Market
Chemicals
Isooctyl Alcohol Market
Chemicals
Japan Methanol Market
Chemicals
Ferric Chloride Market
Chemicals
Benzoyl Alcohol Market
Chemicals
Global Aluminum Hydroxide Market
Chemicals
Chemical Distribution Market
Chemicals
Insect Repellent Active Ingredients Market
Chemicals
Global Tetraacetylethylenediamine (TAED) Market
Chemicals
Fatty Alcohol Ethoxylates Market
Chemicals
Lauryl Dimethyl Amine Oxide Market
Chemicals
Elemental Fluorine Market
Chemicals
Global Electronic Grade Phosphoric Acid Market
Chemicals
Natural Fatty Alcohols Market
Chemicals
Egypt Acidulants Market