
 Fatty Alcohol Ethoxylates Market | 2026-2036
Fatty Alcohol Ethoxylates Market Size, Share, and Industry Trends Forecast 2026-2036
Fatty Alcohol Ethoxylates Market Analysis
Petrochemical-derived fatty alcohols is decoupling from cost parity with oleochemical routes as palm kernel and coconut oil feedstocks stabilize in Southeast Asia. BASF SE leverages integrated ethylene oxide supply chains in Europe and North America to sustain margin capture across detergent-grade ethoxylates. Wilmar International Ltd. anchors its position through backward integration into Malaysian palm oil refining, securing feedstock access that competitors lack. Stepan Company differentiates via specialized narrow-range ethoxylation technology for personal care applications requiring low residual alcohol content.
Fatty alcohol ethoxylates are nonionic surfactants produced by reacting fatty alcohols with ethylene oxide in alkali-catalyzed processes, yielding products with ethoxylation degrees typically ranging from 3 to 50 moles of ethylene oxide per mole of alcohol; these compounds function primarily as wetting agents, emulsifiers, and detergents across aqueous formulations. The nonionic surfactants segment dominates volume due to its ubiquity in laundry and dishwashing formulations, while emulsifiers command premium positioning in cosmetics where skin mildness specifications tighten. Liquid formulations lead in industrial and household channels for dosing convenience, though concentrates are gaining traction as brand owners reduce water content in shipped goods.
EPA Safer Choice criteria and REACH restrictions on aquatic toxicity are narrowing the acceptable window for residual free fatty alcohol and ethoxylate distribution, forcing reformulation investments across the supply base. ECHA's classification of certain ethoxylates as substances of very high concern is redirecting R&D toward narrow-range and bio-based alternatives in European supply chains. ISO 17025 testing protocols for surfactant purity are becoming baseline requirements for market access in regulated jurisdictions. Stakeholders must monitor feedstock certification schemes and ethoxylation catalyst advances to preserve formulation flexibility as regulatory thresholds tighten.
Market Dynamics
REACH restrictions on aquatic toxicity and EPA Safer Choice standards are compressing acceptable ethoxylate distribution windows, forcing manufacturers to abandon broad-range catalysts and invest in narrow-range ethoxylation infrastructure that reduces residual free fatty alcohol content.
Growth Catalysts
- EU Green Deal chemical sustainability targets:Bio-based feedstock mandates accelerate oleochemical route expansion across European detergent supply chains, advantaging producers with certified palm kernel oil access.
- Personal care formulators in Indonesia:Southeast Asian cosmetic manufacturers are consolidating procurement around locally ethoxylated narrow-range products to meet skin mildness specifications while reducing import dependence.
- Ethoxylation catalyst advances:Novel alkaline catalyst systems enabling tighter ethylene oxide distribution curves are unlocking premium positioning in pharmaceutical and food-grade emulsifier segments.
Market Restraints
- Palm kernel oil price volatility:Feedstock cost swings in Malaysian and Indonesian oleochemical supply chains erode margin predictability for bio-based ethoxylate producers.
- ECHA SVHC classification pressure:Substances of very high concern listings for certain ethoxylate chemistries create reformulation liabilities and stranded inventory risk across European value chains.
- Petrochemical route lock-in:Existing ethylene oxide infrastructure in Germany and the United States creates path dependency that slows feedstock pivot decisions despite oleochemical cost convergence.
Strategic Opportunities
- Indian agrochemical emulsifier demand:Crop protection formulation growth creates import substitution potential for domestic ethoxylation capacity serving pesticide and fertilizer applications.
- ISO 17025 certification premiums:Third-party purity verification protocols enable price stratification between certified and uncertified surfactant suppliers in regulated personal care markets.
- Concentrate formulation channels:Water-reduced detergent and cleaning product formats reward ethoxylate producers with logistics-optimized liquid concentrate supply capabilities.
Industry Challenges
- Narrow-range process engineering talent scarcity:Specialized alkoxylation reactor operation and catalyst optimization expertise concentrates among legacy European and North American technical workforces.
- Multi-jurisdiction certification timelines:Simultaneous EPA Safer Choice, REACH registration, and BIS compliance for Indian market entry stretches regulatory affairs capacity and delays revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fatty Alcohol Ethoxylates Market |
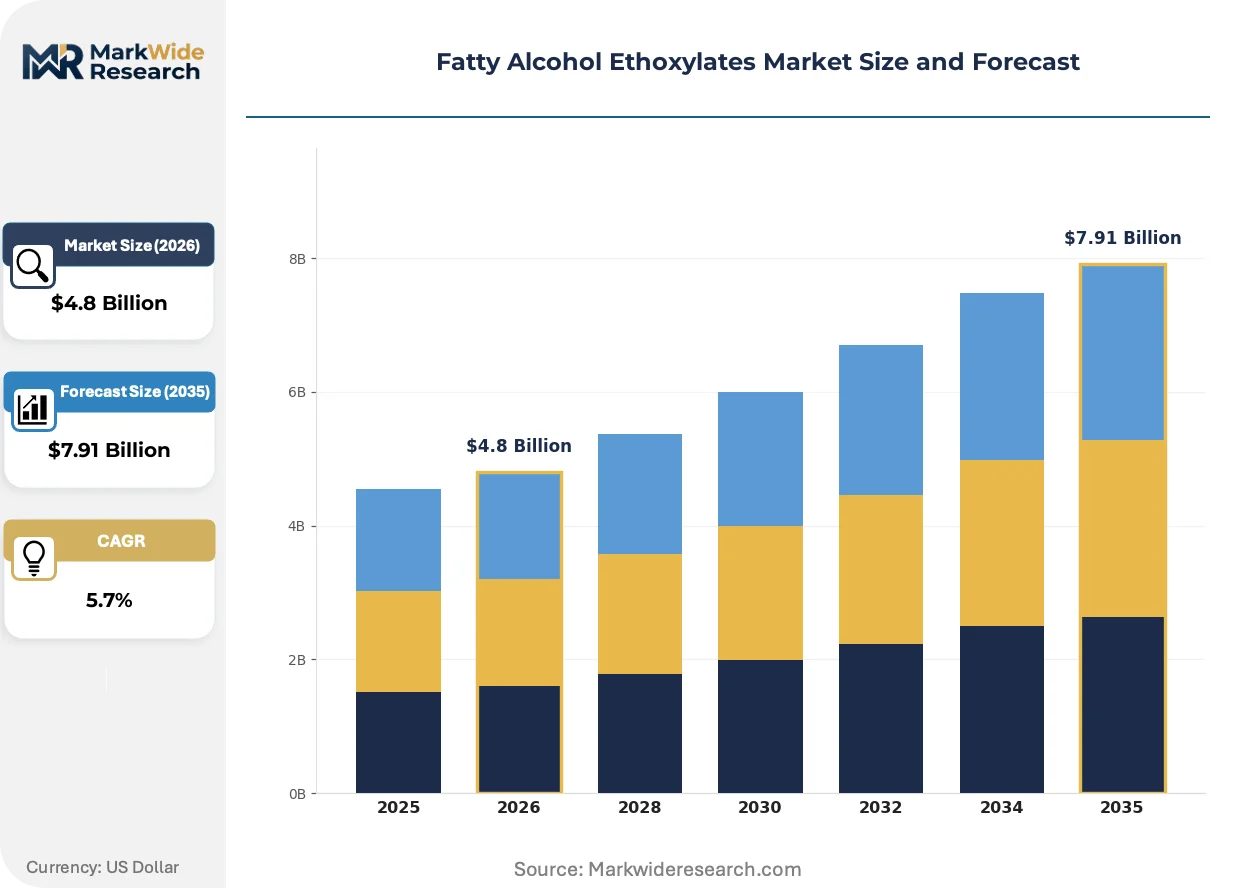
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nonionic Surfactants, Detergents, Emulsifiers, Wetting Agents End User: Personal Care, Household Cleaning, Industrial Applications, Food Processing Formulation Type: Liquid Formulations, Powder Formulations, Solid Granules, Concentrates Application: Cosmetics, Soap Production, Surface Cleaning, Oil Recovery |
| Companies Covered | Huntsman International LLC, Stepan Company, BASF SE, Wilmar International Ltd., Croda International, Clariant, Akzo Nobel N.V., Ecogreen Oleochemicals, P&G Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fatty Alcohol Ethoxylates Market Emerging Trajectories
Catalyst innovation and regulatory stringency are restructuring competitive advantage around ethoxylation precision rather than scale economies, compressing the viable technology set and rewarding specialized process capabilities.
Narrow-range ethoxylation technology is overtaking conventional broad-distribution processes in premium personal care and pharmaceutical applications. Cosmetic formulators in France and Germany now specify ethoxylation degree distributions within 1-2 moles rather than 4-6 mole spans. This precision requirement is compressing the supplier base to producers with advanced alkaline catalyst systems and in-line analytical control.
REACH restrictions on aquatic toxicity are narrowing formulation freedom across European industrial and consumer cleaning segments. ECHA's evolving classification criteria for ethoxylate biodegradation byproducts are forcing detergent manufacturers to validate narrower ethoxylation distributions through ISO 17025 certified testing protocols. Personal care brands with EU market exposure are accelerating supplier qualification audits to preempt compliance gaps.
Direct procurement relationships between oleochemical refiners and ethoxylate end-users are displacing traditional distributor intermediaries in Southeast Asian supply chains. Malaysian palm oil integrated producers are establishing captive ethoxylation capacity to serve Indonesian and Thai detergent manufacturers. This channel compression is visible in procurement pattern shifts among large Southeast Asian personal care multinationals seeking feedstock traceability and cost transparency.
Fatty Alcohol Ethoxylates Market Segmentation
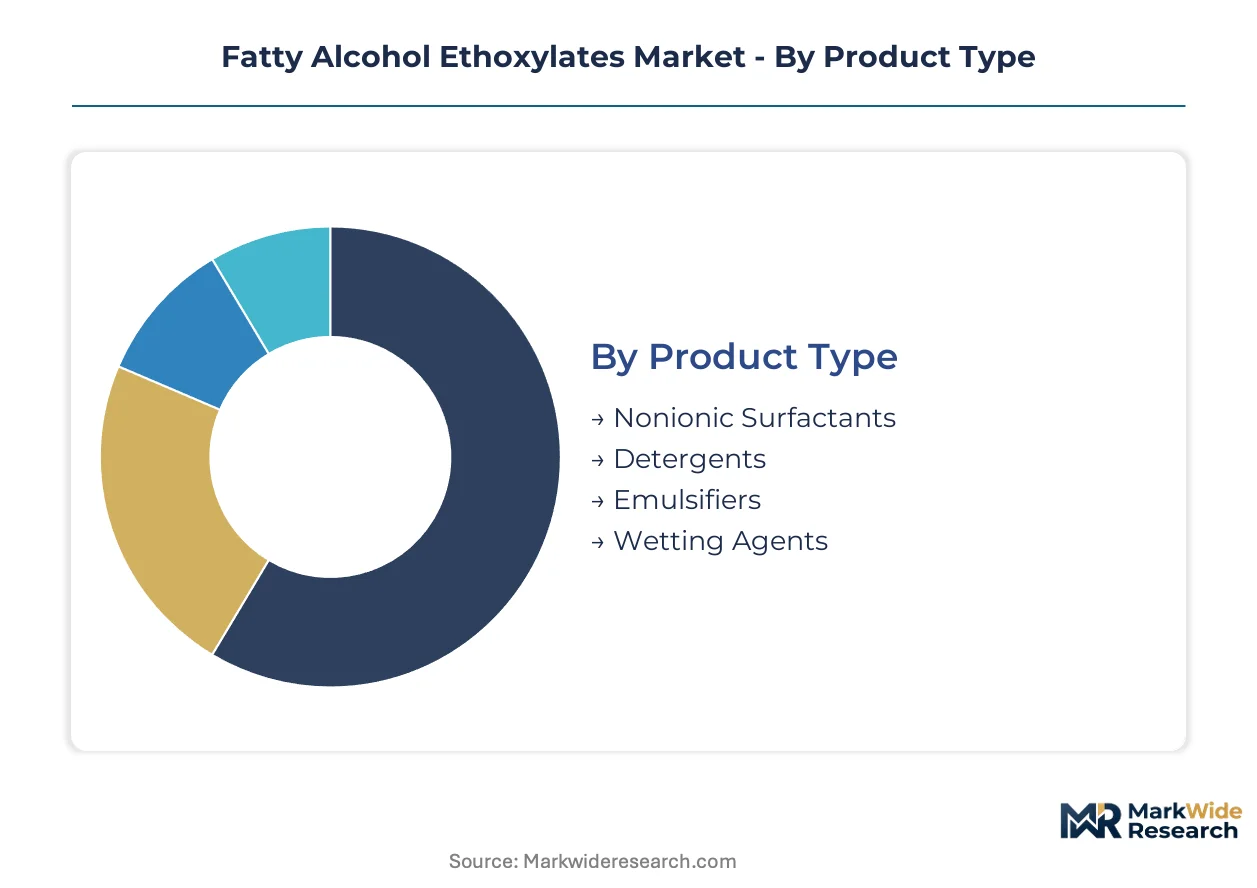
Ethoxylation degree distribution and feedstock origin create distinct performance tiers that separate commodity detergent applications from premium personal care formulations. Buyers select segments based on regulatory compliance requirements, skin mildness specifications, and supply chain traceability needs rather than surfactant activity alone.
Product Type:
Cost tier separates commodity surfactant buyers from premium emulsifier purchasers seeking narrow-range specifications.
- Nonionic Surfactants:Broad-ethoxylation products with 7-15 mole EO distributions dominate laundry and dishwashing formulations. Demand concentrates in Indonesian and Thai detergent manufacturing where oleochemical feedstock integration supports cost-competitive supply.
- Emulsifiers:Narrow-range ethoxylates with 1-2 mole distribution precision serve cosmetic formulations requiring low residual fatty alcohol content. European personal care brands specify these grades to meet REACH aquatic toxicity thresholds.
- Detergents:Mid-range ethoxylation products balance foaming performance with biodegradability compliance.
- Wetting Agents:Low-EO grades enhance spreading in agricultural and industrial coating applications.
Volume sits with nonionic surfactants; growth tilts toward emulsifiers.
End User:
Application maturity drives margin structure, with established household channels competing on logistics efficiency while personal care commands certification premiums.
- Personal Care:Skin mildness specifications and ISO 17025 purity verification requirements dominate supplier selection. Southeast Asian formulators consolidate procurement around Malaysian-produced narrow-range ethoxylates to reduce import dependence.
- Household Cleaning:Concentrate formulations and water-reduced shipping formats reward suppliers with liquid concentrate logistics capabilities.
- Industrial Applications:Process efficiency and bulk pricing determine procurement patterns in metalworking and textile processing.
- Food Processing:Food-grade emulsifier specifications restrict supply base to producers with catalyst systems validated for pharmaceutical and edible oil applications.
Household cleaning captures volume leadership; personal care delivers the steepest expansion trajectory.
Formulation Type:
Customer type segmentation separates industrial bulk buyers from brand owners optimizing shipped water content.
- Liquid Formulations:Dosing convenience dominates household and industrial channels, though concentrate dilution ratios are compressing traditional ready-to-use formats.
- Concentrates:Water-reduced formats reduce freight costs and packaging waste, aligning with EU Green Deal chemical sustainability targets.
- Powder Formulations:Spray-dried ethoxylates serve automatic dishwasher tablets and laundry powders in European markets.
- Solid Granules:Low-dust handling properties suit agricultural chemical compounding and institutional cleaning tablets.
Liquid formulations retain volume dominance; concentrates are climbing the fastest.
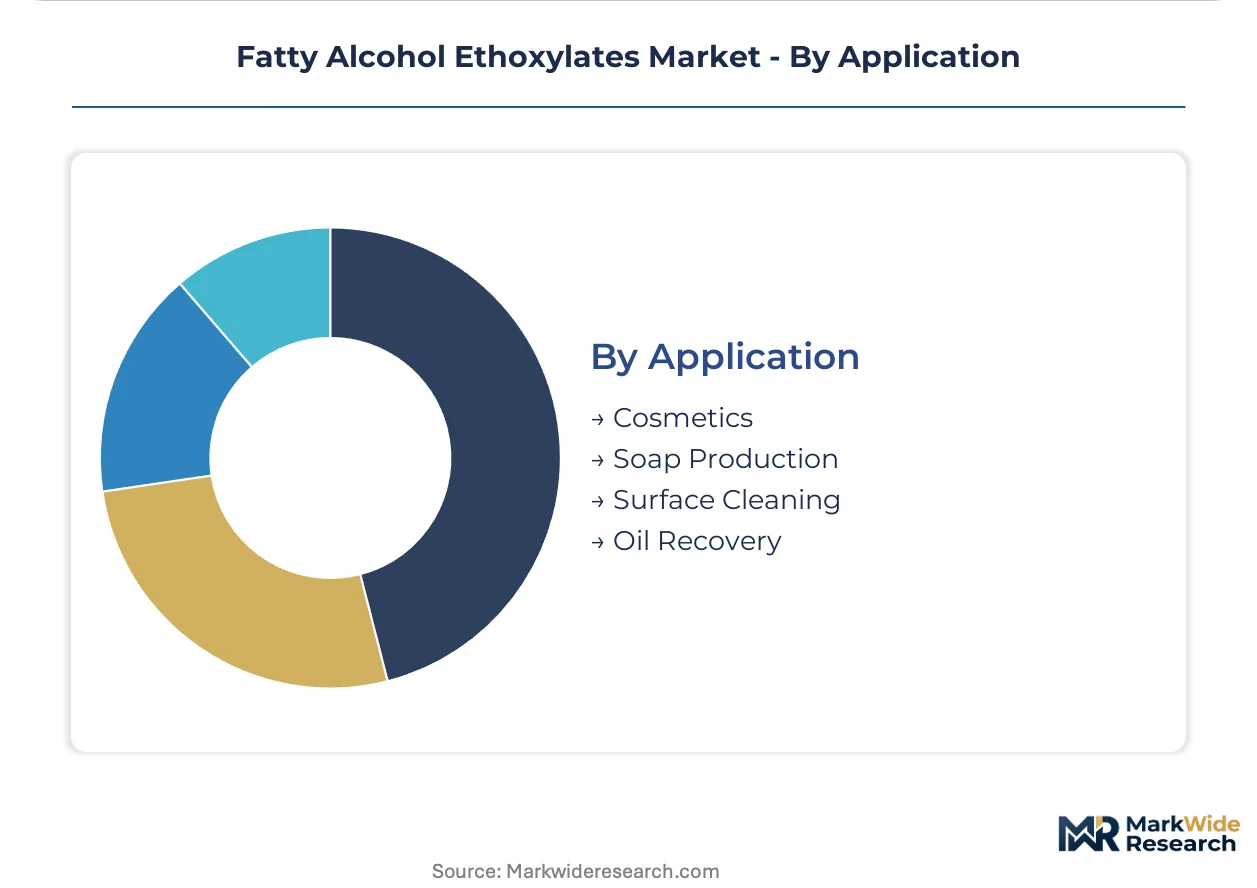
Application:
Geography determines specification intensity, with European cosmetics and North American oil recovery imposing divergent purity requirements.
- Cosmetics:ECHA SVHC classification pressure and REACH aquatic toxicity restrictions narrow acceptable ethoxylate distribution windows. French and German formulators now specify ethoxylation degree distributions within 1-2 moles.
- Surface Cleaning:Institutional and industrial degreasing applications balance performance against biodegradability validation costs.
- Soap Production:Syndet bar manufacturing in Southeast Asia integrates locally ethoxylated feedstocks for cost and traceability advantages.
- Oil Recovery:Enhanced oil extraction formulations in North American shale operations demand specialized wetting agent chemistries.
Surface cleaning holds volume; cosmetics gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for fatty alcohol ethoxylates concentrates in Southeast Asian detergent manufacturing clusters and European personal care formulation centers, with feedstock proximity and regulatory stringency determining regional competitive advantages.
Indonesia
Indonesian detergent manufacturers are expanding procurement of locally ethoxylated surfactants to reduce import dependence on Singaporean and Malaysian suppliers. The country's national standards body enforces BIS-aligned purity specifications for imported surfactants, creating compliance barriers for uncertified producers. Manufacturing activity clusters around Surabaya and Jakarta, where palm oil-derived feedstock integration supports cost-competitive ethoxylation capacity expansion.
Germany
German personal care formulators specify narrow-range ethoxylates with 1-2 mole distribution precision to meet ECHA aquatic toxicity thresholds. REACH restrictions on residual free fatty alcohol content compress acceptable formulation windows, forcing suppliers to validate products through ISO 17025 certified testing protocols. The Rhine-Ruhr industrial corridor hosts specialized alkoxylation reactor operations where catalyst optimization expertise concentrates among legacy technical workforces.
United States
EPA Safer Choice standards drive reformulation investments across American household cleaning supply chains, with concentrate formulations gaining traction as brand owners reduce water content in shipped goods. The agency's evolving criteria for surfactant biodegradation byproducts narrow acceptable ethoxylate distribution curves. Gulf Coast petrochemical infrastructure in Texas and Louisiana sustains ethylene oxide supply chains for detergent-grade ethoxylate production despite oleochemical cost convergence.
Malaysia
Malaysian palm oil integrated producers are establishing captive ethoxylation capacity to serve Indonesian and Thai detergent manufacturers seeking feedstock traceability. Wilmar International Ltd. anchors its position through backward integration into domestic palm oil refining, securing feedstock access that competitors lack. The Port Klang-Pasir Gudang corridor functions as the primary oleochemical processing hub where direct procurement relationships displace traditional distributor intermediaries.
India
Indian agrochemical emulsifier demand creates import substitution potential for domestic ethoxylation capacity serving pesticide and fertilizer applications. BIS compliance requirements for surfactant purity stretch regulatory affairs capacity for multinational suppliers entering the market. Manufacturing investments concentrate in Gujarat and Maharashtra, where specialty chemical clusters support narrow-range process engineering capabilities for pharmaceutical-grade emulsifier segments.
Fatty Alcohol Ethoxylates Market Vendor Landscape
Backward integration into oleochemical feedstocks dominates the current landscape, with producers securing palm kernel oil access to stabilize margin predictability against petrochemical price volatility. The vendor base organizes around three strategic tiers: integrated oleochemical majors with captive refining assets, specialized ethoxylation houses with narrow-range catalyst expertise, and multinational chemical conglomerates leveraging ethylene oxide supply chain scale. M&A activity targets regional distributors in Southeast Asia, while capacity expansion concentrates in Indonesian and Malaysian manufacturing corridors.
Within the integrated oleochemical tier, Wilmar International Ltd. exemplifies feedstock-controlled competitive positioning through its Malaysian palm oil refining operations. BASF SE occupies a position among multinational chemical conglomerates leveraging ethylene oxide infrastructure across European and North American supply chains. Stepan Company represents the specialized ethoxylation archetype, with narrow-range technology capabilities serving personal care applications requiring low residual alcohol content.
| Leading Market Players |
|---|
| Huntsman International LLC |
| Stepan Company |
| BASF SE |
| Wilmar International Ltd. |
| Croda International |
| Clariant |
| Akzo Nobel N.V. |
| Ecogreen Oleochemicals |
| P&G Chemicals |
| Others |
Supply Flow & Price Mechanics
Indonesian detergent manufacturers purchasing narrow-range ethoxylates operate on contract-based long-term offtake agreements that compress spot market liquidity and anchor price discovery to Malaysian oleochemical benchmarks. REACH compliance costs in Europe and EPA Safer Choice certification requirements in the United States create tiered pricing stratification across premium certified, standard industrial, and economy detergent grades.
Pricing Analysis
Volume sits with broad-ethoxylation nonionic surfactants where commodity spot pricing prevails; margins concentrate in narrow-range emulsifiers commanding certification premiums. Price differentiation rests on ISO 17025 purity verification and REACH aquatic toxicity compliance, with European personal care brands paying substantial premiums for validated narrow-distribution products. Cost compression in commodity detergent grades is intensifying because Indonesian and Thai manufacturers are consolidating procurement around integrated Malaysian suppliers. Household cleaning channels exhibit highest price sensitivity due to bulk volume negotiations, while pharmaceutical and food-grade emulsifier buyers prioritize specification compliance over unit cost.
Supply Chain Analysis
Reverse-logistics flows for catalyst recovery and spent ethoxylation solvent reclamation concentrate specialized handling capabilities in the Rhine-Ruhr corridor and Port Klang-Pasir Gudang hub. Manufacturing gravity centers on Malaysia, Indonesia, and Germany, with feedstock access determining competitive positioning. Raw material dependencies draw from palm kernel oil, coconut oil, and ethylene oxide feedstocks, with oleochemical routes gaining preference as petrochemical cost parity erodes. Single-source vulnerability concentrates in Malaysian palm oil refining capacity controlled by integrated majors. Distribution runs through direct procurement relationships displacing traditional distributor intermediaries in Southeast Asian supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into oleochemical feedstocks defines competitive positioning as producers secure palm kernel oil access to stabilize margin predictability against petrochemical price swings.
For Market Incumbents: Acquire narrow-range ethoxylation reactor assets and specialized catalyst optimization expertise to defend premium positioning against emerging Southeast Asian integrated producers. Secure captive palm oil refining capacity in Malaysia or Indonesia to eliminate feedstock cost volatility exposure. Invest in ISO 17025 certification infrastructure to maintain European personal care market access as ECHA SVHC classifications tighten. For New Entrants and Emerging Players: Indian agrochemical emulsifier buyers represent the most penetrable white-space opportunity, with import substitution potential for domestic ethoxylation capacity serving pesticide formulation growth. Establish toll manufacturing partnerships with existing oleochemical refiners to bypass capital-intensive feedstock infrastructure. Target concentrate formulation channels in household cleaning where logistics-optimized liquid supply capabilities reward specialized entrants. For Investors and Strategic Acquirers: The window for entry favors specialized ethoxylation houses with narrow-range catalyst expertise over commodity surfactant producers facing margin compression. Long-term viability hinges on regulatory compliance capabilities and feedstock integration depth rather than scale alone. Monitor ECHA SVHC classification expansions and EPA Safer Choice criteria evolution as inflection indicators for stranded inventory risk and reformulation liability exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive palm oil refining in Malaysia eliminates feedstock cost volatility for ethoxylate producers. |
| Narrow-Range Capacity Expansion | Specialized alkoxylation reactor investments unlock REACH-compliant supply to European personal care formulators. |
| ISO 17025 Certification Program | Third-party purity verification enables price stratification in regulated cosmetics and pharmaceutical segments. |
| Long-Term Supply Agreement | Contract-based offtake with Indonesian detergent manufacturers reduces spot market exposure and stabilizes utilization. |
| Joint Venture | Partnerships with Malaysian oleochemical majors accelerate market entry for narrow-range technology specialists. |
Methodological Framework
Independent corroboration across plant managers at ethoxylation facilities, procurement leads at downstream detergent and personal care OEMs, distribution channel partners, and technical R&D directors underwrites the qualitative findings in this study. Primary interviews combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and REACH registration databases establish market sizing boundaries. Bottom-up capacity assessments and top-down demand triangulation cross-validate volume estimates across the analysis window.
Rate-of-change decomposition separates volume growth from price/mix effects across ethoxylation degree distribution, feedstock origin, end-use industry, formulation type, and regional production hub dimensions. CAGRs derive from segment-level growth trajectories modeled against oleochemical feedstock cost convergence, regulatory compliance cost inflation, and narrow-range technology adoption curves. Forecast inputs incorporate catalyst innovation timelines and ECHA classification evolution patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to palm kernel oil price volatility, REACH restriction expansions, and Indonesian domestic capacity buildout. Practitioners should monitor ECHA SVHC candidate list updates, Malaysian oleochemical export license policies, and EPA Safer Choice criteria revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Sodium Azide Market
Chemicals
(S)-(+)-2-Amino-1-Propanol Market
Chemicals
North America Tartaric Acid Market
Chemicals
Desalination Chemicals Market
Chemicals
Germany Methanol Market
Chemicals
Asia-Pacific Surface Treatment Chemicals Market
Chemicals
Indonesia Nitric Acid Market
Chemicals
Benzalkonium Bromide Market
Chemicals
Electronic Grade Hydrofluoric Acid Market
Chemicals
Global N-Butanol Market
Chemicals
Isopropyl Alcohol (IPA) Market
Chemicals
Hexamethylenetetramine (HMTA) Market
Chemicals
Global Oxo Alcohols Market
Chemicals
Cumene Hydroperoxide Market
Chemicals
Azodicarbonamide (ADC) Market
Chemicals
North America Methanol Market