
 Global Aldehyde Market | 2026-2036
Global Aldehyde Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aldehyde Market Foresight
Pharmaceutical-grade specification tiers is bifurcating the competitive landscape as buyers enforce stricter impurity ceilings. BASF SE leverages integrated C1 chemistry platforms to sustain supply security across formaldehyde and acetaldehyde chains. Eastman Chemical Company anchors North American acetaldehyde derivatives through backward integration into vinyl acetate monomer production. Huntsman Corporation differentiates via specialized glutaraldehyde grades for medical disinfectant applications.
Aldehydes comprise organic compounds bearing a terminal carbonyl group (R-CHO), typically manufactured through catalytic oxidation of alcohols or hydrocarbons, with purity grades ranging from technical to pharmaceutical specification depending on end-use toxicity thresholds. Formaldehyde dominates volume flows into resins and coatings for construction and infrastructure, where urea-formaldehyde and phenol-formaldehyde polymers bind engineered wood products. Benzaldehyde and glutaraldehyde command premium positions in pharmaceuticals and agrochemicals, where nitrogen heterocycle synthesis and crop protection formulations reward higher purity inputs.
EPA toxics release thresholds, REACH registration requirements under ECHA, and China's GB standards through SAMR collectively constrain emission profiles and mandate closed-loop handling systems for volatile aldehyde streams. FDA oversight of pharmaceutical excipients and disinfectant registrations further segments accessible markets by compliance tier. Stakeholders must monitor regulatory divergence between jurisdictions to align capacity investments with enforceable purity and emissions benchmarks.
Market Dynamics
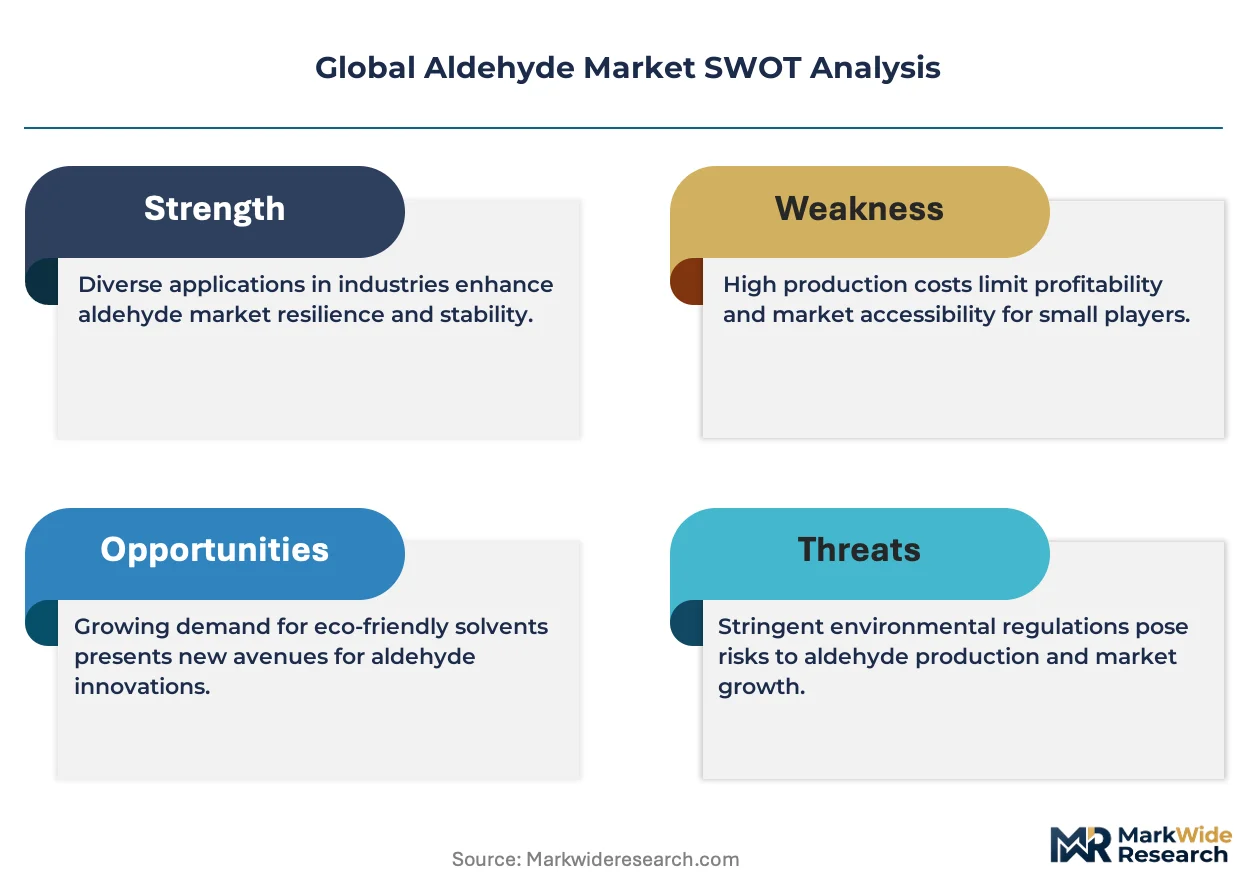
Pharmaceutical-grade purity thresholds are splitting the aldehyde market into parallel supply chains, as REACH registration requirements and FDA excipient standards force technical-grade producers to either upgrade purification infrastructure or retreat to commodity resin applications.
Growth Catalysts
- Pharmaceutical intermediates:Nitrogen heterocycle synthesis for oncology and antiviral APIs demands sub-50 ppm impurity ceilings that only specialized oxidation trains can deliver.
- REACH Article 57 authorization:ECHA's tightening SVHC criteria for formaldehyde releasers is accelerating substitution toward controlled-release glutaraldehyde biocides in medical device sterilization.
- India's PLI scheme:Domestic API manufacturing incentives under the Production Linked Incentive program are drawing acetaldehyde derivative capacity toward Gujarat and Hyderabad clusters.
Market Restraints
- Methanol feedstock volatility:Natural gas price swings in the US Gulf and coal cost fluctuations in China's Shanxi province transmit directly into formaldehyde variable costs.
- Shandong supply concentration:Three integrated C1 chemistry complexes control over half of Asia's merchant acetaldehyde output, creating single-source vulnerability for Southeast Asian derivative producers.
- Aqueous ammonia substitution:Pre-treatment of engineered wood with ammonium salts is displacing low-concentration formaldehyde resins in European furniture manufacturing.
Strategic Opportunities
- Brazilian agrochemical formulators:ANVISA's streamlined registration pathway for generic crop protection molecules is opening premium benzaldehyde demand for pyrethroid synthesis.
- Closed-loop catalytic oxidation:Integration of membrane separation with silver-catalyzed methanol oxidation is bifurcating emissions profiles between zero-vent plants and legacy atmospheric discharge facilities.
- EU Green Deal carbon border adjustments:CBAM scope expansion toward chemical intermediates will reward low-carbon intensity aldehyde production with preferential access to German automotive coatings supply chains.
Industry Challenges
- Process analytical chemistry talent:Real-time monitoring of carbonyl impurity spectra requires scarce spectroscopists capable of validating ICH Q3D elemental impurity methods.
- Pharmaceutical-grade certification timelines:FDA Type II drug master file preparation and EMA CEP dossier compilation extend qualification cycles to 18-24 months for new aldehyde suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aldehyde Market |
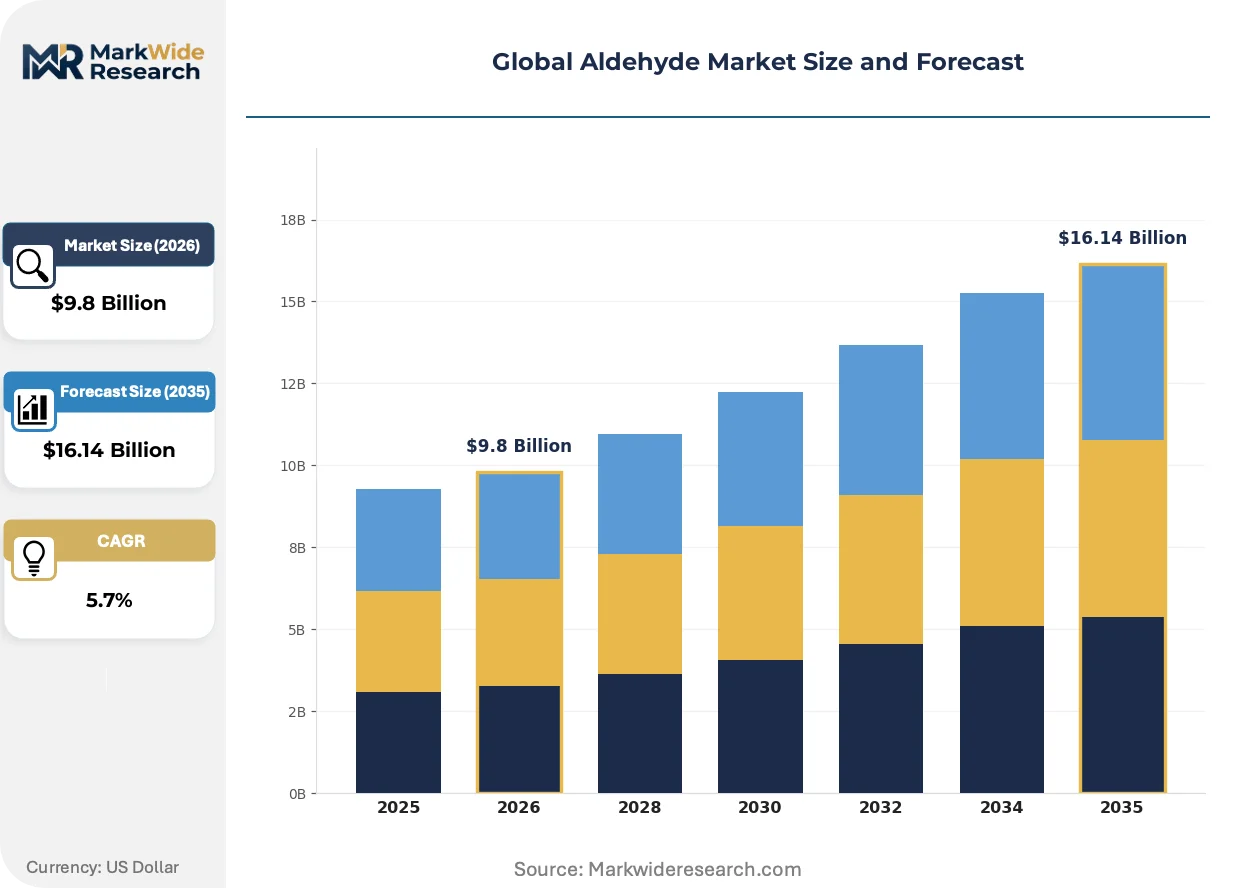
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $16.14 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
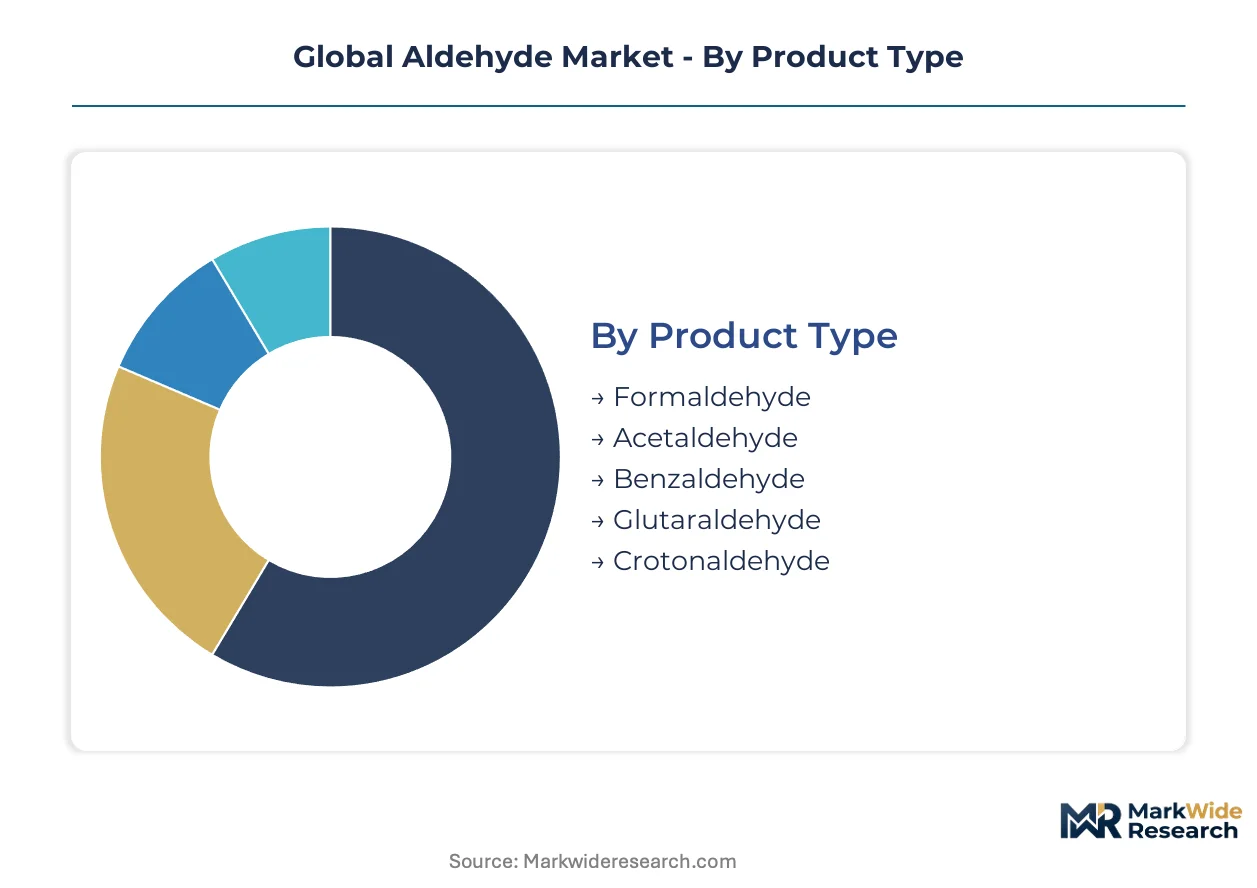
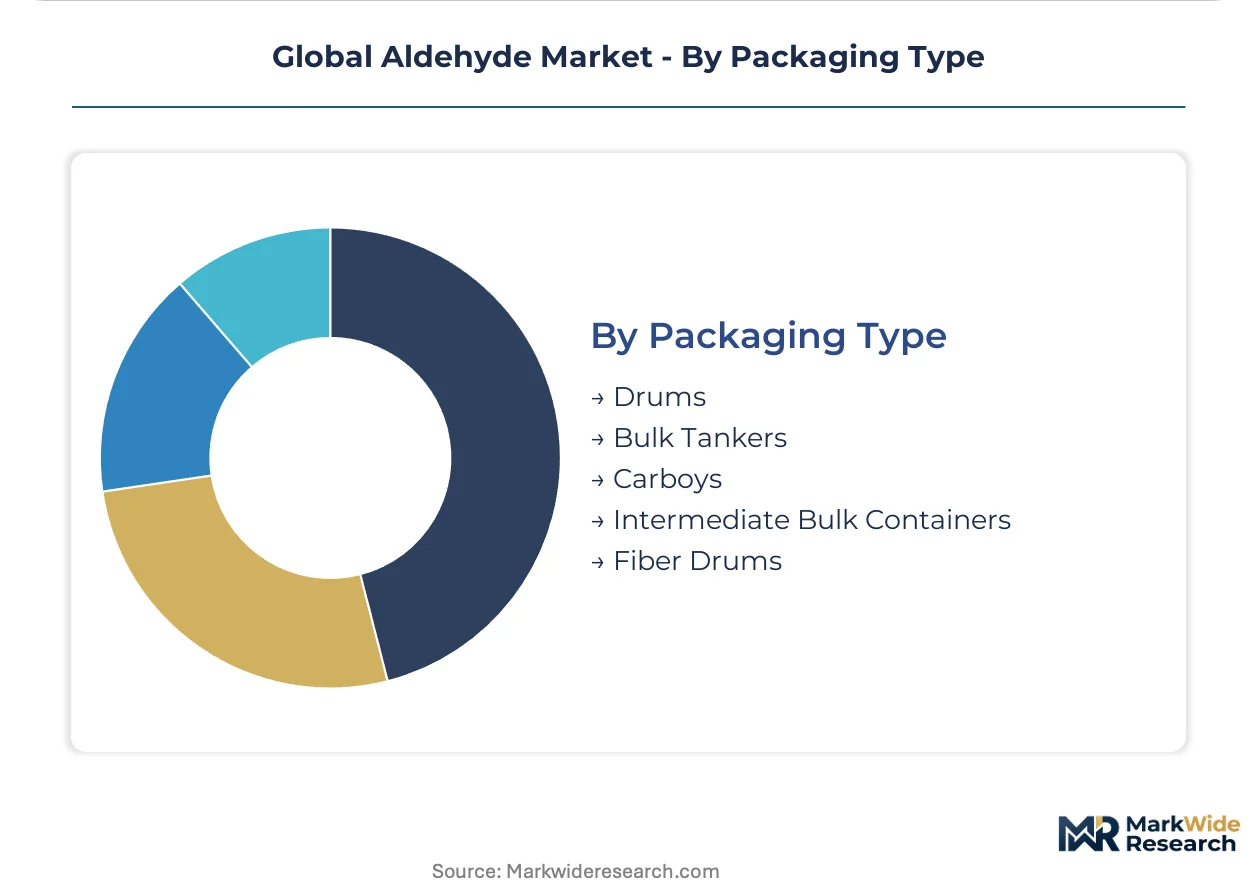
| Segmentation | Product Type: Formaldehyde, Acetaldehyde, Benzaldehyde, Glutaraldehyde, Crotonaldehyde Application: Resins & Coatings, Plasticizers, Agrochemicals, Textile Processing, Pharmaceuticals End User Industry: Construction & Infrastructure, Chemical Manufacturing, Agriculture, Personal Care, Automotive Suppliers Packaging Type: Drums, Bulk Tankers, Carboys, Intermediate Bulk Containers, Fiber Drums |
| Companies Covered | BASF SE, Eastman Chemical Company, Huntsman Corporation, Celanese Corporation, Dow Inc, Evonik Industries AG, Sumitomo Chemical Co., Ltd., Arkema S.A., Lonza Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aldehyde Market Shifts & Advancements
Continuous processing technology and spectroscopic quality control are converging to compress batch cycle times while tightening specification bands. These advances are redrawing the boundary between commodity and specialty aldehyde production.
Silver-catalyzed methanol-to-formaldehyde oxidation is bifurcating plant economics between single-train mega-facilities exceeding 500 kilotonnes annual capacity and modular skid-mounted units serving regional resin blenders. German automotive OEMs now require ISO 14001-certified formaldehyde for interior trim adhesives, forcing Tier-2 suppliers to source exclusively from integrated producers with verified carbon intensity disclosures. The technology is compressing margins for mid-scale atmospheric plants lacking heat recovery integration.
REACH Annex XIV authorization requirements for formaldehyde are accelerating substitution toward glutaraldehyde and glyoxal in leather tanning and textile finishing applications. ECHA's 2023 restriction proposal on skin-sensitizing aldehydes is forcing Italian upholstery manufacturers to reformulate with controlled-release biocide systems. The regulatory pressure is most acute in German automotive seating supply chains, where OEMs are pre-emptively banning formaldehyde-releasing preservatives ahead of legal deadlines.
Pharmaceutical buyers are consolidating active pharmaceutical ingredient procurement around qualified aldehyde suppliers with dedicated pharmaceutical-grade production lines. Large-scale generic drug manufacturers in India are signing multi-year toll manufacturing agreements with domestic acetaldehyde producers rather than importing technical-grade material for in-house purification. This concentration is most visible in Hyderabad's bulk drug park, where CDSCO inspection readiness has become a non-negotiable supplier selection criterion.
Global Aldehyde Market Segmentation
Regulatory divergence across jurisdictions fragments the aldehyde market into parallel supply chains. REACH SVHC listings, FDA excipient standards, and China's GB specifications each demand distinct purity tiers, forcing producers to segment capacity by compliance grade rather than chemistry alone.
Product Type:
REACH Article 57 authorization requirements and ECHA's restriction proposals on formaldehyde releasers are bifurcating production into controlled-release biocide grades versus legacy commodity streams.
- Formaldehyde:The simplest aldehyde (HCHO), manufactured via silver-catalyzed methanol oxidation with purity grades spanning 37% aqueous solutions to low-emission resins. Construction demand in China and Germany concentrates volume flows into urea-formaldehyde and phenol-formaldehyde binders for engineered wood products.
- Acetaldehyde:A two-carbon aldehyde (CH3CHO) produced through ethylene oxidation or ethanol dehydrogenation, serving as the backbone for vinyl acetate monomer and pyridine derivatives. India's PLI scheme for domestic API manufacturing is drawing acetaldehyde capacity toward Gujarat and Hyderabad clusters for pharmaceutical intermediate synthesis.
- Benzaldehyde:Aromatic aldehyde (C6H5CHO) commanding premium positioning in agrochemical and flavor applications.
- Glutaraldehyde:Five-carbon dialdehyde (OHC(CH2)3CHO) displacing formaldehyde in medical device sterilization under REACH substitution mandates.
- Crotonaldehyde:Unsaturated aldehyde (CH3CH=CHCHO) for sorbic acid and vitamin synthesis.
Formaldehyde handles the majority of throughput; glutaraldehyde is gaining share fastest on regulatory substitution.
Application:
Cost tier differentiation separates commodity resin applications from pharmaceutical-grade nitrogen heterocycle synthesis.
- Resins & Coatings:Formaldehyde-based thermoset polymers dominate construction adhesives and automotive interior trim. German OEMs now require ISO 14001-certified material with verified carbon intensity disclosures, forcing Tier-2 suppliers toward integrated producers.
- Pharmaceuticals:Nitrogen heterocycle synthesis for oncology and antiviral APIs demands sub-50 ppm impurity ceilings. CDSCO inspection readiness in Hyderabad's bulk drug park has become a non-negotiable supplier selection criterion for generic drug manufacturers.
- Plasticizers:Acetaldehyde derivatives for polymer flexibility enhancement.
- Agrochemicals:Benzaldehyde and crotonaldehyde inputs for pyrethroid and herbicide synthesis.
- Textile Processing:Glutaraldehyde and glyoxal crosslinking agents for durable press finishes.
Resins and coatings absorb the bulk of volume; pharmaceuticals delivers the steepest expansion trajectory on API localization incentives.
End User Industry:
Customer type stratification aligns procurement power with specification stringency—pharmaceutical buyers consolidate around qualified suppliers while construction markets fragment across regional blenders.
- Construction & Infrastructure:Engineered wood manufacturers in China and Germany consume formaldehyde resins at scale. Aqueous ammonia pre-treatment is displacing low-concentration formaldehyde in European furniture manufacturing.
- Chemical Manufacturing:Intermediate producers for vinyl acetate, pentaerythritol, and acetic acid derivatives.
- Agriculture:Brazilian formulators source benzaldehyde for generic pyrethroid synthesis under ANVISA's streamlined registration pathway.
- Personal Care:Preservative applications facing ECHA restriction proposals on skin-sensitizing aldehydes.
- Automotive Suppliers:Interior trim adhesive specifications from German OEMs mandate closed-loop production verification.
Construction and infrastructure commands the dominant share; automotive suppliers are climbing fastest on carbon border adjustment preparedness.
Packaging Type:
Volume scale determines packaging economics—bulk tankers serve integrated resin plants while drums and carboys address pharmaceutical-grade parcel requirements.
- Bulk Tankers:Dedicated stainless-steel tankers for formaldehyde and acetaldehyde delivery to large-scale resin and VAM producers.
- Drums:Standard 200-liter steel drums for mid-volume chemical manufacturing customers.
- Intermediate Bulk Containers:1,000-liter totes for regional resin blenders and agrochemical formulators.
- Carboys:Glass or fluoropolymer-lined containers for pharmaceutical-grade benzaldehyde and glutaraldehyde.
- Fiber Drums:Lightweight option for solid aldehyde derivatives and powder formulations.
Bulk tankers move the largest tonnage; intermediate bulk containers are expanding most quickly on modular plant proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Three integrated C1 chemistry complexes in Shandong province control over half of Asia's merchant acetaldehyde output, while German automotive OEMs now mandate ISO 14001-certified formaldehyde with verified carbon intensity disclosures for interior trim adhesives.
China
Shandong province hosts the dominant formaldehyde and acetaldehyde capacity clusters serving construction resin and pharmaceutical intermediate demand. SAMR's GB standards through evolving purity thresholds constrain emission profiles for volatile aldehyde streams. Guangzhou and Shanghai pharmaceutical manufacturers are consolidating API procurement around domestic suppliers with CDSCO-equivalent inspection readiness.
Germany
Automotive OEM specifications for interior trim adhesives now require closed-loop production verification and carbon intensity disclosures from Tier-2 suppliers. ECHA's REACH Article 57 authorization and Annex XIV restrictions on formaldehyde releasers are accelerating substitution toward controlled-release biocide systems. The Ruhr industrial region maintains specialized glutaraldehyde capacity for medical device sterilization applications.
India
Gujarat and Hyderabad clusters are drawing acetaldehyde derivative capacity under the Production Linked Incentive scheme for domestic API manufacturing. CDSCO inspection readiness has become a non-negotiable supplier selection criterion in Hyderabad's bulk drug park. Domestic generic drug manufacturers are signing multi-year toll manufacturing agreements rather than importing technical-grade material.
United States
EPA toxics release thresholds and evolving standards constrain formaldehyde emission profiles from Gulf Coast resin production. The Texas-Louisiana petrochemical corridor anchors North American acetaldehyde supply for vinyl acetate monomer derivatives. Huntsman Corporation maintains specialized glutaraldehyde production for medical disinfectant registrations under FDA oversight.
Brazil
ANVISA's streamlined registration pathway for generic crop protection molecules is opening premium benzaldehyde demand for pyrethroid synthesis among agrochemical formulators. São Paulo state concentrates import-dependent derivative production for regional crop protection markets. Brazilian formulators are qualifying Asian benzaldehyde suppliers against tightening impurity specifications.
Global Aldehyde Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated C1 chemistry platforms commanding supply security advantages while modular producers serve regional resin blenders. The competitive structure bifurcates between pharmaceutical-grade specialists with dedicated production lines and commodity-scale formaldehyde operators serving construction markets. Three archetypes dominate: integrated petrochemical majors with backward integration into methanol feedstocks, pharmaceutical-grade specialists with regulatory qualification expertise, and regional modular producers with membrane separation technology. Dominant competitive moves include capacity expansion in India and China under API localization incentives, and strategic partnerships between automotive OEMs and certified low-carbon intensity suppliers.
Among European-based integrated producers, BASF SE and Evonik Industries AG exemplify the petrochemical major archetype with C1 chemistry platform control, while Eastman Chemical Company represents North American acetaldehyde derivative positioning through captive vinyl acetate monomer supply. Huntsman Corporation occupies the pharmaceutical-grade specialist tier with differentiated glutaraldehyde positioning for medical disinfectant applications under FDA and ECHA regulatory frameworks.
| Leading Market Players |
|---|
| BASF SE |
| Eastman Chemical Company |
| Huntsman Corporation |
| Celanese Corporation |
| Dow Inc |
| Evonik Industries AG |
| Sumitomo Chemical Co., Ltd. |
| Arkema S.A. |
| Lonza Group |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Shandong formaldehyde producers and German automotive OEMs lock in supply access while anchoring price visibility across pharmaceutical-grade and technical-grade tiers. These agreements transfer feedstock volatility risk from buyers to integrated producers with captive methanol supply.
Pricing Analysis
REACH Article 57 authorization dictates the pricing tier structure across European aldehyde markets, separating controlled-release biocide grades from legacy commodity streams. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and industrial-grade levels reflects certification investment and impurity ceiling differentials. Pricing pressure stems from methanol feedstock volatility in the US Gulf and Shanxi province coal cost fluctuations. Construction resin buyers exhibit highest price sensitivity, while pharmaceutical API manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites methanol feedstock delivery to Shandong province C1 chemistry complexes serving Asian derivative markets. China, Germany, and India concentrate over sixty percent of merchant acetaldehyde capacity and glutaraldehyde specialty production. Raw material dependencies center on natural gas, coal-based methanol, and silver catalyst supply. Single-source vulnerability pervades Southeast Asian markets dependent on Shandong merchant output. Distribution runs through dedicated stainless-steel tankers for integrated resin plants and fluoropolymer-lined carboys for pharmaceutical-grade parcel requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compliance services represent a faster-expanding revenue layer than commodity aldehyde production, as ECHA dossier preparation and FDA Type II drug master file consulting command premium attach rates. Pharmaceutical buyers increasingly outsource qualification burden to suppliers with dedicated regulatory affairs capabilities.
For Market Incumbents: Compound certification advantages by extending CDSCO-equivalent inspection readiness to Brazilian ANVISA and US FDA frameworks simultaneously. Capacity addition in Gujarat and Hyderabad clusters under India's PLI scheme defends position against emerging Chinese pharmaceutical-grade specialists. Backward integration into methanol feedstock insulates margin structures from natural gas price swings.
For New Entrants and Emerging Players: Real-time carbonyl impurity spectroscopy services address a service-layer gap where incumbents under-serve mid-scale generic drug manufacturers. Brazilian agrochemical formulators present the most penetrable geography under ANVISA's streamlined generic registration pathway. Position through toll manufacturing partnerships with Hyderabad bulk drug park occupants seeking domestic acetaldehyde qualification.
For Investors and Strategic Acquirers: Modular skid-mounted oxidation unit operators with membrane separation technology represent the priority acquisition archetype for regional market consolidation. Long-term viability hinges on EU Green Deal carbon border adjustment preparedness across the projection horizon. Monitor ECHA restriction proposal timelines on skin-sensitizing aldehydes as inflection indicator for glutaraldehyde substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methanol Feedstock | Captive supply from US Gulf steam crackers insulates BASF and Eastman from natural gas volatility. |
| Pharmaceutical-Grade Certification Investment | CDSCO inspection readiness in Hyderabad qualifies domestic suppliers for multi-year toll agreements. |
| Closed-Loop Catalytic Oxidation Deployment | Zero-vent plants with membrane separation meet German OEM carbon intensity disclosure requirements. |
| Long-Term Supply Agreement with Automotive OEMs | ISO 14001-certified formaldehyde contracts lock in Tier-2 adhesive supply chain position. |
| Joint Venture in Gujarat Pharmaceutical Cluster | PLI scheme incentives draw acetaldehyde derivative capacity toward API localization demand. |
Research Methodology
Desk research of customs trade data, ECHA registration dossiers, and SEC chemical segment disclosures preceded structured interviews with plant managers at Shandong C1 complexes, procurement leads at German automotive OEMs, and regulatory affairs directors at Hyderabad API manufacturers. Primary fieldwork with distribution channel partners and technical R&D directors validated secondary findings. Bottom-up capacity modeling triangulated against top-down consumption estimates from construction resin and pharmaceutical intermediate applications.
Variance decomposition across feedstock cost, regulatory compliance burden, and substitution elasticity shaped the analytical framework over the projection horizon. Segmentation dimensions encompassed grade tier, end-use industry, packaging format, and regional production hub. CAGRs derived from elasticity-adjusted volume projections incorporating methanol price scenarios and REACH authorization timeline assumptions. Industry-specific inputs included SAMR GB standard evolution and EPA toxics release threshold modifications.
Underlying assumptions cover sustained PLI scheme funding in India, ECHA restriction proposal adoption timelines, and methanol feedstock cost stability, with deviation risk concentrated in Shandong supply concentration and EU carbon border adjustment scope expansion. Forecasts reflect documented conditions with revision triggers tied to named regulatory milestones. Practitioners should keep alternative scenarios live as ECHA SVHC listing procedures and ANVISA registration pathways evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
North America Methanol Market
Chemicals
Welding Chemicals Market
Chemicals
Non PVC Plasticizers Market
Chemicals
Laboratory Chemical Reagents Market
Chemicals
Egypt Acidulants Market
Chemicals
Dimethyl Phosphate Market
Chemicals
P-Hydroxybenzoic Acid (PHBA) Market
Chemicals
Global E Series Glycol Ether Market
Chemicals
Rocket Propellant Chemicals Market
Chemicals
Global Boron Trifluoride Market
Chemicals
Allyl Alcohol Market
Chemicals
Global Syringaldehyde Market
Chemicals
Italy Laboratory Chemicals Market
Chemicals
CHPTAC Market
Chemicals
Global Methyl Methacrylate (MMA) Monomer Market
Chemicals
De-Icing Agents Market